
 Alanine Market | 2026-2036
Alanine Market Size, Share, and Industry Trends Forecast 2026-2036
Alanine Market Outlook
A shift from single-source fermentation supply toward multi-source biomanufacturing partnerships is pivoting procurement strategies across the alanine value chain. Ajinomoto Co., Inc. leverages decades of microbial fermentation expertise to sustain premium positioning in pharmaceutical-grade L-alanine. Evonik Industries AG anchors its European production network with advanced biotechnology platforms for amino acid purification. Kyowa Hakko Bio Co., Ltd. competes through specialized enzymatic synthesis routes that differentiate its product specifications from commodity suppliers.
Alanine is a non-essential alpha-amino acid with the chemical formula C3H7NO2, produced industrially through microbial fermentation of carbohydrate feedstocks or chemical synthesis from acetaldehyde, ammonia, and hydrogen cyanide, serving primarily as a building block for protein synthesis, parenteral nutrition formulations, and flavor enhancement in processed foods. L-Alanine dominates volume consumption in food and pharmaceutical applications where chirality-specific functionality commands premium pricing, while DL-Alanine occupies broader industrial uses with lower purity thresholds. The sports nutrition segment within the Application dimension exhibits the fastest structural expansion as protein fortification demand from athletic consumers reshapes formulation priorities.
Food and pharmaceutical regulators including FDA, EFSA, and China's SAMR enforce varying purity and labeling standards that directly shape product specifications and market access requirements for alanine manufacturers. REACH compliance in Europe and GB standards in China impose divergent toxicity testing and documentation burdens, fragmenting certification costs across regional supply chains. Stakeholders must monitor evolving amino acid classification debates among regulators to anticipate whether stricter pharmaceutical-grade requirements will spread into food and nutraceutical categories.
Market Dynamics
Fermentation-based biomanufacturing is displacing chemical synthesis as the dominant production pathway, forcing capacity reconfiguration across European and Asian supply bases while tightening feedstock carbohydrate sourcing requirements.
Growth Catalysts
- Parenteral nutrition expansion:Hospital formulators are expanding L-alanine incorporation in intravenous feeding solutions to support critical care patient recovery protocols.
- REACH compliance acceleration:European chemical registration requirements are favoring bio-based amino acid production over petroleum-derived synthetic routes.
- Sports nutrition protein fortification:Athletic supplement manufacturers are driving volume demand for crystalline L-alanine in pre-workout and recovery formulations.
Market Restraints
- Feedstock price volatility:Corn and molasses carbohydrate costs fluctuate with agricultural commodity cycles, compressing fermentation margins unpredictably.
- Chinese supply concentration:Domestic biotechnology manufacturers control disproportionate amino acid fermentation capacity, creating single-source vulnerability for international buyers.
- DL-alanine substitution pressure:Industrial applications with lower chirality requirements increasingly accept racemic mixtures over premium-priced L-enantiomers.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO quality standards alignment creates entry pathway for pharmaceutical-grade L-alanine suppliers serving domestic injectable drug producers.
- Cell culture media applications:Biopharmaceutical contract manufacturers are qualifying amino acids for monoclonal antibody production processes.
- Precision fermentation scale-up:Continuous processing technology convergence with synthetic biology strain engineering enables titers beyond traditional batch limits.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA and EMA drug master file approvals require 18-36 month validation cycles that delay market entry.
- Enzymatic purification capex:Chiral resolution infrastructure demands significant capital deployment for membrane filtration and crystallization systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alanine Market |
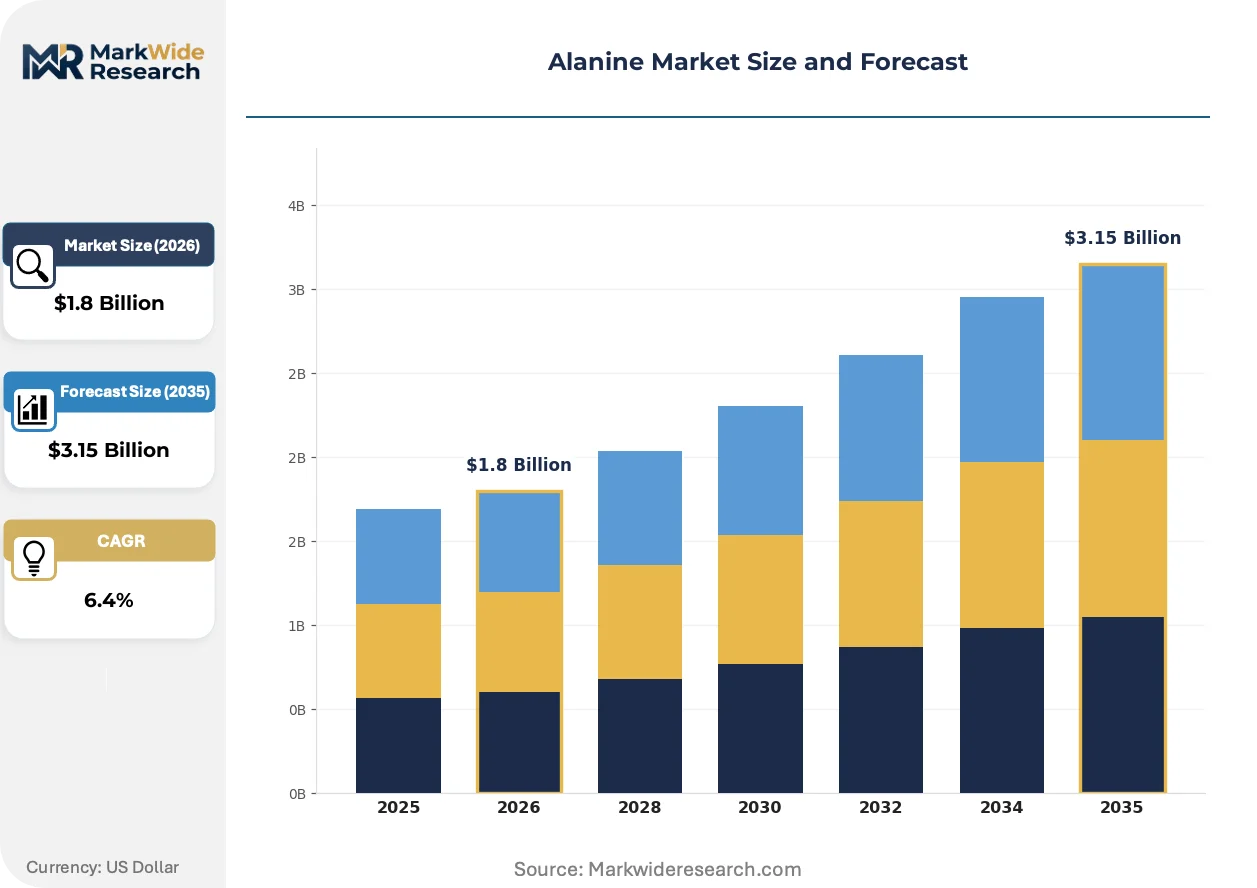
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: L-Alanine, D-Alanine, DL-Alanine, N-ethyl-L-Alanine Application: Food Industry, Pharmaceuticals, Sports Nutrition, Animal Feed End User: Manufacturers, Researchers, Health Professionals, Nutraceutical Companies Delivery Mode: Syrups, Powders, Capsules, Mixed Forms |
| Companies Covered | Ajinomoto Co., Inc., Evonik Industries AG, Kyowa Hakko Bio Co., Ltd., Anhui Huaheng Biotechnology Co., Ltd., SINOGEL Amino Acid Co., Ltd., Fufeng Group Limited, CJ CheilJedang Corporation, Meihua Holdings Group Co., Ltd., Archer-Daniels-Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alanine Market Strategic Shifts
Digital process control systems and continuous bioprocessing architectures are compressing batch cycle times while improving optical purity consistency. These advances intersect with tightening pharmaceutical quality standards and evolving procurement sophistication among downstream formulators.
Continuous fermentation monitoring with inline spectroscopy and AI-driven metabolic flux control is automating titer optimization in real-time. Biomanufacturing facilities in Germany and Japan are retrofitting legacy batch vessels with sensor arrays and automated feeding protocols. This technology is automating the shift from empirical process development to predictive bioprocess control, reducing development timelines from months to weeks.
EFSA's updated food additive re-evaluation protocols are tightening purity specifications for amino acids used in infant nutrition and medical foods. Manufacturers must now submit extended toxicological datasets and stability data under accelerated aging conditions. European suppliers are responding by segregating production campaigns and implementing dedicated pharmaceutical-grade manufacturing lines to maintain dual regulatory compliance.
Formulators are consolidating amino acid suppliers and demanding integrated certificate-of-analysis documentation with each shipment. Sports nutrition contract manufacturers in the United States are shifting from spot-market purchasing to annual volume agreements with quality-locked pricing. This consolidation is most visible in the direct-to-consumer protein brand segment, where supply chain transparency has become a marketing differentiator requiring full batch traceability.
Alanine Market Segmentation
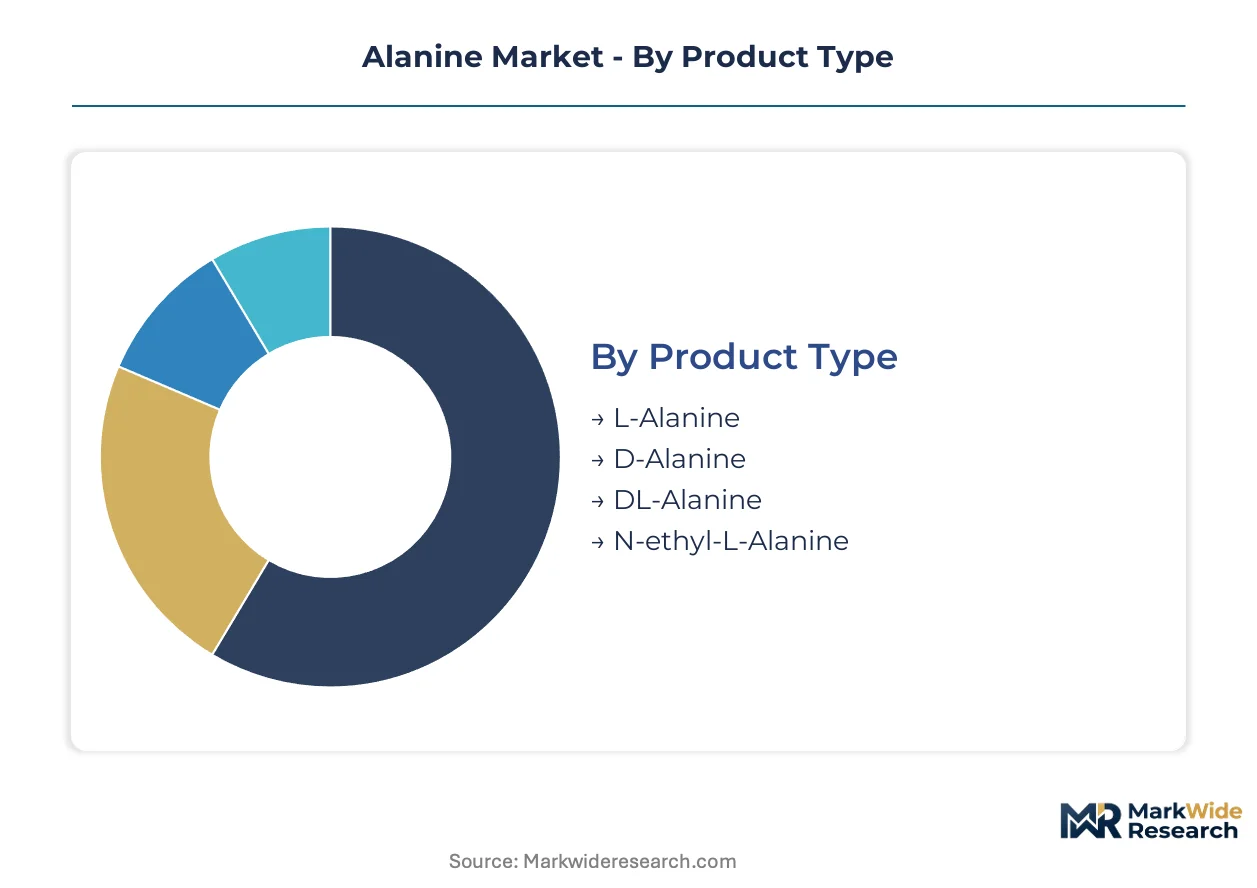
Alanine market segmentation reveals distinct value capture patterns across chirality-specific products and application-driven purity requirements. Pharmaceutical-grade specifications command premium pricing against industrial-grade alternatives, while delivery format choices reflect downstream formulation complexity.
Product Type:
Integration depth varies sharply: L-Alanine serves as standalone active pharmaceutical ingredient in parenteral nutrition, while DL-Alanine embeds primarily as cost-optimized industrial intermediate.
- L-Alanine:The levorotatory enantiomer meets USP and EP pharmacopeia standards for intravenous feeding solutions and cell culture media. Hospital formulators in Germany and Japan specify optical purity above 99 percent for critical care applications. Chiral resolution infrastructure limits supplier base to fermentation specialists with enzymatic purification capabilities.
- DL-Alanine:Racemic mixtures combine equal D- and L-enantiomers through chemical synthesis from acetaldehyde precursors. Industrial applications in metal chelation and polymer synthesis absorb volume in China and India where cost sensitivity outweighs chirality requirements.
- D-Alanine:The dextrorotatory form serves specialized bacterial cell wall synthesis research and peptide antibiotic manufacturing. Niche demand concentrates among academic laboratories and contract research organizations.
- N-ethyl-L-Alanine:This modified derivative functions as chiral building block for custom pharmaceutical synthesis and agrochemical intermediates. Limited commercial availability restricts adoption to specialized chemical suppliers serving bespoke synthesis contracts.
DL-Alanine leads volumes today; L-Alanine is gaining share fastest.
Application:
Cost tier stratification separates pharmaceutical-grade certification investments from commodity food additive positioning.
- Pharmaceuticals:Injectable-grade L-Alanine integrates into parenteral nutrition bags and dialysis solutions under FDA and EMA drug master file requirements. Sterile manufacturing protocols and endotoxin testing add 40-60 percent cost premium over food-grade equivalents.
- Sports Nutrition:Crystalline powders and pre-workout formulations drive volume expansion among athletic supplement brands. Direct-to-consumer protein fortification demands batch-level certificate-of-analysis documentation.
- Food Industry:Flavor enhancement and nutritional fortification in processed foods utilize food-grade L-Alanine and DL-Alanine. EFSA and FDA Generally Recognized As Safe designations govern maximum inclusion levels.
- Animal Feed:Livestock nutrition formulations incorporate DL-Alanine as cost-effective amino acid supplement. Pricing pressure from lysine and methionine alternatives constrains penetration in poultry and swine rations.
Sports Nutrition climbs the fastest; Pharmaceuticals retains the highest margin tier.
End User:
Customer type determines procurement sophistication and contract structure complexity.
- Manufacturers:Pharmaceutical and food processing companies negotiate annual volume agreements with locked quality specifications. Integrated supply chain audits and dual-sourcing requirements dominate enterprise procurement.
- Nutraceutical Companies:Sports nutrition and dietary supplement brands prioritize supply chain transparency for consumer marketing. Third-party testing and full batch traceability have become standard contractual terms.
- Health Professionals:Hospital pharmacy directors and clinical nutritionists specify L-Alanine for parenteral nutrition compounding. Group purchasing organizations aggregate demand across regional health systems.
- Researchers:Academic laboratories and biotechnology companies source small-quantity, high-purity grades for experimental protocols. Catalog distributors and specialized chemical suppliers serve this fragmented demand.
Manufacturers dominate procurement volumes; Nutraceutical Companies are expanding contract value most quickly.
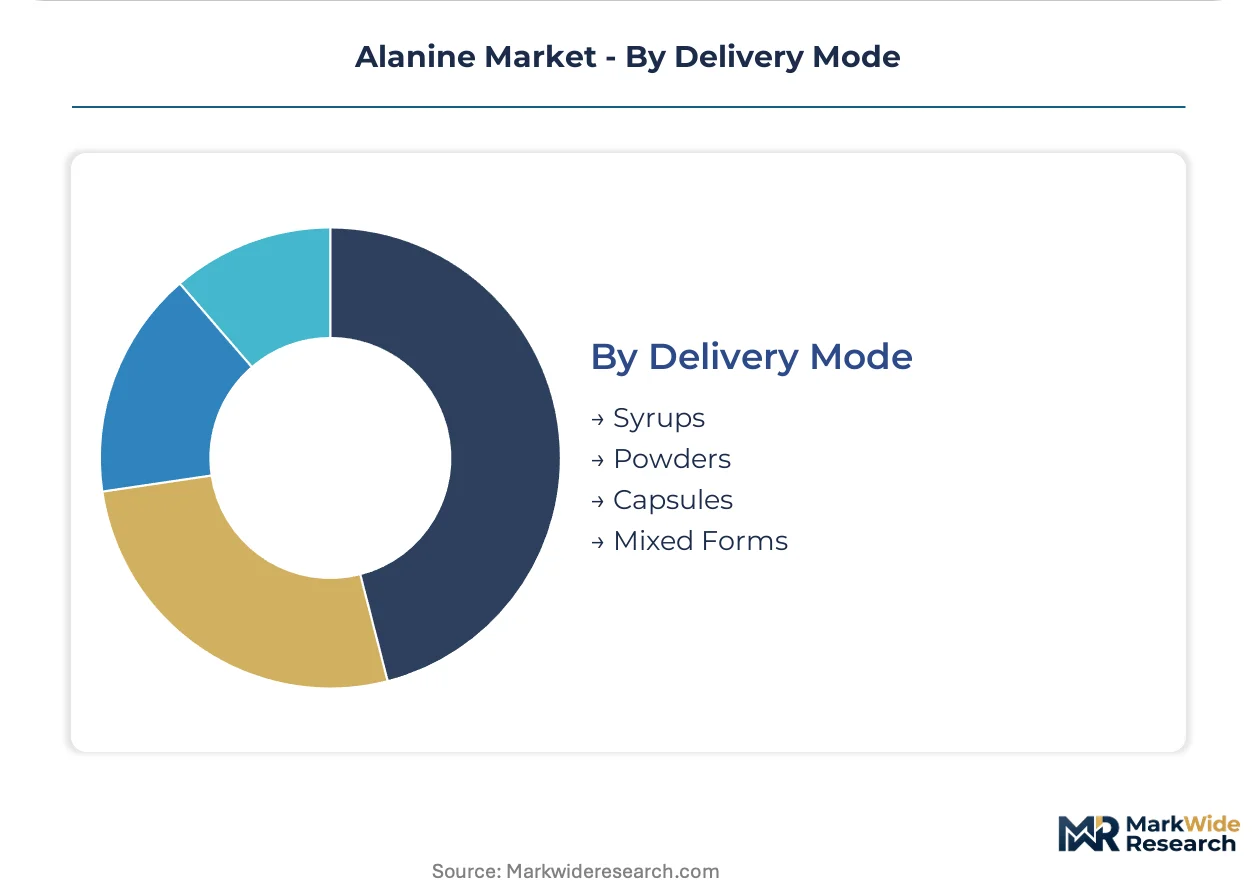
Delivery Mode:
Maturity differentiation separates established powder formats from emerging convenience-oriented presentations.
- Powders:Crystalline and micronized grades serve bulk pharmaceutical manufacturing and sports nutrition blending. Hygroscopicity management and caking prevention drive packaging specification negotiations.
- Capsules:Pre-measured unit doses target direct-to-consumer supplement markets and clinical trial supplies. Hard gelatin and vegetarian shell options respond to formulation preference segmentation.
- Syrups:Liquid formulations facilitate pediatric and geriatric parenteral nutrition administration. Sterile filling and stability testing requirements limit supplier qualification.
- Mixed Forms:Co-formulated amino acid blends and effervescent tablets address convenience positioning in mass-market channels. Flavor masking and dissolution rate optimization consume formulation development resources.
Powders anchor current supply volumes; Capsules demonstrate steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta fermentation corridor hosts the world's densest concentration of amino acid biomanufacturing capacity. European pharmaceutical-grade demand pulls against Asian commodity supply, creating distinct regional value chains. Regulatory divergence between FDA, EMA, and SAMR standards fragments certification requirements across export destinations.
China
Domestic biotechnology manufacturers dominate global fermentation capacity expansion for L-alanine and DL-alanine grades. SAMR's GB standards for food additive purity and NMPA pharmaceutical registration requirements shape dual-track production protocols. Hebei and Shandong provinces concentrate amino acid fermentation clusters where Fufeng Group and Meihua Holdings operate integrated carbohydrate-to-amino-acid facilities.
Germany
Evonik Industries anchors European pharmaceutical-grade amino acid purification through advanced biotechnology platforms in Marl and Hanau. REACH compliance and EMA drug master file requirements favor bio-based production routes over petroleum-derived synthesis. The country's chemical-pharma corridor along the Rhine sustains specialized chiral resolution infrastructure for injectable-grade L-alanine.
United States
Hospital formulators and sports nutrition contract manufacturers drive demand for crystalline L-alanine with batch-level certificate-of-analysis documentation. FDA's drug master file approval timelines and USP pharmacopeia standards govern pharmaceutical-grade market access. New Jersey and North Carolina biopharma clusters host parenteral nutrition compounders qualifying amino acid suppliers for monoclonal antibody production processes.
Japan
Ajinomoto Co., Inc. leverages decades of microbial fermentation expertise from its Kawasaki and Tokai production sites. PMDA pharmaceutical regulations and METI industrial policy support premium positioning for chirality-specific amino acids. The country's biomanufacturing base specializes in high-purity grades for cell culture media and specialized research applications.
India
Domestic injectable drug producers create entry pathways for pharmaceutical-grade L-alanine suppliers aligning with CDSCO quality standards. The country's PLI scheme for active pharmaceutical ingredients incentivizes backward integration into amino acid fermentation. Maharashtra and Gujarat pharmaceutical manufacturing zones concentrate demand from generic injectable exporters seeking dual-source supply security.
Alanine Market Competitive Environment
Global majors compete with regional champions across fermentation scale and pharmaceutical-grade certification depth. Market structure tilts toward consolidated supply at the premium tier and fragmented capacity at commodity grades. Three archetypes dominate: integrated fermentation specialists with carbohydrate feedstock control, pharmaceutical-grade purity specialists with chiral resolution capabilities, and diversified amino acid portfolios with cross-product economies. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure carbohydrate supply agreements and pharmaceutical customer qualifications.
Within the fermentation specialist tier, Ajinomoto Co., Inc. and Kyowa Hakko Bio Co., Ltd. exemplify Japanese precision in microbial strain engineering and enzymatic purification. Evonik Industries AG occupies a position among European chemical-pharma conglomerates with integrated biotechnology platforms. Chinese manufacturers including Fufeng Group Limited and Meihua Holdings Group Co., Ltd. represent scale-driven regional champions leveraging domestic carbohydrate supply chains. These named entities anchor competitive dynamics without exhausting the supplier base, as SINOGEL Amino Acid Co., Ltd. and Anhui Huaheng Biotechnology Co., Ltd. occupy additional positions in the fermentation-capacity landscape.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Evonik Industries AG |
| Kyowa Hakko Bio Co., Ltd. |
| Anhui Huaheng Biotechnology Co., Ltd. |
| SINOGEL Amino Acid Co., Ltd. |
| Fufeng Group Limited |
| CJ CheilJedang Corporation |
| Meihua Holdings Group Co., Ltd. |
| Archer-Daniels-Midland Company |
| Others |
Value Chain & Pricing Dynamics
Family-owned fermentation specialists in China's Hebei and Shandong provinces anchor upstream carbohydrate conversion capacity, translating feedstock control into pricing discipline that resists spot-market volatility. Their integrated starch-to-amino-acid operations compress working capital cycles and buffer margin erosion when corn and molasses costs swing with agricultural commodity cycles.
Pricing Analysis
Input-cost pass-through from carbohydrate feedstocks dominates contract negotiations, with corn futures movements repricing quarterly supply agreements across Asian manufacturing bases. Pharmaceutical-grade L-alanine commands premium-mid-economy pricing differentiation against industrial DL-grades, with USP and EP certification tiers adding 40-60 percent cost premiums for sterile manufacturing protocols. Pricing pressure stems from DL-alanine substitution in industrial applications where chirality requirements relax, squeezing L-enantiomer premiums. Sports nutrition contract manufacturers exhibit highest price sensitivity, consolidating suppliers to secure quality-locked annual volume agreements.
Supply Chain Analysis
Certification gating through FDA drug master file and EMA qualification timelines restricts pharmaceutical-grade supplier pools to fermentation specialists with chiral resolution infrastructure. Supply concentrates in China, Germany, and Japan, with Hebei province and Japan's Kawasaki corridor hosting densest amino acid biomanufacturing clusters. Raw material dependencies center on corn starch, molasses, and enzymatic purification reagents. Single-source vulnerability from Chinese capacity concentration creates structural risk for international buyers seeking dual-source security. Distribution runs through direct annual contracts with pharmaceutical compounders and sports nutrition contract manufacturers, with integrated certificate-of-analysis documentation now standard.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alanine functions as a regulatory compounder where EFSA's updated food additive re-evaluation protocols and tightening infant nutrition purity specifications are accelerating pharmaceutical-grade certification investments across European supply chains.
For Market Incumbents: Extend fermentation capacity utilization through continuous processing retrofits that compress batch cycle times while maintaining optical purity above 99 percent for critical care applications. Defend against DL-alanine substitution pressure by segregating pharmaceutical-grade production lines and locking annual volume agreements with hospital formulators. Backward integration into carbohydrate feedstock sourcing in Hebei and Shandong provinces secures margin control against agricultural commodity volatility. For New Entrants and Emerging Players: CDSCO quality standards alignment in India opens a window for pharmaceutical-grade L-alanine suppliers serving domestic injectable drug producers under the country's PLI scheme for active pharmaceutical ingredients. Target Maharashtra and Gujarat pharmaceutical manufacturing zones where generic injectable exporters seek dual-source supply security. Lead with integrated certificate-of-analysis documentation and full batch traceability to differentiate from established commodity suppliers. For Investors and Strategic Acquirers: Valuations sit cheapest among fermentation-capacity specialists lacking pharmaceutical-grade certification depth but possessing carbohydrate feedstock control and regional market access. Five-to-ten-year viability hinges on regulatory qualification timelines compressing and precision fermentation scale-up enabling titers beyond traditional batch limits. Watch for FDA and EMA drug master file approval accelerations as inflection indicators for premium-tier supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Synthetic biology strain engineering with continuous processing technology enables titers beyond traditional batch fermentation limits in German and Japanese facilities. |
| Pharmaceutical-Grade Certification Investment | Dedicated manufacturing line segregation responds to EFSA's tightened purity specifications for infant nutrition and medical food applications. |
| Carbohydrate Feedstock Integration | Upstream control over corn starch and molasses supply chains buffers margin compression from agricultural commodity price cycles. |
| Cell Culture Media Qualification | Biopharmaceutical contract manufacturers are qualifying amino acid suppliers for monoclonal antibody production processes in New Jersey and North Carolina clusters. |
| Annual Volume Agreement Lock-In | Sports nutrition contract manufacturers shift from spot-market purchasing to quality-locked contracts with full batch traceability documentation. |
Study Parameters
Bottom-up pharmaceutical and sports nutrition demand modeling reconciled against top-down fermentation capacity tracking forms the analytical core of this study. Primary interviews with hospital pharmacy directors, clinical nutritionists, pharmaceutical procurement managers, and sports nutrition contract manufacturing executives combined with secondary validation from FDA drug master file databases, EMA submissions, USP pharmacopeia standards, and customs trade records. Triangulation across stakeholder inputs and regulatory filings ensures segmentation integrity across chirality grades and application tiers.
Input-output matrix framing connects carbohydrate feedstock availability through fermentation titer yields to finished amino acid pricing tiers across the projection horizon. Segmentation dimensions modeled include product type (L-alanine, DL-alanine, D-alanine, derivatives), application (pharmaceuticals, sports nutrition, food industry, animal feed), and delivery mode (powders, capsules, syrups, mixed forms). CAGRs derive from regression analysis against parenteral nutrition volume expansion and sports nutrition protein fortification demand curves, with precision fermentation technology adoption curves and regulatory re-evaluation timelines as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under feedstock price volatility spikes or accelerated pharmaceutical-grade certification requirements. Model outputs reflect assumptions around fermentation yield improvements and regulatory approval timelines without claiming predictive certainty. A model refresh is warranted upon material change in EFSA food additive re-evaluation protocols or SAMR pharmaceutical registration requirement shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Absolute Ethanol Market
Organic Chemicals
Acetaldehyde Market
Organic Chemicals
Cyclohexanone Market
Organic Chemicals
Benzyl Cyanide Market
Organic Chemicals
Asia-Pacific Synthetic Camphor Market
Organic Chemicals
Synthetic Antioxidants Market
Organic Chemicals
Chlorocyclopentane Market
Organic Chemicals
Humic Acid Market
Organic Chemicals
Ethyl Levulinate Market
Organic Chemicals
Triethylene Glycol Market
Organic Chemicals
Synthetic Camphor Market
Organic Chemicals
2-Fluorobenzotrifluoride Market
Organic Chemicals
Global Glycolic Acid Market
Organic Chemicals
Global Carboxylic Acid Market
Organic Chemicals
N-Hexyl Chloride Market
Organic Chemicals
Dimethylformamide (DMF) Market