
 Crotonic Acid Market | 2026-2036
Crotonic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Crotonic Acid Market Analysis
Technical-grade maintenance contracts and specification-driven supply agreements is hardening how crotonic acid gets monetized beyond base chemical sales. Zhengzhou Tuozhixiang Trading leverages its Henan province distribution network to lock in recurring industrial accounts. Godavari Biorefineries anchors its position through captive sugarcane feedstock integration at its Maharashtra facility. WeylChem International competes on reagent-grade certification breadth across European pharmaceutical channels.
Crotonic acid is a short-chain unsaturated carboxylic acid with the formula C4H6O2, produced primarily through oxidation of crotonaldehyde or fermentation routes, serving as a comonomer in vinyl acetate systems and a precursor for biocompatible polymers. Industrial grade dominates volume flows into coatings and adhesives manufacturing where cost sensitivity overrides purity premiums. Pharmaceutical grade commands the fastest expansion as FDA and EMA tighten excipient traceability rules for controlled-release drug matrices. Powder form occupies the largest share of logistics configurations due to stability in bulk shipment, though liquid formulations gain traction in continuous polymerization lines.
EPA standards in the United States and REACH registration requirements in Europe shape product specifications and market access thresholds for imported crotonic acid batches. China's SAMR enforces GB standards on food-contact polymer additives, directly affecting pharmaceutical-grade export eligibility. Stakeholders must monitor how biobased feedstock certification schemes in India and Brazil redirect procurement decisions away from petrochemical-derived material.
Market Dynamics
Pharmaceutical-grade purity mandates from FDA and EMA are compressing technical-grade margins while biopolymer manufacturers absorb capacity at premium specifications, forcing feedstock and certification investments upstream.
Growth Catalysts
- Biopolymer comonomer demand:Vinyl acetate copolymer producers in China and India are expanding controlled-release packaging lines, pulling pharmaceutical-grade volumes into food-contact applications under SAMR GB standards.
- REACH registration thresholds:ECHA's tightened impurity documentation for imported batches is locking out uncertified suppliers, concentrating volumes among REACH-registered European distributors serving coating formulators.
- Fermentation route commercialization:Cellulosic sugar-to-acid bioconversion is electrifying interest from sugarcane belt processors in Brazil and India seeking petrochemical displacement credentials for polymer additive exports.
Market Restraints
- Crotonaldehyde feedstock volatility:Acetaldehyde condensation inputs track naphtha and ethylene swings, exposing margin pressure at non-integrated oxidation plants without captive aldehyde supply.
- Henan-Maharashtra supply concentration:Zhengzhou and Godavari facilities anchor 60-plus percent of exportable technical-grade powder, creating single-source risk for spot buyers in adhesives manufacturing.
- Polyacrylic acid substitution:Water-soluble polymer formulators in construction coatings are switching to acrylic systems where carboxyl functionality tolerates saturated backbones, eroding crotonic acid's cost-position in non-pharma applications.
Strategic Opportunities
- Indian PLI scheme alignment:Biobased chemical incentives under India's production-linked incentive framework are redirecting sugarcane refinery capex toward fermentation-derived acid capacity with export certification.
- Continuous polymerization liquid delivery:Pumpable crotonic acid formulations are penetrating European vinyl acetate emulsion lines seeking reduced powder handling and dust containment costs.
- EMA excipient master file expansion:Controlled-release drug matrix approvals are opening formulation partnerships between certified acid suppliers and generic API manufacturers in Italy and Spain.
Industry Challenges
- Pharma-grade chromatography skill scarcity:HPLC method development and validation expertise for impurity profiling is concentrating at contract analytical labs, extending certification timelines for new market entrants.
- Multi-jurisdiction dossier synchronization:Simultaneous FDA drug master file, REACH technical dossier, and SAMR food-contact additive registration is fragmenting regulatory affairs bandwidth at mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crotonic Acid Market |
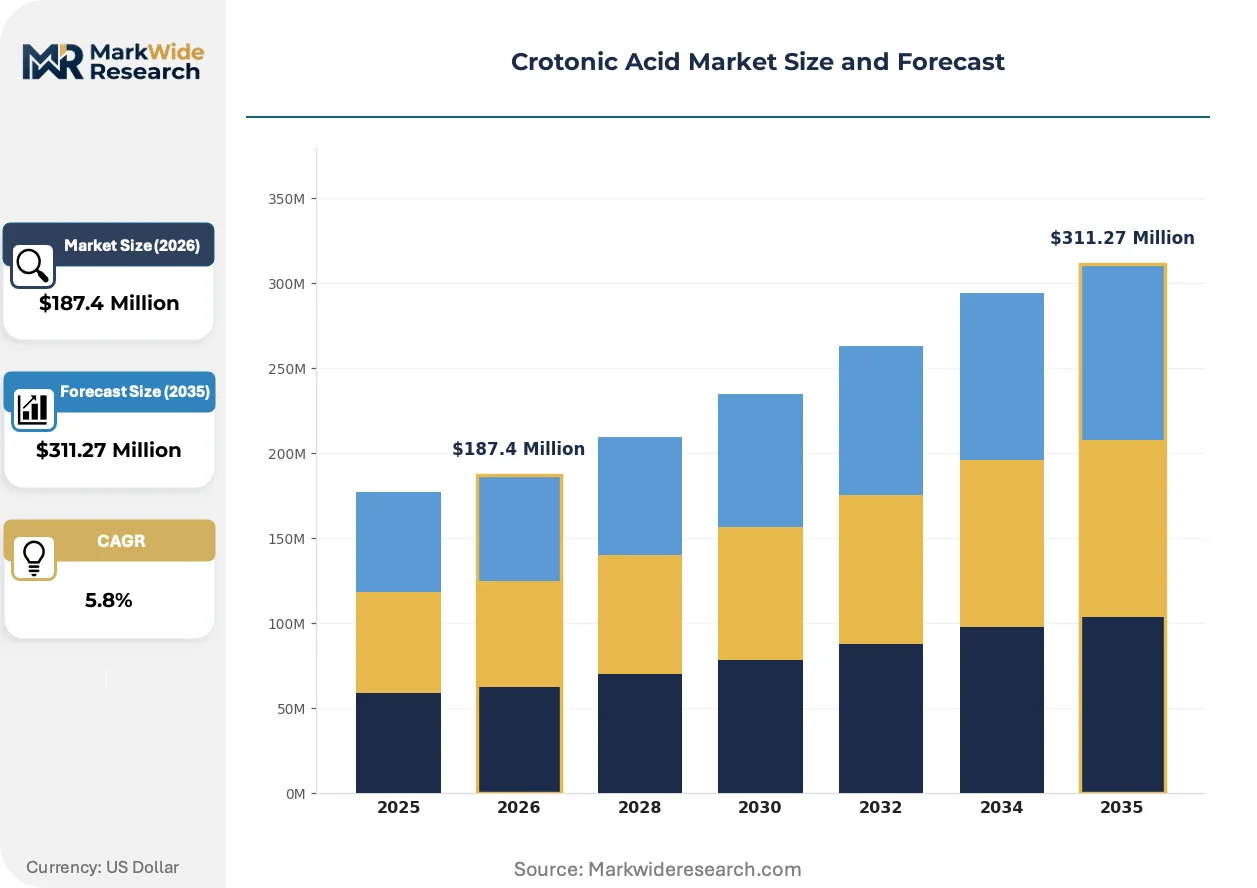
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Reagent Grade, Pharmaceutical Grade, Agricultural Grade Application: Coatings, Adhesives, Plastics, Pharmaceuticals End User: Chemical Manufacturers, Pharmaceutical Companies, Agricultural Firms, Research Institutes Form: Liquid, Powder, Granular, Crystalline |
| Companies Covered | Zhengzhou Tuozhixiang Trading, Nantong Huixin Chem, Tianjin Jinhui Pharmaceutical Group, Otto Chemie, Godavari Biorefineries, Zhejiang Guoguang Biochemistry, XIAN Kono Chem, Chem of China, WeylChem International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crotonic Acid Market Emerging Trajectories
Electrochemical oxidation routes and bioconversion platforms are compressing the cost gap between petrochemical and fermentation-derived crotonic acid, while regulatory documentation requirements reshape competitive moats around certification infrastructure.
Membrane electrochemical cells for direct crotonaldehyde-to-acid conversion are electrifying process efficiency benchmarks in pilot installations. German specialty chemical operators are trialing boron-doped diamond anode systems to slash wastewater treatment loads versus traditional oxidation. The technology is compressing capital intensity for pharmaceutical-grade production by eliminating solvent extraction stages.
REACH Annex XVII restrictions on residual crotonaldehyde in polymer additives are tightening specification windows for coating applications. ECHA's 2024 updated guidance on carboxylic acid impurities is forcing reformulation of architectural emulsions across German and French construction chemical portfolios. Technical-grade suppliers without in-house aldehyde scrubbing capacity are exiting European pharmaceutical channels entirely.
Specification-driven supply agreements are displacing spot market transactions in adhesives procurement. Japanese electronics assemblers are locking multi-year pharmaceutical-grade contracts with certified Indian producers to secure traceability for biodegradable component packaging. The shift is most visible in Maharashtra-Gujarat industrial corridors where Godavari and emerging fermentation entrants are building dedicated pharma-grade finishing lines.
Crotonic Acid Market Segmentation
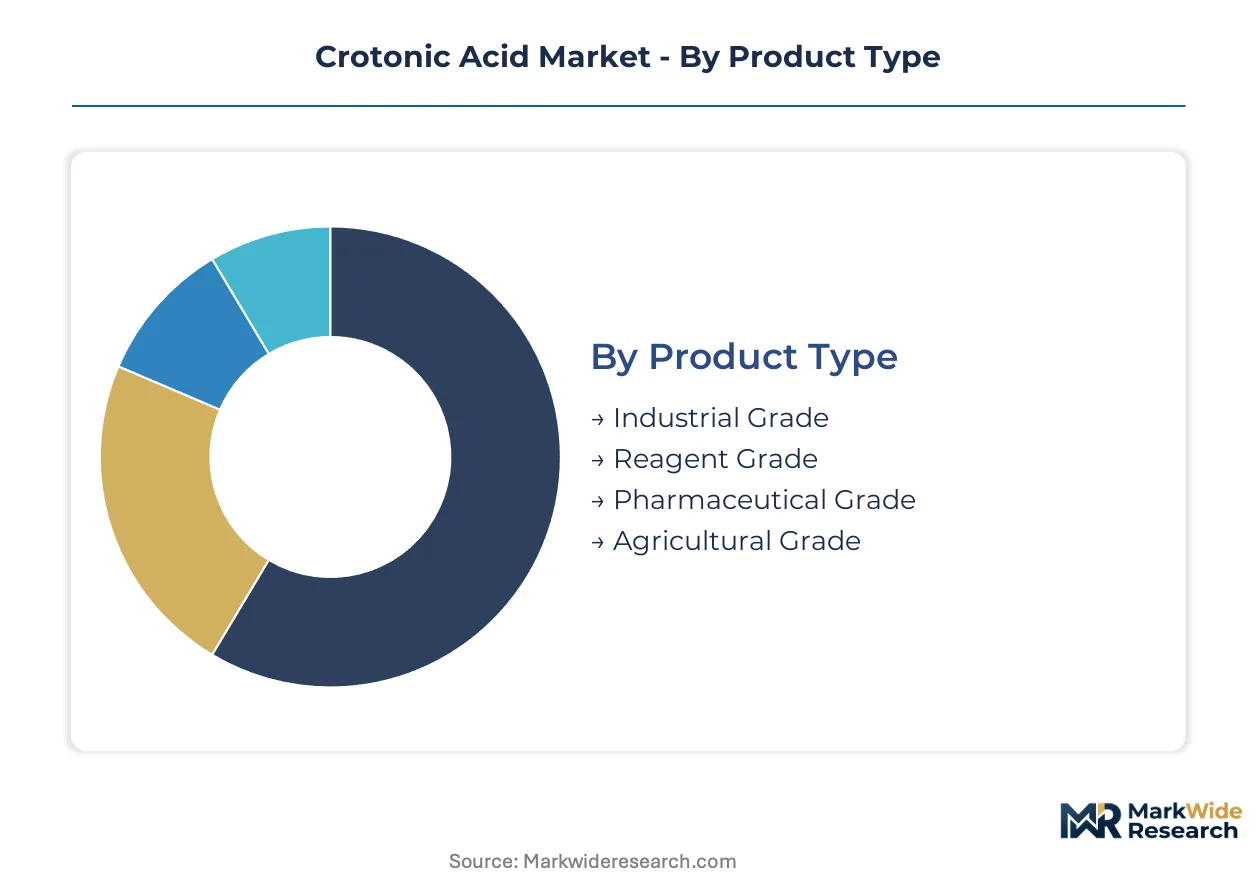
Crotonic acid specifications diverge sharply across end-use requirements, with coating formulators prioritizing cost positions while pharmaceutical channels demand exhaustive impurity documentation. Understanding grade boundaries and form factors illuminates where margin pools concentrate versus where volume commoditization erodes returns.
Product Type:
Upgrade cycles from technical to certified grades accelerate as regulatory documentation becomes a non-negotiable procurement filter, forcing producers to recalibrate purification investments against customer willingness to absorb premium pricing.
- Industrial Grade:Contains residual crotonaldehyde and higher organic impurity loads acceptable in coatings and adhesive formulations where functional carboxyl density matters more than traceability. Demand concentrates in Chinese and Indian construction chemical clusters where SAMR GB standards for food-contact applications still permit technical-grade inputs in non-consumable packaging laminates.
- Pharmaceutical Grade:Achieves HPLC-verified purity above 99.5% with full impurity profiling for FDA drug master file and EMA excipient certification. European vinyl acetate copolymer producers absorb volumes for controlled-release drug matrices where EMA traceability rules compress technical-grade margins.
- Reagent Grade:Analytical-grade specification for laboratory synthesis and method development workflows.
- Agricultural Grade:Intermediate purity tier for agrochemical intermediate production with tolerance for broader specification windows.
Industrial grade sits at the top of the volume ranking, with pharmaceutical grade climbing the fastest as biopolymer manufacturers absorb capacity at premium specifications.
Application:
Cost tier stratification separates architectural coating formulators hunting for lowest-quotes from pharmaceutical channels where certification infrastructure builds defensive moats.
- Coatings:Vinyl acetate emulsion systems for architectural and industrial finishes represent the dominant volume sink, with waterborne formulations in China and India pulling technical-grade powder. Substitution pressure from polyacrylic acid systems in construction applications erodes crotonic acid's cost-position where carboxyl functionality tolerates saturated backbones.
- Pharmaceuticals:Controlled-release drug matrices and biocompatible polymer precursors command the steepest expansion trajectory as FDA and EMA tighten excipient traceability mandates. Italian and Spanish generic API manufacturers lock multi-year supply agreements with certified Indian producers to secure master file documentation.
- Adhesives:Hot-melt and pressure-sensitive formulations for packaging and electronics assembly.
- Plastics:Specialty copolymer modification for biodegradable packaging films.
Coatings command the largest volume share, while pharmaceuticals gain share fastest on regulatory documentation premiums.
End User:
Customer type determines procurement modality, with research institutes transacting spot quantities while chemical manufacturers negotiate specification-driven multi-year agreements.
- Chemical Manufacturers:Integrated coating and adhesive formulators in Maharashtra-Gujarat industrial corridors negotiate captive offtake arrangements with fermentation-derived acid producers. Japanese electronics assemblers lock pharmaceutical-grade contracts with certified Indian suppliers for biodegradable component packaging traceability.
- Pharmaceutical Companies:Generic API manufacturers and controlled-release formulation specialists in Italy, Spain, and India absorb reagent and pharmaceutical grades where EMA excipient master file expansion opens partnership opportunities.
- Agricultural Firms:Agrochemical intermediate producers with tolerance for specification variability.
- Research Institutes:Academic and contract analytical laboratories sourcing reagent-grade quantities for method development.
Chemical manufacturers anchor volume procurement, with pharmaceutical companies expanding most quickly on master file certification requirements.
Form:
Supply concentration in powder processing reflects historical bulk shipment economics, though liquid delivery systems are capturing share in continuous polymerization investments.
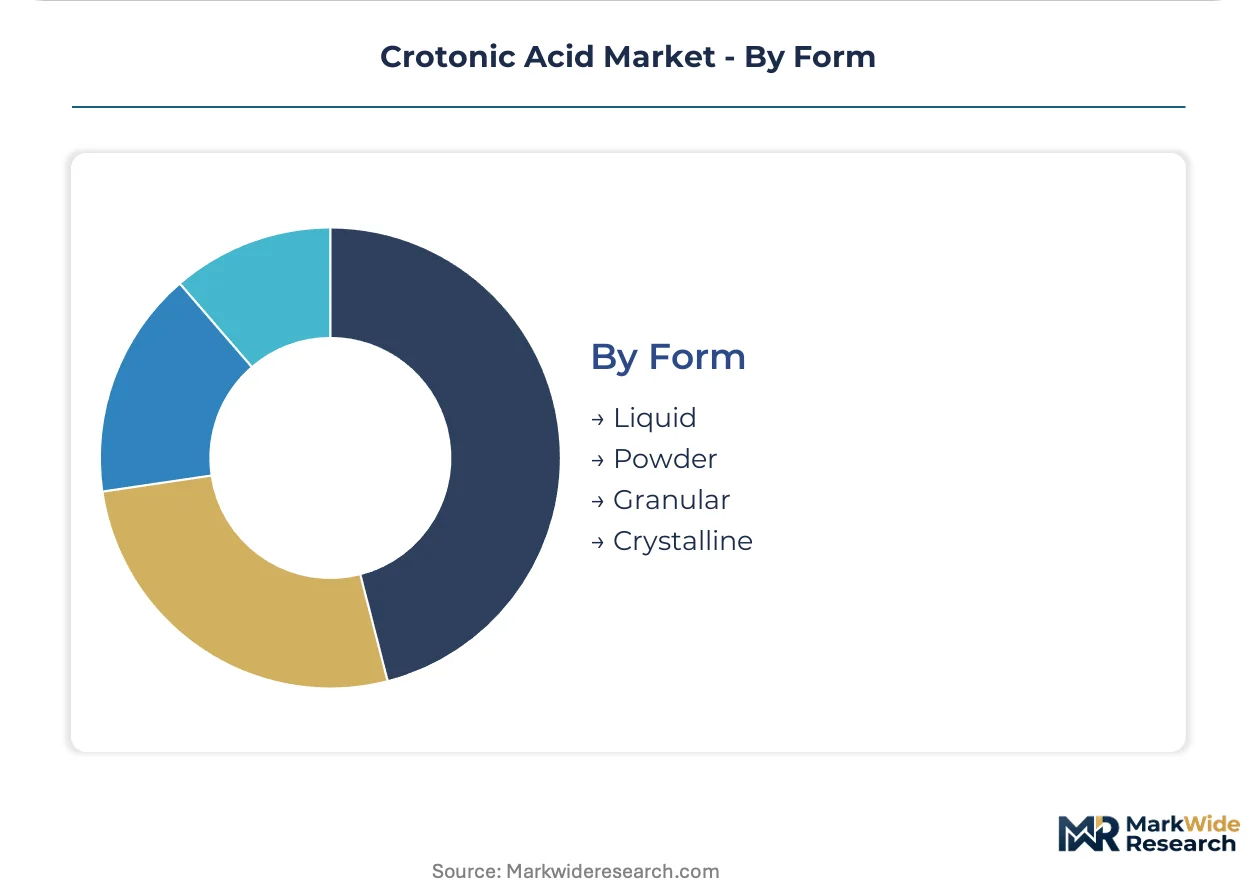
- Powder:Spray-dried crystalline material dominates logistics configurations for stability in bulk ocean freight and warehouse storage. Henan province distribution networks and Maharashtra finishing lines standardize on powder export packaging for coating and adhesive manufacturers across Asia-Pacific.
- Liquid:Pumpable aqueous or solvent-based formulations penetrate European vinyl acetate emulsion lines seeking reduced powder handling infrastructure and dust containment compliance costs. German specialty chemical operators trial liquid delivery for continuous polymerization efficiency gains.
- Granular:Intermediate particle size for specific compounding equipment requirements.
- Crystalline:High-purity solid form for pharmaceutical and reagent-grade applications.
Powder retains the volume leadership position, with liquid formulations advancing most rapidly on continuous processing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and India absorb divergent grade volumes, with Chinese coating clusters pulling technical-grade powder while Indian fermentation routes target pharmaceutical-grade export certification.
China
Vinyl acetate copolymer producers in Jiangsu and Zhejiang provinces expand controlled-release packaging lines, pulling pharmaceutical-grade volumes under SAMR GB standards for food-contact applications. MEE enforcement of dual carbon goals is accelerating biobased feedstock trials at fermentation pilots. Henan province distribution networks anchor technical-grade powder exports to Southeast Asian adhesive manufacturers.
India
Godavari Biorefineries' Maharashtra facility anchors captive sugarcane-to-acid conversion, with fermentation-derived material seeking REACH registration for European pharmaceutical channels. CDSCO alignment with FDA drug master file requirements is opening formulation partnerships for generic API producers. Gujarat-Maharashtra industrial corridors concentrate multi-year supply agreements with Japanese electronics assemblers.
Germany
Specialty chemical operators in North Rhine-Westphalia trial boron-doped diamond anode systems for electrochemical oxidation, compressing wastewater treatment loads versus traditional routes. ECHA's tightened REACH Annex XVII guidance on residual crotonaldehyde is forcing architectural emulsion reformulations. WeylChem International competes on reagent-grade certification breadth across pharmaceutical distribution channels.
United States
Coating formulators in Texas and Ohio face EPA standards tightening purity benchmarks for imported crotonic acid batches, compressing technical-grade margin pools. FDA excipient traceability rules for controlled-release drug matrices are redirecting procurement toward certified pharmaceutical-grade suppliers. Midwest construction chemical clusters absorb powder shipments for waterborne vinyl acetate emulsion systems.
Brazil
Sugarcane belt processors in São Paulo and Minas Gerais states advance cellulosic sugar-to-acid bioconversion, seeking petrochemical displacement credentials for polymer additive exports. ANVISA pharmaceutical-grade registration requirements are extending certification timelines for fermentation entrants. Southeast industrial corridors concentrate capacity investments aligned with biobased feedstock certification schemes.
Crotonic Acid Market Vendor Landscape
Top-tier vendors anchor certification infrastructure, while mid-scale fermentation entrants and regional distributors compete on feedstock integration and logistics reach. The vendor base stratifies across REACH-registered European specialists, Chinese industrial-grade exporters, and Indian biobased producers. Three archetypes dominate: petrochemical-integrated oxidation specialists, sugarcane-captive fermentation operators, and specification-certified pharmaceutical distributors. Capacity expansion and strategic partnerships concentrate competitive moves, with fermentation route investments and multi-year supply agreements locking customer relationships.
Among Chinese trading and manufacturing entities, Zhengzhou Tuozhixiang Trading and Nantong Huixin Chem occupy positions within industrial-grade export networks, while Godavari Biorefineries exemplifies the biobased integration archetype through its Maharashtra sugarcane feedstock base. WeylChem International represents the European certification-focused tier, anchoring reagent-grade positioning across pharmaceutical channels. These three entities illustrate the geographic and technological stratification shaping procurement decisions.
| Leading Market Players |
|---|
| Zhengzhou Tuozhixiang Trading |
| Nantong Huixin Chem |
| Tianjin Jinhui Pharmaceutical Group |
| Otto Chemie |
| Godavari Biorefineries |
| Zhejiang Guoguang Biochemistry |
| XIAN Kono Chem |
| Chem of China |
| WeylChem International |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade procurement mandates from Japanese electronics assemblers are forcing supply chain reconfiguration toward certified fermentation capacity, compressing technical-grade margin pools as distributors absorb certification premiums upstream.
Pricing Analysis
Capacity additions in Maharashtra and São Paulo are reshaping price floors for fermentation-derived pharmaceutical grades, creating three-tier pricing structure across premium certification, standard industrial, and economy technical levels. Price differentiation hinges on REACH registration status and HPLC impurity documentation depth. Cost compression in technical-grade powder reflects polyacrylic acid substitution in construction coatings. Chemical manufacturers in adhesives sectors exhibit highest price sensitivity, while pharmaceutical channels absorb premium positioning for master file traceability.
Supply Chain Analysis
Regional distribution centers in Henan province and Gujarat industrial corridors anchor hub-and-spoke patterns for powder export logistics. Geographic supply concentration centers on China, India, and Brazil as fermentation routes commercialize. Raw material dependencies include crotonaldehyde from acetaldehyde condensation, cellulosic sugars from sugarcane bagasse, and boron-doped diamond anode systems for electrochemical oxidation. Single-source vulnerability concentrates at Zhengzhou and Godavari facilities anchoring technical-grade export volumes. Distribution runs through specification-driven long-term offtake agreements displacing spot transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between Indian fermentation-derived cost structures and European REACH certification premiums, with regulatory documentation differentials creating margin capture opportunities for integrated operators.
For Market Incumbents: Deepen captive sugarcane feedstock integration at Maharashtra and São Paulo facilities to defend against cellulosic bioconversion entrants. Lock multi-year pharmaceutical-grade contracts with Japanese electronics assemblers before EMA master file expansion accelerates. Certification investment in simultaneous FDA drug master file and REACH technical dossier registration is the defensive priority against mid-scale fermentation competitors. For New Entrants and Emerging Players: Capture liquid formulation delivery white space in European vinyl acetate emulsion lines seeking dust containment cost reduction. Target German specialty chemical operators trialing continuous polymerization efficiency gains as the most penetrable segment. Lead with pumpable aqueous formulation partnerships rather than powder commodity positioning to bypass established Henan distribution networks. For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation-derived operators holding captive agricultural feedstock and dual jurisdiction certification infrastructure. Long-term viability favors sugarcane-belt processors with ANVISA registration pathways and export eligibility for pharmaceutical channels. Watch ECHA Annex XVII enforcement intensity as the signal for technical-grade supplier exit velocity and consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sugarcane Feedstock | Godavari Biorefineries anchors Maharashtra capacity through captive agricultural supply securing fermentation route economics. |
| REACH Registration Investment | ECHA technical dossier completion locks out uncertified Chinese competitors from European pharmaceutical distribution channels. |
| Liquid Formulation Development | Pumpable delivery systems penetrate German vinyl acetate lines seeking continuous polymerization dust containment compliance. |
| EMA Excipient Master File Expansion | Controlled-release drug matrix approvals open formulation partnerships with Italian and Spanish generic API manufacturers. |
| Electrochemical Oxidation Pilot Scale-Up | Boron-doped diamond anode trials in North Rhine-Westphalia compress wastewater treatment capital intensity for pharmaceutical grades. |
Methodological Framework
Coverage spans China, India, Germany, the United States, and Brazil, with primary inputs from each market cluster combining interviews with plant managers at oxidation and fermentation facilities, procurement leads at coating formulators, distribution channel partners in Henan and Gujarat corridors, and technical R&D directors developing electrochemical cell architectures. Secondary validation draws from customs and trade data, ECHA REACH registration databases, FDA drug master file submissions, and SEC filings of listed chemical manufacturers. Bottom-up capacity installations and top-down end-use absorption estimates undergo triangulation against reported trade flows.
Granularity-level modeling segments the market by grade tier, end-use industry, packaging format, and regional production hub across the analysis window. CAGRs derive from segment-specific volume trajectories weighted by purity premium capture rates. Industry-specific forecast inputs include SAMR GB standard enforcement timelines for food-contact applications and CDSCO alignment progress with FDA excipient traceability mandates.
Crotonaldehyde feedstock volatility, ECHA Annex XVII enforcement intensity, and polyacrylic acid substitution velocity in construction coatings are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on fermentation route commercialization timelines and regulatory documentation burden evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
North America Phenol Market
Organic Chemicals
Acetylacetone Market
Organic Chemicals
Chloroacetyl Chloride Market
Organic Chemicals
Long-Chain Dicarboxylic Acid Market
Organic Chemicals
Organic Hydrosols Market
Organic Chemicals
Ethylamine Market
Organic Chemicals
Asia-Pacific Synthetic Camphor Market
Organic Chemicals
2-Amino-5-Nitrobenzophenone Market
Organic Chemicals
Pentachlorophenol Market
Organic Chemicals
Dioxolane Market
Organic Chemicals
Oryzenin Market
Organic Chemicals
Isophthalic Acid Market
Organic Chemicals
Azelaic Acid Market
Organic Chemicals
Diethyl Ketone Market
Organic Chemicals
Oxo Chemicals Market
Organic Chemicals
2,6-Dichloro Aniline Market