
 Synthetic Antioxidants Market | 2026-2036
Synthetic Antioxidants Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Antioxidants Market Outlook
Direct procurement between antioxidant producers and polymer compounders is narrowing as large resin manufacturers consolidate vendor lists. BASF leverages its integrated phenolics chain to sustain cost advantages across BHT and TBHQ grades. SI Group anchors North American supply through captive alkyl phenol production. SONGWON competes aggressively in Asia with specialized phosphite blends for polyolefin stabilization.
Synthetic antioxidants are chemically manufactured stabilizers—predominantly hindered phenols like BHA and BHT, or quinone-derived TBHQ and propyl gallate—synthesized via alkylation or esterification routes to interrupt free-radical oxidation chains in organic substrates. These compounds primarily extend service life and sensory stability in plastics, edible oils, and cosmetic emulsions. Among product types, BHT occupies the mature volume position with thin margins, while TBHQ captures expanding demand from high-temperature frying oil applications. By end user, plastics manufacturing outpaces food industry growth in absolute tonnage, though pharmaceutical-grade antioxidants command superior unit economics due to USP certification overhead.
FDA food additive regulations under 21 CFR 172 govern antioxidant permissible limits and labeling thresholds in edible applications, while REACH registration mandates toxicity dossiers for European chemical imports. China's SAMR enforces GB standards for food-grade antioxidant purity that often exceed legacy Codex thresholds, raising compliance costs for non-domestic suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation penalties and supply disqualification.
Market Dynamics
Consolidation among polymer resin manufacturers is compressing vendor lists and forcing antioxidant suppliers to secure captive feedstock positions or exit. This structural pressure favors integrated phenolics producers while fragmenting non-integrated compounders.
Growth Catalysts
- REACH registration mandates:ECHA toxicity dossier requirements for European chemical imports are disqualifying legacy traders and redirecting volumes toward registered producers with compliant supply chains.
- High-temperature frying oil processors:Food service chains in Southeast Asia are adopting TBHQ stabilization for extended fry life, pulling demand away from traditional BHT blends.
- China's plastics manufacturing cluster:Zhejiang and Guangdong province compounders are scaling phosphite antioxidant consumption for polyolefin stabilization at rates exceeding domestic supply growth.
Market Restraints
- Para-cresol feedstock volatility:BHT and hindered phenol production costs fluctuate with refinery aromatic byproduct availability, squeezing margins for non-integrated producers.
- Substitution by natural antioxidants:Rosemary extract and tocopherol blends are capturing clean-label food applications where processors accept shorter shelf life for marketing claims.
- SAMR purity enforcement:China's GB standards for food-grade antioxidant certification impose testing burdens that raise qualification costs for non-domestic suppliers.
Strategic Opportunities
- Pharmaceutical-grade USP certification:Antioxidant producers with dedicated GMP facilities can capture premium pricing from injectable and biologic formulation houses seeking excipient security.
- India's FSSAI modernization:India's food safety regulator is harmonizing additive standards with Codex, opening import pathways for compliant synthetic antioxidant suppliers previously blocked by legacy BIS barriers.
- Recycled plastics stabilization:Mechanical recycling streams degrade polymer chains through heat history, creating demand for phosphite-phenol synergist packages that restore processability.
Industry Challenges
- Alkylation reactor capex intensity:Hindered phenol synthesis requires high-pressure hydrogenation capacity that locks capital for 8-12 year depreciation cycles, constraining capacity response.
- REACH only representative liability:Non-EU suppliers face legal exposure from importer-only representative arrangements, forcing direct subsidiary establishment or market withdrawal.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Antioxidants Market |
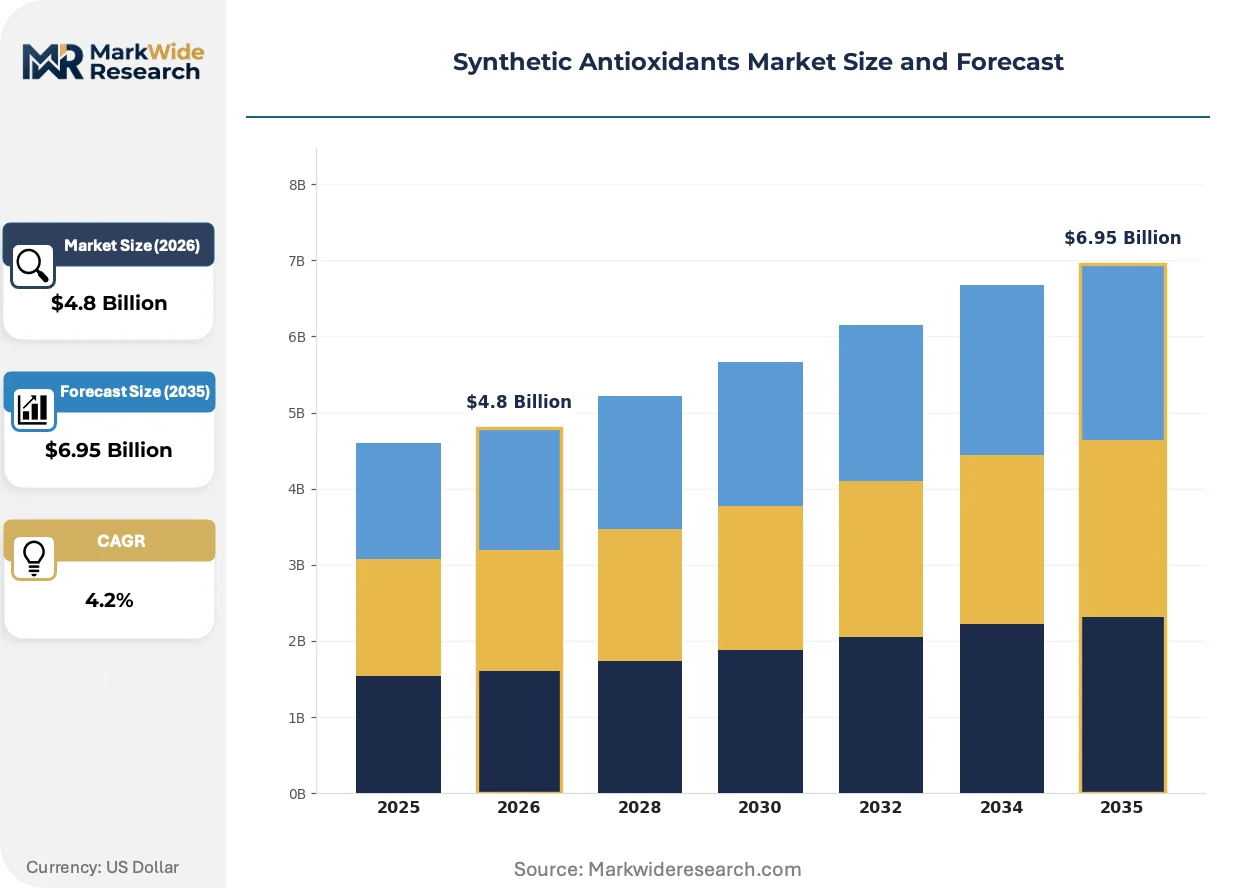
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BHA, BHT, TBHQ, PG Application: Food Preservation, Cosmetic Formulations, Plastics Manufacturing, Agricultural Chemicals End User: Food Industry, Personal Care, Pharmaceuticals, Agriculture Distribution Channel: Online Sales, Retail Stores, Direct Sales, Distributors |
| Companies Covered | SI Group, Everspring, BASF, Clariant, Solvay, Lanxess, Adeka, Rianlon, SONGWON, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Antioxidants Market Strategic Shifts
Antioxidant formulation science is pivoting from commodity volume plays toward performance-anchored specialty blends. This shift rewards technical service capabilities over pure manufacturing scale.
Liquid phosphite stabilizers with reduced hydrolytic sensitivity are collapsing the traditional solid phosphite market in polyolefin extrusion. European compounders are adopting these grades for continuous compounding lines where powder handling downtime was unacceptable. The technology is collapsing equipment utilization gaps between large integrated resin producers and smaller toll compounders.
REACH authorization sunset dates for certain phenolic intermediates are forcing reformulation cycles across European plastics additives. Compounders must validate alternative antioxidant packages or secure continued use authorizations through supply chain consortiums. Food-contact applications face the tightest substitution timelines given EFSA consumer exposure assessments.
Direct mill procurement of antioxidant masterbatches is displacing distributor-mediated sourcing among North American rotational molders. Large tank and container manufacturers are qualifying single-source antioxidant suppliers for multi-year tolling agreements. This pattern concentrates most visibly in the US Gulf Coast petrochemical corridor where resin production and rotational molding plants co-locate.
Synthetic Antioxidants Market Segmentation
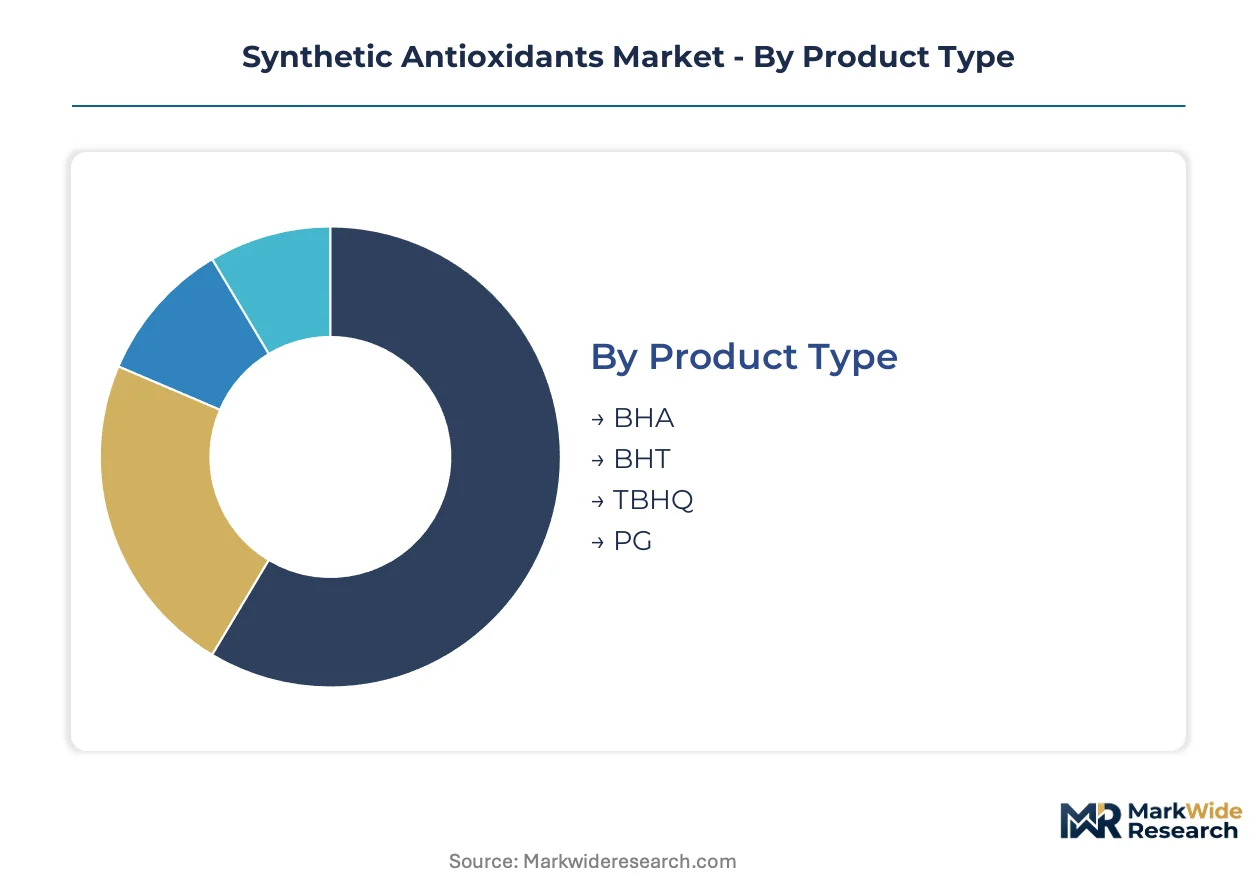
Antioxidant procurement patterns diverge sharply across product chemistries and end-use specifications. Segmentation reveals where formulation complexity commands premium positioning versus commodity volume plays.
Product Type:
Mature phenolic antioxidants dominate current throughput while quinone-derived grades capture emerging high-temperature applications.
- BHT:The hindered phenol synthesized via para-cresol alkylation serves as the baseline stabilizer for polyolefin extrusion and edible oil preservation. Demand concentrates in China's Zhejiang province compounders seeking cost-efficient polymer stabilization amid domestic feedstock integration.
- TBHQ:Tert-butylhydroquinone withstands thermal degradation above 200°C, making it indispensable for extended frying oil cycles in Southeast Asian food service chains. SAMR's GB purity enforcement raises qualification barriers for non-domestic suppliers targeting China's TBHQ import market.
- BHA:Butylated hydroxyanisole functions as a synergist in cosmetic emulsion stabilization where ECHA REACH dossier compliance filters supplier pools.
- PG:Propyl gallate esterifies gallic acid for pharmaceutical-grade excipient applications requiring USP certification overhead.
BHT handles the majority of throughput; TBHQ is the fastest mover on share.
Application:
Cost tier separation distinguishes high-specification formulation work from commodity volume stabilization.
- Plastics Manufacturing:Polyolefin stabilization consumes phosphite-phenol synergist packages at scale, with Guangdong province compounders driving phosphite antioxidant consumption rates exceeding domestic supply growth. REACH authorization sunset dates for phenolic intermediates force European compounders into reformulation cycles.
- Food Preservation:Edible oil processors specify antioxidant blends based on fry temperature profiles and shelf-life targets. FDA 21 CFR 172 permissible limits govern labeling thresholds while India's FSSAI modernization opens import pathways previously blocked by legacy BIS barriers.
- Cosmetic Formulations:Emulsion stability demands drive antioxidant selection alongside preservative systems in skincare and haircare products.
- Agricultural Chemicals:Pesticide formulation houses employ antioxidants to protect active ingredient integrity through storage and field application cycles.
Plastics Manufacturing commands the dominant cost tier; Food Preservation exhibits the steepest expansion trajectory as processors reformulate for extended shelf-life claims.
End User:
Customer type determines whether procurement flows through distributor networks or direct mill qualification programs.
- Food Industry:Processors of frying oils, baked goods, and snack foods specify antioxidant systems based on thermal processing requirements and clean-label positioning pressures.
- Personal Care:Cosmetic formulators prioritize oxidative stability in emulsions and anhydrous systems where sensory performance intersects with preservative efficacy.
- Pharmaceuticals:Injectable and biologic formulation houses demand USP-certified excipients with dedicated GMP facilities, capturing premium pricing through supply security guarantees.
- Agriculture:Crop protection manufacturers integrate antioxidants into pesticide formulations to extend active ingredient shelf stability.
Food Industry anchors procurement volume; Pharmaceuticals delivers the highest margin capture per kilogram.
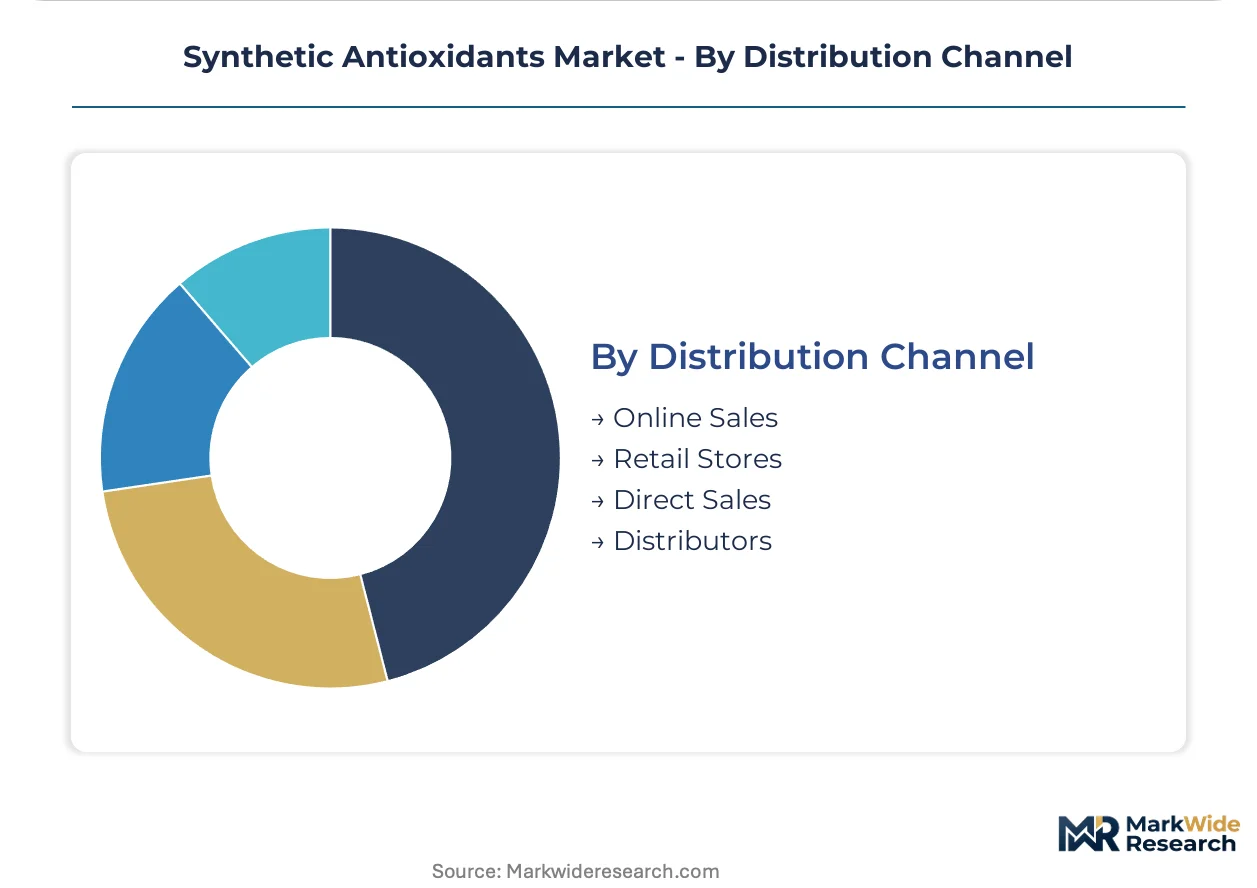
Distribution Channel:
Supply concentration shapes whether antioxidant procurement routes through integrated resin producers or fragmented toll compounder networks.
- Direct Sales:Large polymer resin manufacturers consolidate vendor lists and negotiate multi-year tolling agreements with single-source antioxidant suppliers, particularly visible in the US Gulf Coast petrochemical corridor.
- Distributors:Regional chemical distributors serve mid-scale compounders and food processors lacking volume to justify direct mill procurement.
- Online Sales:Specialty chemical marketplaces facilitate small-lot procurement for R&D formulation work and pilot-scale production.
- Retail Stores:Limited consumer-packaged antioxidant sales occur through industrial supply retailers serving maintenance and small-batch processors.
Direct Sales captures the majority of tonnage; Distributors retain relevance in fragmented compounder segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp pipeline corridor underwrites Europe's antioxidant distribution architecture, feeding polymer compounders across the Rhine-Ruhr industrial belt with phenolic stabilizer feedstocks.
United States
Gulf Coast petrochemical producers consume phosphite-phenol synergist packages at scale for polyolefin extrusion. FDA 21 CFR 172 governs permissible limits for food-contact applications. Houston-area resin manufacturers negotiate multi-year tolling agreements with single-source antioxidant suppliers.
Germany
REACH authorization sunset dates for phenolic intermediates force compounders into reformulation cycles. ECHA toxicity dossier requirements redirect volumes toward registered producers with compliant supply chains. Ludwigshafen's integrated chemical parks sustain cost advantages across hindered phenol grades.
China
Zhejiang and Guangdong province compounders scale phosphite antioxidant consumption for polyolefin stabilization. SAMR enforces GB standards for food-grade antioxidant purity that exceed legacy Codex thresholds. Ningbo's plastics manufacturing cluster drives domestic consumption rates exceeding supply growth.
India
FSSAI modernization harmonizes additive standards with Codex, opening import pathways for compliant suppliers. High-temperature frying oil processors in Mumbai and Delhi adopt TBHQ stabilization for extended fry life. Gujarat's edible oil refineries specify antioxidant blends based on thermal processing requirements.
Japan
Cosmetic formulators in Osaka prioritize oxidative stability in emulsion systems where sensory performance intersects preservative efficacy. METI oversees chemical substance reporting for antioxidant imports. Kanto region personal care manufacturers drive demand for pharmaceutical-grade excipient certification.
Synthetic Antioxidants Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the phenolics chain. The vendor base compresses around integrated producers with captive alkyl phenol capacity and non-integrated compounders facing structural pressure. Three archetypes dominate: integrated phenolics producers with refinery linkages, specialty phosphite blenders serving polyolefin stabilization, and pharmaceutical-grade excipient houses with dedicated GMP facilities. Consolidation among resin manufacturers and REACH registration mandates represent the dominant competitive moves reshaping supplier qualification.
Among Germany-based chemical conglomerates, BASF occupies a position exemplifying integrated phenolics production. SI Group anchors North American supply through its captive feedstock position. SONGWON represents the Asia-specialist archetype competing with phosphite blends for polyolefin stabilization.
| Leading Market Players |
|---|
| SI Group |
| Everspring |
| BASF |
| Clariant |
| Solvay |
| Lanxess |
| Adeka |
| Rianlon |
| SONGWON |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's Zhejiang phenolics corridor is compressing spot margins for non-integrated BHT producers while rewarding captive feedstock operators with pricing power across contract negotiations. This utilization asymmetry forces merchant producers toward tolling arrangements or exit, consolidating margin capture among refinery-linked suppliers.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels separates USP-certified excipients from Codex-compliant food additives and commodity polymer stabilizers. Price differentiation hinges on certification overhead and volume scale, with pharmaceutical-grade antioxidants commanding premiums due to GMP facility requirements. Cost compression in industrial-grade phenolics is intensifying because of para-cresol feedstock volatility and Chinese domestic oversupply. Food processors exhibit the highest price sensitivity, while injectable formulation houses prioritize supply security over unit cost.
Supply Chain Analysis
Para-cresol and alkyl phenol feedstock availability centers on China, Germany, and the United States, with refinery aromatic byproduct yields determining regional cost competitiveness. Synthetic antioxidant production draws from petrochemical intermediates, phosphite ester precursors, and gallic acid derivatives. Single-source vulnerability runs through China's concentrated phenolics capacity, where environmental enforcement disruptions can cascade through global polyolefin stabilization supply. Distribution runs through integrated resin producers for large polymer compounders and regional chemical distributors for mid-scale food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic antioxidants constitute a defensive-moat market where regulatory entrenchment protects qualified suppliers; REACH dossier completion and FDA food additive petitions create switching costs that lock in incumbent positions.
For Market Incumbents: Harden regulatory moats by accelerating REACH authorization sunset date compliance ahead of European compounder reformulation cycles. Secure captive para-cresol supply through backward integration or long-term offtake agreements with refinery operators to defend against feedstock volatility. Natural antioxidant substitution in clean-label food applications represents the primary demand-side threat requiring technical service investment to demonstrate performance superiority. For New Entrants and Emerging Players: India's underpenetrated TBHQ import market offers the most accessible white-space target following FSSAI harmonization with Codex standards. Pharmaceutical-grade USP certification in underdeveloped GMP jurisdictions presents a second penetration vector. A toll-manufacturing partnership with established phenolics producers enables qualification without alkylation reactor capital intensity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated phenolics producers with multi-year resin manufacturer contracts. Long-term viability favors suppliers with refinery linkages and regulatory dossier depth over merchant compounders facing structural compression. The signal to watch is REACH authorization consortium formation, which indicates substitution pressure and reformulation-driven volume shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Para-Cresol | Captive feedstock supply locks cost advantage against merchant competitors in Zhejiang corridor. |
| Pharmaceutical-Grade USP Certification | GMP facility investment captures premium pricing from injectable formulation houses. |
| Long-Term Tolling Agreements | Multi-year contracts with Gulf Coast resin producers secure volume visibility. |
| Phosphite-Phenol Synergist Development | Liquid phosphite innovation addresses hydrolytic sensitivity in continuous compounding lines. |
| REACH Authorization Consortium Participation | Continued use authorization secures European volume against sunset date substitution. |
Study Parameters
Initial hypotheses were tested against primary input from polymer compounder procurement leads, edible oil processor technical directors, pharmaceutical excipient qualification managers, and antioxidant R&D chemists and refined through secondary validation against customs trade data, SEC 10-K chemical segment disclosures, ECHA registration dossiers, and food additive petition filings. Bottom-up volume estimates from end-use consumption patterns were triangulated with top-down production capacity assessments across major phenolics corridors.
Demand-supply balance modeling across the analysis window incorporated grade tier differentiation, end-use industry concentration, regional production hub clustering, and regulatory compliance stratification. CAGRs were derived from segmented growth trajectory analysis calibrated to polymer extrusion rates, frying oil processing expansion, and pharmaceutical formulation growth. Forecast inputs included REACH authorization timeline impacts, China's SAMR enforcement intensity, and India's FSSAI modernization pace.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-linked phenolics producers or accelerated natural antioxidant substitution in European food applications would shift outcomes. Cross-checking against ECHA registration volume data and regional customs import statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Anisole Derivatives Market
Organic Chemicals
Dioctyl Phthalate Market
Organic Chemicals
Organic Hydrosols Market
Organic Chemicals
Nonylphenol Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
Acrylic Acid Market
Organic Chemicals
Acetaldehyde Market
Organic Chemicals
Cyclohexanone Market
Organic Chemicals
Methyl Isobutyl Ketone (MIBK) Market
Organic Chemicals
Bio-Acetic Acid Market
Organic Chemicals
2-Fluorobenzotrifluoride Market
Organic Chemicals
Benzethonium Chloride Market
Organic Chemicals
Cyclic Ketones Market
Organic Chemicals
Ethyl Levulinate Market
Organic Chemicals
Organic Peroxide Market
Organic Chemicals
Chloroethylene Market