
 1,3-Dioxolane Market | 2026-2036
1,3-Dioxolane Market Size, Share, and Industry Trends Forecast 2026-2036
1,3-Dioxolane Market Analytics
REACH compliance is shifting the cost-of-entry calculus for European suppliers of 1,3-dioxolane. BASF Chemical Intermediates leverages its integrated ethylene oxide pipeline to sustain margin stability under tightening purity mandates. Merck KGaA anchors its position through pharmaceutical-grade certification that exceeds baseline industrial specifications. Kairav Chemofarbe Industries Ltd. competes on volume scale across Asian solvent markets.
1,3-Dioxolane is a cyclic acetal with the molecular formula C3H6O2, typically produced via acid-catalyzed condensation of formaldehyde with ethylene glycol, and serves primarily as a polar aprotic solvent and electrolyte co-solvent in lithium battery formulations. Industrial grade material dominates volume throughput for chemical manufacturing applications, while pharmaceutical grade commands premium pricing through CDSCO and FDA certification pathways. Electrolyte applications are expanding fastest as battery producers seek low-viscosity co-solvents with enhanced flash-point profiles.
EPA oversight in the United States governs formaldehyde emissions from acetal production facilities, while China's MEE enforces dual carbon goals that constrain energy-intensive glycol processing. ECHA's REACH authorization list continues to tighten impurity thresholds for cyclic solvents entering European battery supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to align certification investments with destination-market requirements.
Market Dynamics
Battery electrolyte manufacturers are consolidating procurement around high-purity 1,3-dioxolane grades, forcing solvent producers to retool purification lines and abandon legacy industrial-grade capacity.
Growth Catalysts
- REACH authorization thresholds:ECHA's tightening impurity mandates for cyclic solvents entering European battery supply chains are pulling through demand for pharmaceutical-grade certification.
- Lithium-ion cell manufacturing:China's Ningbo and Shenzhen industrial clusters are scaling electrolyte blending capacity, consuming rising volumes of low-viscosity co-solvents.
- Dual carbon goals:China's MEE enforcement is accelerating facility upgrades that improve energy efficiency in glycol processing, expanding compliant supply availability.
Market Restraints
- Formaldehyde feedstock volatility:EPA emissions controls on acetal production facilities constrain capacity expansion in the United States, capping regional supply growth.
- East Asian supply concentration:Overreliance on Chinese ethylene oxide derivatives creates vulnerability to MEE environmental inspections and energy rationing protocols.
- Propylene carbonate substitution:Alternative cyclic carbonates with comparable dielectric properties threaten 1,3-dioxolane's cost position in mid-tier battery formulations.
Strategic Opportunities
- Indian pharmaceutical solvent demand:CDSCO certification pathways for excipient-grade material remain underpenetrated relative to the country's expanding generic API manufacturing base.
- Solid-state battery electrolyte convergence:Polymer-ceramic hybrid cell architectures are creating specifications for ultra-dry 1,3-dioxolane with moisture specifications below 10 ppm.
- Direct procurement channels:Electrolyte blenders are bypassing traditional distributor networks to secure volume commitments with solvent producers, compressing margin capture by intermediaries.
Industry Challenges
- Analytical chemistry talent scarcity:Gas chromatography-mass spectrometry specialists capable of validating trace impurity profiles command premium compensation, constraining quality lab expansion.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EMA, and CDSCO filing requirements extend product launch cycles by 18-24 months for pharmaceutical-grade entrants.
- Legacy acetal reactor retrofit costs:Acid-catalyzed condensation units require corrosion-resistant lining replacement to meet current mechanical integrity standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 1,3-Dioxolane Market |
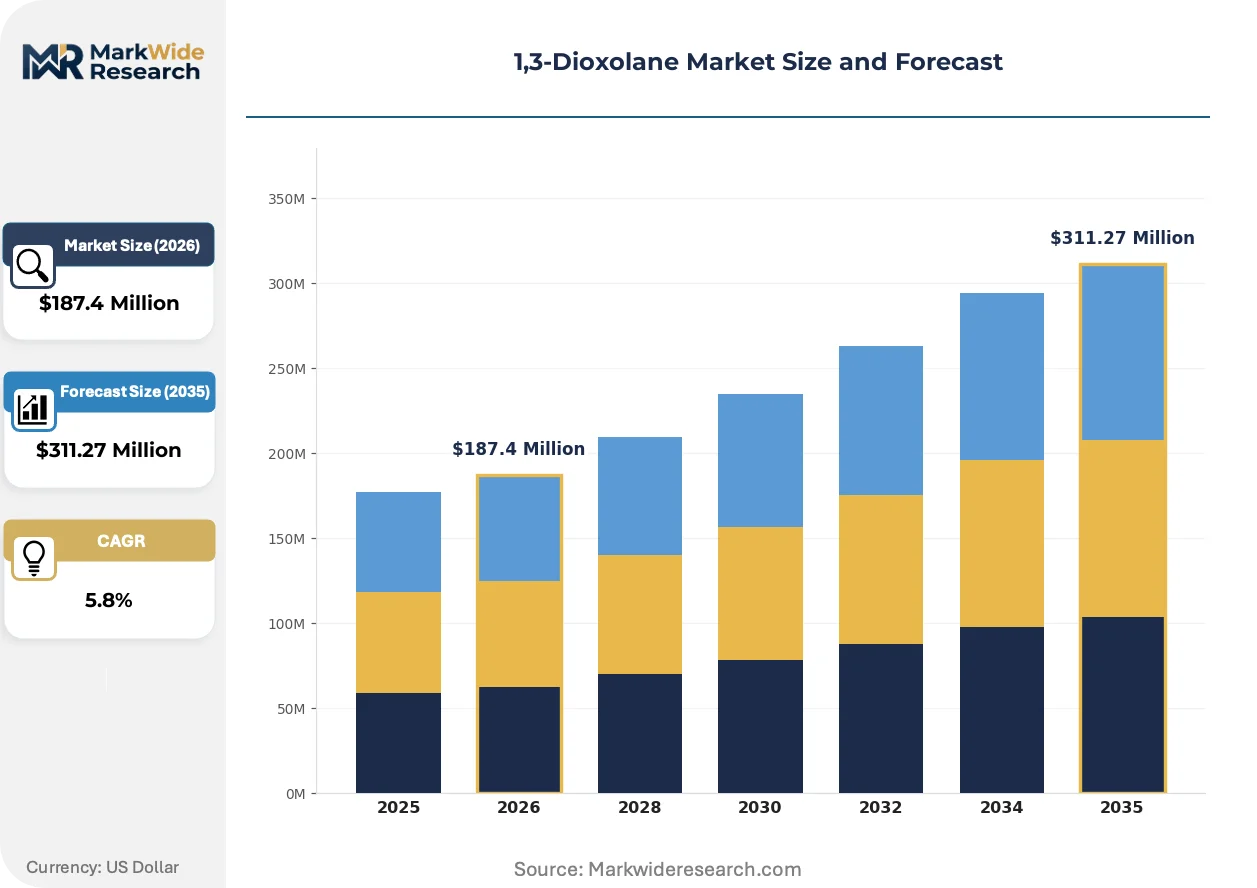
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Laboratory Grade, Pharmaceutical Grade, Reagent Grade Application: Solvents, Protic and Aprotic Reagents, Electrolytes, Additives End User: Chemical Manufacturers, Pharmaceuticals, Academics, Research Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | BASF Chemical Intermediates, Lambiotte & Cie S.A, Merck KGaA, Kairav Chemofarbe Industries Ltd., TCI Chemicals Pvt. Ltd., Chemdyes Corporation, Hefei TNJ Chemical Industry Co. Ltd., Henan DaKen Chemical Co. Ltd., FuYang Taian Chemical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
1,3-Dioxolane Market Evolving Landscape
Electrolyte formulation science is driving specification divergence between battery-grade and legacy industrial applications, fragmenting what was historically a commodity solvent category.
Molecular sieve dehydration technology is expanding into battery electrolyte supply chains as the dominant purification method for achieving sub-50 ppm moisture specifications. Korean and Japanese cell producers are mandating this specification tier for next-generation silicon-anode cells. The technology is expanding into mid-tier Chinese producers previously reliant on atmospheric distillation, compressing the viable supply base to firms with capital-intensive drying infrastructure.
REACH authorization list updates are forcing reformulation of electrolyte blends containing cyclic acetals with specific impurity profiles. European battery assemblers are now requiring Certificates of Analysis documenting absence of regulated substances at ppb thresholds. German and Polish cell manufacturers are responding by dual-sourcing from REACH-registered suppliers and maintaining buffer inventories to hedge against authorization delays.
Specification-driven purchasing is consolidating buyer power among tier-one electrolyte blenders capable of validating solvent quality in-house. Smaller battery producers are losing access to premium-grade supply as producers prioritize volume commitments from certified cell manufacturers. This concentration is most visible in China's Guangdong province, where Shenzhen-based electrolyte leaders have established direct offtake agreements with solvent producers, displacing traditional chemical distributor relationships.
1,3-Dioxolane Market Segmentation
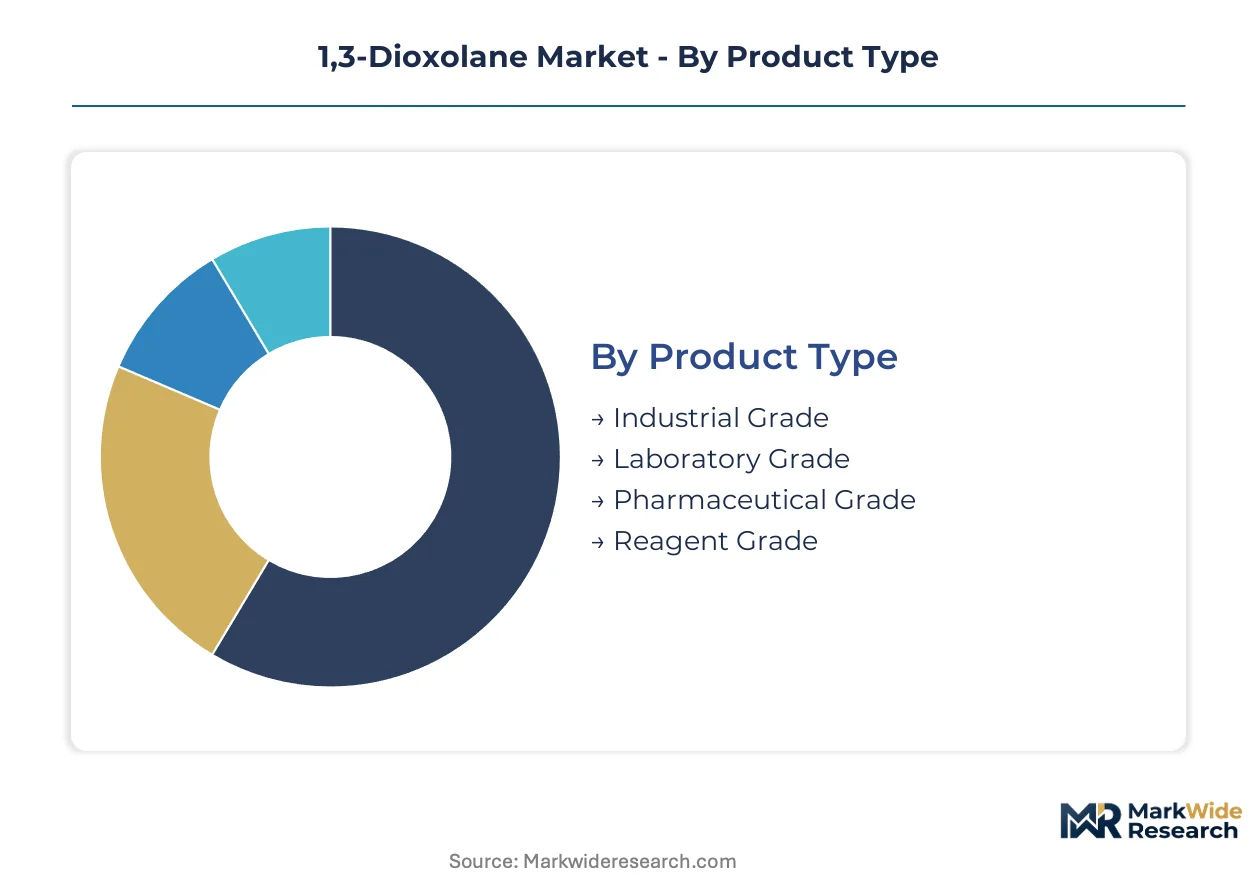
Grade purity tiers and application specifications fragment what was once a commodity solvent category. Each segment carries distinct certification burdens and margin profiles that reshape competitive positioning across battery, pharmaceutical, and industrial demand pools.
Product Type:
Industrial grade operates as a standalone commodity with minimal downstream integration requirements, while pharmaceutical and laboratory grades embed into tightly regulated formulation chains.
- Industrial Grade:Acid-catalyzed condensation yields material with 98-99% purity, sufficient for polymer synthesis and general chemical manufacturing. Chinese glycol processors in Jiangsu province dominate volume output, though MEE environmental inspections periodically constrain supply availability.
- Pharmaceutical Grade:FDA and EMA certification mandates sub-100 ppm total impurities with documented absence of regulated substances. CDSCO pathways in India remain underpenetrated relative to the country's expanding generic API manufacturing base.
- Laboratory Grade:Validated for analytical applications with Certificates of Analysis per batch.
- Reagent Grade:Ultra-high purity for specialized synthesis protocols.
Industrial grade leads volumes today; pharmaceutical grade is gaining share fastest.
Application:
Cost tiers separate commodity solvent use from premium electrolyte formulations where purity premiums command 3-5x pricing multiples.
- Electrolytes:Low-viscosity co-solvent properties enhance lithium-ion cell performance in silicon-anode architectures. Korean and Japanese producers mandate sub-50 ppm moisture specifications via molecular sieve dehydration, compressing the viable supply base to capital-intensive operators.
- Solvents:Polar aprotic characteristics serve polymer dissolution and extraction processes across chemical manufacturing. Demand concentrates in China's Ningbo industrial cluster where electrolyte blenders consume rising volumes.
- Protic and Aprotic Reagents:Functional group reactivity supports organic synthesis workflows.
- Additives:Stabilizer and co-solvent roles in specialty formulations.
Solvent applications anchor current revenue; electrolyte use is expanding most quickly.
End User:
Customer type determines procurement complexity, with chemical manufacturers prioritizing volume scale and pharmaceutical buyers demanding multi-jurisdiction certification packages.
- Chemical Manufacturers:Volume procurement with specification flexibility. East Asian acetal producers leverage integrated ethylene oxide pipelines to sustain margin stability under formaldehyde feedstock volatility.
- Pharmaceuticals:Excipient-grade requirements with simultaneous FDA, EMA, and CDSCO filing timelines extending product launch cycles. German and Polish cell manufacturers dual-source from REACH-registered suppliers to hedge authorization delays.
- Academics:Small-batch procurement with reagent-grade specifications.
- Research Institutions:Custom synthesis support and analytical validation services.
Chemical manufacturers dominate offtake today; pharmaceutical demand is climbing the fastest.
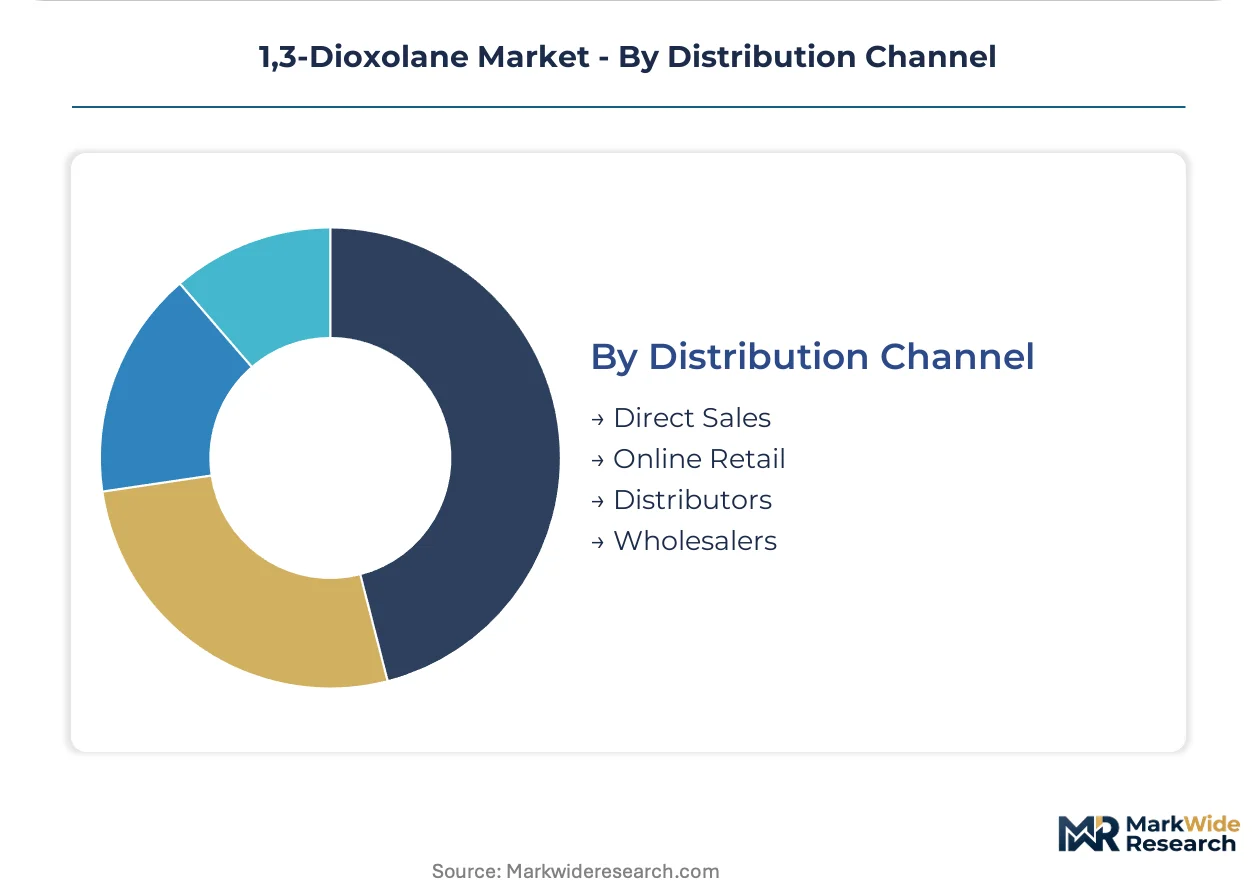
Distribution Channel:
Supply concentration favors direct relationships over intermediary networks as electrolyte blenders consolidate procurement power.
- Direct Sales:Volume commitments with solvent producers bypass traditional distributor margins. Shenzhen-based electrolyte leaders in Guangdong province have established direct offtake agreements, displacing chemical distributor relationships.
- Distributors:Regional inventory management for mid-tier battery producers losing access to premium-grade supply as producers prioritize certified cell manufacturers.
- Online Retail:Laboratory-scale procurement with rapid fulfillment.
- Wholesalers:Bulk aggregation for industrial-grade throughput.
Distributor networks handle majority volume today; direct sales channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized analytical chemists capable of validating trace impurity profiles concentrate in Germany, China, and the United States, anchoring regional quality infrastructure for high-purity solvent production.
China
Lithium-ion cell manufacturing and ethylene oxide derivatives processing dominate demand. MEE enforces dual carbon goals that constrain energy-intensive glycol processing in Jiangsu province. Shenzhen and Ningbo industrial clusters scale electrolyte blending capacity, consuming rising volumes of low-viscosity co-solvents.
Germany
REACH-registered suppliers serve European battery assemblers requiring Certificates of Analysis at ppb thresholds. ECHA's tightening impurity mandates for cyclic solvents pull through demand for pharmaceutical-grade certification. German cell manufacturers dual-source from compliant suppliers and maintain buffer inventories to hedge authorization delays.
United States
EPA emissions controls on acetal production facilities constrain formaldehyde feedstock availability for solvent manufacturing. The country's national pharmaceutical regulator maintains strict excipient-grade requirements for electrolyte applications. Domestic producers face capacity expansion limits under environmental oversight protocols.
India
Generic API manufacturing expansion creates underpenetrated demand for CDSCO-certified excipient-grade material. The country's national pharmaceutical regulator extends product launch timelines through multi-jurisdiction filing requirements. Gujarat and Maharashtra industrial corridors attract solvent distributors serving mid-tier pharmaceutical formulators.
Japan
Korean and Japanese cell producers mandate sub-50 ppm moisture specifications via molecular sieve dehydration for silicon-anode architectures. METI oversees industrial chemical standards that exceed baseline international specifications. Domestic electrolyte blenders prioritize direct procurement channels with REACH-registered suppliers.
1,3-Dioxolane Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive ethylene oxide supply. Three tiers separate multinational diversified producers, regional acetal specialists, and commodity glycol processors. Dominant competitive moves include backward integration into formaldehyde feedstock and purification technology licensing to achieve pharmaceutical-grade certification.
Within the multinational tier, BASF Chemical Intermediates and Merck KGaA exemplify divergent positioning strategies. BASF leverages integrated ethylene oxide pipelines to sustain margin stability, while Merck anchors its market presence through pharmaceutical-grade certification exceeding industrial specifications. Among Asian specialists, Kairav Chemofarbe Industries Ltd. occupies a volume-scale position across regional solvent markets.
| Leading Market Players |
|---|
| BASF Chemical Intermediates |
| Lambiotte & Cie S.A |
| Merck KGaA |
| Kairav Chemofarbe Industries Ltd. |
| TCI Chemicals Pvt. Ltd. |
| Chemdyes Corporation |
| Hefei TNJ Chemical Industry Co. Ltd. |
| Henan DaKen Chemical Co. Ltd. |
| FuYang Taian Chemical Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between pharmaceutical-grade and industrial-grade material manifests in both pricing premiums and supply chain configurations. REACH-registered producers in Germany command 3-5x multiples over commodity acetal suppliers in Jiangsu province, while direct procurement channels from Shenzhen electrolyte blenders compress distributor margins across the value chain.
Pricing Analysis
Pharmaceutical-grade certification bundles analytical validation services with base material, while industrial-grade transactions remain unbundled commodity spot purchases. Price differentiation stems from FDA/EMA documentation burdens and molecular sieve dehydration capital intensity. Cost compression in battery-grade tiers intensifies as Chinese electrolyte blenders consolidate procurement power. Mid-tier battery producers exhibit highest price sensitivity, whereas Korean silicon-anode cell manufacturers prioritize specification compliance over unit economics.
Supply Chain Analysis
Freight cost escalation from Jiangsu province to European battery assemblers amplifies the landed cost advantage of German REACH-registered suppliers. Supply concentrates in China, Germany, and the United States, with ethylene oxide derivatives and formaldehyde feedstock anchoring upstream dependencies. Single-source vulnerability to MEE environmental inspections in Jiangsu creates supply interruption risk. Distribution runs through direct offtake agreements for tier-one electrolyte blenders, with regional distributors serving price-sensitive mid-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization milestones function as demand compounding mechanisms, pulling pharmaceutical-grade certification requirements through European battery supply chains and reshaping procurement specifications globally.
For Market Incumbents: To counter propylene carbonate substitution in mid-tier battery formulations, BASF and Merck KGaA should deepen backward integration into formaldehyde feedstock and license molecular sieve dehydration technology to anchor premium positioning. Certification investment in simultaneous FDA, EMA, and CDSCO pathways defends margin structure against Asian volume competitors. For New Entrants and Emerging Players: Capture underpenetrated CDSCO-certified excipient demand in Gujarat and Maharashtra pharmaceutical corridors, where generic API manufacturing expansion outpaces qualified solvent supply. A go-to-market angle targeting mid-tier Indian formulators with abbreviated certification timelines offers viable entry before multinational incumbents complete regulatory filings. For Investors and Strategic Acquirers: Consolidation pressure builds where analytical chemistry talent scarcity constrains quality lab expansion and multi-jurisdiction certification timelines extend product launch cycles. Long-term viability favors acquisition targets with captive ethylene oxide supply and existing REACH registration. The signal to watch is ECHA authorization list updates that disqualify non-registered suppliers from European battery supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Formaldehyde Feedstock | Captive supply of acetal precursors insulates margin stability from EPA emissions controls on merchant formaldehyde. |
| Molecular Sieve Dehydration Capacity Expansion | Sub-50 ppm moisture specifications from Korean and Japanese cell producers compress viable supply base to capital-intensive operators. |
| Multi-Jurisdiction Certification Investment | Simultaneous FDA, EMA, and CDSCO filings extend product launch cycles but lock out commodity competitors from pharmaceutical-grade demand. |
| Direct Procurement Channel Development | Shenzhen-based electrolyte leaders bypassing distributor networks compress intermediary margin capture and anchor volume commitments. |
| REACH Registration Maintenance and Expansion | ECHA tightening impurity mandates for cyclic solvents entering European battery supply chains disqualifies non-registered suppliers. |
Research Methodology
Bottom-up electrolyte blender modeling reconciled against top-down ethylene oxide derivatives tracking forms the analytical core of this study. Primary interviews with solvent plant managers, procurement leads at battery OEMs, distribution channel partners, and technical R&D directors combined with secondary validation from customs/trade data, Cefic solvent reports, and SEC 10-K filings. Triangulation against bottom-up grade-tier demand and top-down production capacity estimates ensures statistical integrity.
Input-output matrices map grade purity tiers, end-use applications, and regional production hubs across the projection horizon. Segmentation dimensions include industrial/pharmaceutical/laboratory grade tiers, electrolyte versus solvent versus reagent applications, and chemical manufacturer versus pharmaceutical versus academic end users. CAGRs derive from elasticity-adjusted demand curves and capacity utilization trajectories, with lithium-ion cell manufacturing expansion and REACH authorization timelines as key forecast inputs.
Formaldehyde feedstock volatility, ECHA authorization delays, and MEE environmental inspection protocols are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context and regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
4-Tert-Amylphenol Market
Organic Chemicals
N-Hexyl Chloride Market
Organic Chemicals
Acrylonitrile Market
Organic Chemicals
Organic Coating Market
Organic Chemicals
Lithium Chemicals Market
Organic Chemicals
Gamma-Butyrolactone (GBL) Market
Organic Chemicals
Europe Cycloalkanes Market
Organic Chemicals
Global Biphenyl Market
Organic Chemicals
Benzethonium Chloride Market
Organic Chemicals
Absolute Ethanol Market
Organic Chemicals
Anisole Derivatives Market
Organic Chemicals
2-Amino-5-Nitrobenzophenone Market
Organic Chemicals
Chloro -Dimethylsilane (CAS 1066-35-9) Market
Organic Chemicals
Acetylacetone Market
Organic Chemicals
Cyclic Ketones Market
Organic Chemicals
Organic Matting Agent Market