
 Triacetate Cellulose Market | 2026-2036
Triacetate Cellulose Market Size, Share, and Industry Trends Forecast 2026-2036
Triacetate Cellulose Market Analytics
The fashion industry's appetite for triacetate cellulose is broadening as luxury apparel brands replace petroleum-based synthetics with biodegradable alternatives. Celanese leverages its acetyl chain integration to secure precursor supply for filament-grade production. Eastman Chemical Company sustains a dominant position in North American film and sheet markets through captive cellulose sourcing. Daicel Corporation anchors Asian supply for optical-grade triacetate used in polarizing films.
Triacetate cellulose is a cellulose ester derived from natural cellulose fully acetylated to approximately 43-44% acetyl content, typically dissolved in methylene chloride for casting into films or spun into fibers; its high optical clarity and moisture resistance make it indispensable for photographic films, LCD polarizer substrates, and premium textiles. Film-grade material commands the deepest margin pools due to stringent optical purity requirements and limited qualified supply, while fiber applications in fashion are expanding fastest as brands reformulate sustainability portfolios. Sheet and laminate segments remain mature with stable demand from automotive interior and decorative surfacing markets.
EPA chemical safety evaluations and REACH substance restrictions in Europe are elevating compliance costs for methylene chloride-based processing, pushing producers toward closed-loop solvent recovery systems. Japan's METI chemical management framework and South Korea's K-REACH alignment are tightening registration requirements for imported cellulose derivatives used in electronics applications. Stakeholders must monitor solvent regulation trajectories in major production jurisdictions to anticipate capital requirements for process retooling and qualification timelines for alternative chemistries.
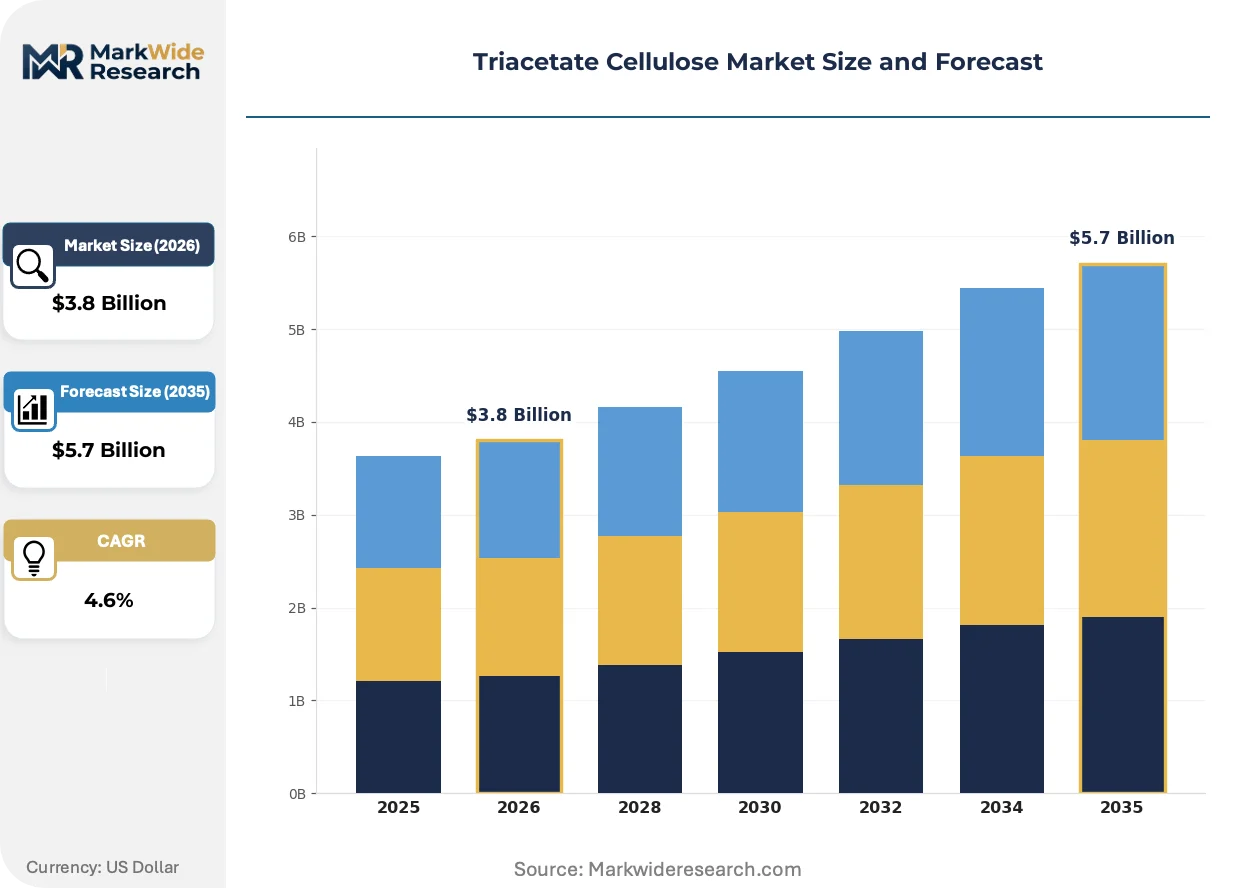
Market Dynamics
Regulatory pressure on methylene chloride processing is forcing capital reallocation toward closed-loop solvent recovery systems, while East Asian optical film demand concentrates manufacturing gravity in Japan and South Korea.
Growth Catalysts
- REACH substance restrictions:European chemical safety frameworks are accelerating qualification of alternative solvent chemistries for cellulose ester production.
- LCD polarizer substrates:Display panel manufacturers in South Korea and Japan are expanding optical-grade triacetate offtake for premium screen applications.
- Biodegradable textile demand:Luxury fashion houses are reformulating material portfolios to replace petroleum-based synthetics with cellulose-derived fibers.
Market Restraints
- Acetyl precursor concentration:Captive supply chains at major acetyl producers limit independent filament-grade manufacturing expansion.
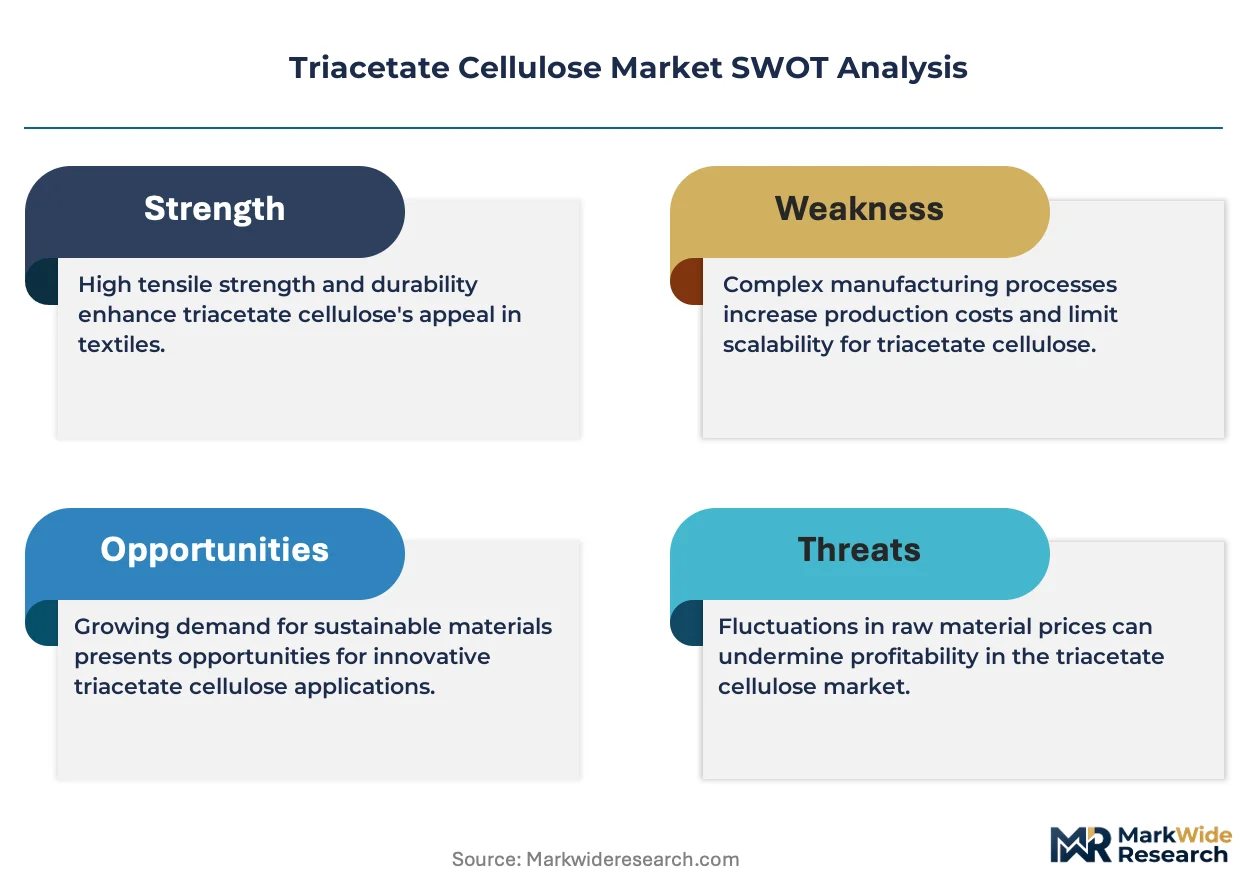
- Methylene chloride volatility:Feedstock cost swings and EPA chemical safety evaluations compress margin predictability for solvent-based processors.
- Optical purity thresholds:Stringent birefringence specifications for polarizing films restrict qualified supply to a narrow producer base.
Strategic Opportunities
- India textile manufacturing:BIS certification alignment and PLI scheme incentives are opening cellulose fiber capacity expansion for export-oriented apparel.
- Solvent-free casting technologies:Ionic liquid dissolution processes are converging with melt-spinning advances to eliminate methylene chloride dependency.
- Automotive interior laminates:Decorative surfacing specifications in premium vehicle segments are creating specification-grade sheet demand.
Industry Challenges
- Specialized polymer engineering talent:Cellulose ester formulation expertise resides at a handful of legacy producers, constraining new entrant technical staffing.
- Optical qualification timelines:Polarizer substrate certification requires 18-24 month validation cycles with display panel manufacturers.
- Solvent recovery capex:Closed-loop methylene chloride systems demand substantial front-loaded capital for regulatory compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triacetate Cellulose Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filament, Sheet, Film, Fiber Application: Textiles, Packaging, Coatings, Laminates End User: Fashion Industry, Automotive, Electronics, Home Furnishings Distribution Channel: Online Sales, Retail Stores, Wholesalers, Distributors |
| Companies Covered | Celanese, Eastman Chemical Company, Fujifilm Holdings Corporation, Merck KGaA, Agfa-Gevaert Group, Konica Minolta, The Eastman Kodak Company, Cayman Chemical, Daicel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triacetate Cellulose Market Evolving Landscape
Processing technology convergence and regulatory chemistry mandates are compressing the viable process window for conventional solvent-based production while enabling next-generation cellulose ester formats.
Ionic liquid dissolution technology is unifying cellulose regeneration with direct fiber spinning, eliminating separate casting and stretching stages. Specialty fiber producers in Japan are piloting continuous filament systems at commercial scale. This unifying architecture collapses capital intensity and solvent inventory requirements for mid-volume manufacturers.
EPA chemical safety evaluations under the Toxic Substances Control Act are tightening workplace exposure limits for methylene chloride in film casting operations. Processing facilities in the United States are retrofitting vapor recovery infrastructure to maintain operating licenses. Fiber-grade producers face lower compliance burdens than optical film specialists due to less stringent purity specifications.
Specification-driven procurement now dominates optical-grade triacetate purchasing, with display panel manufacturers consolidating qualified supplier lists to three or fewer approved sources. Long-term offtake agreements with fixed volume commitments are displacing spot market transactions. This concentration is most pronounced in South Korea, where Samsung Display and LG Display anchor regional demand.
Triacetate Cellulose Market Segmentation
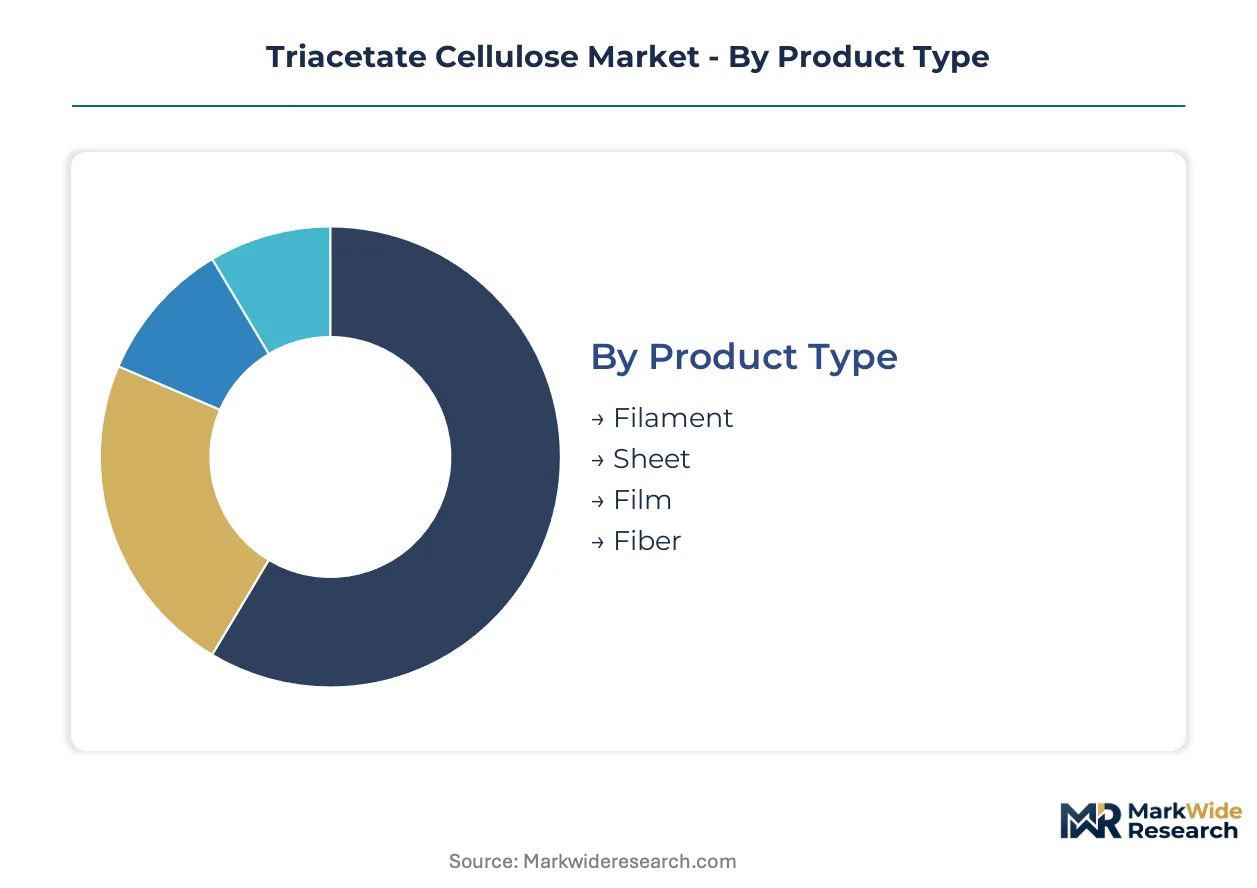
Triacetate cellulose buyers prioritize optical purity, biodegradability, or process compatibility depending on end-use. Segment boundaries blur as fiber-grade producers pivot toward fashion sustainability mandates and film specialists defend polarizer substrate qualifications.
Product Type:
Performance specifications and margin architecture vary sharply across physical formats, with optical-grade film commanding qualification premiums and filament products scaling through textile partnerships.
- Film:Cast from methylene chloride solutions to achieve sub-nanometer surface roughness and controlled birefringence. Samsung Display and LG Display in South Korea consolidate offtake for LCD polarizer substrates, locking suppliers into 18-24 month validation cycles.
- Fiber:Spun from cellulose ester dope into continuous filaments for luxury apparel applications. Italian and Japanese fashion houses source biodegradable alternatives to petroleum-based synthetics, with Daicel Corporation anchoring Asian supply.
- Filament:High-tenacity yarn for industrial textiles and premium sewing threads. Celanese leverages captive acetyl chain integration to secure precursor supply for filament-grade production.
- Sheet:Thermoformed laminates for automotive interior surfacing and decorative architectural panels. Eastman Chemical Company sustains dominant position in North American sheet markets through captive cellulose sourcing.
Volume sits with fiber and filament for textile scale; growth tilts toward film for display panel expansion.
Application:
End-use requirements dictate acetyl content tolerances, with packaging demanding moisture resistance and laminates prioritizing heat-formability.
- Textiles:Premium apparel and lining fabrics exploit triacetate's silk-like drape and dimensional stability. REACH compliance in Europe and evolving EPA standards tighten purity requirements for consumer-facing fiber products.
- Laminates:Decorative surfacing for automotive interiors and furniture. Japanese automotive specifications drive qualification complexity for exterior-grade weatherability.
- Packaging:Transparent blister packs and cosmetic containers leverage high clarity and grease resistance. BIS certification alignment in India opens capacity expansion for export-oriented packaging.
- Coatings:Protective finishes for photographic papers and specialty papers. Mature demand with stable replacement cycles in commercial printing segments.
Procurement concentrates in textiles for volume; specification-grade laminates capture margin expansion.
End User:
Customer technical capabilities and sustainability disclosure requirements fragment demand patterns across industrial buyers.
- Electronics:Display panel manufacturers in Japan and South Korea dominate optical-grade consumption. METI chemical management framework and K-REACH alignment tighten registration requirements for imported cellulose derivatives.
- Fashion Industry:Luxury houses reformulate material portfolios to meet Science Based Targets initiative commitments. Biodegradable fiber demand from LVMH and Kering supply chains accelerates filament qualification.
- Automotive:Interior trim suppliers specify heat-resistant laminates for dashboard and door panel applications. German OEMs lead technical specification development through KBA material approval processes.
- Home Furnishings:Upholstery and decorative surfacing for residential and contract furniture. Price-sensitive procurement competes with PVC and PET alternatives on total installed cost.
Electronics anchors value concentration; fashion industry procurement expands most quickly on sustainability mandates.
Distribution Channel:
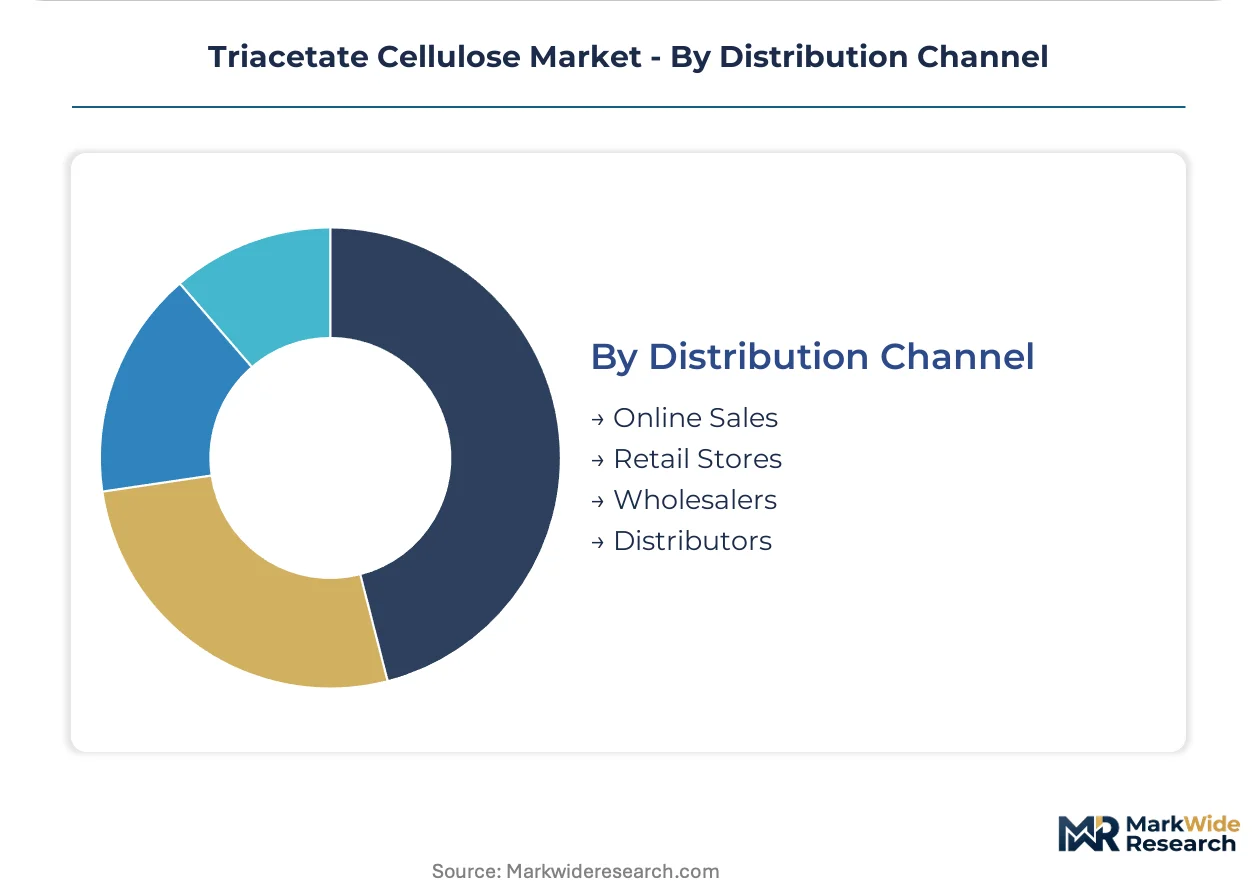
Order scale and technical service intensity determine channel selection, with qualified film moving through direct supply agreements.
- Distributors:Regional inventory holders serve mid-volume textile and packaging converters with standard grades. Japanese and South Korean distributors maintain optical film consignment stocks for qualified display panel suppliers.
- Wholesalers:Bulk handlers of fiber and sheet products for downstream processing into yarns and laminates. European wholesalers manage REACH documentation chains for imported cellulose esters.
- Online Sales:Sample ordering and small-lot procurement for R&D and specialty coating applications. Limited to non-qualified grades lacking polarizer substrate certification.
- Retail Stores:Direct consumer sales of triacetate-based products rather than raw materials. Negligible channel share for industrial cellulose ester procurement.
Qualified film bypasses distribution entirely; fiber and sheet flow through wholesaler networks for processing scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in East Asia drive manufacturing concentration for triacetate cellulose, with Japan's coastal industrial corridors and South Korea's display panel clusters anchoring optical-grade production capacity. European REACH enforcement and U.S. EPA chemical safety evaluations reshape compliance investment patterns across legacy production bases.
Japan
Optical film demand from display manufacturers concentrates acetyl cellulose capacity in the Chubu and Kansai regions. METI's chemical management framework tightens registration requirements for imported cellulose derivatives used in electronics. Nagoya-based production clusters scale specialty fiber systems for luxury textile export.
South Korea
Samsung Display and LG Display anchor LCD polarizer substrate consumption in the Gyeonggi-Seoul corridor. K-REACH alignment with EU chemical safety standards elevates purity documentation burdens for cellulose ester importers. Busan-Ulsan petrochemical complexes feed precursor supply for captive triacetate manufacturing.
United States
Eastman Chemical's Tennessee operations sustain North American film and sheet dominance through captive cellulose sourcing. EPA chemical safety evaluations under TSCA tighten workplace exposure limits for methylene chloride in casting operations. Kingsport processing facilities retrofit vapor recovery infrastructure to maintain operating licenses.
Germany
Automotive interior laminate specifications from BMW and Mercedes-Benz drive specification-grade sheet demand in Baden-Württemberg. KBA material approval processes govern heat-resistant dashboard and door panel applications. Ludwigshafen chemical corridors integrate acetyl chain supply for downstream cellulose ester production.
India
PLI scheme incentives and BIS certification alignment open cellulose fiber capacity expansion for export-oriented apparel in Gujarat and Maharashtra. Textile manufacturing clusters in Surat and Mumbai reformulate sustainability portfolios toward biodegradable alternatives. Central government production-linked incentives accelerate filament-grade qualification timelines for European fashion house supply chains.
Triacetate Cellulose Market Competitive Landscape
Top-tier vendors anchor optical-grade film supply, while mid-scale processors compete on textile fiber volume and laminate sheet specifications. The producer base stratifies sharply around acetyl precursor access and polarizer substrate qualification status. Strategic archetypes include captive acetyl chain integrators, display panel-qualified optical specialists, and fashion-focused fiber spinners. Competitive moves center on backward integration into cellulose sourcing and 18-24 month validation cycles with electronics manufacturers.
Among Japanese and U.S.-based chemical conglomerates, Fujifilm Holdings Corporation, Eastman Chemical Company, and Daicel Corporation exemplify divergent strategic positions. Fujifilm occupies a position within legacy photographic material specialists pivoting toward display applications. Eastman Chemical represents North American captive supply chain integration. Daicel Corporation anchors Asian optical-grade capacity for polarizing film substrates. These three entities collectively illustrate how geographic concentration, precursor control, and end-use qualification status determine competitive positioning in constrained supply environments.
| Leading Market Players |
|---|
| Celanese |
| Eastman Chemical Company |
| Fujifilm Holdings Corporation |
| Merck KGaA |
| Agfa-Gevaert Group |
| Konica Minolta |
| The Eastman Kodak Company |
| Cayman Chemical |
| Daicel Corporation |
| Others |
Value Network & Pricing Analysis
Cellulose pulp price indices and methylene chloride spot benchmarks cascade through triacetate cellulose supply chains into three-tier pricing structures across premium, standard, and economy levels. Optical-grade film commands qualification premiums tied to polarizer substrate certification timelines, while fiber-grade products compete on volume scale and sustainability credentials.
Pricing Analysis
Short lead-time premiums reward qualified suppliers holding consignment inventory near Samsung Display and LG Display facilities, while spot inventory discounts clear non-certified material. Three-tier pricing structure across premium, standard, and economy levels separates optical-grade film from textile fiber and commodity sheet products. Cost compression in fiber-grade segments is intensifying because Indian textile clusters scale biodegradable alternatives under PLI scheme incentives. Fashion industry buyers exhibit highest price sensitivity due to substitution elasticity with viscose and lyocell fibers, whereas electronics manufacturers accept premium pricing for validated polarizer substrate supply.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from display panel manufacturers, bypassing distributor markups for qualified optical film. Manufacturing gravity centers on Japan, South Korea, and the United States, with Nagoya and Gyeonggi-Seoul corridors anchoring optical-grade capacity. Raw material flows draw from cotton linters, wood pulp, and acetic anhydride feedstocks. Single-source vulnerability concentrates in methylene chloride solvent supply for casting operations. Distribution runs through regional wholesalers for fiber and sheet products serving mid-volume textile converters and automotive laminate processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Triacetate cellulose markets are transitioning from solvent-based casting toward ionic liquid dissolution technologies that eliminate methylene chloride dependency. This chemistry shift is reshaping competitive positioning and capital allocation priorities across the producer base.
For Market Incumbents: Lock in long-term offtake agreements with display panel manufacturers before alternative substrate technologies mature. Secure captive cellulose sourcing through backward integration into pulp supply chains. Celanese and Eastman Chemical demonstrate how acetyl chain control defends margin position against feedstock volatility. Invest in closed-loop solvent recovery systems to preempt EPA enforcement actions and METI registration requirements.
For New Entrants and Emerging Players: E-commerce sample ordering platforms open low-friction entry for specialty coating and R&D-grade material supply. Target Indian textile manufacturing clusters in Surat and Mumbai where BIS certification alignment and PLI scheme incentives reduce qualification barriers. Partner with European fashion houses seeking biodegradable fiber alternatives to petroleum-based synthetics. Avoid direct competition in optical-grade film where validation timelines and qualified supplier lists create insurmountable entry barriers.
For Investors and Strategic Acquirers: The window for entry favors mid-scale fiber producers with solvent-free processing pilots and established textile industry relationships. Acquirers should target assets with ionic liquid dissolution technology convergence and captive pulp sourcing arrangements. Monitor EPA chemical safety evaluation timelines and METI solvent restriction announcements as inflection indicators for process technology substitution rates. Long-term viability hinges on qualification status with electronics manufacturers and sustainability certification alignment with luxury fashion supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cellulose Sourcing | Eastman Chemical's Tennessee captive pulp supply secures precursor cost stability against commodity volatility. |
| Closed-Loop Solvent Recovery Installation | Kingsport facility retrofits meet EPA TSCA workplace exposure limits for methylene chloride casting operations. |
| Ionic Liquid Dissolution Pilot Scale-Up | Japanese specialty fiber producers collapse capital intensity by unifying regeneration with direct spinning stages. |
| Long-Term Polarizer Substrate Offtake Agreement | Samsung Display and LG Display lock qualified suppliers into fixed volume commitments displacing spot transactions. |
| PLI Scheme-Aligned Capacity Expansion | Indian government incentives accelerate filament-grade qualification timelines for European fashion house supply chains. |
Research Methodology
Trade flow databases, SEC 10-K chemical segment disclosures, and METI chemical management registration records formed the secondary backbone for supply-side calibration. Primary interviews with plant managers at acetyl production facilities, procurement leads at display panel manufacturers, distribution channel partners in East Asian optical film markets, and technical R&D directors at cellulose ester processors validated capacity and qualification timelines. Bottom-up and top-down triangulation reconciled filament-grade production estimates against textile industry fiber consumption surveys.
Bottom-up modeling aggregated segment-level volume assumptions across film, fiber, filament, and sheet product categories, while top-down analysis cross-checked aggregate market value against acetyl chain revenue disclosures. Segmentation dimensions included optical purity grade, end-use application, acetyl content specification, and regional manufacturing hub. CAGRs were derived from regression analysis of historical cellulose ester pricing against pulp and solvent input cost trajectories. Forecast inputs incorporated K-REACH alignment timelines and EPA chemical safety evaluation schedules.
The model holds under stable solvent regulatory trajectories; deviation in methylene chloride restriction schedules or ionic liquid technology cost curves would shift capacity investment patterns and qualification timelines. Forecasts reflect documented assumptions regarding display panel demand elasticity and fashion industry sustainability commitment durability. Periodic stress-testing of base assumptions is recommended against METI and EPA enforcement action frequencies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Continuous Fiber Thermoplastic (CFT) Market
Fibers
Fiberglass Sunscreen Market
Fibers
Vinylon Market
Fibers
Global R-Glass Fiber Market
Fibers
Global Fiberglass Mold Market
Fibers
Keratin Market
Fibers
Polytetrahydrofuran Market
Fibers
Viscose Market
Fibers
Viscose Filament Yarn Market
Fibers
Drug Integrated Polymer Fibers Market
Fibers
Asia-Pacific Optical Fiber Raw Material Market
Fibers
Carbon Fiber Market
Fibers
Ultra-High Molecular Weight Polyethylene Fibers Market
Fibers
High Performance Fibers for Defense Market
Fibers
Global Perfluorinated Type Plastic Optical Fiber Market
Fibers
Carbon Fiber Filament Market