
 High Performance Fibers for Defense Market | 2026-2036
High Performance Fibers for Defense Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Fibers for Defense Market Foresight
Multi-source procurement of aramid and UHMWPE precursors is recalibrating how prime contractors manage supply security for body armor programs. DuPont leverages its integrated Kevlar manufacturing chain to sustain domestic qualification advantages for US military contracts. Toray Industries anchors Asian carbon fiber supply for aerospace-defense hybrid structures. Honeywell International dominates Spectra fiber production for helmet and plate applications, competing on specific strength metrics against European aramid alternatives.
High performance fibers for defense encompass synthetic filaments engineered to tensile strengths exceeding 3 GPa with low areal density, manufactured through gel-spinning, dry-jet wet spinning, or pyrolysis processes for ballistic energy absorption and structural reinforcement. Aramid retains the largest volume position in body armor inserts where cost-performance balance favors established vest designs, while ultra-high molecular weight polyethylene captures the fastest growth in helmet and maritime platform applications due to its superior strength-to-weight ratio. Carbon fiber concentrates margin pools in vehicle armor and aerospace-defense composites where intermediate modulus grades command premium qualification timelines.
FDA standards for occupational protective equipment, NHTSA guidelines on blast mitigation for tactical vehicles, and ISO 14800 ballistic test protocols collectively shape fiber specification requirements and market access conditions for defense suppliers. The Department of Defense's Berry Amendment compliance mandates domestic sourcing percentages that restrict non-US fiber producers from certain contract tiers. Stakeholders must monitor evolving NIJ threat level certifications and congressional appropriations for next-generation soldier protection to anticipate procurement shifts between aramid and polyethylene fiber platforms.
Market Dynamics
The shift from steel plate to composite armor systems is restructuring procurement priorities across military vehicle programs and personal protection equipment, with fiber manufacturers racing to qualify lighter alternatives under accelerated defense modernization timelines.
Growth Catalysts
- Berry Amendment compliance:The Department of Defense's domestic sourcing mandates channel federal contracts toward US-based aramid and UHMWPE production facilities, insulating qualified suppliers from import competition.
- NIJ threat level upgrades:Evolving ballistic certification standards for body armor inserts are compelling militaries to replace legacy vest inventories with next-generation fiber composites rated against armor-piercing ammunition.
- Maritime platform lightweighting:Naval architects are specifying ultra-high molecular weight polyethylene for shipboard ballistic protection to reduce topside weight and improve vessel stability margins.
Market Restraints
- Petrochemical feedstock volatility:UHMWPE production depends on ethylene-derived precursors whose pricing fluctuates with crude oil markets, compressing margin predictability for gel-spinning operations.
- Carbon fiber supply concentration:Aerospace-grade intermediate modulus fiber for vehicle armor applications sources primarily from Japanese and US producers, creating single-point vulnerability for defense contractors.
- Aramid thermal degradation limits:Para-aramid fibers lose tensile strength above 400°C, restricting their deployment in engine compartment armor or hypersonic vehicle structures where ablative ceramics outperform.
Strategic Opportunities
- India defense indigenization:The country's PLI scheme for specialty fibers offers tariff advantages to domestic manufacturers supplying the Ministry of Defence's import substitution targets for soldier protection systems.
- Helmet-integrated electronics convergence:Fiber-reinforced composite shells are accommodating embedded power and data pathways for augmented reality displays, opening adjacent revenue streams in soldier modernization programs.
- EU Green Deal procurement criteria:Emerging sustainability mandates for defense equipment are favoring fiber producers with verified lifecycle carbon footprints in European tender evaluations.
Industry Challenges
- Ballistic test facility bottlenecks:ISO 14800 certification queues at accredited laboratories extend qualification timelines for new fiber formulations, delaying contract awards.
- Multi-material integration complexity:Hybrid armor systems combining UHMWPE, aramid, and ceramic layers require specialized bonding processes that few Tier-2 fabricators have mastered at production scale.
- Skilled gel-spinning technician scarcity:The proprietary knowledge base for ultra-high molecular weight polyethylene fiber production concentrates among retiring cohorts at established facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Performance Fibers for Defense Market |
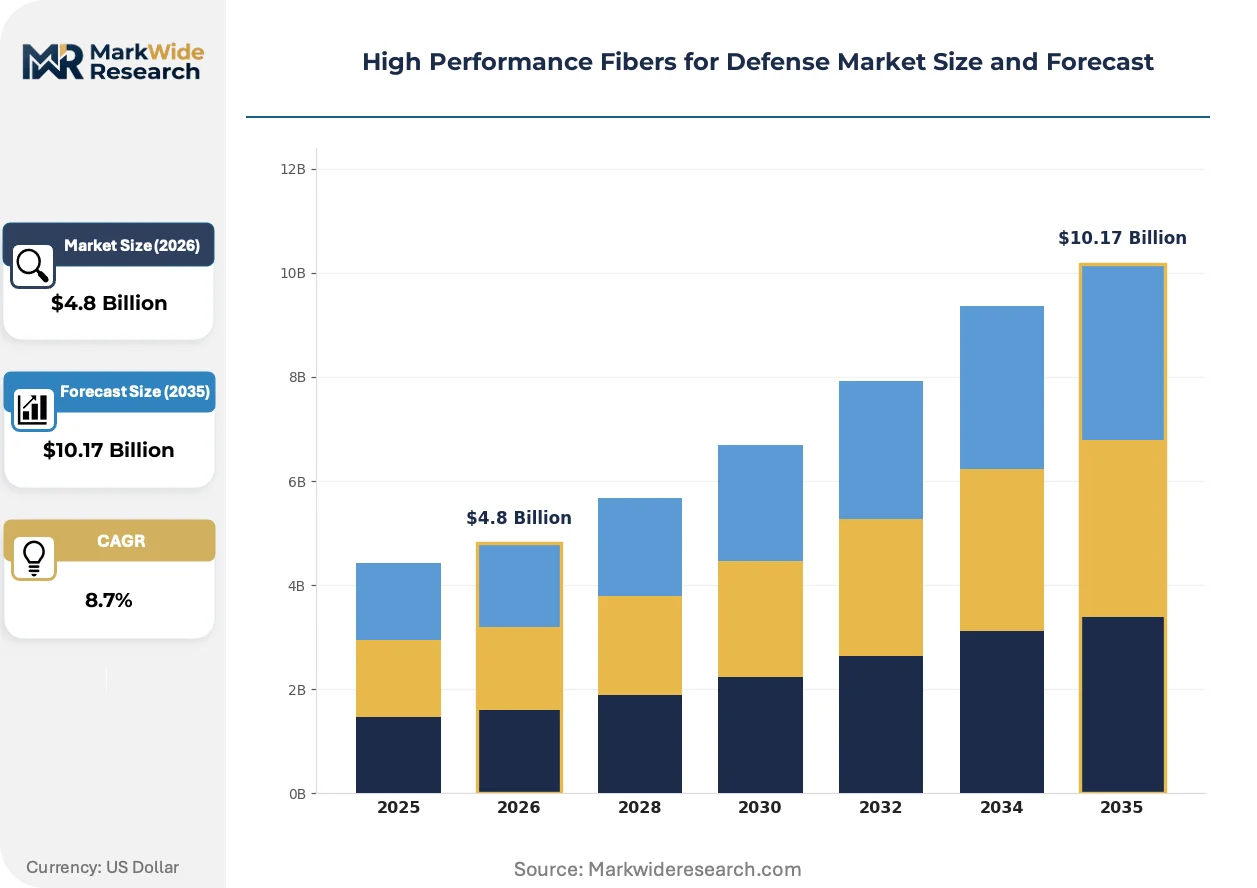
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aramid, Carbon Fiber, Glass Fiber, Ultra-High Molecular Weight Polyethylene End User: Military, Aerospace, Law Enforcement, Security Firms Application: Body Armor, Ballistic Shields, Vehicle Armor, Tactical Gear Manufacturing Stage: Raw Material, Intermediate, Finished Product, Composite |
| Companies Covered | Honeywell International, Mitsubishi Chemical Corporation, Toray Industries, TOYOBO, Solvay, DuPont, Hexcel Corporation, Kolon Industries, Teijin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Fibers for Defense Market Shifts & Advancements
Defense fiber markets are converging around three vectors: molecular engineering for strength-to-weight gains, regulatory pressure for domestic supply security, and procurement reform favoring integrated system suppliers over commodity vendors.
Multi-axial non-crimp fabric architectures are absorbing blast energy more efficiently than unidirectional tapes in vehicle underbody protection, prompting armor integrators to retool layup automation for complex curvature panels. Marine Corps Systems Command has accelerated qualification of these textiles for joint light tactical vehicle programs. The technology is absorbing market share from welded aluminum appliqué armor in wheeled platform retrofits.
REACH authorization requirements for chemical precursors are constraining European aramid producers' feedstock flexibility, forcing reformulation of spinning dopes to eliminate Substances of Very High Concern. ECHA's evolving candidate list is pushing manufacturers toward bio-based alternatives in pilot production lines. German and French defense procurement agencies are now requiring SVHC-free declarations for soldier equipment tenders.
Multi-year indefinite delivery contracts are displacing annual spot purchases for body armor programs, concentrating volume with fiber suppliers willing to hold finished goods inventory under vendor-managed stock agreements. The US Army's PEO Soldier has pioneered this approach for next-generation helmet procurements. This pattern is most visible in Department of Defense personal protection modernization budgets, where prime contractors now bear carrying costs previously absorbed by government depots.
High Performance Fibers for Defense Market Segmentation
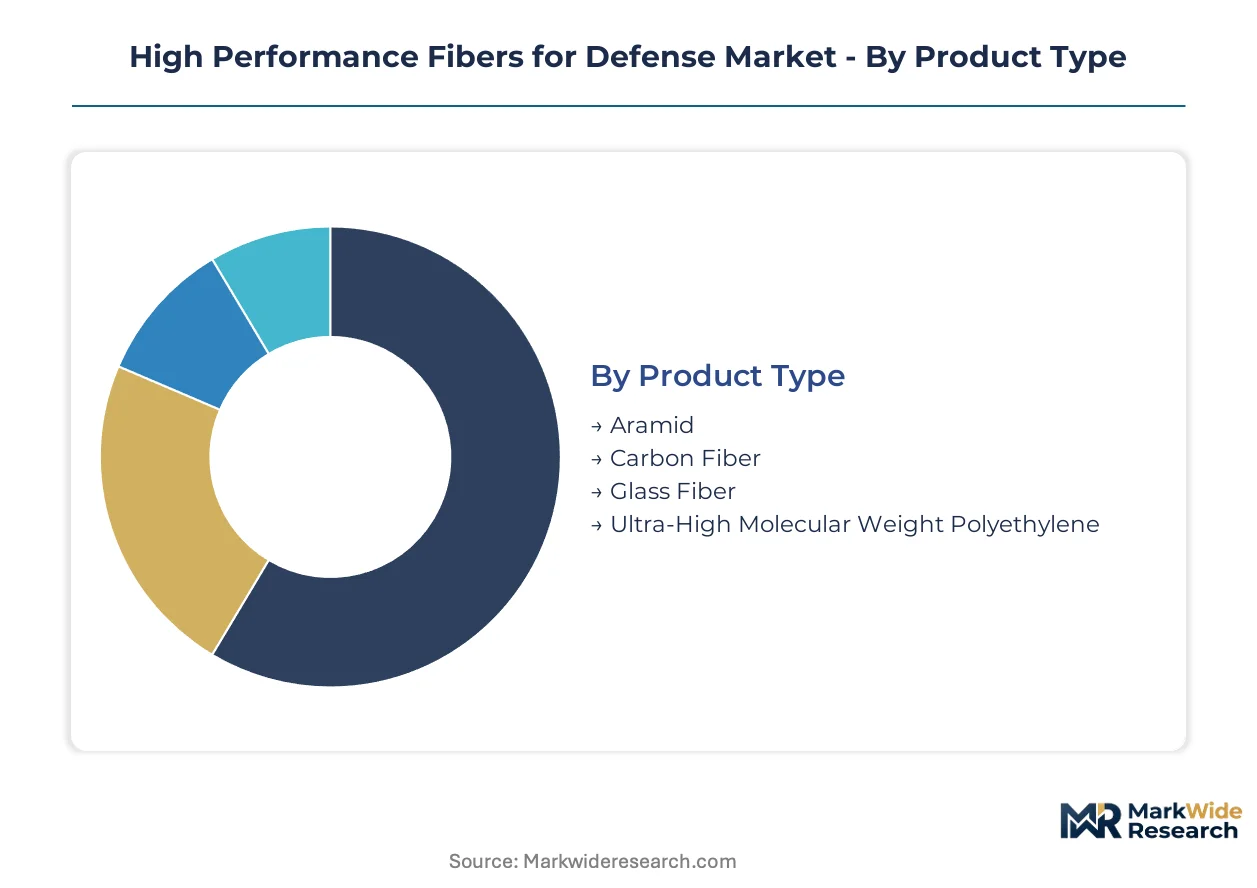
Defense procurement decisions split across fiber chemistry, end-user mission profiles, and manufacturing integration depth. Each segmentation axis reveals distinct margin structures and qualification barriers that reshape how suppliers compete for military contracts.
Product Type:
Cost-performance tradeoffs dominate material selection, with threat-level requirements and weight budgets forcing explicit comparisons between established aramid and emerging polyethylene platforms.
- Aramid:Para-aramid fibers spun from aromatic polyamides deliver tensile strength above 3 GPa with inherent flame resistance. The US Army's PEO Soldier continues specifying aramid for soft armor vests where decades of ballistic data support contractual risk mitigation.
- Ultra-High Molecular Weight Polyethylene:Gel-spun UHMWPE achieves strength-to-weight ratios exceeding aramid by 40%, driving its displacement of legacy materials in maritime ballistic protection where topside weight reduction improves vessel stability margins.
- Carbon Fiber:Intermediate modulus grades from pyrolysis of polyacrylonitrile precursors anchor structural armor for tactical vehicles.
- Glass Fiber:E-glass and S-glass variants serve cost-sensitive spall liners and training equipment.
Volume sits with aramid; growth tilts toward ultra-high molecular weight polyethylene.
End User:
Mission-criticality and budget scale separate procurement patterns across institutional buyers.
- Military:Department of Defense modernization programs underwrite multi-year indefinite delivery contracts for next-generation soldier protection systems, with Berry Amendment compliance mandating domestic fiber sourcing.
- Law Enforcement:NIJ threat-level certifications govern municipal and state agency purchases of body armor and tactical shields, creating fragmented demand across thousands of independent procurement offices.
- Aerospace:Defense contractors integrate carbon fiber composites into airframe structures requiring FAA airworthiness qualifications alongside military specifications.
- Security Firms:Private sector demand concentrates in executive protection and critical infrastructure guarding where commercial insurance mandates drive equipment standards.
Contract value concentrates with military; procurement velocity favors law enforcement.
Application:
Ballistic threat environment and mobility requirements dictate fiber specification intensity.
- Body Armor:Soft armor panels for fragmentation protection and hard armor plates for rifle threats demand distinct fiber architectures, with polyethylene capturing helmet applications and aramid retaining soft vest dominance.
- Vehicle Armor:Multi-axial non-crimp fabrics replace welded aluminum appliqué in joint light tactical vehicle retrofits, absorbing blast energy through composite deformation rather than metallic fracture.
- Ballistic Shields:Handheld and deployed shield systems prioritize areal density for tactical mobility.
- Tactical Gear:Load-bearing equipment and helmet-mounted systems integrate fiber reinforcement for weight reduction.
Platform integration complexity peaks with vehicle armor; unit volume concentrates in body armor.
Manufacturing Stage:
Supply chain positioning determines margin capture and qualification burden for fiber producers.
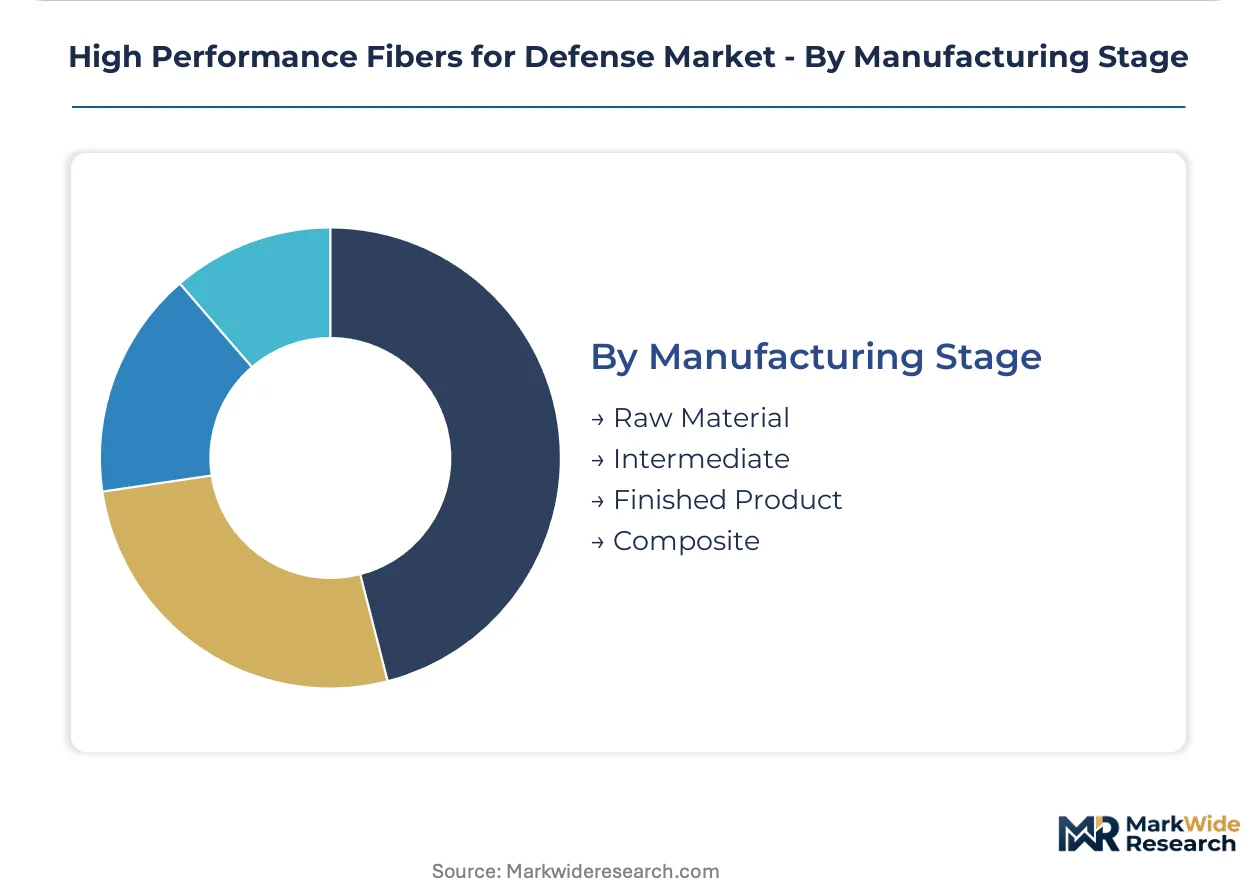
- Raw Material:Petrochemical-derived precursors—p-phenylenediamine for aramid, ethylene for UHMWPE, acrylonitrile for carbon fiber—face feedstock volatility that compresses margin predictability for non-integrated producers.
- Intermediate:Yarn spinning, tow processing, and fabric weaving constitute the primary value-add steps where proprietary gel-spinning or pyrolysis expertise creates defensible positions.
- Finished Product:Cut-and-sewn armor panels and pre-formed helmet shells require ISO 14800 ballistic certification queues that extend qualification timelines.
- Composite:Hybrid systems bonding UHMWPE, aramid, and ceramic layers demand specialized fabrication capabilities few Tier-2 suppliers have mastered at production scale.
Margin pools concentrate at intermediate processing; systems integration captures premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Department of Defense procurement channels concentrate global demand for high performance defense fibers within the United States, where Berry Amendment compliance mandates reshape supplier qualification pathways. Military modernization budgets in Western Europe and Indo-Pacific allies are accelerating parallel sourcing strategies.
United States
PEO Soldier modernization programs and Marine Corps Systems Command vehicle retrofits drive aramid and UHMWPE consumption. Berry Amendment domestic sourcing requirements restrict federal contract access to US-based fiber production facilities. The mid-Atlantic industrial corridor anchors integrated Kevlar and Spectra manufacturing chains serving Pentagon qualification timelines.
China
Domestic carbon fiber capacity expansion targets aerospace-defense hybrid structures under MIIT industrial policy guidance. GB standards for ballistic protection equipment create parallel certification pathways distinct from ISO protocols. The Yangtze River Delta concentration hosts gel-spinning operations supplying People's Liberation Army equipment modernization.
Germany
ECHA REACH authorization constraints on aramid precursors force spinning dope reformulation across specialty fiber producers. KBA vehicle safety regulations extend blast mitigation standards to tactical platform exports. The Baden-Württemberg industrial cluster maintains pyrolysis expertise for intermediate modulus carbon fiber serving Bundeswehr vehicle armor programs.
Japan
METI strategic material designations prioritize domestic carbon fiber supply security for aerospace-defense applications. JIS ballistic test protocols create qualification alternatives to ISO 14800 for regional procurement. The Chubu/Nagoya manufacturing belt concentrates Toray Industries' PAN precursor-to-tow integration serving Asia-Pacific defense contractors.
India
Ministry of Defence import substitution targets under the PLI scheme for specialty fibers attract domestic manufacturing investment. BIS certification requirements for soldier protection equipment establish local qualification barriers. Tamil Nadu and Gujarat industrial corridors host emerging gel-spinning capacity targeting paramilitary and police force modernization budgets.
High Performance Fibers for Defense Market Competitive Landscape
Capacity expansion dominates the current landscape as fiber manufacturers race to qualify lighter alternatives under accelerated defense modernization timelines. The supplier base concentrates around three tiers: integrated petrochemical giants with captive precursor supply, specialized gel-spinning and pyrolysis operators with proprietary process knowledge, and regional fabricators serving domestic qualification requirements. Strategic archetypes include upstream-integrated chemical conglomerates, technology-licensed regional producers, and defense-prime captive fiber operations. M&A activity and strategic partnerships constitute the dominant competitive moves, with technology licensing agreements bridging capability gaps for emerging market entrants.
Among US-based chemical conglomerates, DuPont and Honeywell International occupy positions reflecting integrated manufacturing chain advantages for domestic military qualification. Toray Industries anchors Japanese carbon fiber supply serving aerospace-defense hybrid structures. European specialty chemical producers including Solvay and Teijin Limited exemplify REACH-compliant aramid and carbon fiber positioning for NATO procurement channels. Korean and Chinese manufacturers represent capacity expansion vectors targeting Indo-Pacific defense indigenization programs.
| Leading Market Players |
|---|
| Honeywell International |
| Mitsubishi Chemical Corporation |
| Toray Industries |
| TOYOBO |
| Solvay |
| DuPont |
| Hexcel Corporation |
| Kolon Industries |
| Teijin Limited |
| Others |
Supply & Pricing Matrix
Department of Defense Berry Amendment compliance mandates for domestic fiber sourcing are forcing prime contractors to absorb qualification premiums for US-based aramid and UHMWPE production, compressing margin pools at intermediate processing stages while elevating pricing power for integrated domestic manufacturers.
Pricing Analysis
Volume concentrates in standard-grade aramid for soft armor vests where decades of ballistic data support contractual risk mitigation, while margins pool in aerospace-grade intermediate modulus carbon fiber where qualification timelines stretch procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates NIJ Level IV certified plates from Level IIIA soft panels and training-grade spall liners. Cost compression in standard aramid is intensifying because of multi-year indefinite delivery contracts displacing spot purchases. Law enforcement agencies exhibit highest price sensitivity due to fragmented municipal procurement budgets, while aerospace-defense contractors show lowest sensitivity given airworthiness qualification requirements.
Supply Chain Analysis
Freight costs for gel-spun UHMWPE precursor shipments from the US Gulf Coast to mid-Atlantic armor fabrication facilities add meaningful landed cost premiums that disadvantage non-integrated producers against Honeywell's Spectra manufacturing chain. Supply concentrates in the United States for Berry-qualified aramid and UHMWPE, Japan for aerospace-grade carbon fiber, and China for expanding gel-spinning capacity serving domestic defense modernization. Raw material dependencies span p-phenylenediamine for aramid, ethylene-derived precursors for UHMWPE, and polyacrylonitrile for carbon fiber. Single-source vulnerability concentrates in Japanese intermediate modulus fiber for vehicle armor applications. Distribution runs through defense prime contractors holding vendor-managed inventory under multi-year indefinite delivery contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled gel-spinning technician scarcity at established facilities props pricing for qualified UHMWPE output, constraining supply expansion despite accelerating helmet and maritime platform demand.
For Market Incumbents: Cement qualification advantages by deepening captive precursor supply for Berry Amendment compliance and accelerating ISO 14800 certification queue investments to extend lead times against emerging Asian gel-spinning capacity. Threat substitution from Chinese carbon fiber expansion in aerospace-defense hybrids demands defensive positioning in intermediate modulus grades. For New Entrants and Emerging Players: Direct-to-defense-prime digital procurement platforms offer bypass routes around established distributor relationships for specialty fiber qualifications. White-space targets concentrate in India's PLI scheme for specialty fibers and EU Green Deal procurement criteria favoring verified lifecycle carbon footprints. The most penetrable segment is maritime platform lightweighting where UHMWPE displaces legacy materials. For Investors and Strategic Acquirers: The window for entry favors integrated petrochemical conglomerates with captive ethylene supply and established gel-spinning process knowledge. Long-term viability across the projection horizon rests on securing Department of Defense indefinite delivery contract positions before qualification timelines extend further. Watch for congressional appropriations shifts between aramid and polyethylene fiber platforms as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive p-phenylenediamine and ethylene supply secures Berry Amendment compliance margins against import competition. |
| ISO 14800 Certification Investment | Accredited ballistic test facility access accelerates qualification timelines for next-generation fiber formulations. |
| Long-term Supply Agreement | Multi-year indefinite delivery contracts with PEO Soldier concentrate volume and shift inventory carrying costs. |
| Joint Venture for Regional Capacity | India PLI scheme partnerships access Ministry of Defence import substitution targets for soldier protection systems. |
| Green Manufacturing Transition | REACH-compliant SVHC-free spinning dopes qualify for EU Green Deal defense procurement criteria. |
Research Methodology
Document review covered Department of Defense budget justifications, Berry Amendment compliance directives, NIJ ballistic test protocols, and ECHA REACH authorization registers, complemented by interviews with defense prime contractor procurement directors, gel-spinning plant managers, PEO Soldier program executives, and accredited ballistic test laboratory technical directors. Secondary validation drew from SEC 10-K filings of integrated fiber producers, customs trade data for precursor imports, and ISO certification body records. Bottom-up fiber consumption estimates triangulated against top-down defense modernization budget allocations.
Cross-referencing historical qualification timeline patterns with expert panel input on emerging threat level requirements shaped the analytical framework across the analysis window. Segmentation dimensions modeled include fiber chemistry, end-user mission profile, manufacturing integration depth, and regional regulatory cluster. CAGRs derived from unit consumption trajectories weighted against defense appropriations growth and substitution elasticity between aramid and polyethylene platforms. Industry-specific forecast inputs incorporated Marine Corps Systems Command vehicle retrofit schedules and naval architects' topside weight reduction specifications.
Inputs from Department of Defense program offices and accredited ballistic test facilities were available through the study window; gaps in proprietary gel-spinning yield data and multi-material hybrid armor bonding process parameters introduce uncertainty bands around intermediate processing stage margin estimates. Forecasts reflect assumptions about NIJ threat level upgrade timing and congressional appropriations continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Global Concrete Fiber Market
Fibers
Renewable Carbon Fibers Market
Fibers
Fiber Metal Laminate (FML) Market
Fibers
Aramid Fiber Reinforcement Materials Market
Fibers
Carbon Fiber in Light Weight Pressure Vessels Market
Fibers
Microfibrillated Cellulose (MFC) Market
Fibers
Sisal Market
Fibers
High Temperature Superconducting Fibers Market
Fibers
Global Bicomponent Fiber Market
Fibers
Keratin Market
Fibers
Asia-Pacific Nanofiber Market
Fibers
Ultra-High Molecular Weight Polyethylene Fibers Market
Fibers
Bleached Linter Cellulose Market
Fibers
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market
Fibers
Fiber Intermediates Market
Fibers
Ceramic Fiber Market