
 Continuous Fiber Thermoplastic (CFT) Market | 2026-2036
Continuous Fiber Thermoplastic (CFT) Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Fiber Thermoplastic (CFT) Market Outlook
Aerospace is pivoting toward thermoplastic composites for wing spars and fuselage frames, displacing thermoset dominance in secondary structures. Toray Industries leverages its carbon fiber precursor supply to anchor Japan's CFT value chain. Solvay competes through polyaryletherketone resin chemistry leadership. Teijin Limited specializes in unidirectional tape formats for automated fiber placement.
Continuous Fiber Thermoplastic denotes a class of advanced composites wherein continuous reinforcing fibers are impregnated with a thermoplastic matrix, typically processed above melting point and consolidated under pressure for weldability and recyclability. The material serves industries requiring high specific strength with reprocessability and corrosion resistance. PPS resin grades dominate current aerospace qualification programs due to flame-smoke-toxicity compliance and chemical resistance. Compression molding captures the fastest process growth as automotive Tier-1 suppliers seek cycle times under three minutes for structural seat backs and battery enclosures. Injection molding remains mature in consumer electronics housings where short fiber substitutes suffice.
Europe's EASA airworthiness directives and REACH chemical registration constrain resin formulation choices, while the FAA in the United States maintains separate qualification pathways that fragment certification costs. Germany's KBA automotive regulator references ECE R94 crash standards that favor CFT energy absorption in electric vehicle battery trays. Stakeholders must monitor divergence between FAA and EASA material qualification databases before committing to platform-specific resin systems.
Market Dynamics
Aerospace OEMs are consolidating thermoplastic composite specifications across platforms, forcing resin suppliers to harmonize qualification databases that previously fragmented by airframe program. This standardization push compresses development timelines while elevating technical barriers for new entrants lacking existing EASA or FAA material approvals.
Growth Catalysts
- EASA Certification Acceleration:The European regulator's streamlined qualification pathways for thermoplastic primary structures reduce airworthiness approval cycles. Munich and Hamburg aerospace clusters leverage this regulatory clarity to expand CFT wing spar production.
- Automotive Crash Standards:Germany's KBA references ECE R94 energy absorption requirements that favor CFT battery trays in electric vehicles. Tier-1 suppliers respond with sub-three-minute compression molding cycles for structural seat backs.
- Weldability Advantages:Thermoplastic matrix reprocessability enables in-situ repair protocols that thermoset composites cannot match. Airlines specify CFT for high-damage-risk fuselage sections to minimize AOG downtime.
Market Restraints
- Precursor Supply Concentration:Polyacrylonitrile carbon fiber feedstock concentrates among Asian petrochemical complexes. Price volatility in acrylonitrile monomer propagates directly to CFT raw material costs.
- REACH Chemical Registration:ECHA's substance authorization requirements constrain polyaryletherketone resin formulation choices. Formulators face compliance costs that disadvantage European production against less regulated jurisdictions.
- Short-Fiber Substitution:Injection-molded discontinuous fiber compounds satisfy consumer electronics housing requirements at lower processing temperatures. This substitute captures volume in applications where continuous fiber performance exceeds functional needs.
Strategic Opportunities
- Urban Air Mobility Airframes:Electric vertical take-off platforms require damage-tolerant, weldable primary structures. CFT unidirectional tape formats suit automated fiber placement for complex eVTOL fuselage geometries.
- Japan's METI Green Innovation Fund:National subsidies for recyclable composites accelerate domestic qualification programs. Japanese aerospace suppliers gain cost advantages in PPS resin system development.
- Hydrogen Pressure Vessel Integration:Thermoplastic liner-overwrap hybrids combine chemical resistance with fiber-dominated strength. CFT towpreg winding processes adapt to Type IV tank manufacturing for fuel cell vehicles.
Industry Challenges
- Automated Fiber Placement Programming:Thermoplastic tape laying requires real-time temperature control algorithms that differ from thermoset prepreg protocols. Equipment operators need retraining on in-situ consolidation parameters.
- FAA-EASA Database Divergence:Separate material qualification pathways force dual certification investments for global platform supply. Stakeholders must monitor regulator-specific property datasets before committing to resin systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Fiber Thermoplastic (CFT) Market |
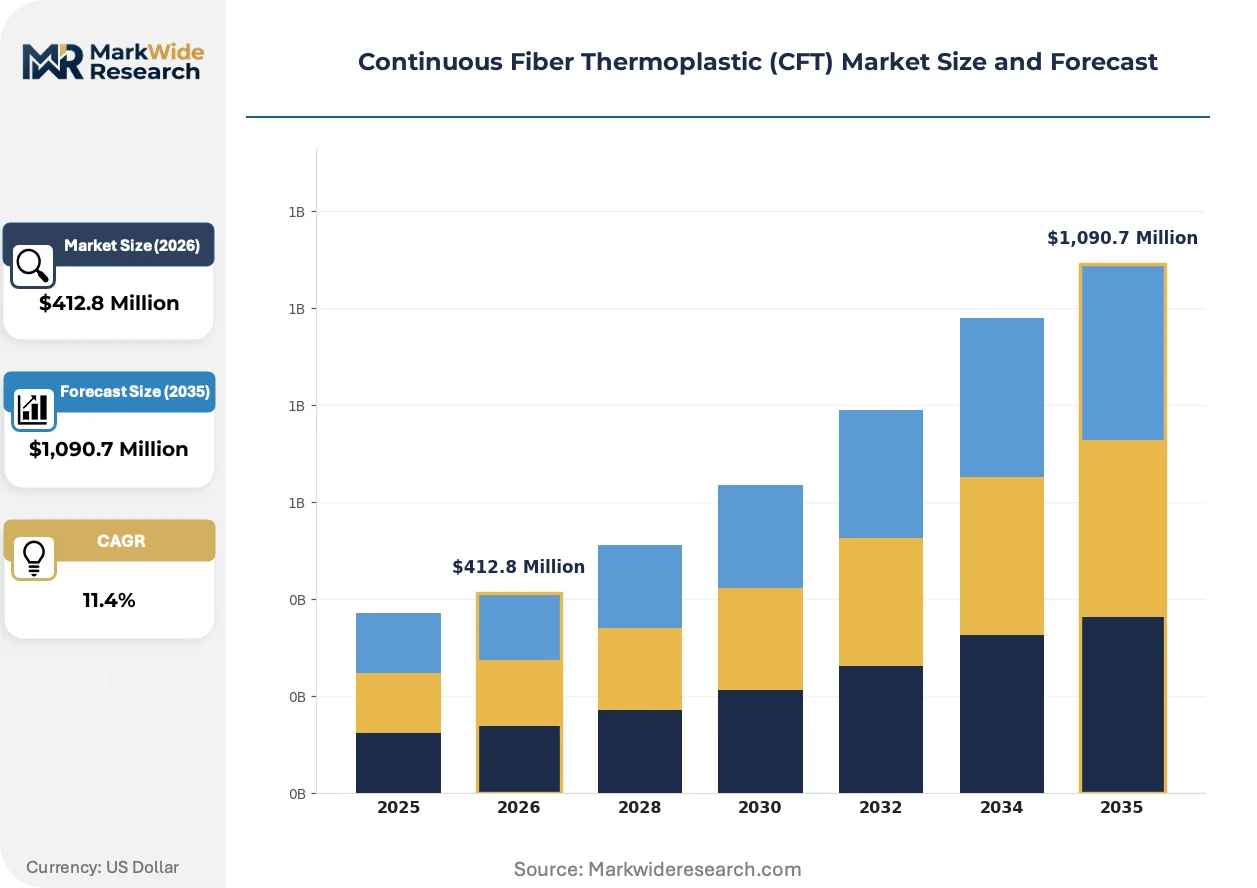
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $1,090.7 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PPS, PA, PPA, PLA Application: Aerospace, Automotive Parts, Industrial Components, Consumer Goods End User: Aerospace Manufacturers, Transportation Industry, Sports Equipment, Electronics Technology: Injection Molding, Compression Molding, Thermoforming, Filament Winding |
| Companies Covered | Solvay, Mitsubishi Chemical Corporation, Toray Industries, Celanese Corporation, Teijin Limited, BASF SE, Hexcel Corporation, TenCate, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Fiber Thermoplastic (CFT) Market Strategic Shifts
Thermoplastic composite processing is converging with digital manufacturing controls, compressing development cycles while fragmenting equipment supplier hierarchies. Three developments dominate competitive positioning.
In-situ consolidation during automated fiber placement is unifying layup and curing into single-pass operations. Aerospace tier suppliers adopt laser-assisted tape laying to eliminate autoclave bottlenecks. This process architecture collapses capital requirements for primary structure manufacturing while demanding precision thermal management systems.
REACH authorization timelines for high-performance polymers are tightening formulation disclosure requirements. European resin suppliers must submit extended safety dossiers for polyaryletherketone chemistries. Aerospace qualification programs face delays as formulators navigate ECHA substance evaluation procedures before EASA material approval.
Airline maintenance organizations now specify weldable repair patches for thermoplastic composite damage events. This operational preference displaces traditional bolted repairs in high-cycle fuselage sections. The specification shift concentrates in European carrier fleets subject to EASA continuing airworthiness directive harmonization.
Continuous Fiber Thermoplastic (CFT) Market Segmentation
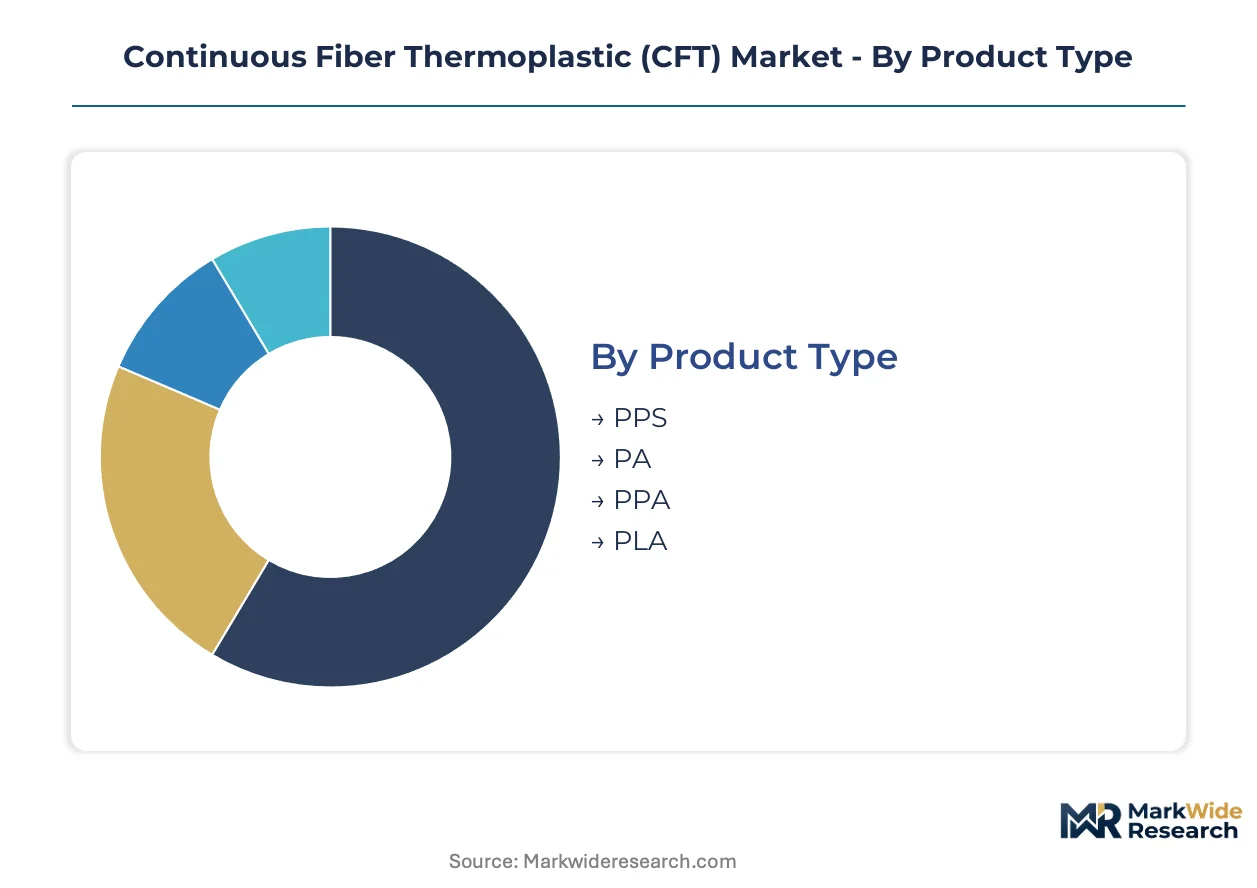
Segmentation in Continuous Fiber Thermoplastic markets reveals how resin chemistry, processing physics, and end-use certification requirements create distinct competitive arenas. Each axis demands specialized technical capabilities that fragment supplier positioning across aerospace, automotive, and industrial verticals.
Product Type:
Resin selection dictates flame-smoke-toxicity compliance, chemical resistance thresholds, and melt-processing windows that qualify materials for specific airframe or vehicle programs.
- PPS:Polyphenylene sulfide matrices dominate current aerospace qualification programs due to inherent flame retardancy and resistance to aviation hydraulic fluids. EASA certification timelines for PPS-based wing spar applications are compressing as Munich-area manufacturers consolidate process parameters. PPS leads on scale; PPA leads on momentum.
- PA:Polyamide grades balance cost and mechanical performance for automotive underhood components where continuous fiber reinforcement replaces metal brackets. Germany's KBA crash standards favor PA-based battery tray designs that absorb collision energy while maintaining electrical isolation. PA captures the steepest expansion trajectory in electric vehicle structural applications.
- PPA:Polyphthalamide resins extend thermal performance beyond standard PA for powertrain components exposed to transmission oil and aggressive coolants. Emerging e-motor housing specifications specify PPA for 150°C continuous service temperatures.
- PLA:Polylactic acid offers biodegradable positioning for consumer goods and select automotive interior trim where load-bearing requirements permit lower glass transition temperatures. Limited moisture resistance constrains adoption outside controlled environments.
PPS commands aerospace specification lock-in; PA scales fastest across automotive platforms.
Application:
End-use sectors impose divergent cost-performance tradeoffs that reshape processing technology selection and fiber format preferences.
- Aerospace:Primary structural applications including wing spars, fuselage frames, and control surfaces demand unidirectional tape formats with automated fiber placement compatibility. EASA streamlined qualification pathways for thermoplastic primary structures are accelerating Munich and Hamburg cluster expansion.
- Automotive Parts:Structural seat backs, battery enclosures, and underbody shields prioritize sub-three-minute compression molding cycles. Germany's KBA references ECE R94 energy absorption standards that favor CFT crash performance in electric vehicle architectures.
- Industrial Components:Chemical processing equipment and oilfield hardware exploit corrosion resistance and reparability through in-situ welding protocols that thermoset alternatives cannot match.
- Consumer Goods:Premium sporting equipment and electronics housings accept higher per-kilogram costs for design flexibility and surface finish quality that compression molding delivers.
Aerospace commands premium pricing; automotive parts scale volume fastest.
End User:
Customer procurement patterns differentiate between specification-driven OEMs and price-sensitive volume buyers.
- Aerospace Manufacturers:Boeing and Airbus tier suppliers consolidate thermoplastic composite specifications across platforms, forcing resin suppliers to harmonize previously fragmented qualification databases. EASA and FAA dual certification requirements elevate barriers for new material entrants.
- Transportation Industry:Rail and heavy truck OEMs specify CFT for interior panels and structural members where fire safety regulations converge with weight reduction mandates.
- Sports Equipment:Bicycle frame and ski manufacturers leverage weldability for complex joint geometries and field repairability that extends product service life.
- Electronics:Laptop and smartphone chassis designers balance electromagnetic shielding performance with thin-wall molding capability that short-fiber compounds often satisfy at lower cost.
Aerospace manufacturers concentrate specification power; transportation industry expands application breadth.
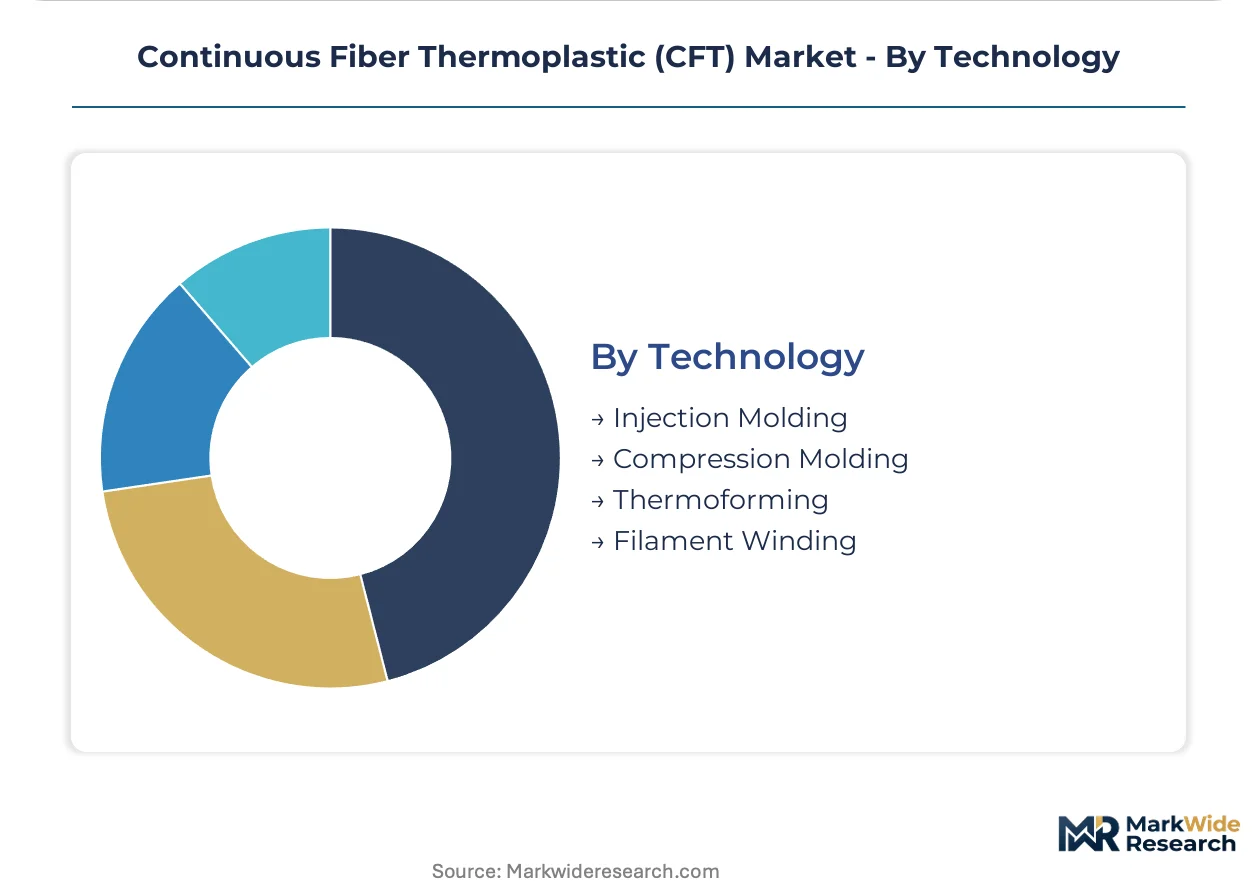
Technology:
Process selection determines capital intensity, cycle economics, and geometric complexity limits that segment supplier capabilities.
- Injection Molding:High-pressure impregnation of continuous fiber reinforcements suits complex three-dimensional geometries with tight dimensional tolerances. Consumer electronics housings and small automotive brackets dominate current throughput.
- Compression Molding:Heated blank consolidation between matched dies achieves sub-three-minute cycles for automotive structural components. Germany's automotive Tier-1 suppliers are retrofitting press lines for organosheet processing.
- Thermoforming:Heated laminate drape-forming over single-sided tools produces large aircraft panels and interior trim with minimal fiber distortion. EASA qualification programs for thermoformed fuselage sections are advancing.
- Filament Winding:Continuous fiber towpreg deposition onto rotating mandrels manufactures pressure vessels and tubular structures. Hydrogen Type IV tank applications are emerging as fuel cell vehicle deployment accelerates.
Compression molding scales fastest; filament winding captures emerging hydrogen infrastructure demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping CFT production geography as REACH compliance costs in Europe push investment toward jurisdictions with streamlined chemical registration. Material suppliers now site precursor capacity where ECHA authorization timelines do not constrain formulation innovation.
United States
FAA qualification pathways for thermoplastic primary structures are consolidating as Boeing and Airbus tier suppliers harmonize previously fragmented material databases. The FAA maintains separate certification protocols from EASA that fragment global platform supply. Seattle and Wichita aerospace clusters are expanding automated fiber placement capacity for wing spar production.
Germany
Germany's KBA references ECE R94 crash standards that favor CFT energy absorption in electric vehicle battery trays. EASA streamlined qualification pathways accelerate Munich and Hamburg aerospace cluster expansion for thermoplastic composite wing production. Compression molding press retrofits for organosheet processing are concentrating around Stuttgart automotive Tier-1 suppliers.
Japan
METI Green Innovation Fund subsidies for recyclable composites accelerate domestic PPS resin system qualification programs. Toray Industries leverages carbon fiber precursor supply to anchor national CFT value chain integration. Nagoya aerospace suppliers gain cost advantages in automated fiber placement equipment deployment.
China
MIIT industrial policy prioritizes domestic carbon fiber self-sufficiency to reduce polyacrylonitrile precursor import dependence. GB standards for composite pressure vessels create regulatory pathways for hydrogen Type IV tank CFT applications. Shanghai and Shenzhen clusters are scaling compression molding for electric vehicle battery enclosure production.
South Korea
MFDS chemical substance registration requirements are less constraining than REACH, attracting resin formulation investment from European suppliers seeking regulatory relief. Hyundai-Kia electric vehicle platforms specify CFT battery trays under KBA-referenced crash standards. Busan-Ulsan industrial corridor is developing filament winding capacity for hydrogen infrastructure pressure vessels.
Continuous Fiber Thermoplastic (CFT) Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with aerospace qualification databases conferring defensive moats that automotive scale players cannot easily replicate. The vendor base concentrates among resin-chemistry leaders and fiber-precursor integrated groups, with mid-tier fabricators competing on compression molding cycle efficiency. Two archetypes dominate: integrated chemical conglomerates with captive polymer supply, and aerospace-focused composite specialists with EASA/FAA dual certification. Competitive moves center on backward integration into carbon fiber precursor and strategic partnerships for automated fiber placement equipment access.
Within the integrated chemical tier, Solvay and BASF SE exemplify resin-chemistry leadership through polyaryletherketone formulation expertise. Among fiber-precursor integrated groups, Toray Industries and Teijin Limited occupy positions anchored by carbon fiber supply control. These three names represent the structural fault lines of CFT competition: chemical formulation depth versus fiber integration scale versus aerospace certification velocity.
| Leading Market Players |
|---|
| Solvay |
| Mitsubishi Chemical Corporation |
| Toray Industries |
| Celanese Corporation |
| Teijin Limited |
| BASF SE |
| Hexcel Corporation |
| TenCate |
| SABIC |
| Others |
Value Chain & Pricing Dynamics
REACH authorization timelines from ECHA constrain qualified resin supply and gate premium-tier pricing access for aerospace-grade CFT systems. Formulators bearing extended safety dossier costs recover through material qualification premiums that fragment the supplier base into certified and non-certified tiers.
Pricing Analysis
Distributor margins compress as direct-to-OEM supply agreements expand for high-volume automotive programs. Pricing stratifies across aerospace-qualified, automotive-performance, and industrial-economy tiers driven by certification depth and fiber format complexity. Cost compression in industrial-grade PA compounds intensifies because Asian producers scale compression molding capacity. Automotive OEMs exhibit highest price sensitivity; aerospace tier-1 suppliers accept qualification-linked premiums.
Supply Chain Analysis
Freight costs for carbon fiber precursor from Japan and South Korea amplify raw material exposure for European compounders. Polyacrylonitrile feedstock concentrates in Japan, South Korea, and China; PPS resin supply draws from U.S. Gulf Coast and German chemical complexes. Single-source vulnerability runs through Toray's precursor dominance. Distribution runs through qualified distributor networks for aerospace and direct mill relationships for automotive volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CFT markets compound steadily as EASA certification acceleration locks in aerospace platform specifications. Regulatory clarity on thermoplastic primary structures creates predictable demand visibility for qualified suppliers.
For Market Incumbents: Lock in EASA-FAA dual certification databases before harmonization closes to new entrants. Expand backward integration into carbon fiber precursor in Japan or South Korea to hedge acrylonitrile volatility. Prioritize automated fiber placement equipment partnerships that cement tier-1 supplier relationships.
For New Entrants and Emerging Players: EASA streamlined qualification pathways in Germany open a window for specialized PPA resin formulators targeting e-motor housings. Target automotive battery tray applications where KBA-referenced crash standards favor CFT but incumbent certification burdens are lighter. Pursue joint development agreements with Stuttgart-area Tier-1 suppliers retrofitting compression molding lines.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap compression molding specialists because automotive electrification multiplies addressable content per vehicle. Five-to-ten-year viability hinges on hydrogen pressure vessel qualification velocity. Monitor EASA material database updates as inflection signal for aerospace specification consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor | Toray's PAN supply control anchors Japanese CFT value chain resilience. |
| EASA Dual Certification Investment | Harmonized aerospace databases elevate barriers for non-qualified resin suppliers. |
| Automated Fiber Placement Partnership | Laser-assisted tape laying collapses autoclave capital for tier-1 manufacturers. |
| Hydrogen Pressure Vessel Qualification | Type IV tank standards from KBA and ECE R134 create CFT filament winding demand. |
| REACH Compliance Dossier Submission | ECHA authorization timelines determine European polyaryletherketone formulation availability. |
Study Parameters
Multiple input streams — primary interviews with resin formulators and aerospace procurement leads, secondary validation through EASA certification databases and customs trade data, and technical literature on thermoplastic composite processing — were reconciled to construct segment-level demand estimates. Bottom-up build-ups from compression molding line counts and automated fiber placement equipment installations were cross-checked against top-down resin consumption figures from chemical industry associations.
Historical capacity utilization patterns were cross-referenced against expert panel assessments of EASA qualification timeline compression. Segmentation modeling spanned resin chemistry, processing technology, end-use sector, and regional regulatory cluster dimensions. CAGRs were derived from slope-matching approaches across the projection horizon, with hydrogen infrastructure deployment rates and electric vehicle platform ramp schedules serving as industry-specific demand drivers.
Revisions become necessary when EASA-FAA database divergence resolves or collapses, when acrylonitrile supply disruptions propagate to precursor availability, or when REACH authorization rejections remove qualified resin systems from the market. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Fiber Intermediates Market
Fibers
Carbon Fiber Tapes Market
Fibers
Sisal Market
Fibers
Pitch-Based Carbon Fiber Market
Fibers
High Temperature Superconducting Fibers Market
Fibers
Asia-Pacific Optical Fiber Raw Material Market
Fibers
Carbon Fiber Market
Fibers
Ultra-High Molecular Weight Polyethylene Fibers Market
Fibers
Global Concrete Fiber Market
Fibers
Global R-Glass Fiber Market
Fibers
Triacetate Cellulose Market
Fibers
E-Glass Fiber Market
Fibers
Ceramic Fiber Market
Fibers
Global Electronic Fiberglass Market
Fibers
Activated Carbon Fiber (ACF) Market
Fibers
Global Basalt Fiber Market