
 Carbon Fiber Market | 2026-2036
Carbon Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Fiber Market Intelligence
Direct supply contracts between precursor producers and aerospace tier-1 fabricators is reconfiguring how carbon fiber reaches end-use markets. Toray Industries sustains one of the world's largest PAN-based carbon fiber manufacturing footprints across Japan, the United States, and France. Hexcel Corporation specializes in advanced composite formulations for defense and commercial aviation customers. SGL Carbon SE leverages its integrated carbon and graphite materials portfolio to serve automotive and industrial applications from European production bases.
Carbon fiber consists of filaments composed primarily of carbon atoms arranged in crystalline formations, typically manufactured through controlled oxidation and carbonization of polyacrylonitrile (PAN) precursor at temperatures exceeding 1,000°C to achieve tensile strengths surpassing 3,500 MPa. The material functions as a high-stiffness, low-weight reinforcement in structural composites where metals impose unacceptable mass penalties. PAN-based technology dominates manufacturing volumes due to cost-efficiency and property consistency, while pitch-based grades occupy premium niches demanding exceptional modulus for satellite and specialized aerospace components. Standard modulus products anchor volume demand across automotive and industrial sectors, whereas intermediate and high modulus categories capture concentrated value in aerospace primary structures where certification requirements create steep barriers.
The Federal Aviation Administration (FAA) and European Union Aviation Safety Agency (EASA) enforce stringent material qualification protocols that extend certification timelines and favor incumbent suppliers with established databases. REACH chemical regulations and the EU Green Deal carbon border adjustments are reshaping precursor sourcing decisions and energy-intensive carbonization economics. Stakeholders must monitor evolving automotive crashworthiness standards and wind turbine blade length requirements as these specifications determine which modulus grades and tow sizes command priority investment.
Market Dynamics
Aerospace OEMs are forcing carbon fiber supply chains to restructure around direct precursor-to-fabricator contracts, bypassing traditional distributor layers that once dominated material flows. This consolidation of procurement channels is compressing margins for intermediate processors while locking in volume commitments for PAN precursor producers.
Growth Catalysts
- EU Green Deal carbon border adjustments:Industrial manufacturers face escalating penalties for embodied carbon in steel and aluminum, accelerating substitution toward carbon fiber reinforced polymers in structural components.
- Wind turbine blade scaling:Offshore installations exceeding 100-meter blade lengths demand intermediate modulus tow sizes that metals cannot satisfy, concentrating procurement among specialized fabricators.
- Automotive OEM lightweighting mandates:Germany's KBA crashworthiness standards for electric vehicle platforms specify mass reduction targets that carbon fiber composites uniquely achieve.
Market Restraints
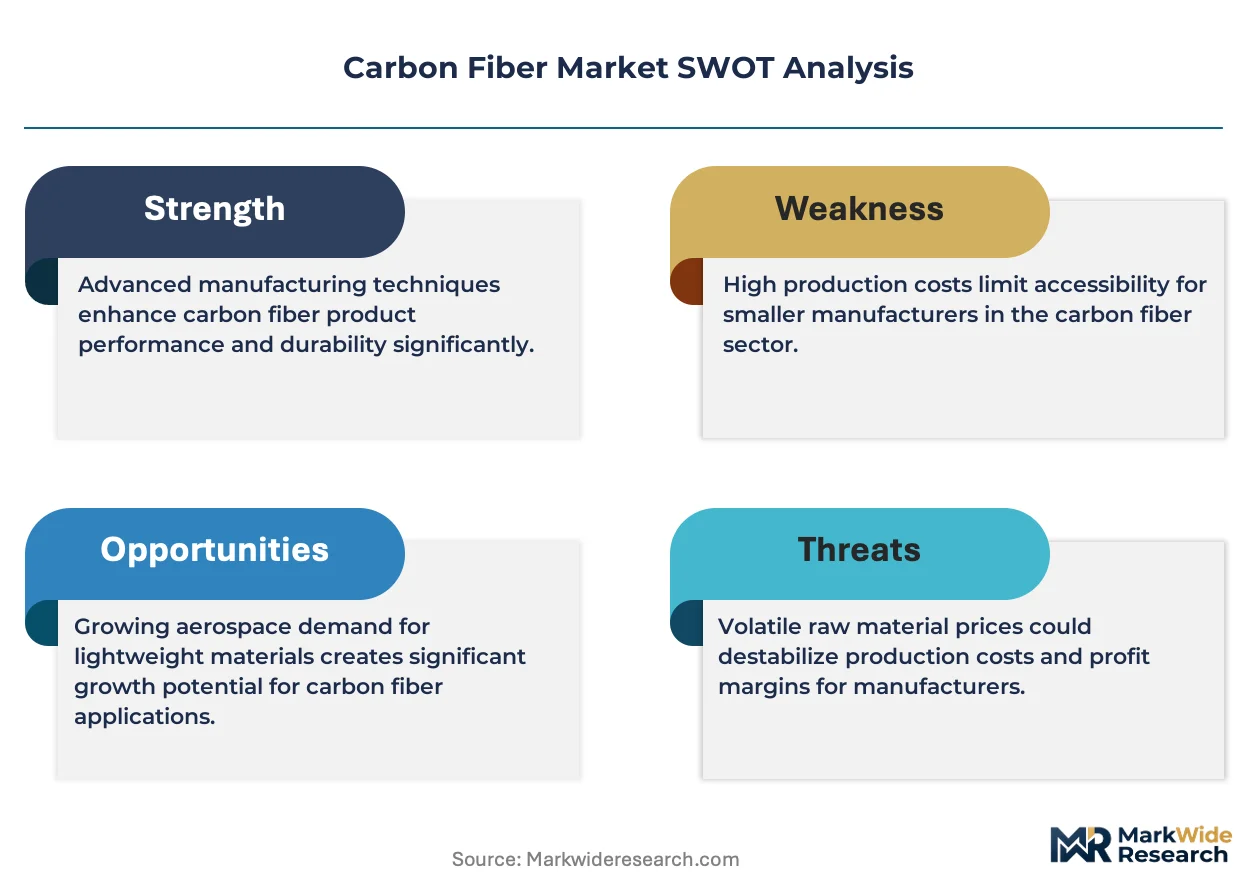
- Acrylonitrile price volatility:PAN precursor production consumes petroleum-derived feedstocks subject to energy market fluctuations, destabilizing carbon fiber cost structures.
- Japanese supply concentration:Toray Industries and Mitsubishi Chemical dominate global PAN precursor capacity, creating single-source vulnerability for aerospace tier-1 fabricators.
- FAA-EASA qualification timelines:Material certification databases require years of testing data, freezing out new entrants regardless of technical merit.
Strategic Opportunities
- India automotive industrialization:PLI scheme incentives for electric vehicle manufacturing create first-mover advantage for carbon fiber component suppliers establishing localized prepreg facilities.
- Recycled fiber integration:Pyrolysis-based reclaimed carbon fiber is achieving mechanical properties suitable for non-structural automotive panels, opening circular economy revenue streams.
- Hydrogen storage pressure vessels:Type IV composite tanks for fuel cell vehicles require specialized filament winding techniques that incumbent aerospace suppliers can leverage.
Industry Challenges
- Carbonization furnace engineering scarcity:Equipment design expertise for high-temperature oxidation and carbonization lines concentrates among retired Japanese and German specialists, constraining capacity expansion.
- Legacy ERP integration:Aerospace fabricators operate traceability systems incompatible with newer composite producers' digital thread platforms, delaying supplier onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Fiber Market |
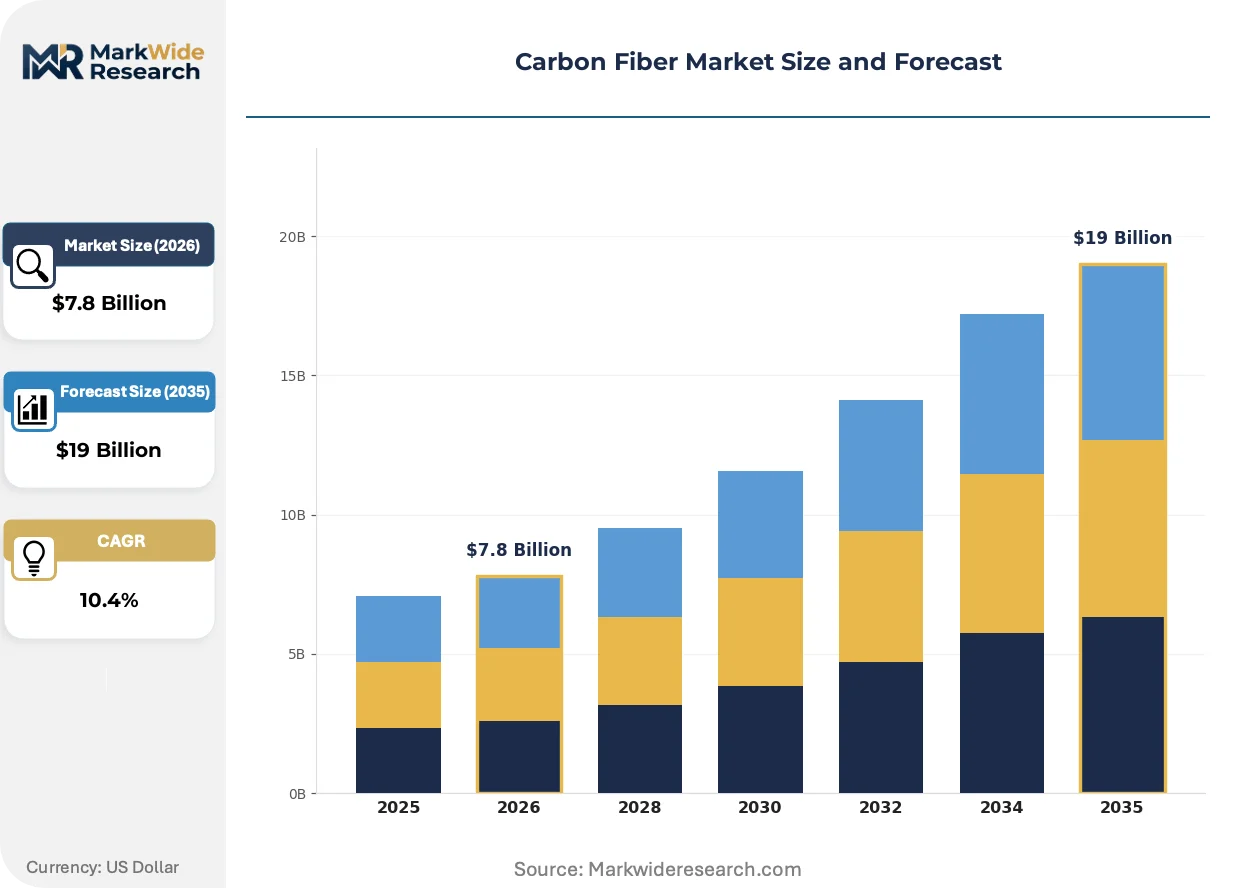
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $19 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Modulus, Intermediate Modulus, High Modulus, Ultra High Modulus Technology: PAN-Based, Pitch-Based, Rayon-Based, Others Application: Aerospace & Defense, Sports Equipment, Wind Energy, Marine Vessels End User Industry: OEMs, Aftermarket Suppliers, Construction, Consumer Goods |
| Companies Covered | Mitsubishi Chemical Holdings Corporation, Toho Tenax Co., Ltd., Toray Industries, Inc., Hyosung Corporation, Zhongfu Shenying, Teijin Limited, SGL Carbon SE, DowAksa Advanced Composites LLC, Hexcel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Fiber Market Strategic Shifts & Innovations
Manufacturing economics are compressing as alternative precursors and accelerated carbonization cycles challenge PAN's decades-long dominance. Three interconnected developments are restructuring how carbon fiber reaches end-use applications.
Thermoplastic resin systems are collapsing the processing cost gap with thermoset alternatives in automotive structural components. BMW and Porsche production lines now stamp carbon fiber-reinforced thermoplastic parts in sub-90-second cycles. This speed is collapsing the traditional aerospace-dominated supply hierarchy and opening volume markets previously reserved for metals.
REACH chemical registration requirements are forcing reformulation of sizing agents and surface treatments used in carbon fiber production. ECHA's 2023 updates to substance authorization lists have disqualified several silane-based coupling chemistries. European producers are responding with plasma activation and aqueous epoxy alternatives that maintain interlaminar shear strength.
Direct mill relationships are displacing distributor-mediated procurement in wind energy and industrial sectors. Vestas and Siemens Gamesa now contract directly with SGL Carbon and Hexcel for multi-year tow supply, bypassing regional composite distributors. This pattern is most visible in Denmark and northern Germany, where blade manufacturing clusters concentrate buying power.
Carbon Fiber Market Segmentation
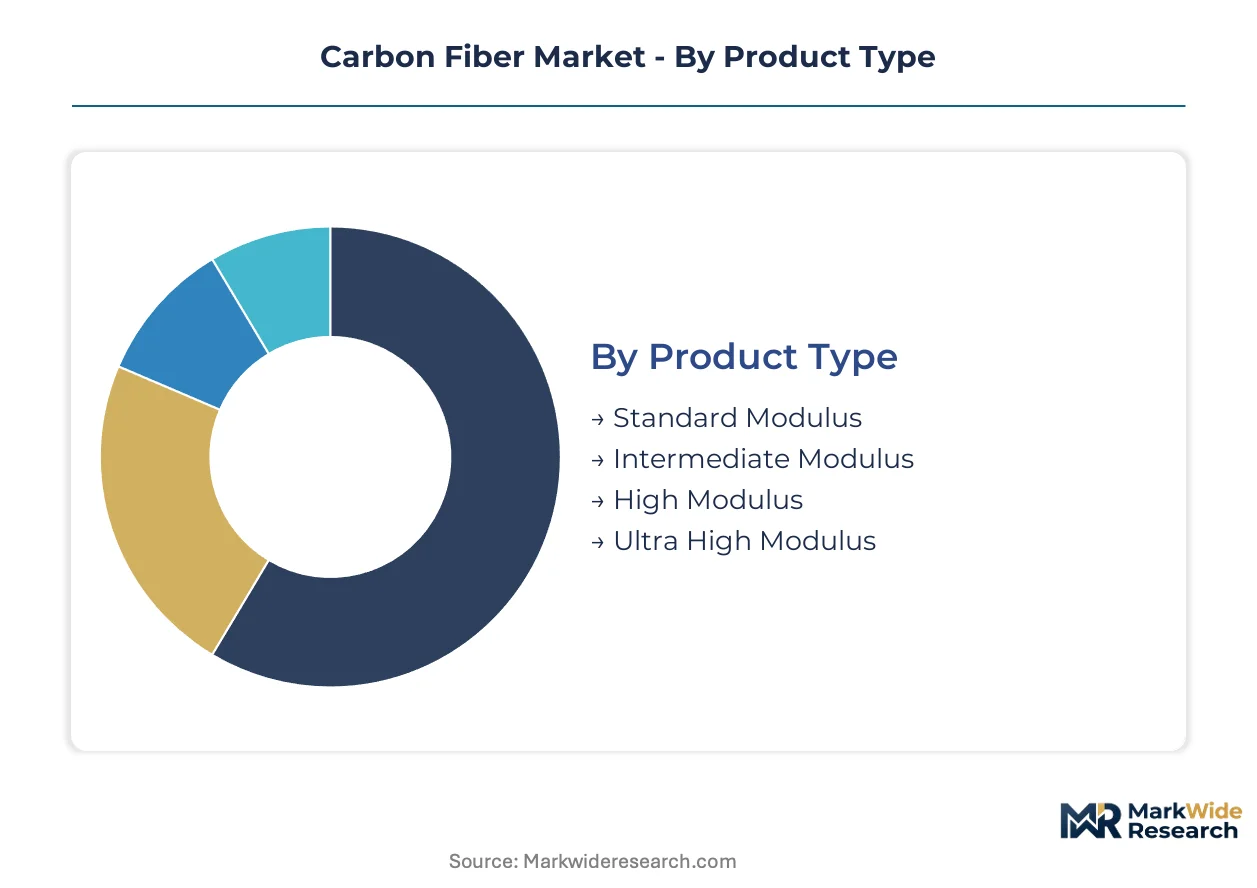
Carbon fiber procurement patterns diverge sharply across modulus grades and precursor technologies, with aerospace certification requirements and automotive cost thresholds creating distinct demand pools. Understanding these segment boundaries reveals where margin concentration and volume expansion operate on separate tracks.
Product Type:
Mature industrial grades anchor baseline demand while emerging high-performance categories capture concentrated value in satellite and defense applications.
- Standard Modulus:Tensile strength ranges from 3,500 to 5,000 MPa with modulus near 230 GPa, manufactured through conventional PAN carbonization cycles. Automotive OEMs in Germany specify this grade for non-structural EV body panels where cost-per-kilogram thresholds exclude higher grades. KBA crashworthiness protocols favor its predictable energy absorption characteristics.
- Intermediate Modulus:Achieves 5,000 to 6,000 MPa tensile strength with modulus of 280 GPa, bridging the gap between industrial affordability and aerospace performance. Offshore wind turbine blades exceeding 100 meters in Denmark and northern Germany demand this grade for spar cap reinforcement where deflection limits are critical. Direct mill contracts between Vestas and SGL Carbon concentrate procurement among European fabricators.
- High Modulus:Modulus exceeding 350 GPa serves primary aerospace structures requiring stiffness-to-weight optimization. FAA-EASA qualification databases lock in incumbent suppliers.
- Ultra High Modulus:Exceptional modulus above 450 GPa commands satellite boom and precision optical bench applications. Pitch-based precursors dominate this niche.
Standard Modulus retains volume leadership; Intermediate Modulus holds the steepest expansion curve.
Technology:
Cost tiers separate mass-market precursors from specialty feedstocks serving modulus extremes.
- PAN-Based:Polyacrylonitrile precursor undergoes controlled oxidation at 200 to 300°C followed by carbonization above 1,000°C, yielding consistent fiber properties at scale. Toray Industries, Mitsubishi Chemical, and Hexcel operate integrated PAN-to-carbon capacity across Japan, the United States, and France. Acrylonitrile price volatility from petroleum feedstock exposure compresses margin predictability.
- Pitch-Based:Mesophase pitch derived from petroleum or coal tar enables graphitic microstructure with modulus exceeding 900 GPa. Japanese and German specialists concentrate furnace engineering expertise for this energy-intensive process.
- Rayon-Based:Cellulosic precursor serves specialized thermal insulation and ablative applications where purity requirements exceed mechanical demands.
- Others:Experimental lignin-based and polyethylene-derived precursors target cost reduction for automotive volume applications.
PAN-Based commands absolute volume dominance; Pitch-Based maintains the highest margin per kilogram.
Application:
Customer type determines whether procurement flows through distributors or direct mill relationships.
- Aerospace & Defense:Primary structures, secondary components, and interior applications each demand distinct qualification databases. Boeing and Airbus tier-1 fabricators contract directly with Toray and Hexcel, bypassing traditional distribution layers.
- Wind Energy:Blade manufacturers in Denmark and Germany now source tow directly from SGL Carbon and Hexcel through multi-year supply agreements. Offshore installations drive intermediate modulus demand.
- Sports Equipment:Bicycle frames, golf shafts, and hockey sticks consume standard modulus grades through regional composite distributors. Price sensitivity constrains precursor specification.
- Marine Vessels:Racing yachts and military craft specify intermediate modulus for mast and hull reinforcement. Saltwater corrosion resistance favors carbon fiber over aluminum in high-performance segments.
Aerospace & Defense retains qualification-driven margin concentration; Wind Energy is expanding most quickly through direct procurement restructuring.
End User Industry:
Supply concentration varies by whether end users possess in-house composite fabrication capability or rely on external processors.
- OEMs:Automotive and aerospace original equipment manufacturers with captive composite shops specify fiber grades directly. BMW's Leipzig and Spartanburg plants stamp thermoplastic composites in sub-90-second cycles.
- Aftermarket Suppliers:Repair stations and modification shops access fiber through distributors with shorter lead times and smaller minimum order quantities.
- Construction:Structural reinforcement and seismic retrofit applications in Japan and California consume standard modulus for concrete strengthening. Building codes lag aerospace in material qualification stringency.
- Consumer Goods:Electronics enclosures and luxury goods prioritize surface finish and brand association over mechanical specification. Shorter product lifecycles tolerate lower durability margins.
OEMs retain direct procurement leverage; Construction is climbing the fastest as building codes modernize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's specialized bulk handling infrastructure anchors northern Germany's carbon fiber precursor import flows. Rotterdam's Maasvlakte terminals distribute acrylonitrile feedstocks across European carbonization facilities. Japan's Nagoya port complex handles PAN precursor exports to aerospace fabricators in France and the United States.
United States
Boeing's 787 and 777X programs in Washington State sustain demand for intermediate modulus tow. The FAA's material qualification protocols lock in incumbent suppliers with established certification databases. The I-90 aerospace corridor between Seattle and Spokane concentrates tier-1 composite fabrication for defense and commercial aviation.
Germany
BMW's Leipzig and Spartanburg stamping lines process carbon fiber-reinforced thermoplastics in sub-90-second cycles. The EU Green Deal's carbon border adjustments penalize embodied carbon in steel and aluminum, accelerating substitution toward CFRP structural components. The Mittelstand belt in Bavaria and Baden-Württemberg hosts specialized automotive composite processors.
Japan
Toray Industries and Mitsubishi Chemical operate integrated PAN-to-carbon capacity across Nagoya and Oita prefectures. METI's industrial decarbonization roadmaps prioritize lightweight material adoption in transportation sectors. The Chubu region's chemical engineering cluster supplies carbonization furnace expertise concentrated among retired specialists.
China
Zhongfu Shenying and domestic precursors scale capacity for wind turbine blade manufacturers in Jiangsu and Guangdong. MIIT's dual carbon goals mandate lightweighting in electric vehicle platforms. The Yangtze River Delta's composite industrial parks attract filament winding specialists for hydrogen storage vessel production.
Denmark
Vestas contracts directly with SGL Carbon and Hexcel for multi-year tow supply agreements bypassing distributors. The country's national wind energy regulator enforces blade certification standards that specify intermediate modulus grades. The Port of Esbjerg's offshore logistics hub serves North Sea installations exceeding 100-meter blade lengths.
Carbon Fiber Market Key Industry Players
On the supply side, the industry is consolidating around integrated precursor-to-fiber manufacturers with captive PAN production. Japanese and German specialists dominate carbonization furnace engineering, constraining capacity expansion for new entrants. Two strategic archetypes define competitive positioning: aerospace-certified incumbents with decade-long qualification databases, and automotive-focused scale players leveraging thermoplastic processing speed. Dominant competitive moves include backward integration into acrylonitrile feedstocks and direct mill contracts that displace distributor layers.
Among Japanese chemical conglomerates, Toray Industries, Mitsubishi Chemical Holdings Corporation, and Teijin Limited exemplify the integrated precursor-fiber archetype with established aerospace certification positions. German specialists SGL Carbon SE and Hexcel Corporation anchor the European supply base, with SGL representing the automotive-wind energy crossover tier and Hexcel occupying the defense-commercial aviation nexus. Chinese players Zhongfu Shenying and Hyosung Corporation exemplify scale-driven challengers targeting volume markets through cost-optimized PAN carbonization.
| Leading Market Players |
|---|
| Mitsubishi Chemical Holdings Corporation |
| Toho Tenax Co., Ltd. |
| Toray Industries, Inc. |
| Hyosung Corporation |
| Zhongfu Shenying |
| Teijin Limited |
| SGL Carbon SE |
| DowAksa Advanced Composites LLC |
| Hexcel Corporation |
| Others |
Cost & Logistics Intelligence
The Port of Hamburg's acrylonitrile import corridors transmit feedstock cost volatility directly into PAN precursor pricing, compressing margins for non-integrated carbonizers while amplifying volume-discount leverage for aerospace tier-1 fabricators with direct mill contracts.
Pricing Analysis
Volume-discount tiering separates aerospace-qualified high-modulus grades from industrial standard-modulus supply. Price differentiation rests on FAA-EASA certification database access and captive PAN production. Cost compression in automotive thermoplastic tiers is intensifying because sub-90-second cycle economics favor scale players. Aftermarket distributors exhibit highest price sensitivity; defense prime contractors show least.
Supply Chain Analysis
Extended payment terms from Japanese precursor producers to European carbonization specialists concentrate working capital risk among mid-tier fabricators. Supply concentrates in Japan, Germany, and the United States. Raw material flows draw from petroleum-derived acrylonitrile, mesophase pitch feedstocks, and specialized carbonization furnace components. Single-source vulnerability around Toray Industries and Mitsubishi Chemical PAN capacity creates structural exposure. Distribution runs through direct mill relationships displacing regional composite distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon fiber penetration sits at early-cycle expansion, with EU Green Deal carbon border adjustments accelerating substitution away from embodied-carbon metals across automotive and wind energy applications.
For Market Incumbents: Build certification database moats by deepening FAA-EASA qualification investment for next-generation intermediate modulus grades. Threats concentrate in Chinese scale players targeting wind energy volume through cost-optimized PAN carbonization. Priority levers include backward integration into acrylonitrile feedstocks and direct mill contracts that lock out distributor-mediated competition. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized electric vehicle component manufacturing, where localized prepreg capacity faces limited incumbent presence. White-space targets include recycled carbon fiber pyrolysis for non-structural automotive panels and hydrogen storage vessel filament winding. Go-to-market angle centers on thermoplastic processing speed partnerships with German automotive OEMs. For Investors and Strategic Acquirers: Specialized carbonization furnace engineering firms with retired Japanese and German specialist networks represent priority acquisition targets. Long-term viability frames around decade-long aerospace qualification cycles and automotive lightweighting mandates. Signal to watch: direct procurement contract announcements between Vestas-class wind turbine manufacturers and SGL Carbon or Hexcel tier suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylonitrile | Toray Industries and Mitsubishi Chemical secure feedstock cost stability against petroleum volatility. |
| Direct Mill Contract Structuring | Vestas and Siemens Gamesa bypass distributors to lock multi-year tow supply with SGL Carbon. |
| Thermoplastic Processing Speed Investment | BMW Leipzig achieves sub-90-second cycle times collapsing cost gap with thermoset alternatives. |
| Recycled Carbon Fiber Pyrolysis Scale-Up | Reclaimed fiber mechanical properties now satisfy non-structural automotive panel specifications. |
| Hydrogen Storage Vessel Filament Winding | Type IV composite tank demand from fuel cell vehicle programs leverages aerospace supplier expertise. |
Research Approach
Desk research of customs trade data, SEC 10-K filings, and ECHA REACH substance registrations preceded structured interviews with carbonization plant managers, aerospace tier-1 procurement leads, wind turbine blade engineers, and automotive composite R&D directors. Primary fieldwork combined with secondary validation across Japan's METI industrial statistics, EU Green Deal implementation documents, and FAA certification databases. Bottom-up capacity modeling and top-down demand segmentation were triangulated for consistency.
Assumptions held fixed include EU carbon border adjustment implementation timelines and existing FAA-EASA qualification database structures, while acrylonitrile price trajectories and wind turbine blade length scaling were varied across sensitivity scenarios. Segmentation dimensions encompassed modulus grade tier, precursor technology type, end-use application, and regional production hub clustering. CAGRs were derived from installed capacity expansion announcements and OEM platform lightweighting commitments.
Sensitivities concentrate around acrylonitrile feedstock cost spikes, Chinese capacity additions, and automotive crashworthiness standard revisions. Forecasts reflect these documented assumptions. Macroeconomic contraction, regulatory delay, or breakthrough alternative material commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Activated Carbon Fiber (ACF) Market
Fibers
E-Glass Fiber Market
Fibers
Global Fiberglass Mold Market
Fibers
Aramid Fiber Reinforcement Materials Market
Fibers
Acoustical Fiber Board Market
Fibers
Carbon Fiber in Light Weight Pressure Vessels Market
Fibers
Artificial Muscle Fibers Market
Fibers
Global Polyvinyl Alcohol Fiber Market
Fibers
Basalt Continuous Fiber (BCF) Market
Fibers
North America Glass Fiber Reinforced Gypsum Market
Fibers
Global Electronic Grade Glass Fibers Market
Fibers
Global Electronic Fiberglass Market
Fibers
Sisal Market
Fibers
Global Basalt Fiber Market
Fibers
Microfibrillated Cellulose (MFC) Market
Fibers
Precision Fiber Molding Market