
 Drug Integrated Polymer Fibers Market | 2026-2036
Drug Integrated Polymer Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Integrated Polymer Fibers Market Analysis
Modular drug-polymer configurations is recalibrating how buyers evaluate fiber-based delivery platforms against conventional depot injections. BASF SE leverages its polymer science heritage to anchor supply relationships with pharmaceutical formulators seeking tunable release kinetics. Teijin Limited specializes in high-tenacity bioresorbable fibers that sustain premium positioning in orthopedic and cardiovascular segments. TissueGen, Inc. competes through electrospun nanofiber platforms that occupy niche positions in wound care and tissue engineering applications.
Drug integrated polymer fibers are engineered filaments or nonwoven meshes comprising active pharmaceutical ingredients homogenously dispersed within biocompatible polymer matrices, typically manufactured via electrospinning, melt-spinning, or solution-spinning processes with fiber diameters ranging from nanometers to micrometers depending on therapeutic release profiles. These constructs serve as implantable or topical drug delivery vehicles that enable zero-order release kinetics, mechanical support, or biodegradation synchronized with tissue regeneration timelines. Multifilament configurations dominate current volume owing to established braiding and weaving infrastructure for surgical implants, while nonwoven formats represent the fastest-expanding structural category as electrospinning scales advance for topical and transdermal applications. Oncology applications command significant margin pools due to the complexity of cytotoxic agent stabilization within polymer carriers and the premium pricing associated with localized tumor-targeting delivery systems.
FDA combination product regulations and EMA medical device directives shape clinical trial requirements and quality management standards for drug-loaded fiber implants across North American and European markets. Japan's PMDA and the Ministry of Health, Labour and Welfare enforce stringent biocompatibility and sterilization validation protocols that influence export-oriented manufacturers targeting Japanese healthcare procurement channels. ISO 10993 biological evaluation standards and USP general chapters on drug release testing provide harmonized benchmarks that reduce technical barriers for cross-border product registration. Stakeholders must monitor evolving pharmacopeial standards for nanofiber-based products and pre-negotiate regulatory strategy with notified bodies before committing capital to scaled manufacturing assets.
Market Dynamics
Electrospinning scale-up economics is compressing manufacturing costs for nanofiber drug delivery platforms, enabling pharmaceutical formulators to displace conventional depot injection systems in localized oncology therapy.
Growth Catalysts
- FDA Combination Product Pathways:Accelerated review timelines for drug-device fiber implants reduce clinical validation periods, incentivizing pharmaceutical investment in localized delivery systems.
- Bioresorbable Polymer Chemistry:Advances in polylactic-co-glycolic acid degradation kinetics enable synchronized drug release with tissue regeneration timelines in orthopedic and cardiovascular applications.
- German Precision Manufacturing Infrastructure:Concentrated electrospinning equipment suppliers and polymer processing expertise in Baden-Württemberg lower technical barriers for clinical-scale fiber production.
Market Restraints
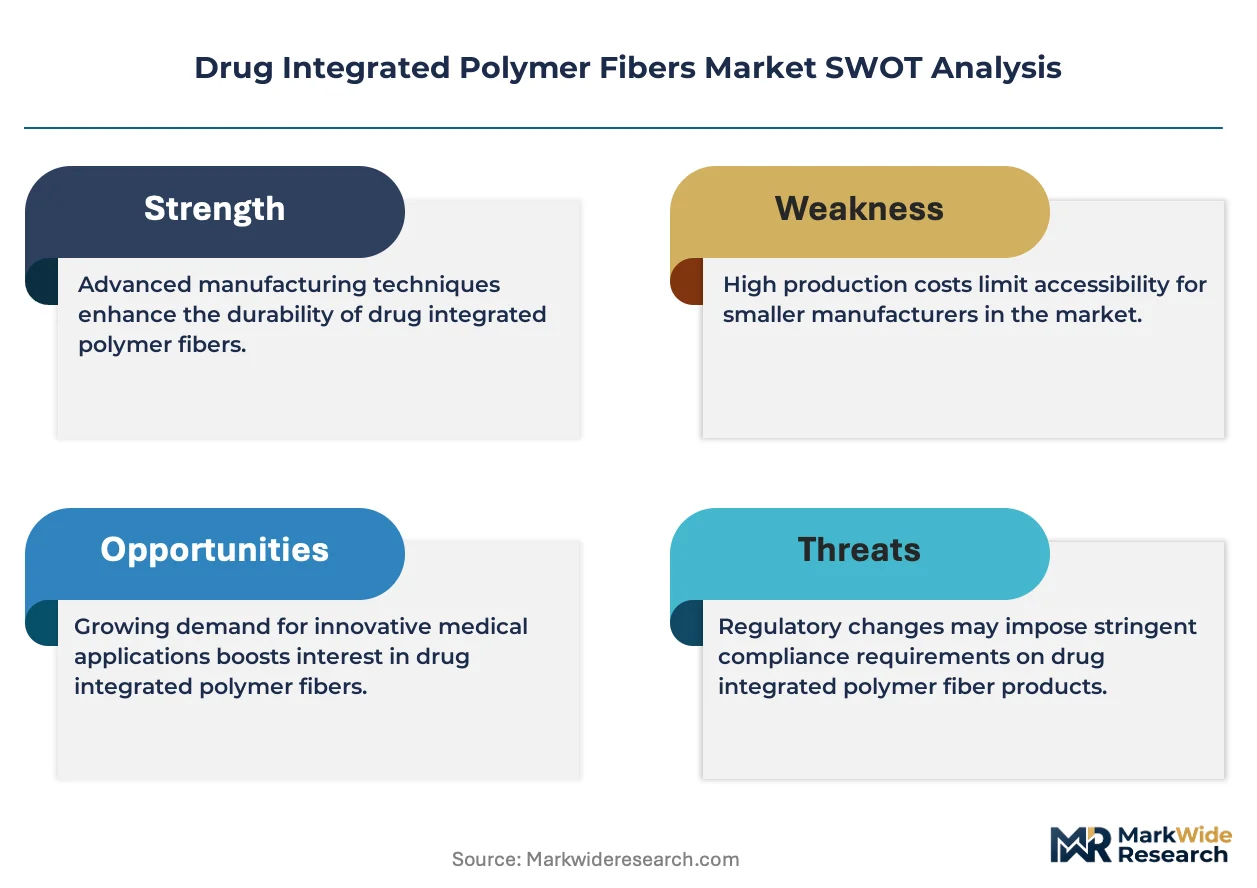
- Active Pharmaceutical Ingredient Instability:Thermal and shear stress during melt-spinning degrades temperature-sensitive biologics, limiting payload compatibility to small-molecule and stable protein therapeutics.
- Solvent Recovery Economics:Electrospinning requires volatile organic solvent systems with stringent EPA and ECHA emission controls, elevating environmental compliance costs above melt-based alternatives.
- Single-Source Biopolymer Supply:Medical-grade polylactic acid and polycaprolacton feedstock concentrates among three specialty chemical producers, creating input vulnerability for scaled fiber manufacturing.
Strategic Opportunities
- Japanese Wound Care Procurement Channels:PMDA's favorable reimbursement stance on advanced dressing materials creates premium positioning for antimicrobial-loaded nanofiber meshes in chronic wound management.
- Transdermal Vaccine Delivery Convergence:Microneedle-integrated polymer fiber arrays combining electrospun matrices with dissolving microprojectiles enable needle-free immunization platforms.
- EU Medical Device Regulation Harmonization:MDR's consolidated quality management requirements reduce cross-border registration friction for fiber-based combination products seeking multi-country market access.
Industry Challenges
- Electrospinning Process Validation:Fiber diameter distribution control across production lots demands statistical process control expertise scarce among traditional pharmaceutical quality teams.
- Sterilization Method Selection:Gamma irradiation and ethylene oxide protocols alter polymer molecular weight and drug potency, requiring extensive stability studies for each product configuration.
- ISO 10993 Biological Evaluation Timeline:Extended cytotoxicity and sensitization testing for novel polymer-drug combinations delays clinical trial initiation by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Integrated Polymer Fibers Market |
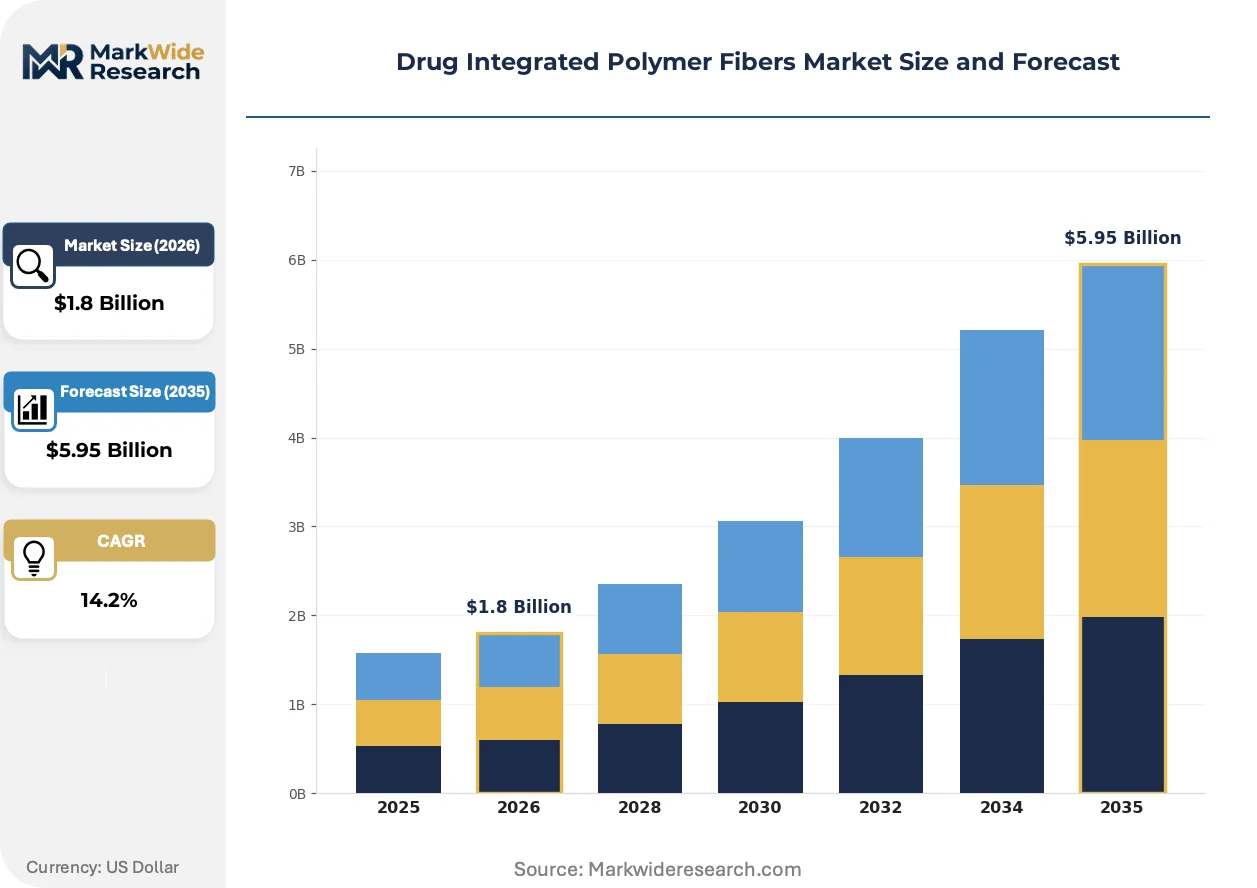
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monofilament, Multifilament, Nonwoven, Composites Therapy Area: Oncology, Cardiovascular, Neurology, Orthopedics End User: Hospitals, Clinics, Research Institutes, Home Healthcare Application: Drug Delivery Systems, Biodegradable Implants, Wound Care, Tissue Engineering |
| Companies Covered | BASF SE, DuPont de Nemours, Inc., Teijin Limited, Toray Industries, Inc., Evonik Industries AG, Solvay S.A., TissueGen, Inc., Micro Engineering Solutions, Inc., Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Integrated Polymer Fibers Market Emerging Trajectories
Manufacturing technology convergence is collapsing the traditional separation between pharmaceutical formulation and medical device fabrication, creating integrated production platforms that compress development timelines.
Coaxial electrospinning is unifying core-shell fiber architectures that separate hydrophilic and hydrorophobic drug compartments within single filaments. Cardiovascular device manufacturers in Germany and the United States are adopting these structures for dual-release anticoagulant and antiproliferative therapies. This unification enables sequential pharmacokinetic profiles previously requiring separate implantable devices.
EMA's Medical Device Regulation implementation is mandating unique device identification and post-market surveillance systems for all implantable fiber products. Device manufacturers must establish quality management systems spanning drug stability and mechanical performance validation. Oncology applications face the steepest compliance burden due to cytotoxic agent handling protocols and extended patient monitoring requirements.
Hospital procurement consortia are consolidating vendor qualification processes, favoring suppliers offering integrated drug-polymer formulation and sterilization services. Academic medical centers in Japan and the United States now require demonstration of lot-to-lot release consistency before contract award. This concentration forces smaller electrospinning specialists to partner with established pharmaceutical CDMOs for manufacturing scale and regulatory dossier depth.
Drug Integrated Polymer Fibers Market Segmentation
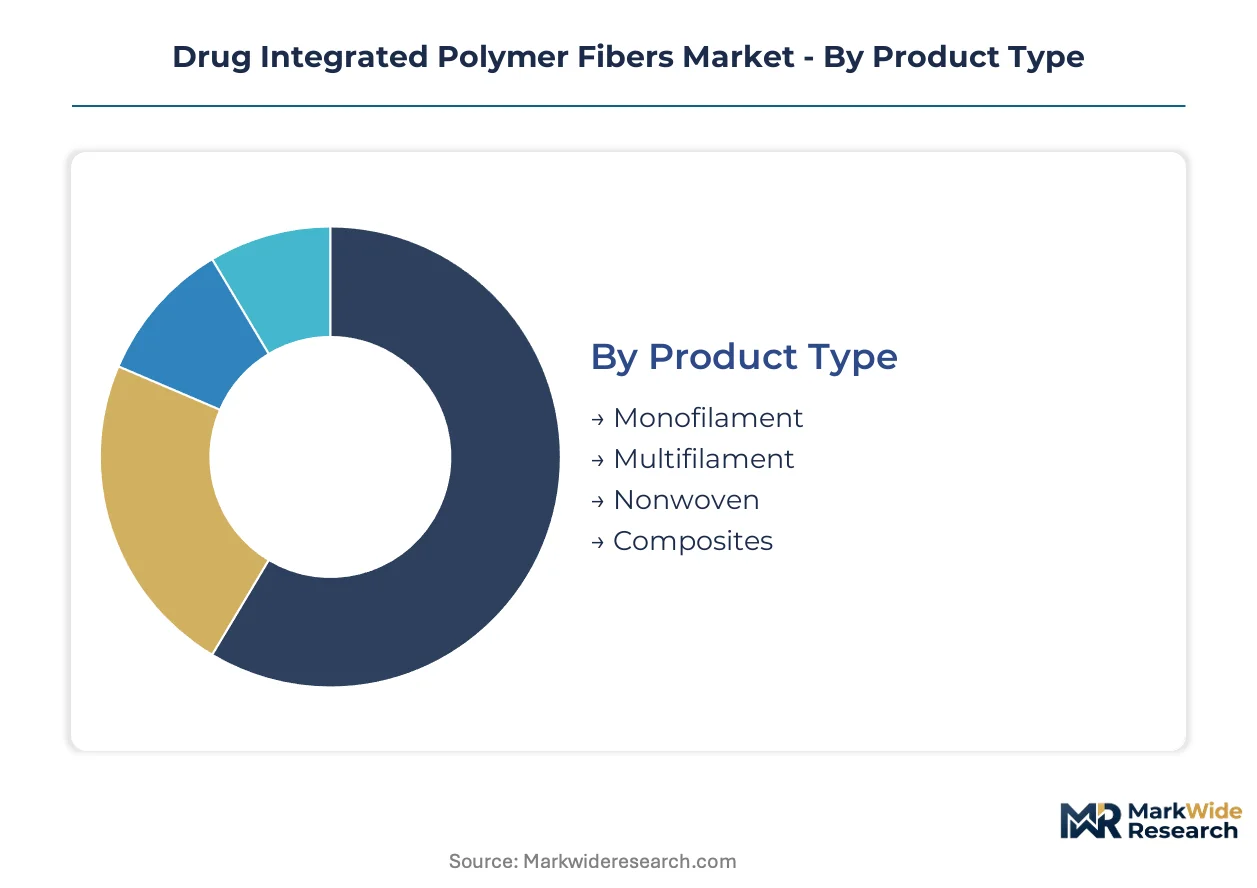
Segmentation in drug integrated polymer fibers reflects divergent manufacturing capabilities and regulatory pathways across therapeutic applications. Product architecture, clinical setting, and biodegradation requirements each create distinct commercial entry points for suppliers.
Product Type:
Electrospinning equipment suppliers in Germany and melt-spinning specialists in Japan concentrate production infrastructure around filament geometries that dictate release kinetics and mechanical performance.
- Monofilament:Single-strand configurations with diameters ranging from 10-100 micrometers enable precise implant positioning in cardiovascular stent coatings and suture-based drug delivery. German device manufacturers favor monofilament architectures for antiproliferative agent elution in peripheral artery interventions, though thermal processing limits payload compatibility to heat-stable small molecules.
- Multifilament:Braided or woven yarn structures dominate orthopedic and surgical applications requiring tensile strength and handling characteristics comparable to conventional sutures. Japanese textile-to-medical converters leverage existing braiding infrastructure from industrial fiber operations to supply braided multifilament constructs for anterior cruciate ligament repair with integrated anti-inflammatory release.
- Nonwoven:Electrospun mesh architectures with sub-micron fiber diameters maximize surface area for topical drug delivery and cell infiltration in wound care matrices.
- Composites:Hybrid structures combining fiber scaffolds with hydrogel or ceramic phases address load-bearing orthopedic applications requiring both drug release and structural support.
Multifilament absorbs the bulk of installed capacity; nonwoven is expanding most quickly.
Therapy Area:
Margin structures vary sharply across therapeutic categories, with cytotoxic handling protocols and extended clinical validation timelines creating tiered barriers to entry.
- Oncology:Localized tumor-targeting platforms command premium pricing due to the complexity of stabilizing cytotoxic agents within degradable polymer carriers. PMDA reimbursement pathways in Japan favor implantable fiber systems for hepatocellular carcinoma, while FDA breakthrough device designation accelerates review for glioblastoma interstitial chemotherapy.
- Cardiovascular:Drug-eluting fiber coatings on stents and vascular grafts require synchronization of antiproliferative release with endothelialization timelines. German manufacturers concentrate supply of polylactic-co-glycolic acid fiber wraps for drug-eluting balloon catheters, facing EMA MDR compliance burdens for post-market surveillance of implantable combinations.
- Neurology:Blood-brain barrier penetration challenges limit current fiber applications to implantable depot systems for chronic pain and epilepsy management.
- Orthopedics:Bioresorbable fixation devices with integrated antibiotic or growth factor release address surgical site infection and bone regeneration in trauma and spinal fusion procedures.
Cardiovascular captures the deepest regulatory expertise; oncology climbs the fastest as localized delivery displaces systemic chemotherapy protocols.
End User:
Procurement concentration and sterilization requirements segment demand across clinical settings with divergent capital equipment and staff training capabilities.
- Hospitals:Academic medical centers in the United States and Japan drive adoption of complex implantable fiber systems requiring surgical implantation and imaging follow-up. Hospital procurement consortia increasingly require integrated sterilization and lot-release documentation that favors suppliers with pharmaceutical-quality manufacturing infrastructure.
- Clinics:Outpatient settings concentrate demand for pre-sterilized, single-use fiber products in wound care and minor surgical applications where handling simplicity outweighs customization.
- Research Institutes:Preclinical and clinical trial material supply represents a fragmented demand base with stringent material characterization requirements.
- Home Healthcare:Transdermal and topical fiber applications for chronic wound management and hormone replacement therapy expand addressable market beyond institutional settings.
Hospitals dominate current volume; home healthcare is gaining share fastest as patient-administered transdermal platforms mature.
Application:
Functional requirements for mechanical support versus pure drug delivery create divergent polymer selection and processing specifications.
- Drug Delivery Systems:Implantable and topical platforms engineered for zero-order release kinetics of antibiotics, hormones, and chemotherapeutics. FDA combination product regulations govern these systems in the United States, requiring quality management systems spanning drug stability and device performance validation.
- Biodegradable Implants:Structural scaffolds designed for complete resorption synchronized with tissue regeneration timelines in bone, tendon, and vascular applications. Degradation rate matching to mechanical load-bearing requirements drives polymer molecular weight selection and crystallinity engineering.
- Wound Care:Antimicrobial-loaded nanofiber dressings leverage high surface area for exudate management and bacterial load reduction in chronic and burn wounds.
- Tissue Engineering:Cell-seeded fiber scaffolds for in vitro expansion or in situ regeneration of cartilage, skin, and neural tissues.
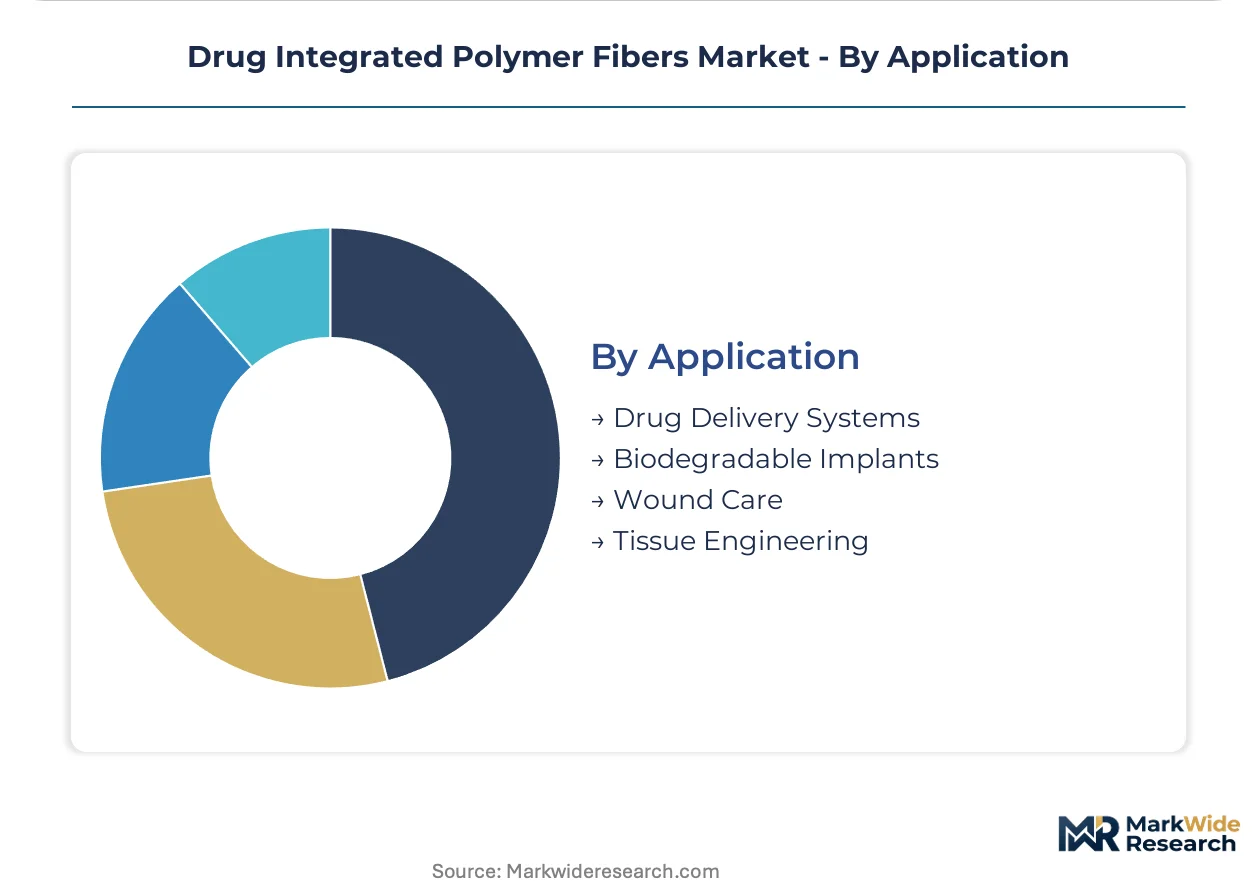
Drug delivery systems account for the majority of commercialized products; wound care shows the steepest expansion trajectory as antimicrobial resistance drives demand for localized silver and peptide release.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's precision manufacturing corridor concentrates electrospinning equipment suppliers and polymer processing expertise that lower technical barriers for clinical-scale fiber production. FDA combination product pathways in the United States and EMA medical device directives in Europe shape divergent clinical trial requirements across major markets. Japan's PMDA reimbursement stance on advanced wound care materials creates premium positioning opportunities for antimicrobial-loaded nanofiber platforms.
United States
Academic medical centers in Boston and the Research Triangle drive demand for complex implantable fiber systems requiring surgical implantation and imaging follow-up. FDA breakthrough device designation accelerates review timelines for glioblastoma interstitial chemotherapy applications. Hospital procurement consortia in the Northeast increasingly require integrated sterilization documentation that favors suppliers with pharmaceutical-quality manufacturing infrastructure.
Germany
Polylactic-co-glycolic acid fiber wraps for drug-eluting balloon catheters concentrate manufacturing in Bavaria and North Rhine-Westphalia. EMA MDR compliance burdens for post-market surveillance of implantable combinations elevate quality management requirements. The Stuttgart polymer cluster anchors supply relationships between electrospinning equipment fabricators and pharmaceutical formulators seeking tunable release kinetics.
Japan
PMDA's favorable reimbursement stance on advanced dressing materials creates premium positioning for antimicrobial-loaded nanofiber meshes in chronic wound management. METI funding programs support bioresorbable polymer chemistry advances that synchronize drug release with tissue regeneration timelines. Osaka-based textile-to-medical converters leverage existing braiding infrastructure from industrial fiber operations to supply orthopedic constructs.
China
NMPA medical device registration reforms streamline pathways for combination drug-device fiber implants targeting the domestic oncology sector. The Yangtze River Delta concentrates electrospinning scale-up manufacturing for export-oriented wound care applications. Shanghai's polymer science institutes collaborate with multinational pharmaceutical formulators on localized tumor-targeting delivery system validation.
Drug Integrated Polymer Fibers Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the drug integrated polymer fibers landscape, creating a tiered structure where polymer science heritage anchors supply relationships. BASF SE and Evonik Industries AG leverage diversified chemical portfolios to offer integrated drug-polymer formulation services. Teijin Limited and Toray Industries, Inc. represent textile-to-medical converters with established fiber processing infrastructure. Strategic moves concentrate on backward integration into medical-grade biopolymer feedstock and partnerships with pharmaceutical CDMOs for regulatory dossier depth.
Within the diversified chemical conglomerate tier, BASF SE and Evonik Industries AG exemplify players leveraging polymer science heritage to anchor supply relationships with pharmaceutical formulators. Among Japan-based textile specialists, Teijin Limited and Toray Industries, Inc. occupy positions that leverage existing braiding and weaving infrastructure from industrial fiber operations. TissueGen, Inc. represents the focused electrospinning specialist archetype, competing through nanofiber platform expertise in niche wound care and tissue engineering applications.
| Leading Market Players |
|---|
| BASF SE |
| DuPont de Nemours, Inc. |
| Teijin Limited |
| Toray Industries, Inc. |
| Evonik Industries AG |
| Solvay S.A. |
| TissueGen, Inc. |
| Micro Engineering Solutions, Inc. |
| Asahi Kasei Corporation |
| Others |
Supply Flow & Price Mechanics
Captive biopolymer production among German and Japanese specialty chemical conglomerates anchors both supply security and premium pricing power for clinical-grade fiber formulations. This backward integration into medical-grade polylactic acid and polycaprolactone feedstock insulates integrated manufacturers from raw material volatility while commanding price premiums for validated drug-polymer combinations.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent clinical-trial material orders from standard production schedules, with expedited electrospinning batches commanding substantial premiums over contracted offtake volumes. Three-tier pricing structure across premium, standard, and economy levels reflects FDA breakthrough device designation status, ISO 10993 certification completeness, and volume scale commitments. Pricing pressure stems from hospital procurement consortia consolidating vendor panels and demanding integrated sterilization documentation. Academic medical centers exhibit lowest price sensitivity due to reimbursement pass-through mechanisms, while outpatient clinics face acute cost compression.
Supply Chain Analysis
Dual-sourcing requirements mandated by FDA combination product regulations and EMA MDR quality management standards force pharmaceutical formulators to qualify multiple electrospinning equipment suppliers and biopolymer feedstock providers. Supply concentrates in Germany, Japan, and the United States, with Baden-Württemberg equipment fabricators, Osaka-based textile converters, and Boston-area CDMOs anchoring regional production nodes. Raw material dependencies center on medical-grade polylactic acid, polycaprolactone, and volatile organic solvent systems. Single-source biopolymer vulnerability from three specialty chemical producers creates structural supply risk. Distribution runs through pharmaceutical CDMOs and hospital procurement consortia rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical-grade biopolymer reactor capacity constraints prop pricing premiums for validated drug-polymer combinations, creating a supply-constrained market structure favoring incumbents with captive feedstock production.
For Market Incumbents: To counter emerging electrospinning specialists capturing niche wound care applications, BASF SE and Evonik Industries AG should expand captive polylactic-co-glycolic acid reactor capacity in North Rhine-Westphalia while accelerating FDA breakthrough device designation support for pharmaceutical partners. Backward integration into medical-grade feedstock remains the critical defensive lever against commodity polymer price volatility. For New Entrants and Emerging Players: Coaxial electrospinning platform expertise offers entry into dual-release cardiovascular applications underserved by incumbent melt-spinning infrastructure. White-space targets concentrate in transdermal vaccine delivery arrays and antimicrobial-loaded nanofiber meshes for Japanese chronic wound management procurement channels. Go-to-market positioning through academic medical center research partnerships bypasses consolidated hospital procurement barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified chemical conglomerates seeking pharmaceutical-quality manufacturing infrastructure and regulatory dossier depth. Long-term viability hinges on demonstrated lot-to-lot release consistency and EMA MDR compliance certification. The inflection signal to monitor is PMDA reimbursement expansion for advanced dressing materials in Japanese home healthcare channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Medical-Grade Biopolymer Production | Captive polylactic acid supply from Evonik's German reactors insulates against specialty chemical producer concentration risk. |
| FDA Breakthrough Device Designation Pathway | Accelerated review timelines for glioblastoma interstitial chemotherapy applications compress clinical validation periods. |
| Coaxial Electrospinning Platform Development | Core-shell fiber architectures enable German cardiovascular device manufacturers to unify dual-release anticoagulant therapies. |
| EMA MDR Quality Management Certification | Post-market surveillance compliance for implantable combinations elevates barriers against unqualified competitors. |
| Japanese Wound Care Procurement Channel Partnership | PMDA reimbursement alignment for antimicrobial nanofiber meshes opens premium positioning in chronic wound management. |
Methodological Framework
FDA 510(k) filings, EMA medical device registration databases, and ClinicalTrials.gov intervention records formed the secondary backbone, cross-referenced against primary interviews with electrospinning equipment engineers, pharmaceutical formulation scientists, hospital GPO contracts managers, and PMDA regulatory consultants. Bottom-up and top-down triangulation validated fiber production capacity estimates against pharmaceutical CDMO utilization rates and hospital procurement database spend patterns.
Bottom-up modeling of electrospinning and melt-spinning installed capacity across German, Japanese, and United States manufacturing clusters anchored volume projections, while top-down pharmaceutical drug-device combination spending patterns calibrated value estimates across the analysis window. Segmentation dimensions included product architecture, therapy area, biodegradation profile, and regional regulatory cluster. CAGR derivation incorporated polymer processing yield improvements, clinical trial initiation rates, and reimbursement pathway expansion trajectories specific to localized oncology delivery systems.
Several conditions sit outside the modeled scope, including preclinical-stage fiber platforms without active pharmaceutical ingredient partnerships, veterinary applications, and non-medical industrial filtration uses. Forecasts reflect assumptions regarding EMA MDR implementation timelines and PMDA reimbursement expansion for advanced wound care materials. A model refresh is warranted upon material change in FDA combination product review staffing levels or medical-grade biopolymer producer capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
North America Optical Fiber Raw Material Market
Fibers
Acoustical Fiber Board Market
Fibers
Global Perfluorinated Type Plastic Optical Fiber Market
Fibers
Asia-Pacific Insoluble Dietary Fibers Market
Fibers
Fiberglass Resin Market
Fibers
Global Fiberglass Mold Market
Fibers
Global Electronic Grade Glass Fibers Market
Fibers
Polycrystalline Alumina Fiber Market
Fibers
Microfibrillated Cellulose (MFC) Market
Fibers
Fiberglass Mat Market
Fibers
Global Basalt Fiber Market
Fibers
Europe Carbon Fiber Market
Fibers
Global R-Glass Fiber Market
Fibers
Carbon Fiber Market
Fibers
Global Fiber Reinforced Composites Market
Fibers
Asia-Pacific Carbon Fiber Market