
 Global Fiberglass Mold Market | 2026-2036
Global Fiberglass Mold Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fiberglass Mold Market Foresight
Direct procurement channels between wind blade manufacturers and mold fabricators is fragmenting as original equipment producers diversify supplier bases across multiple continents. Gurit Holding AG leverages its prepreg expertise to sustain premium positioning in aerospace-grade tooling. Janicki Industries Inc. anchors North American supply through large-scale five-axis machining capabilities for precision master plugs. TPI Composites Inc. competes on integrated blade-to-mold service bundles that reduce client lead times.
Fiberglass molds are precision tooling structures fabricated from glass-reinforced polymer composites, typically incorporating E-glass or S-glass fiber matrices bound by thermoset resins and engineered to withstand repeated thermal cycling above 150°C during part production. These molds enable net-shape manufacturing of large, geometrically complex components where metallic tooling would impose prohibitive weight and cost penalties. Compression molds command the deepest margin pools in high-volume automotive and consumer goods applications where cycle time economics dominate procurement decisions. Resin transfer molds represent the fastest-expanding technology segment as wind energy blade lengths exceed 80 meters and vacuum infusion processes become essential for void-free laminate quality.
EPA emission standards and REACH registration requirements in Europe are restricting volatile organic compound content in polyester and vinyl ester resin systems, pushing mold fabricators toward epoxy and phenolic formulations with lower hazardous air pollutant profiles. China's MEE enforces GB standards on industrial composite manufacturing that affect export-oriented mold producers supplying domestic wind turbine assembly lines. Stakeholders must monitor evolving F-Gas Regulation amendments in Europe and state-level renewable portfolio standards across multiple United States jurisdictions to anticipate capacity allocation decisions between marine, aerospace, and wind energy mold production.
Market Dynamics
Wind blade scaling beyond 100 meters is virtualizing traditional mold fabrication workflows, forcing fabricators to abandon segmented plug-and-mold approaches for continuous fiber placement systems that eliminate thermal expansion mismatches across joint lines.
Growth Catalysts
- Offshore wind buildout in China:State-backed coastal provinces mandate 80-meter-plus blade classes, requiring high-capacity mold infrastructure that domestic fabricators are scaling to meet.
- REACH resin reformulation:ECHA restrictions on styrene emissions in polyester systems push mold makers toward epoxy and phenolic chemistries with superior thermal cycling durability.
- Vacuum infusion process maturation:Closed-mold RTM techniques reduce void content below 0.5% in thick laminate sections, qualifying fiberglass molds for aerospace primary structure tooling.
Market Restraints
- Epoxy resin supply concentration:Three chemical conglomerates control 70% of aerospace-grade epoxy feedstock, exposing mold fabricators to price volatility and allocation risk.
- Master plug machining bottleneck:Five-axis gantry capacity for 50-meter-plus plugs concentrates in Germany and the United States, creating 14-18 month lead times for precision surface finishing.
- Steel mold substitution in high-volume automotive:Compression molding of Class-A body panels below 150°C cycle temperatures favors aluminum and steel tooling with faster heat transfer.
Strategic Opportunities
- India renewable manufacturing corridors:Tamil Nadu and Gujarat state industrial policies offer 25-year land leases for composite tooling facilities serving domestic wind turbine assembly.
- Thermoplastic resin convergence:Polypropylene and PEEK matrix systems enable in-situ welding of mold segments, eliminating bonded joints in large marine hull tooling.
- Digital twin integration:Real-time thermal mapping during blade cure cycles allows predictive mold maintenance, reducing unplanned downtime in 24/7 production environments.
Industry Challenges
- Composite tooling engineer scarcity:Master pattern fabrication and mold surface finishing require 8-12 year apprenticeship pipelines that technical institutes have failed to replenish.
- AS9100D certification timelines:Aerospace mold qualification demands 18-24 month audit cycles with documented thermal expansion coefficients across 150°C operational ranges.
- Legacy polyester mold retrofit complexity:Existing vinyl ester tooling cannot accommodate epoxy prepreg cure cycles without full surface reconstruction or replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fiberglass Mold Market |
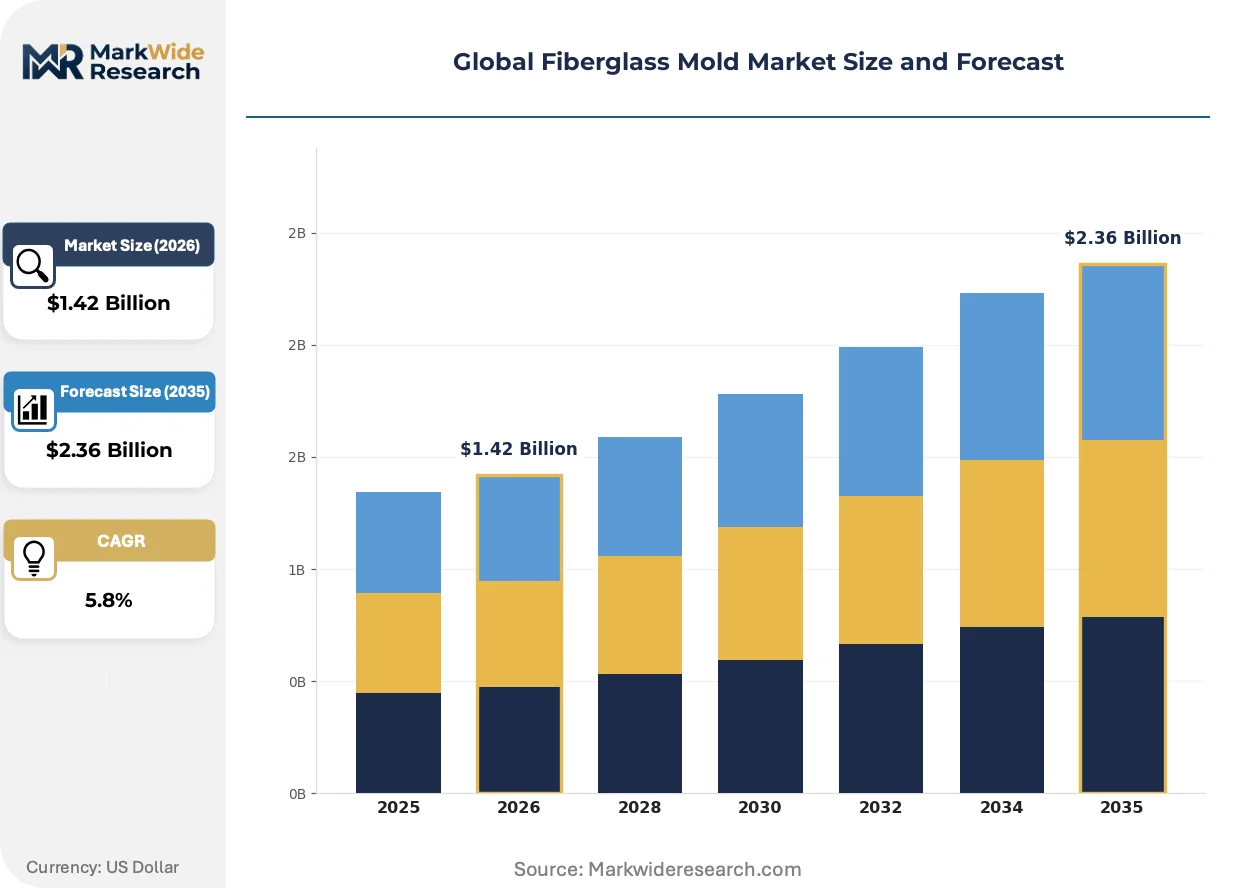
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Lay-Up Molds, Spray-Up Molds, Compression Molds, Injection Molds, Resin Transfer Molds Technology: Vinyl Ester, Polyester, Epoxy, Phenolic, Polyurethane Molds Application: Aerospace Components, Marine Equipment, Consumer Goods, Sports Equipment, Wind Energy End User Industry: Boat Manufacturers, Aircraft Assemblers, Sports Goods Producers, Renewable Energy Providers, Architectural Firms |
| Companies Covered | Gurit Holding AG, Janicki Industries Inc., Molded Fiber Glass Cos, TPI Composites Inc., Dencam Composite A/S, SSP Technology, Indutch Composites Technology Private Limited, Norco GRP Ltd, SCHÜTZ GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fiberglass Mold Market Shifts & Advancements
Computational design tools and in-process sensing are compressing mold development cycles while regulatory chemistry constraints reshape material selection across all major production geographies.
Modular plug-and-mold systems using carbon fiber reinforced polymer substructures are virtualizing traditional monolithic fiberglass construction. Wind turbine OEMs in Denmark and Spain now specify segmented mold architectures that ship in standard containers and assemble on-site. This approach collapses logistics costs for remote offshore wind manufacturing hubs while maintaining surface tolerances within 0.1 millimeters.
EPA New Source Performance Standards for reinforced plastic composites tighten volatile organic compound limits to 100 tons per year for major facilities. Mold fabricators in Texas and Florida are installing thermal oxidizers and switching to low-HAP epoxy formulations. The regulatory pressure falls heaviest on boat builders using open-mold spray techniques, accelerating closed-mold adoption in marine applications.
Blade manufacturers now contract directly for mold capacity rather than purchasing tooling outright. TPI Composites and LM Wind Power operate captive mold fleets while independent fabricators sell mold-hours through tolling agreements. This asset-light model concentrates in North American wind corridors where turbine OEMs prioritize balance sheet flexibility over tooling ownership.
Global Fiberglass Mold Market Segmentation
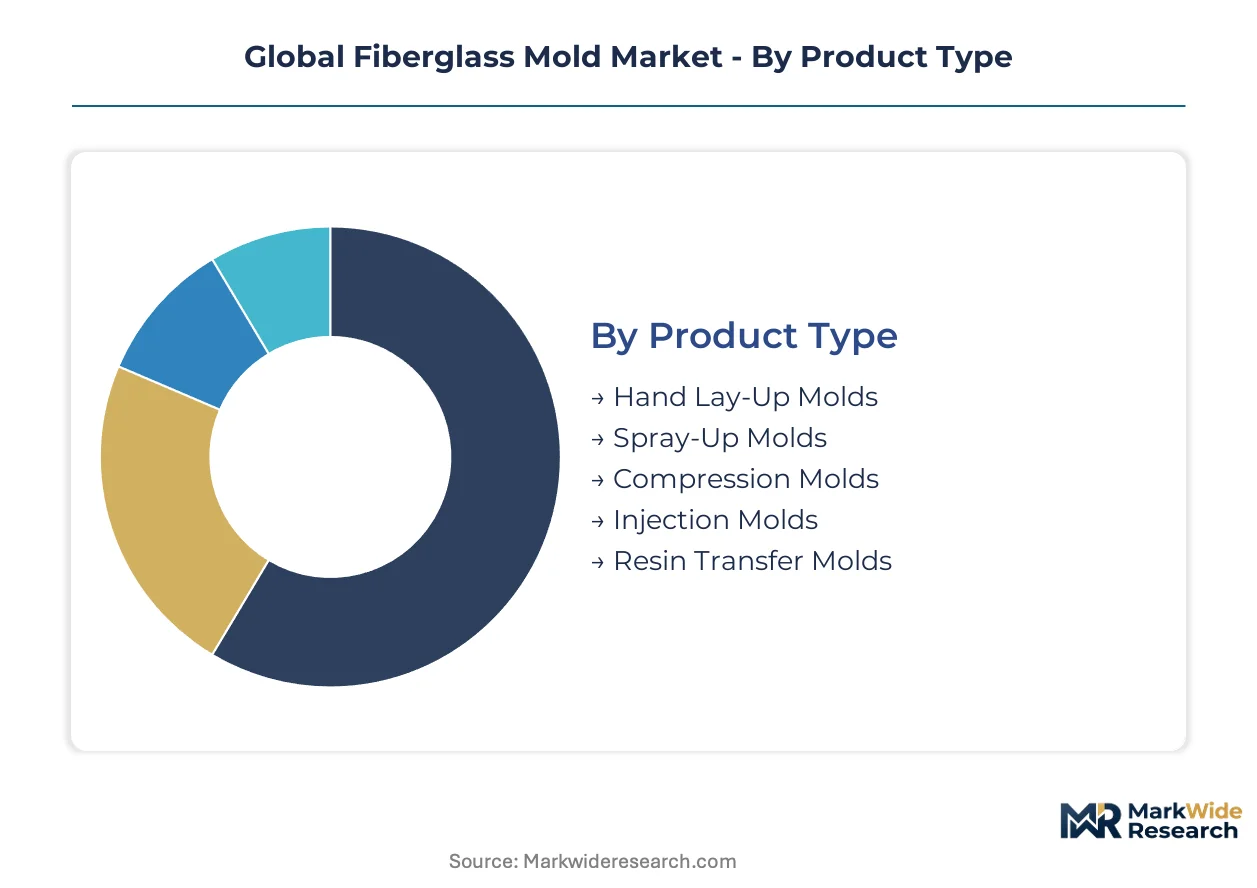
Segmentation in fiberglass molds reveals divergent service intensity profiles across product architectures. Compression and resin transfer systems demand precision refurbishment cycles every 2,000-4,000 shots, while hand lay-up tooling requires continuous surface restoration. Understanding these maintenance rhythms shapes procurement economics and supplier selection criteria.
Product Type:
After-sales service intensity varies dramatically by mold architecture, with closed-mold systems requiring thermal management recalibration and vacuum integrity testing throughout operational life.
- Compression Molds:Matched metal dies with heated platens sustain 150°C+ cycle temperatures for automotive body panel production. Demand concentrates in Germany and the United States where Tier 1 suppliers operate high-volume thermoset stamping lines; cycle time economics dominate procurement decisions despite premium upfront tooling costs.
- Resin Transfer Molds:Sealed cavity tooling with integrated injection ports and vacuum channels enables void-free laminate infusion for wind blades exceeding 80 meters. China anchors demand through state-backed offshore wind programs in Jiangsu and Guangdong provinces; blade scaling beyond 100 meters forces abandonment of segmented plug approaches.
- Hand Lay-Up Molds:Open-faced single-sided tooling accommodates low-volume marine hull and architectural component fabrication.
- Spray-Up Molds:Chopped fiber deposition systems serve boat builders with reduced labor content versus hand lamination.
- Injection Molds:High-pressure resin injection suits complex geometric consumer goods with tight dimensional tolerances.
Compression molds hold the largest share; momentum sits with resin transfer molds.
Technology:
Resin chemistry selection directly determines thermal cycling durability and regulatory compliance pathways across major production geographies.
- Epoxy Molds:Cross-linked thermoset systems with glass transition temperatures above 180°C accommodate aerospace autoclave cure cycles. Demand concentrates in France and Germany where AS9100D-certified fabricators supply Airbus and Safran tooling programs; REACH styrene restrictions accelerate substitution from polyester legacy systems.
- Phenolic Molds:Formaldehyde-condensed resin matrices deliver fire-resistant properties for rail and marine interior applications. China and India drive specification through GB and BIS flame-smoke toxicity standards; low smoke emission profiles qualify tooling for mass transit component production.
- Vinyl Ester Molds:Hybrid epoxy-polyester chemistry offers corrosion resistance for chemical processing equipment.
- Polyester Molds:Orthophthalic and isophthalic formulations dominate legacy marine tooling despite emission regulatory pressure.
- Polyurethane Molds:Elastomeric surface coatings enable rapid-cycle consumer goods production with reduced demold times.
Epoxy systems command premium positioning; phenolic formulations are climbing the fastest on regulatory tailwinds.
Application:
Application-driven segmentation exposes divergent tolerance requirements and certification burdens that reshape mold fabrication workflows.
- Wind Energy:Precision tooling for glass-reinforced epoxy blade shells and shear webs demands thermal expansion coefficients matched to 50-meter-plus laminate structures. Denmark and Spain specify segmented mold architectures that ship in standard containers; on-site assembly collapses logistics costs for remote offshore manufacturing hubs.
- Aerospace Components:Carbon fiber prepreg tooling for wing skins and control surfaces requires CTE-matched invar or composite mold faces. The United States and France concentrate demand through Boeing and Airbus supply chains; AS9100D qualification demands 18-24 month audit cycles with documented thermal expansion data.
- Marine Equipment:Hull and deck tooling for recreational vessels spans open-mold spray-up to closed-mold infusion systems.
- Consumer Goods:Appliance housings and furniture components utilize lower-cost polyester tooling with reduced durability requirements.
- Sports Equipment:Bicycle frames and ski molds balance weight optimization with impact resistance specifications.
Wind energy anchors current volume; aerospace components show the steepest expansion trajectory on qualification backlogs.
End User Industry:
End-user procurement models fragment between captive mold ownership and tolling-based capacity access across renewable energy corridors.
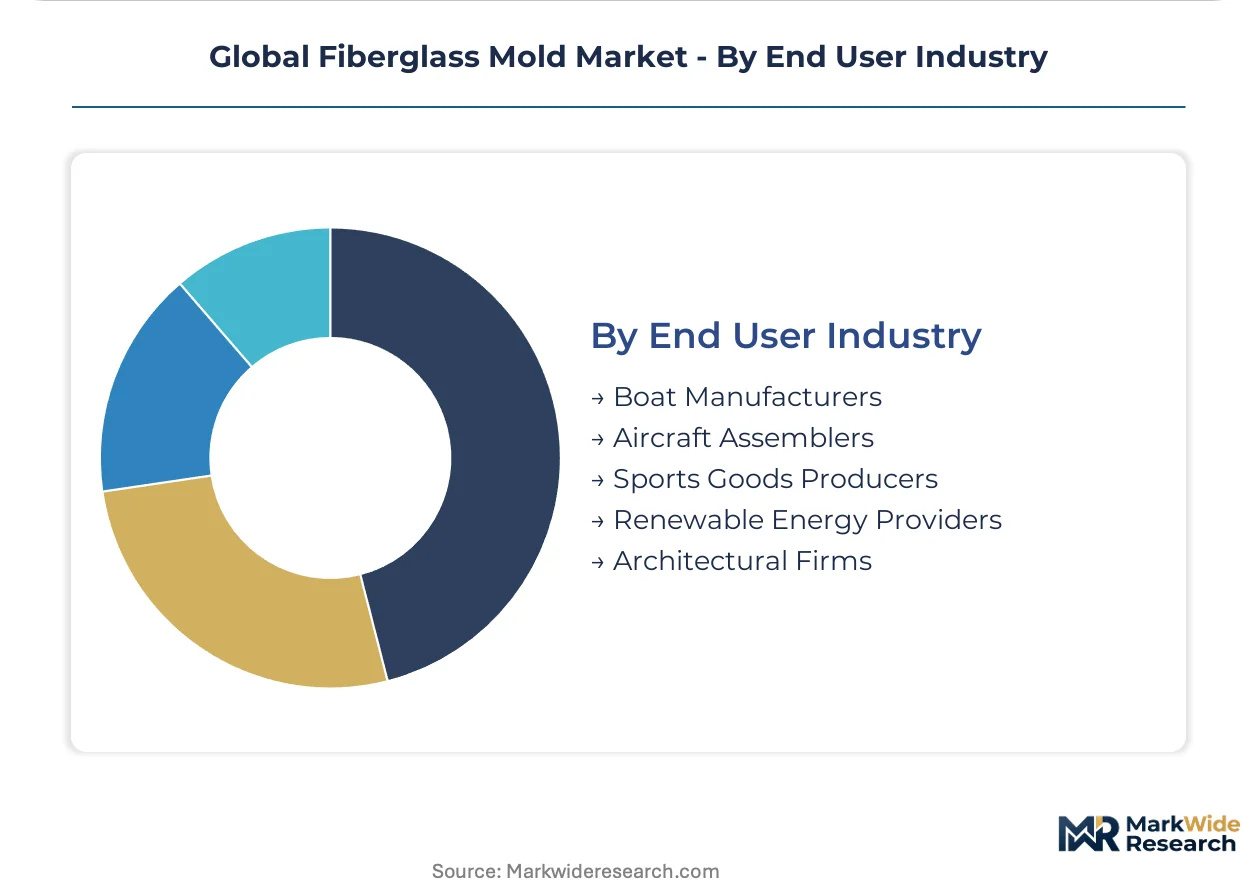
- Renewable Energy Providers:Wind turbine OEMs and project developers contract directly for mold capacity rather than purchasing tooling outright. TPI Composites and LM Wind Power operate captive fleets in the United States while independent fabricators sell mold-hours through tolling agreements; asset-light models prioritize balance sheet flexibility.
- Boat Manufacturers:Recreational and commercial vessel builders in Florida and Texas face EPA New Source Performance Standards tightening VOC limits to 100 tons annually; thermal oxidizer installation accelerates closed-mold adoption.
- Aircraft Assemblers:Prime contractors and tier suppliers specify mold thermal expansion coefficients for autoclave cure cycles.
- Sports Goods Producers:Bicycle and winter sports equipment manufacturers utilize lower-volume tooling with faster design refresh cycles.
- Architectural Firms:Building cladding and decorative composite elements require custom facade tooling with aesthetic surface finishes.
Renewable energy providers hold the largest share; boat manufacturers are gaining share fastest on regulatory-driven equipment upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese mold fabricators command pricing leverage through state-backed offshore wind procurement, while European suppliers absorb REACH compliance premiums that compress margin structures. This asymmetry reshapes capacity allocation decisions across major production geographies.
China
State-backed coastal provinces in Jiangsu and Guangdong mandate 80-meter-plus blade classes, driving high-volume mold infrastructure expansion. MEE enforces GB standards on industrial composite manufacturing that constrain emission profiles for export-oriented producers. The Yangtze River Delta cluster concentrates precision tooling capacity serving domestic turbine assembly lines.
Germany
Five-axis gantry capacity for 50-meter-plus master plugs concentrates in Bavaria and Baden-Württemberg, creating 14-18 month lead times for surface finishing. ECHA styrene restrictions accelerate substitution from polyester to epoxy formulations. The Mittelstand tooling sector around Stuttgart maintains AS9100D-certified capacity for aerospace autoclave applications.
United States
TPI Composites and LM Wind Power operate captive mold fleets across Texas and Iowa wind corridors, while independent fabricators sell mold-hours through tolling agreements. EPA New Source Performance Standards tighten VOC limits to 100 tons annually for major facilities. Thermal oxidizer installation accelerates in Florida boat-building clusters facing emission enforcement.
Denmark
Vestas and Siemens Gamesa specify segmented mold architectures that ship in standard containers and assemble on-site for remote offshore hubs. EU F-Gas Regulation amendments constrain refrigerant choices in mold temperature control systems. The Copenhagen-Aalborg corridor hosts design engineering for virtualized plug-and-mold workflows.
India
Tamil Nadu and Gujarat state industrial policies offer 25-year land leases for composite tooling facilities serving domestic wind turbine assembly. BIS flame-smoke toxicity standards drive phenolic resin specification for rail interior applications. The Chennai-Coimbatore belt attracts mold fabricators targeting renewable energy manufacturing corridors.
Global Fiberglass Mold Market Competitive Landscape
Integrated blade-to-mold service providers and precision machining specialists split the market along capability-depth lines. Consolidation concentrates around three strategic archetypes: captive fleet operators serving turbine OEMs directly, independent tolling-based fabricators selling mold-hours, and aerospace-grade specialists with AS9100D certification. Competitive moves center on geographic expansion into India renewable corridors and technology licensing for thermoplastic resin convergence.
Within the captive fleet tier, TPI Composites Inc. and Gurit Holding AG exemplify divergent strategic positioning. TPI Composites anchors North American supply through integrated service bundles that reduce client lead times. Gurit Holding AG, a Swiss-based AG, occupies premium positioning through prepreg expertise in aerospace-grade tooling. Janicki Industries Inc., a Washington State-based fabricator, represents the precision machining archetype with large-scale five-axis capabilities for master plug production.
| Leading Market Players |
|---|
| Gurit Holding AG |
| Janicki Industries Inc. |
| Molded Fiber Glass Cos |
| TPI Composites Inc. |
| Dencam Composite A/S |
| SSP Technology |
| Indutch Composites Technology Private Limited |
| Norco GRP Ltd |
| SCHÜTZ GmbH & Co. KGaA |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese mold fabrication clusters compresses pricing power for standard wind blade tooling while elevating premiums for aerospace-grade capacity. This utilization asymmetry forces European and North American suppliers toward configured-to-order positioning and captive fleet economics.
Pricing Analysis
Configured-to-order mold engineering commands 40-60 percent premiums over standard catalog offerings due to thermal expansion coefficient matching and AS9100D documentation requirements. Pricing stratifies across aerospace-certified, industrial-grade, and marine-economy tiers with differentiation resting on glass transition temperature thresholds and vacuum integrity guarantees. Cost compression in polyester-based marine tooling intensifies as EPA emission enforcement accelerates closed-mold conversion. Renewable energy providers exhibit highest price sensitivity due to tolling-based procurement models, while aerospace primes accept premium positioning for CTE-matched autoclave tooling.
Supply Chain Analysis
Epoxy resin feedstock draws from concentrated petrochemical complexes in Germany, South Korea, and the United States, with aerospace-grade formulations resting on bisphenol-A and epichlorohydrin supply chains. E-glass fiber roving sources from China, Egypt, and the United States, while five-axis gantry machining capacity for master plugs clusters in Bavaria and Washington State. Single-source vulnerability in aerospace epoxy precursors exposes mold fabricators to allocation risk during chemical plant turnarounds. Distribution runs through direct procurement channels between turbine OEMs and tier-one fabricators, supplemented by tolling agreements for independent mold-hour sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fiberglass mold demand sits in early-cycle expansion as blade scaling beyond 100 meters forces abandonment of segmented tooling architectures. Wind energy procurement models favor asset-light tolling structures over captive ownership.
For Market Incumbents: Harden aerospace certification moats through AS9100D audit maintenance and invar-face composite CTE matching capabilities. Defend against thermoplastic resin substitution by securing epoxy formulation partnerships with Huntsman and Hexion. Prioritize backward integration into five-axis master plug machining to collapse 14-18 month lead time bottlenecks.
For New Entrants and Emerging Players: India's Tamil Nadu and Gujarat renewable manufacturing corridors represent the most penetrable entry point given 25-year land lease incentives and underdeveloped domestic mold capacity. Marine retrofit demand in Florida and Texas offers secondary white-space as EPA thermal oxidizer mandates accelerate closed-mold conversion. Lead with tolling-based mold-hour sales to bypass capital-intensive fleet ownership barriers.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because REACH and EPA emission thresholds permanently elevate barriers for unspecialized fabricators. Target acquisition archetypes include AS9100D-certified precision machinists with aerospace customer relationships and Indian domestic producers with MEE GB standard compliance. Watch ECHA styrene restriction amendments as inflection signal for epoxy substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| AS9100D Certification Investment | Qualifies mold fabricators for Airbus and Boeing autoclave tooling programs with 18-24 month audit cycles. |
| Backward Integration into Master Plug Machining | Captures five-axis gantry value chain margin concentrated in Bavaria and Washington State. |
| India Manufacturing Corridor Entry | Accesses Tamil Nadu and Gujarat state land leases serving domestic wind turbine assembly demand. |
| Epoxy Resin Formulation Partnership | Secures aerospace-grade feedstock allocation from Huntsman and Hexion amid supply concentration risk. |
| Tolling-Based Mold-Hour Sales Model | Aligns with TPI Composites and LM Wind Power asset-light procurement preferences in North American wind corridors. |
Research Methodology
Cross-validation between primary interviews with mold fabrication engineers, wind turbine procurement directors, and aerospace quality assurance managers anchors the qualitative findings against secondary validation through ECHA REACH registration databases, EPA New Source Performance Standards filings, and China MEE GB standard documentation. Customs and trade data from Germany, China, and the United States triangulate capacity utilization signals with bottom-up facility assessments and top-down market sizing across compression, resin transfer, and hand lay-up mold architectures.
Calibration against historical CAGRs from wind energy installation trajectories and aerospace tooling qualification backlogs shapes the projection framework. Segmentation dimensions span product type, resin chemistry, application vertical, and end-user procurement model with regional regulatory cluster overlays. Growth rates derive from elasticity modeling of blade length scaling, emission compliance cost pass-through, and tolling agreement penetration across the analysis window.
Macroeconomic conditions sit as an overlay; deviation in offshore wind auction volumes, epoxy resin commodity pricing, or yuan-euro exchange rates would shift the trajectory. Forecasts embed assumptions around REACH amendment timelines and EPA enforcement intensity that regulatory discretion could revise. Cross-checking against IEA wind energy deployment benchmarks and Airbus-Boeing order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
PAN-Based Carbon Fibers Market
Fibers
Renewable Carbon Fibers Market
Fibers
Europe Carbon Fiber Market
Fibers
Polycrystalline Alumina Fiber Market
Fibers
Asia-Pacific Optical Fiber Raw Material Market
Fibers
Drug Integrated Polymer Fibers Market
Fibers
Polytetrahydrofuran Market
Fibers
Aramid Fiber Reinforcement Materials Market
Fibers
Glass Fiber Reinforced Polymer Market
Fibers
Artificial Muscle Fibers Market
Fibers
Global Nylon Monofilament Market
Fibers
Carbon Fiber in Light Weight Pressure Vessels Market
Fibers
Viscose Filament Yarn Market
Fibers
Natural Fiber Reinforcement Materials Market
Fibers
Micro-Fibrillated Cellulose Market
Fibers
E-Glass Fiber Market