
 Polytetrahydrofuran Market | 2026-2036
Polytetrahydrofuran Market Size, Share, and Industry Trends Forecast 2026-2036
Polytetrahydrofuran Market Analysis
REACH is consolidating the cost-of-entry calculus for European PTHF producers, forcing upstream investment in purification and traceability systems. BASF leverages its integrated C4 value chain to sustain margin capture across Ludwigshafen and Asian operations. Mitsubishi Chemical anchors its position through captive BDO supply and specialized elastomer-grade output. INVISTA competes on spandex precursor specialization, dominating the textile-facing segment of the PTHF trade.
Polytetrahydrofuran (PTHF) is a linear polyether diol synthesized via cationic ring-opening polymerization of tetrahydrofuran, with molecular weights typically ranging from 650 to 3000 g/mol and hydroxyl functionality determining end-use performance. The material serves primarily as a soft-segment building block for thermoplastic polyurethanes, spandex fibers, and high-performance elastomers where flexibility and hydrolysis resistance prove critical. Liquid-grade PTHF commands the dominant share of value given its direct use in cast elastomer and coating formulations, while fiber-grade material grows fastest through spandex chain expansion in Asia. Granule formats occupy a mature niche in adhesives and sealants where handling convenience outweighs melt-processing flexibility.
EPA oversight of tetrahydrofuran emissions shapes US plant siting and solvent recovery investments, while REACH registration requirements in Europe restrict non-compliant imports and elevate documentation burdens for downstream formulators. China's MEE enforces wastewater discharge limits on THF polymerization facilities, pushing producers toward closed-loop process water systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded capacity in grades that fail emerging purity or carbon-intensity thresholds.
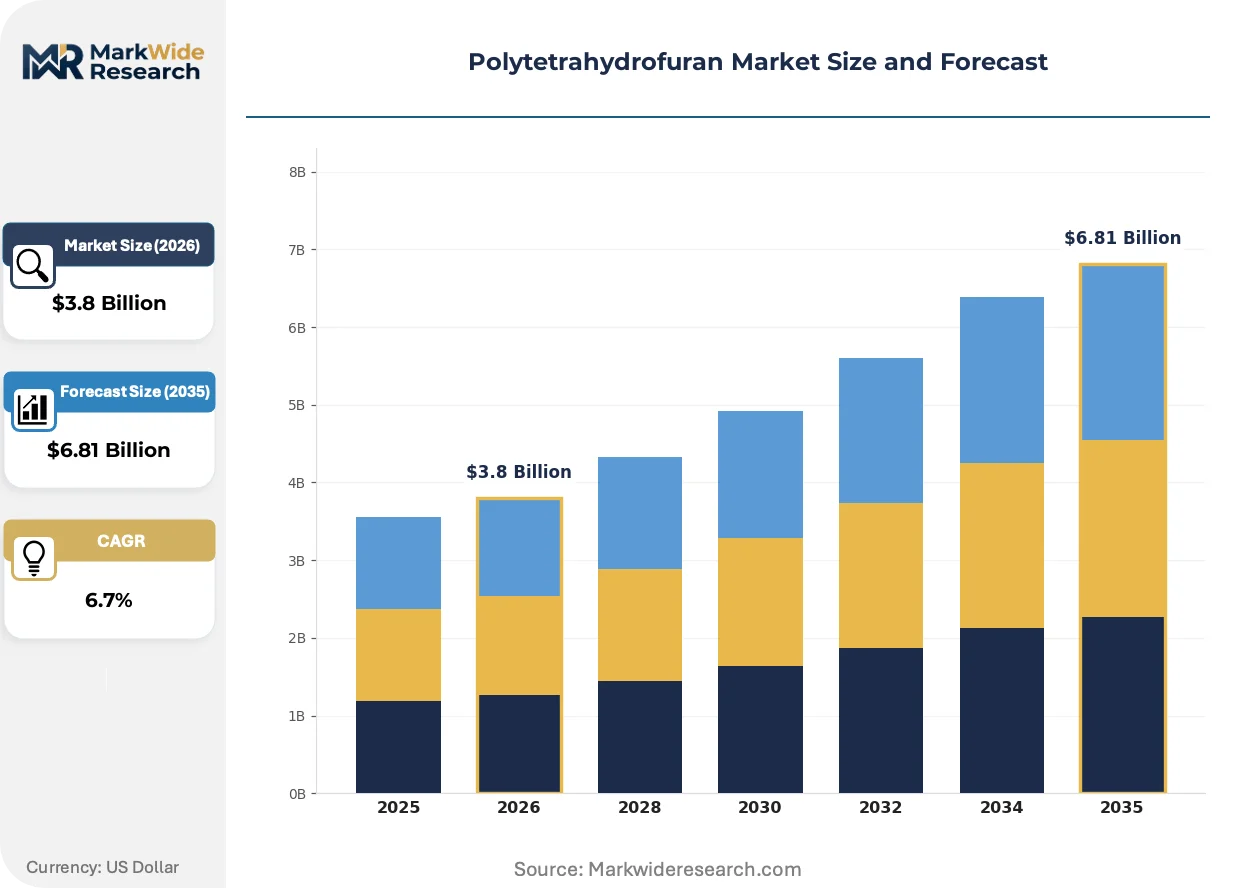
Market Dynamics
REACH compliance is forcing European PTHF producers to deploy closed-loop purification systems, while Asian spandex manufacturers drive volume concentration through integrated BDO-PTHF-spandex corridors. This regulatory-cost asymmetry is splitting competitive strategy between jurisdictions.
Growth Catalysts
- Spandex fiber expansion:Textile manufacturers in Vietnam and Indonesia are commissioning new elastomer-grade PTHF reactors to supply regional apparel hubs. This capacity buildout absorbs intermediate-grade output from established producers.
- REACH registration thresholds:ECHA's tightened purity documentation for polymer intermediates is locking out non-compliant imports, creating protected demand pockets for certified European supply.
- Thermoplastic polyurethane compounding:Automotive seating and medical tubing formulators are specifying higher molecular weight liquid PTHF grades for hydrolysis resistance in electric vehicle battery enclosures and sterilizable devices.
Market Restraints
- THF feedstock volatility:Tetrahydrofuran prices track n-butane and maleic anhydride markets, exposing PTHF margins to C4 value chain swings that producers cannot fully hedge.
- Chinese supply concentration:Coastal chemical clusters around Shanghai and Ningbo host over half of global PTHF nameplate capacity, creating single-geography risk for downstream formulators.
- Polyether glycol substitution:Polypropylene glycol and polycarbonate diols compete in lower-specification polyurethane soft-segments, capping PTHF pricing power in commodity elastomer applications.
Strategic Opportunities
- India specialty chemicals corridor:Gujarat and Maharashtra are attracting PTHF investments under PLI scheme incentives for advanced materials, with domestic BDO supply scaling through Reliance and BASF joint ventures.
- Bio-based THF pathways:Furan-to-THF hydrogenation technologies are maturing, offering defossilized feedstock routes for producers seeking EU Green Deal alignment and carbon-intensity certifications.
- Direct-to-compounder digital channels:Specialty distributors are launching technical e-procurement platforms that bypass traditional chemical merchant networks for mid-volume polyurethane formulators.
Industry Challenges
- Cationic polymerization expertise scarcity:Operating acid-catalyzed THF ring-opening systems requires specialized process safety training that competing industries drain from the talent pool.
- Multi-jurisdiction registration synchronization:Producers must align REACH dossiers, EPA TSCA filings, and China's MEE environmental permits for the same product grades, stretching regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polytetrahydrofuran Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granule, Powder, Liquid, Fiber End Use Industry: Automotive, Textile, Construction, Adhesives Application: Coatings, Sealants, Elastomers, Surfboards Distribution Channel: Direct Sales, Online Retail, Distributors, Manufacturers |
| Companies Covered | BASF, Dairen Chemical Corporation, Mitsubishi Chemical, INVISTA, Hyosung Chemical Fiber, Formosa Asahi Spandex, Korea PTG, Sinopec Yizheng, Ashland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polytetrahydrofuran Market Emerging Trajectories
Process intensification and regulatory digitization are compressing the gap between laboratory-grade PTHF specifications and industrial-scale output consistency. These forces are elevating quality assurance from a cost center to a competitive differentiator.
Continuous cationic polymerization reactor designs are automating molecular weight distribution control that batch systems achieved through manual sampling and adjustment. Spandex fiber producers in South Korea and Taiwan are adopting these systems to reduce off-specification lots. This automation is compressing the premium that laboratory-grade PTHF previously commanded over standard industrial material.
ECHA's SCIP database requirements for articles containing substances of very high concern are forcing PTHF downstream users to document polymer chain composition through the full supply chain. Polyurethane formulators serving European automotive OEMs must now certify diol purity at the monomer level. Medical device manufacturers are responding by specifying pre-certified elastomer-grade PTHF with full compositional traceability.
Buyers in China's Yangtze River Delta are consolidating annual PTHF contracts around three preferred suppliers rather than maintaining six-to-eight qualified sources. This concentration reflects risk-management fatigue from 2022-2023 feedstock disruptions and a preference for integrated BDO-PTHF producers with captive supply security. The shift is most visible in thermoplastic polyurethane compounding for synthetic leather, where formulators prioritize supply continuity over price competition.
Polytetrahydrofuran Market Segmentation
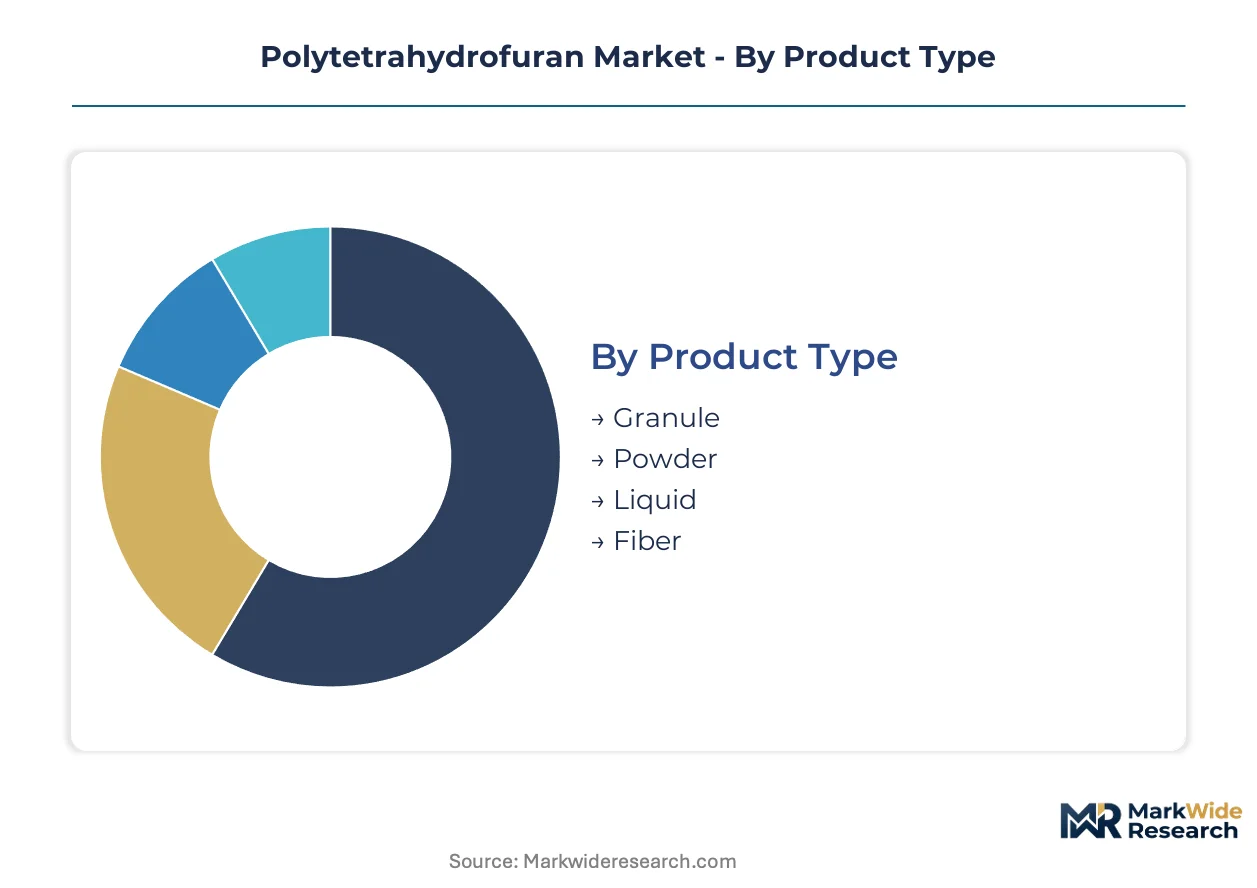
Polytetrahydrofuran grades differ fundamentally in processing characteristics and end-use performance. Formulators select formats based on melt viscosity requirements, hydroxyl functionality needs, and handling infrastructure constraints.
Product Type:
Material upgrades follow equipment replacement cycles in polyurethane compounding and fiber spinning, with processors timing format switches to capital expenditure windows.
- Liquid:Low-viscosity polyether diol with molecular weights from 650 to 3000 g/mol enables direct metering into cast elastomer and reactive coating systems. Demand clusters in China's Yangtze River Delta thermoplastic polyurethane compounding facilities, where continuous reactor designs favor pumpable feedstocks.
- Fiber:High-purity spandex precursor grades with narrow molecular weight distribution specifications serve textile fiber producers. Vietnam and Indonesia apparel hubs drive uptake as regional elastomer-grade reactors commission to supply integrated BDO-PTHF-spandex corridors.
- Granule:Solid-phase material for adhesive and sealant formulators prioritizing handling convenience over melt-processing flexibility. Mature niche with stable demand in construction bonding applications.
- Powder:Micronized format for specialized coating and surfboard lamination processes requiring precise dispersion control. Limited volume segment serving performance composites manufacturers.
Volume placements concentrate in Liquid; the faster expansion belongs to Fiber.
End Use Industry:
Cost-tier differentiation separates specification-grade automotive and medical applications from commodity textile and construction consumption.
- Textile:Spandex fiber production consumes the dominant share of elastomer-grade PTHF output. Asian apparel manufacturing clusters in Vietnam, Indonesia, and South Korea anchor demand through integrated precursor supply chains.
- Automotive:Thermoplastic polyurethane seating, interior skins, and electric vehicle battery enclosure seals specify higher molecular weight liquid grades for hydrolysis resistance and thermal stability. European OEMs enforce REACH-compliant purity documentation through ECHA SCIP database requirements.
- Construction:Sealant and adhesive formulators use granule and powder formats for moisture-cure polyurethane systems. Demand tracks building activity cycles with limited specification premium capture.
- Adhesives:Reactive hot-melt and structural bonding applications favor liquid and granule grades depending on application viscosity requirements. Industrial assembly lines drive consistent offtake.
Automotive commands the highest specification premiums; Textile generates the steepest expansion trajectory through regional capacity buildout.
Application:
Customer-type segmentation separates specification-driven medical and automotive formulators from price-sensitive industrial coatings buyers.
- Elastomers:Thermoplastic polyurethane soft-segments for cast wheels, rollers, and industrial belts demand precise hydroxyl functionality control. Medical device manufacturers specify pre-certified grades with full compositional traceability for sterilizable tubing.
- Coatings:Reactive polyurethane systems for industrial and automotive finishes use liquid PTHF as a flexibility and adhesion modifier. Formulators balance solvent-borne and high-solids formulations against volatile organic compound regulations.
- Sealants:Construction and transportation sealing applications combine PTHF polyols with isocyanate curing systems for elastic joint performance. Granule formats dominate batch mixing operations.
- Surfboards:Specialized lamination resins and core materials for performance watercraft represent a niche consumption segment with seasonal demand patterns.
Procurement is shifting toward certified elastomer grades in automotive and medical; surfboard applications remain fragmented across regional manufacturers.
Distribution Channel:
Supply concentration shapes channel selection, with integrated producers favoring direct relationships and specialty distributors capturing technical service requirements.
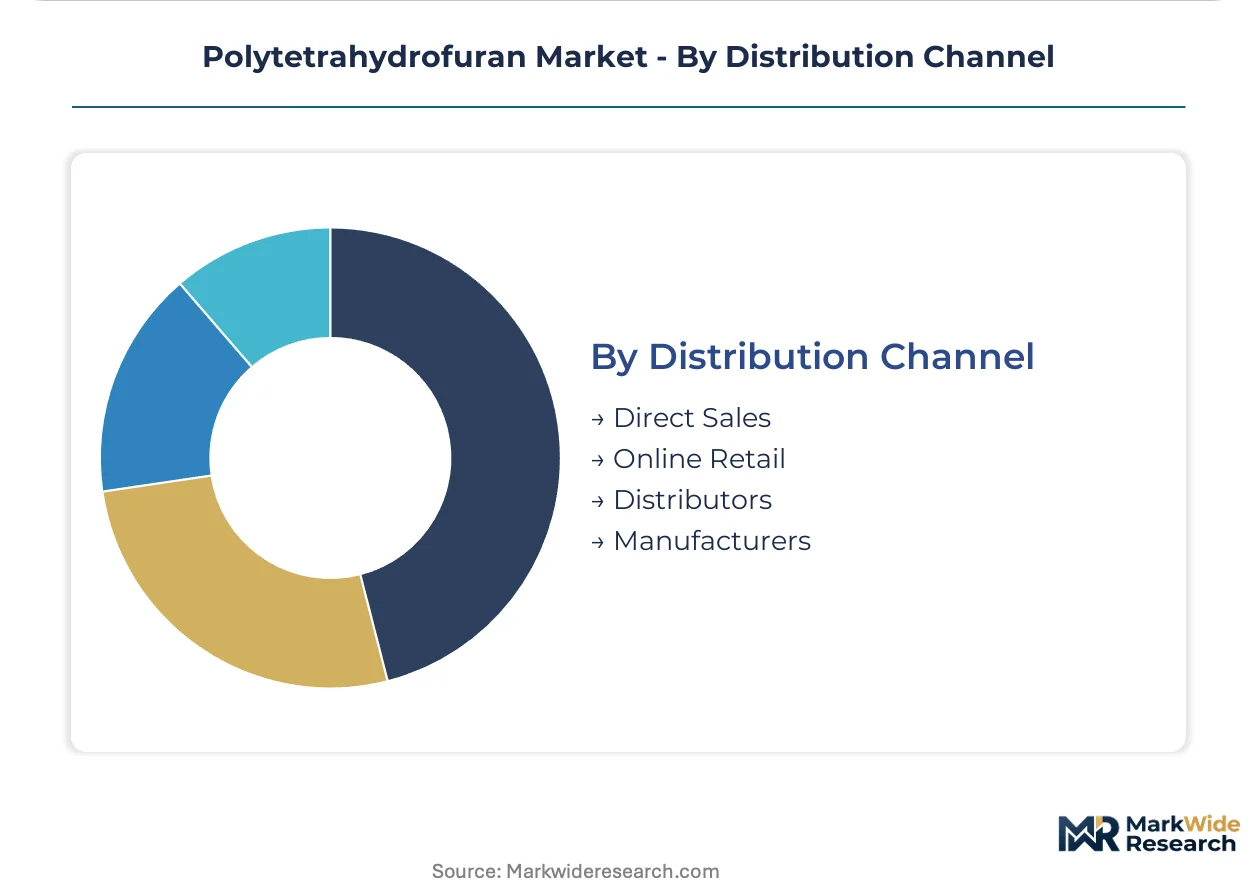
- Direct Sales:Volume contracts between PTHF producers and large polyurethane compounders, spandex fiber manufacturers, and automotive tier suppliers. China's Yangtze River Delta buyers are consolidating annual contracts around three preferred suppliers rather than maintaining six-to-eight qualified sources.
- Distributors:Technical distributors serve mid-volume formulators with inventory management, blending services, and regulatory documentation support. Specialty distributors are launching technical e-procurement platforms that bypass traditional chemical merchant networks.
- Manufacturers:Captive consumption through backward-integrated BDO-PTHF-spandex operations, particularly prevalent in Asian chemical clusters. Mitsubishi Chemical and BASF leverage integrated C4 value chains to sustain margin capture.
- Online Retail:Emerging channel for small-laboratory and pilot-scale procurement, with limited penetration in industrial-scale PTHF offtake.
Direct sales capture the largest volume commitments; distributor channels are expanding fastest through digital platform investments and technical service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal chemical clusters around Shanghai and Ningbo concentrate over half of global PTHF nameplate capacity, drawing feedstock integration advantages and export logistics infrastructure that rival production zones cannot replicate.
China
Spandex fiber manufacturers in Vietnam and Indonesia source elastomer-grade PTHF from integrated BDO-PTHF corridors along the Yangtze River Delta. China's MEE enforces wastewater discharge limits on THF polymerization facilities, pushing producers toward closed-loop process water systems. Ningbo and Shanghai host the dominant share of liquid-grade output serving thermoplastic polyurethane compounding operations.
Germany
Automotive seating and medical tubing formulators specify higher molecular weight liquid PTHF grades manufactured at Ludwigshafen and other Rhineland chemical sites. REACH registration requirements restrict non-compliant imports and elevate documentation burdens for downstream formulators. BASF leverages its integrated C4 value chain to sustain margin capture across European operations while serving export markets.
United States
EPA oversight of tetrahydrofuran emissions shapes plant siting decisions and drives solvent recovery investments along the Gulf Coast petrochemical corridor. Thermoplastic polyurethane producers for electric vehicle battery enclosures source hydrolysis-resistant grades from domestic compounders. Texas and Louisiana host the bulk of North American capacity, with formulators prioritizing supply security over price competition.
South Korea
Textile fiber producers in Gumi and Daegu commission continuous cationic polymerization reactor designs to reduce off-specification lots in spandex precursor manufacturing. The country's national chemical regulator enforces purity documentation aligned with ECHA SCIP database requirements for automotive OEM supply chains. Busan-Ulsan chemical complexes anchor integrated BDO-PTHF-spandex operations serving regional apparel hubs.
India
Gujarat and Maharashtra attract PTHF investments under PLI scheme incentives for advanced materials, with domestic BDO supply scaling through joint ventures. Polyurethane formulators for synthetic leather applications consolidate annual contracts around preferred suppliers with captive feedstock security. Reliance's Jamnagar complex anchors upstream integration efforts for specialty chemicals production.
Polytetrahydrofuran Market Vendor Landscape
German and Chinese producers anchor one tier; South Korean and Taiwanese specialists hold differentiated positions in fiber-grade refinement. The market structures around integrated petrochemical conglomerates with captive BDO supply, mid-scale regional compounders serving textile corridors, and technology licensors exporting continuous polymerization designs. Strategic moves concentrate on backward integration into THF feedstock and certification investments for REACH-compliant purity documentation.
Within the integrated petrochemical tier, BASF, Mitsubishi Chemical, and INVISTA exemplify divergent geographic and segment positioning. BASF represents European-based value chain integration with C4 chemistry dominance. Mitsubishi Chemical anchors Japanese production through specialized elastomer-grade output. INVISTA occupies a position in spandex precursor specialization, dominating textile-facing segments of the PTHF trade through North American and Asian operational footprints.
| Leading Market Players |
|---|
| BASF |
| Dairen Chemical Corporation |
| Mitsubishi Chemical |
| INVISTA |
| Hyosung Chemical Fiber |
| Formosa Asahi Spandex |
| Korea PTG |
| Sinopec Yizheng |
| Ashland |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between REACH-compliant European supply and standard-grade Asian output shapes both pricing power and procurement geography. Premium-capture concentrates with producers holding ECHA-validated dossiers, while commodity-grade liquid PTHF trades on spot THF feedstock differentials across China's coastal clusters.
Pricing Analysis
Short-lead-time premiums of fifteen to twenty percent separate spot buyers from annual contract holders in Asian spandex precursor markets. Pricing stratifies across certified elastomer-grade, standard liquid-grade, and granule formats based on hydroxyl functionality precision and documentation depth. Cost compression in standard liquid grades intensifies as polypropylene glycol substitution threats cap ceiling prices. Automotive formulators exhibit lowest price sensitivity, prioritizing REACH-compliant traceability over unit cost.
Supply Chain Analysis
Direct-to-compounder channels handle hyperscale thermoplastic polyurethane demand in China's Yangtze River Delta, while technical distributors serve mid-volume formulators with blended inventory and regulatory documentation. Supply concentrates in China, Germany, and South Korea, with feedstock drawn from n-butane derivatives and maleic anhydride pathways. Single-geography vulnerability runs through Shanghai-Ningbo chemical corridors, where over half of global nameplate capacity sits within flood-prone coastal zones. Distribution runs through integrated BDO-PTHF-spandex corridors in Asia and merchant chemical networks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous cationic polymerization automation is displacing legacy batch reactor systems, compressing quality premiums and forcing capital reinvestment timelines.
For Market Incumbents: Deepen backward integration into THF feedstock through captive BDO supply or long-term offtake agreements with C4 crackers, insulating margins from n-butane volatility. Fortify REACH dossier maintenance and SCIP database compliance infrastructure to defend European automotive and medical share against emerging bio-based THF entrants. For New Entrants and Emerging Players: Begin with India's Gujarat-Maharashtra specialty chemicals corridor, where PLI scheme incentives and nascent domestic BDO supply create white-space opportunity for elastomer-grade PTHF. Target synthetic leather formulators consolidating procurement around preferred suppliers with captive feedstock security, offering technical service bundling as differentiation. For Investors and Strategic Acquirers: Re-rating potential sits with continuous polymerization technology licensors given automation adoption curves in South Korean and Taiwanese fiber-grade operations. Monitor bio-based THF pathway maturation as inflection signal for defossilized feedstock premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into BDO Feedstock | Captive supply security anchors margin stability against C4 value chain swings. |
| Continuous Reactor Technology Deployment | Automation reduces off-specification lots for South Korean spandex producers. |
| REACH Dossier Certification Investment | ECHA compliance unlocks protected demand pockets in European automotive supply. |
| Bio-Based THF Pathway Development | Furan hydrogenation technologies align with EU Green Deal carbon-intensity thresholds. |
| Direct E-Procurement Platform Launch | Technical distributors bypass merchant networks for mid-volume polyurethane formulators. |
Methodological Framework
Multi-period observation of THF feedstock pricing spreads, REACH registration timelines, and spandex fiber capacity commissioning anchored the trend analysis, supplemented by interviews with plant managers at integrated petrochemical complexes, procurement leads at polyurethane compounders, distribution channel partners in Asian chemical clusters, and technical R&D directors specializing in cationic polymerization. Secondary validation drew from customs trade data, ACC and Cefic industry reports, SEC 10-K filings of listed chemical producers, and ECHA registration dossiers. Bottom-up capacity modeling and top-down demand triangulation from end-use consumption verified volume estimates.
Segment-weighting across molecular weight tiers, format types, and end-use industries structured the analytical framework, with regional production hub clustering as an additional dimension. CAGRs were derived from fitted trend extrapolation against historical commissioning cycles and announced capacity additions. Forecast inputs incorporated BDO supply elasticity, textile fiber demand trajectories in Vietnam and Indonesia, and regulatory divergence scenarios between REACH and China's MEE discharge limits.
Underlying measurement precision varies by segment; certified elastomer-grade and fiber-grade categories carry tighter precision than commodity liquid-grade volumes given disclosure concentration among integrated producers. Forecasts reflect assumptions regarding THF feedstock cost pass-through rates, spandex substitution elasticity, and regulatory harmonization timelines. Periodic stress-testing of base assumptions against feedstock disruption events and certification requirement changes is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Fiberglass Sunscreen Market
Fibers
E-Glass Fiber Market
Fibers
Artificial Muscle Fibers Market
Fibers
Global Glass Fiber Reinforced Gypsum (GFRG) Market
Fibers
Short Fiber Thermoplastics Market
Fibers
North America Carbon Fiber Market
Fibers
Carbon Fiber Filament Market
Fibers
Fiberglass Resin Market
Fibers
High Performance Fibers for Defense Market
Fibers
4-Strand Fan-Shaped Strand Wire Rope Market
Fibers
North America Optical Fiber Raw Material Market
Fibers
Ultra-High Molecular Weight Polyethylene Fibers Market
Fibers
Viscose Market
Fibers
Asia-Pacific Carbon Fiber Market
Fibers
Fiber Metal Laminate (FML) Market
Fibers
North America Glass Fiber Reinforced Gypsum Market