
 Listeriosis Treatment Market | 2026-2036
Listeriosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Listeriosis Treatment Market Foresight
The FDA's updated Food Safety Modernization Act enforcement protocols is realigning hospital procurement priorities toward broad-spectrum antimicrobial readiness. Pfizer Inc. leverages its manufacturing scale to maintain consistent ampicillin supply chains across acute care networks. Sun Pharmaceutical Industries Limited anchors generic gentamicin production for cost-sensitive institutional buyers. Novartis AG competes through specialized hospital formulary partnerships in North American and European tertiary centers.
Listeria monocytogenes infection management encompasses antimicrobial therapy targeting gram-positive intracellular pathogens, with first-line regimens combining ampicillin or penicillin G with aminoglycosides to achieve bactericidal synergy and cerebrospinal fluid penetration. The primary clinical purpose centers on reducing mortality in invasive manifestations, particularly among neonates, elderly patients, and immunocompromised hosts where case fatality rates remain elevated. Antibiotics dominate current value generation due to established clinical protocols and mandatory stockpiling requirements, while intravenous delivery commands preference in severe CNS and sepsis presentations where rapid therapeutic levels prove critical. Supportive care occupies a secondary but structurally important position as prolonged ICU stays generate ancillary revenue streams.
FDA antimicrobial stewardship guidelines, EMA pharmacovigilance frameworks, and WHO essential medicines listings collectively shape prescribing patterns, manufacturing priorities, and market access conditions for listeriosis therapeutics. These regulatory layers enforce quality benchmarks, restrict empirical broad-spectrum overuse, and influence national stockpiling mandates that directly determine manufacturer offtake volumes. Stakeholders must monitor evolving resistance surveillance data and alternative therapy pipelines to anticipate shifts in first-line protocol design and procurement specifications.
Market Dynamics
FDA antimicrobial stewardship mandates are compressing empirical broad-spectrum prescribing windows, forcing acute care networks to pre-position targeted gram-positive coverage while maintaining cost discipline.
Growth Catalysts
- Neonatal ICU protocol standardization:National perinatal quality collaboratives in the United States mandate ampicillin-gentamicin readiness for early-onset sepsis coverage, institutionalizing dual-therapy procurement.
- EMA pharmacovigilance frameworks:Strengthened adverse event reporting for foodborne pathogens drives tertiary centers toward documented bactericidal synergy regimens with established cerebrospinal fluid penetration.
- Immunocompromised patient volume expansion:Transplant oncology and biologic therapy growth in tertiary referral networks sustains standby intravenous antimicrobial inventories for atypical CNS presentations.
Market Restraints
- API supply concentration:Penicillin G and ampicillin active pharmaceutical ingredient manufacturing clusters in China create single-source vulnerability for North American and European formulators.
- Aminoglycoside nephrotoxicity monitoring burden:Gentamicin therapeutic drug monitoring requirements prolong ICU length of stay and elevate ancillary labor costs, pressuring formulary committees toward alternative synergy approaches.
- Generic price erosion:Off-patent status across first-line agents compresses manufacturer margins, reducing incentive for production capacity expansion during shortage periods.
Strategic Opportunities
- Alternative synergy regimens:Linezolid and trimethoprim-sulfamethoxazole combinations for penicillin-allergic patients represent underdeveloped protocol segments with limited dedicated manufacturing.
- Point-of-care molecular diagnostics:Rapid Listeria species identification from cerebrospinal fluid specimens enables targeted therapy initiation, reducing empirical broad-spectrum exposure and supporting stewardship metrics.
- Stockpiling mandate expansion:WHO essential medicines list inclusion for listeriosis coverage prompts national strategic reserve specifications in middle-income health systems previously reliant on ad hoc procurement.
Industry Challenges
- Specialized infectious disease pharmacist scarcity:Tertiary centers face recruitment gaps for clinicians capable of optimizing aminoglycoside dosing in renal impairment and pregnancy.
- Legacy EMR integration complexity:Antimicrobial stewardship dashboard deployment requires costly interface development with established electronic medical record platforms, delaying real-time prescribing intervention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Listeriosis Treatment Market |
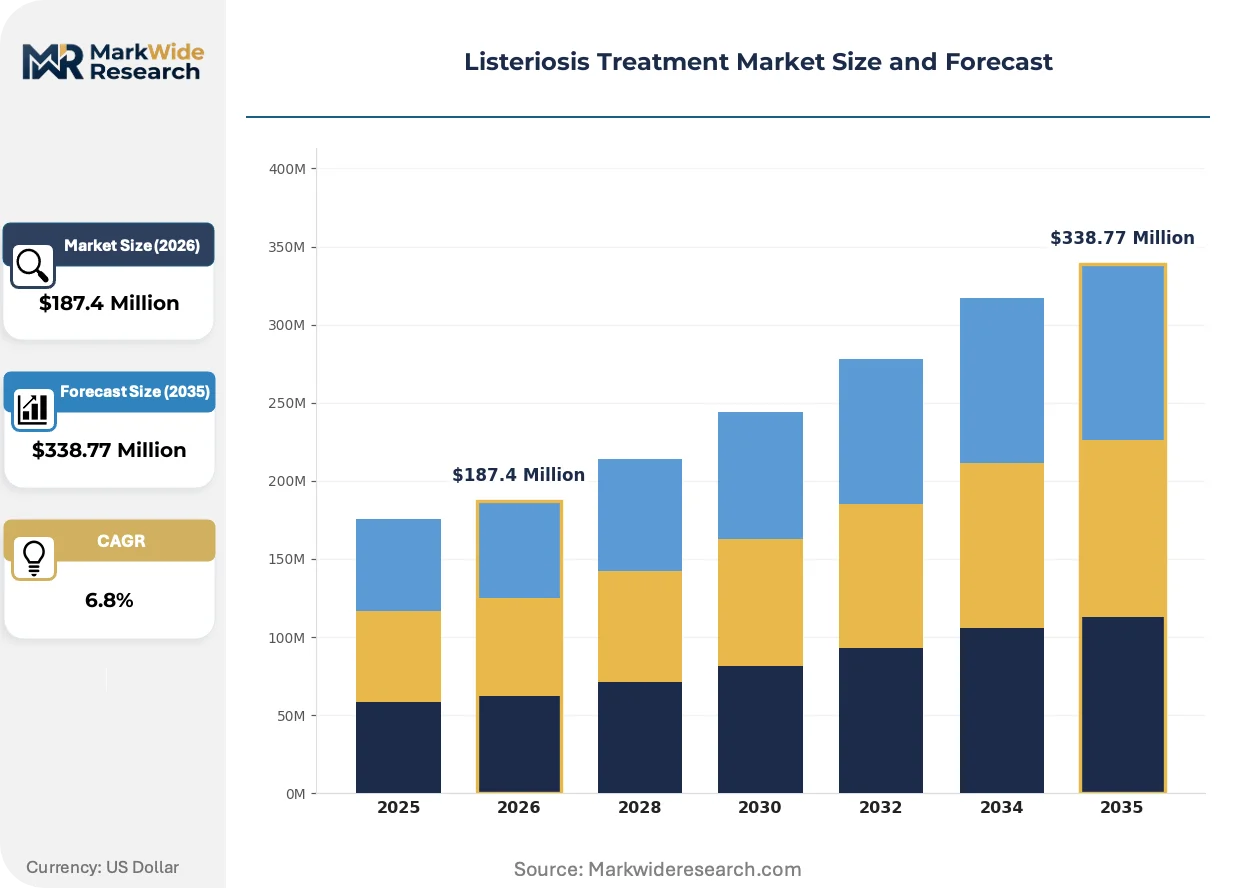
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Supportive Care, Immunoglobulin Therapy, Probiotics Application: Vertical Infections, Central Nervous System Infection, Gastric Infection, Sepsis End User: Hospitals, Clinics, Long-term Care Facilities, Home Care Delivery Mode: Parenteral, Oral, Intravenous, Topical |
| Companies Covered | Pfizer Inc., Novartis AG, Sanofi S.A., Teva Pharmaceutical Industries Ltd., GlaxoSmithKline plc, Merck & Co., Inc., AstraZeneca PLC, Cipla Ltd., Sun Pharmaceutical Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Listeriosis Treatment Market Shifts & Advancements
Diagnostic acceleration and regulatory pressure on empirical prescribing are compressing the window between symptom presentation and pathogen-directed therapy selection in invasive listeriosis management.
Phage therapy development for intracellular gram-positive pathogens is converging with CRISPR-engineered bacteriophage platforms that penetrate Listeria monocytogenes biofilm matrices. Academic medical center microbiology laboratories in the United States and Switzerland are piloting compassionate-use protocols for refractory CNS infections. This convergence is enabling alternative therapeutic pathways for patients with severe beta-lactam hypersensitivity, though manufacturing scale remains constrained.
REACH authorization requirements for pharmaceutical manufacturing effluent are tightening environmental discharge standards for antibiotic production facilities across European Union member states. EMA guidance on manufacturing-derived antimicrobial resistance gene dissemination is forcing API producers to invest in closed-system fermentation and advanced wastewater treatment. German and Dutch formulation plants are responding with supplier qualification audits that prioritize environmental compliance alongside traditional quality metrics.
Consolidated purchasing through national hospital group procurement organizations is displacing fragmented institutional tendering for parenteral antibiotics in North American acute care networks. These entities now negotiate multi-year ampicillin and gentamicin supply agreements with penalty clauses for shortage-related stockouts. The behavioral shift is most visible in United States health systems participating in CMS accountable care frameworks, where total cost of care metrics reward reduced therapeutic failure rates.
Listeriosis Treatment Market Segmentation
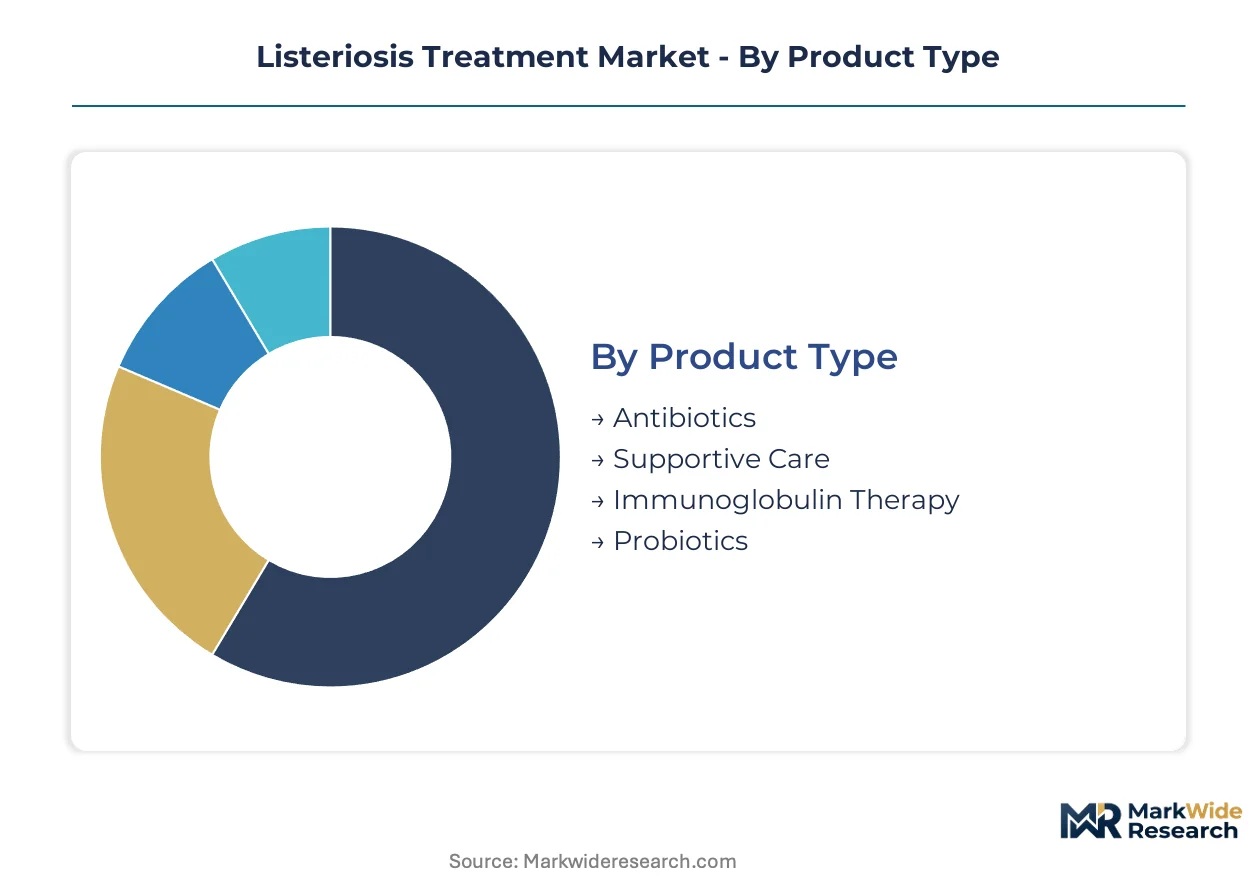
Listeriosis treatment protocols vary sharply by infection severity, patient immunocompetence, and care setting economics. Segmentation reveals where pharmaceutical investment concentrates versus where ancillary services generate secondary revenue.
Product Type:
Antimicrobial mechanism and clinical efficacy define procurement hierarchies across acute care networks.
- Antibiotics:Beta-lactam and aminoglycoside combinations achieve bactericidal synergy against intracellular Listeria monocytogenes with established cerebrospinal fluid penetration. Hospital formularies in the United States maintain ampicillin-gentamicin as mandatory stockpile items under perinatal quality collaborative mandates.
- Supportive Care:Intensive care unit management of septic shock and respiratory failure extends length of stay and generates substantial ancillary revenue. Tertiary centers in Germany bundle mechanical ventilation and vasopressor therapy into diagnosis-related group reimbursement frameworks.
- Immunoglobulin Therapy:Adjunctive intravenous immunoglobulin for refractory neonatal sepsis remains limited to specialized pediatric referral networks.
- Probiotics:Competitive exclusion products for high-risk food handlers show preventive application in institutional food service settings.
Antibiotics lead on scale; probiotics lead on momentum.
Application:
Mortality risk stratification determines therapeutic intensity and reimbursement tier placement.
- Central Nervous System Infection:Meningitis and meningoencephalitis presentations demand prolonged parenteral therapy with documented blood-brain barrier penetration. Swiss tertiary centers report extended ICU stays for rhombencephalitis variants requiring multidisciplinary neurocritical care.
- Sepsis:Bacteremic spread triggers empirical broad-spectrum initiation before pathogen identification, concentrating resource consumption in emergency departments. United States sepsis bundle compliance mandates drive rapid antimicrobial administration within one hour of recognition.
- Vertical Infections:Maternal-fetal transmission protocols in France mandate prenatal screening and intrapartum prophylaxis for documented colonization.
- Gastric Infection:Gastroenteritis presentations in immunocompetent hosts typically resolve without antimicrobial intervention, limiting pharmaceutical utilization.
CNS infection commands the highest reimbursement intensity; sepsis protocols drive the steepest volume expansion.
End User:
Care setting infrastructure determines therapy modality and monitoring capability.
- Hospitals:Acute care networks command intravenous antimicrobial administration with therapeutic drug monitoring for aminoglycoside nephrotoxicity surveillance. Japanese tertiary centers maintain dedicated infectious disease pharmacist staffing for complex dosing optimization.
- Long-term Care Facilities:Skilled nursing environments face heightened regulatory scrutiny following multistate outbreak investigations, prompting enhanced food safety and surveillance protocols. CMS surveyor emphasis on environmental contamination control drives consulting expenditure.
- Clinics:Outpatient parenteral antimicrobial therapy programs enable step-down management for stable patients completing extended courses.
- Home Care:Infusion nursing services support early discharge for patients with reliable vascular access and caregiver support structures.
Hospitals dominate absolute expenditure; long-term care facilities are gaining regulatory attention fastest.
Delivery Mode:
Pharmacokinetic requirements and infection severity dictate route selection.
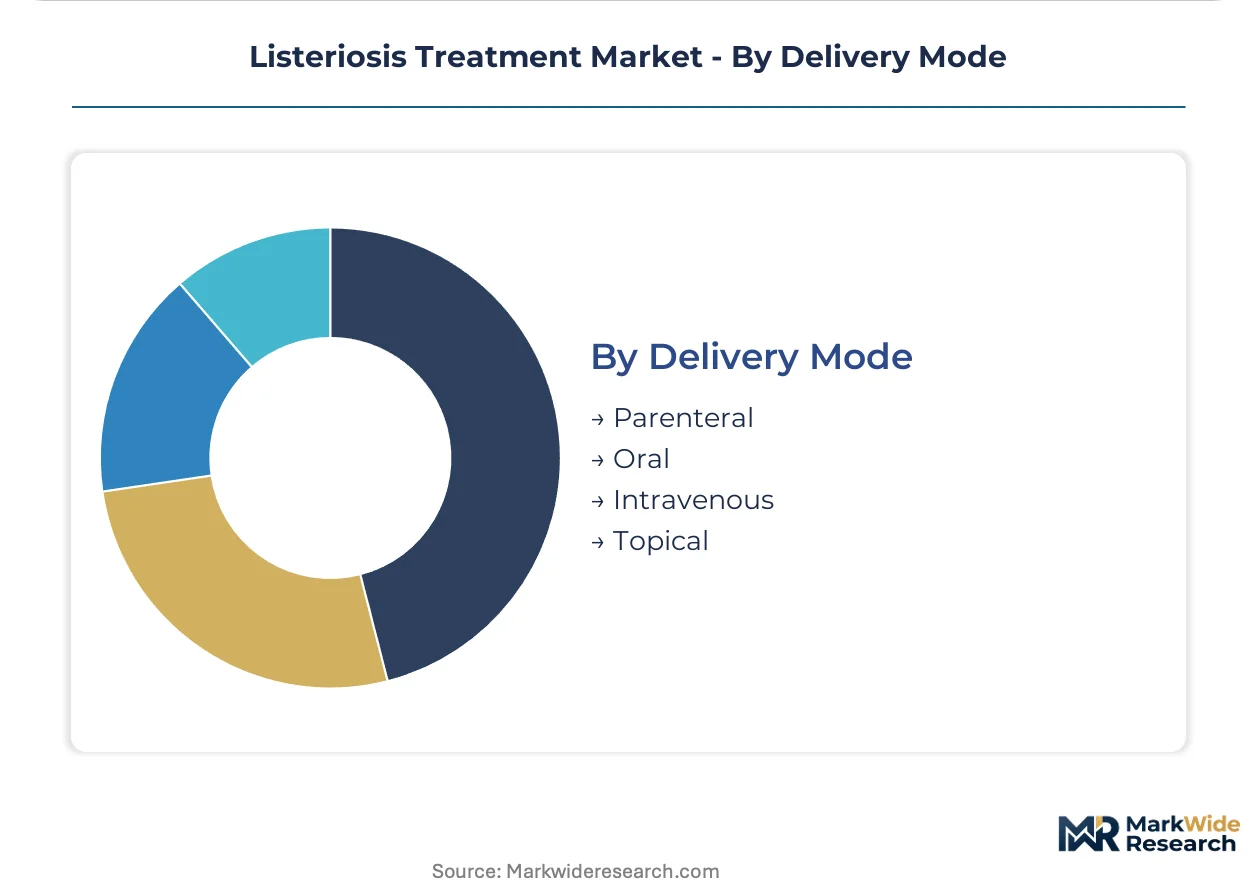
- Intravenous:Direct vascular administration achieves rapid therapeutic levels for CNS penetration and bactericidal synergy in critical illness. United States neonatal intensive care units mandate central line placement for extended ampicillin courses in premature infants.
- Parenteral:Intramuscular depot formulations support transition therapy in patients with unreliable gastrointestinal absorption.
- Oral:Step-down to trimethoprim-sulfamethoxazole enables outpatient completion after clinical stabilization in uncomplicated presentations.
- Topical:Limited relevance for systemic listeriosis; occasional use for cutaneous manifestations in rare disseminated cases.
Intravenous delivery anchors acute care protocols; oral transition enables cost-efficient completion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antimicrobial therapy for listeriosis first achieved systematic protocolization in French perinatal centers during the 1980s, establishing the ampicillin-gentamicin regimen now replicated across tertiary networks worldwide. Current demand concentrates in jurisdictions with aging demographics, sophisticated neonatal intensive care infrastructure, and stringent food safety enforcement.
United States
Neonatal ICU quality collaboratives mandate dual-therapy readiness for early-onset sepsis, institutionalizing procurement volumes that exceed other acute care segments. FDA antimicrobial stewardship guidelines compress empirical prescribing windows while maintaining stockpile requirements for gram-positive coverage. Boston and Philadelphia anchor the largest hospital procurement clusters, where consolidated purchasing organizations negotiate multi-year supply agreements with shortage penalties.
Germany
Tertiary referral networks sustain elevated inventories for transplant oncology and biologic therapy patients presenting with atypical CNS manifestations. REACH authorization requirements tighten environmental discharge standards for antibiotic manufacturing facilities, forcing API suppliers toward closed-system fermentation. The Rhine-Ruhr industrial corridor hosts formulation plants prioritizing supplier qualification audits that weight environmental compliance alongside traditional quality benchmarks.
France
Maternal-fetal transmission protocols mandate prenatal screening and intrapartum prophylaxis for documented Listeria colonization, generating sustained demand for perinatal antimicrobial coverage. ANSM pharmacovigilance frameworks strengthen adverse event reporting for foodborne pathogens, driving documented bactericidal synergy regimens. Lyon and Paris concentrate the nation's specialized pediatric referral networks where adjunctive intravenous immunoglobulin sees limited application for refractory neonatal sepsis.
Switzerland
Swissmedic regulatory standards enforce manufacturing quality benchmarks that influence procurement specifications across adjacent European markets. Academic medical center microbiology laboratories pilot compassionate-use phage therapy protocols for refractory CNS infections in patients with severe beta-lactam hypersensitivity. Basel and Zurich anchor the country's pharmaceutical research corridor, where CRISPR-engineered bacteriophage development converges with intracellular pathogen targeting.
Japan
PMDA guidelines shape antimicrobial prescribing patterns while METI industrial policy supports domestic manufacturing resilience for essential medicines. Japanese tertiary centers maintain dedicated infectious disease pharmacist staffing for complex aminoglycoside dosing optimization in renal impairment. The Kanto region around Tokyo commands the nation's highest concentration of neonatal intensive care units with mandatory central line placement protocols for extended ampicillin courses in premature infants.
Listeriosis Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across manufacturing scale and formulary partnership depth, with the former commanding dedicated hospital supply agreements and the latter competing on tender pricing for generic procurement. The vendor base stratifies into three tiers: multinational innovators with established CNS penetration portfolios, regional generic manufacturers with cost-sensitive institutional focus, and emerging specialists in alternative synergy regimens for penicillin-allergic patients. Dominant competitive moves include capacity expansion for API fermentation and strategic partnerships with national hospital group purchasing organizations.
Within the multinational tier, Pfizer Inc. and Novartis AG occupy positions reflecting divergent strategic emphases on manufacturing scale versus specialized hospital formulary relationships. Sun Pharmaceutical Industries Limited exemplifies the regional generic archetype, anchoring cost-sensitive production for institutional buyers. These three companies collectively represent the competitive spectrum from premium-tier partnership depth to commodity-margin volume supply.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Sanofi S.A. |
| Teva Pharmaceutical Industries Ltd. |
| GlaxoSmithKline plc |
| Merck & Co., Inc. |
| AstraZeneca PLC |
| Cipla Ltd. |
| Sun Pharmaceutical Industries Limited |
| Others |
Supply & Pricing Matrix
Consolidated hospital group purchasing organizations in the United States anchor procurement volume and enforce contract-based long-term offtake pricing with shortage penalty clauses. This buyer concentration compresses manufacturer margins while stabilizing demand visibility across multi-year supply agreements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates originator beta-lactam formulations from certified generic ampicillin and unbranded gentamicin vials. Price differentiation hinges on FDA establishment inspection compliance status and volume scale commitments from integrated delivery networks. Cost compression in the economy tier is intensifying because of Chinese API oversupply and tender pricing wars among regional generic manufacturers. Long-term care facilities exhibit the highest price sensitivity due to fixed per-diem reimbursement, while tertiary neonatal ICUs prioritize supply security over unit cost.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan maintain hub-and-spoke cold-chain networks for parenteral antibiotic distribution with temperature-validated last-mile delivery. Active pharmaceutical ingredient manufacturing clusters in China and India feed formulation plants in North America and Europe, creating single-source vulnerability for penicillin G fermentation-derived intermediates. Supply chain risk centers on tariff exposure for imported API from designated trade-sensitive jurisdictions. Distribution runs through national hospital group purchasing organizations with direct-to-warehouse drop-ship arrangements that bypass traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Listeriosis Treatment Market functions as a stable compounder sustained by mandatory neonatal ICU protocol adherence that institutionalizes recurring procurement cycles regardless of economic cycles.
For Market Incumbents: Cement formulary lock-in through dedicated infectious disease pharmacist training programs and multi-year supply agreements with shortage penalty clauses. Capacity addition in domestic fermentation facilities reduces exposure to Chinese API concentration risk. Invest in closed-system manufacturing to preempt REACH authorization enforcement and EMA pharmacovigilance audit requirements. For New Entrants and Emerging Players: CRISPR-engineered bacteriophage platforms for beta-lactam-hypersensitive patients represent the most penetrable white-space segment with limited incumbent manufacturing investment. Target penicillin-allergic protocol gaps in Swiss and United States academic medical centers where compassionate-use frameworks already exist. Pursue hospital microbiology laboratory partnerships as the primary go-to-market angle to bypass entrenched formulary committees. For Investors and Strategic Acquirers: Hospital systems with captive specialty pharmacy operations are the most active acquirer in this space, seeking vertical integration into parenteral antimicrobial sourcing. The market supports long-term viability through defensive reimbursement structures and irreplaceable clinical protocols. Watch FDA shortage designation frequency as the inflection indicator for supply-constraint-driven pricing power restoration.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Domestic fermentation capacity expansion reduces Chinese API dependency and satisfies FDA inspection readiness requirements. |
| Regulatory Approval Pathway | EMA pharmacovigilance compliance investments preempt REACH authorization enforcement across European formulation plants. |
| Hospital System Partnership | Multi-year supply agreements with United States neonatal ICU quality collaboratives institutionalize recurring procurement volumes. |
| Pipeline Diversification | Alternative synergy regimens for penicillin-allergic patients address underserved protocol segments with limited manufacturing competition. |
| Long-term Supply Agreement | API offtake contracts with Indian and Chinese fermentation specialists secure input cost visibility across the analysis window. |
Research Methodology
Multiple input streams — infectious disease pharmacist interviews, hospital procurement manager surveys, and regulatory affairs lead consultations — were reconciled against FDA drug shortage databases, EMA inspection outcome reports, and hospital formulary databases. Secondary validation drew from ClinicalTrials.gov entries for alternative listeriosis therapeutics and CMS Medicare reimbursement data for neonatal ICU stays. Bottom-up demand modeling across patient population segments was cross-checked against top-down pharmaceutical manufacturer revenue disclosures.
Historical prescribing pattern analysis was cross-referenced with panel input from formulary directors and GPO contracts managers to construct the projection framework. Segmentation dimensions modeled include treatment line, administration route, patient immunocompetence status, and regional regulatory cluster. CAGRs were derived from reconciled volume and value trajectories incorporating neonatal ICU birth rate projections and immunocompromised patient population growth across the analysis window. Forecast inputs included antimicrobial stewardship guideline evolution and strategic reserve mandate expansion in middle-income health systems.
The model holds under stable regulatory enforcement intensity and consistent neonatal protocol adherence; deviation in FDA shortage designation frequency or EMA manufacturing audit stringency would shift manufacturer capacity investment timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Neurosyphilis Market
Specialty Medicine
Disruptive Behavior Disorders Market
Specialty Medicine
Nuclear Medicine Therapeutics Market
Specialty Medicine
North America Precision Medicine Market
Specialty Medicine
Intramedullary Osteosarcoma Treatment Market
Specialty Medicine
Blastomycosis Treatment Market
Specialty Medicine
Veno-Occlusive Hepatic Disease Therapeutics Market
Specialty Medicine
Secondary Progressive Multiple Sclerosis (SPMS) Treatment Market
Specialty Medicine
Global Fungal Keratitis Treatment Market
Specialty Medicine
HTLV-1 Associated Myelopathy (HAM) Market
Specialty Medicine
Sports Medicine Market
Specialty Medicine
Intussusception Market
Specialty Medicine
Pyoderma Gangrenosum Therapeutics Market
Specialty Medicine
Global Laryngeal Cancer Therapeutics Market
Specialty Medicine
Herpes Zoster (Shingles) Market
Specialty Medicine
Tularemia Therapeutics Market