
 Severe Hypertriglyceridemia (SHTG) Treatment Market | 2026-2036
Severe Hypertriglyceridemia (SHTG) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Severe Hypertriglyceridemia (SHTG) Treatment Market Analytics
Specialty lipid clinics within integrated delivery networks are bifurcating from general cardiology practices as the primary demand anchor for SHTG therapies. Amarin Corporation leverages its marine-derived omega-3 platform to dominate the prescription EPA segment. Ionis Pharmaceuticals anchors its position through antisense oligonucleotide innovation targeting apolipoprotein C-III. Arrowhead Pharmaceuticals competes with RNA interference candidates designed for triglyceride modulation.
Severe Hypertriglyceridemia treatment encompasses pharmacological intervention for fasting triglyceride levels exceeding 500 mg/dL, utilizing agents that modulate lipoprotein lipase activity, VLDL synthesis, or chylomicron clearance to prevent acute pancreatitis and atherosclerotic cardiovascular disease. Omega-3 fatty acids occupy the mature volume tier with established generic competition, while injectable antisense and siRNA platforms represent the fastest-expanding margin pool due to pricing power and orphan-disease positioning. Oral fibrate formulations sustain steady hospital formulary presence despite safety monitoring requirements.
The FDA maintains stringent cardiovascular outcomes study expectations for novel triglyceride-lowering agents, directly shaping Phase III trial investment and commercial launch timelines. EMA parallel assessment through centralized procedures influences simultaneous European access strategies for developers. Payers and providers must monitor how outcomes-based contracting for injectable biologics reshapes site-of-care economics and patient adherence programs.
Market Dynamics
Injectable RNA-targeted therapies are compressing the traditional oral fibrate dominance in severe hypertriglyceridemia management, forcing hospital formularies to restructure their lipid clinic procurement hierarchies around biologic infusion protocols and specialty pharmacy distribution.
Growth Catalysts
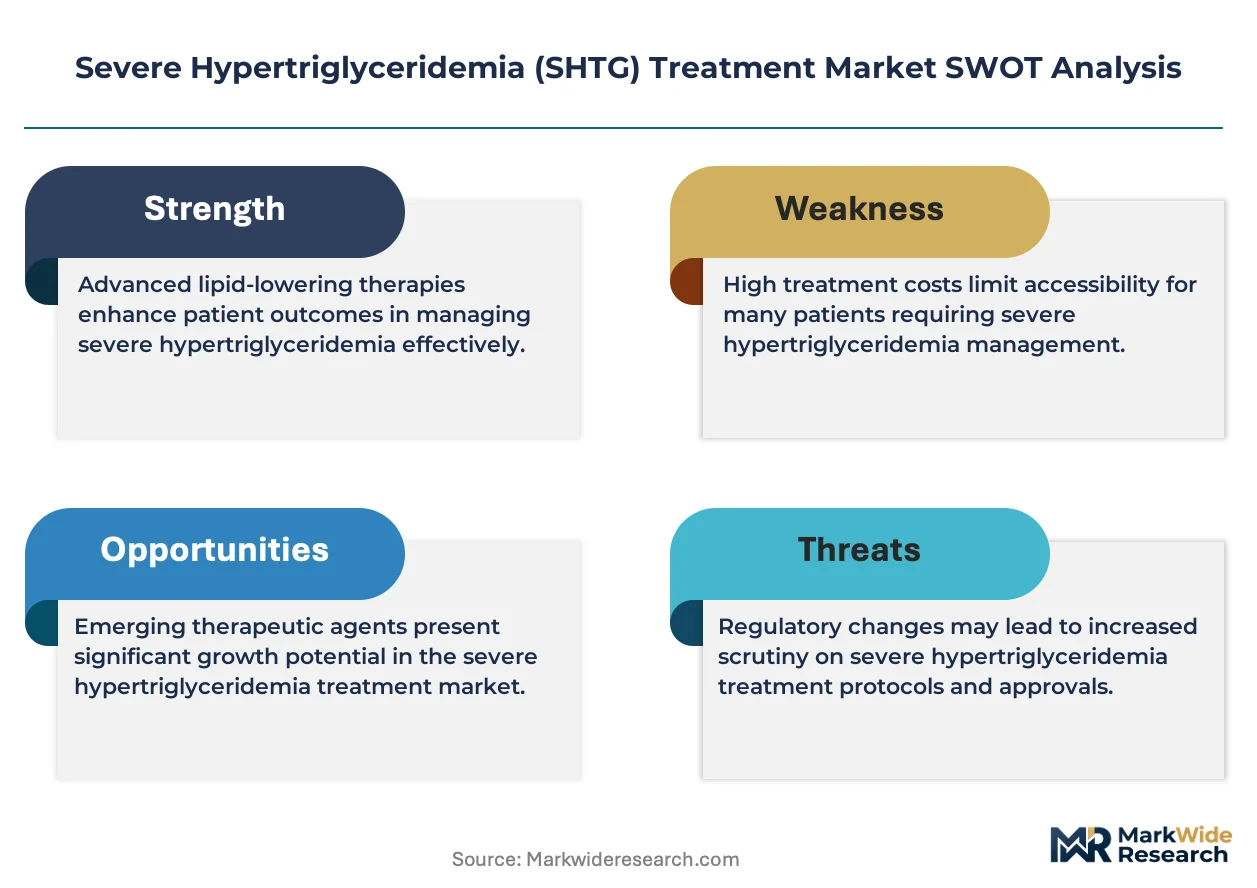
- CV Outcomes Mandates:FDA cardiovascular outcomes study requirements for novel triglyceride-lowering agents are accelerating investment in large-scale Phase III infrastructure and reshaping clinical trial site selection toward integrated delivery networks with established pancreatitis registries.
- Specialty Pharmacy Networks:United States-based specialty pharmacy distribution for injectable biologics is expanding patient access to RNA interference therapies through hub-and-spoke models that centralize prior authorization management and adherence monitoring.
- Apolipoprotein C-III Targeting:Antisense oligonucleotide innovation against APOC3 is creating new therapeutic categories beyond omega-3 fatty acids, opening orphan-disease positioning pathways and premium pricing corridors for ultra-rare hypertriglyceridemia subtypes.
Market Restraints
- Marine Source Volatility:Prescription EPA supply chains face input concentration risk from Peruvian and Chilean anchovy fisheries, where El Niño patterns disrupt omega-3 fatty acid raw material availability and pricing predictability.
- Biologic Manufacturing Concentration:Injectable antisense and siRNA production concentrates among a limited cohort of contract manufacturing organizations with oligonucleotide synthesis expertise, creating single-source vulnerability for commercial-scale nucleotide supply.
- Fibrate Safety Monitoring:Oral fibrate formulations require ongoing hepatic enzyme surveillance and myopathy risk management, imposing persistent clinical burden that constrains prescriber enthusiasm despite generic cost accessibility.
Strategic Opportunities
- Pediatric Severe Hypertriglyceridemia:Underpenetrated demand among adolescent and pediatric populations with familial chylomicronemia syndrome offers expansion corridors for subcutaneous RNA-targeted formulations with weight-based dosing protocols.
- Integrated Delivery Network Partnerships:Direct contracting between manufacturers and United States-based IDNs for outcomes-based reimbursement is creating preferred formulary placement pathways that bypass traditional payer prior authorization barriers.
- Combination Therapy Positioning:Convergence of statin backbone therapy with adjunctive triglyceride-specific agents is enabling fixed-dose development programs that address residual cardiovascular risk in mixed dyslipidemia populations.
Industry Challenges
- Oligonucleotide Toxicology Expertise:Scarce preclinical development talent capable of designing APOC3-targeted liver safety studies is extending IND timelines and inflating CRO contract values for RNA therapeutic developers.
- Legacy EHR Integration:Hospital lipid clinics struggle to incorporate novel triglyceride biomarker tracking into existing cardiovascular risk calculators, forcing manual data entry workflows that degrade registry quality and outcomes study enrollment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Severe Hypertriglyceridemia (SHTG) Treatment Market |
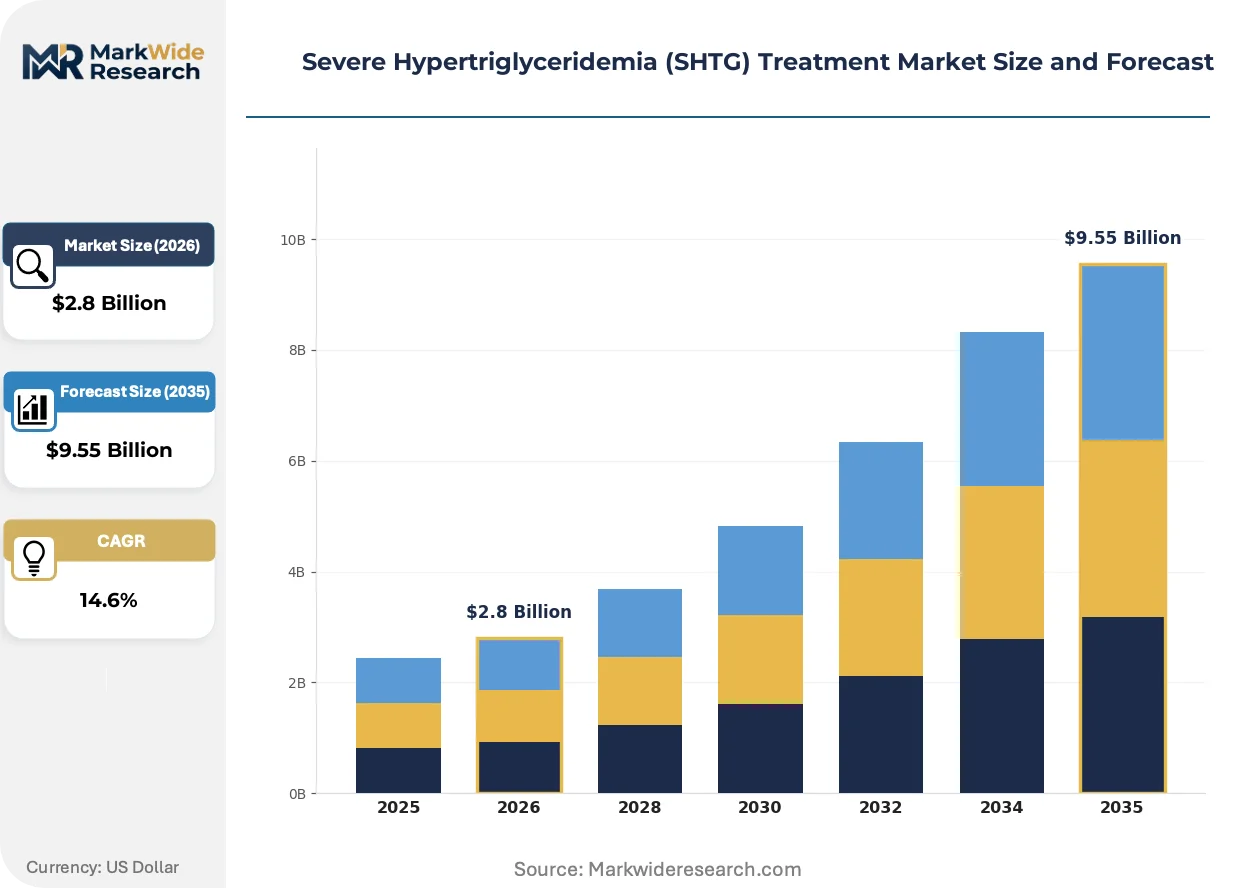
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fibrates, Omega-3 Fatty Acids, Niacin, Statins Administration Route: Oral, Injectable, Intravenous, Sublingual End User: Hospitals, Clinics, Homecare, Pharmacies Distribution Channel: Direct Sales, Online Pharmacies, Retail Pharmacies, Wholesalers |
| Companies Covered | Amarin Corporation, Ionis Pharmaceuticals, Arrowhead Pharmaceuticals, Novartis, Pfizer, AstraZeneca, Regeneron Pharmaceuticals, Novo Nordisk, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Severe Hypertriglyceridemia (SHTG) Treatment Market Evolving Landscape
RNA-targeted therapeutic platforms are bifurcating the severe hypertriglyceridemia treatment algorithm from decades of oral small-molecule dominance, embedding genetic modulation into standard-of-care conversations previously limited to metabolic management.
GalNAc-conjugated siRNA delivery technology is fragmenting the injectable biologic competitive set by enabling quarterly dosing intervals that reduce infusion center burden. Hospital systems with limited lipid clinic capacity are prioritizing these extended-interval formulations over monthly antisense alternatives. The technology is fragmenting prescriber loyalty patterns that historically favored established omega-3 platforms with familiar safety profiles.
EMA centralized assessment procedures for orphan-designated triglyceride-lowering agents are compressing European launch timelines relative to historical national pricing negotiation sequences. Manufacturers are synchronizing FDA and EMA submission packages to capture simultaneous transatlantic approval windows. The policy shift most acutely affects developers of apolipoprotein C-III inhibitors seeking premium reimbursement in German and French hospital formularies.
Site-of-care economics are driving hospital-owned specialty pharmacies to displace traditional retail distribution for high-cost injectable biologics. United States-based integrated delivery networks are capturing 340B pricing advantages and infusion revenue through captive specialty pharmacy entities. This channel migration concentrates patient volume within health system walls and degrades independent community pharmacy participation in SHTG therapy fulfillment.
Severe Hypertriglyceridemia (SHTG) Treatment Market Segmentation
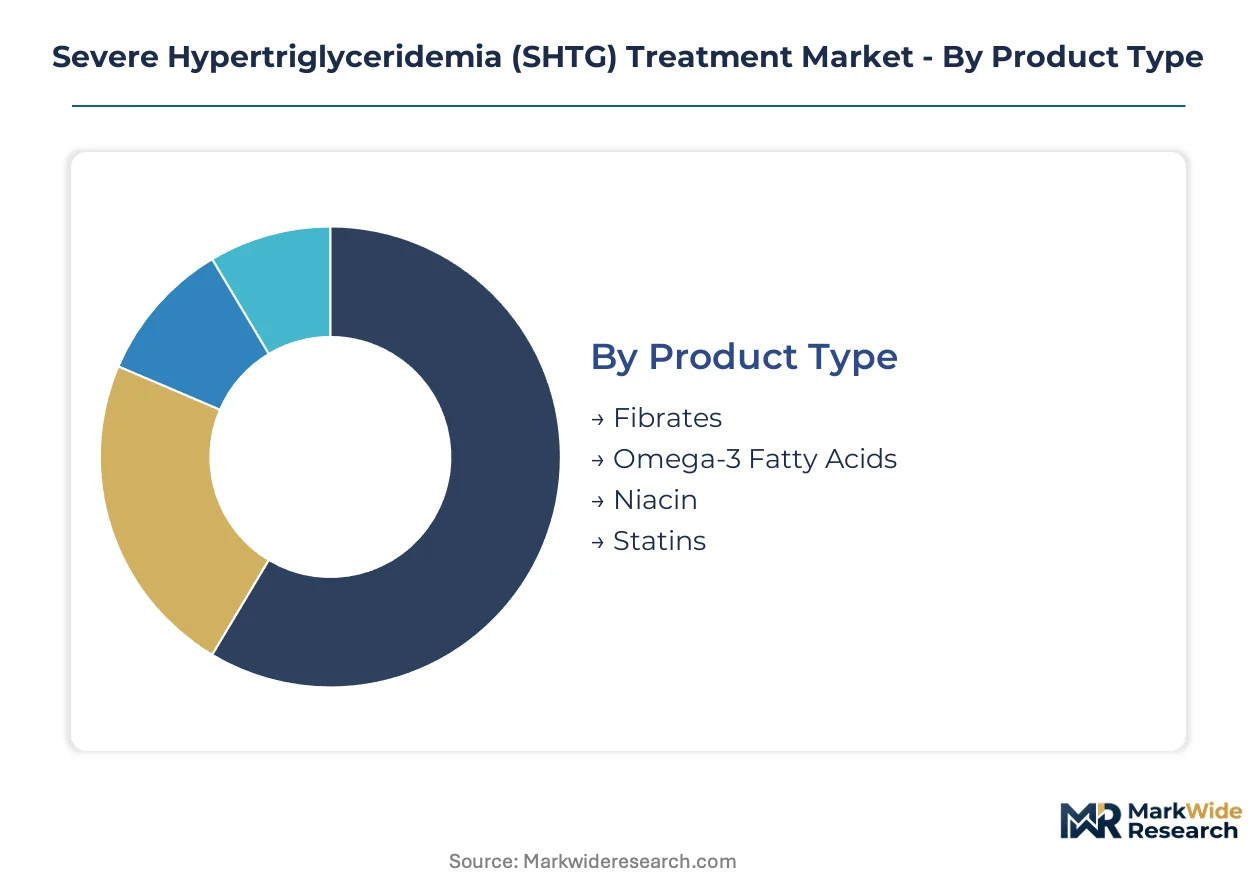
Severe Hypertriglyceridemia treatment markets fragment across pharmacological mechanisms, delivery technologies, and care settings. Each segmentation axis reveals distinct margin architectures and competitive entry points for manufacturers.
Product Type:
Margin pools concentrate in injectable biologics and prescription-grade omega-3 formulations, while oral generics compete on volume accessibility.
- Fibrates:Oral peroxisome proliferator-activated receptor agonists reduce hepatic VLDL production through established generic formulations. Hospital formularies in the United States sustain volume demand despite hepatotoxicity monitoring burdens and myopathy risk protocols that constrain prescriber enthusiasm.
- Omega-3 Fatty Acids:Marine-derived eicosapentaenoic acid formulations occupy the prescription EPA segment with purified ethyl ester compositions. Amarin Corporation's platform anchors this category through cardiovascular outcomes labeling, though Peruvian anchovy fishery volatility introduces raw material pricing unpredictability.
- Niacin:Nicotinic acid derivatives modulate lipolysis in adipose tissue with extended-release formulations. Flushing side effects and limited outcome data have compressed commercial relevance.
- Statins:HMG-CoA reductase inhibitors provide foundational LDL lowering with modest triglyceride effects. Prescribers deploy these as backbone therapy rather than SHTG-specific intervention.
Fibrates hold installed capacity across hospital procurement systems. Omega-3 Fatty Acids are rotating up the share rankings through cardiovascular outcomes differentiation.
Administration Route:
Delivery modality determines site-of-care economics and patient adherence architecture, with quarterly dosing intervals commanding premium positioning.
- Oral:Tablet and capsule formulations dominate outpatient prescribing through pharmacy dispensing convenience. Fibrate and omega-3 platforms sustain this channel despite inferior triglyceride lowering relative to injectable alternatives.
- Injectable:Subcutaneous antisense oligonucleotide and siRNA platforms target apolipoprotein C-III with GalNAc-conjugated liver delivery. Ionis Pharmaceuticals and Arrowhead Pharmaceuticals compete through quarterly versus monthly dosing schedules that reshape infusion center capacity planning.
- Intravenous:Hospital-administered formulations address acute hypertriglyceridemic pancreatitis episodes requiring immediate lipid lowering. Emergency department protocols drive episodic demand rather than chronic maintenance.
- Sublingual:Rapid-absorption formulations address swallowing difficulties in elderly populations. Limited clinical evidence constrains formulary adoption.
Oral administration holds installed capacity across retail pharmacy networks. Injectable routes are rotating up the share rankings through specialty pharmacy hub-and-spoke distribution expansion.
End User:
Care setting segmentation tracks risk stratification intensity and reimbursement complexity, with integrated delivery networks capturing high-value patient cohorts.
- Hospitals:Acute care facilities manage pancreatitis complications and initiate intensive triglyceride lowering through inpatient protocols. United States-based IDNs are consolidating lipid clinic services within system-owned specialty pharmacies to capture 340B pricing advantages.
- Clinics:Outpatient lipid specialty practices perform cardiovascular risk stratification and biologic infusion administration. These sites are bifurcating from general cardiology as dedicated SHTG management centers.
- Homecare:Self-administered subcutaneous injection programs reduce infusion center burden for stable patients. Nurse training and cold-chain logistics determine program viability.
- Pharmacies:Community and specialty pharmacy dispensing handles oral maintenance therapies with prior authorization support.
Hospitals hold installed capacity through emergency pancreatitis admissions. Clinics are rotating up the share rankings as dedicated lipid specialty practices proliferate.
Distribution Channel:
Channel structure determines manufacturer margin capture and patient access friction, with captive health system pharmacies displacing independent retail.
- Direct Sales:Manufacturer-to-institution contracting bypasses wholesale markups for high-cost biologics. Outcomes-based agreements with United States IDNs are creating preferred formulary placement pathways.
- Online Pharmacies:Digital dispensing platforms expand geographic access to maintenance therapies. Cold-chain shipping capabilities determine biologic eligibility.
- Retail Pharmacies:Community pharmacy networks handle oral generic volume with limited clinical support services. Margins compress as formulary control shifts to health systems.
- Wholesalers:Three-tier distribution maintains inventory buffers for oral small molecules. Oligonucleotide biologics bypass this channel due to temperature sensitivity and limited shelf stability.
Wholesalers hold installed capacity for oral generic distribution. Direct Sales are rotating up the share rankings through IDN captive pharmacy expansion and biologic cold-chain requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based specialty pharmacy networks export distribution expertise to Canadian hospital systems seeking lipid clinic infrastructure. German and French hospital formularies import antisense manufacturing know-how through EMA centralized assessment pathways. Japanese metabolic disease centers anchor Asia-Pacific demand for marine-derived omega-3 formulations.
United States
Integrated delivery networks in Texas and Florida consolidate pancreatitis registries to accelerate CV outcomes trial enrollment. FDA cardiovascular outcomes study mandates reshape Phase III investment toward IDNs with established lipid specialty infrastructure. Boston and San Francisco biotech clusters concentrate antisense oligonucleotide development talent.
Germany
University hospital lipid clinics in Munich and Heidelberg pioneer apolipoprotein C-III inhibitor protocols for familial chylomicronemia syndrome. EMA centralized procedures compress German national pricing negotiation timelines for orphan-designated therapies. The Rhine-Ruhr industrial corridor concentrates contract manufacturing organizations with oligonucleotide synthesis expertise.
Japan
Metabolic disease specialists in Tokyo and Osaka drive prescription EPA demand through cardiovascular risk stratification protocols. PMDA alignment with FDA cardiovascular outcomes expectations accelerates simultaneous submission strategies for RNA-targeted therapies. The Kansai region anchors marine omega-3 raw material processing partnerships with Peruvian suppliers.
United Kingdom
NHS lipid specialty services in London and Manchester expand access to injectable biologics through hub-and-spoke distribution models. NICE technology appraisals impose cost-effectiveness thresholds that favor quarterly-dosing siRNA formulations over monthly alternatives. The Cambridge life sciences cluster concentrates rare disease trial infrastructure.
France
Hospital lipid clinics in Paris and Lyon prioritize GalNAc-conjugated delivery platforms to reduce infusion center capacity constraints. ANSM pharmacovigilance requirements shape liver safety study designs for APOC3-targeted candidates. The Île-de-France region concentrates outcomes-based contracting expertise for high-cost biologic reimbursement.
Severe Hypertriglyceridemia (SHTG) Treatment Market Competitive Landscape
Listed leaders compete with private specialists across RNA therapeutic development platforms, creating a bifurcated structure where public companies anchor cardiovascular outcomes infrastructure and private entities concentrate on delivery technology innovation. The competitive set organizes around three archetypes: marine-derived omega-3 incumbents with established generic competition, antisense oligonucleotide developers targeting apolipoprotein C-III, and siRNA platform specialists exploiting extended-interval dosing advantages. Dominant competitive moves include direct IDN contracting to bypass payer prior authorization barriers and GalNAc conjugation technology licensing to compress dosing frequency.
Among RNA-targeted therapy developers, Ionis Pharmaceuticals and Arrowhead Pharmaceuticals exemplify the platform-specialist archetype, while Amarin Corporation anchors the mature prescription EPA segment. Ionis represents antisense oligonucleotide innovation with monthly administration protocols, whereas Arrowhead occupies the extended-interval positioning enabled by GalNAc-conjugated siRNA delivery. Amarin exemplifies cardiovascular outcomes differentiation within the omega-3 fatty acid category despite raw material sourcing concentration in South American fisheries.
| Leading Market Players |
|---|
| Amarin Corporation |
| Ionis Pharmaceuticals |
| Arrowhead Pharmaceuticals |
| Novartis |
| Pfizer |
| AstraZeneca |
| Regeneron Pharmaceuticals |
| Novo Nordisk |
| Sanofi |
| Others |
Value Network & Pricing Analysis
FDA cardiovascular outcomes study requirements gate both clinical trial site qualification and premium pricing corridors for novel triglyceride-lowering agents, compressing margin differentiation between validated biologic platforms and commodity oral formulations. This regulatory threshold simultaneously constrains supply base entry and enables value-based price positioning for RNA-targeted therapies.
Pricing Analysis
Three-generation pricing stratification separates quarterly-dosing GalNAc-conjugated siRNA platforms from monthly antisense alternatives and mature oral omega-3 formulations. Premium tiers command value-based positioning through orphan-disease labeling and CV outcomes differentiation, while generic fibrate price erosion intensifies from formulary consolidation by United States integrated delivery networks. Hospital procurement committees exhibit highest price sensitivity for oral maintenance therapies, whereas specialty pharmacy networks absorb biologic premium for reduced infusion center burden.
Supply Chain Analysis
Just-in-time inventory strategies dominate oligonucleotide manufacturing given temperature sensitivity and limited shelf stability, forcing manufacturers to maintain strategic raw material buffers for nucleotide precursors. Commercial-scale production concentrates in Germany, Switzerland, and the United States among contract manufacturing organizations with specialized synthesis expertise. Peruvian and Chilean anchovy fisheries anchor marine omega-3 raw material sourcing, exposing prescription EPA supply to El Niño-driven commodity volatility. Distribution runs through captive hospital specialty pharmacies for injectable biologics, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oligonucleotide toxicology expertise scarcity extends IND timelines and inflates CRO contract values, creating defensive moats for developers with established liver safety study capabilities. This capability gap shapes competitive durability across the RNA therapeutic landscape.
For Market Incumbents: Secure captive manufacturing capacity through backward integration into nucleotide precursor supply or exclusive CMO partnerships, insulating against single-source vulnerability as antisense and siRNA demand accelerates. Defend formulary positioning by embedding outcomes-based contracting with United States integrated delivery networks, neutralizing payer prior authorization friction for emerging competitors. For New Entrants and Emerging Players: Differentiate on pediatric severe hypertriglyceridemia protocols with weight-based dosing formulations, exploiting underpenetrated demand in adolescent familial chylomicronemia syndrome. Target direct-to-IDN contracting pathways that bypass traditional wholesale markups, leveraging hub-and-spoke specialty pharmacy infrastructure for patient access. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across GalNAc-conjugated siRNA manufacturing, favoring platform specialists with validated liver delivery technology over single-asset developers. Long-term viability concentrates in entities with diversified APOC3-targeted pipelines and established EMA centralized assessment track records. Watch FDA label expansion decisions for triglyceride-lowering agents as inflection signals for premium pricing durability.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | CV outcomes study infrastructure anchors Phase III investment toward IDNs with pancreatitis registries. |
| Regulatory Approval Pathway | EMA centralized procedures compress European launch timelines for orphan-designated APOC3 inhibitors. |
| Manufacturing Scale-Up | Oligonucleotide synthesis capacity expansion reduces single-source dependency for commercial nucleotide supply. |
| Pipeline Diversification | Combination therapy programs with statin backbone address residual cardiovascular risk in mixed dyslipidemia. |
| Strategic Partnership | Direct IDN contracting creates preferred formulary placement bypassing traditional payer authorization barriers. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchors the qualitative findings against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient volume modeling and top-down pharmaceutical spending analysis triangulate market size estimates across pharmacological mechanism and administration route segments.
Sensitivity analysis frameworks test forecast robustness across regulatory approval scenarios, pricing negotiation outcomes, and supply disruption events over the projection horizon. Segmentation dimensions include product type, administration route, end user, and distribution channel, with CAGRs derived from epidemiological trend extrapolation and therapy adoption curve modeling. Forecast inputs incorporate pancreatitis incidence trajectories, CV outcomes study completion rates, and specialty pharmacy network expansion patterns.
The analysis sits within stated boundaries; outcomes outside sustained FDA outcomes study requirements or stable marine fishery supply conditions would require recalibration. Forecasts reflect documented assumptions regarding regulatory pathway continuity and reimbursement policy stability. Revision becomes warranted when El Niño intensity crosses thresholds that materially disrupt Peruvian anchovy harvest volumes or when EMA centralized assessment timelines diverge from historical patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Ulcerated Necrobiosis Lipoidica Management Market
Specialty Medicine
Personalized Medicine Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
Cirrhosis Management Market
Specialty Medicine
Pyoderma Gangrenosum Therapeutics Market
Specialty Medicine
Global Eye Allergy Therapeutics Market
Specialty Medicine
Global Major Depressive Disorder (MDD) Market
Specialty Medicine
Lateral Epicondylitis (Tennis Elbow) Treatment Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market
Specialty Medicine
Epilepsy Treatment Market
Specialty Medicine
Tropical Spastic Paraparesis Market
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
ADHD Therapeutics Market
Specialty Medicine
Lamellar Ichthyosis Treatment Market
Specialty Medicine
Nonerosive Reflux Disease Treatment Market
Specialty Medicine
Biliary Atresia Treatment Market