
 Rumination Syndrome Market | 2026-2036
Rumination Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Rumination Syndrome Market Outlook
Pediatric gastroenterology is reorganizing demand patterns as younger patient cohorts receive earlier diagnoses and referral pathways tighten. Eisai Co., Ltd. leverages its neurology portfolio to explore off-label applications in motility disorders. Pfizer Inc. competes through its established gastroenterology franchise and clinical trial infrastructure. AbbVie anchors its position via immunology and gut-brain axis research platforms that intersect with functional GI conditions.
Rumination syndrome constitutes a functional gastrointestinal disorder characterized by effortless, repetitive regurgitation of recently ingested food into the oral cavity without retching, nausea, or associated structural abnormalities, typically managed through diaphragmatic breathing retraining and behavioral modification protocols. Its primary purpose centers on restoring normal esophagogastric function and preventing secondary malnutrition, dental erosion, and psychosocial impairment. Pharmacological treatments currently lead revenue contribution due to prescriber familiarity and formulary access, while behavioral therapies represent the fastest-growing segment as evidence-based protocols gain payer recognition. Telehealth delivery models are capturing margin pools by reducing specialist visit burdens and enabling rural patient access.
The FDA shapes device clearance requirements for diaphragmatic pacing systems and neuromodulatory implants targeting refractory rumination, while HIPAA governs telehealth platform architectures that handle sensitive behavioral health data. The EMA's Medical Device Regulation imposes additional clinical evidence standards on European market entrants. Stakeholders must monitor evolving digital therapeutics frameworks and determine whether to build proprietary platforms or partner with existing telehealth infrastructure.
Market Dynamics
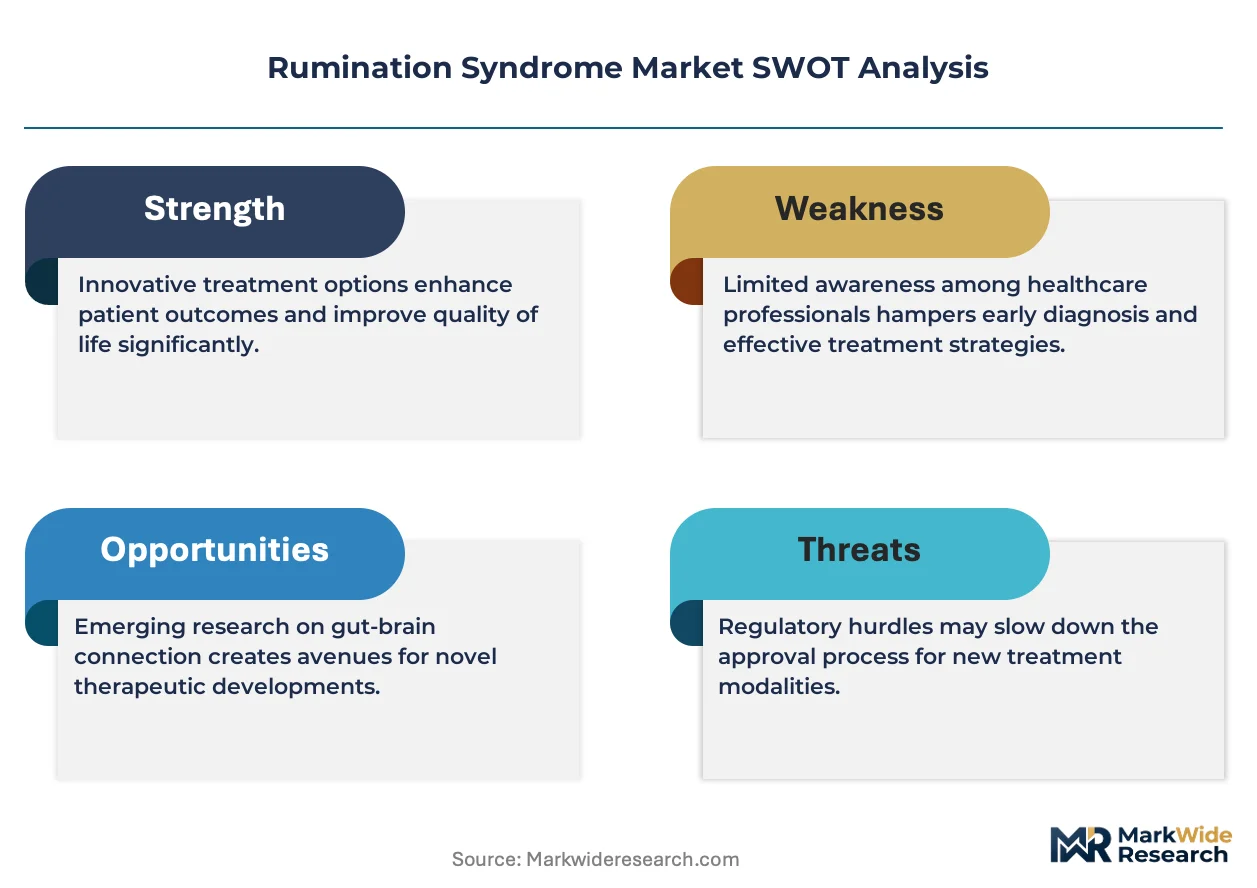
Pediatric gastroenterology clinics are tightening referral pathways for refractory rumination cases, while the FDA's evolving guidance on neuromodulator devices is compressing reimbursement timelines for device-assisted therapies. This regulatory momentum is redistributing investment between pharmacological and behavioral intervention platforms.
Growth Catalysts
- Telehealth infrastructure expansion:HIPAA-compliant platform architectures are enabling rural patient access to diaphragmatic breathing protocols previously confined to academic medical centers.
- Pediatric diagnostic protocols:Earlier identification in school-aged cohorts is expanding addressable patient populations within pediatric gastroenterology networks.
- Neuromodulation reimbursement pathways:The FDA's device clearance framework for diaphragmatic pacing systems is unlocking payer coverage for refractory case management.
Market Restraints
- Specialist concentration:Qualified behavioral therapists cluster in metropolitan academic corridors, leaving tertiary and rural markets underserved.
- Device capital intensity:Implantable neuromodulator systems require substantial upfront investment and specialized surgical infrastructure.
- Formulary inertia:Off-label prescribing of motility agents faces prior authorization friction from commercial payers.
Strategic Opportunities
- Digital therapeutic platforms:FDA breakthrough device designation pathways offer accelerated market access for algorithm-guided breathing retraining applications.
- Integrated care models:Co-location of gastroenterology and behavioral health services within single specialty clinics reduces patient drop-off.
- European market entry:The EMA's Medical Device Regulation creates first-mover advantage for firms with robust clinical evidence packages.
Industry Challenges
- Behavioral protocol standardization:Variability in diaphragmatic breathing certification curricula complicates workforce scaling.
- Cross-specialty coordination:Gastroenterology, psychiatry, and speech-language pathology operate under disconnected electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rumination Syndrome Market |
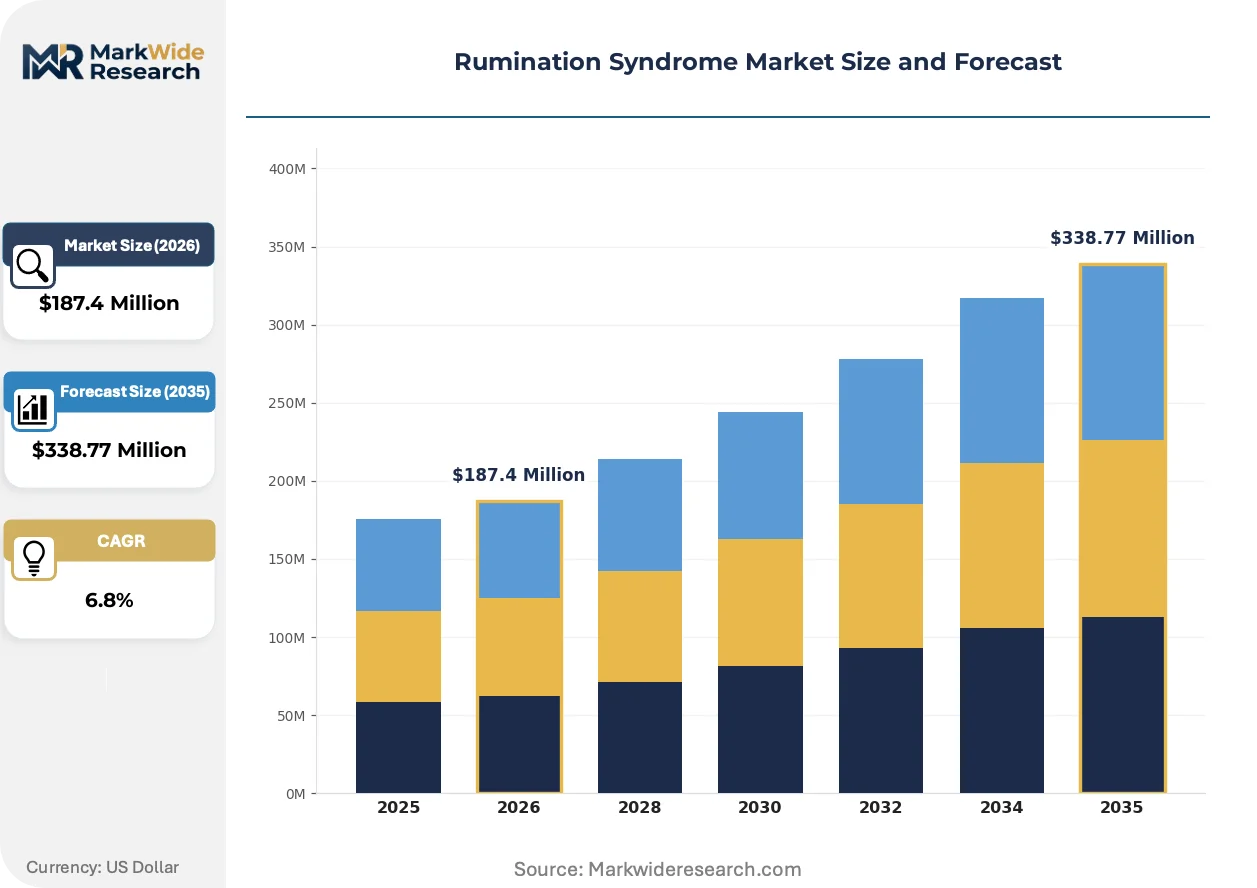
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutic Interventions, Behavioral Therapies, Nutritional Support, Pharmacological Treatments End User: Pediatric Patients, Adult Patients, Healthcare Providers, Caregivers Delivery Model: In-Clinic, At-Home Care, Telehealth, Group Therapy Application: Clinical Research, Patient Management, Treatment Monitoring, Support Groups |
| Companies Covered | Eisai Co., Ltd., AbbVie, Pfizer Inc., Johnson & Johnson, Novo Nordisk A/S, Medtronic, Takeda Pharmaceutical Company Limited, Bayer AG, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rumination Syndrome Market Strategic Shifts
Neuromodulation hardware and digital therapeutic delivery are converging to reshape treatment hierarchies for refractory functional gastrointestinal disorders. Device-assisted protocols are gaining traction as first-line behavioral interventions face capacity constraints.
Diaphragmatic pacing systems deliver rhythmic electrical stimulation to the phrenic nerve, automating the respiratory retraining central to rumination syndrome management. Academic medical centers in the United States are piloting these implants for patients failing conventional behavioral protocols. This automation is supplanting labor-intensive therapist-guided breathing sessions, compressing per-patient specialist hour requirements.
The FDA's evolving guidance on implanted neuromodulators for functional GI conditions is tightening clinical evidence requirements while streamlining breakthrough designation pathways. Device manufacturers must now demonstrate sustained symptomatic improvement beyond six months to secure premarket approval. Pediatric gastroenterology programs are responding by establishing dedicated rumination disorder registries to generate real-world evidence.
Care delivery is fragmenting across synchronous telehealth, asynchronous app-based protocols, and hybrid in-person models. Payers are unbundling behavioral health reimbursement from traditional office visit codes, enabling standalone coverage for remote diaphragmatic training. This shift is most visible in United States commercial insurance markets, where prior authorization requirements for telehealth behavioral services have relaxed substantially.
Rumination Syndrome Market Segmentation
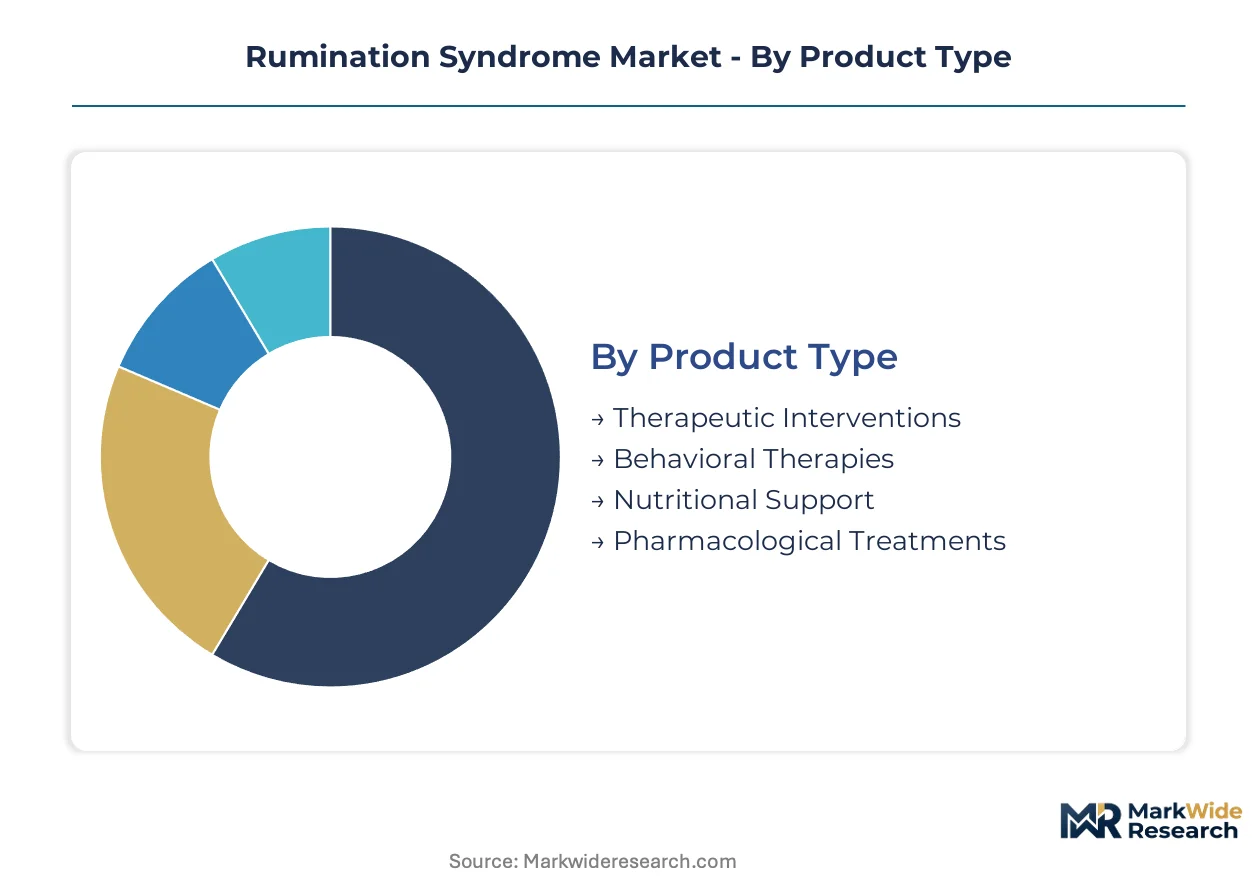
Rumination syndrome treatment pathways fragment across intervention modalities, patient demographics, and care delivery infrastructure. Understanding how margin pools distribute across these dimensions reveals where capital deployment concentrates and where reimbursement arbitrage opportunities emerge.
Product Type:
Behavioral therapies capture the highest per-patient lifetime value through recurring session billing, while pharmacological treatments dominate transaction volume via prescriber familiarity and formulary access.
- Therapeutic Interventions:Diaphragmatic pacing systems and implantable neuromodulators automate respiratory retraining for refractory cases. Academic medical centers in the United States pilot these devices for patients failing conventional protocols, though capital intensity limits penetration to tertiary referral networks.
- Behavioral Therapies:Therapist-guided diaphragmatic breathing retraining constitutes first-line management, delivered via individual or group formats. Pediatric gastroenterology clinics are tightening referral pathways for these services as school-aged diagnostic protocols expand addressable populations.
- Nutritional Support:Registered dietitian interventions address secondary malnutrition and dental erosion prevention. Demand concentrates in multidisciplinary rumination disorder programs co-locating gastroenterology and behavioral health services.
- Pharmacological Treatments:Off-label motility agents and neuromodulators face prior authorization friction from commercial payers. Prescriber familiarity sustains volume despite formulary inertia and limited FDA-approved indications.
Pharmacological treatments hold installed capacity. Behavioral therapies are rotating up the share rankings.
End User:
Pediatric patients generate the steepest expansion trajectory as earlier identification protocols activate school-based screening and referral networks.
- Pediatric Patients:School-aged cohorts drive volume growth through expanded diagnostic awareness. Pediatric gastroenterology clinics reorganize intake protocols to capture refractory cases previously managed in general pediatric settings.
- Adult Patients:Refractory cases in adult populations sustain demand for device-assisted interventions. Academic medical centers build dedicated rumination disorder programs targeting this segment with integrated care models.
- Healthcare Providers:Gastroenterologists, psychiatrists, and speech-language pathologists require cross-specialty coordination tools. Disconnected electronic health record systems complicate workforce scaling across care teams.
- Caregivers:Family members deliver at-home reinforcement of breathing protocols. Telehealth infrastructure enables rural caregiver training previously confined to metropolitan academic corridors.
Pediatric patients concentrate volume growth. Adult patients anchor reimbursement premiums for refractory interventions.
Delivery Model:
Telehealth platforms are displacing in-clinic volume as HIPAA-compliant architectures enable asynchronous protocol delivery and rural market access.
- In-Clinic:Traditional office-based delivery remains concentrated in metropolitan academic medical centers. Specialist scarcity in tertiary and rural markets constrains geographic reach.
- At-Home Care:Caregiver-mediated breathing retraining extends protocol adherence between clinical encounters. Digital therapeutic platforms algorithmically guide home-based practice sessions.
- Telehealth:Synchronous video and asynchronous app-based delivery capture margin pools by reducing specialist visit burdens. United States commercial insurers have relaxed prior authorization requirements for remote behavioral services.
- Group Therapy:Cost-efficient format for behavioral protocol delivery in pediatric and adult cohorts. Payer recognition of evidence-based group formats varies across regional markets.
Telehealth is gaining share fastest. In-clinic retains premium pricing for complex case management.
Application:
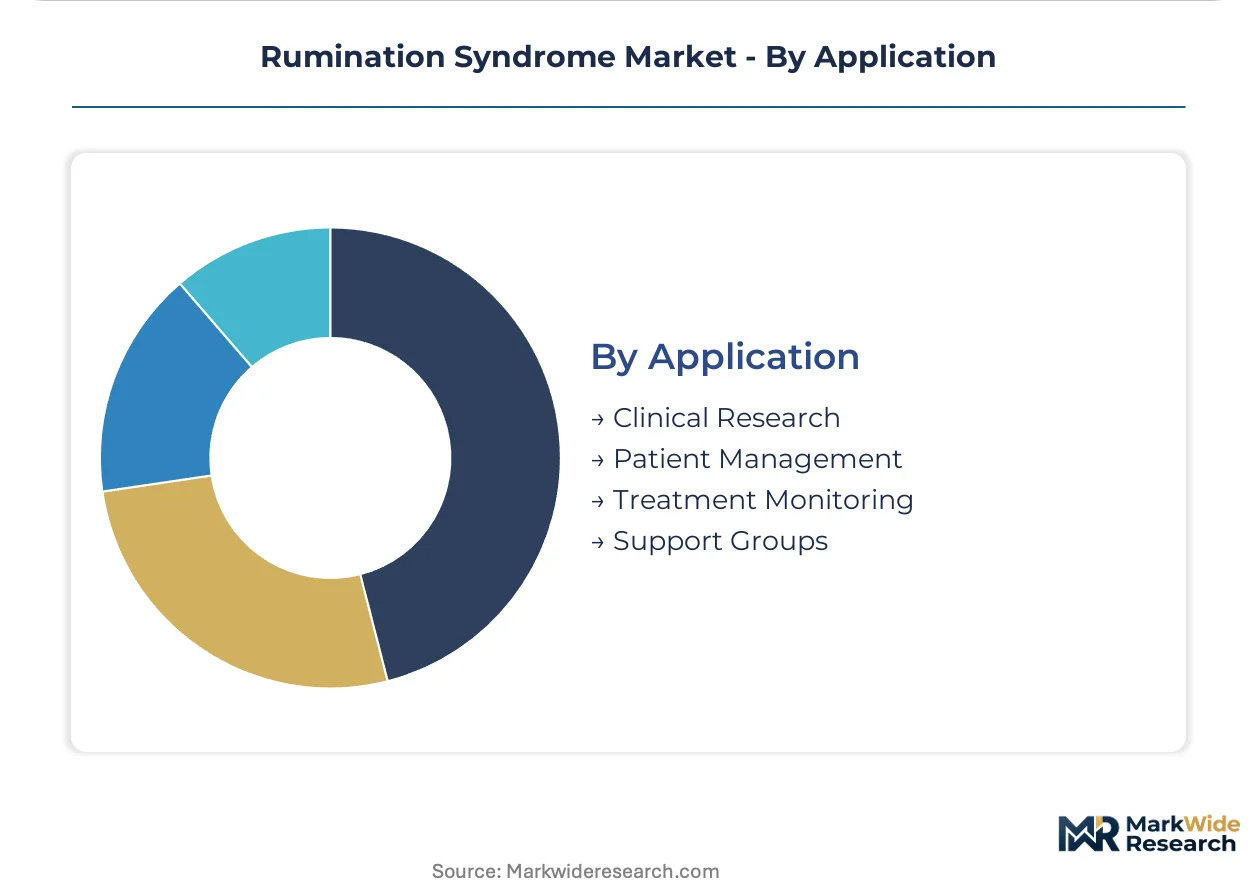
Patient management commands recurring revenue streams while clinical research generates evidence assets for regulatory submissions and payer negotiations.
- Clinical Research:Dedicated rumination disorder registries generate real-world evidence for FDA device clearance and EMA Medical Device Regulation compliance. Academic medical centers sponsor investigator-initiated trials for neuromodulation systems.
- Patient Management:Longitudinal care coordination across gastroenterology, psychiatry, and behavioral health disciplines. Integrated specialty clinics reduce patient drop-off through co-located service delivery.
- Treatment Monitoring:Digital biomarkers and patient-reported outcome measures track protocol adherence and symptomatic response. Remote monitoring infrastructure enables asynchronous clinician oversight.
- Support Groups:Peer-mediated interventions address psychosocial impairment and treatment adherence. Demand concentrates in patient advocacy organization networks and academic center-affiliated programs.
Patient management holds installed base. Clinical research is climbing the fastest as evidence requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist infrastructure for rumination syndrome treatment clusters in nations with mature pediatric gastroenterology networks and favorable neuromodulation reimbursement frameworks. Device-assisted therapy adoption tracks regulatory clarity on implanted systems.
United States
Pediatric gastroenterology programs at academic medical centers in Boston and Philadelphia drive diagnostic protocol standardization. The FDA's breakthrough device designation pathway accelerates market access for diaphragmatic pacing systems. Cleveland Clinic and Mayo Clinic anchor dedicated rumination disorder registries generating real-world evidence for payer negotiations.
Germany
Integrated care contracts between statutory health insurers and gastroenterology practices expand behavioral therapy access. The EMA's Medical Device Regulation imposes additional clinical evidence requirements on neuromodulator market entrants. Heidelberg and Munich university hospitals coordinate multicenter trials for refractory functional GI conditions.
Japan
PMDA consultations on functional GI disorder devices streamline premarket approval timelines for diaphragmatic pacing systems. Tokyo and Osaka academic centers specialize in gut-brain axis research intersecting with rumination pathophysiology. METI funding for digital therapeutics supports algorithm-guided breathing retraining platform development.
United Kingdom
NHS England's specialized commissioning frameworks concentrate refractory case management in designated tertiary centers. MHRA post-Brexit device regulations maintain alignment with EMA standards while enabling streamlined national access pathways. London and Manchester pediatric gastroenterology networks pilot school-based screening protocols.
Australia
TGA priority review pathways for novel neuromodulation devices attract sponsor submissions from Asia-Pacific headquarters operations. Melbourne and Sydney teaching hospitals build multidisciplinary rumination disorder clinics combining gastroenterology and clinical psychology. Medicare reimbursement for telehealth behavioral services enables rural patient access to diaphragmatic breathing protocols.
Rumination Syndrome Market Competitive Environment
Concentration sits with diversified pharmaceutical conglomerates and emerging neuromodulation specialists. Market structure reflects tiered competition between established gastroenterology franchises and device-focused entrants targeting refractory case segments. Two strategic archetypes dominate: neurology-motility portfolio diversifiers and implantable system pure-plays. Competitive moves center on clinical trial infrastructure deployment and integrated care model partnerships with academic medical centers.
Among Japanese pharmaceutical conglomerates, Eisai Co., Ltd. represents the neurology portfolio diversification archetype, while Takeda Pharmaceutical Company Limited occupies a comparable position through its established gastroenterology franchise. Medtronic exemplifies the implantable device specialization vector within this competitive set. Pfizer Inc. and AbbVie anchor the North American pharmaceutical tier, with the former leveraging clinical trial infrastructure and the latter intersecting immunology research with gut-brain axis applications. These five entities collectively illustrate the market's bifurcation between pharmacological and device-assisted intervention platforms.
| Leading Market Players |
|---|
| Eisai Co., Ltd. |
| AbbVie |
| Pfizer Inc. |
| Johnson & Johnson |
| Novo Nordisk A/S |
| Medtronic |
| Takeda Pharmaceutical Company Limited |
| Bayer AG |
| AstraZeneca |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation agreements with academic medical centers lock in neuromodulator device access while compressing price volatility for implantable diaphragmatic pacing systems. These contractual structures tether supply security to predictable cost baselines across United States pediatric gastroenterology networks.
Pricing Analysis
FDA breakthrough device designation dictates the pricing tier structure for neuromodulation systems, separating PMA-track implants from 510(k)-cleared alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and bundled behavioral health support. Cost compression in the standard tier is intensifying because commercial payers are tightening prior authorization requirements for device-assisted therapies. Pediatric patients exhibit highest price sensitivity due to caregiver out-of-pocket exposure, while adult refractory cases anchor premium tier willingness-to-pay.
Supply Chain Analysis
Strategic stockpile preferences dominate neuromodulator component procurement, with manufacturers maintaining buffer inventories of phrenic nerve leads and pulse generators to offset surgical scheduling volatility. Device assembly concentrates in the United States, Ireland, and Costa Rica, drawing from specialized microelectronics feedstocks and biocompatible polymer substrates. Single-source vulnerability sits with sole-approved suppliers of implantable-grade titanium housings. Distribution runs through GPO-negotiated contracts with academic medical center networks and specialized pediatric gastroenterology clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rumination syndrome care is approaching a platform-economics inflection as telehealth infrastructure and implantable device registries achieve interoperability, enabling longitudinal patient data liquidity across previously siloed gastroenterology and behavioral health workflows.
For Market Incumbents: Secure exclusive data-sharing agreements with pediatric gastroenterology registries to defend against digital therapeutic platform encroachment. Deepen backward integration into diaphragmatic pacing electrode manufacturing to capture margin pools currently flowing to single-source component suppliers. Lock in capacity reservation contracts with Cleveland Clinic and Mayo Clinic referral networks before FDA PMA requirements tighten. For New Entrants and Emerging Players: Anchor in asynchronous app-based breathing protocol delivery, the most penetrable segment where HIPAA-compliant architectures have relaxed prior authorization barriers. Target rural United States markets underserved by behavioral therapist concentration in metropolitan corridors. Pursue hospital-at-home partnership models that bundle caregiver training with remote monitoring infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telehealth platform operators with integrated patient-reported outcome capture, positioning them as premium acquisition targets against device-centric pure-plays. Five-to-ten year viability hinges on FDA digital therapeutics framework maturation and EMA MDR compliance cost absorption. Watch for inflection when pediatric diagnostic protocols achieve school-based screening mandate status in multiple United States states.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pursuit | Accelerated PMA pathway for diaphragmatic pacing systems compresses time-to-reimbursement coverage at CMS. |
| Academic Medical Center Registry Partnership | Real-world evidence generation satisfies EMA MDR clinical evidence standards for European market entry. |
| Telehealth Platform Integration | HIPAA-compliant asynchronous delivery captures margin pools from rural patient populations previously excluded. |
| Backward Integration into Electrode Manufacturing | In-house production of phrenic nerve leads reduces single-source dependency and procurement cost volatility. |
| Pediatric Gastroenterology Clinic Co-location | Integrated care models reduce patient drop-off between behavioral and medical service encounters. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with pediatric gastroenterologists, behavioral health therapists, hospital GPO contract managers, and neuromodulator device engineers; and secondary validation through FDA 510(k) and PMA filings, ClinicalTrials.gov entries, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up patient volume estimates triangulated against top-down pharmaceutical and device manufacturer revenue disclosures.
Across the analysis window, forecasts employed segmented modeling across intervention modality, patient age cohort, care delivery infrastructure, and geographic regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns for comparable functional GI disorder therapies. Key inputs included pediatric diagnostic protocol expansion timelines, FDA device clearance probability assessments, and commercial payer prior authorization relaxation trajectories.
Material uncertainties — regulatory rejection of breakthrough device applications, reimbursement coding delays, and behavioral therapist workforce scaling constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding telehealth platform penetration and neuromodulator surgical capacity expansion. Revision becomes warranted when FDA PMA clinical evidence requirements extend beyond six-month sustained improvement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Epidermal Nevus Syndrome Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Global Scleroderma Diagnostics and Therapeutics Market
Specialty Medicine
Angioimmunoblastic T-Cell Lymphoma (AILT) Market
Specialty Medicine
Bronchiectasis Market
Specialty Medicine
Recto-Vaginal Fistula Market
Specialty Medicine
Bipolar Disorder (BPD) Market
Specialty Medicine
Aflatoxicosis Treatment Market
Specialty Medicine
Global Prurigo Nodularis Treatment Market
Specialty Medicine
Benign and Malignant Soft Tissue Tumors Treatment Market
Specialty Medicine
Global Pemphigus Vulgaris Market
Specialty Medicine
Barlow's Syndrome Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Cryptococcosis Market
Specialty Medicine
Global Sarcopenia Treatment Market
Specialty Medicine
Bartter Syndrome Treatment Market