
 Anxiety Disorders and Depression Treatment Market | 2026-2036
Anxiety Disorders and Depression Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Anxiety Disorders and Depression Treatment Market Intelligence
Buyer concentration among outpatient clinics is shifting as independent practices consolidate into regional behavioral health networks. Pfizer Inc. leverages its established psychiatric portfolio to maintain formulary positioning across these networks. Eli Lilly and Company differentiates through its neuroscience R&D intensity, while Johnson & Johnson anchors its presence via diversified mental health assets spanning pharmaceuticals and digital therapeutics.
Anxiety disorders and depression treatment encompasses pharmacological interventions, neuromodulation devices, and structured psychotherapeutic protocols designed to regulate serotonergic, noradrenergic, and glutamatergic neurotransmission. Antidepressants and anxiolytics constitute the mature revenue base, though digital delivery modes represent the fastest-expanding margin pool as remote patient monitoring and app-based cognitive behavioral therapy gain clinical validation. Oral formulations dominate volume, while injectable long-acting antidepressants command premium positioning in hospital and mental health facility settings.
The FDA governs new drug approvals and post-market surveillance for antidepressant therapies, while HIPAA mandates data security standards for digital mental health platforms. The DEA regulates controlled-substance scheduling for anxiolytic compounds, directly constraining prescribing flexibility. Stakeholders must monitor evolving FDA guidance on psychedelic-assisted therapies and state-level parity enforcement as these frameworks determine which modalities achieve scalable reimbursement.
Market Dynamics
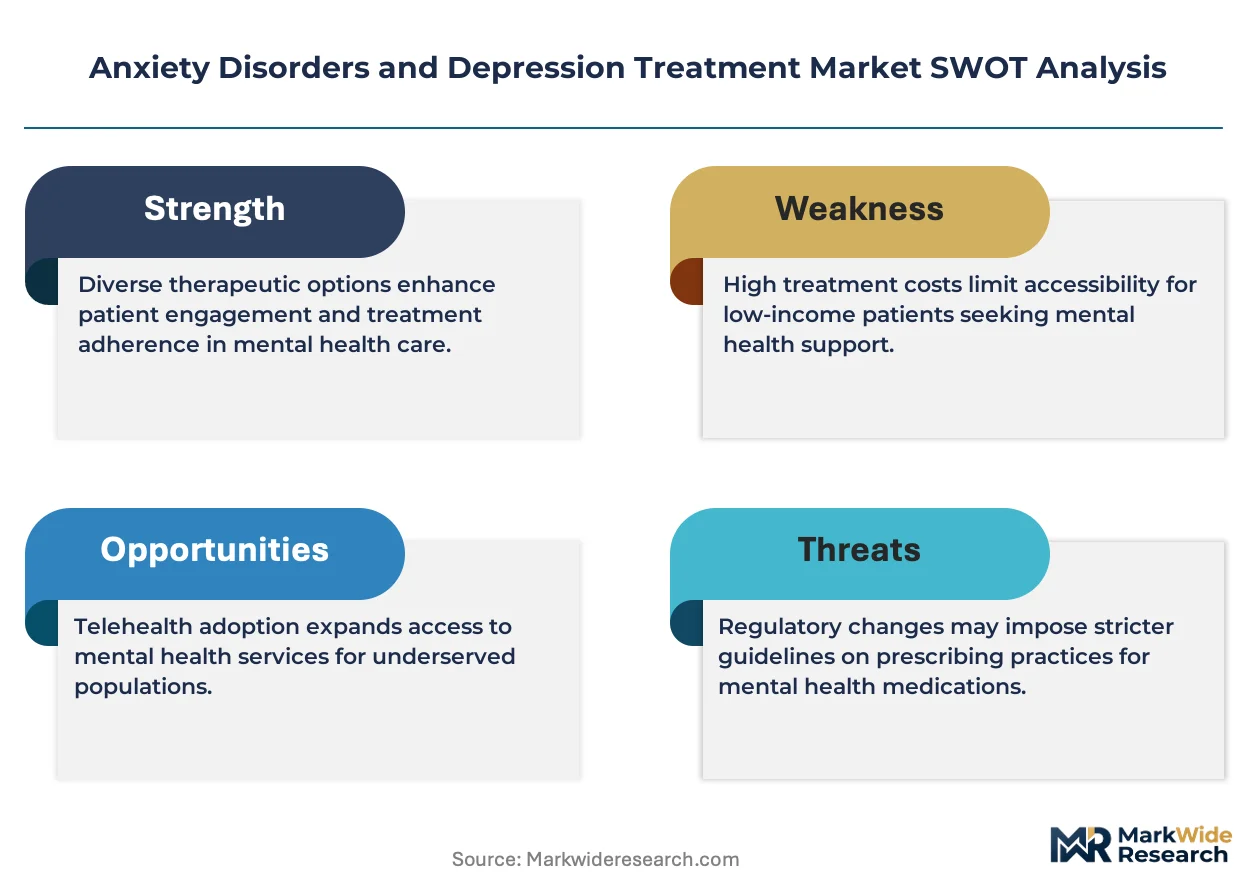
The FDA's accelerated approval pathways for novel antidepressant mechanisms are compressing development timelines while simultaneously fragmenting competitive positioning between established pharmaceutical portfolios and emerging psychedelic-assisted therapy candidates.
Growth Catalysts
- Integrated Care Networks:Reimbursement reforms within United States commercial and Medicaid programs are expanding patient access through value-based contracting models that reward outcome documentation.
- Digital Therapeutic Validation:App-based cognitive behavioral therapy platforms are gaining clinical credibility through randomized controlled trials, creating new prescription pathways for psychiatrists and primary care physicians.
- Long-Acting Injectable Formulations:Hospital and mental health facility procurement is shifting toward depot antidepressants that reduce medication adherence failures and emergency readmission rates.
Market Restraints
- Controlled-Substance Scheduling:DEA restrictions on anxiolytic prescribing create administrative burden for outpatient clinics and limit telehealth expansion for benzodiazepine-dependent patients.
- Specialty Pharmacy Concentration:Distribution of novel antidepressants concentrates among three national specialty pharmacy networks, creating single-source vulnerability for health systems.
- Placebo Response Variability:Elevated and inconsistent placebo response rates in depression trials inflate Phase III costs and extend regulatory review timelines for mechanistically novel compounds.
Strategic Opportunities
- Psychedelic-Assisted Therapy Frameworks:Oregon and Colorado state-level regulatory infrastructure for psilocybin administration services creates template markets for clinic-based psychedelic delivery models.
- Remote Patient Monitoring Integration:Wearable biomarker tracking combined with AI-driven symptom prediction is opening reimbursement codes for continuous care models between clinical visits.
- Neuromodulation Device Expansion:Transcranial magnetic stimulation protocols are migrating from hospital settings to outpatient behavioral health networks, broadening addressable patient populations.
Industry Challenges
- Psychiatric Workforce Constraints:Fellowship-trained child and adolescent psychiatrist scarcity limits expansion of early-intervention programs for anxiety disorders in pediatric populations.
- EHR Interoperability Friction:Digital therapeutic platforms face integration complexity with legacy electronic health record systems, delaying deployment across regional health networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anxiety Disorders and Depression Treatment Market |
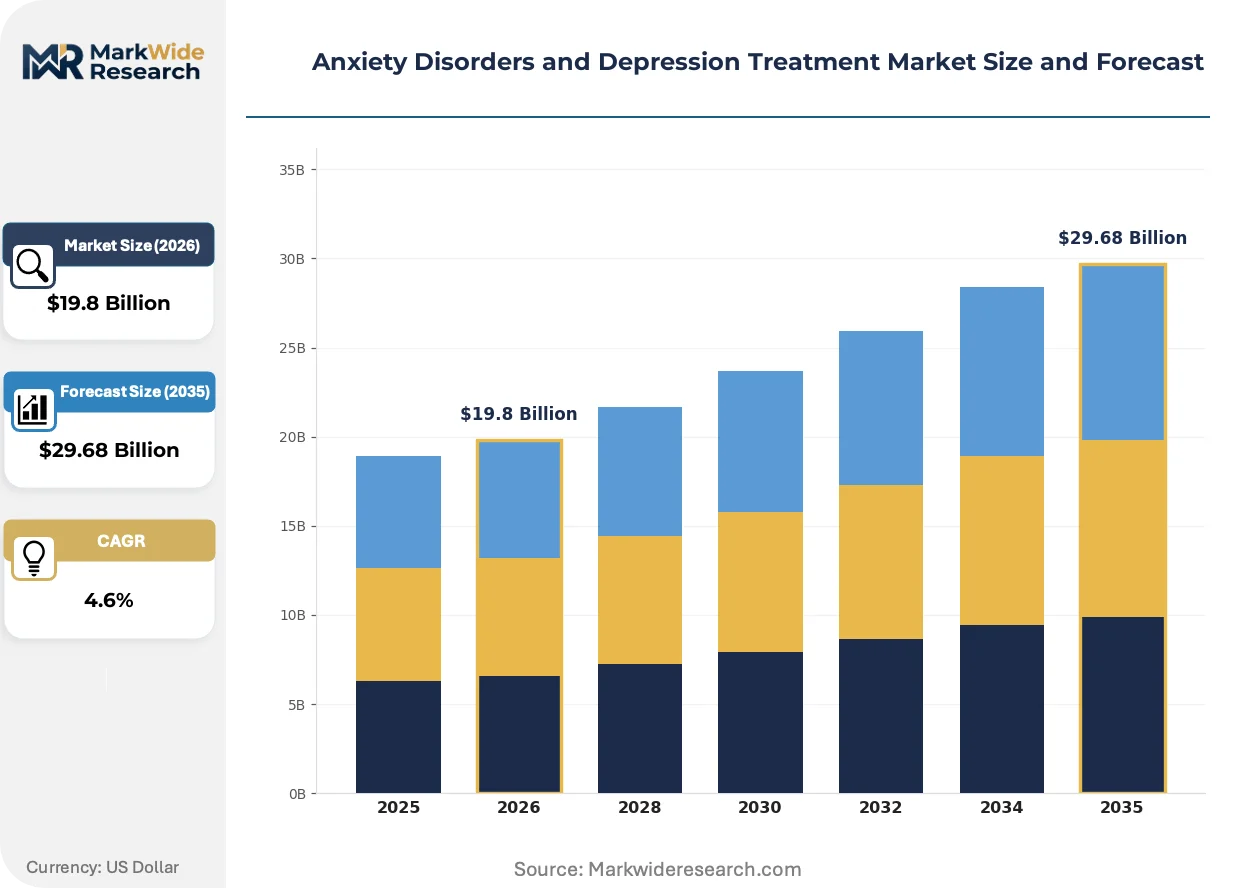
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $29.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antidepressants, Anxiolytics, Therapy Devices, Cognitive Behavioral Therapy End User: Hospitals, Outpatient Clinics, Home Care Settings, Mental Health Facilities Delivery Mode: Oral, Injectable, Transdermal, Digital Age Group: Children, Adolescents, Adults, Seniors |
| Companies Covered | Pfizer Inc., Eli Lilly and Company, GlaxoSmithKline plc, Johnson & Johnson, Merck & Co., Inc., H. Lundbeck A/S, AstraZeneca plc, AbbVie Inc., Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anxiety Disorders and Depression Treatment Market Strategic Shifts & Innovations
Novel mechanisms targeting glutamatergic and GABAergic pathways are displacing serotonin-centric development pipelines, while regulatory frameworks for digital therapeutics mature alongside hardware-based neuromodulation advances.
Digital phenotyping through smartphone sensor data is unifying passive behavioral monitoring with active clinical assessment. Outpatient psychiatric practices are adopting these platforms to extend care continuity between appointments. The technology is unifying symptom tracking with automated intervention triggers, compressing the feedback loop between patient experience and clinician response.
EMA's evolving guidance on decentralized clinical trials is reshaping antidepressant development logistics. Virtual trial components reduce patient dropout in depression studies where travel burden traditionally inflates placebo response. European neuropsychiatric drug developers are restructuring protocols to incorporate telehealth assessments and local laboratory networks.
Employer-sponsored mental health benefits are expanding direct-to-patient access models that bypass traditional payer preauthorization requirements. Large self-insured corporations are contracting directly with digital therapeutic platforms and virtual psychiatry networks. This channel shift concentrates volume in California, Texas, and New York metropolitan employment centers where Fortune 500 headquarters cluster.
Anxiety Disorders and Depression Treatment Market Segmentation
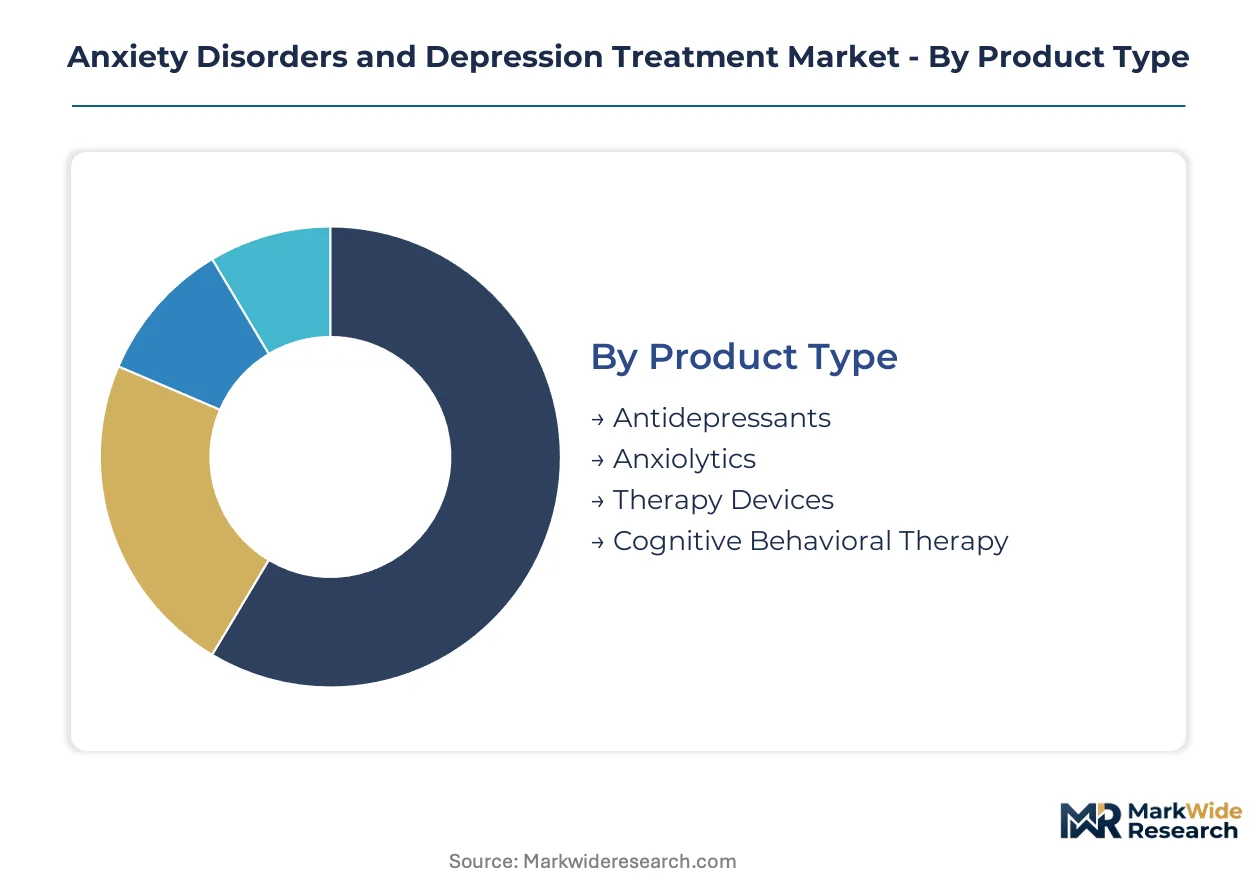
Segmentation in the anxiety disorders and depression treatment market reveals how reimbursement pathways, patient acuity, and care setting economics fragment commercial opportunity. Understanding these divisions illuminates where pharmaceutical portfolios, device manufacturers, and digital platforms compete for margin and volume.
Product Type:
Formulary positioning and patent life cycles drive procurement decisions across institutional buyers.
- Antidepressants:Serotonin reuptake inhibitors and atypical antidepressants constitute the mature revenue base, with long-acting injectable formulations commanding premium hospital contracts. Pfizer and Eli Lilly anchor market presence through established psychiatric portfolios across integrated care networks.
- Anxiolytics:Benzodiazepines and buspirone formulations face DEA scheduling constraints that limit telehealth expansion, concentrating volume in specialty pharmacy networks. Prescribing restrictions create administrative burden for outpatient clinics managing chronic anxiety patients.
- Therapy Devices:Transcranial magnetic stimulation and vagus nerve stimulation systems are migrating from hospital settings to outpatient behavioral health networks.
- Cognitive Behavioral Therapy:Structured psychotherapeutic protocols delivered through certified practitioners or validated digital platforms are gaining clinical credibility through randomized controlled trials.
Antidepressants lead on scale; cognitive behavioral therapy leads on momentum.
End User:
Facility type determines reimbursement rates, patient volume thresholds, and technology adoption speed.
- Hospitals:Emergency departments and inpatient psychiatric units handle acute depressive episodes and medication-resistant cases, with long-acting injectable antidepressants reducing readmission penalties under value-based contracting.
- Outpatient Clinics:Independent psychiatric practices consolidating into regional behavioral health networks are shifting procurement toward digital therapeutic platforms and remote patient monitoring integration.
- Home Care Settings:Employer-sponsored mental health benefits are expanding direct-to-patient access models that bypass traditional payer preauthorization requirements.
- Mental Health Facilities:Dedicated psychiatric hospitals and residential treatment centers are expanding service capacity to address rising patient volumes through depot medication protocols.
Hospitals capture the highest acuity cases; outpatient clinics are expanding most quickly.
Delivery Mode:
Patient adherence patterns and administration costs shape formulary tier placement.
- Oral:Immediate-release and extended-release tablets dominate prescription volume across primary care and psychiatry practices, though generic saturation compresses margins.
- Injectable:Long-acting formulations reduce medication adherence failures and emergency readmission rates, commanding premium positioning in hospital and mental health facility procurement.
- Transdermal:Patch-based delivery systems offer alternative administration for patients with gastrointestinal intolerance or swallowing difficulties.
- Digital:App-based cognitive behavioral therapy platforms and AI-driven symptom prediction tools are opening new reimbursement codes for continuous care models between clinical visits.
Oral formulations dominate volume; digital delivery shows the steepest expansion trajectory.
Age Group:
Regulatory scrutiny and workforce availability constrain pediatric expansion while senior populations drive polypharmacy complexity.
- Children:Fellowship-trained child and adolescent psychiatrist scarcity limits expansion of early-intervention programs, with FDA pediatric indication requirements extending development timelines for novel antidepressants.
- Adolescents:Rising anxiety disorder diagnoses in teenage populations are concentrating demand in academic medical centers and specialized adolescent psychiatric units.
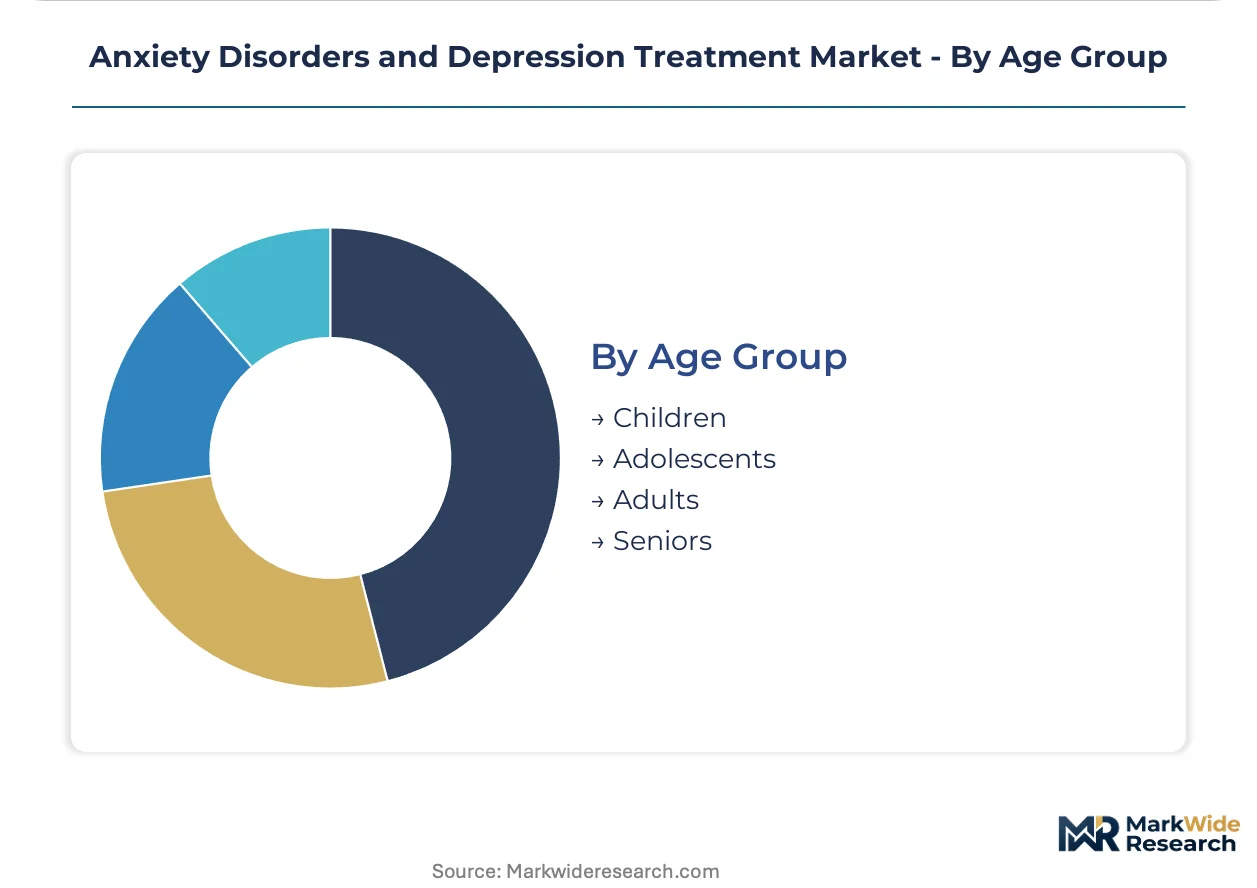
- Adults:The largest addressable population drives volume across all product categories, with integrated care networks targeting working-age patients through employer-sponsored benefit structures.
- Seniors:Late-life depression and comorbid cognitive decline create complex medication management challenges in Medicare Advantage populations.
Adults anchor commercial scale; adolescents are gaining share fastest amid diagnostic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement reforms outpace European parity enforcement in expanding treatment access, while Asian markets concentrate manufacturing capacity for active pharmaceutical ingredients.
United States
Integrated care networks in California and Texas are consolidating independent psychiatric practices into regional behavioral health systems. The FDA's accelerated approval pathways for novel antidepressant mechanisms compress development timelines for emerging therapies. Massachusetts academic medical centers anchor clinical trial infrastructure for psychedelic-assisted therapy candidates.
Germany
EMA decentralized trial guidance enables virtual assessment components that reduce patient dropout in depression studies. The country's national pharmaceutical regulator maintains stringent post-market surveillance for antidepressant therapies. Bavaria's pharmaceutical corridor hosts neuromodulation device development clusters alongside established psychiatric research hospitals.
Japan
PMDA streamlined review processes for digital therapeutics are accelerating app-based cognitive behavioral therapy platform approvals. METI innovation programs subsidize AI-driven symptom prediction tool development. Tokyo-Osaka metropolitan corridors concentrate employer-sponsored mental health benefit contracting with direct-to-patient access models.
United Kingdom
NHS England value-based contracting models reward outcome documentation for depression treatment pathways. MHRA post-Brexit regulatory autonomy enables faster adaptation to novel antidepressant mechanisms. London's digital health cluster attracts venture financing for remote patient monitoring integration platforms.
India
CDSCO manufacturing facility inspections for active pharmaceutical ingredients supply generic antidepressant volume to regulated markets. The country's national pharmaceutical regulator aligns with ICH guidelines for novel drug substance approvals. Hyderabad and Ahmedabad pharmaceutical corridors export sertraline and escitalopram intermediates to North American and European formulation facilities.
Anxiety Disorders and Depression Treatment Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the anxiety disorders and depression treatment landscape. The vendor base stratifies into three tiers: large-cap pharmaceutical portfolios with established psychiatric divisions, mid-cap neuroscience specialists with concentrated R&D intensity, and emerging platform developers commercializing digital therapeutic modalities. Consolidation pressure intensifies as regional behavioral health networks demand integrated formulary contracts spanning pharmacological and device-based interventions. Dominant competitive moves include portfolio diversification into long-acting injectable formulations and strategic partnerships with digital health platforms for remote patient monitoring integration.
Within the large-cap pharmaceutical tier, Pfizer Inc. and Eli Lilly and Company occupy anchor positions through established psychiatric portfolios. Pfizer Inc. leverages formulary positioning across consolidated care networks, while Eli Lilly and Company exemplifies neuroscience R&D intensity in novel mechanism development. Johnson & Johnson sits within the diversified healthcare conglomerate archetype, spanning pharmaceutical and digital therapeutic assets.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Eli Lilly and Company |
| GlaxoSmithKline plc |
| Johnson & Johnson |
| Merck & Co., Inc. |
| H. Lundbeck A/S |
| AstraZeneca plc |
| AbbVie Inc. |
| Bristol-Myers Squibb Company |
| Others |
Cost & Logistics Intelligence
Integrated care network consolidation across United States regional behavioral health systems is compressing procurement timelines and forcing supply chains to prioritize formulary positioning over volume discounts, elevating price sensitivity among outpatient clinic buyers while rewarding manufacturers with established psychiatric portfolios.
Pricing Analysis
Capacity additions in India and China for active pharmaceutical ingredient manufacturing are reshaping price floors for generic antidepressant formulations. Three-tier pricing structure across premium, standard, and economy levels separates long-acting injectable depot medications from immediate-release oral tablets and unbranded generics. Cost compression in the oral generic tier is intensifying because of CDSCO-inspected facility expansions in Hyderabad and Ahmedabad. Outpatient clinics exhibit the highest price sensitivity due to reimbursement rate stagnation, while hospital systems show greater tolerance for premium positioning when tied to readmission reduction metrics.
Supply Chain Analysis
Specialty chemical supply for serotonin reuptake inhibitor precursors rests on Indian and Chinese active pharmaceutical ingredient manufacturers, with formulation finishing concentrated in United States and European Union facilities. Key inputs include escitalopram base, sertraline hydrochloride, and fluoxetine intermediates. Single-source vulnerability concentrates among three national specialty pharmacy networks distributing novel antidepressants. Distribution runs through wholesaler agreements with integrated delivery networks and direct-to-pharmacy contracts for long-acting injectable products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in anxiety and depression treatment hinges on the shift toward digital therapeutic platforms and long-acting formulations, where premium pricing persists against generic oral saturation.
For Market Incumbents: Anchor formulary positioning through backward integration into long-acting injectable manufacturing capacity in United States and European Union production corridors. Digital therapeutic platform partnerships offer defensive moats against app-based cognitive behavioral therapy entrants. FDA accelerated approval pathway expertise constitutes a sustainable lever for novel mechanism antidepressants. For New Entrants and Emerging Players: The price-point gap between premium neuromodulation devices and economy-tier oral generics creates entry space for mid-market digital therapeutic platforms validated through randomized controlled trials. Employer-sponsored mental health benefits in California, Texas, and New York metropolitan corridors represent the most penetrable channel. Reimbursement code acquisition for remote patient monitoring integration offers a defensible go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with digital therapeutic developers possessing FDA breakthrough device designation and established health system pilot contracts. Five-to-ten year viability favors platforms combining wearable biomarker tracking with AI-driven intervention triggers. The signal to watch is state-level psychedelic-assisted therapy regulatory framework expansion beyond Oregon and Colorado.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Injectable Scale-Up | Reduces medication adherence failures in Medicaid and Medicare Advantage populations. |
| Digital Therapeutic FDA Submission | Unlocks prescription pathways through psychiatry and primary care physician networks. |
| Regional Behavioral Health Network Partnership | Secures formulary tier placement across consolidated outpatient clinic systems. |
| Psychedelic-Assisted Therapy Clinic Licensing | Establishes first-mover infrastructure in Oregon and Colorado template markets. |
| Remote Patient Monitoring Integration | Captures continuous care reimbursement codes between clinical visit intervals. |
Research Approach
Direct dialogue with drug development executives, formulary directors at integrated care networks, hospital procurement managers, and payer access specialists grounded the qualitative assessment. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov protocols, and CMS Medicare reimbursement databases. Bottom-up prescription volume modeling and top-down epidemiological prevalence estimates were triangulated across the analysis window.
Top-down macroeconomic drivers and bottom-up segment-level pricing dynamics shaped the analytical framework. Segmentation dimensions included product type, delivery mode, end-user facility category, and regional regulatory cluster. CAGRs were derived from patient volume trajectories, pricing elasticity assumptions, and penetration rates for digital therapeutic modalities. Forecast inputs incorporated FDA approval timeline probabilities and state-level parity enforcement patterns.
Caveats apply where DEA scheduling decisions for novel anxiolytic mechanisms or state-level psychedelic therapy regulatory reversals could materially shift the outlook. Forecasts reflect assumptions about reimbursement code expansion for digital therapeutics and workforce availability for child and adolescent psychiatry. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Germany Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
US Behavioral Health Market
Mental Health Services
Behavioral Health Care Software and Services Market
Mental Health Services
Seasonal Affective Disorder (SAD) Market
Mental Health Services
Global Mental Health Care Software and Services Market
Mental Health Services
South Korea Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
UK Mental Health Apps Market
Mental Health Services
Global Mental Health Apps Market
Mental Health Services
Obsessive-Compulsive Disorder Market
Mental Health Services
Panic Attack Treatment Market
Mental Health Services
US Workplace Stress Management Market
Mental Health Services
Maternal Mental Health Market
Mental Health Services
AI-Powered Mental Health Solutions Market
Mental Health Services
Mental Health Market
Mental Health Services
Postpartum Depression (PPD) Treatment Market
Mental Health Services
Depression Treatment Market