
 Cereal Packaging Market | 2026-2036
Cereal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Cereal Packaging Market Analytics
ISO 18606 compostability certification is rotating supplier eligibility across the European supply base, forcing converters to retest laminate structures. Amcor Limited leverages its global film extrusion network to sustain multi-layer barrier R&D programs. Smurfit Kappa Group anchors regional kraft paper supply through integrated pulp operations in Scandinavia. Mondi Group competes on molded-fiber technology leadership for dry-goods protection.
Cereal packaging encompasses primary and secondary containment systems engineered to preserve organoleptic stability, moisture resistance, and shelf-life extension for processed grain products, typically incorporating oxygen-barrier films, grease-resistant paperboard, or metallized substrates in form-fill-seal or pre-made configurations. Bags and boxes retain the largest installed base, though pouches with resealable zipper closures are capturing growth in premium and organic cereal segments where portion control and freshness retention command price premiums. Plastic remains dominant in high-barrier applications, yet paper and fiber-based materials are displacing conventional structures where fiber sourcing and recyclability credentials influence retailer procurement decisions.
The EU Packaging and Packaging Waste Regulation and the FDA's food-contact substance notification requirements jointly govern material migration limits and recycling claims, compelling converters to maintain dual-jurisdiction compliance documentation. The EPA's emerging sustainable materials management priorities and state-level extended producer responsibility frameworks in California and Oregon are adding compliance layers for North American suppliers. Stakeholders must monitor evolving recyclability definitions and invest in mono-material or fiber-based validated structures before mandatory recycled-content thresholds lock in supplier qualifications.
Market Dynamics
Material transition mandates from the EU Packaging and Packaging Waste Regulation are forcing converters to abandon multi-layer plastic laminates before recyclability thresholds take full effect, compressing qualification timelines for paper-based barrier alternatives.
Growth Catalysts
- EU Green Deal packaging targets:Mandatory recycled-content thresholds for fiber-based formats are pulling investment into kraft paper extrusion and coating lines across German and French converter facilities.
- Organic cereal segment expansion:Premium grain producers in the United States are specifying zipper-equipped stand-up pouches to differentiate shelf presence and justify price positioning.
- Mono-material polyethylene advances:Metallocene catalyst technology is enabling high-barrier single-substrate films that satisfy oxygen transmission requirements without aluminum oxide layers.
Market Restraints
- Pulp cost volatility:Scandinavian integrated producers control regional kraft supply, exposing non-integrated converters to NBSK price swings without captive fiber security.
- Barrier performance gaps:Paper-based grease resistance and moisture vapor transmission rates lag metallized PET specifications, limiting adoption in nut-cluster and granola formats with high oil content.
- Extended producer responsibility fees:California and Oregon state frameworks are layering compliance costs onto plastic-format suppliers before recycled-content mandates mature.
Strategic Opportunities
- India organized retail penetration:Modern trade expansion in Mumbai and Bangalore is creating first-mover advantage for pre-made pouch suppliers serving multinational cereal licensees.
- Home-composting certification pathway:ISO 18606 validation opens premium positioning in German and Austrian markets where municipal composting infrastructure supports consumer disposal claims.
- E-commerce fulfillment optimization:D2C cereal subscription services are specifying damage-resistant molded-fiber secondary packaging to reduce dimensional weight charges and returns.
Industry Challenges
- Migration testing backlog:EFSA food-contact substance notification queues are delaying laminate structure approvals by 14-18 months, freezing product launches.
- Retrofit capex intensity:Converting legacy form-fill-seal lines to handle heat-sealable paper webs requires $2-4 million per production cell excluding qualification downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cereal Packaging Market |
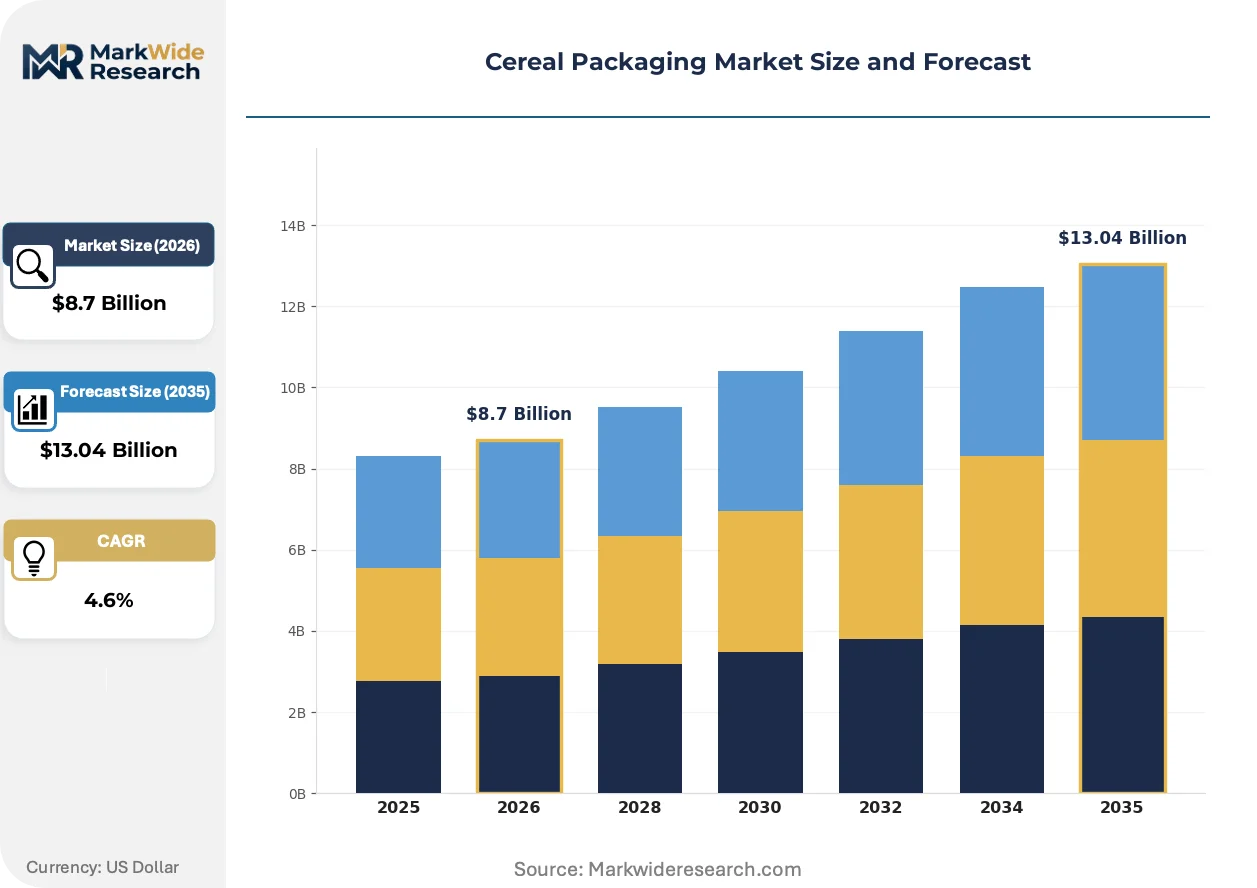
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bags, Boxes, Pouches, Cans Material: Plastic, Paper, Glass, Metal End User: Retail, Food Service, Wholesalers, Distributors Closure Type: Zipper, Seal, Cap, Tie |
| Companies Covered | Amcor Limited, Smurfit Kappa Group, Mondi Group, WestRock Company, DS Smith, Graphic Packaging International, Berry Global, Huhtamaki, Tetrapak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cereal Packaging Market Evolving Landscape
Active and intelligent packaging integration is redefining shelf-life assurance, with oxygen-scavenging films and time-temperature indicators migrating from pharmaceutical applications into dry-goods protection.
Barrier coating chemistry is bifurcating between bio-based waterborne dispersions and plasma-deposited silicon oxide layers. Premium organic brands in Germany and the Netherlands are specifying polylactic acid-coated kraft for composting credentials, while conventional mass-market producers retain metallized substrates for cost-controlled performance. This split is compressing mid-tier converter margins as qualification costs force specialization at either end of the performance spectrum.
REACH substance restriction proposals targeting per- and polyfluoroalkyl substances are eliminating grease-resistant fluorochemical treatments from paperboard cereal liners by 2026. ECHA consultation timelines are accelerating reformulation programs at Scandinavian pulp integrators who supply recycled-content folding carton grades. Breakfast cereal manufacturers with EU distribution are pre-qualifying silicone and clay-based alternatives to avoid supply discontinuity.
Retail buyer consolidation is concentrating procurement authority among German and US supermarket chains, compressing supplier rosters and extending payment terms. Private-label cereal producers are responding with direct mill relationships that bypass traditional converter-distributor channels, particularly for standard-grade kraft pillow bags. This disintermediation is most visible in Aldi and Lidl supply chains across Central Europe.
Cereal Packaging Market Segmentation
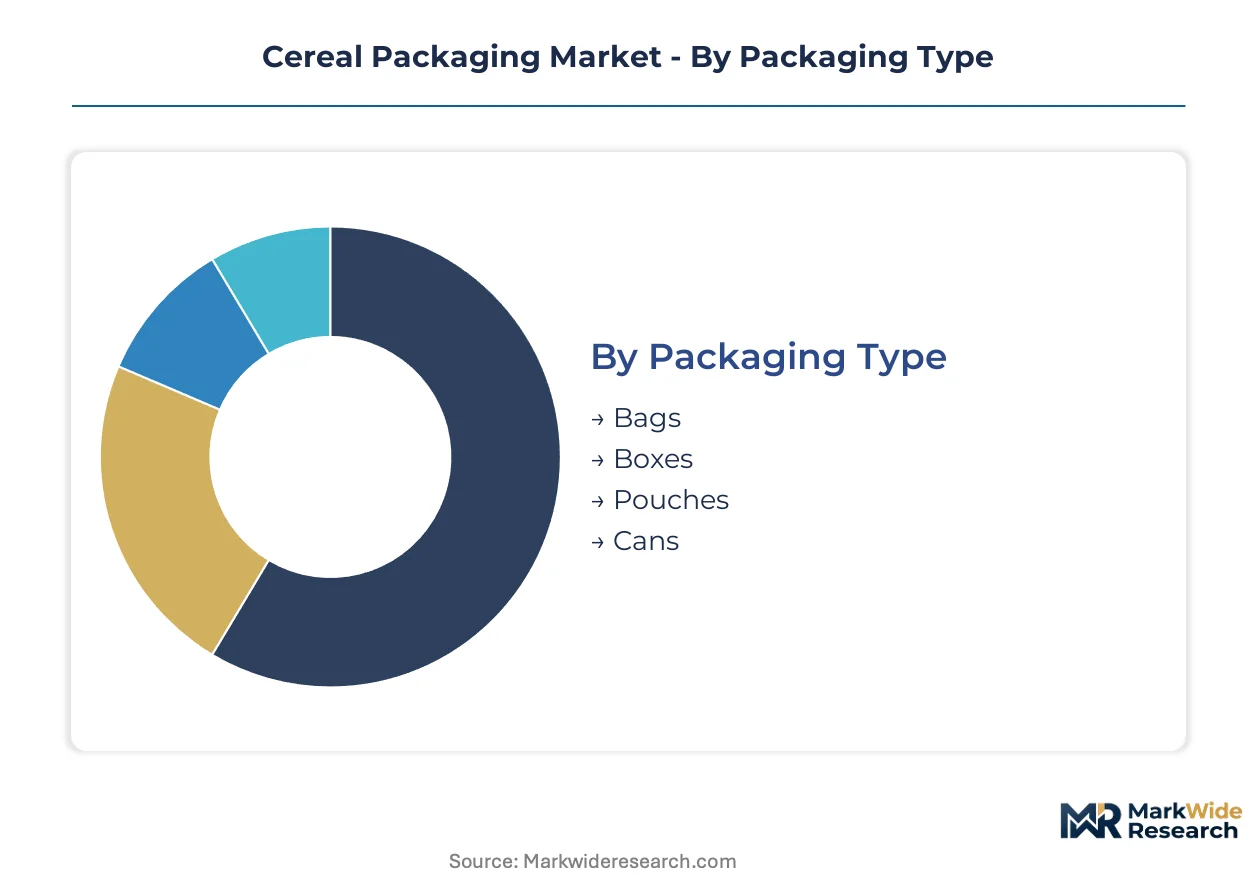
Packaging format selection in cereal markets hinges on shelf-life engineering, retail channel requirements, and material compliance costs. Each segmentation axis reveals distinct margin architectures and supplier qualification barriers that shape procurement decisions across branded and private-label producers.
Packaging Type:
Margin pools concentrate in formats offering barrier customization and resealability premiums, with commodity formats facing price compression from retailer consolidation.
- Bags:Pillow pouches and gusseted bags dominate high-volume production runs through continuous form-fill-seal operations. German and US private-label producers specify heat-sealable polypropylene or paper-laminate structures for cost-controlled distribution through Aldi and Lidl networks.
- Boxes:Folding cartons with liner bags retain the largest installed base in mass-market cereals, leveraging established paperboard supply chains and high-speed erecting equipment. The format faces margin pressure as EPR fees layer onto plastic liner components in California and Oregon state frameworks.
- Pouches:Stand-up configurations with resealable zipper closures command price premiums in organic and premium segments where portion control and freshness retention justify higher unit costs. Mumbai and Bangalore modern trade expansion is pulling first-mover investment into pre-made pouch capacity.
- Cans:Metal composite containers serve gift and export markets requiring maximum protection against moisture and oxygen ingress, though material cost and shipping weight limit penetration beyond specialty applications.
Boxes hold installed capacity across North American and European retail. Pouches are rotating up the share rankings in premium organic segments.
Material:
Raw material qualification timelines and regulatory migration testing are concentrating procurement authority among converters with dual-jurisdiction compliance documentation.
- Plastic:Multi-layer laminates with metallized or aluminum oxide barrier layers retain dominance in nut-cluster and granola formats where oxygen transmission rates below 0.1 cc/m²/day are mandatory. Metallocene-catalyzed mono-material polyethylene advances are displacing complex laminates where recyclability claims influence retailer acceptance.
- Paper:Kraft and recycled-content folding grades are capturing share through EU Green Deal recycled-content mandates and compostability certifications. Scandinavian integrated pulp producers anchor regional supply, exposing non-integrated converters to NBSK price volatility without captive fiber security.
- Glass:Premium positioning in artisanal and gift cereal segments leverages inert material properties and reuse potential, though weight and fragility constrain distribution economics.
- Metal:Tinplate and aluminum composite cans serve export and long-shelf-life applications where maximum barrier performance outweighs material and logistics costs.
Plastic retains barrier-performance leadership. Paper is climbing the fastest as EU recyclability thresholds tighten.
End User:
Channel-specific packaging specifications are diverging as retail consolidation concentrates procurement authority while food service and e-commerce create specialized demand pockets.
- Retail:Supermarket and hypermarket chains in Germany and the United States specify standardized case counts, pallet configurations, and on-shelf visibility requirements that favor high-volume box and bag formats with established supply chain footprints.
- Food Service:Hotels, cafeterias, and institutional buyers specify bulk formats with portion-control features and dispensing compatibility, often requiring custom case packs outside retail-standard configurations.
- Wholesalers:Distribution intermediaries aggregate demand across smaller retail accounts, favoring standardized packaging that minimizes inventory complexity and maximizes cross-dock efficiency.
- Distributors:Specialty and organic cereal distributors specify packaging with sustainability credentials and premium shelf presence to align with curated product assortments and higher service-level expectations.
Retail commands volume concentration. Food service is rotating up the share rankings as out-of-home consumption patterns shift.
Closure Type:
Resealability technology investments are segmenting the supplier base between zipper-equipped premium formats and commodity seal configurations.
- Zipper:Press-to-close and slider mechanisms in stand-up pouches justify price premiums through extended freshness retention and portion control, with German organic brands leading specification adoption.
- Seal:Heat-sealed fin or lap seals dominate high-speed bag and pouch production, offering lowest unit cost where single-use consumption patterns predominate.
- Cap:Screw and snap closures on composite cans serve bulk and institutional formats requiring repeated access and controlled dispensing.
- Tie:Twist ties and clip closures retain niche application in bakery-style and artisanal cereals where traditional presentation supports brand positioning.
Seal configurations hold installed capacity. Zipper closures are rotating up the share rankings in premium segment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European cereal packaging logistics, handling kraft paper imports from Scandinavian pulp mills and distributing converted materials across Central European manufacturing corridors.
United States
Private-label cereal producers in Wisconsin and Michigan are retrofitting form-fill-seal lines for recyclable paper-based formats. The EPA's sustainable materials management priorities and California's extended producer responsibility framework are layering compliance costs onto plastic-format suppliers. Chicago-area converter clusters are investing in mono-material polyethylene extrusion capacity to satisfy retailer recyclability mandates.
Germany
Organic cereal brands in Bavaria are specifying zipper-equipped stand-up pouches to justify premium shelf positioning. The EU Packaging and Packaging Waste Regulation's recycled-content thresholds are pulling investment into kraft paper coating lines across Baden-Württemberg converter facilities. The Hamburg-Rotterdam corridor anchors regional distribution for Nordic-sourced fiber materials.
India
Modern trade expansion in Mumbai and Bangalore is creating first-mover advantage for pre-made pouch suppliers serving multinational cereal licensees. The FSSAI's evolving food-contact material standards are accelerating converter qualification timelines. Gujarat-based flexible packaging clusters are scaling metallized film capacity for granola and nut-cluster formats.
United Kingdom
Supermarket chain consolidation is concentrating procurement authority among London-headquartered retailers, compressing supplier rosters for standard-grade kraft pillow bags. The UK's post-EU packaging regulations are maintaining alignment with REACH substance restrictions while introducing domestic extended producer responsibility fee structures. The Midlands packaging corridor is retrofitting legacy equipment for heat-sealable paper web handling.
France
Premium organic cereal producers in Île-de-France are specifying polylactic acid-coated kraft for home-composting certification pathways. ECHA consultation timelines on per- and polyfluoroalkyl substance restrictions are accelerating reformulation programs at folding carton suppliers. The Lyon-Grenoble industrial basin is developing plasma-deposited silicon oxide barrier coating capacity for grease-resistant applications.
Cereal Packaging Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and R&D scale, creating a tiered structure where scale-driven converters anchor high-volume supply while regional specialists capture premium niches. The vendor base clusters around three archetypes: integrated pulp-to-package operators, film extrusion specialists with barrier R&D programs, and molded-fiber technology leaders. M&A activity concentrates on coating technology acquisitions and regional converter roll-ups, while capacity expansion focuses on mono-material extrusion lines and paper-based barrier validation.
Within the integrated pulp-to-package tier, Smurfit Kappa Group and Mondi Group exemplify operators with captive fiber security and regional kraft supply anchoring. Among film extrusion specialists, Amcor Limited occupies a position representing global multi-layer barrier R&D scale. These three entities sit within distinct competitive vectors—Nordic fiber integration, Central European molded-fiber leadership, and Asia-Pacific extrusion network breadth—illustrating how geographic and technological specialization shapes positioning without overlapping core competencies.
| Leading Market Players |
|---|
| Amcor Limited |
| Smurfit Kappa Group |
| Mondi Group |
| WestRock Company |
| DS Smith |
| Graphic Packaging International |
| Berry Global |
| Huhtamaki |
| Tetrapak |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Scandinavian pulp integrators and German folding carton converters lock in kraft fiber supply visibility while insulating buyers from NBSK spot price volatility. These contracts bundle volume commitments with coating technology access, embedding price predictability into EU Green Deal compliance timelines.
Pricing Analysis
Volume-discount tiering structures separate premium organic brands specifying zipper-equipped stand-up pouches from mass-market private-label producers sourcing standard-grade pillow bags. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 18606 certification status, captive fiber integration, and barrier performance specifications. Cost compression in commodity paper-laminate formats is intensifying because Aldi and Lidl procurement consolidation extends payment terms and compresses converter margins. Private-label cereal producers exhibit highest price sensitivity, while premium organic brands with composting certification requirements demonstrate lowest sensitivity due to sustainability-driven consumer willingness to pay.
Supply Chain Analysis
Sweden and Finland anchor regional kraft pulp supply through integrated mill operations, while Germany and France concentrate converting capacity for heat-sealable paper webs and barrier coating lines. Raw material dependencies draw from Nordic softwood fiber, metallocene-catalyzed polyethylene resin, and plasma-deposited silicon oxide precursors. Single-source vulnerability concentrates in Scandinavian NBSK supply where non-integrated converters lack captive fiber security. Distribution runs through the Hamburg-Rotterdam corridor for Central European manufacturing, with Chicago-area clusters serving North American retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
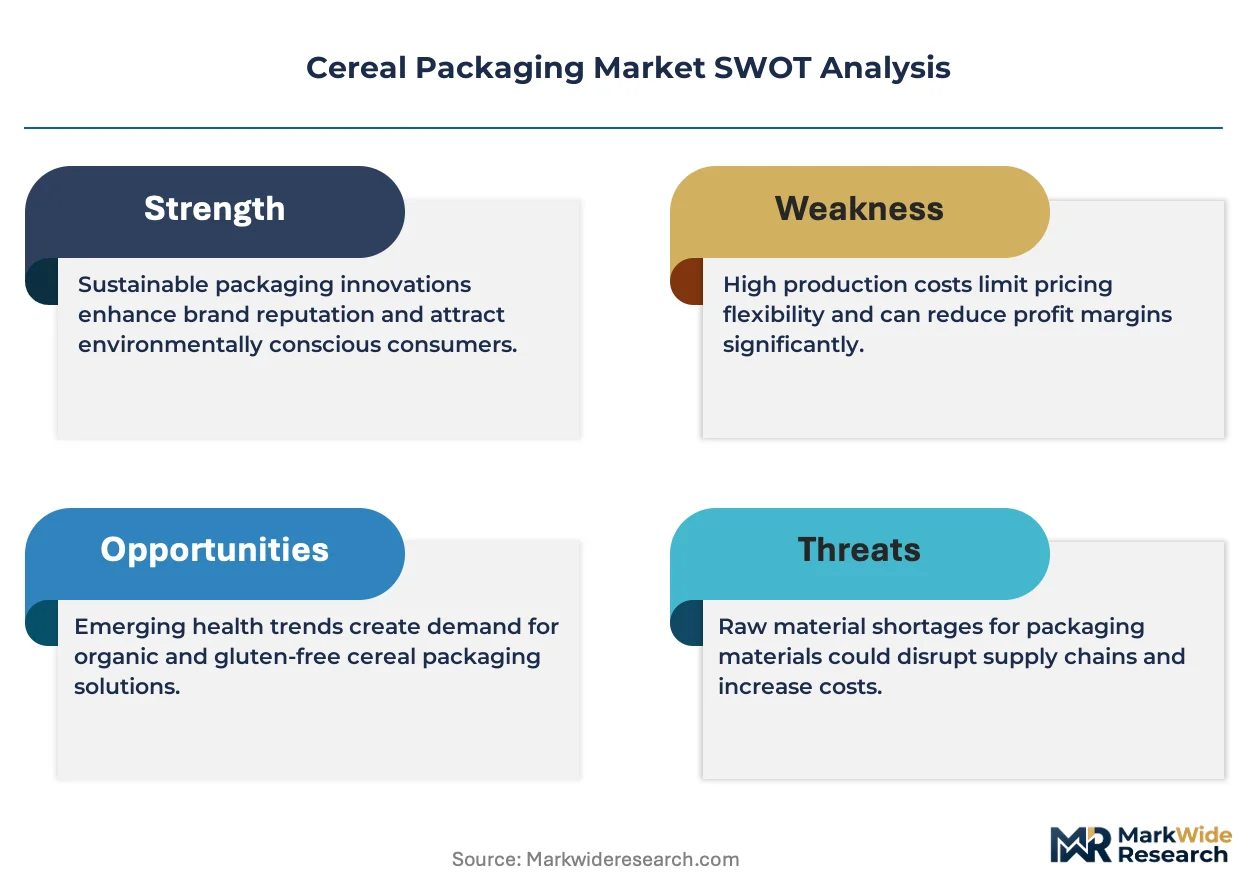
Cereal packaging functions as a platform-economics inflection where EU Packaging and Packaging Waste Regulation compliance creates interoperability requirements across converter networks, forcing standardization on validated mono-material and fiber-based structures.
For Market Incumbents: Consolidate coating technology capabilities through selective acquisition of plasma-deposited barrier specialists in the Lyon-Grenoble basin, securing grease-resistant performance without fluorochemical treatments. Deepen backward integration into Nordic pulp supply through equity stakes or long-term offtake structures, insulating against NBSK price volatility that threatens margin stability in standard-grade formats. For New Entrants and Emerging Players: Lead with home-composting certification pathways targeting German and Austrian municipal composting infrastructure, where ISO 18606 validation commands price premiums unavailable to conventional suppliers. Penetrate the India organized retail expansion in Mumbai and Bangalore through pre-made pouch capacity partnerships with multinational cereal licensees, leveraging FSSAI qualification timelines that disadvantage established European converters. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap converters with validated paper-barrier structures and established retailer qualification relationships, positioned to capture share as EU recyclability thresholds displace multi-layer plastic laminates. Watch for EFSA food-contact substance notification queue clearance rates as the inflection signal indicating which laminate structures will unlock frozen product launches and supplier requalification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Technology Acquisition | Plasma-deposited silicon oxide capacity in France addresses REACH fluorochemical restrictions before 2026 deadlines. |
| Mono-Material Extrusion Scale-Up | Metallocene-catalyzed polyethylene lines in Chicago satisfy California EPR framework recyclability mandates. |
| Composting Certification Investment | ISO 18606 validation opens premium positioning in German and Austrian municipal composting markets. |
| Direct Retail Mill Relationships | Bypassing converter-distributor channels aligns with Aldi and Lidl supply chain disintermediation trends. |
| E-Commerce Secondary Packaging Development | Molded-fiber protection reduces dimensional weight charges for D2C cereal subscription fulfillment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU Packaging and Packaging Waste Regulation consultation documents, EFSA food-contact substance notification queues, and Scandinavian pulp producer trade disclosures. Primary interviews captured converter operations directors, cereal manufacturer procurement leads, and retailer category buyers across Germany, the United States, and India. Secondary validation drew from customs trade data, SEC filings of listed packaging companies, and EPA sustainable materials management priority statements. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers.
Segmentation dimensions modeled include packaging format type, material substrate classification, closure mechanism, end-user channel, and regional regulatory cluster across the analysis window. CAGRs were derived from installed base rotation rates, capacity expansion announcements, and compliance-driven substitution elasticities. Industry-specific forecast inputs incorporated ECHA consultation timelines on per- and polyfluoroalkyl substance restrictions and FSSAI food-contact material standard evolution.
The analysis sits within stated boundaries; outcomes outside EU Packaging and Packaging Waste Regulation implementation timelines or FSSAI acceleration scenarios would require recalibration. Forecasts reflect assumptions about barrier coating technology maturation, pulp cost volatility ranges, and retailer procurement consolidation trajectories. Recalibration cycles align with material shifts in EFSA notification queue clearance rates and EU recycled-content threshold enforcement phases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Pie Packaging Market
Food Packaging
Food Partition Trays Market
Food Packaging
Cupcake Containers Market
Food Packaging
Fresh Produce Trays Market
Food Packaging
Coffee Capsules and Pod Packaging Market
Food Packaging
Fast Food Containers Market
Food Packaging
Sugar Packaging Market
Food Packaging
North America Frozen Food Packaging Market
Food Packaging
Oven Bags and Pouches Market
Food Packaging
Chocolate Packaging Market
Food Packaging
Pizza Box Market
Food Packaging
United States Frozen Food Packaging Market
Food Packaging
North America Food Packaging Market
Food Packaging
Europe Canned Food Packaging Market
Food Packaging
Chilled Food Packaging Market
Food Packaging
Honey Packaging Market