
 North America Food Packaging Market | 2026-2036
North America Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Packaging Market Intelligence
Multi-source procurement among protein processors and dairy cooperatives is broadening as buyers seek resilience against resin price volatility and logistics bottlenecks. Amcor plc leverages its continental extrusion network to sustain film supply commitments across the Midwest. Silgan Holdings anchors metal food can production through captive steel sourcing and Midwestern stamping operations. Sealed Air Corporation differentiates through automated case-ready packaging systems deployed at poultry and beef processing plants.
North America food packaging encompasses materials and containers engineered to preserve shelf stability, prevent contamination, and enable temperature-controlled distribution of edible products, with oxygen transmission rates and moisture vapor barriers constituting critical functional parameters. Flexible packaging dominates volume in snack and frozen vegetable segments due to lightweighting and format versatility, while rigid paperboard commands margin pools in premium ready-meal and organic cereal applications. Biodegradable materials represent the fastest-growing material category as brand owners respond to California and New York state-level extended producer responsibility mandates.
The FDA governs food contact notifications and migration thresholds for plastic additives, while Health Canada enforces the Safe Food for Canadians Regulations governing packaging material safety declarations. EPA guidelines on per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant paper and molded fiber alternatives across the supply base. Stakeholders must monitor pending state-level packaging EPR legislation and PFAS bans to anticipate capital reallocation between conventional and bio-based production lines.
Market Dynamics
Extended producer responsibility mandates across California, New York, and Canada are forcing capital reallocation from conventional plastics to bio-based and recyclable substrates, compressing legacy film margins while rewarding early movers in molded fiber and compostable barrier technologies.
Growth Catalysts
- California's SB 54 EPR framework:The mandate requires 30% post-consumer recycled content by 2028, pulling investment into rPET extrusion capacity and chemical recycling infrastructure for food-grade resins.
- Quick-service restaurant expansion:Chains are standardizing fiber-based clamshells and molded pulp bowls for hot sandwich and bowl programs, creating pull-through demand for integrated thermoforming and fiber molding equipment.
- High-pressure processing adoption:Cold pasteurization technology enables clean-label shelf extension without retort, driving demand for flexible high-barrier films that withstand 600 MPa pressure cycles in protein and beverage applications.
Market Restraints
- Resin price volatility:Ethylene and propylene feedstock swings tied to Gulf Coast petrochemical capacity constrain margin predictability for multilayer film converters serving frozen food and snack segments.
- Midwest steel concentration:Tinplate and chromium-coated steel for food cans clusters around Ohio and Indiana mills, creating single-source vulnerability when automotive demand spikes absorb rolling capacity.
- PFAS regulatory friction:EPA enforcement of TSCA Section 5 on fluorinated grease barriers forces immediate reformulation of microwave popcorn bags and fast-food wrappers without fully qualified commercial alternatives.
Strategic Opportunities
- Mexico nearshoring corridor:Querétaro and Guanajuato packaging clusters offer duty-advantaged export platforms to US retail and foodservice buyers seeking to de-risk Asia-Pacific supply chains.
- Smart packaging convergence:Integration of time-temperature indicators and NFC-enabled traceability into modified-atmosphere trays creates premium positioning for protein processors serving club retail channels.
- Canada's single-use plastics prohibition:Federal bans on checkout bags, cutlery, and stirrers accelerate demand for certified compostable alternatives, opening first-mover slots for domestic PLA and PHA compounders.
Industry Challenges
- Migration testing backlog:FDA food contact notification review timelines have extended to 18-24 months for novel bio-based barrier coatings, delaying commercialization of seaweed-derived films and lignin-based oxygen scavengers.
- Legacy equipment retrofit costs:Converting existing form-fill-seal lines to handle thinner gauge films and recyclable mono-material structures requires $2-5 million per facility in servo controls and sealing jaw modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Packaging Market |
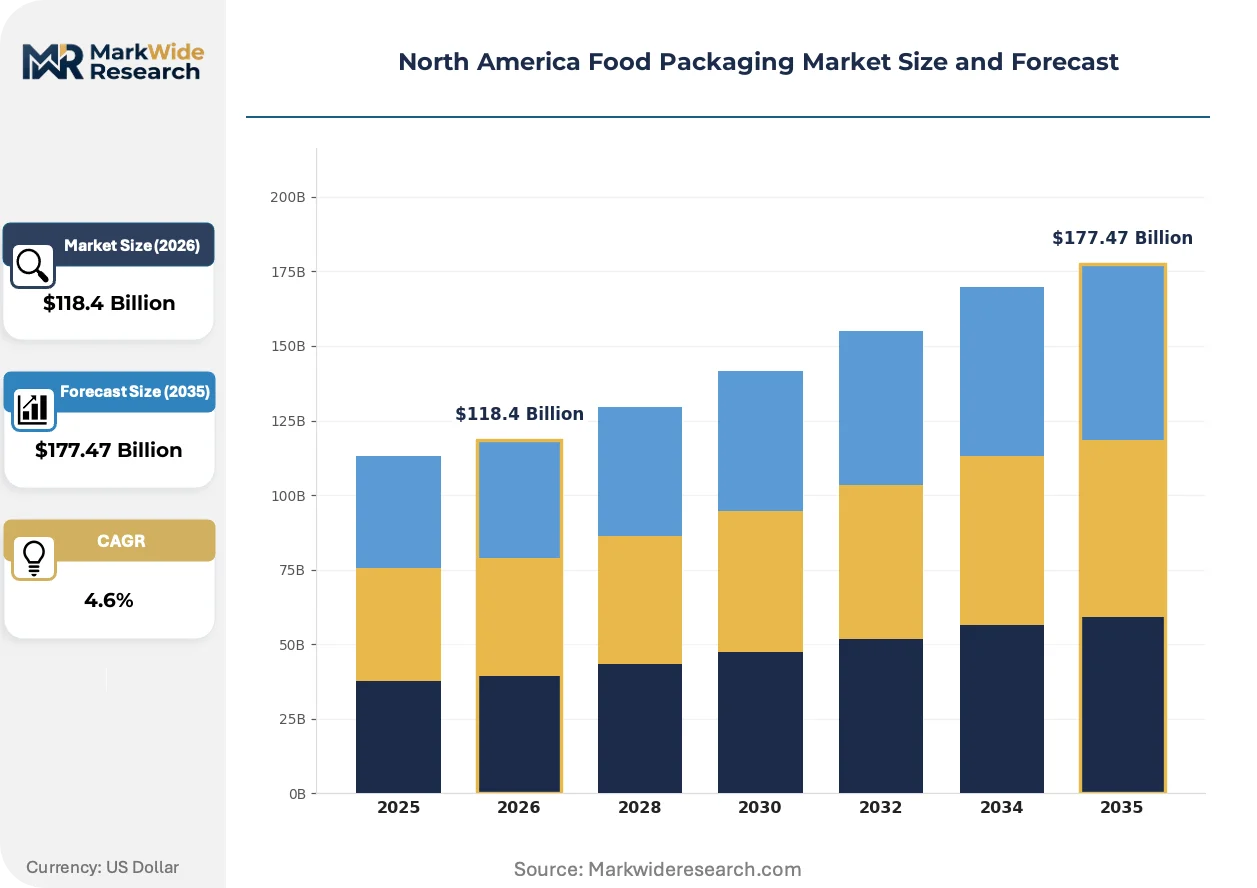
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $177.47 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
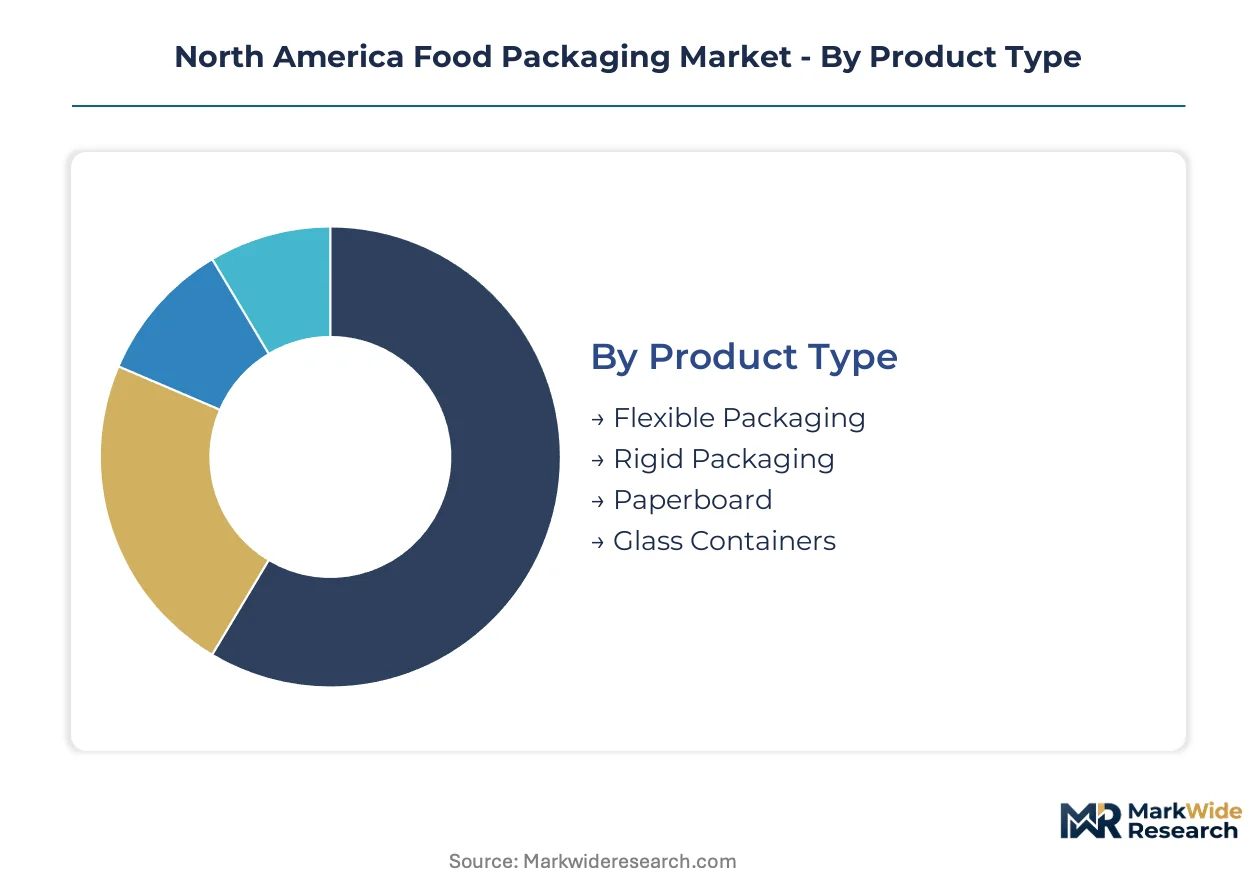
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Paperboard, Glass Containers Material: Plastic, Metal, Paper, Biodegradable Materials End User: Food & Beverage, Bakery, Dairy, Snack Foods Packaging Type: Wraps, Bags, Bottles, Trays |
| Companies Covered | Silgan Holdings, Sealed Air Corporation, Amcor plc, Sonoco Products Company, Pactiv Evergreen, Crown Holdings, WestRock Company, Graphic Packaging International, Ball Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Packaging Market Strategic Shifts & Innovations
Active and intelligent packaging systems are migrating from pharmaceutical traceability into food safety applications, while mechanical and chemical recycling advances narrow the performance gap between virgin and post-consumer resins for direct food contact.
Mono-material polyethylene structures with enhanced ethylene vinyl alcohol coextrusion are absorbing barrier functionality previously delivered by incompatible multilayer films. Retail grocers and branded snack manufacturers are accelerating qualification timelines for these recyclable alternatives. The shift is absorbing capital from conventional PET/PE/EVOH laminates and compressing demand for non-recyclable pouch formats in private-label frozen vegetable and granola segments.
EPA enforcement of per- and polyfluoroalkyl substance restrictions under TSCA Section 6 is eliminating long-chain fluorochemicals from grease-resistant paperboard and molded fiber foodservice items. Paper mills and molded pulp converters are scrambling to qualify silicone, clay, and bio-wax barrier coatings that meet FDA migration thresholds. Quick-service chains in California and Washington state face the most immediate compliance deadlines and are driving specification changes across national supply contracts.
Direct-store-delivery networks for bakery and dairy are consolidating procurement authority into regional cooperative buying groups, displacing fragmented distributor purchasing. These aggregators are standardizing returnable plastic crate and reusable container specifications to reduce single-use corrugated spend. The consolidation is most visible in the Northeast dairy corridor and Pacific Northwest artisan bread distribution, where independent processors now pool volume to negotiate packaging-as-a-service contracts with pooling system operators.
North America Food Packaging Market Segmentation
Food packaging procurement decisions in North America diverge sharply between commodity volume plays and specification-driven premium formats. Understanding where customization ends and standardization begins within each segment category enables suppliers to align capacity investments with actual buyer willingness to pay for performance differentiation.
Product Type:
Standardization dominates at the commodity end of this spectrum, while flexible and rigid formats command premium engineering margins through tailored barrier specifications.
- Flexible Packaging:Multilayer films combining polyethylene, EVOH, and nylon deliver oxygen transmission rates below 0.5 cc/m²/day for protein applications. Demand concentrates in Midwest frozen vegetable processing plants and Texas beef case-ready operations where lightweighting reduces freight cost per unit. The segment absorbs the majority of resin hedging activity among protein processors.
- Rigid Packaging:Injection-molded PP and thermoformed PET containers withstand retort temperatures and high-pressure processing cycles. Adoption concentrates in California and New York ready-meal manufacturing corridors where shelf differentiation commands retail slotting fee offsets. Extended producer responsibility mandates accelerate mono-material specification shifts.
- Paperboard:SBS and CUK grades with clay-coated surfaces serve organic cereal and premium snack segments requiring direct food contact compliance without plastic windows.
- Glass Containers:Amber and flint glass jars retain dominant share in baby food and premium sauce segments where chemical inertness outweighs weight penalties.
Leading the category by volume: Flexible Packaging. Expanding most quickly: Rigid Packaging.
Material:
Cost tier stratification separates virgin fossil-based resins from emerging bio-based alternatives with performance gaps narrowing through compounding advances.
- Plastic:rPET, HDPE, and PP constitute the procurement baseline across frozen food and dairy applications. FDA food contact notification requirements constrain chemical recycling feedstock qualification timelines. Buyers in the Great Lakes manufacturing corridor prioritize post-consumer content thresholds to meet California SB 54 compliance deadlines.
- Metal:Tinplate and aluminum deliver absolute oxygen and light barriers for shelf-stable protein and vegetable applications. Midwest steel mill concentration creates supply vulnerability during automotive demand surges.
- Paper:Kraft and bleached grades with grease-resistant coatings face immediate reformulation pressure from EPA PFAS enforcement actions.
- Biodegradable Materials:PLA and PHA compounds certified under BPI and CMA standards capture quick-service restaurant demand in California and Canada where single-use plastics prohibitions take earliest effect.
Highest volume share: Plastic. Steepest expansion trajectory: Biodegradable Materials.
End User:
Customer type determines specification authority concentration, with national brand owners driving standardization and regional processors accepting tailored solutions.
- Food & Beverage:Carbonated soft drink and bottled water producers specify lightweight PET with optimized preform designs. Procurement centralization at Atlanta and Purchase headquarters enables volume-based resin contracting.
- Bakery:High-moisture barrier films and modified atmosphere trays extend artisan bread shelf life in direct-store-delivery networks. Pacific Northwest cooperative buying groups standardize returnable crate specifications to displace corrugated.
- Dairy:Fluid milk gallon HDPE and yogurt cup PP face margin compression from private-label concentration. Northeast dairy corridor processors pool volume for packaging-as-a-service contracts.
- Snack Foods:Metallized film and high-barrier pouches protect oxidative stability in nut and chip segments where shelf life directly determines distribution radius.
Dominant procurement volume: Food & Beverage. Gaining share fastest: Snack Foods.
Packaging Type:
Application mechanics dictate format selection, with hand-held consumption favoring flexible formats and shelf-stable storage requiring structural rigidity.
- Wraps:Flow-wrap and overwrap films with heat-sealable layers serve single-serve bakery and confectionery items. Quick-service restaurant standardization programs drive specification consolidation.
- Bags:Stand-up pouches with resealable zipper features displace rigid canisters in granola and dried fruit segments. Vertical form-fill-seal equipment retrofits enable gauge reduction and mono-material transitions.
- Bottles:PET and HDPE containers with barrier multilayer constructions address juice and ready-to-drink tea oxygen sensitivity. Blow molding capacity clusters near Atlanta and Los Angeles distribution hubs.
- Trays:CPET and PP thermoformed bases with lidding film combinations dominate refrigerated and frozen ready-meal segments. High-pressure processing compatibility creates specification premiums.
Highest unit volume: Bags. Climbing the fastest: Trays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene and propylene feedstock availability from Gulf Coast petrochemical complexes anchors packaging resin supply across the continent. FDA food contact notification requirements and EPA PFAS enforcement create divergent compliance timelines by jurisdiction. Manufacturing gravity concentrates in three national corridors with distinct regulatory exposure profiles.
United States
Quick-service restaurant chains and retail grocers drive specification authority for fiber-based clamshells and high-barrier films. California's SB 54 mandates 30% post-consumer recycled content by 2028, pulling investment into rPET extrusion capacity. The Great Lakes manufacturing corridor hosts Midwestern frozen vegetable processing plants and beef case-ready operations where lightweighting reduces freight cost per unit.
Canada
Federal single-use plastics prohibitions on checkout bags, cutlery, and stirrers accelerate demand for certified compostable alternatives. Health Canada enforces Safe Food for Canadians Regulations governing packaging material safety declarations. Ontario's packaging hub near Toronto concentrates thermoforming and fiber molding equipment serving cross-border retail distribution.
Mexico
Duty-advantaged export platforms in Querétaro and Guanajuato attract US retail and foodservice buyers seeking to de-risk Asia-Pacific supply chains. Mexico's proximity to Texas petrochemical infrastructure enables resin cost advantages for multilayer film converters. The Bajío Region packaging clusters specialize in vertical form-fill-seal equipment serving snack and frozen food segments.
North America Food Packaging Market Key Industry Players
Capacity expansion dominates the current landscape as converters retrofit legacy lines for mono-material and recyclable structures. The vendor base separates into integrated multinational suppliers with captive resin sourcing, regional specialists with equipment integration capabilities, and niche compounders of bio-based barrier coatings. Tiered competitive positioning reflects capital intensity differences between commodity film extrusion and specification-driven rigid formats. M&A activity and strategic partnerships concentrate around chemical recycling feedstock qualification and smart packaging technology licensing.
Within the integrated multinational tier, Amcor plc and Silgan Holdings exemplify scale-driven supply security through continental manufacturing footprints. Sealed Air Corporation occupies a position among automation-focused specialists deploying systems at protein processing plants. These three entities represent divergent strategic archetypes: resin-integrated film supply, captive metal sourcing for shelf-stable formats, and equipment-integrated packaging systems respectively.
| Leading Market Players |
|---|
| Silgan Holdings |
| Sealed Air Corporation |
| Amcor plc |
| Sonoco Products Company |
| Pactiv Evergreen |
| Crown Holdings |
| WestRock Company |
| Graphic Packaging International |
| Ball Corporation |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between FDA-compliant barrier films and uncertified commodity alternatives manifests in both pricing premiums and supply chain fragmentation across the North American food packaging landscape. California's SB 54 post-consumer recycled content mandates create a two-tier procurement environment where compliant suppliers command price premiums while legacy converters face margin compression from reformulation costs.
Pricing Analysis
Service-bundling separates packaging-as-a-service contracts from transactional spot purchases. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, with FDA food contact notification tiers and BPI compostable certifications commanding 15-25% premiums. Cost compression in commodity flexible films is intensifying because resin hedging costs have risen with Gulf Coast petrochemical volatility. Quick-service restaurant chains exhibit highest price sensitivity due to standardized national contracts, while premium ready-meal manufacturers show lowest sensitivity given shelf differentiation value.
Supply Chain Analysis
Single-source vulnerability sits with Midwest steel mills supplying tinplate for food cans, where automotive demand surges absorb rolling capacity. Raw material flows draw from Texas Gulf Coast ethylene crackers, Ontario resin compounding facilities, and Quebec aluminum smelters. Feedstock price volatility constitutes the dominant structural risk, with propylene and ethylene swings tied to petrochemical capacity utilization. Distribution runs through regional cooperative buying groups consolidating procurement authority for dairy and bakery processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American food packaging functions as a cost-of-compliance market where California's SB 54 and EPA PFAS enforcement create regulatory moats favoring early movers in certified recyclable and bio-based substrates.
For Market Incumbents: Deepen backward integration into rPET chemical recycling feedstock to secure California-compliant resin supply before qualification backlogs extend. Expand thermoforming capacity in Ontario's packaging hub to capture cross-border retail demand. Silgan Holdings' captive steel sourcing model demonstrates how upstream control insulates against Midwest mill concentration risk. For New Entrants and Emerging Players: Regional dairy cooperative buying groups represent an underserved buyer archetype seeking packaging-as-a-service alternatives to fragmented distributor purchasing. Mexico's Querétaro corridor offers duty-advantaged export platforms for US foodservice buyers de-risking Asia-Pacific supply chains. Lead with certified compostable PLA compounds targeting Canada's single-use plastics prohibition deadlines. For Investors and Strategic Acquirers: Re-rating potential sits with automated packaging systems specialists given quick-service restaurant standardization programs driving equipment-integrated solutions. Chemical recycling feedstock qualification capabilities constitute the acquisition target archetype with 5-10 year viability as FDA notification timelines stretch. Monitor EPA PFAS enforcement acceleration as inflection signal for barrier coating reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Chemical Recycling | Secures California SB 54 compliant feedstock before FDA qualification bottlenecks intensify. |
| Automated Case-Ready Packaging Deployment | Sealed Air Corporation's protein plant installations demonstrate equipment-integrated margin capture. |
| Compostable Barrier Coating Qualification | BPI and CMA certification opens California and Canada single-use plastics prohibition markets. |
| Mexico Nearshoring Capacity Expansion | Querétaro and Guanajuato clusters offer duty-advantaged export platforms for US retail buyers. |
| Smart Packaging Convergence Investment | NFC-enabled traceability integration creates premium positioning for club retail protein channels. |
Research Approach
Document review covered FDA food contact substance notifications, EPA TSCA Section 6 enforcement records, and California SB 54 implementation guidance, complemented by interviews with resin procurement managers at protein processors, thermoforming equipment operators in Ontario, and quick-service restaurant supply chain directors. Secondary validation drew from SEC 10-K filings of integrated packaging suppliers, American Chemistry Council resin production data, and Health Canada Safe Food for Canadians Regulations compliance databases. Bottom-up volume modeling across material-grade segments triangulated with top-down market sizing from trade flow analysis.
Historical capacity utilization patterns were cross-referenced against executive panel input regarding capital allocation timelines across the projection horizon. Segmentation dimensions modeled include material substrate, packaging format rigidity, end-use application, and regulatory compliance tier. CAGRs were derived from elasticity-adjusted demand projections incorporating resin price volatility assumptions and EPR mandate implementation schedules. Industry-specific inputs encompassed high-pressure processing adoption curves and mono-material specification shift velocities.
Revisions become necessary when EPA PFAS enforcement timelines accelerate, FDA food contact notification backlogs extend beyond current 18-24 month windows, or Gulf Coast petrochemical capacity disruptions materialize. Forecasts reflect documented assumptions regarding state-level EPR adoption rates and chemical recycling commercialization trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Food Green Packaging Market
Food Packaging
Food Punnets Market
Food Packaging
Food Partition Trays Market
Food Packaging
Meat, Poultry, and Seafood Packaging Market
Food Packaging
Seafood Packaging Market
Food Packaging
Chocolate Bar Packaging Market
Food Packaging
Middle East and Africa Canned Food Packaging Market
Food Packaging
Flexible Frozen Food Packaging Market
Food Packaging
Edible Oil Packaging Market
Food Packaging
Insulated Food and Beverage Carriers Market
Food Packaging
Ready Meals Packaging Market
Food Packaging
Food Tub Packaging Market
Food Packaging
Europe Canned Food Packaging Market
Food Packaging
India Food and Beverage Packaging Market
Food Packaging
Self-Heating Food Packaging Market
Food Packaging
Poultry Packaging Market