
 Food Green Packaging Market | 2026-2036
Food Green Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Food Green Packaging Market Analysis
Fresh produce distribution is restructuring food green packaging procurement priorities as retailers demand shelf-life extension without synthetic barriers. Mondi Group anchors European kraft paper supply through integrated pulp-to-package operations. Sealed Air Corporation differentiates via active packaging films that reduce perishable spoilage. Amcor plc dominates flexible bioplastic formats for protein and dairy segments.
Food green packaging encompasses materials and formats engineered to minimize environmental impact across extraction, use, and end-of-life phases, typically incorporating bio-based polymers, recycled fiber content above 60%, or compostable films meeting ASTM D6400 or EN 13432 degradation thresholds. Its primary purpose centers on containing and protecting food products while eliminating fossil-derived inputs and enabling circular recovery streams. Paperboard formats lead in volume across dry grocery applications where moisture sensitivity remains low. Bioplastics represent the fastest-expanding material pool as enzymatic recycling infrastructure matures in select European markets. Flexible packaging captures concentrated margin pools in premium snack and convenience food channels where barrier performance commands price premiums.
EU Green Deal packaging regulations, EFSA food contact material standards, and REACH chemical compliance frameworks collectively mandate migration limits, recyclability labeling, and recycled content minimums that reshape formulation roadmaps across the value chain. FDA food contact notification requirements in the United States impose parallel safety validation burdens for bio-based barrier coatings seeking market entry. Stakeholders must monitor evolving extended producer responsibility fee structures and infrastructure investment timelines to align capacity decisions with collection and sorting realities.
Market Dynamics
EU Green Deal packaging regulations are compressing formulation timelines as manufacturers race to substitute fossil-derived barriers with bio-based alternatives before compliance deadlines crystallize.
Growth Catalysts
- EU Green Deal packaging rules:Mandatory recyclability targets and recycled content minimums are forcing format redesigns across ready-meal and fresh produce categories, accelerating demand for compostable films and molded fiber trays.
- Enzymatic recycling infrastructure:Select European markets are deploying industrial-scale enzymatic depolymerization for PLA and PHA streams, enabling closed-loop recovery for food-contact bioplastics previously landfilled or incinerated.
- Quick-service restaurant procurement:Major chains in Germany and France are executing multi-year compostable container rollout programs, converting procurement specifications to mandate ASTM D6400 or EN 13432 certification for all single-use items.
Market Restraints
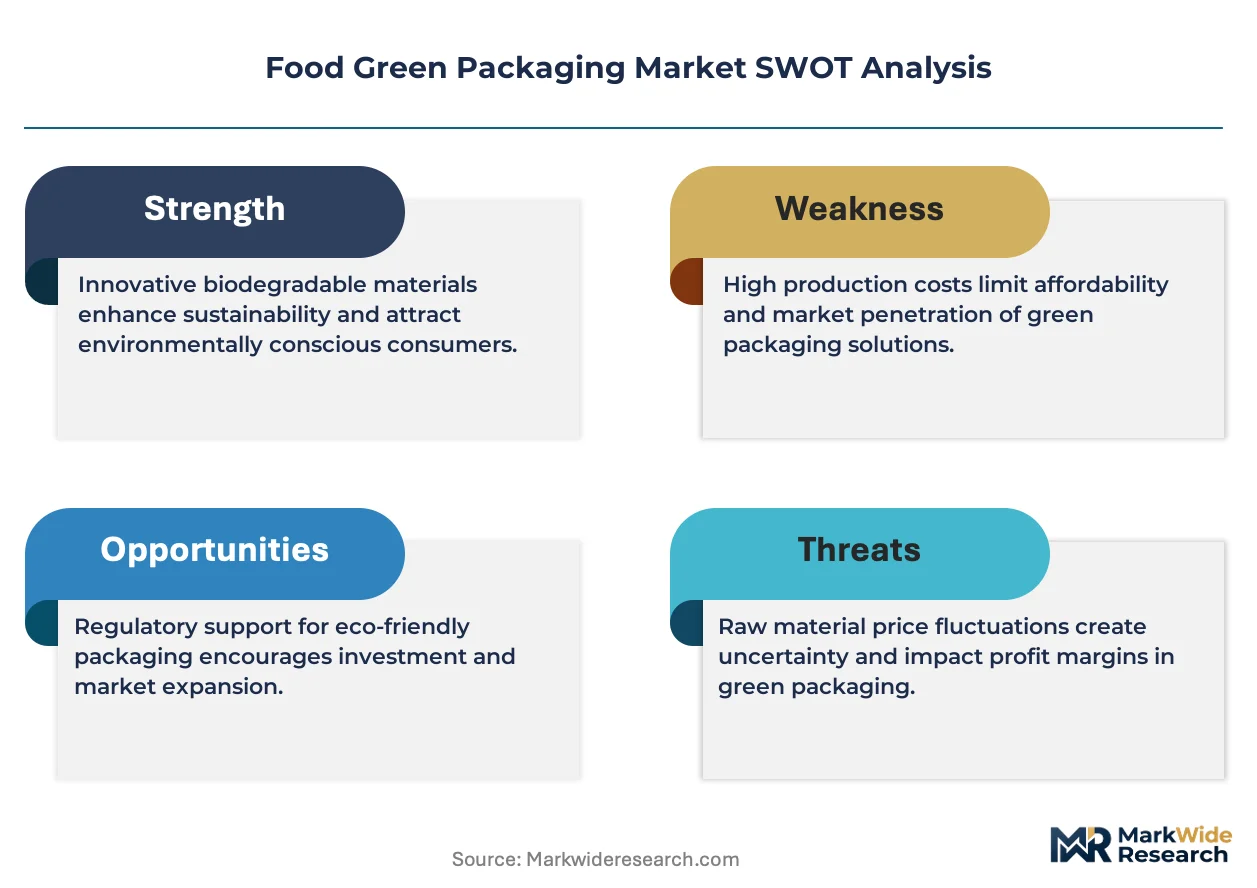
- Wood pulp cost volatility:Kraft paper and molded fiber input costs fluctuate with Nordic pulp contract pricing, squeezing margins for converters lacking long-term supply agreements or captive pulp access.
- Barrier performance gaps:Bio-based coatings for oxygen and moisture resistance still underperform synthetic EVOH and PVDC layers in high-fat protein applications, limiting format substitution in premium meat and cheese segments.
- Composting infrastructure asymmetry:Industrial composting facility coverage remains concentrated in Northern France, the Netherlands, and Belgium, leaving Southern and Eastern European markets without viable end-of-life pathways for certified compostable packaging.
Strategic Opportunities
- Active packaging convergence:Integration of oxygen scavengers and moisture regulators into bio-based films is creating shelf-life extension products for minimally processed produce, opening premium pricing tiers in German and Dutch retail.
- Extended producer responsibility expansion:France's Citeo fee modulation scheme and Italy's CONAI eco-modulation are penalizing non-recyclable formats while rewarding fiber-based alternatives, redirecting investment toward paper-dominant material platforms.
- Direct-to-consumer subscription channels:Meal-kit operators in the UK and Germany are specifying custom-fit molded fiber insulation and chilled packaging, bypassing conventional retail distribution and capturing higher margin per unit through format optimization.
Industry Challenges
- Food contact notification timelines:EFSA safety assessments for novel bio-based barrier coatings currently span 18-24 months, delaying product launches and requiring parallel regulatory submissions across multiple member states.
- Legacy equipment retrofit costs:Converting existing form-fill-seal lines to handle heat-sensitive bioplastic films demands temperature control upgrades and tooling modifications that strain mid-cap converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Green Packaging Market |
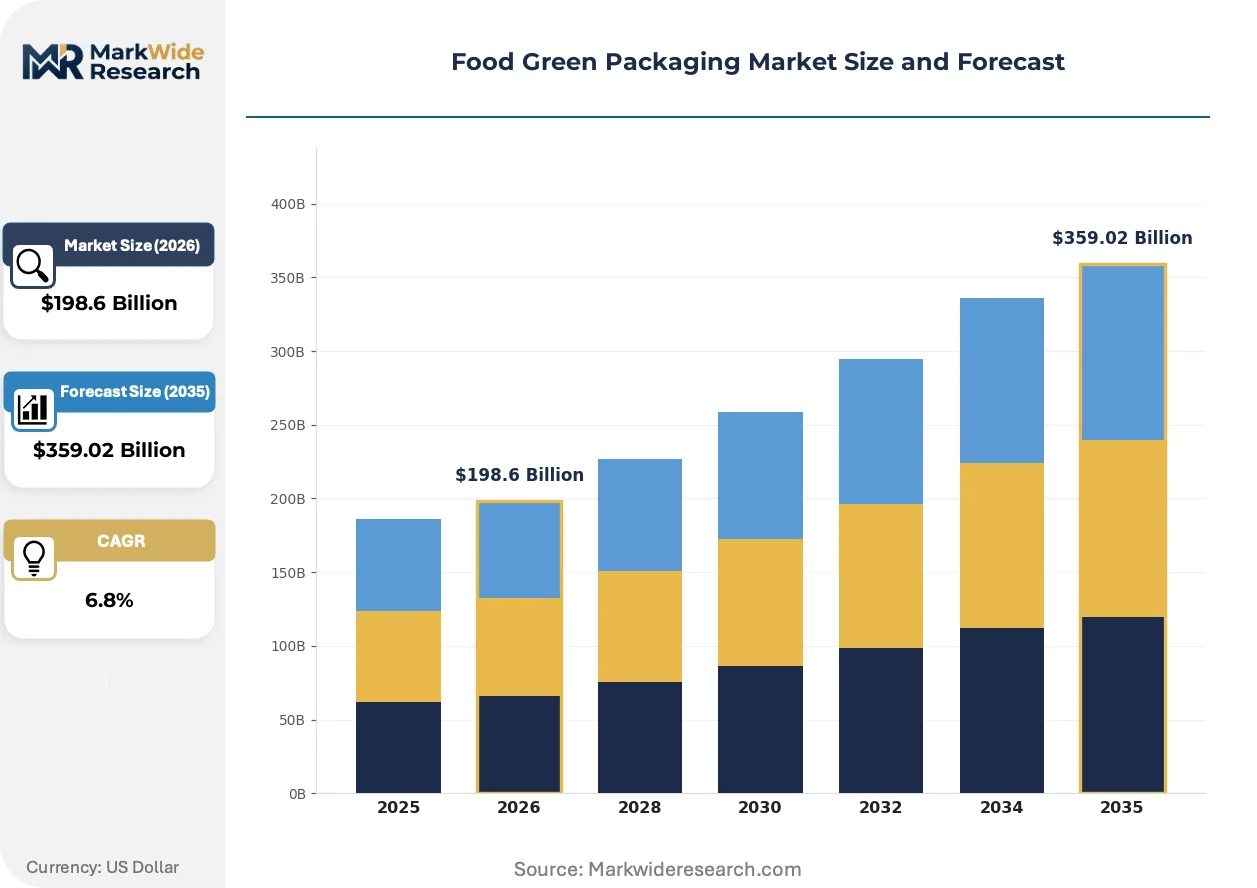
| Market Size in 2026 | $198.6 Billion |
| Market Size in 2035 | $359.02 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Bioplastics, Paperboard, Recycled Paper, Plant-based Films Packaging Format: Flexible Packaging, Rigid Packaging, Stand-up Pouches, Containers Application: Beverages, Snacks, Fresh Produce, Dairy Products End User: Food Manufacturers, Retailers, Restaurants, Catering Services |
| Companies Covered | Amcor plc, Mondi Group, International Paper, Sealed Air Corporation, Berry Global Inc., Ball Corporation, Tetra Pak, DS Smith, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Green Packaging Market Emerging Trajectories
Material science breakthroughs are dissolving the traditional trade-off between barrier performance and end-of-life circularity, enabling formats that satisfy both food safety imperatives and regulatory compostability mandates.
Cellulose nanofiber reinforcement is converging with conventional kraft paper substrates to produce thermoformed trays and lids with grease resistance matching fluorochemical-treated alternatives. German bakery chains and French charcuterie processors are piloting these formats for ambient and chilled distribution. The technology is converging with existing paperboard converting infrastructure, allowing mills to defend position against bioplastic substitution without capital-intensive equipment replacement.
REACH chemical compliance frameworks are tightening migration limits for per- and polyfluoroalkyl substances in food contact materials, triggering a wholesale phase-out of greaseproof fluorochemical treatments by 2026. Paperboard converters are accelerating investment in bio-based sizing agents and plasma surface treatments to maintain functionality. Ready-to-eat sandwich and fried snack categories face the most acute reformulation pressure, with UK and Irish suppliers already executing specification changes to maintain EU market access.
Retail sustainability scorecards are consolidating supplier qualification criteria across German grocery chains, compressing vendor selection into binary pass-fail decisions based on packaging circularity metrics. Fresh produce distributors are responding by pre-certifying entire packaging portfolios to EN 13432 or home-compostable OK Compost HOME standards, eliminating negotiation friction at the procurement stage. This pattern is most visible in the Berlin-Brandenburg logistics corridor, where centralized distribution centers enforce uniform compliance thresholds for all inbound supplier shipments.
Food Green Packaging Market Segmentation
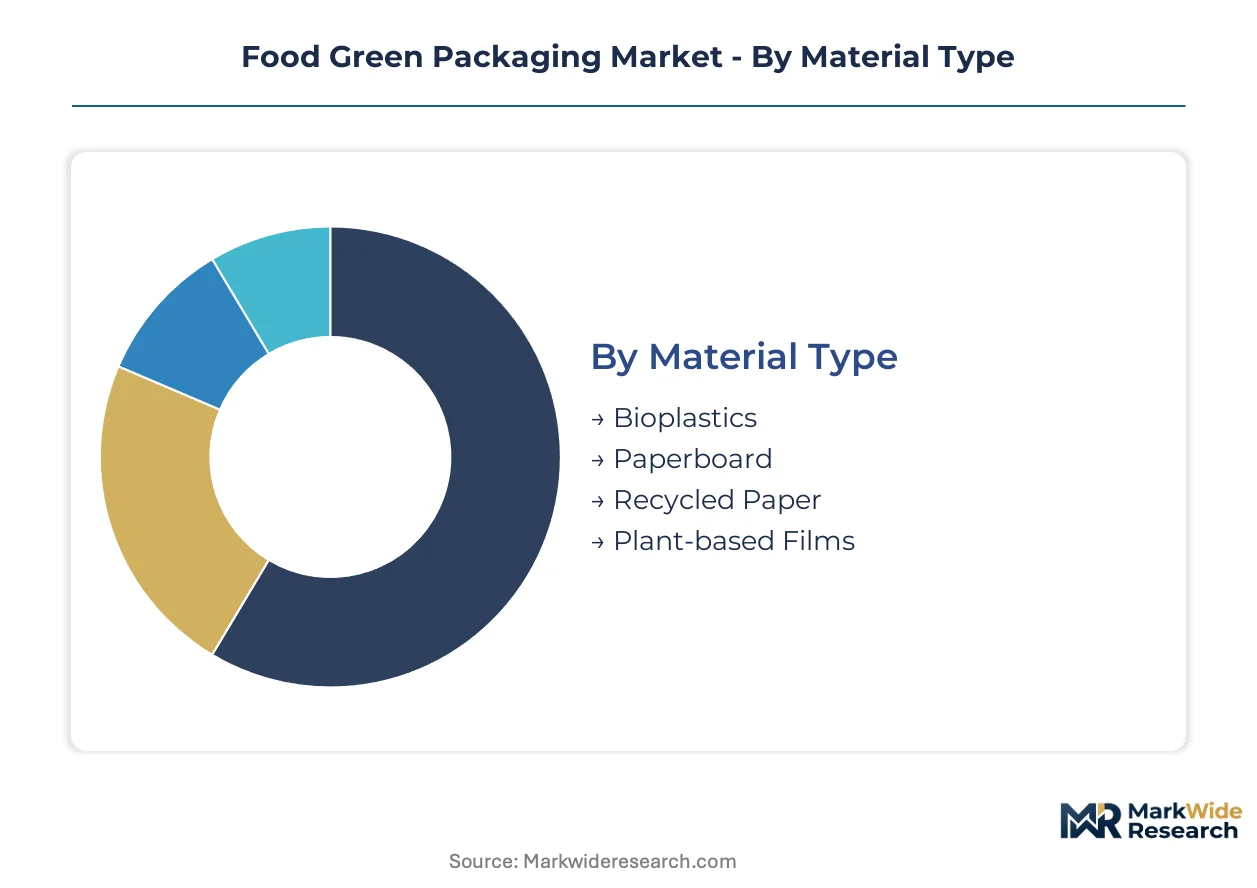
Food green packaging procurement splits across material chemistry, structural format, and channel application, with each axis commanding distinct specification regimes and compliance burdens. Suppliers must map capabilities against these dimensions to qualify for retailer scorecards and food manufacturer supplier lists.
Material Type:
Upgrade cycles in material platforms are accelerating as EU Green Deal deadlines force substitution of fossil-derived barriers with certified alternatives.
- Bioplastics:Polylactic acid and polyhydroxyalkanoate formulations deliver thermoplastic processability with ASTM D6400 or EN 13432 end-of-life certification. Demand concentrates in German quick-service restaurant chains executing compostable container rollouts under tightening EFSA food contact material standards.
- Paperboard:Virgin and recycled fiber substrates above 60% post-consumer content dominate dry grocery applications with low moisture sensitivity. Nordic pulp contract pricing volatility squeezes converter margins, driving long-term supply agreement negotiations with integrated mills.
- Recycled Paper:Post-industrial and post-consumer fiber streams require de-inking and strength retention treatments to meet food contact migration limits under REACH frameworks.
- Plant-based Films:Cellulose and starch-derived transparent barriers substitute conventional petroleum films in produce overwrap and bakery windows.
Paperboard sits at the top of the volume ranking, with bioplastics climbing the fastest as enzymatic recycling infrastructure matures in France and the Netherlands.
Packaging Format:
Format selection tracks directly to barrier performance requirements and existing converting equipment capabilities across European converter bases.
- Flexible Packaging:Rollstock and pre-made pouch formats capture premium snack and convenience food channels where oxygen and moisture barriers command price premiums. Amcor plc and Sealed Air Corporation anchor supply for protein and dairy segments.
- Rigid Packaging:Thermoformed trays, clamshells, and injection-molded containers serve ready-meal and fresh produce categories with structural protection needs. Mondi Group's integrated pulp-to-package operations defend kraft paper-based rigid formats against bioplastic substitution.
- Stand-up Pouches:Doyen and gusseted configurations with reseal features expand in ambient sauce and dried fruit segments.
- Containers:Lidded tubs and bowls target chilled prepared foods requiring microwave compatibility and freezer stability.
Flexible packaging captures the steepest margin expansion trajectory, while rigid formats retain volume leadership in produce distribution.
Application:
Application-driven specification divergence reflects spoilage risk profiles and retail display requirements across ambient, chilled, and frozen supply chains.
- Fresh Produce:Modified atmosphere and breathable films extend shelf life for minimally processed vegetables and fruits. German retail chains enforce sustainability scorecards that pre-certify supplier packaging to EN 13432 or OK Compost HOME standards.
- Beverages:Aseptic cartons, bottles, and pouch formats face migration limit compliance under EFSA and FDA food contact notification requirements for bio-based barrier coatings.
- Snacks:High-fat content demands grease resistance without per- and polyfluoroalkyl substances as REACH frameworks phase out fluorochemical treatments.
- Dairy Products:Oxygen scavenger integration and light-blocking layers protect fermented and fresh cheese categories with premium positioning.
Fresh produce leads application segment volume, with beverages gaining share fastest as bottled water and plant-based milk alternatives convert to bio-based formats.
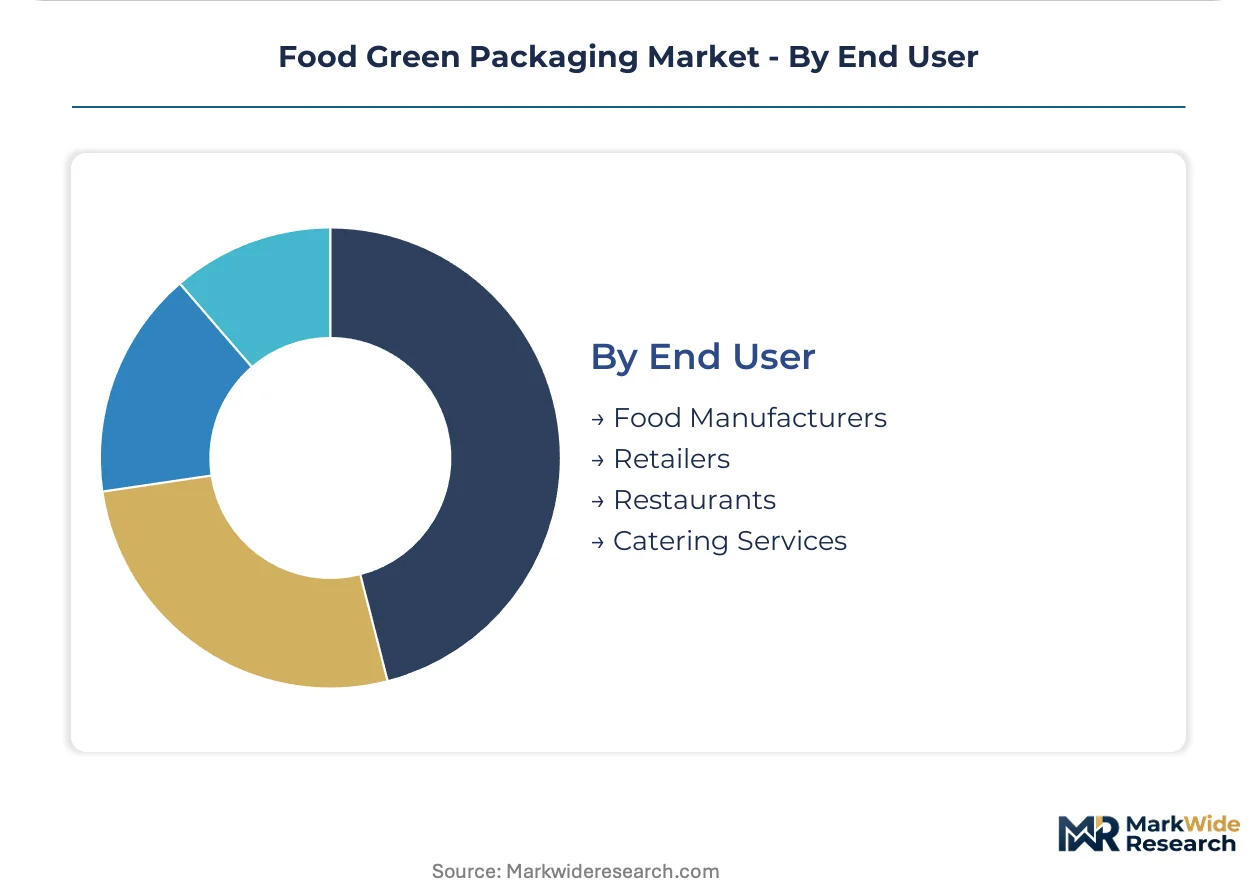
End User:
End-user procurement patterns split between specification-heavy retail channels and volume-driven food service operations with diverging compliance timelines.
- Retailers:Centralized distribution networks in Germany, France, and the Netherlands mandate uniform packaging circularity metrics across supplier bases. Berlin-Brandenburg logistics corridors enforce binary pass-fail qualification on inbound shipments.
- Food Manufacturers:Branded and private-label producers balance EFSA safety assessment timelines against product launch windows for novel bio-based barrier coatings.
- Restaurants:Quick-service chains in France execute multi-year compostable container programs converting procurement specifications to mandate ASTM D6400 or EN 13432 certification.
- Catering Services:Event and institutional food service operators prioritize cost-controlled molded fiber and paperboard disposables with industrial composting disposal pathways.
Retailers command the largest procurement volume, with restaurants expanding most quickly as EU Green Deal packaging rules tighten single-use item compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate converting capacity toward jurisdictions with mature composting infrastructure and harmonized EFSA compliance pathways.
Germany
Retail sustainability scorecards now enforce binary pass-fail supplier qualification across Berlin-Brandenburg distribution corridors. EU Green Deal packaging rules mandate recycled content minimums that accelerate kraft paper and molded fiber procurement. The Rhine-Ruhr industrial cluster hosts integrated pulp-to-package operations defending market position against bioplastic substitution.
France
Quick-service restaurant chains execute multi-year compostable container rollouts mandating ASTM D6400 or EN 13432 certification. Citeo fee modulation schemes penalize non-recyclable formats while rewarding fiber-based alternatives. Northern France industrial composting facility concentration enables viable end-of-life pathways unavailable in Southern regions.
Netherlands
Enzymatic recycling infrastructure deployment for PLA and PHA streams enables closed-loop recovery previously landfilled or incinerated. REACH chemical compliance frameworks tighten migration limits for per- and polyfluoroalkyl substances in food contact materials. The Rotterdam-Antwerp port corridor concentrates bioplastic resin import and converting activity.
United States
FDA food contact notification requirements impose parallel safety validation burdens for bio-based barrier coatings seeking market entry. California and New York state-level extended producer responsibility legislation precedes federal action. The Midwest paperboard manufacturing belt leverages captive pulp supply to offset Nordic contract pricing volatility.
China
Dual carbon goals and GB standards for food contact materials accelerate domestic bioplastic capacity expansion. SAMR enforcement of migration limits creates compliance barriers for imported barrier coatings. The Yangtze River Delta packaging converting cluster scales cellulose nanofiber reinforcement trials for grease-resistant paperboard formats.
Food Green Packaging Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pulp-to-package operators commanding volume leadership in paperboard while flexible film converters capture premium pricing in protein and dairy channels. The vendor base organizes around three strategic archetypes: integrated fiber-based specialists with captive pulp access, diversified material science conglomerates spanning multiple packaging substrates, and pure-play bioplastic innovators dependent on enzymatic recycling infrastructure maturation. Dominant competitive moves include backward integration into raw fiber supply and strategic partnerships with quick-service restaurant chains for multi-year compostable container procurement programs.
Among diversified packaging conglomerates, Amcor plc and Mondi Group occupy positions exemplifying scale-driven material platform breadth, while Sealed Air Corporation represents the active packaging convergence archetype integrating shelf-life extension technologies into bio-based film structures. These three entities anchor competitive positioning across the flexible-rigid format divide without reliance on speculative technology licensing or unproven bioplastic resin supply agreements.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi Group |
| International Paper |
| Sealed Air Corporation |
| Berry Global Inc. |
| Ball Corporation |
| Tetra Pak |
| DS Smith |
| DuPont |
| Others |
Supply Flow & Price Mechanics
German quick-service restaurant procurement concentration anchors contract-based long-term offtake pricing for compostable containers, with volume scale and EN 13432 certification grade driving tiered spreads between integrated mills and spot-market converters.
Pricing Analysis
Distributor margins compress as Nordic pulp contract pricing volatility feeds through kraft paper and molded fiber formats, while direct-to-retailer agreements for certified bioplastic films capture premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates captive-pulp integrated suppliers from merchant converters and import-dependent traders. Cost compression in standard-grade paperboard intensifies because wood pulp input fluctuations squeeze mid-cap balance sheets. Quick-service chains exhibit highest price sensitivity due to procurement volume scale, while premium dairy and protein packers absorb markups for active packaging integration.
Supply Chain Analysis
Workforce availability constraints in German and French converting corridors are redirecting molded fiber thermoforming investment toward automated lines, even as Nordic pulp mill labor pools tighten. Geographic supply concentration centers on Germany, France, and the Netherlands, with bioplastic resin flows through the Rotterdam-Antwerp corridor. Raw material dependencies rest on Nordic softwood pulp, PLA/PHA resin streams, and bio-based barrier coating formulations. Single-source vulnerability in enzymatic recycling infrastructure creates bottleneck risk for closed-loop PLA recovery. Distribution runs through centralized retail distribution centers in Berlin-Brandenburg and Paris-region logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where fresh produce shelf-life extension specifications are displacing commodity barrier formats across German retail scorecards.
For Market Incumbents: To counter bioplastic substitution threats in rigid formats, Mondi Group and integrated pulp-to-package operators should deepen captive fiber supply control through long-term Nordic softwood agreements, while accelerating cellulose nanofiber reinforcement R&D to defend kraft paper position against PLA tray incursion in chilled ready-meal channels. For New Entrants and Emerging Players: Launch via direct-to-consumer meal-kit subscription channels specifying custom-fit molded fiber insulation, bypassing retail distribution gatekeepers and capturing format-optimization premiums in UK and German urban corridors where sustainability scorecard compliance remains uneven. For Investors and Strategic Acquirers: Packaging conglomerates with active packaging capabilities are the most active acquirer in this space, targeting mid-cap bioplastic film specialists with FDA food contact notification clearances. Long-term viability hinges on enzymatic recycling infrastructure maturation timelines. The signal to watch is Citeo and CONAI eco-modulation penalty expansion beyond France and Italy into German federal frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive Nordic softwood access insulates margins from contract pricing volatility squeezing merchant converters. |
| Active Packaging Convergence | Oxygen scavenger integration into bio-based films opens premium pricing tiers in German and Dutch retail produce segments. |
| Enzymatic Recycling Partnership | PLA closed-loop recovery agreements with Netherlands infrastructure operators secure end-of-life compliance for quick-service procurement. |
| Direct-to-Consumer Format Optimization | Custom molded fiber insulation for meal-kit channels bypasses retail scorecard friction and captures higher margin per unit. |
| REACH Fluorochemical Phase-Out Compliance | Bio-based greaseproof sizing investment maintains EU market access as per- and polyfluoroalkyl substance bans crystallize. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sustainability procurement leads at German retail chains, quick-service restaurant supply chain directors, EFSA regulatory affairs specialists, and Nordic pulp mill commercial managers with secondary validation from EU Green Deal regulatory filings, Citeo eco-modulation fee schedules, EN 13432 certification databases, and REACH chemical restriction updates. Bottom-up converter capacity assessments and top-down retail procurement spend estimates were triangulated to anchor volume figures.
Segment-weighting approaches distributed value across material type, packaging format, and application dimensions, with bioplastic growth trajectories modeled separately from fiber-based format stability across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating EU Green Deal compliance deadline phasing and quick-service restaurant rollout schedules. Industry-specific forecast inputs included enzymatic recycling infrastructure deployment timelines and EFSA food contact notification clearance backlogs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under composting infrastructure asymmetry persistence or wood pulp cost spike scenarios. Projections reflect documented assumptions regarding regulatory enforcement intensity and enzymatic recycling scale-up cadence. Material deviation in EU Green Deal implementation timelines or Nordic pulp supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Reclosable Food Packaging Market
Food Packaging
Food Can Market
Food Packaging
Burger Boxes Market
Food Packaging
Microwaveable Liquid Food Packaging Market
Food Packaging
Insulated Food and Beverage Carriers Market
Food Packaging
Fast Food Containers Market
Food Packaging
Canada Disposable Tableware Market
Food Packaging
Honey Packaging Market
Food Packaging
Food and Drink Packaging Market
Food Packaging
Egg Packaging Market
Food Packaging
North America PET Food Packaging Market
Food Packaging
PVDC Coating Food Packaging Market
Food Packaging
Asia-Pacific Skin Packaging for Fresh Meat Market
Food Packaging
Hot Drinks Packaging Market
Food Packaging
Cereal Packaging Market
Food Packaging
Europe Food Contract Manufacturing and Packaging Market