
 PET Food Trays Market | 2026-2036
PET Food Trays Market Size, Share, and Industry Trends Forecast 2026-2036
PET Food Trays Market Outlook
Multi-pack bundling of portion-controlled trays is realigning how households purchase wet pet food, shifting volume from single-unit impulse buys toward subscription-friendly configurations. Amcor plc leverages its global flexible packaging footprint to supply laminated barrier films for lidded tray formats. Sealed Air Corporation anchors North American production with thermoformed PET and PP tray lines optimized for retort applications. Silgan Holdings Inc. competes through metal tray expertise, sustaining shelf-stable pet food contracts with major brand owners.
PET food trays are rigid or semi-rigid containers engineered from polyethylene terephthalate, polypropylene, aluminum, or molded pulp, designed to hold single-serve wet, raw, or fresh pet meals with heat-sealed or snap-fit closure systems; they typically incorporate oxygen barrier layers and are manufactured via thermoforming, injection molding, or deep-drawing processes to preserve product integrity through retort, hot-fill, or cold-chain distribution. Plastic trays dominate current volume due to cost efficiency and design flexibility, though biodegradable segments are gaining structural attention as European retailers impose packaging reduction targets. Veterinarian and pet store channels concentrate margin pools through prescription diet and premium brand placement, while online retail expansion redistributes volume toward direct-to-consumer tray subscription models.
FDA food contact substance regulations govern tray material safety in the United States, while EFSA and the EU Packaging and Packaging Waste Regulation shape permissible substrates and recyclability mandates across European markets. REACH compliance and emerging extended producer responsibility frameworks are forcing material substitutions away from non-recyclable multi-layer structures toward mono-material or fiber-based alternatives. Stakeholders must monitor evolving state-level packaging legislation in California and New York, where precedent-setting rules on recycled content minimums could cascade into national sourcing requirements.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing material substitutions across European supply chains, compressing design cycles for mono-material tray formats while retailers accelerate packaging reduction targets ahead of compliance deadlines.
Growth Catalysts
- Pet Humanization:Premium wet food demand in Germany and France sustains above-average investment in portion-controlled tray configurations with enhanced barrier properties.
- REACH Compliance Deadlines:Extended producer responsibility frameworks are redirecting R&D spending toward recyclable mono-material structures, creating first-mover advantages for compliant suppliers.
- Retort Technology:Advanced oxygen barrier films enable shelf-stable pet meals without refrigeration, unlocking distribution expansion into veterinary and prescription diet channels.
Market Restraints
- Aluminum Price Volatility:Raw material swings for metal tray substrates compress margins for shelf-stable product lines during commodity spikes.
- Multi-Layer Technical Limitations:Current laminated barrier films face mechanical recycling exclusion under EU waste directives, forcing premature asset retirement.
- German Retailer Concentration:Discounter and supermarket chain buying power concentrates volume allocation decisions among fewer procurement gatekeepers.
Strategic Opportunities
- Molded Pulp Convergence:Fiber-based tray technology combined with bio-based barrier coatings addresses compostability mandates in Nordic markets.
- Subscription Channel Expansion:Direct-to-consumer bundling of multi-pack configurations bypasses traditional retail slotting fees and builds recurring revenue streams.
- California State Legislation:Precedent-setting recycled content minimums under SB 54 create early compliance templates that may cascade into national sourcing requirements.
Industry Challenges
- Thermoforming Equipment Lead Times:Capital expenditure cycles for retort-compatible PET lines extend 18-24 months, constraining capacity response to demand surges.
- Cross-Border EFSA Variability:Divergent national interpretations of food contact substance approvals create compliance fragmentation across EU member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Food Trays Market |
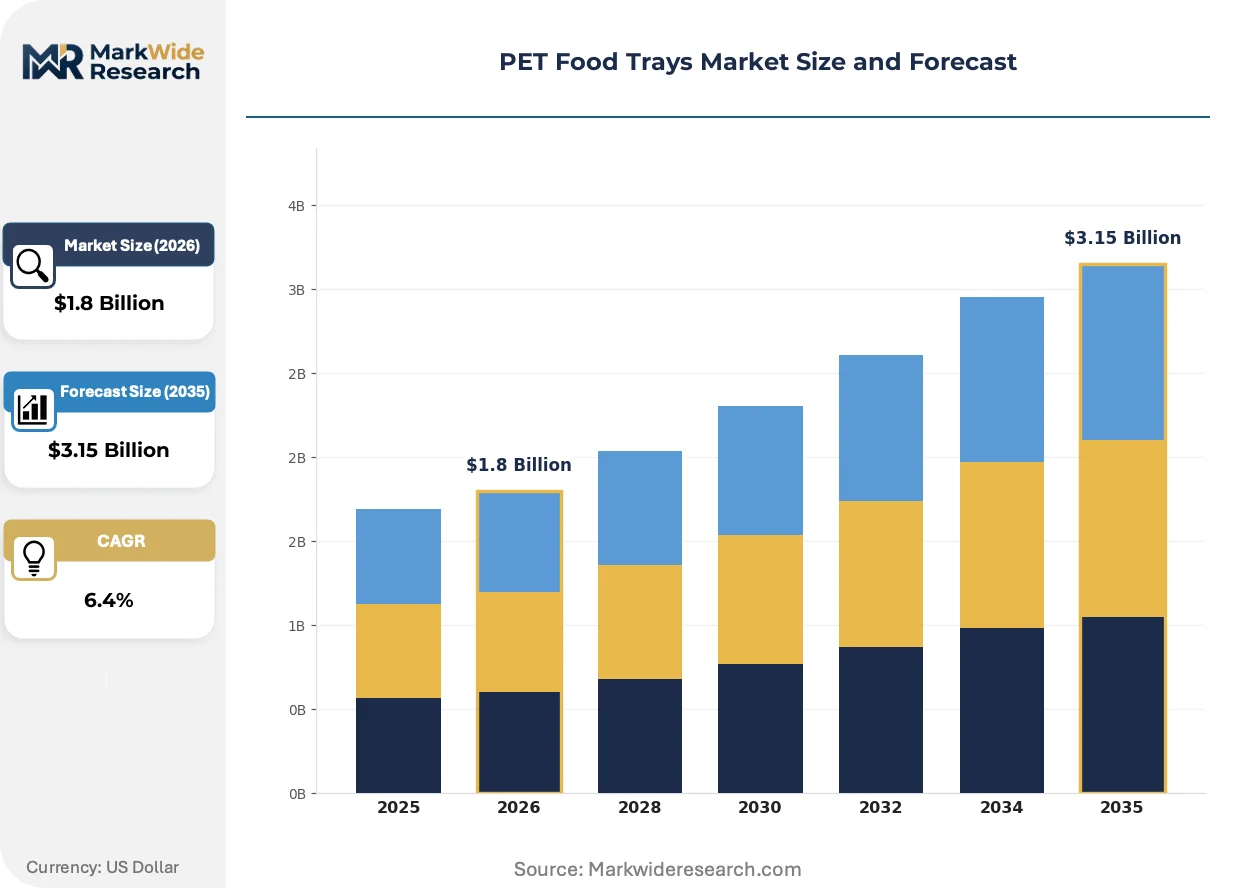
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Biodegradable, Ceramic End User: Pet Owners, Veterinarians, Pet Stores, Animal Shelters Material: Stainless Steel, Melamine, Wood, Silicone Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesalers |
| Companies Covered | Sealed Air Corporation, Amcor plc, Silgan Holdings Inc., Sonoco Products Company, Pactiv LLC, CKF Inc., Easy Pak LLC, Anchor Packaging Inc., Novolex Holdings LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Food Trays Market Strategic Shifts
Material science breakthroughs and regulatory compression are converging to redefine tray construction standards, with sustainability mandates now dictating design parameters rather than retrofitting existing formats.
Mono-material PET trays with integrated oxygen scavenger layers is overtaking multi-layer laminated structures in premium wet food applications. German and French brand owners are specifying these formats for retort lines to preempt Ecodesign for Sustainable Products Regulation compliance. The shift is compressing demand for conventional barrier films and forcing laminate suppliers to pivot toward separable or recyclable alternatives.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated barrier coatings from food contact applications by 2025. The industrial consequence is accelerated qualification of silicon oxide and aluminum oxide vapor-deposited alternatives. Wet pet food manufacturers serving EU markets are reformulating filling temperatures and pH tolerances to accommodate these substitute barrier technologies.
Subscription-based portion planning is consolidating household purchasing into predictable monthly cycles rather than impulse retail acquisition. Direct-to-consumer platforms and veterinary telehealth services are capturing tray volume through auto-ship configurations. This pattern is most visible in US coastal metros and UK urban centers where pet humanization indices correlate with digital service adoption rates.
PET Food Trays Market Segmentation
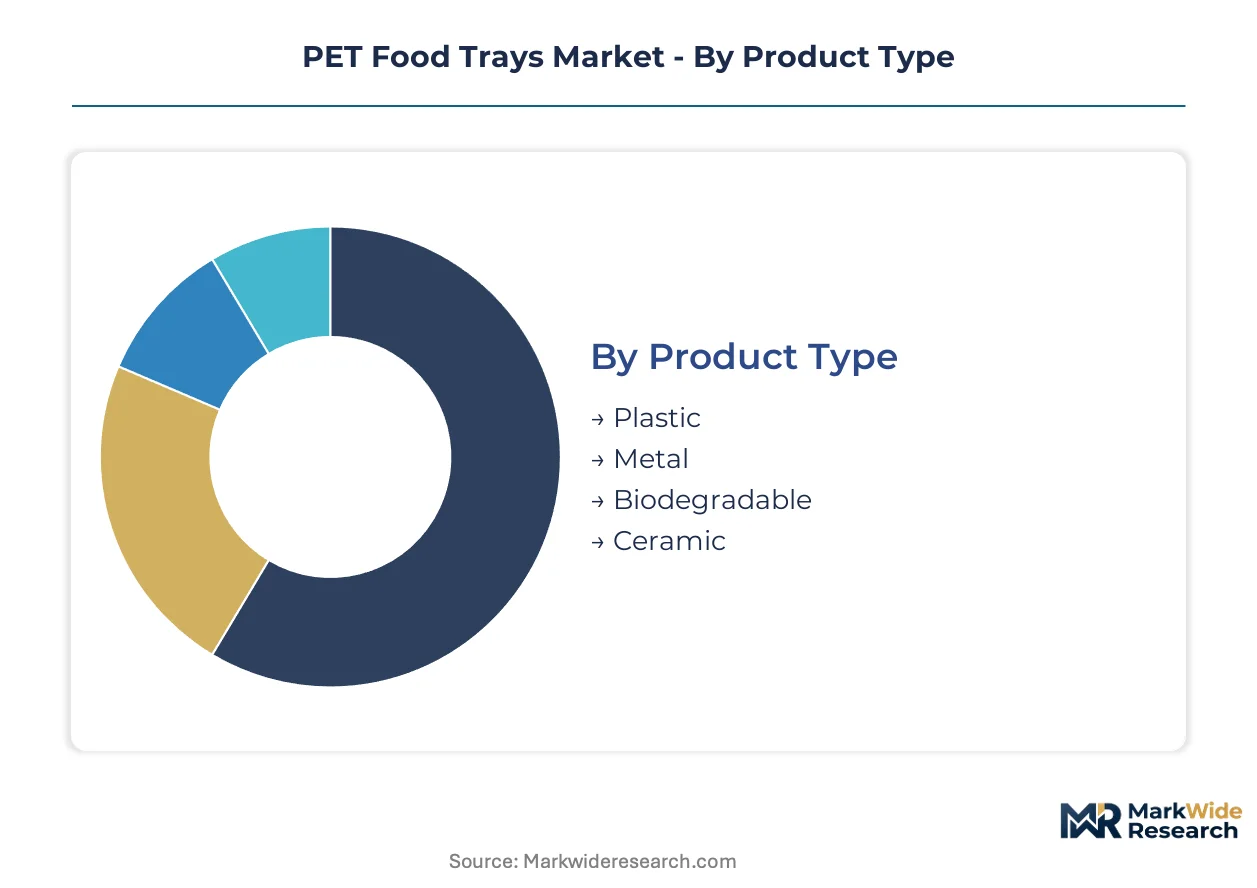
Segmentation in the PET food trays market reveals divergent purchasing logic across material preferences, institutional versus household demand, and channel economics. Understanding these fault lines enables suppliers to align production assets with the highest-margin application clusters.
Product Type:
Buyers differentiate primarily by shelf-life requirements and sustainability positioning, with cost tolerance varying sharply across premium wet food versus mass-market dry food applications.
- Plastic:Thermoformed PET and PP trays dominate volume through retort compatibility and oxygen barrier integration. German retailers specify these formats for premium wet food lines to meet EU Packaging and Packaging Waste Regulation compliance timelines.
- Metal:Aluminum and steel trays anchor shelf-stable segments with superior thermal conductivity for sterilization cycles. Demand concentrates in veterinary prescription channels where extended shelf stability justifies material cost premiums.
- Biodegradable:Molded pulp and PLA variants address Nordic retailer compostability mandates.
- Ceramic:Artisan positioning targets gift and specialty segments with limited volume scale.
Plastic leads volumes today; biodegradable formats are gaining share fastest.
End User:
Procurement authority shifts dramatically between household decision-makers seeking convenience and institutional buyers prioritizing clinical outcomes.
- Pet Owners:Subscription bundling of portion-controlled trays drives recurring purchase patterns in UK and US urban centers. Auto-ship configurations now capture volume formerly routed through impulse retail.
- Veterinarians:Prescription diet placement concentrates margin pools through therapeutic nutrition protocols. FDA food contact substance compliance is non-negotiable for clinic procurement committees.
- Pet Stores:Premium brand slotting fees and exclusive distribution agreements shape assortment decisions.
- Animal Shelters:Bulk purchasing of economy-grade trays operates on municipal contract cycles.
Pet owners generate the largest absolute volume; veterinarians deliver the steepest margin expansion trajectory.
Material:
Surface chemistry and durability specifications determine suitability across feeding environments from household kitchens to clinical boarding facilities.
- Stainless Steel:Non-porous surfaces resist bacterial colonization and withstand industrial dishwasher cycles. German veterinary chains specify medical-grade 304 stainless for prescription diet feeding protocols.
- Melamine:Lightweight shatter resistance suits multi-pet households and travel applications. REACH compliance on formaldehyde migration limits is tightening acceptable supplier pools.
- Wood:Natural aesthetic positioning targets sustainability-conscious buyers in French and Italian markets.
- Silicone:Collapsible designs address space-constrained urban pet owners.
Stainless steel commands premium pricing; silicone is climbing the fastest among emerging material alternatives.
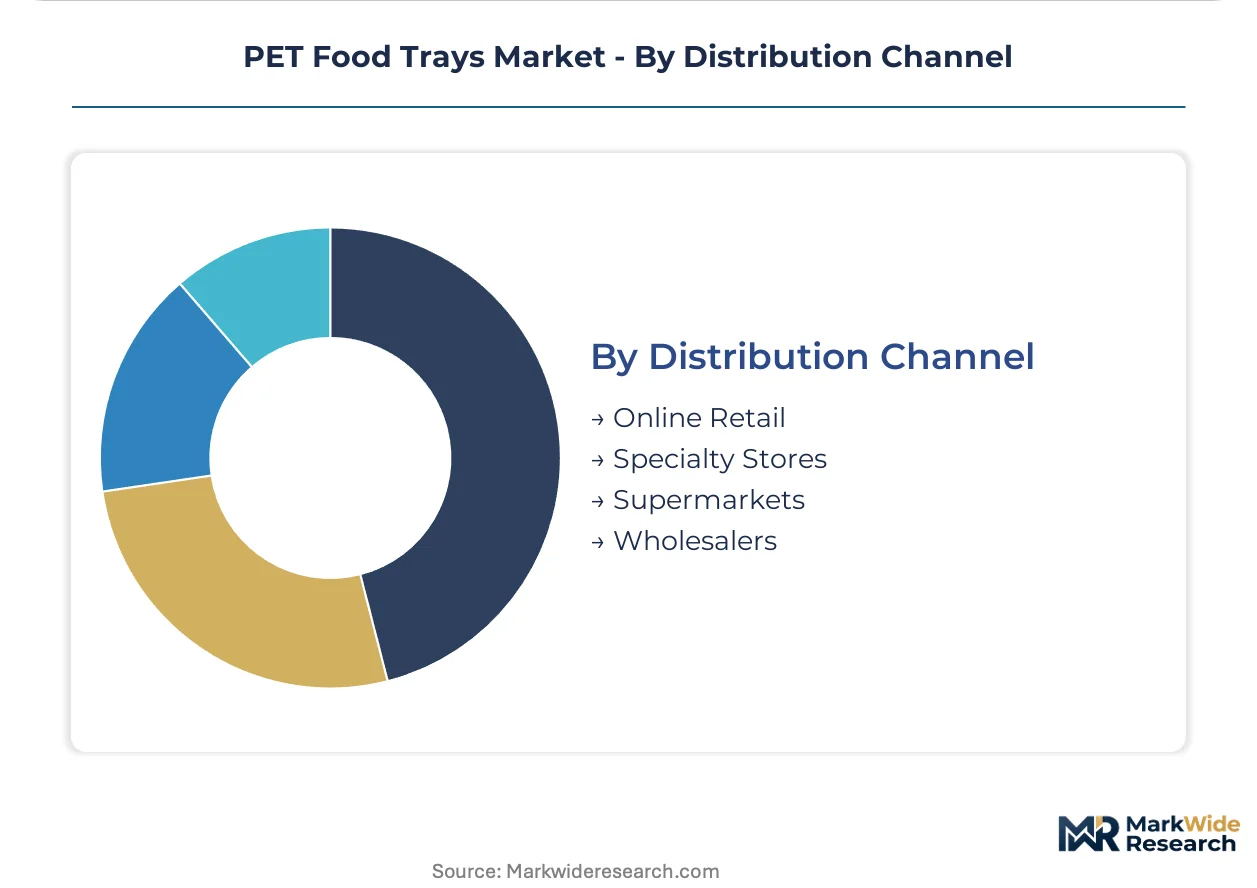
Distribution Channel:
Channel selection reflects trade-off between customer acquisition cost and lifetime value capture, with digital platforms restructuring traditional retail economics.
- Online Retail:Direct-to-consumer platforms bypass slotting fees and capture subscription revenue through auto-ship algorithms. California and New York metro areas show highest digital adoption correlation with pet humanization indices.
- Specialty Stores:Curated assortments and staff expertise sustain premium price realization for therapeutic and raw food formats.
- Supermarkets:Discounter buying power in Germany concentrates volume allocation among fewer procurement gatekeepers.
- Wholesalers:Institutional and shelter supply contracts operate on annual tender cycles with thin margins.
Supermarkets move the most units today; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial-scale thermoforming for pet food packaging during the 1990s, establishing the technical foundations that now define retort-compatible tray standards across Europe and North America.
Germany
Premium wet food demand and pet humanization sustain above-average investment in portion-controlled tray configurations. The EU Packaging and Packaging Waste Regulation compresses design cycles for mono-material formats ahead of compliance deadlines. The Rhine-Ruhr industrial corridor hosts concentrated thermoforming capacity serving major brand owners.
United States
Subscription-based auto-ship models and veterinary telehealth platforms capture tray volume through direct-to-consumer channels. FDA food contact substance regulations govern material safety while California SB 54 establishes recycled content precedents. The Chicago metropolitan area anchors North American production with retort-optimized PET and PP tray lines.
France
Discerning pet owners drive specification of enhanced barrier properties in premium wet food applications. REACH restrictions on per- and polyfluoroalkyl substances eliminate fluorinated coatings by 2025, accelerating silicon oxide alternatives. The Lyon-Grenoble industrial cluster concentrates barrier film qualification and testing infrastructure.
United Kingdom
Urban digital adoption correlates with subscription bundling of multi-pack tray configurations in London and southeast metro areas. Extended producer responsibility frameworks redirect procurement toward recyclable mono-material structures. The Midlands manufacturing belt sustains thermoforming operations optimized for portion-controlled formats.
China
Rising pet ownership in tier-one cities generates demand for shelf-stable wet food packaging with oxygen barrier integration. GB standards and SAMR oversight shape food contact material compliance requirements. The Yangtze River Delta hosts expanding thermoforming capacity serving domestic brand owners and export markets.
PET Food Trays Market Competitive Environment
Premium-margin players sit above commodity-margin players across material science capabilities and retort compatibility certification. The vendor base stratifies into three tiers: integrated packaging conglomerates with global flexible film footprints, specialized tray fabricators with regional thermoforming expertise, and metal packaging specialists serving shelf-stable segments. Two dominant competitive moves are reshaping positioning: accelerated R&D spending on mono-material recyclable structures to preempt EU regulatory deadlines, and backward integration into barrier film production to capture margin pools from laminate suppliers.
Within the integrated packaging tier, Amcor plc and Sealed Air Corporation exemplify scale-driven archetypes with global supply network coverage. Silgan Holdings Inc. anchors the metal packaging specialist position. These three entities represent contrasting strategic postures—flexible film integration, thermoforming equipment optimization, and metal substrate expertise—each capturing distinct margin pools across wet food, prescription diet, and shelf-stable application clusters.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Amcor plc |
| Silgan Holdings Inc. |
| Sonoco Products Company |
| Pactiv LLC |
| CKF Inc. |
| Easy Pak LLC |
| Anchor Packaging Inc. |
| Novolex Holdings LLC |
| Others |
Value Chain & Pricing Dynamics
Aluminum ingot volatility flows through metal tray substrate costs to compress margins for shelf-stable product lines, while PET resin stability supports pricing predictability in thermoformed segments serving German and French premium wet food buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates retort-compatible barrier trays from basic mono-material formats from bulk institutional configurations. Price differentiation rests on oxygen barrier certification grade and volume scale commitments from major brand owners. Cost compression in economy-grade plastic trays is intensifying because supermarket chain buying power concentrates procurement decisions among fewer German gatekeepers. Veterinarian channels show least price sensitivity due to prescription diet reimbursement protocols, while animal shelters operate as most price-sensitive buyers on municipal tender cycles.
Supply Chain Analysis
Regional distribution centers in the Rhine-Ruhr corridor, Chicago metropolitan area, and Yangtze River Delta anchor hub-and-spoke patterns for tray fulfillment. Thermoforming capacity draws from Germany, United States, and China, with barrier film supply anchored in France and Japan. Single-source vulnerability concentrates in specialized oxygen scavenger resin grades qualified for EU food contact. Distribution runs through veterinary telehealth platforms and direct-to-consumer auto-ship algorithms alongside traditional retail wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in mono-material tray conversion as REACH compliance deadlines force material substitutions and first-mover suppliers capture premium pricing from late-adapting competitors.
For Market Incumbents: Hedge against laminate film asset stranding by accelerating R&D spending on separable barrier technologies before EU Packaging and Packaging Waste Regulation enforcement tightens. Backward integration into captive PET resin production secures supply continuity during commodity spikes. Channel control through exclusive veterinary distribution agreements defends margin pools from direct-to-consumer disintermediation. For New Entrants and Emerging Players: Enter via biodegradable molded pulp segments in Nordic markets where retailer compostability mandates outpace incumbent supplier qualification timelines. White-space opportunity concentrates in subscription bundling configurations for UK and US urban pet owners. Go-to-market leverage rests on veterinary telehealth platform partnerships that bypass traditional retail slotting fee structures. For Investors and Strategic Acquirers: Consolidation pressure builds where thermoforming equipment lead times extend eighteen to twenty-four months and capacity scarcity favors integrated packaging conglomerates with existing retort-compatible lines. Long-term viability favors suppliers with mono-material patent portfolios and EFSA pre-approval dossiers. Acquisition target archetype: regional tray fabricators with qualified barrier film relationships and German retailer supply contracts. Signal to watch: California SB 54 recycled content rulemaking that may cascade into national sourcing requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Format Conversion | REACH compliance deadlines in Europe force laminate suppliers to pivot toward recyclable alternatives. |
| Barrier Film Backward Integration | Captive production of oxygen scavenger layers secures margin pools from specialty chemical suppliers. |
| Veterinary Channel Partnership | Prescription diet placement concentrates high-margin volume through therapeutic nutrition protocols. |
| Subscription Platform Launch | Auto-ship algorithms in UK and US metros capture recurring revenue from pet humanization trends. |
| Nordic Compostability Certification | Molded pulp qualification addresses retailer packaging reduction targets ahead of compliance deadlines. |
Study Parameters
Coverage spans Germany, United States, France, United Kingdom, and China, with primary inputs from each market combined with secondary validation across regulatory filings and trade databases. Interviews with thermoforming plant managers, procurement leads at major pet food brand owners, veterinary clinic administrators, and retail category buyers informed demand-side assumptions. Secondary sources include EFSA food contact substance approvals, FDA packaging regulations, EU Packaging and Packaging Waste Regulation drafts, and customs trade data. Bottom-up volume modeling triangulated against top-down market sizing from packaging industry associations.
Rate-of-change decomposition across the analysis window segments growth by material substrate, end-user channel, and distribution format. The analytical framework models product type transitions from multi-layer laminates toward mono-material structures, end-user shifts from impulse retail toward subscription bundling, and channel migration from supermarkets toward direct-to-consumer platforms. CAGRs were derived from regression analysis of historical thermoforming capacity additions correlated with pet food production volumes and regulatory compliance timelines.
Inputs from EFSA pre-approval dossiers and state-level packaging legislation drafts were available through the study window; gaps in proprietary barrier film performance data introduce uncertainty bands around mono-material adoption speed assumptions. Forecasts reflect documented assumptions on REACH enforcement timing and retailer sustainability mandate acceleration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
APAC Canned Food Packaging Market
Food Packaging
Foam Food Container Market
Food Packaging
Canada Disposable Tableware Market
Food Packaging
Global Ambient Food Packaging Market
Food Packaging
Europe Canned Food Packaging Market
Food Packaging
Fresh Produce Trays Market
Food Packaging
Europe Food Contract Manufacturing and Packaging Market
Food Packaging
Coffee Capsules and Pod Packaging Market
Food Packaging
Food Punnets Market
Food Packaging
Meat, Poultry, and Seafood Packaging Market
Food Packaging
PCR Packaging for Food and Beverages Applications Market
Food Packaging
North America PET Food Packaging Market
Food Packaging
Cereal Packaging Market
Food Packaging
Global Disposable Plates Market
Food Packaging
Chocolate Bar Packaging Market
Food Packaging
North America Canned Food Packaging Market