
 Wooden Cutlery Market | 2026-2036
Wooden Cutlery Market Size, Share, and Industry Trends Forecast 2026-2036
Wooden Cutlery Market Outlook
Subscription-based replenishment programs for food-service operators is rebalancing how wooden cutlery reaches end users, shifting volume from spot purchasing to contracted supply tiers. Hoffmaster Group, Inc. leverages its distributor relationships to secure placement across institutional channels. Greenwood anchors North American production with birch-sourcing networks in the Great Lakes region. Vinzor Wood competes on cost structures through integrated bamboo processing in southern China.
Wooden cutlery encompasses disposable eating implements manufactured from solid timber or laminated wood sheets, typically measuring 160–200 mm in length and finished with food-safe mineral oil or wax coatings to prevent moisture absorption during use. These products serve the food-service industry as compostable alternatives to petroleum-based utensils, with birch variants offering denser grain structures that resist splintering under load. Spoons and forks lead volume within the product-type dimension because stirrers face substitution from paper straws and beverage-specific tools. Bamboo material commands premium positioning in retail packs sold through eco-conscious grocers, while birch dominates bulk shipments to restaurants where unit cost governs procurement decisions. Food trucks represent the fastest-expanding end-user segment as mobile vendors seek lightweight, brand-differentiated packaging that aligns with municipal waste-diversion targets.
The EU Single-Use Plastics Directive and FDA food-contact substance regulations jointly determine which coatings and adhesives qualify for wooden cutlery bound for transatlantic trade, with REACH compliance adding testing burdens for European-bound shipments. BIS certification requirements in India and GB standards in China create additional conformity layers for manufacturers exporting from Asian production bases. Stakeholders must monitor how fragmented national compostability certifications reshape market access before committing to regional capacity expansion.
Market Dynamics
Regulatory mandates against single-use plastics have triggered a wholesale material substitution cycle across food-service supply chains, forcing distributors to rebuild procurement frameworks around compostable alternatives.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory phase-outs of polystyrene utensils across member states are redirecting institutional procurement toward birch and bamboo substitutes.
- Quick-service restaurant chains:Burger King, McDonald's, and independent food trucks are embedding wooden cutlery into brand sustainability commitments to satisfy municipal waste-diversion targets.
- Festival and catering contracts:German event organizers now specify compostable utensil kits as standard terms, creating predictable volume pipelines for distributors.
Market Restraints
- Birch supply concentration:Great Lakes region timber harvesting faces seasonal constraints and competing demand from plywood manufacturers.
- REACH compliance costs:European-bound shipments require extensive coating and adhesive testing, adding documentation burdens that disadvantage smaller exporters.
- Paper straw substitution:Wooden stirrers face direct displacement from fiber-based alternatives in beverage applications, compressing a once-stable product segment.
Strategic Opportunities
- Subscription replenishment models:Food-service operators are migrating from spot purchasing to contracted supply tiers, enabling predictable revenue streams for distributors with logistics scale.
- India BIS certification pathways:Domestic manufacturers meeting Bureau of Indian Standards requirements can capture institutional catering growth in Tier-1 and Tier-2 cities.
- Retail eco-conscious positioning:Premium bamboo sets packaged for grocery channels command shelf-space premiums in Germany, France, and the Netherlands.
Industry Challenges
- Fragmented compostability certifications:National standards in Italy, France, and the Netherlands create testing duplication for pan-European suppliers.
- Coating chemistry expertise:Food-safe mineral oil and wax formulation requires specialized knowledge scarce among traditional wood processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wooden Cutlery Market |
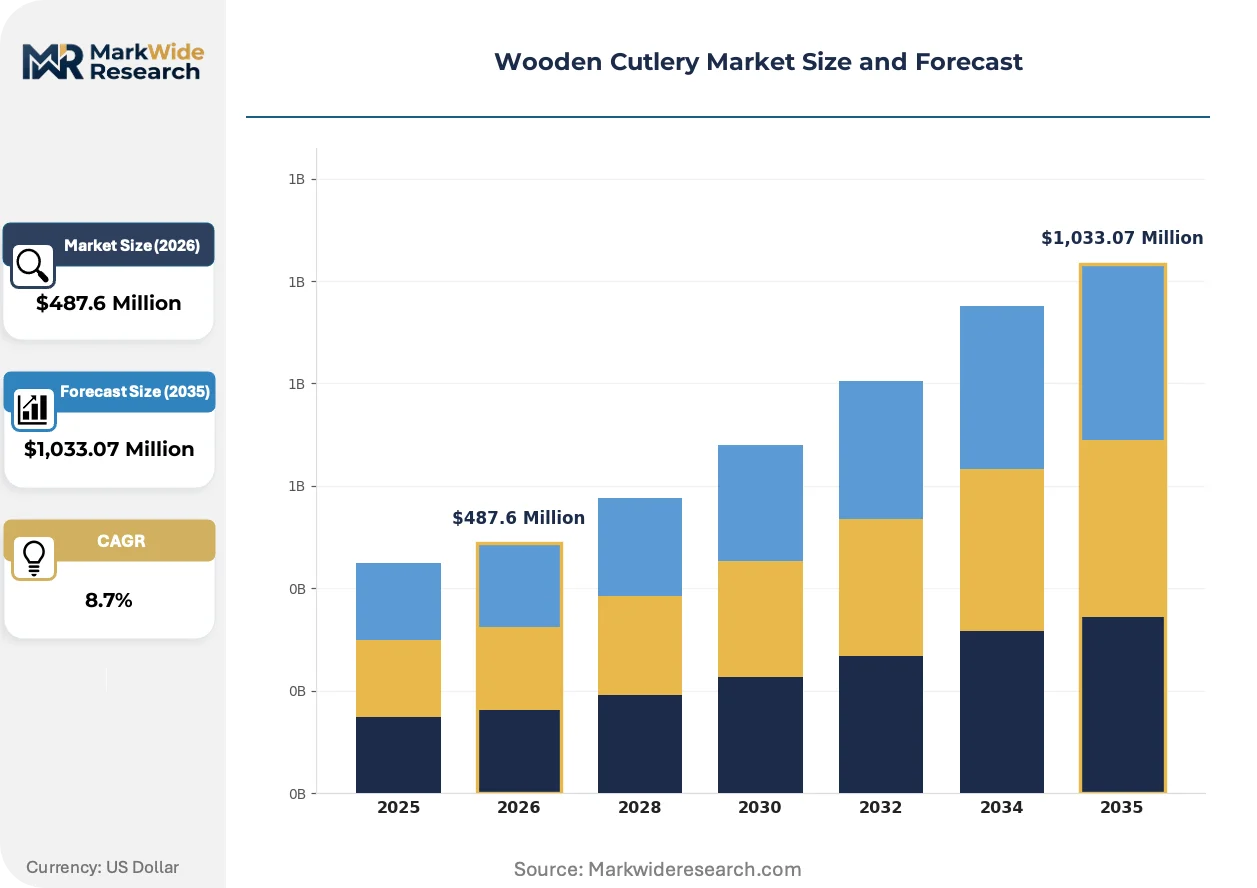
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forks, Spoons, Knives, Stirrers End User: Restaurants, Catering Services, Households, Food Trucks Material: Bamboo, Birch, Maple, Poplar Packaging Type: Bulk, Individual Wrapping, Kits, Retail Packs |
| Companies Covered | Vinzor Wood, Hoffmaster Group, Inc., Greenwood, Earlywood Designs, Alder-Tek Manufacturing, You Cheng, Tianjin Senyangwood Co., Ltd, Allegheny Treenware, Ancheng, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wooden Cutlery Market Strategic Shifts
Material science advances and procurement digitization are converging to reshape how wooden cutlery moves from forest to food-service operator, compressing traditional supply chain intermediaries.
Laser-etched branding technology is expanding into wooden cutlery production, enabling food trucks and restaurant chains to embed logos directly onto utensil surfaces without adhesive labels. Mobile vendors in California and Texas are adopting this capability at accelerating rates. The technology is expanding into mid-sized regional chains that previously relied on generic unbranded stock, collapsing the gap between commodity supply and customized packaging.
REACH chemical registration requirements are tightening scrutiny on mineral oil coatings used for moisture resistance in European-bound shipments. ECHA enforcement actions have triggered reformulation efforts among Asian manufacturers. Quick-service distributors in Germany are now demanding pre-certified coating documentation before contract execution, shifting compliance verification upstream to production facilities.
Consolidated procurement platforms are aggregating demand from independent restaurants and food trucks into volume-tiered contracts that bypass traditional distributor markups. Web-based ordering systems operated by specialized food-service intermediaries are capturing share from legacy phone-and-fax relationships. This channel compression is most visible in California, where municipal composting mandates have synchronized purchasing cycles across fragmented operator bases.
Wooden Cutlery Market Segmentation
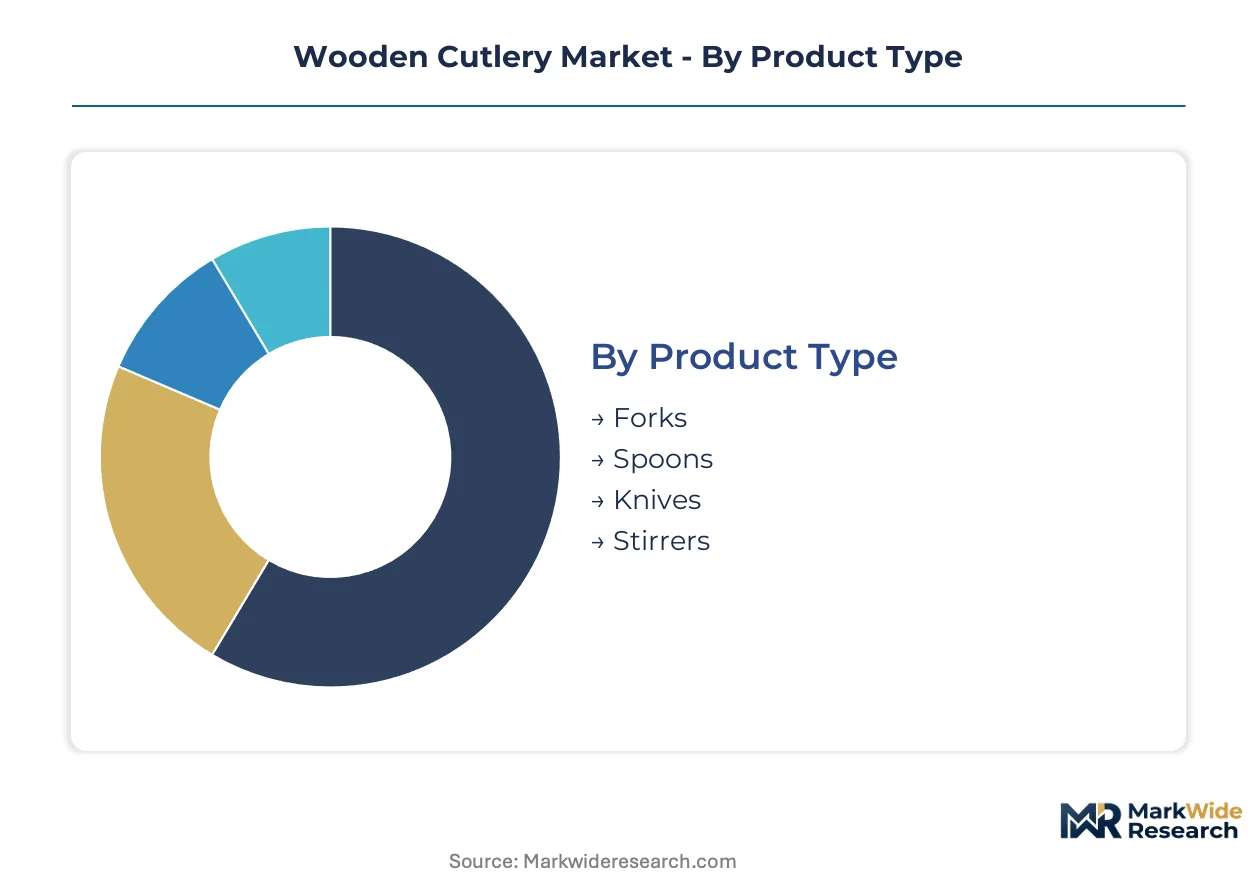
Wooden cutlery procurement diverges sharply between institutional buyers optimizing for unit economics and retail channels seeking shelf differentiation. Understanding these segment boundaries clarifies where coating investments, certification burdens, and logistics configurations create margin separation.
Product Type:
Customization intensity spans from unbranded commodity utensils to laser-etched branded implements, with functional load requirements determining material grade selection.
- Spoons:Solid birch or laminated bamboo construction, typically 160–180 mm length, finished with food-safe mineral oil to prevent moisture absorption during hot soup service. Demand concentrates in quick-service restaurant chains across Germany and California where municipal composting mandates synchronize procurement cycles.
- Forks:Tine structures require denser grain patterns to resist splintering under mechanical load, favoring Great Lakes birch over faster-growing alternatives. Food trucks in Texas and festival caterers in France specify these for brand-differentiated utensil kits.
- Knives:Serrated edge profiles demand harder wood species and precision cutting equipment, limiting supplier pools to integrated manufacturers with in-house tooling.
- Stirrers:Simple linear forms face direct displacement from paper straws in beverage applications, compressing volume as coffee chains reformulate packaging.
Most installed capacity flows through Spoons. Expansion is steepest in Forks.
End User:
Volume concentration versus margin capture splits across operator scale, with procurement sophistication determining contract structure and replenishment frequency.
- Restaurants:Full-service and quick-service operators purchase bulk unbranded stock through food-service distributors, prioritizing unit cost over customization. California and EU regulatory compliance documentation now precedes price negotiation.
- Food Trucks:Mobile vendors in Austin, Los Angeles, and Berlin adopt laser-etched branding to differentiate at point of service, accepting premium pricing for customized minimum order quantities.
- Catering Services:Event operators in Germany specify compostable utensil kits as standard contract terms, creating predictable seasonal volume pipelines.
- Households:Retail pack purchasers through eco-conscious grocers in France and the Netherlands drive bamboo premium positioning.
Restaurants absorb the largest volume share. Food trucks are climbing the fastest.
Material:
Regional timber access and processing infrastructure determine cost structures, with certification requirements filtering supplier eligibility for transatlantic trade.
- Birch:Dense grain structures from Great Lakes region harvesting resist splintering under load, dominating bulk institutional procurement where unit cost governs decisions. Seasonal constraints and plywood manufacturer competition tighten supply.
- Bamboo:Southern Chinese integrated processing enables cost structures that compete with temperate hardwoods, though REACH coating compliance adds documentation burdens for European-bound shipments.
- Maple:Harder density suits knife applications requiring edge retention, with North American sourcing networks concentrated in northeastern forests.
- Poplar:Faster growth cycles and softer grain limit applications to low-load stirrers and economy-tier disposable sets.
Birch commands the greatest installed base. Bamboo is gaining share fastest.
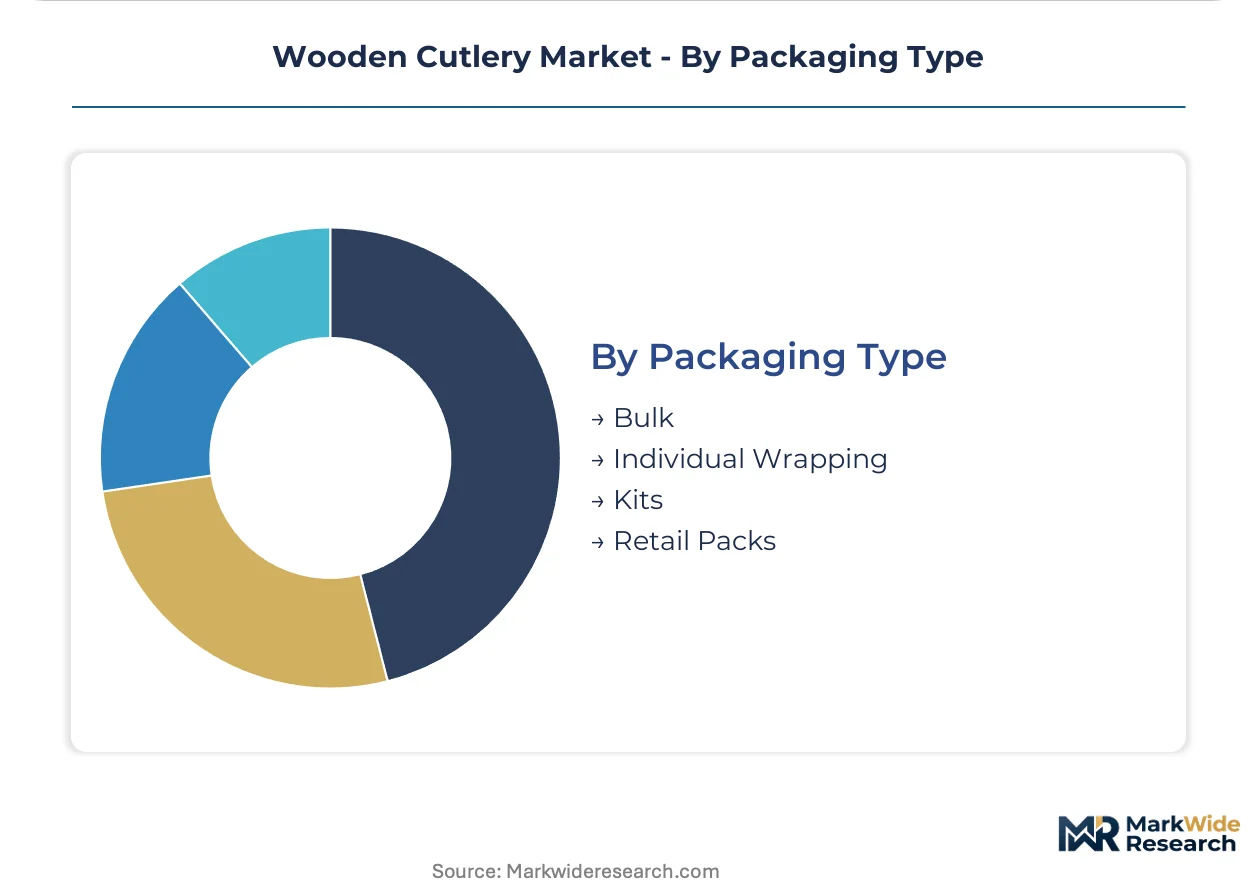
Packaging Type:
Channel economics and food-safety regulations fragment configurations, with individual wrapping requirements diverging between EU and US jurisdictions.
- Bulk:Unwrapped cartons of 500–1000 units serve high-volume restaurant operators in Germany and California, minimizing per-unit packaging cost and downstream waste volume.
- Kits:Pre-assembled fork-spoon-knapkin combinations streamline festival and catering logistics, with German event organizers specifying these as standard procurement terms.
- Individual Wrapping:Paper or bio-film sleeves satisfy FDA and EU food-contact regulations for single-serve distribution, adding unit cost that quick-service chains absorb for regulatory compliance.
- Retail Packs:Shelf-ready cartons of 12–24 units target household purchasers through eco-conscious grocers in France and the Netherlands, commanding premium positioning for bamboo variants.
Bulk shipments dominate installed throughput. Kits show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as coating compliance costs diverge across jurisdictions. Manufacturers in southern China exploit integrated bamboo processing to offset REACH documentation burdens for European-bound shipments. Great Lakes birch harvesters face tightening supply competition from plywood mills.
Germany
Festival caterers and quick-service chains drive institutional procurement volume. The EU Single-Use Plastics Directive mandates compostable utensil kits for municipal events. Food-service distributors in Berlin and Hamburg stock pre-assembled wooden cutlery packages for seasonal catering contracts.
United States
Food trucks in Austin and Los Angeles adopt laser-etched branding for point-of-service differentiation. FDA food-contact substance regulations govern mineral oil coatings for interstate commerce. California's municipal composting mandates synchronize purchasing cycles across fragmented restaurant operators.
China
Integrated bamboo processing clusters in southern provinces enable cost structures competitive with temperate hardwoods. GB standards and REACH compliance documentation filter supplier eligibility for transatlantic export. Manufacturers face reformulation pressure from ECHA enforcement actions on coating chemistry.
France
Eco-conscious grocers in Paris and Lyon command premium shelf positioning for retail-packaged bamboo sets. ANSM and CNIL oversight adds conformity layers alongside EU-wide directives. Compostability certifications from national standards bodies create testing duplication for pan-European suppliers.
India
Tier-1 and Tier-2 city caterers generate institutional demand for certified disposable utensils. BIS certification requirements create domestic manufacturing incentives. Food-service operators in Mumbai and Delhi specify compostable alternatives for corporate event contracts.
Wooden Cutlery Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with distributor relationships determining institutional access and retail positioning commanding premium capture. The vendor base clusters around three archetypes: integrated timber processors controlling upstream birch supply, Asian bamboo converters exploiting labor-cost advantages, and brand-owners leveraging food-service distributor networks. Capacity expansion and certification pre-qualification represent the dominant competitive moves as procurement digitization compresses traditional channel markups.
Among North American fabricators, Greenwood anchors production through Great Lakes birch-sourcing networks. Hoffmaster Group, Inc. exemplifies the distributor-relationship archetype, securing placement across institutional channels. Vinzor Wood occupies a position within the cost-driven tier, competing through integrated southern Chinese bamboo processing. These three represent distinct strategic postures: captive supply control, channel access leverage, and manufacturing-scale efficiency.
| Leading Market Players |
|---|
| Vinzor Wood |
| Hoffmaster Group, Inc. |
| Greenwood |
| Earlywood Designs |
| Alder-Tek Manufacturing |
| You Cheng |
| Tianjin Senyangwood Co., Ltd |
| Allegheny Treenware |
| Ancheng |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between REACH-compliant European shipments and bulk North American restaurant supply manifests in both coating chemistry investments and logistics configurations. Premium bamboo retail packs for French eco-conscious grocers absorb documentation and testing burdens that commodity birch shipments to California quick-service chains bypass entirely.
Pricing Analysis
Distributor margin compression is reshaping how wooden cutlery reaches end users, with subscription-based replenishment models collapsing traditional 30-40 point markups into contracted supply tiers. Three-tier pricing structure across premium, standard, and economy levels separates laser-etched branded kits for Texas food trucks from unwrapped bulk cartons for German festival caterers and economy stirrers facing paper straw displacement. Cost compression in the stirrer segment is intensifying because beverage chains are reformulating packaging around fiber-based alternatives. Quick-service restaurant procurement teams show highest price sensitivity, while mobile vendors in Austin and Los Angeles accept premium positioning for point-of-service differentiation.
Supply Chain Analysis
Domestic-content mandates in India and China's GB standards are reshaping sourcing patterns, pushing manufacturers toward in-country certification investments rather than export-only production. Birch supply draws from Great Lakes region harvesting and southern Chinese bamboo processing clusters, with maple knife production concentrated in northeastern North American forests. Raw material dependencies rest on food-safe mineral oil coatings, laminated wood sheet adhesives, and precision cutting equipment maintenance. Single-source vulnerability runs through Great Lakes birch concentration facing plywood manufacturer competition. Distribution runs through food-service intermediaries in California and Germany, with web-based platforms compressing legacy phone-and-fax relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
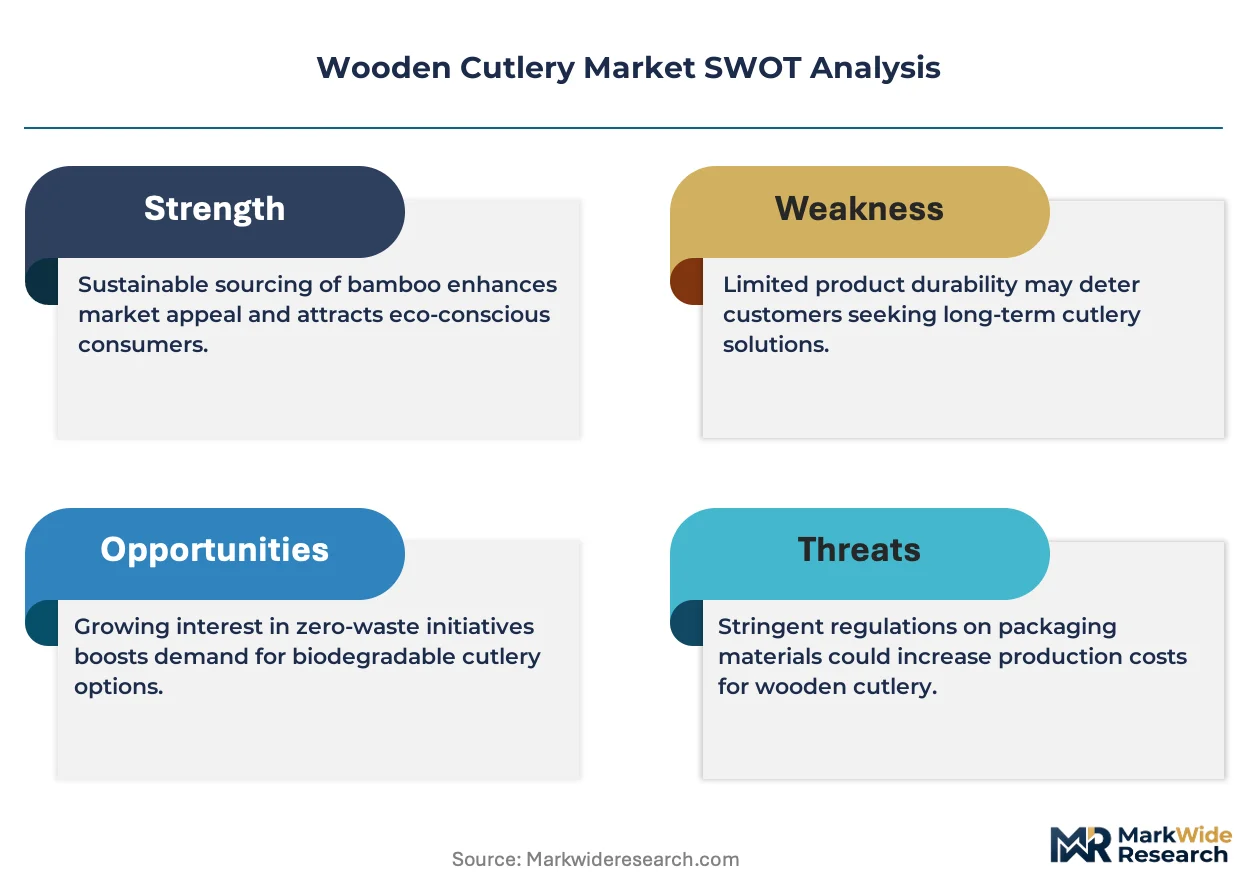
The wooden cutlery market functions as a stable compounder anchored by regulatory mandates that phase out petroleum-based alternatives across multiple jurisdictions.
For Market Incumbents: Acquire coating chemistry expertise to defend against REACH enforcement actions that are disqualifying traditional wood processors from European contracts. Secure captive birch supply through long-term harvesting agreements in the Great Lakes region before plywood manufacturers tighten timber access further. Expand pre-certified production capacity in southern China to maintain cost positioning for Asian export bases. For New Entrants and Emerging Players: Begin with BIS certification pathways for Tier-1 and Tier-2 Indian city caterers, where institutional demand for certified disposable utensils outruns domestic manufacturing capacity. Target festival and catering logistics in Germany, where event organizers now specify compostable utensil kits as standard contract terms. Pursue direct-to-food-truck digital channels in Texas and California, bypassing legacy distributor markups through consolidated procurement platforms. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated bamboo processors possessing in-house REACH documentation capabilities and southern Chinese labor-cost structures. The five-to-ten year viability window favors manufacturers with upstream timber control and downstream brand relationships. Monitor ECHA enforcement action frequency as the inflection indicator for coating chemistry reformulation costs.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Pre-Certification Investment | ECHA enforcement actions in Germany are disqualifying uncertified Asian exporters from contract eligibility. |
| Subscription Replenishment Platform Launch | California food-service operators are migrating from spot purchasing to contracted supply tiers with predictable revenue. |
| Great Lakes Birch Supply Agreement | Seasonal constraints and plywood competition are tightening raw material access for North American fabricators. |
| Laser-Etching Capability Expansion | Texas and Los Angeles food trucks are adopting branded utensil surfaces for point-of-service differentiation. |
| India BIS Certification Pathway | Tier-1 city caterers in Mumbai and Delhi specify certified compostable alternatives for corporate event contracts. |
Study Parameters
Direct dialogue with food-service procurement directors, coating chemistry formulators, timber harvest operators, and festival catering logistics managers grounded the qualitative foundation of this analysis. Secondary validation drew from EU Single-Use Plastics Directive implementation reports, FDA food-contact substance filings, ECHA enforcement action databases, and German food-service distributor inventory records. Bottom-up demand modeling across quick-service chains and food trucks triangulated against top-down regulatory mandate timelines.
Segmentation outputs across material type, product form, end-user scale, and regional regulatory cluster fed into the projection framework. CAGRs were derived from volume-weighted regulatory phase-out schedules and substitution elasticity estimates for petroleum-based alternatives. Birch supply constraints, bamboo processing capacity expansion, and coating chemistry reformulation timelines served as key forecast inputs.
Several conditions sit outside the modeled scope, including unannounced national compostability certifications, abrupt ECHA substance restrictions, and trade policy shifts affecting transatlantic wooden goods tariffs. Forecasts reflect documented assumptions about regulatory implementation pacing and food-service operator procurement digitization rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Global Ambient Food Packaging Market
Food Packaging
Food and Beverage Packaging Market
Food Packaging
Food Packaging Market
Food Packaging
Pet Food Packaging Market
Food Packaging
Asia-Pacific Skin Packaging for Fresh Meat Market
Food Packaging
Chocolate Bar Packaging Market
Food Packaging
Transparent Food Packaging Market
Food Packaging
Produce Packaging Market
Food Packaging
On the Go Food Packaging Market
Food Packaging
Food Partition Trays Market
Food Packaging
PCR Packaging for Food and Beverages Applications Market
Food Packaging
Global Fresh Meat Packaging Market
Food Packaging
Foam Food Container Market
Food Packaging
Self-Heating Food Packaging Market
Food Packaging
Pet Beverage Packaging Market
Food Packaging
Europe Frozen Food Packaging Market