
 Transient Voltage Suppressor Market | 2026-2036
Transient Voltage Suppressor Market Size, Share, and Industry Trends Forecast 2026-2036
Transient Voltage Suppressor Market Analytics
Silicon carbide substrate integration is decoupling TVS component costs from traditional silicon wafer pricing volatility. Vishay Intertechnology leverages vertical integration across wafer fabrication and assembly operations to sustain margin stability. Littelfuse anchors its position through automotive-grade TVS diode specialization aligned with OEM qualification requirements. Infineon Technologies competes by extending silicon-based Zener technology into high-temperature industrial applications.
A transient voltage suppressor is a semiconductor protection device engineered to clamp voltage spikes within nanosecond response times, typically utilizing avalanche breakdown mechanisms in silicon or Zener structures to safeguard downstream circuitry. These components maintain system integrity by shunting surge currents away from sensitive integrated circuits during electrostatic discharge or lightning-induced events. TVS diodes dominate value capture across consumer electronics and telecommunications end uses where board-space constraints prioritize discrete surface-mount packages. ESD suppressors represent the fastest-expanding category as USB-C and HDMI interface proliferation demands polymer-based multi-channel array solutions. Automotive power-line applications concentrate margin pools in high-reliability components qualified under AEC-Q101 stress-test protocols.
The US Federal Communications Commission enforces electromagnetic emission limits that mandate TVS inclusion in networked equipment designs, while the EPA's Restriction of Hazardous Substances alignment pressures lead-free solder compatibility in component terminations. European CE marking requirements under the EMC Directive compel manufacturers to validate surge immunity through standardized IEC 61000-4-5 testing. China's Ministry of Industry and Information Technology accelerates domestic GB standard harmonization with international pulse immunity benchmarks. Stakeholders must monitor material qualification timelines as substrate transitions from silicon to wide-bandgap compounds redefine reliability testing protocols and OEM approval cycles.
Market Dynamics
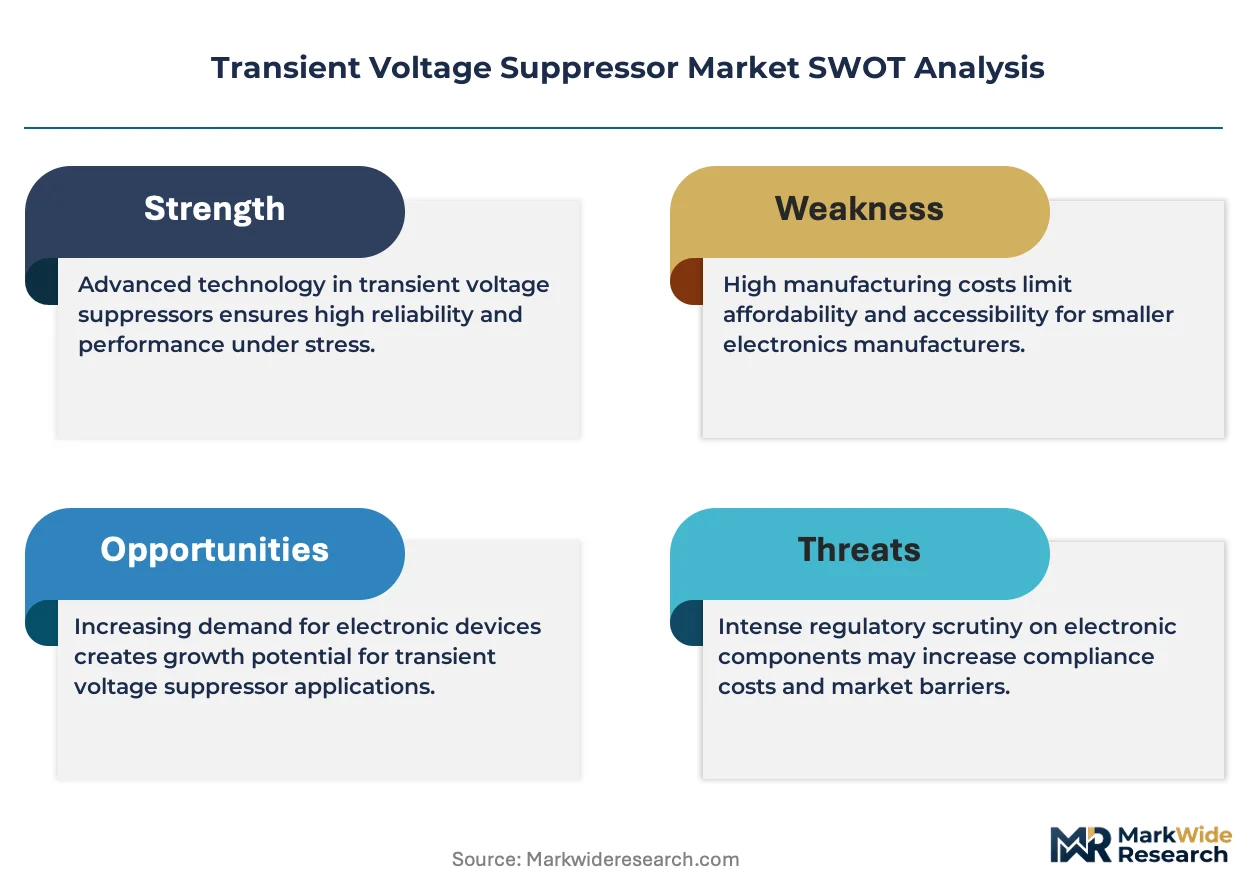
Silicon carbide substrate adoption is restructuring cost structures across the Transient Voltage Suppressor Market, decoupling component pricing from traditional silicon wafer volatility while forcing qualification protocol overhauls at major OEMs.
Growth Catalysts
- Electric vehicle powertrain electrification:Automotive electronics manufacturers are expanding procurement of TVS arrays for battery management system protection, driven by ISO 7637 pulse immunity mandates for high-voltage architectures.
- IEC 61000-4-5 surge immunity standardization:European CE marking requirements under the EMC Directive compel networked equipment designs to integrate TVS components, tightening component specifications across telecommunications supply chains.
- China's telecommunications infrastructure buildouts:Domestic semiconductor packaging capacity in Shenzhen and Shanghai supports localized TVS component sourcing for 5G base station deployments, concentrating demand in eastern provinces.
Market Restraints
- Silicon carbide wafer supply concentration:Substrate fabrication capacity concentrates among limited specialty foundries, creating input cost volatility that compresses margins for discrete TVS diode assemblers.
- AEC-Q101 qualification timelines:Automotive-grade stress-test protocols extend OEM approval cycles to 18-24 months, creating regulatory friction for new market entrants seeking power-line protection contracts.
- Polymer-based ESD suppressor substitution:Multi-channel array solutions for USB-C and HDMI interfaces threaten discrete silicon TVS diode volumes in consumer electronics board-space constrained applications.
Strategic Opportunities
- Wide-bandgap compound convergence:Integration of gallium nitide with silicon carbide substrates enables high-temperature industrial TVS applications previously unreachable by conventional Zener structures.
- India's electronics manufacturing incentives:PLI scheme subsidies for semiconductor packaging are attracting TVS array producers to establish captive supply for domestic telecommunications and automotive demand.
- EPA Restriction of Hazardous Substances alignment:Lead-free solder compatibility mandates in component terminations create regulatory tailwinds for specialized plating and metallization service providers.
Industry Challenges
- Reliability testing protocol redefinition:Substrate transitions from silicon to wide-bandgap compounds require OEMs to rebuild accelerated life-test frameworks, extending certification timelines and freezing design wins.
- GB standard harmonization complexity:China's Ministry of Industry and Information Technology is accelerating domestic pulse immunity benchmark alignment with IEC 61000, forcing dual-qualification investments for export-oriented suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transient Voltage Suppressor Market |
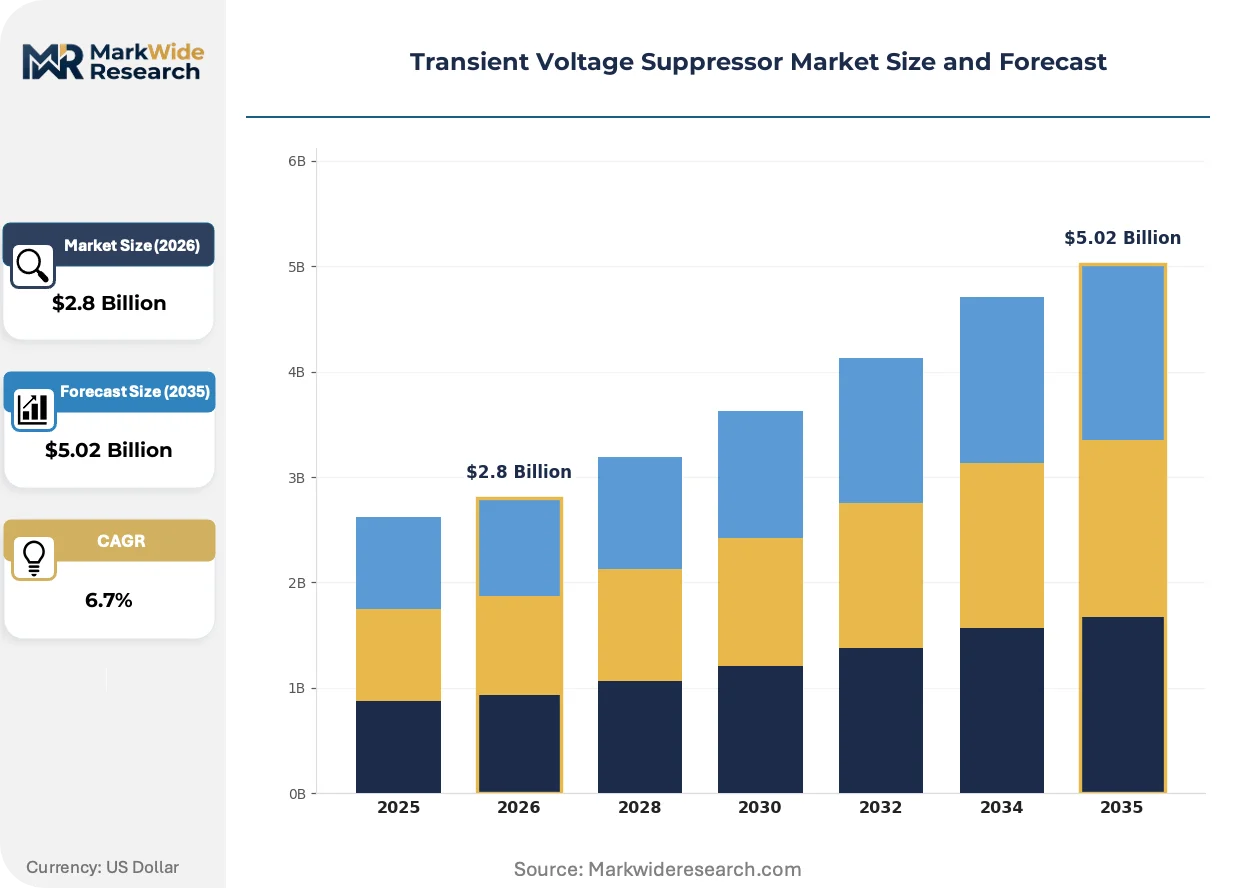
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TVS Diodes, TVS Arrays, TVS Components, ESD Suppressors End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Technology: Silicon, Zener, Varistor, Polymer Application: Data Lines, Power Lines, Communication Systems, Other |
| Companies Covered | Vishay Intertechnology, Littelfuse, Infineon Technologies, STMicroelectronics, Semtech Corporation, Diodes Incorporated, Nexperia, Bourns, MDE Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transient Voltage Suppressor Market Evolving Landscape
Material science breakthroughs and electromagnetic compatibility mandate tightening are converging to reshape component specifications, qualification workflows, and procurement criteria across protection device supply chains.
Silicon carbide substrate integration is electrifying high-reliability TVS architectures by enabling avalanche breakdown mechanisms at temperatures exceeding 175°C. Automotive Tier-1 suppliers are adopting these devices for engine compartment powertrain protection, compressing the performance gap between silicon-based Zener diodes and ceramic transient voltage suppression solutions.
Europe's F-Gas Regulation and RoHS substance restrictions are tightening material disclosure requirements for semiconductor packaging, forcing TVS manufacturers to requalify molding compounds and die-attach epoxies. Component suppliers serving industrial automation and medical device end uses are responding by accelerating halogen-free material transitions ahead of 2027 compliance deadlines.
Telecommunications OEMs are consolidating supplier bases around vertically integrated TVS array providers capable of delivering IEC 61000-4-5 pre-tested protection modules. This behavior change is displacing discrete diode procurement from distribution channels in Germany and Japan, where NTT and Deutsche Telekom infrastructure tenders now mandate integrated surge protection subassemblies.
Transient Voltage Suppressor Market Segmentation
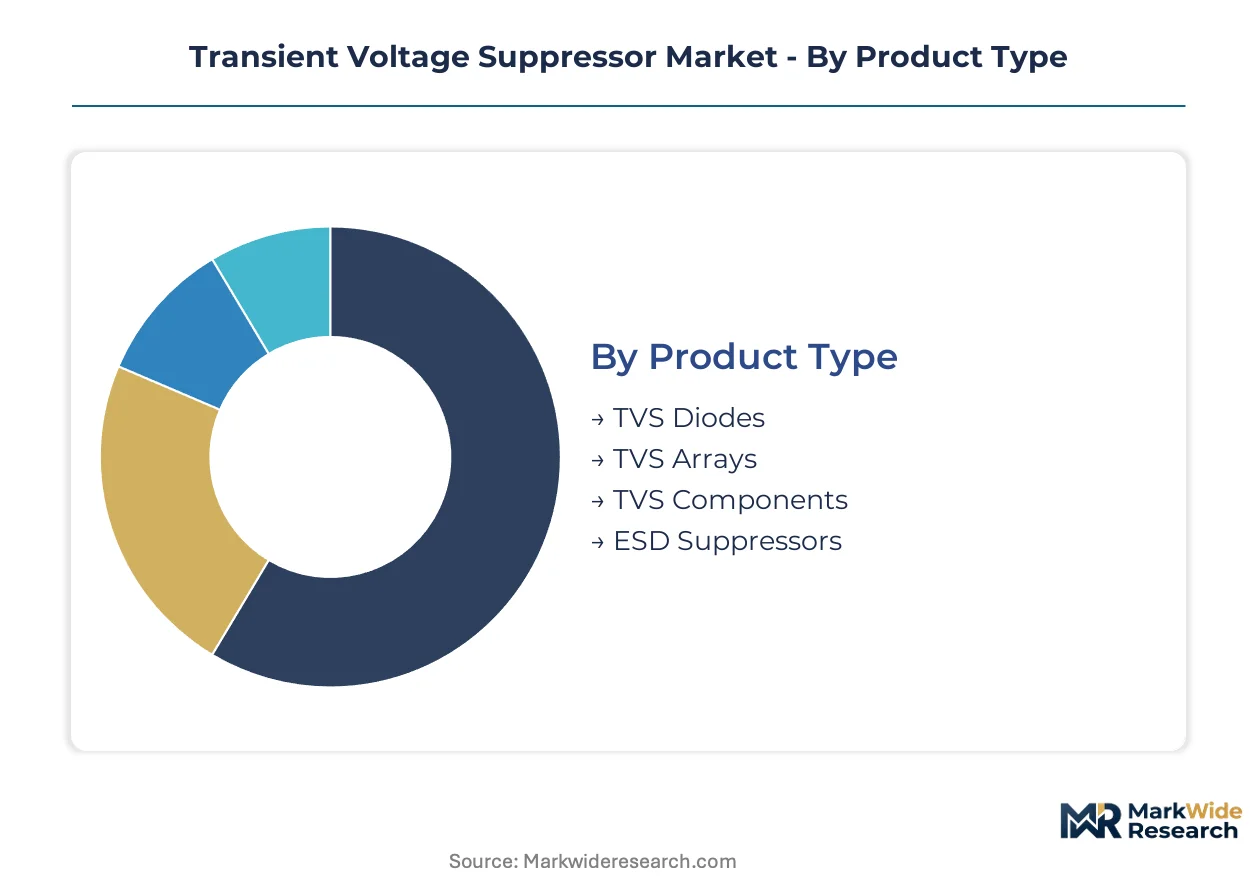
TVS component selection hinges on response time requirements, voltage clamping thresholds, and board-space constraints that vary sharply across automotive powertrain, consumer interface, and telecommunications infrastructure deployments. Procurement patterns diverge by end-use reliability mandates, with AEC-Q101 automotive qualifications imposing 18-24 month approval cycles that reshape supplier economics.
Product Type:
Cost sensitivity and integration complexity separate buyers selecting discrete diodes versus multi-channel array solutions.
- TVS Diodes:Single-channel silicon avalanche devices deliver sub-nanosecond response for discrete surge protection. Automotive battery management systems in Germany and Japan concentrate procurement of surface-mount packages qualified under ISO 7637 pulse immunity protocols.
- ESD Suppressors:Polymer-based multi-channel arrays clamp electrostatic discharge below 1pF capacitance for high-speed data interfaces. USB-C and HDMI proliferation across Shenzhen consumer electronics manufacturing is accelerating volume migration from discrete silicon alternatives.
- TVS Arrays:Integrated multi-line protection modules reduce board space in telecommunications equipment. 5G base station deployments favor these solutions.
- TVS Components:Hybrid assemblies combining diodes with passive filtering elements serve niche industrial automation applications requiring custom voltage thresholds.
TVS Diodes lead volumes today; ESD Suppressors are gaining share fastest.
End User:
Reliability tier requirements stratify procurement, with automotive and medical applications commanding 3-5x price multiples over consumer-grade equivalents.
- Automotive:AEC-Q101 stress-test protocols mandate extended temperature cycling and humidity resistance for powertrain protection. Electric vehicle manufacturers in Shanghai and Stuttgart are expanding TVS array procurement for 800V battery architectures subject to ISO 7637 transient immunity verification.
- Telecommunications:IEC 61000-4-5 surge immunity mandates drive integrated protection module adoption. Deutsche Telekom and NTT infrastructure tenders now require pre-tested subassemblies rather than discrete component sourcing.
- Consumer Electronics:Board-space constraints and cost minimization prioritize polymer ESD suppressors over silicon diodes in smartphone and laptop manufacturing.
- Industrial Equipment:Extended temperature ranges and harsh environmental exposure favor ceramic and silicon carbide TVS solutions in factory automation deployments.
Automotive commands premium pricing; Telecommunications is expanding most quickly.
Technology:
Substrate material selection determines thermal performance ceilings and qualification protocol requirements that reshape OEM approval timelines.
- Silicon:Mature avalanche breakdown technology dominates cost-sensitive consumer applications. Traditional wafer pricing volatility has compressed assembler margins, accelerating foundry transitions to wide-bandgap alternatives.
- Silicon Carbide:Wide-bandgap substrates enable avalanche operation above 175°C for engine compartment powertrain protection. Automotive Tier-1 suppliers in Japan and Germany are qualifying these devices ahead of 2027 halogen-free packaging mandates under Europe's F-Gas Regulation.
- Zener:Precision voltage clamping structures serve low-power signal line protection in industrial control systems.
- Polymer:Organic composite materials deliver ultra-low capacitance for multi-gigabit data interface protection.
Silicon retains volume leadership; Silicon Carbide shows the steepest expansion trajectory.
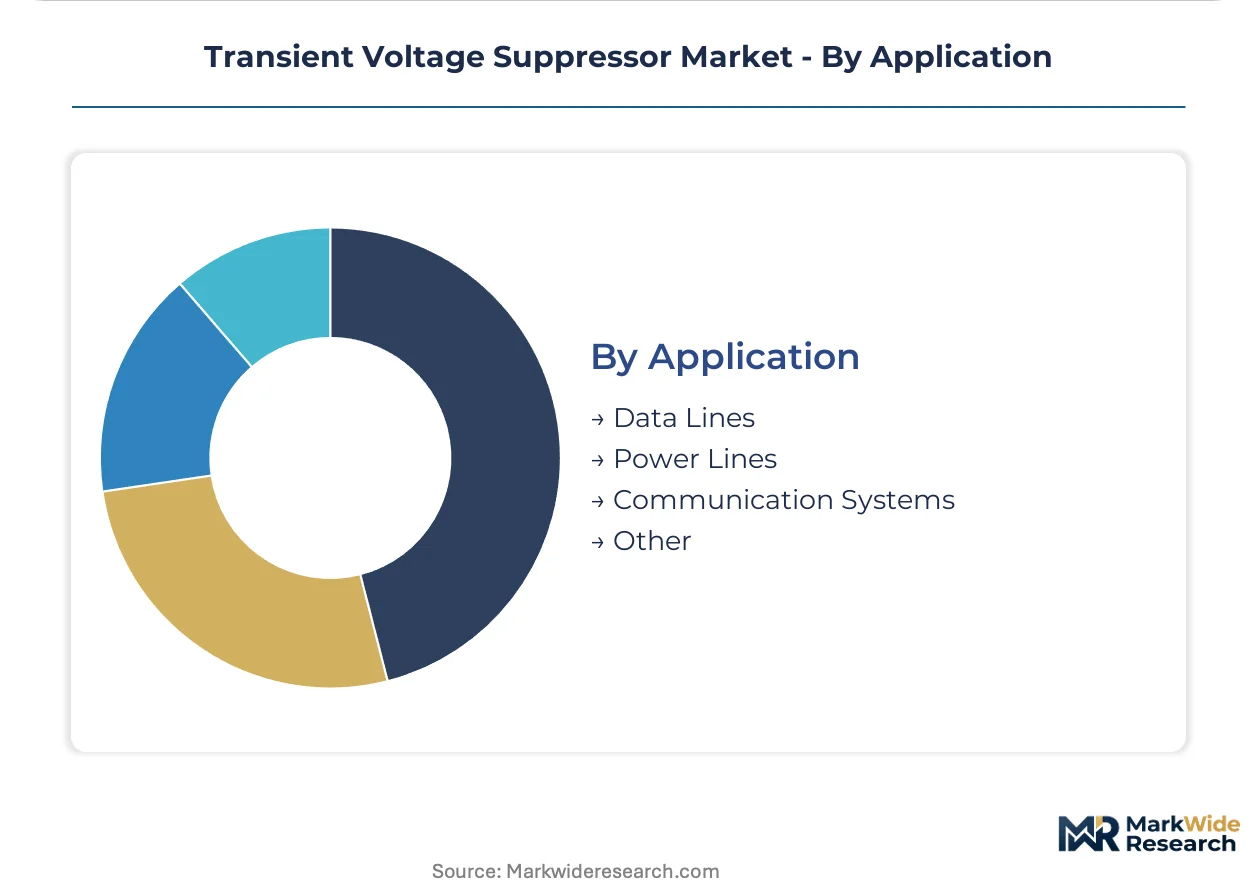
Application:
Voltage amplitude and surge duration requirements differentiate protection strategies across signal integrity versus power conditioning use cases.
- Power Lines:High-energy absorption requirements for AC mains and DC bus protection favor large-package TVS diodes and metal-oxide varistors. Solar inverter and EV charging infrastructure buildouts in China and India are concentrating demand for 1.5kW+ peak pulse power ratings.
- Data Lines:Low-capacitance polymer suppressors preserve signal integrity in USB, HDMI, and Ethernet interfaces. Consumer electronics manufacturing in Shenzhen and Taipei drives multi-channel array volumes.
- Communication Systems:RF front-end protection combines gas discharge tubes with semiconductor clamps for base station lightning immunity.
- Other:Specialized applications including medical device isolation and aerospace avionics command custom qualification protocols.
Power Lines dominate value capture; Data Lines are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's semiconductor packaging corridor anchors global TVS component sourcing, with capacity expansion concentrated across eastern Chinese provinces serving telecommunications infrastructure buildouts. Domestic foundries in Shanghai and Suzhou are scaling silicon carbide substrate fabrication to meet automotive qualification timelines. Regulatory harmonization pressures are reshaping procurement patterns across major demand centers.
United States
Electric vehicle manufacturers in Detroit and Austin are expanding TVS array procurement for 800V battery architectures. The FCC enforces electromagnetic emission limits mandating surge protection inclusion in networked equipment designs. California's semiconductor design clusters concentrate fabless TVS specification development for consumer electronics interfaces.
Germany
Automotive Tier-1 suppliers in Stuttgart and Munich are qualifying silicon carbide TVS devices for engine compartment powertrain protection. The CE marking requirements under the EMC Directive compel IEC 61000-4-5 surge immunity validation. Bavaria's industrial automation sector concentrates demand for high-reliability protection modules in factory robotics deployments.
Japan
NTT infrastructure tenders now mandate pre-tested integrated surge protection subassemblies rather than discrete component sourcing. METI coordinates domestic standard alignment with international pulse immunity benchmarks. Nagoya's automotive electronics corridor concentrates AEC-Q101 qualification activity for hybrid vehicle powertrain protection.
India
PLI scheme subsidies for semiconductor packaging are attracting TVS array producers to establish captive supply for domestic telecommunications demand. The CEA mandates surge protection inclusion in grid-connected solar inverter installations. Karnataka's electronics manufacturing clusters in Bengaluru are scaling assembly capacity for USB-C interface protection components.
Transient Voltage Suppressor Market Competitive Landscape
Global majors compete with regional champions across substrate technology and automotive qualification capabilities, creating a tiered structure where scale-driven incumbents face specialized challengers. The vendor base separates into three strategic archetypes: vertically integrated wafer-to-package operators, automotive-grade specialists with AEC-Q101 certification depth, and fabless designers leveraging foundry partnerships. Dominant competitive moves include backward integration into silicon carbide substrate fabrication and strategic partnerships for halogen-free packaging qualification ahead of Europe's F-Gas Regulation deadlines.
Within the premium-tier vector, Vishay Intertechnology and Littelfuse occupy positions exemplifying automotive-grade specialization and vertical manufacturing control. Infineon Technologies represents the scale-driven archetype extending silicon-based technology into industrial temperature applications. These three anchors illustrate how qualification depth and substrate integration capabilities determine competitive positioning across OEM procurement evaluations.
| Leading Market Players |
|---|
| Vishay Intertechnology |
| Littelfuse |
| Infineon Technologies |
| STMicroelectronics |
| Semtech Corporation |
| Diodes Incorporated |
| Nexperia |
| Bourns |
| MDE Semiconductor |
| Others |
Value Network & Pricing Analysis
Automotive OEM consolidation around AEC-Q101-qualified suppliers is forcing component assemblers to absorb extended qualification costs or cede share to vertically integrated rivals, compressing margins across silicon-based TVS tiers while widening spreads for silicon carbide alternatives.
Pricing Analysis
Silicon wafer pricing volatility passes through directly to discrete TVS diode assemblers lacking captive substrate supply. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels separates margin pools sharply. Cost compression in consumer electronics tiers is intensifying because polymer ESD suppressor substitution erodes silicon diode volumes. Consumer electronics manufacturers exhibit highest price sensitivity, while automotive Tier-1 suppliers accept premium positioning for ISO 7637 compliance.
Supply Chain Analysis
Workforce availability constraints in Shenzhen and Shanghai semiconductor packaging corridors are pushing TVS array producers toward automated assembly investments. Substrate fabrication concentrates in China, Japan, and Germany, while die packaging draws from Taiwanese and South Korean operations. Raw material dependencies span silicon carbide wafers, halogen-free molding compounds, and lead-free solder plating chemistries. Single-source vulnerability in specialty silicon carbide foundries creates supply chain risk. Distribution runs through authorized distributors serving automotive and telecommunications OEMs directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide substrate integration unlocks margin expansion by decoupling component economics from commodity silicon wafer cycles while commanding premium positioning in high-temperature automotive applications.
For Market Incumbents: Extend AEC-Q101 certification depth into silicon carbide architectures before 2027 halogen-free packaging mandates take effect. Deepen backward integration into substrate fabrication to defend against specialty foundry cost volatility. Lock in long-term supply agreements with Shenzhen packaging houses to secure capacity for telecommunications infrastructure tenders. For New Entrants and Emerging Players: Begin with India's PLI-subsidized semiconductor packaging corridors to serve domestic solar inverter and automotive demand with lower qualification overhead. Target industrial automation applications requiring custom voltage thresholds where incumbent qualification cycles create procurement gaps. Pursue direct OEM relationships rather than distribution channel dependence to bypass entrenched supplier lists. For Investors and Strategic Acquirers: Asymmetric upside sits with fabless designers possessing IEC 61000-4-5 pre-tested module portfolios and established Deutsche Telekom or NTT qualification records. Five-to-ten-year viability hinges on substrate technology transition execution rather than legacy silicon scale. Watch for silicon carbide wafer supply loosening as the inflection signal for margin expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Integration | Enables 175°C+ operation for engine compartment powertrain protection in Stuttgart and Nagoya automotive clusters. |
| Halogen-Free Packaging Transition | Secures CE marking compliance under Europe's F-Gas Regulation ahead of 2027 deadlines. |
| AEC-Q101 Certification Investment | Unlocks 800V battery architecture contracts with Shanghai and Austin electric vehicle manufacturers. |
| Telecommunications Module Pre-Testing | Meets Deutsche Telekom and NTT tender requirements for integrated surge protection subassemblies. |
| India PLI Scheme Manufacturing Entry | Captures domestic solar inverter and USB-C protection demand in Karnataka electronics corridors. |
Research Methodology
Direct dialogue with automotive Tier-1 procurement officers, telecommunications infrastructure planners, semiconductor packaging engineers, and EMC test laboratory directors grounded this analysis in operational reality. Secondary validation drew from IEC 61000 standard documentation, EPA RoHS alignment filings, SEC 10-K disclosures from protection device manufacturers, and MIIT GB standard harmonization notices. Bottom-up component demand modeling and top-down end-use market sizing were triangulated to constrain forecast variance.
Segment-level outputs across product type, end user, technology, and application dimensions were generated through the projection horizon. CAGRs were derived from installed base growth, content-per-vehicle trends in electric architectures, and infrastructure deployment schedules. Key inputs included silicon carbide wafer supply forecasts, AEC-Q101 qualification pipeline tracking, and telecommunications capital expenditure disclosures from NTT and Deutsche Telekom.
Several conditions sit outside the modeled scope, including unannounced substrate technology breakthroughs, abrupt tariff reconfigurations affecting semiconductor packaging trade flows, and regulatory acceleration of halogen-free mandates beyond current timelines. Forecasts reflect documented assumptions about OEM design win conversion rates and foundry capacity expansion schedules. Material deviation in silicon carbide substrate availability or automotive qualification timeline compression warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
Betavoltaic Device Market
Detection and Regulation Devices
Null Detector Market
Detection and Regulation Devices
Latin America Trace Detection Market
Detection and Regulation Devices
Compliance Monitoring Devices Market
Detection and Regulation Devices
US Pin and Sleeve Devices Market
Detection and Regulation Devices
Indeflator Devices Market
Detection and Regulation Devices
Europe Portable Gas Detector Market
Detection and Regulation Devices
Pedestrian Detection System Market
Detection and Regulation Devices
South East Asia Gas Detection Device Market
Detection and Regulation Devices
Underwater Signaling Devices Market
Detection and Regulation Devices
Arc Fault Detection Market
Detection and Regulation Devices
Registering Clock Driver (RCD) Market
Detection and Regulation Devices
Limiter Diodes Market
Detection and Regulation Devices
Infrared Detection Chip Market
Detection and Regulation Devices
Asia-Pacific Trace Detection Screening Market