
 HID Ballast Market | 2026-2036
HID Ballast Market Size, Share, and Industry Trends Forecast 2026-2036
HID Ballast Market Outlook
Chinese ballast manufacturing clusters is recalibrating output mix toward electronic variants as export specifications tighten. Eaton Corporation leverages its electrical infrastructure portfolio to sustain commercial lighting channel dominance across North American distribution networks. Philips Lighting Holding B.V. anchors European demand through specialized HID ballast designs for sports facilities and street lighting applications. OSRAM Licht AG competes on technology leadership in ceramic metal halide driver systems for precision retail illumination.
An HID ballast is an electrical device that regulates starting voltage and operating current for high-intensity discharge lamps, typically managing 35-watt to 1000-watt systems across mercury vapor, metal halide, and high-pressure sodium technologies. Its core function is delivering controlled ignition pulses followed by stable current limitation to prevent thermal runaway and extend lamp life in demanding industrial and outdoor environments. Electronic ballasts now command the primary margin pool as energy efficiency mandates displace magnetic core-and-coil designs across warehouse and street lighting applications. Smart ballasts with integrated dimming protocols and network connectivity represent the fastest-expanding segment, though from a smaller base, as municipal buyers prioritize remote asset management capabilities.
The US Department of Energy enforces minimum efficiency standards under federal lamp ballast regulations, while the EU F-Gas Regulation and Ecodesign Directive constrain mercury-containing lamp systems and drive retrofit demand. China's GB standards through SAMR and MIIT impose electromagnetic compatibility and energy labeling requirements that filter import access and shape domestic procurement specifications. Buyers must weigh stranded asset risk in magnetic ballast inventories against the upfront capital requirements of smart electronic systems as regulatory phaseouts accelerate across major economies.
Market Dynamics
Electronic ballast architectures are displacing magnetic core-and-coil designs as efficiency mandates tighten across municipal procurement specifications. This technology transition concentrates margin capture among suppliers with semiconductor integration capabilities while stranding legacy inventories.
Growth Catalysts
- US DOE Efficiency Standards:Federal minimum efficiency regulations for fluorescent and HID lamp ballasts accelerate electronic ballast procurement across commercial lighting retrofits.
- Smart City Infrastructure:Municipal buyers in China prioritize network-connected ballast systems with remote asset management for street lighting networks.
- Ceramic Metal Halide Drivers:Precision retail illumination applications demand advanced driver systems that extend lamp life and improve color rendering consistency.
Market Restraints
- Copper and Ferrite Core Volatility:Magnetic ballast production remains exposed to commodity price swings in core transformer materials.
- Mercury Phaseout Constraints:The EU F-Gas Regulation and Ecodesign Directive constrain mercury-containing lamp systems, compressing addressable demand for compatible ballast hardware.
- LED Substitution Pressure:Solid-state lighting systems erode HID install bases in warehouse and industrial verticals where retrofit economics favor complete luminaire replacement.
Strategic Opportunities
- India Industrial Zone Electrification:BIS certification requirements and CEA grid expansion programs create procurement windows for electronic ballast suppliers in manufacturing corridor developments.
- Integration of Powerline Communication and DALI Protocols:Converged control architectures enable granular dimming and energy metering that command pricing premiums in smart building deployments.
- US Infrastructure Investment:IRA-funded municipal lighting modernization programs expand addressable demand for networked HID ballast systems in highway and tunnel applications.
Industry Challenges
- Electromagnetic Compatibility Certification:China's GB standards through SAMR and MIIT impose testing timelines that delay product launches and strain engineering bandwidth.
- Legacy System Integration Complexity:Smart ballast deployment requires backward compatibility with existing HID lamp inventories and analog control infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HID Ballast Market |
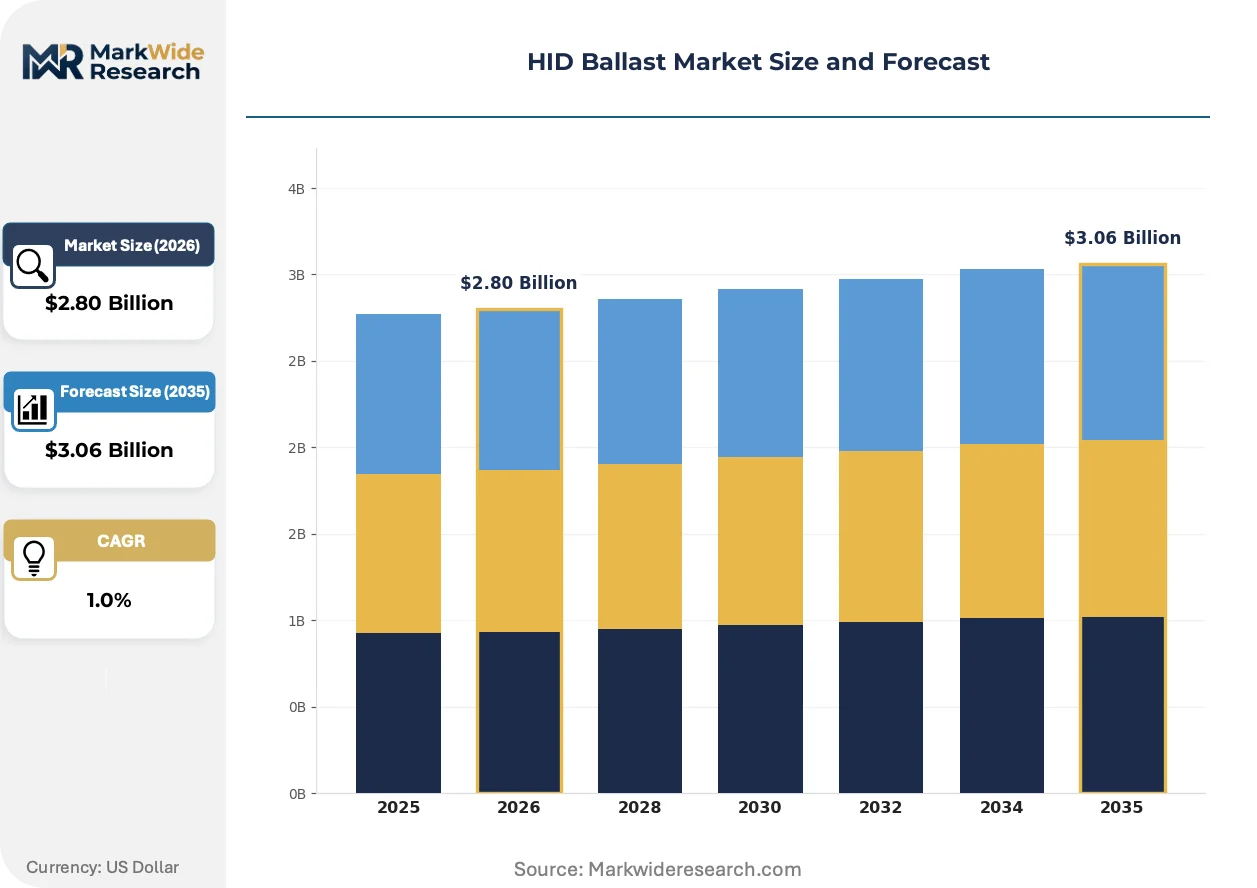
| Market Size in 2026 | $2.80 Billion |
| Market Size in 2035 | $3.06 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Ballasts, Electronic Ballasts, Smart Ballasts, Hybrid Ballasts End User: Commercial Lighting, Industrial Lighting, Outdoor Lighting, Residential Lighting Technology: Fluorescent, LED, High-Intensity Discharge, Induction Application: Street Lighting, Warehouse Lighting, Retail Lighting, Sports Facilities |
| Companies Covered | Eaton Corporation, Universal Lighting Technologies, Philips Lighting Holding B.V., Villa Industrias S.A. de C.V., Acuity Brands Lighting, General Electric Company, OSRAM Licht AG, Hatch Lighting, Fulham Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HID Ballast Market Strategic Shifts
Digital control architectures are redefining ballast functionality beyond basic current regulation. The convergence of power electronics and communication protocols creates new value layers in lighting system management.
Multi-lamp electronic ballast platforms with integrated power factor correction are consolidating market share across warehouse and industrial installations. Large-format retail and logistics operators specify these systems for 320-watt to 750-watt metal halide arrays. The technology is consolidating supplier tiers by rewarding semiconductor integration capabilities over discrete component assembly expertise.
REACH substance restrictions and RoHS compliance deadlines are accelerating design refresh cycles across European ballast manufacturing. Industrial consequences include reformulated potting compounds and lead-free solder transitions that elevate unit costs. Sports facility and street lighting procurement in Germany and France now mandates full material disclosure, filtering supplier access.
Municipal buyers are bundling ballast procurement with long-term service and remote monitoring subscriptions. Traditional distributor channels face compression as direct manufacturer relationships capture recurring revenue streams. This pattern is most visible in Chinese smart city deployments where MIIT-backed standardization enables platform-based purchasing at provincial scale.
HID Ballast Market Segmentation
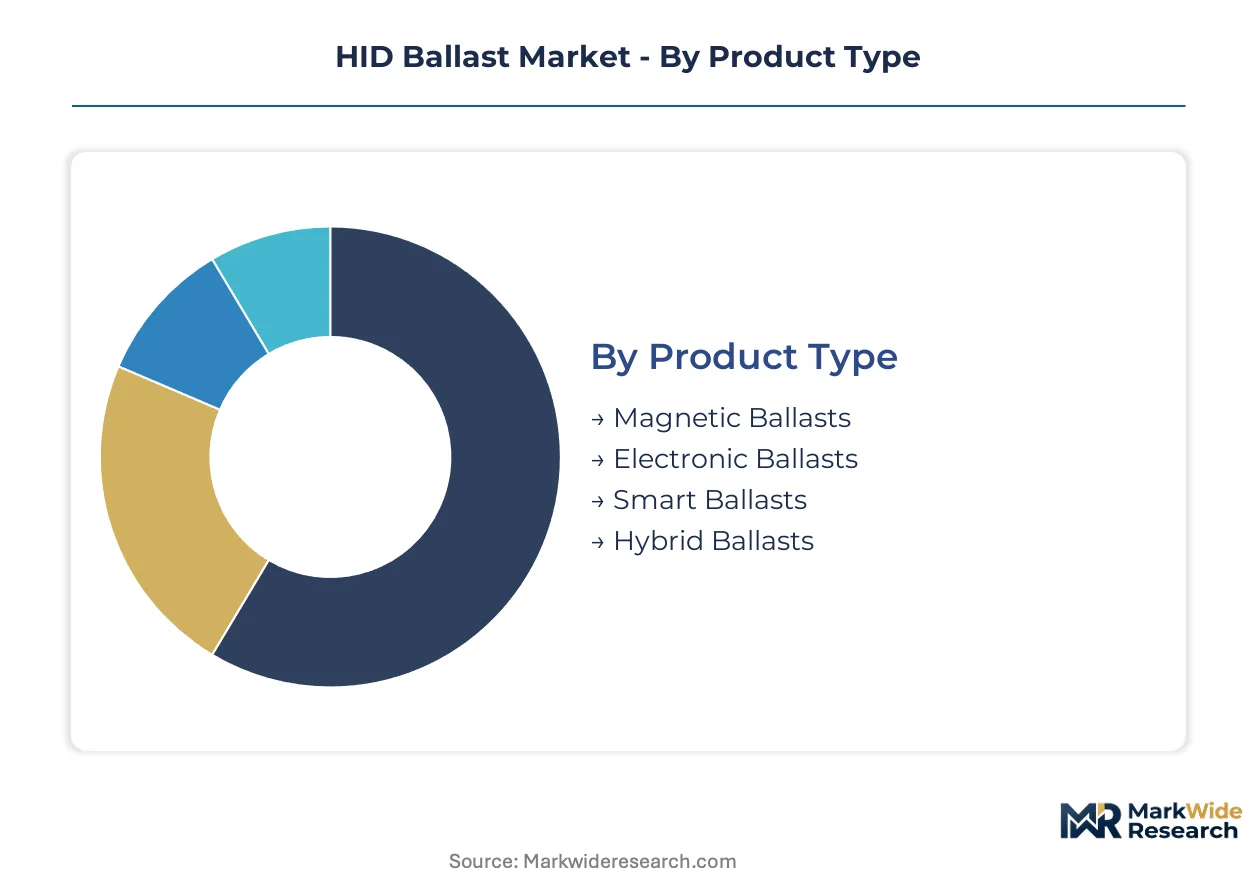
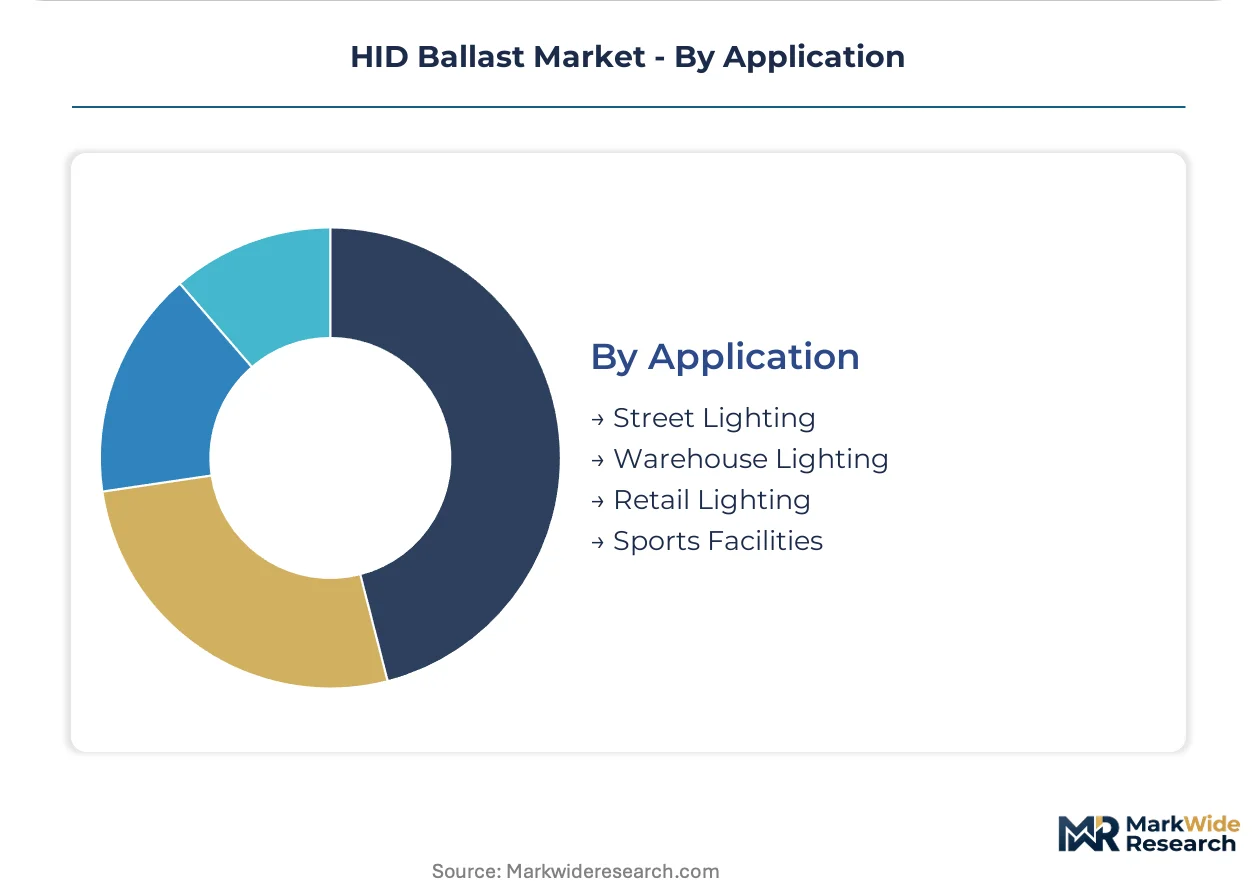
HID ballast procurement patterns diverge sharply across installation environments and control architectures. Specification requirements for outdoor infrastructure differ fundamentally from indoor commercial retrofits, creating distinct margin pools and certification pathways for suppliers.
Product Type:
Technology architecture determines efficiency compliance, semiconductor content, and service revenue potential in ballast procurement.
- Magnetic Ballasts:Core-and-coil designs using copper windings and ferrite transformers dominate legacy installations in industrial facilities with long replacement cycles. Municipal buyers in China continue specifying these systems for cost-constrained rural electrification projects despite efficiency disadvantages.
- Electronic Ballasts:High-frequency switching circuits with integrated power factor correction now anchor commercial lighting retrofits across warehouse and retail verticals. US DOE efficiency standards are accelerating displacement of magnetic hardware in North American distribution networks.
- Smart Ballasts:Network-connected platforms with DALI and powerline communication protocols enable remote dimming and asset monitoring. Procurement concentrates in Chinese smart city deployments where MIIT-backed standardization supports provincial-scale platform purchasing.
- Hybrid Ballasts:Transitional architectures combining electromagnetic starting with electronic operating stages serve retrofit applications requiring backward compatibility with existing HID lamp inventories.
Mature deployment sits with magnetic ballasts in legacy industrial infrastructure. Newer deployment is concentrated in smart ballast systems for connected municipal lighting networks.
End User:
Customer type shapes specification intensity, procurement channel, and lifecycle service expectations in ballast demand.
- Commercial Lighting:Office complexes and retail chains specify electronic ballasts with rapid-start capabilities and extended warranty terms. US commercial building codes through ASHRAE standards are tightening efficiency requirements for fluorescent and HID retrofits.
- Industrial Lighting:Manufacturing facilities and logistics hubs prioritize multi-lamp electronic platforms for 320-watt to 750-watt metal halide arrays. Procurement emphasizes thermal resilience and vibration resistance in heavy-duty operating environments.
- Outdoor Lighting:Street, highway, and tunnel installations drive demand for weather-sealed housings and surge protection. IRA-funded infrastructure programs in the US are expanding procurement windows for networked HID systems.
- Residential Lighting:Limited uptake concentrates in high-end architectural applications and rural electrification projects where grid stability favors HID over LED alternatives.
Volume concentration rests with industrial lighting in manufacturing corridor developments. Pricing premiums are extracting most effectively from outdoor lighting buyers bundling long-term monitoring subscriptions.
Technology:
Lamp technology alignment determines ballast electrical characteristics and regulatory exposure in system design.
- Fluorescent:Rapidly contracting install base faces phaseout pressure from EU Ecodesign Directive constraints on mercury-containing systems. Ballast demand survives in specialized horticultural and medical applications requiring specific spectral output.
- LED:Solid-state systems operate on constant-current drivers rather than traditional ballast architectures, creating competitive substitution rather than complementary demand.
- High-Intensity Discharge:Mercury vapor, metal halide, and high-pressure sodium systems constitute the core addressable market for dedicated HID ballast hardware. Ceramic metal halide variants command specialized driver designs for precision color rendering in retail environments.
- Induction:Electrodeless lamp systems require high-frequency electronic ballasts with extended operating lifecycles, serving niche applications in hard-to-access installations.
Revenue gravity centers on high-intensity discharge technology across municipal and industrial procurement. Induction systems are climbing the fastest among specialized retrofit applications.
Application:
Installation environment dictates ingress protection ratings, thermal management requirements, and control protocol integration in ballast specification.
- Street Lighting:Pole-mounted installations require surge-resistant electronics and photocell compatibility. Chinese urban expansion programs sustain procurement volumes for high-wattage sodium vapor systems.
- Warehouse Lighting:High-bay installations favor multi-lamp electronic platforms with occupancy sensor integration. Logistics operators specify these systems for energy metering and demand response participation.
- Retail Lighting:Precision illumination demands ceramic metal halide drivers with tight color consistency control. European sports facilities and luxury retail chains now mandate full material disclosure under REACH substance restrictions.
- Sports Facilities:Stadium and arena installations require instant-restrike capabilities and broadcast-quality flicker performance. Procurement emphasizes German and French certification for large-format venue projects.
Specification complexity peaks in sports facilities requiring broadcast-grade performance. Volume scale concentrates in warehouse lighting for logistics network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper and ferrite core supply chains anchor ballast manufacturing across East Asian industrial corridors. Procurement specifications diverge sharply between efficiency-mandated retrofit markets and cost-driven electrification programs.
United States
IRA-funded highway and tunnel modernization sustains demand for networked HID systems. DOE federal efficiency standards accelerate displacement of magnetic hardware in commercial retrofits. Texas and California distribution networks concentrate procurement for industrial lighting arrays.
Germany
REACH substance restrictions and RoHS compliance deadlines elevate unit costs for reformulated potting compounds. Ecodesign Directive constraints on mercury-containing lamps compress compatible ballast demand. Bavarian sports facility procurement mandates full material disclosure for large-format venue projects.
China
Urban expansion and MIIT-backed smart city standardization drive provincial-scale platform purchasing. GB standards through SAMR impose electromagnetic compatibility testing timelines that filter import access. Yangtze River Delta manufacturing clusters recalibrate output mix toward electronic variants for tightening export specifications.
India
CEA grid expansion programs and BIS certification requirements create procurement windows in manufacturing corridor developments. Industrial zone electrification concentrates demand in Gujarat and Maharashtra logistics hubs. Domestic procurement specifications increasingly favor electronic architectures over legacy magnetic systems.
Japan
Precision retail illumination applications sustain specialized driver demand for ceramic metal halide systems. METI efficiency guidelines shape commercial building retrofit specifications. Kanto region distribution networks prioritize multi-lamp electronic platforms with integrated power factor correction.
HID Ballast Market Competitive Environment
Global majors compete with regional champions across technology integration capabilities and distribution channel depth. Market structure shows moderate consolidation around semiconductor-integrated suppliers while legacy magnetic specialists face margin compression. Three archetypes dominate: diversified electrical infrastructure conglomerates, specialized lighting component manufacturers, and electronics-focused driver system suppliers. Capacity expansion and strategic partnerships represent the primary competitive moves as manufacturers navigate regulatory phaseout timelines.
Among diversified electrical infrastructure conglomerates, Eaton Corporation exemplifies the channel-dominance archetype across North American commercial lighting networks. Philips Lighting Holding B.V. occupies a position within the specialized lighting tier, anchoring European demand through sports facility and street lighting applications. OSRAM Licht AG represents the technology-leadership archetype in precision driver systems for retail illumination environments.
| Leading Market Players |
|---|
| Eaton Corporation |
| Universal Lighting Technologies |
| Philips Lighting Holding B.V. |
| Villa Industrias S.A. de C.V. |
| Acuity Brands Lighting |
| General Electric Company |
| OSRAM Licht AG |
| Hatch Lighting |
| Fulham Co. Inc. |
| Others |
Value Chain & Pricing Dynamics
Copper futures and ferrite powder indices cascade through HID ballast manufacturing cost structures, compressing margins on magnetic core-and-coil designs while amplifying pricing power for semiconductor-integrated electronic suppliers. Chinese procurement offices exploit this divergence through provincial-scale tendering that rewards backward-integrated manufacturers with captive ferrite sourcing.
Pricing Analysis
Warranty bundling separates premium electronic ballast suppliers from transactional magnetic hardware vendors, with multi-year remote monitoring subscriptions now standard in Chinese smart city contracts. Three-tier pricing structure across premium smart ballasts, standard electronic units, and economy magnetic designs reflects certification intensity under SAMR electromagnetic compatibility testing. Cost compression in magnetic tiers stems from copper volatility and stranded inventory risk as DOE efficiency mandates accelerate phaseout timelines. Municipal buyers in India exhibit highest price sensitivity, while European sports facility operators absorb premiums for REACH-compliant material disclosure.
Supply Chain Analysis
Direct-to-municipal channels handle volume procurement for Chinese smart city deployments, bypassing traditional electrical distributors. Manufacturing concentrates in China, Germany, and Mexico, with Yangtze River Delta clusters dominating ferrite core winding and semiconductor integration. Production draws from copper cathode, ferrite powder, and silicon steel inputs, with semiconductor content rising in electronic architectures. Single-source vulnerability concentrates in rare-earth ferrite suppliers serving high-frequency switching circuits. Distribution runs through electrical infrastructure distributors in North America and direct manufacturer relationships in Chinese provincial tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HID ballast manufacturing is consolidating around upstream semiconductor integration and downstream service revenue capture, with ballast-as-a-service models reshaping competitive economics. Players lacking either captive component sourcing or networked control platform capabilities face margin compression.
For Market Incumbents: To counter LED substitution pressure in warehouse and industrial verticals, accelerate ceramic metal halide driver development for precision retail applications where color rendering requirements sustain HID relevance. Secure backward integration into ferrite core manufacturing to insulate cost structures from commodity volatility, while embedding powerline communication capabilities to capture recurring monitoring revenue streams.
For New Entrants and Emerging Players: Smart ballast protocol standardization gaps present entry vectors for DALI-integrated platforms targeting Indian manufacturing corridor electrification under CEA grid expansion programs. Prioritize BIS certification pathways for electronic architectures in Gujarat and Maharashtra logistics hubs, with direct sales to industrial facility operators bypassing established distributor relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor semiconductor-integrated mid-tier suppliers in Chinese Yangtze River Delta manufacturing clusters facing export specification recalibration costs. Long-term viability hinges on service revenue attachment rates and smart city platform consolidation. Monitor MIIT standardization announcements for provincial purchasing platform authorization as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite Core Manufacturing | Captive ferrite sourcing insulates margin structures from commodity volatility in magnetic ballast production. |
| Smart Ballast Platform Certification | MIIT-backed DALI protocol standardization unlocks provincial-scale municipal procurement in Chinese smart cities. |
| Ceramic Metal Halide Driver Specialization | Precision color rendering capabilities command pricing premiums in European sports facility and luxury retail segments. |
| Service Revenue Attachment Models | Remote monitoring subscriptions transform transactional hardware sales into recurring revenue streams. |
| BIS Certification Investment for India Entry | CEA grid expansion programs create procurement windows for certified electronic ballast suppliers in manufacturing corridors. |
Study Parameters
Document review covered regulatory filings from DOE, SAMR, and ECHA, complemented by interviews with electrical infrastructure procurement managers, municipal lighting engineers, ballast manufacturing plant directors, and distribution channel partners. Secondary validation drew from customs trade data, SEC 10-K disclosures, and MIIT standardization bulletins. Bottom-up demand modeling across installation types and top-down supply capacity assessments were triangulated against efficiency mandate implementation timelines.
Historical shipment data was cross-referenced against expert panel input on technology transition velocity. The analytical framework modeled product architecture, end-user vertical, lamp technology alignment, and application environment across the projection horizon. CAGRs were derived from segment-level demand build-ups incorporating regulatory phaseout schedules and retrofit cycle assumptions. Forecast inputs included copper price trajectory scenarios and smart city infrastructure investment disbursement patterns.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments, breakthrough LED cost reductions, and geopolitical disruptions to ferrite supply chains. Forecasts reflect documented assumptions on efficiency standard enforcement timelines and municipal procurement authorization procedures. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Electrical Steel Coatings Market
Electrical Equipment
Global General Purpose Contactor Market
Electrical Equipment
Vacuum Interrupter Market
Electrical Equipment
Magnetic Shielding Device Market
Electrical Equipment
Current Clamps Market
Electrical Equipment
Ultra High Voltage (UHV) Appliances Market
Electrical Equipment
Electric Motors for Conveyor System Market
Electrical Equipment
Cable Distribution Cabinets Market
Electrical Equipment
Axial Fans Market
Electrical Equipment
Electrical Enclosures Market
Electrical Equipment
Electrical Measuring Instrument Market
Electrical Equipment
United States Electric Insulator Market
Electrical Equipment
Heat Shrink Terminations Market
Electrical Equipment
Slip Ring Market
Electrical Equipment
Medium Voltage Transformer Market
Electrical Equipment
Europe Circuit Breakers Market