
 Waveguide Market | 2026-2036
Waveguide Market Size, Share, and Industry Trends Forecast 2026-2036
Waveguide Market Intelligence
Expertise in radio frequency engineering and high-precision microfabrication is rotating toward integrated photonics and substrate-integrated designs. CommScope Holding Company, Inc. leverages its extensive portfolio in telecommunications infrastructure to meet this shift. Mega Industries specializes in high-power microwave components for scientific and industrial applications, while Ducommun Incorporated positions itself with advanced solutions for the aerospace and defense sectors.
A waveguide is a physical structure designed to guide electromagnetic waves with minimal energy loss. Typically constructed from conductive metals like aluminum or copper, these hollow tubes operate above a specific cutoff frequency to support wave propagation. Rectangular waveguides remain a dominant product type, particularly for high-power radar systems. In terms of application, the telecommunications segment leads, but photonic waveguides are seeing rapid adoption in medical devices and consumer electronics.
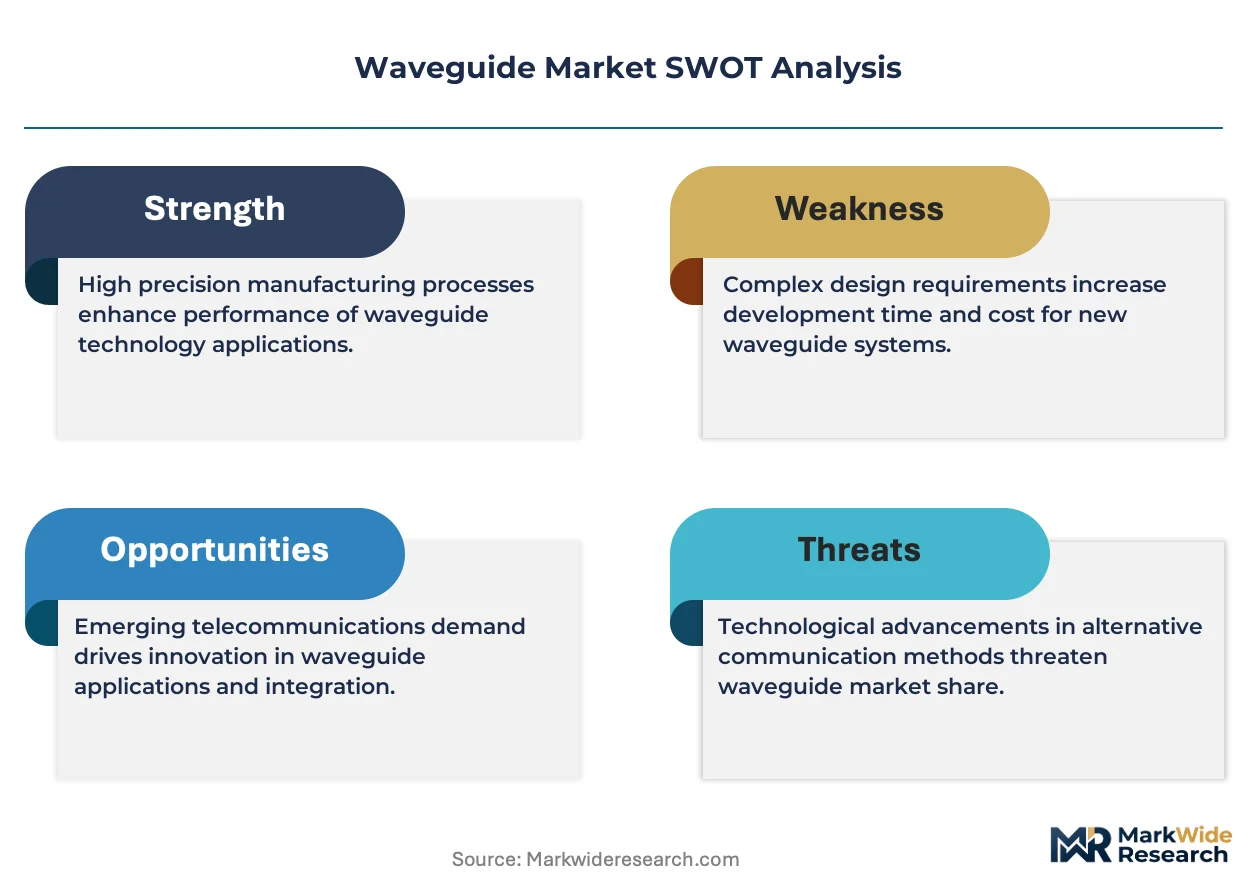
Spectrum allocation policies from bodies like the U.S. Federal Communications Commission (FCC) and China's Ministry of Industry and Information Technology (MIIT) directly influence component design for 5G and 6G. Adherence to CE marking requirements in Europe and military-grade specifications governs market access and product reliability standards for defense applications. Component manufacturers must now navigate a complex trade-off between performance at higher frequencies and the cost constraints of mass-market commercial deployments.
Market Dynamics
The imperative to support higher frequency bands for 5G, satellite communications, and emerging 6G networks is the central force shaping the waveguide market. This push toward millimeter wave spectra necessitates advances in materials and microfabrication to manage signal integrity and thermal loads.
Growth Catalysts
- Millimeter Wave Technology:The deployment of next-generation telecommunication networks depends on components that can efficiently handle high-frequency data transmission, creating sustained demand for advanced waveguides.
- LEO Satellite Constellations:The rapid expansion of low Earth orbit satellite networks for global internet access requires vast quantities of Ka-band and Ku-band waveguide components for ground stations and satellite payloads.
- China's 5G Expansion:Aggressive national policies from China's MIIT to build out 5G infrastructure and promote industrial automation create a concentrated zone of high-volume demand for waveguide assemblies.
Market Restraints
- Manufacturing Complexity:The high precision required for fabricating waveguides, especially for millimeter-wave frequencies, leads to high manufacturing costs and limits the pool of qualified suppliers.
- Signal Attenuation:At higher frequencies, inherent signal loss (insertion loss) becomes a significant technical barrier, complicating system design and often requiring more powerful or numerous components.
- Substitution from Photonics:For certain high-bandwidth, short-distance applications, silicon photonics and advanced optical fibers present a viable alternative, competing directly with traditional RF waveguide solutions.
Strategic Opportunities
- Automotive Radar Systems:The integration of advanced driver-assistance systems (ADAS) and the development of autonomous vehicles are driving demand for high-resolution automotive radar, opening a new high-volume application vertical.
- Substrate-Integrated Waveguides:The convergence of waveguide structures with standard printed circuit board (PCB) manufacturing processes offers a path to miniaturization and cost reduction for consumer electronics and IoT devices.
- Indian 5G Rollout:As India accelerates its 5G network deployment under frameworks established by the TRAI, it represents a significant future growth market for telecommunication infrastructure components.
Industry Challenges
- RF Engineering Talent Scarcity:A limited pool of radio frequency engineers with the specialized skills needed for high-frequency component design and simulation creates a bottleneck for product development and innovation.
- Navigating Global Standards:Manufacturers face complexity in adhering to a patchwork of standards, including FCC rules in the US, CE marking in Europe, and MIIT requirements in China.
- Legacy System Integration:In the defense sector, integrating new, high-frequency waveguide components into existing aerospace and naval platforms requires extensive and costly re-certification and testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waveguide Market |
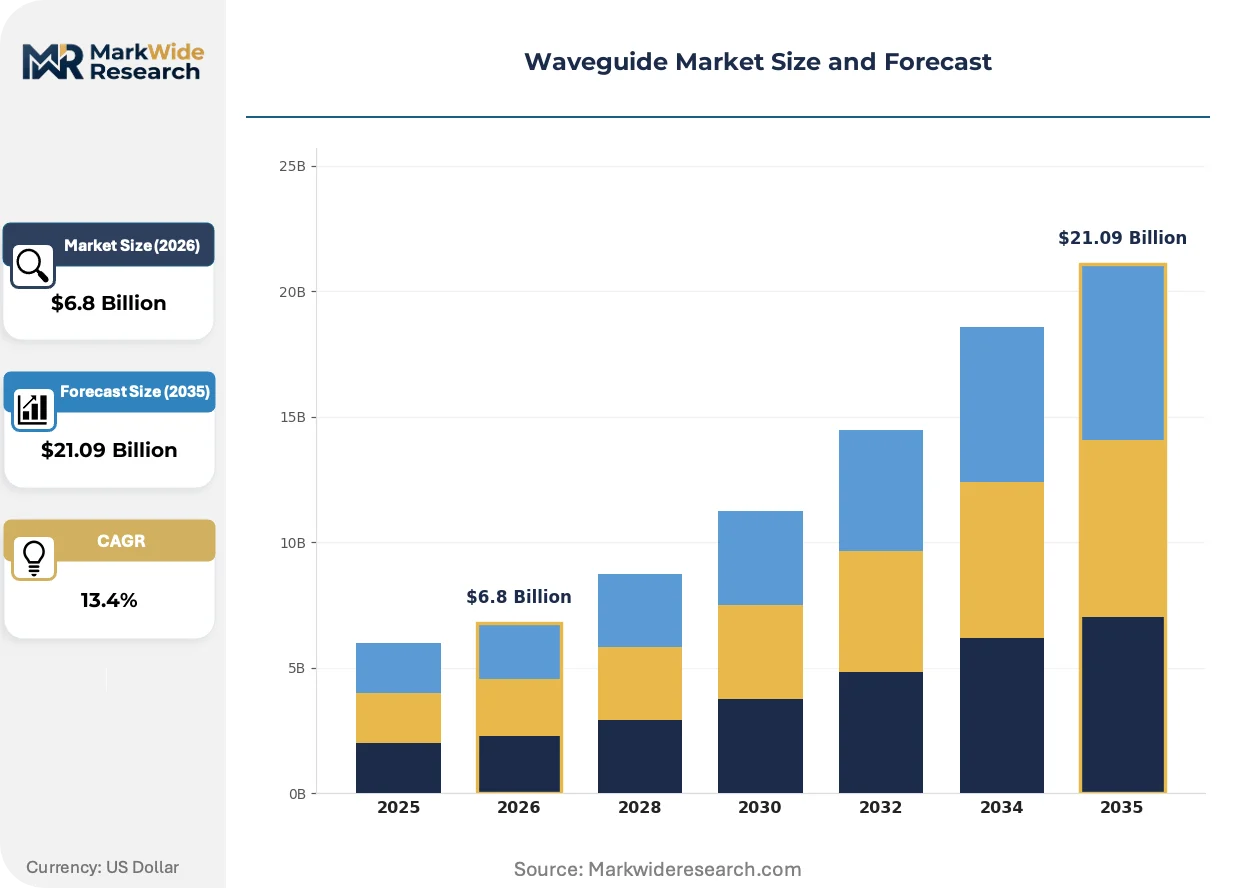
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.09 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rectangular Waveguide, Circular Waveguide, Optical Waveguide, Photonic Waveguide Technology: Millimeter Wave Technology, Optoelectronic Technology, Substrate Integrated Technology, Microfabrication Technology Application: Telecommunications, Aerospace & Defense, Medical Devices, Consumer Electronics End User: Telecom Operators, Military & Defense, Healthcare Providers, Electronics Manufacturers |
| Companies Covered | Eravant, Mega Industries, Ducommun Incorporated, Millimeter Wave Products, QuinStar Technology, CommScope Holding Company, Inc., Fairview Microwave, Raditek, Maury Microwave, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waveguide Market Strategic Shifts & Innovations
A fundamental shift from discrete, bulky components toward integrated and miniaturized solutions is redefining waveguide technology. This evolution prioritizes manufacturability and cost efficiency for mass-market applications without sacrificing performance at higher frequencies, especially for telecommunications and consumer electronics.
Substrate-integrated waveguide (SIW) technology embeds waveguide structures directly within a printed circuit board dielectric. The telecommunications and automotive sectors are adopting SIW for its significant cost and size advantages over traditional hollow metal guides. This adoption is bifurcating the market into high-power, hollow-metal components for radar and scientific use versus low-cost, integrated solutions for high-volume commercial products.
Spectrum allocation policies, such as the FCC's actions in the United States and MIIT's directives in China, are opening new millimeter-wave bands. This directly compels component manufacturers to design and test waveguides capable of operating efficiently at frequencies above 24 GHz. The aerospace and defense segment is most affected, needing to ensure new systems do not interfere with commercial bands while meeting stringent military-grade specifications.
A move toward platform-based procurement is altering how aerospace and defense contractors source components. This disrupts the traditional model of purchasing discrete parts, favoring suppliers who can deliver pre-integrated and pre-validated subsystems. This trend is most visible in the United States and Europe, where prime defense contractors seek to reduce system integration risk and accelerate development timelines.
Waveguide Market Segmentation
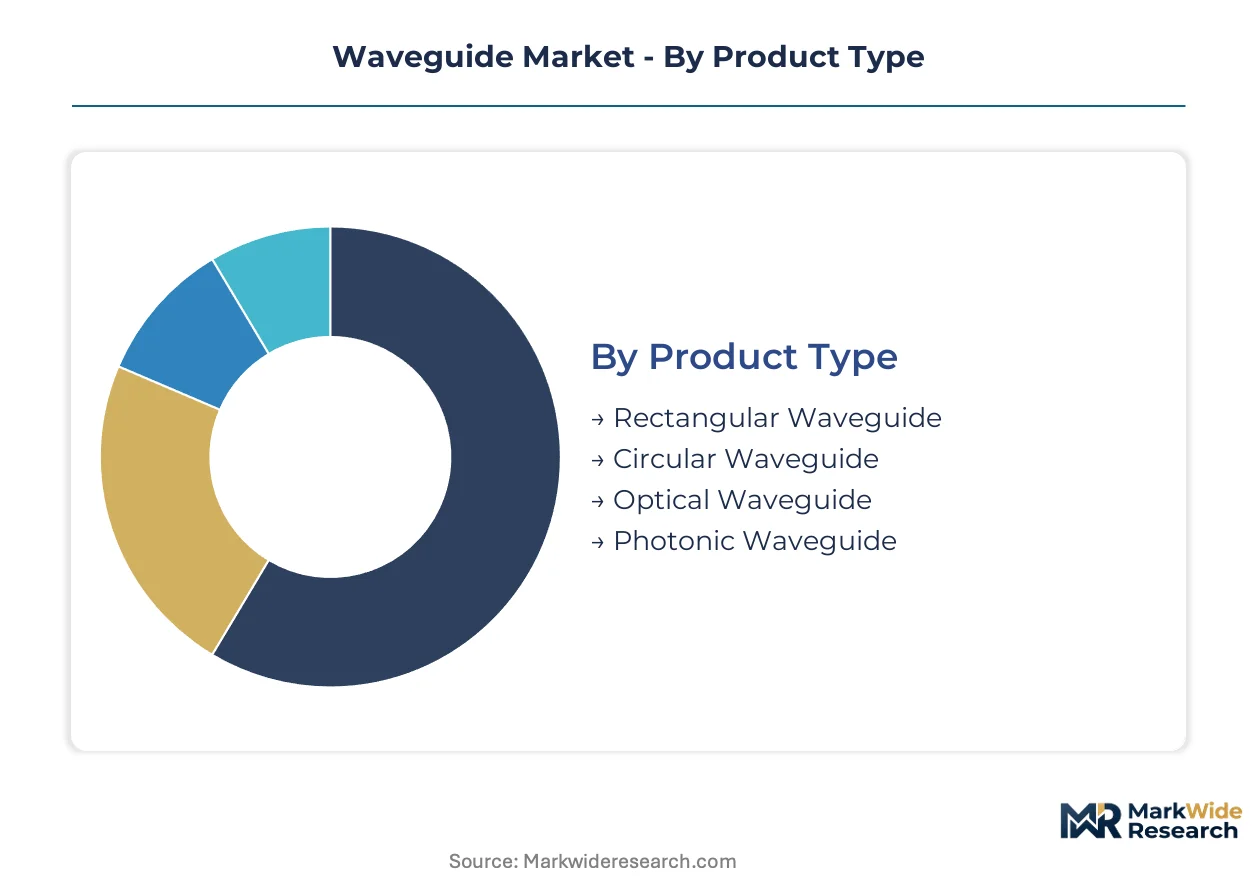
Understanding the waveguide market through granular segmentation reveals the diverse technological requirements and end-user demands shaping its evolution. This structured view highlights where innovation is concentrated and where established product types continue to dominate revenue streams.
Product Type:
Certain product types demonstrate strong export potential, while others primarily serve domestic infrastructure needs.
- Rectangular Waveguide:These are hollow metal tubes, typically constructed from conductive metals like aluminum or copper, designed to guide electromagnetic waves above a specific cutoff frequency. Demand concentrates in military radar systems and scientific research facilities due to their robust high-power handling capabilities in critical defense applications.
- Photonic Waveguide:Structures engineered to guide light, often fabricated from dielectric materials such as silicon or specialized polymers, enabling high-speed optical signal transmission. Demand is expanding rapidly in medical devices and consumer electronics for high-bandwidth, short-distance data transmission within integrated systems.
- Circular Waveguide:These guides feature a circular cross-section, frequently employed in rotating joints and specific antenna feeds for satellite communications and high-frequency radar systems.
- Optical Waveguide:Guiding structures specifically designed for optical signals, commonly found in fiber optic communication systems and advanced sensor applications where light manipulation is essential.
Rectangular Waveguide commands the established base. The steepest expansion runs through Photonic Waveguide.
Technology:
The technological landscape bifurcates between established methodologies and emerging innovations driving future market growth.
- Millimeter Wave Technology:This technology utilizes very high-frequency electromagnetic waves (above 24 GHz) for high-speed data transmission, crucial for next-generation wireless communication. Demand concentrates in telecommunications infrastructure, driven by the extensive deployment of 5G and emerging 6G networks across China and India.
- Substrate Integrated Technology:This involves embedding waveguide structures directly within printed circuit board (PCB) dielectric materials, enabling miniaturization, reduced weight, and cost-effective manufacturing. Demand is accelerating in consumer electronics and automotive radar systems due to significant size and cost advantages.
- Optoelectronic Technology:This combines optical and electronic components for signal processing, crucial for high-speed data centers, long-haul communication links, and advanced sensor integration.
- Microfabrication Technology:Precision manufacturing techniques used to create extremely small components and integrated circuits, essential for advanced sensors, high-frequency modules, and miniaturized waveguide designs.
Traditional Optoelectronic Technology maintains a stable presence. Substrate Integrated Technology is expanding most quickly in new deployments.
Application:
Applications vary significantly in their volume requirements, ranging from mass-market commercial deployments to highly specialized industrial uses.
- Telecommunications:This segment involves the transmission of voice, data, and video signals over wireless and wired networks, utilizing waveguides for base stations, antennas, and backhaul infrastructure. Demand concentrates in China and India, driven by aggressive 5G network build-outs and ongoing infrastructure upgrades under MIIT and TRAI directives.
- Aerospace & Defense:Waveguides are critical components for radar systems, satellite communication, electronic warfare, and missile guidance in aircraft, naval vessels, and ground-based platforms. Demand is concentrated in the United States and European defense sectors, driven by stringent military-grade specifications and continuous system modernization.
- Medical Devices:Waveguides facilitate precise signal delivery in diagnostic imaging equipment such as MRI machines, microwave ablation devices, and advanced therapeutic instruments, ensuring minimal energy loss.
- Consumer Electronics:Integrated waveguides support high-frequency wireless connectivity, sensing functions, and power delivery in devices like smartphones, smart home systems, and augmented reality headsets.
Telecommunications remains the largest application segment. Consumer Electronics is experiencing significant uptake reflecting new integration paradigms.
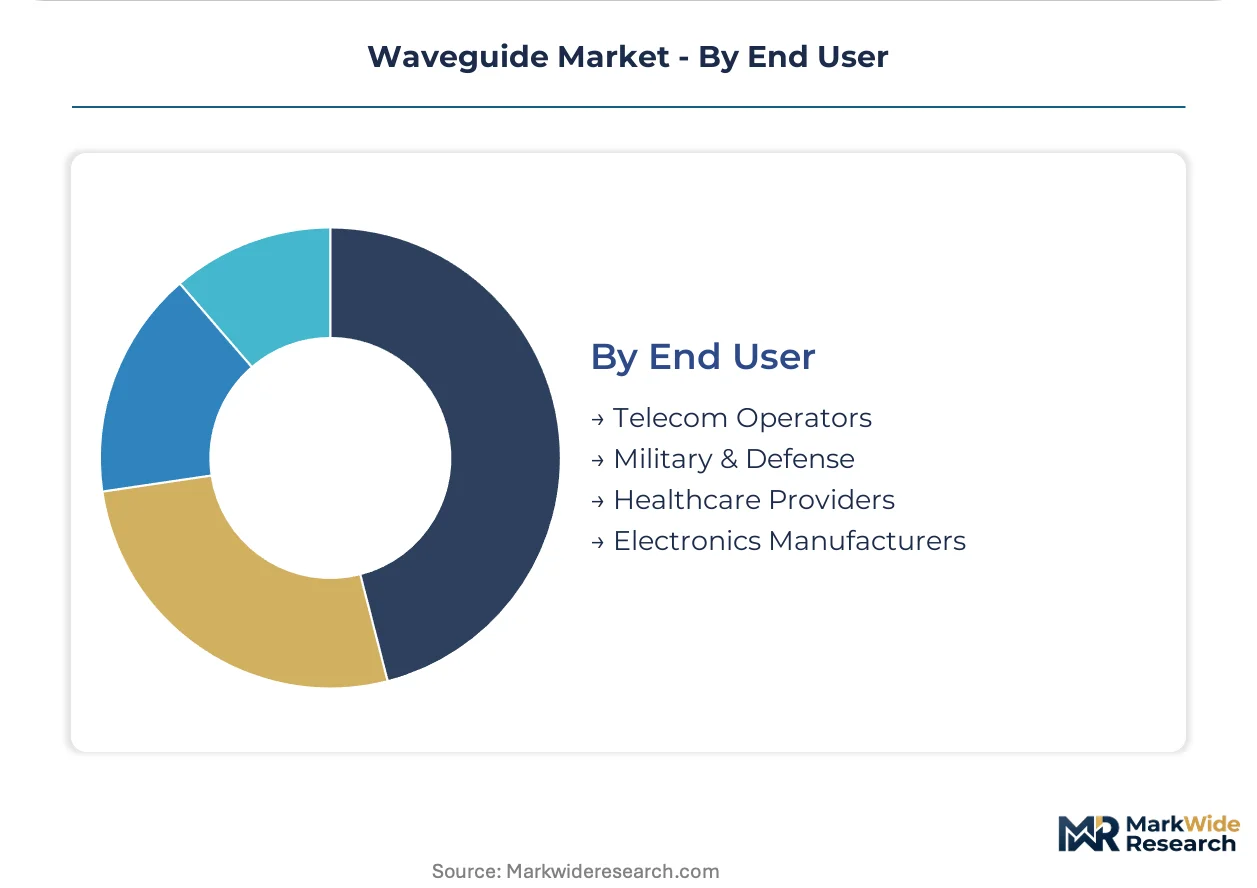
End User:
End-user segments exhibit diverse procurement patterns, with some prioritizing long-term strategic partnerships and others focusing on transactional efficiency.
- Telecom Operators:These companies deploy and manage extensive telecommunication networks, requiring waveguides for base stations, antennas, and backhaul infrastructure to support high-speed data transmission. Demand concentrates in countries with active 5G rollouts, such as China and India, due to large-scale network expansions and capacity upgrades.
- Military & Defense:Government defense agencies and their contractors procure waveguides for advanced radar, electronic warfare, and secure communication systems that demand extreme reliability and performance. Demand is concentrated in the US and European defense industries, driven by the need for high reliability and performance in critical applications.
- Healthcare Providers:Hospitals, clinics, and research institutions utilize waveguide components in sophisticated medical equipment, including diagnostic imaging systems and various therapeutic devices.
- Electronics Manufacturers:Companies producing consumer gadgets, industrial electronics, and automotive systems integrate waveguides for high-frequency connectivity, sensing capabilities, and power management within their products.
Telecom Operators represent a foundational customer base. Electronics Manufacturers are increasingly integrating waveguide components into new product lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ministry of Industry and Information Technology (MIIT) directives significantly influence the global waveguide market, particularly for 5G network expansion. These policies drive demand for advanced waveguide components across Asia. Other major economies also contribute through defense spending and telecommunications upgrades.
China
China's extensive 5G infrastructure build-out and industrial automation initiatives generate substantial demand for waveguide components. MIIT's aggressive national policies prioritize domestic development and deployment of next-generation communication technologies. The Yangtze River Delta region is a hub for telecommunications equipment manufacturing, driving high-volume waveguide assembly production for national and international markets.
India
India's accelerating 5G network deployment and the expansion of LEO satellite ground stations necessitate a wide range of waveguide solutions. The Telecommunications Regulatory Authority of India (TRAI) frameworks support this infrastructure expansion, creating new opportunities for component suppliers. Bengaluru's technology ecosystem supports specialized component development for network infrastructure and satellite communications.
United States
The United States aerospace and defense sector modernization, alongside significant investments in satellite communications, fuels demand for high-performance waveguides. U.S. Federal Communications Commission (FCC) spectrum allocation policies guide component design for both military and commercial applications. Silicon Valley and defense contractors in Southern California concentrate on high-frequency component design for military-grade systems.
Germany
Germany's market for waveguides is driven by high-power radar systems, industrial applications, and the burgeoning automotive radar sector. CE marking requirements ensure product safety and performance for industrial exports across Europe and beyond. Bavaria's industrial base develops precision waveguides for advanced manufacturing and automotive sensor integration.
Japan
Japan's focus on advanced telecommunications research, including emerging 6G networks, and precision instrumentation creates specific demand for innovative waveguides. METI initiatives support cutting-edge materials science and microfabrication techniques crucial for high-frequency applications. Tokyo's technology firms and research institutes focus on next-generation photonic waveguide development for high-speed data.
Waveguide Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the waveguide market. The market structure exhibits a tiered consolidation, with established players dominating high-value segments and newer entrants focusing on integrated solutions. Strategic archetypes include specialized high-power component manufacturers, large telecommunications infrastructure providers, and agile innovators in integrated photonics. Dominant competitive moves involve strategic partnerships for technology co-development and portfolio diversification into higher-frequency solutions.
Among specialized manufacturers, Mega Industries exemplifies expertise in high-power microwave components for scientific and industrial applications. Ducommun Incorporated occupies a position supplying advanced solutions for the demanding aerospace and defense sectors. CommScope Holding Company, Inc. represents a major telecommunications infrastructure provider, leveraging its extensive portfolio to address the shift towards integrated photonics. These companies anchor different segments of the market, reflecting diverse technological requirements and end-user demands.
| Leading Market Players |
|---|
| Eravant |
| Mega Industries |
| Ducommun Incorporated |
| Millimeter Wave Products |
| QuinStar Technology |
| CommScope Holding Company, Inc. |
| Fairview Microwave |
| Raditek |
| Maury Microwave |
| Others |
Cost & Logistics Intelligence
Photonic waveguide substitution for traditional metal guides reshapes manufacturing geography in Asia and redefines cost-plus pricing models. This dynamic shifts supply from high-precision metal fabrication to silicon foundries.
Pricing Analysis
Geographic price spreads for waveguides vary significantly, with higher costs in regions with stringent military specifications. The dominant pricing structure involves contract-based long-term offtake for defense and telecom, alongside per-unit transactional models for consumer electronics. Price differentiation stems from military-grade specifications, customization levels, and volume scale. Pricing pressure intensifies for high-frequency components due to manufacturing complexity, while consumer electronics manufacturers exhibit high price sensitivity.
Supply Chain Analysis
Inbound logistics costs, particularly for specialized raw materials from Asia, influence waveguide component availability and final pricing. Supply concentration for advanced waveguides centers on China, Japan, and the United States. Raw material dependencies include high-purity copper, aluminum alloys, and specialized dielectric materials. A structural risk involves single-source vulnerability for high-precision microfabrication foundries. Distribution runs through direct sales channels to large OEMs and system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The waveguide market presents a significant service-attach opportunity, with specialized calibration and integration support services expanding faster than core hardware sales. This recurring revenue stream enhances customer lifetime value for component manufacturers.
For Market Incumbents:Consolidate R&D efforts in integrated photonics and substrate-integrated designs to counter the threat of substitution from advanced optical fibers. Incumbents should acquire niche microfabrication specialists to control critical high-frequency component production. Investing in CE marking and military-grade certification processes secures market access. Vertical integration into specialized dielectric materials enhances supply chain resilience and cost control.
For New Entrants and Emerging Players:Certification fast-track pathways for automotive radar systems offer a strategic entry point for new waveguide manufacturers. Target the underpenetrated consumer electronics and IoT segments with cost-effective substrate-integrated waveguide solutions. Focus on rapid prototyping and design-for-manufacturability to meet aggressive product development cycles. Partnering with established PCB manufacturers provides an efficient go-to-market angle.
For Investors and Strategic Acquirers:FCC's millimeter-wave spectrum allocation reshapes the acquisition landscape, favoring companies with proven high-frequency component design capabilities. Long-term viability centers on firms enabling next-generation communication (5G/6G, LEO satellites) and autonomous systems. Target acquisition archetypes include specialists in proprietary microfabrication IP or those with established positions in automotive radar. The signal to watch is China's MIIT directives on 6G research and domestic supply chain mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Secures supply for growing 5G and automotive radar demand. |
| Technology Licensing | Accelerates market penetration for substrate-integrated waveguide solutions. |
| Joint Venture | Drives innovation in next-generation 6G network component designs. |
| Regulatory Approval Pathway | Unlocks access to European and defense markets for new products. |
| Portfolio Diversification | Captures new revenue streams in medical devices and consumer electronics. |
Research Approach
The analysis maps waveguide sub-sectors including telecommunications, aerospace & defense, and medical devices, each validated through interviews with industry experts. Primary research included discussions with RF engineers, procurement leads, and product development managers. Secondary validation drew from FCC filings, MIIT directives, military-grade specifications, and academic papers. This approach triangulated insights from bottom-up and top-down perspectives.
Forecast outputs underwent consistency checks against external benchmarks and historical market trends across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user, and regional policy frameworks. Compound annual growth rates were derived through regression analysis and market share projections. Key forecast inputs included 5G rollout schedules and LEO satellite deployment plans.
Underlying assumptions cover a stable regulatory environment and consistent technological advancement, with deviation risk concentrated in geopolitical trade tensions. Forecasts reflect these documented assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
HID Ballast Market
Electrical Equipment
Rotary and RF Rotary Joints Market
Electrical Equipment
Vacuum Interrupter Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
Global Dehydrating Breather Market
Electrical Equipment
US Industrial Ceiling Fan Market
Electrical Equipment
Current Clamps Market
Electrical Equipment
Low Voltage Circuit Breakers Market
Electrical Equipment
High Voltage PTC Heater Market
Electrical Equipment
MCB and MCCB Market
Electrical Equipment
Low Voltage Motor Control Centers Market
Electrical Equipment
Global Sealed DC Contactor Market
Electrical Equipment
Air Circuit Breaker Market
Electrical Equipment
North America Commercial Lighting Control Market
Electrical Equipment
Global Dehumidifier Market
Electrical Equipment
Global Busbar Market