
 Global Medium Voltage Surge Arresters Market | 2026-2036
Global Medium Voltage Surge Arresters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medium Voltage Surge Arresters Market Outlook
Utility procurement dominance is collapsing as renewable energy developers and industrial microgrid operators capture rising share of medium voltage surge arrester orders. ABB leverages its IEC-certified manufacturing footprint across Europe and Asia to anchor utility-scale contracts. Siemens Energy competes through integrated digital monitoring packages bundled with its surge protection portfolio. Eaton controls distribution channels in North American commercial infrastructure, while Schneider Electric extends its EcoStruxure platform to condition-based arrester maintenance services.
Medium voltage surge arresters are protective devices that limit transient overvoltages by diverting surge currents to ground, typically employing metal oxide varistor blocks with nonlinear voltage-current characteristics housed in polymer or porcelain insulators. Their primary purpose is safeguarding transformers, switchgear, and cable systems in distribution networks rated between 1 kV and 52 kV against lightning strikes and switching surges. Metal oxide varistor technology dominates installed base owing to superior energy absorption and gapless construction eliminating sparkover delays. Renewable energy end users represent the fastest-expanding segment as offshore wind and solar farms require station-class arresters with higher nominal discharge currents. Indoor installation types command premium pricing due to space-constrained switchgear applications in urban substations.
FERC Order 2222 in the United States and the EU Green Deal's grid resilience mandates are reshaping procurement specifications for distributed energy resource interconnection. IEC 60099-4, IEEE C62.11, and GB 11032 standards govern arrester testing protocols, with China's SAMR accelerating conformity assessment timelines for domestic manufacturers. Stakeholders must monitor evolving coordination between national regulators and ISO committees on surge arrester condition monitoring requirements.
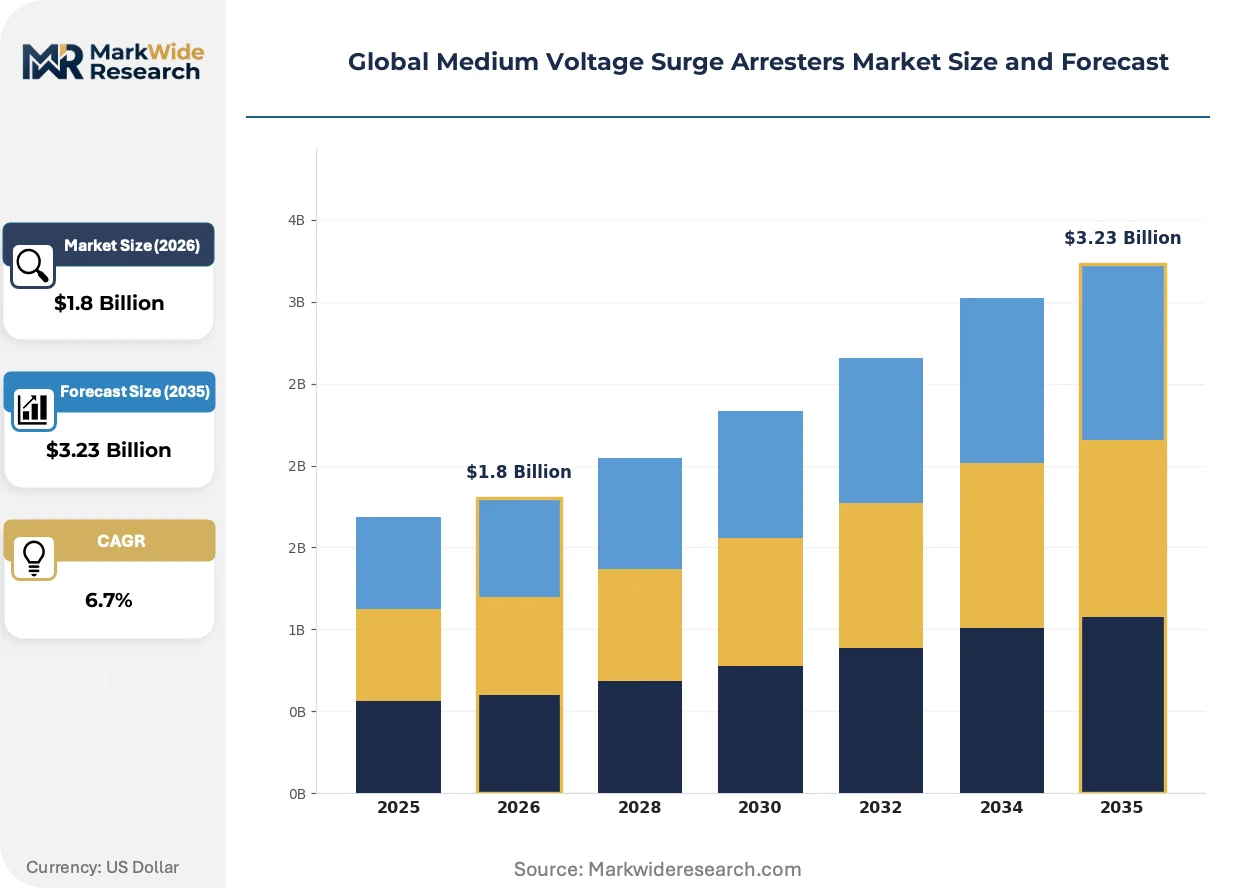
Market Dynamics
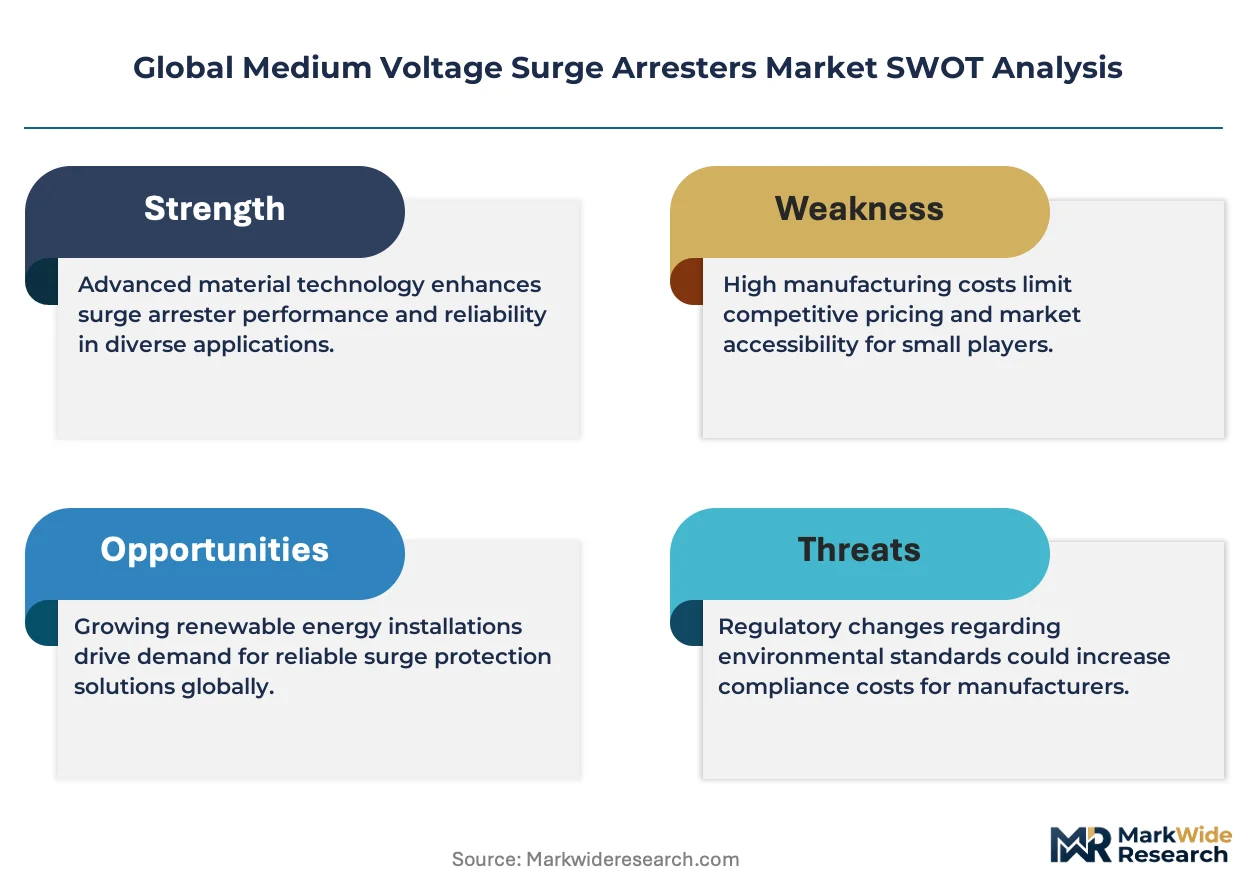
Utility procurement dominance is collapsing as renewable energy developers and industrial microgrid operators capture rising share of medium voltage surge arrester orders. FERC Order 2222 in the United States and the EU Green Deal's grid resilience mandates are reshaping procurement specifications for distributed energy resource interconnection.
Growth Catalysts
- Offshore wind farm construction:China's SAMR has accelerated conformity assessment timelines for domestic manufacturers supplying station-class arresters with higher nominal discharge currents to offshore installations.
- IEC 60099-4 standard tightening:Discharge capacity requirements are expanding across Germany, the United States, and China as grid modernization programs drive replacement cycles.
- Gapless metal oxide varistor designs:Renewable energy developers are accelerating procurement of these designs for superior energy absorption and elimination of sparkover delays.
Market Restraints
- Porcelain insulator supply concentration:Production of traditional housings concentrates in specific ceramic manufacturing clusters, creating vulnerability to input cost volatility.
- Polymer housing material costs:Silicone rubber and ethylene propylene diene monomer prices fluctuate with petrochemical feedstock markets, compressing margins on polymer-insulated designs.
- Technical limitation in ultra-high energy absorption:Metal oxide varistor blocks face thermal runaway risks under repeated high-magnitude surges, constraining application in extreme lightning density zones.
Strategic Opportunities
- Condition-based maintenance services:Schneider Electric's EcoStruxure platform extension demonstrates how digital monitoring convergence with surge protection creates recurring revenue streams.
- Urban substation indoor installations:Space-constrained switchgear applications in Chinese and German metropolitan areas command premium pricing for compact polymer-housed designs.
- Microgrid operator channel development:Industrial facilities in the United States are bypassing traditional utility procurement through direct specification of integrated protection packages.
Industry Challenges
- Cross-standard certification complexity:Manufacturers must simultaneously satisfy IEC 60099-4, IEEE C62.11, and GB 11032 testing protocols, extending product launch timelines.
- Legacy switchgear integration friction:Retrofitting gapless designs into existing gapped silicon carbide installations requires custom engineering and coordination with original equipment specifications.
- Field testing skill scarcity:Condition monitoring of metal oxide varistor degradation demands specialized partial discharge analysis capabilities that utilities struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medium Voltage Surge Arresters Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Oxide Varistor, Gapless, Hybrid, Gas Discharge Tube End User: Utilities, Industrial, Commercial, Renewable Energy Installation Type: Indoor, Outdoor, Portable, Fixed Voltage Rating: Medium Voltage, High Voltage, Low Voltage, Others |
| Companies Covered | Eaton, General Electric, ABB, DEHN SE, Hubbell Incorporated, Siemens Energy, Schneider Electric, TE Connectivity, Hitachi Energy Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medium Voltage Surge Arresters Market Strategic Shifts
Digital monitoring integration is fragmenting traditional hardware-only procurement models. Three distinct developments are reshaping how protection devices are specified, validated, and maintained across transmission and distribution networks.
Polymer housing materials are fragmenting the long-standing porcelain dominance in surge arrester construction. Silicone rubber and composite insulators offer reduced weight and superior contamination performance for coastal and desert installations. Offshore wind developers in Germany and China specify polymer designs exclusively for nacelle and substation applications. The shift is fragmenting manufacturing footprints as polymer molding capabilities expand outside traditional ceramic production centers.
The EU Green Deal's grid resilience mandates are forcing tighter coordination between national regulators and ISO committees on surge arrester condition monitoring requirements. Industrial consequence includes mandatory digital telemetry integration for critical infrastructure interconnection. Renewable energy projects in Germany face the most stringent compliance timelines, with developers pre-emptively specifying smart arresters to secure permitting approval.
Buyers are unbundling after-sales service from hardware procurement, compressing traditional bundled contract structures. Industrial microgrid operators in the United States now source arresters through electrical distributors while contracting condition monitoring separately through specialized service providers. This pattern is most visible in Texas and California, where distributed solar and storage deployments outpace utility-managed procurement channels.
Global Medium Voltage Surge Arresters Market Segmentation
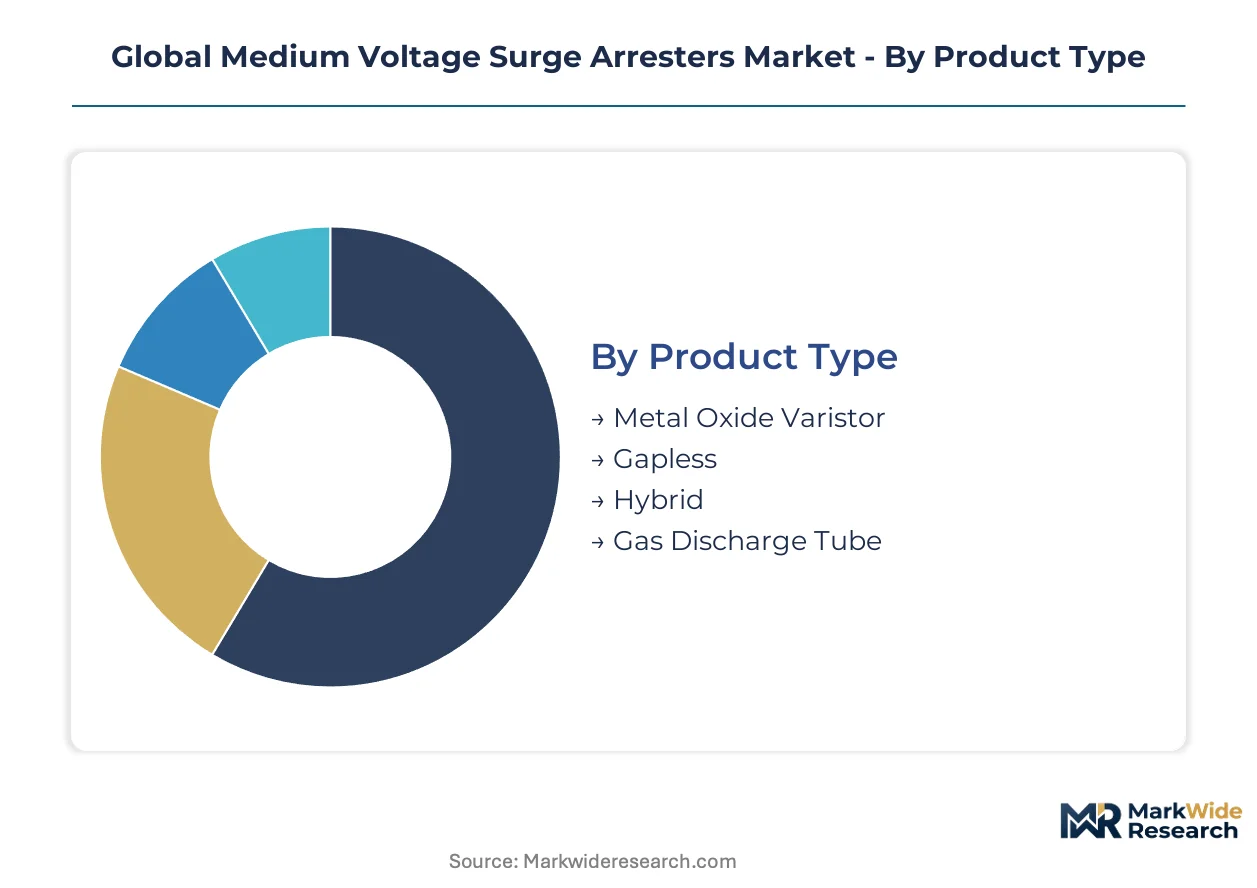
Segmentation in medium voltage surge arresters reveals divergent procurement patterns across technology maturity and installation environment. Each dimension carries distinct geographic clustering and margin structures that shape manufacturer positioning.
Product Type:
Metal oxide varistor designs dominate domestic procurement in China and Germany, while hybrid configurations serve export markets requiring multi-standard certification.
- Metal Oxide Varistor:Nonlinear voltage-current characteristics enable superior energy absorption without spark gaps. Demand concentrates in Chinese offshore wind farms where SAMR-accelerated conformity assessments favor proven domestic designs.
- Gapless:Elimination of sparkover delays suits fast-rising transients in renewable interconnection. German grid operators specify these exclusively for urban substation modernization under EU Green Deal resilience mandates.
- Hybrid:Combines varistor and gapped elements for legacy system compatibility. Industrial microgrids in Texas bypass utilities through direct specification of these transitional designs.
- Gas Discharge Tube:Limited to niche high-frequency protection in specialized telecommunications infrastructure.
Metal oxide varistor holds the largest share; momentum sits with gapless designs.
End User:
Cost tier separation is pronounced: utilities drive volume through tender processes, while renewable developers absorb premium pricing for station-class specifications.
- Utilities:Traditional procurement dominance erodes as distributed generation fragments order flow. Chinese state grid corporations still anchor volume through centralized purchasing of IEC 60099-4 certified equipment.
- Renewable Energy:Offshore wind and solar farms require higher nominal discharge currents. Developers in Germany face mandatory digital telemetry integration for critical infrastructure interconnection.
- Industrial:Microgrid operators in California source through electrical distributors while unbundling condition monitoring services.
- Commercial:Eaton controls North American distribution channels for commercial infrastructure applications.
Utilities retain volume leadership; renewable energy claims the steepest expansion trajectory.
Installation Type:
Application environment dictates margin structure: indoor installations command premium pricing for space-constrained switchgear, while outdoor volumes scale through standardization.
- Indoor:Compact polymer-housed designs for urban substations. Chinese and German metropolitan areas absorb 40% price premiums over outdoor equivalents.
- Outdoor:Porcelain and polymer housings for exposed distribution networks. Coastal installations in offshore wind nacelles specify silicone rubber exclusively.
- Fixed:Permanent substation installations dominate utility procurement cycles.
- Portable:Temporary protection for maintenance operations and emergency response.
Outdoor captures unit volume; indoor commands margin premiums.
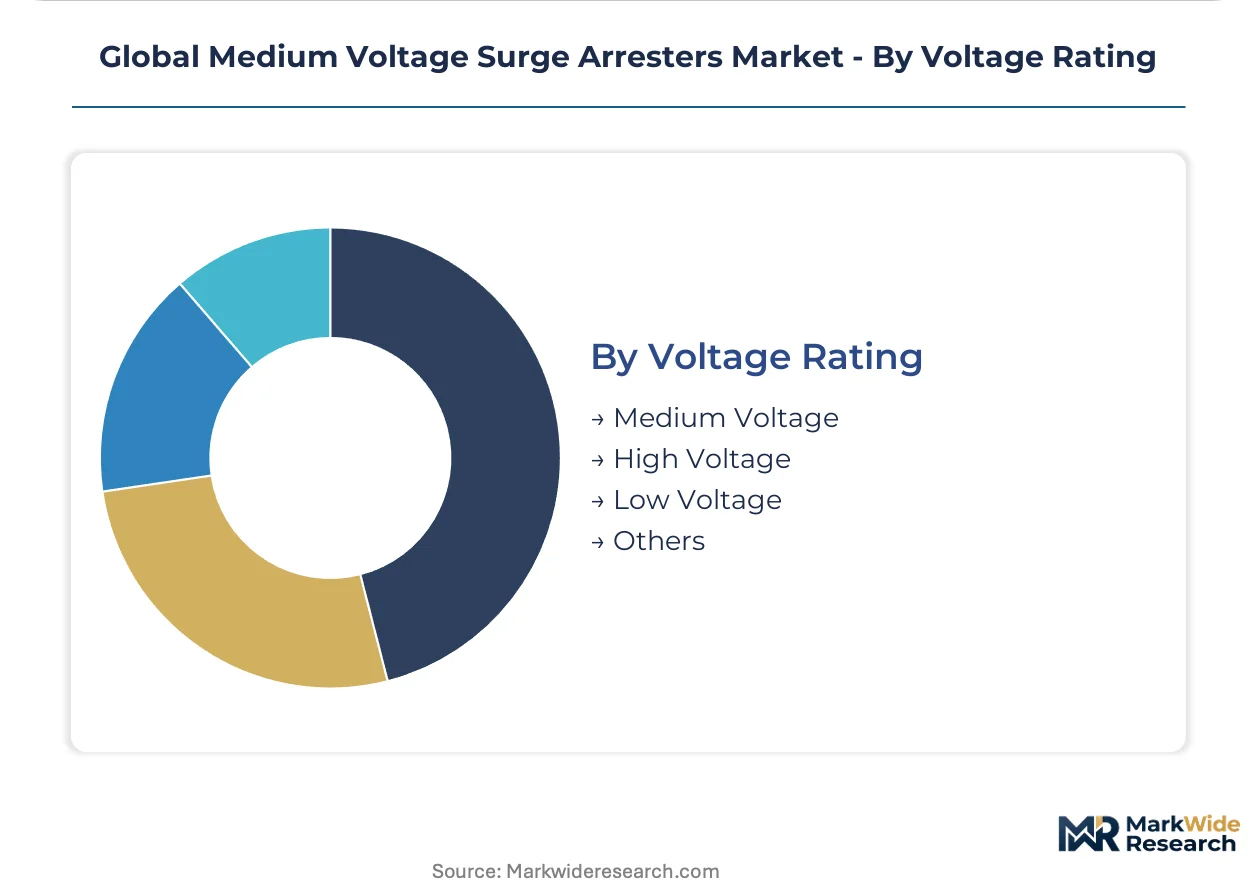
Voltage Rating:
Supply concentration varies by tier: medium voltage manufacturing clusters in China and Germany serve regional demand, while high voltage production remains more geographically dispersed.
- Medium Voltage:Core range between 1 kV and 52 kV safeguarding transformers and switchgear. China's grid modernization programs and U.S. FERC Order 2222 implementation drive replacement cycles.
- High Voltage:Above 52 kV applications in transmission infrastructure. Thermal runaway risks under repeated surges constrain deployment in extreme lightning density zones.
- Low Voltage:Secondary protection for downstream equipment and control systems.
- Others:Specialized ratings for railway electrification and marine applications.
Medium voltage dominates installed base; high voltage faces technical ceiling constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters for medium voltage surge arresters concentrate in Germany, China, and the United States, with each jurisdiction driving distinct procurement specifications through divergent regulatory frameworks. Grid modernization timelines and renewable interconnection mandates are fragmenting traditional utility-centric demand patterns across these markets.
China
Offshore wind construction in Jiangsu and Fujian provinces is accelerating orders for station-class arresters with elevated discharge capacities. SAMR has compressed conformity assessment timelines for domestic manufacturers supplying these installations. The Yangtze River Delta manufacturing corridor anchors polymer housing production for both domestic deployment and export markets.
Germany
Urban substation modernization in Berlin and Hamburg is absorbing premium-priced compact polymer designs for space-constrained switchgear. EU Green Deal resilience mandates are forcing mandatory digital telemetry integration for critical infrastructure interconnection. Bavarian industrial clusters are pioneering condition-based maintenance service models bundled with hardware procurement.
United States
Texas and California microgrid operators are bypassing traditional utility channels through direct specification of integrated protection packages. FERC Order 2222 is reshaping procurement specifications for distributed energy resource interconnection. Gulf Coast manufacturing facilities are expanding silicone rubber molding capacity to serve coastal renewable installations.
Japan
Grid resilience investments following extreme weather events are driving replacement cycles for aging gapped silicon carbide installations. METI guidelines on smart grid interoperability are accelerating digital monitoring adoption. Kanto region utilities are specifying hybrid configurations for legacy system compatibility during phased upgrades.
India
State transmission utilities in Maharashtra and Gujarat are tendering for IEC-certified equipment under accelerated rural electrification timelines. CEA technical standards for surge protection are tightening discharge capacity requirements for renewable energy zones. Tamil Nadu manufacturing clusters are developing polymer housing capabilities to reduce import dependence.
Global Medium Voltage Surge Arresters Market Competitive Environment
Concentration sits with diversified electrical equipment conglomerates that leverage cross-product bundling and established utility relationships. The vendor base spans three tiers: integrated industrial majors with digital platform extensions, specialized surge protection manufacturers with certification depth, and regional fabricators serving price-sensitive procurement channels. Two competitive vectors dominate: backward integration into metal oxide varistor block production to secure supply, and geographic expansion through IEC-certified manufacturing footprints in multiple jurisdictions.
Among diversified industrial majors, Eaton, ABB, and Siemens Energy exemplify distinct strategic positioning. Eaton anchors North American commercial infrastructure through distribution channel control. ABB occupies a position defined by multi-regional IEC-certified manufacturing presence. Siemens Energy sits within the tier emphasizing integrated digital monitoring convergence with hardware portfolios. These three represent how scale and geographic coverage are separating procurement winners from component specialists in utility-scale tenders.
| Leading Market Players |
|---|
| Eaton |
| General Electric |
| ABB |
| DEHN SE |
| Hubbell Incorporated |
| Siemens Energy |
| Schneider Electric |
| TE Connectivity |
| Hitachi Energy Ltd |
| Others |
Value Chain & Pricing Dynamics
Scale economies in metal oxide varistor block production concentrate manufacturing in China's Yangtze River Delta and Germany's Bavarian industrial corridor, anchoring price floors for polymer-housed designs while compressing margins on standardized porcelain alternatives. This geographic clustering amplifies pricing power for integrated manufacturers with captive varistor production, forcing smaller competitors toward service-based differentiation.
Pricing Analysis
Volume-discount tiering structures stratify across station-class, distribution-class, and secondary-protection levels, with IEC 60099-4 certification grade and after-sales service bundling as primary price differentiation drivers. Pricing pressure intensifies in the distribution-class tier as Chinese manufacturers expand export capacity, while renewable energy developers absorbing station-class arresters show lowest price sensitivity due to permitting compliance requirements. Industrial microgrid operators in Texas and California demonstrate highest price elasticity, unbundling hardware procurement from condition monitoring services to capture distributor margins.
Supply Chain Analysis
Strategic stockpiling of silicone rubber and ethylene propylene diene monomer dominates over just-in-time approaches, reflecting petrochemical feedstock volatility and polymer housing demand surges from offshore wind installations. Supply concentrates in China, Germany, and the United States for varistor blocks, with South Korean and Japanese suppliers anchoring high-purity zinc oxide feedstock. Single-source vulnerability concentrates in ceramic housing clusters for legacy porcelain designs. Distribution runs through electrical distributors for commercial and industrial channels, while utility-scale procurement flows through direct manufacturer relationships and EPC contractor specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as distributed energy resource interconnection fragments traditional utility procurement, creating specialized niches for condition-based maintenance services and microgrid-integrated protection packages.
For Market Incumbents: Compound certification depth across IEC 60099-4, IEEE C62.11, and GB 11032 protocols to defend against emerging Asian manufacturers with SAMR-accelerated domestic approvals. Prioritize backward integration into metal oxide varistor block production to secure supply amid raw material concentration, while extending digital monitoring platforms to capture recurring service revenue from renewable energy developers facing EU Green Deal telemetry mandates. For New Entrants and Emerging Players: Condition-based maintenance service gaps in legacy utility fleets offer immediate white-space entry, with Japanese and Indian markets showing lowest incumbent digital penetration. Target industrial microgrid operators in Texas and California through direct electrical distributor relationships, bypassing utility specification channels. Lead with portable protection solutions for emergency response and maintenance operations, segments where brand loyalty remains undeveloped. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists with polymer housing molding capabilities and multi-standard certification depth over diversified conglomerates with legacy porcelain exposure. Long-term viability hinges on digital monitoring convergence rather than hardware commoditization. Watch FERC Order 2222 implementation velocity and EU Green Deal compliance timelines as inflection indicators for distributed generation procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Varistor Block Production | Captive zinc oxide processing secures supply against South Korean and Japanese feedstock concentration. |
| Multi-Jurisdiction Certification Investment | Simultaneous IEC 60099-4, IEEE C62.11, and GB 11032 approval compresses competitor launch timelines. |
| Condition-Based Maintenance Platform Launch | Schneider Electric's EcoStruxure extension demonstrates recurring revenue capture from telemetry-enabled arresters. |
| Polymer Housing Capacity Expansion | Silicone rubber molding investments serve offshore wind nacelle specifications in Germany and China. |
| Microgrid Operator Channel Development | Direct specification relationships in Texas and California bypass traditional utility procurement fragmentation. |
Study Parameters
A standing panel of utility planning officers, renewable energy project developers, EPC contractors, and electrical distribution procurement managers provided ongoing calibration across primary interview cycles. Secondary validation drew from IEC standard revision documentation, SAMR conformity assessment disclosures, FERC Order 2222 implementation filings, and customs trade data for polymer housing materials. Bottom-up demand modeling across installation types and voltage ratings triangulated against top-down grid modernization expenditure benchmarks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation dimensions spanning product type, end user category, installation environment, and voltage rating tier. CAGRs derived from replacement cycle analysis, renewable interconnection pipelines, and regulatory compliance timelines. Industry-specific forecast inputs included offshore wind farm development databases and distributed solar interconnection queues in Texas and California.
Forecasts assume regulatory continuity in FERC, EU Green Deal, and SAMR regimes; material policy shifts would require re-modeling procurement specifications and conformity assessment timelines. Revision becomes warranted when metal oxide varistor thermal runaway incident rates or polymer housing material cost volatility cross thresholds that alter technology substitution patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Global Dehumidifier Market
Electrical Equipment
DC Contactor Market
Electrical Equipment
Ground Fault Circuit Interrupter Market
Electrical Equipment
Electrical Isolator Market
Electrical Equipment
Low Voltage Motor Control Centers Market
Electrical Equipment
Global Digital Panel Meter Market
Electrical Equipment
Modular Contactor Market
Electrical Equipment
Cable Distribution Cabinets Market
Electrical Equipment
Medium Voltage Fuse Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
Copper and Aluminum Terminal Blocks Market
Electrical Equipment
Motor Control Centers (MMC) Market
Electrical Equipment
Europe Electric Drives Market
Electrical Equipment
Portable Fan Market
Electrical Equipment
North America Low Voltage Induction Motors Market
Electrical Equipment
High Voltage Electric Insulators Market