
 ESD Suppressors Market | 2026-2036
ESD Suppressors Market Size, Share, and Industry Trends Forecast 2026-2036
ESD Suppressors Market Foresight
Distributor consolidation across Asia-Pacific is rewriting component availability dynamics for ESD suppressor procurement. Littelfuse leverages captive silicon foundry partnerships to secure die supply for high-reliability automotive grades. Vishay Intertechnology anchors European demand through its broad varistor portfolio serving industrial automation OEMs. Murata Manufacturing specializes in multilayer ceramic-based TVS arrays for smartphone board-level protection.
ESD suppressors are transient voltage protection devices engineered to clamp electrostatic discharge pulses within nanosecond response times, typically exhibiting breakdown voltages from 3.3 V to 450 V depending on application requirements. Their primary purpose is safeguarding integrated circuits and sensitive semiconductors from catastrophic failure during human-body-model discharge events. TVS diodes command the largest revenue share among product types due to their established use in high-speed data line protection, while gallium nitride technology is gaining traction in telecommunications infrastructure where lower capacitance specifications enable 5G millimeter-wave signal integrity. Silicon-based solutions still dominate automotive devices applications where AEC-Q101 qualification requirements create high barriers to material substitution.
FCC Part 15 emissions rules in the United States and EU Electromagnetic Compatibility Directive 2014/30/EU both mandate ESD immunity compliance for electronic equipment market access, directly shaping suppressor performance thresholds. China's GB/T 17626.2 standard, administered by the Standardization Administration of China, aligns with IEC test methodologies while adding domestic certification layers for locally manufactured consumer electronics. Automotive OEMs and telecommunications providers must monitor how evolving wide-bandgap semiconductor roadmaps reshape clamping speed requirements across hybrid protection architectures.
Market Dynamics
Automotive electrification is compressing qualification timelines for silicon-based transient voltage suppression, forcing suppliers to synchronize AEC-Q101 certification cycles with EV platform launches from Detroit to Stuttgart to Shanghai.
Growth Catalysts
- IEC 61000-4-2 Test Level Escalation:Tighter ESD immunity thresholds for consumer electronics are mandating higher-performance clamping devices across smartphone and wearable supply chains.
- EV Powertrain Electronics Proliferation:Battery management systems and inverter controls require dedicated protection arrays, pulling demand from traditional internal combustion applications.
- China Semiconductor Packaging Expansion:Domestic backend capacity growth is shortening procurement lead times for board-level TVS diode integration.
Market Restraints
- Silicon Wafer Cost Volatility:Foundry pricing fluctuations for 200mm and 300mm substrates compress margin structures for discrete protection component manufacturers.
- Single-Source Gallium Nitride Epiwafer Supply:Concentrated substrate production creates vulnerability for telecommunications-grade low-capacitance suppressor development.
- Wide-Bandgap Material Substitution Ceiling:Silicon carbide protection devices face thermal coefficient mismatches that limit adoption in high-temperature automotive underhood environments.
Strategic Opportunities
- India Electronics Manufacturing Incentives:PLI scheme subsidies for mobile phone and component production are creating localized demand for multilayer ceramic TVS arrays.
- 5G Millimeter-Wave Infrastructure Deployment:Base station radio units require sub-0.5 pF capacitance specifications that favor advanced compound semiconductor protection architectures.
- EU Battery Regulation Traceability Mandates:Supply chain documentation requirements favor qualified second-source suppressor suppliers with established automotive certification portfolios.
Industry Challenges
- AEC-Q101 Rev-E Qualification Timeline Compression:Extended high-temperature reverse bias testing cycles conflict with 18-month EV platform development windows.
- Legacy Automotive 12V System Integration:Mixed-voltage architectures require suppressor portfolios spanning 3.3V to 450V breakdown ranges, complicating inventory and design support.
- Cross-Domain EMC Engineering Talent Scarcity:Shortage of specialists fluent in both IC-level ESD protection and system-level electromagnetic compatibility verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ESD Suppressors Market |
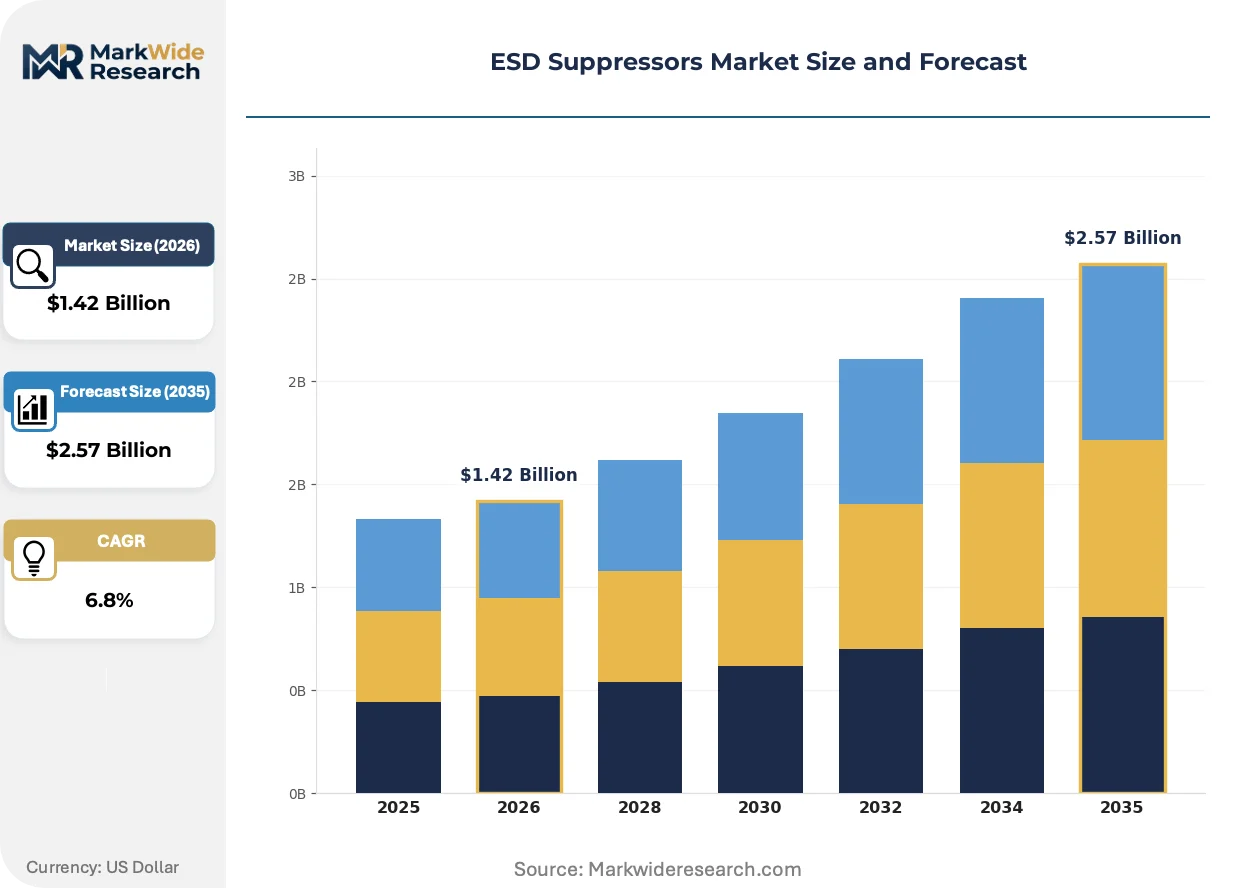
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TVS Diodes, Varistors, TVS Arrays, Filters Application: Consumer Electronics, Industrial Equipment, Automotive Devices, Telecommunications End User: Electronics Manufacturers, Automotive OEMs, Telecommunication Providers, Industrial Users Technology: Silicon, Gallium Nitride, Hybrid Solutions, Others |
| Companies Covered | Littelfuse, Nexperia, Vishay Intertechnology, ON Semiconductor, STMicroelectronics, Texas Instruments, Murata Manufacturing, TDK Corporation, Bourns, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ESD Suppressors Market Shifts & Advancements
Material science advances and qualification protocol evolution are redefining performance benchmarks across automotive, telecommunications, and consumer electronics verticals.
Silicon-based TVS diode technology is migrating from standard capacitance specifications toward sub-picofarad designs for high-speed data line integrity. Telecommunications infrastructure OEMs are accelerating adoption for 25G and 100G Ethernet backhaul. This migration is compressing the addressable market for traditional ceramic varistor solutions in signal path applications.
China's GB/T 17626.2 standard alignment with IEC methodologies is adding domestic certification layers atop international test protocols. Local manufacturers must now navigate dual compliance tracks for consumer electronics export and domestic sale. Smartphone OEMs headquartered in Shenzhen and Dongguan are restructuring component qualification workflows to parallel-process both certification streams.
Consolidated distributor networks across Asia-Pacific are compressing component availability dynamics for mid-volume ESD suppressor procurement. Tier-two automotive suppliers are bypassing traditional catalog distribution to secure direct allocation from silicon foundry partners. This channel restructuring is most visible in South Korea's automotive electronics cluster, where Hyundai-Kia tier suppliers have established preferred supplier agreements with protection device specialists.
ESD Suppressors Market Segmentation
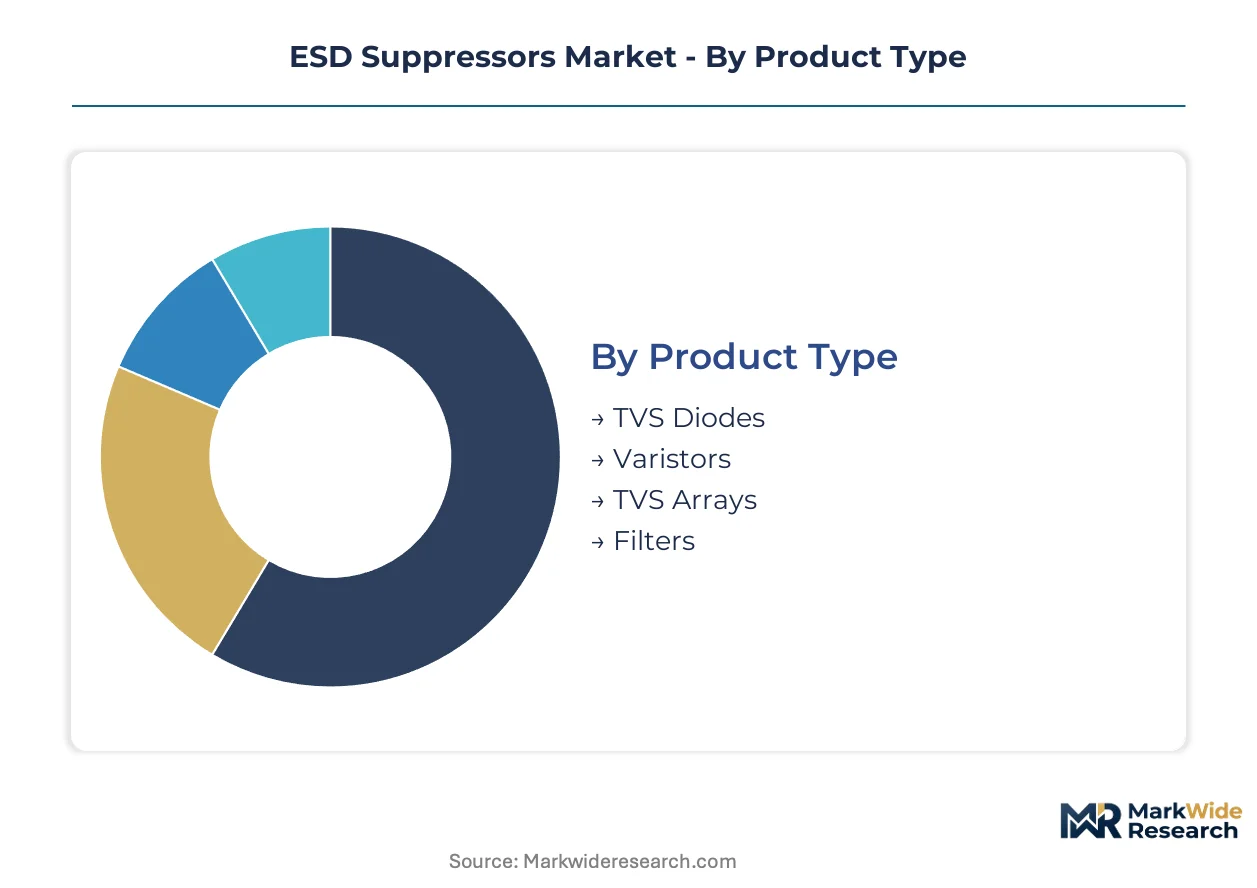
ESD suppressor procurement patterns diverge sharply across product architectures and end-use qualification requirements. Understanding these segment boundaries clarifies where silicon foundry capacity, AEC-Q101 certification timelines, and IEC compliance testing create divergent margin structures for suppliers.
Product Type:
Mature clamping technologies anchor high-volume consumer electronics, while emerging architectures penetrate 5G infrastructure and automotive Ethernet.
- TVS Diodes:Unidirectional and bidirectional silicon devices deliver sub-nanosecond response times with breakdown voltages spanning 3.3 V to 450 V. Automotive OEMs in Stuttgart and Detroit concentrate procurement for battery management system protection, pulling capacity from consumer-grade lines.
- Varistors:Zinc oxide ceramic discs provide high-energy absorption for industrial motor drives and power supply input stages. Vishay's European manufacturing base serves German automation OEMs with established MLCC-adjacent production infrastructure.
- TVS Arrays:Multi-channel silicon devices protect high-speed data buses in smartphones and tablets.
- Filters:Integrated EMI/ESD suppression components address radiated emissions compliance in medical devices.
TVS Diodes handles the majority of throughput; TVS Arrays is gaining share fastest in smartphone board-level integration.
Application:
Cost tier segmentation separates qualified automotive grades from catalog-distribution consumer components with radically different pricing structures.
- Consumer Electronics:Smartphones, wearables, and laptops drive the highest unit volumes with sub-picofarad capacitance requirements for USB-C and HDMI signal integrity. Shenzhen-based OEMs compress qualification cycles to match seasonal product launches.
- Automotive Devices:Battery management systems, inverter controls, and ADAS sensor modules demand AEC-Q101 Rev-E certification with extended temperature ranges. Hyundai-Kia tier suppliers in South Korea secure direct foundry allocation to bypass distribution lead times.
- Industrial Equipment:Programmable logic controllers and motor drives prioritize energy absorption over clamping speed.
- Telecommunications:5G millimeter-wave base stations require sub-0.5 pF capacitance specifications.
Consumer Electronics moves the highest unit volumes; Automotive Devices expands most quickly as EV platform proliferation accelerates.
End User:
Customer type determines procurement channel structure, from catalog distribution for mid-volume electronics manufacturers to direct foundry partnerships for automotive tier suppliers.
- Electronics Manufacturers:Contract assemblers and ODMs in Dongguan and Shenzhen source through consolidated Asia-Pacific distributor networks with compressed availability dynamics.
- Automotive OEMs:Volkswagen, BMW, and BYD mandate second-source qualification for all protection components, favoring suppliers with captive silicon capacity.
- Telecommunication Providers:Ericsson, Nokia, and Huawei specify low-capacitance devices for 25G and 100G Ethernet backhaul infrastructure.
- Industrial Users:Siemens and Rockwell Automation prioritize varistor solutions for motor drive protection with established supply relationships through European distribution.
Electronics Manufacturers represent the broadest addressable base; Automotive OEMs command the steepest expansion trajectory as electrification multiplies protection nodes per vehicle.
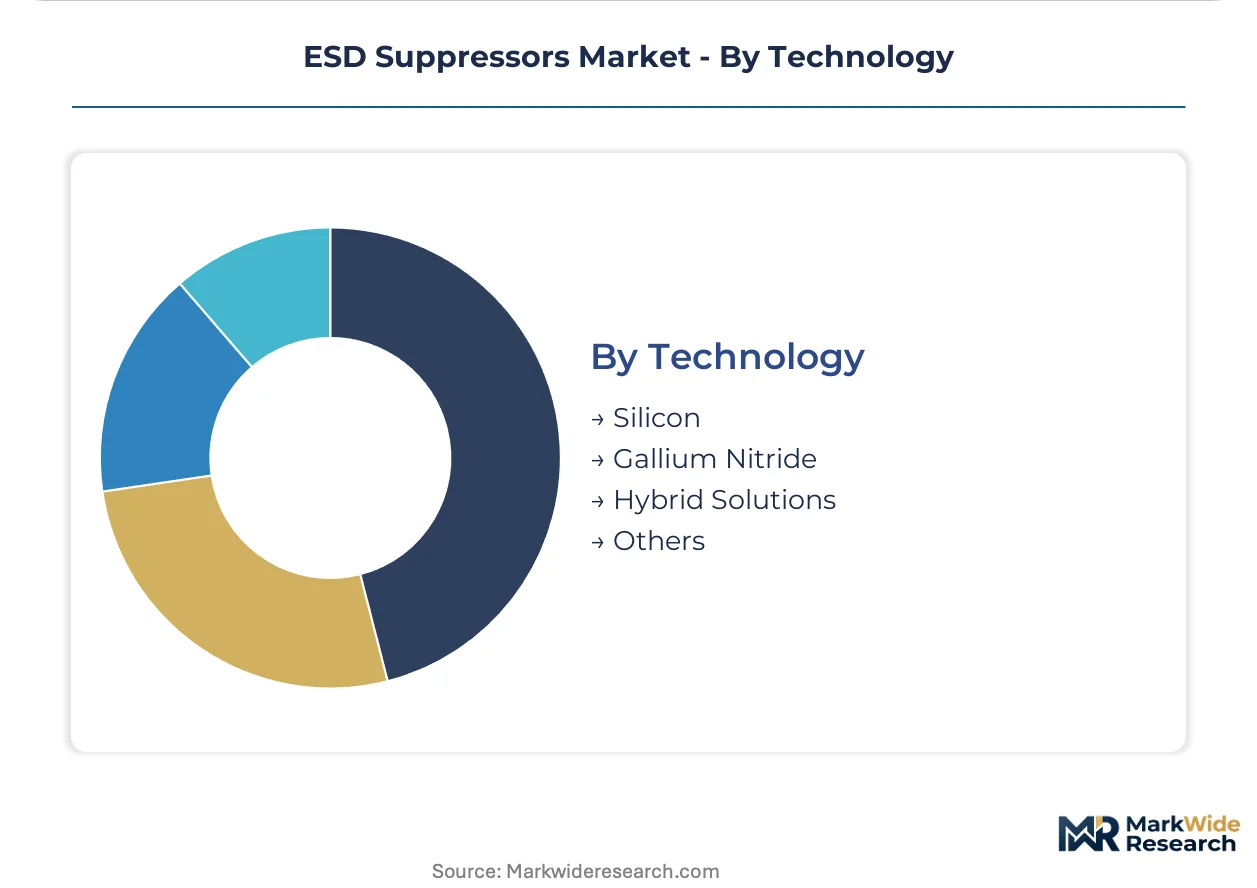
Technology:
Material science roadmaps create divergent performance ceilings across silicon dominance, wide-bandgap emergence, and hybrid integration.
- Silicon:Mature epitaxial planar and trench processes deliver established AEC-Q101 qualification paths with foundry capacity concentrated in Taiwan and China. Thermal coefficient stability under hood temperatures sustains automotive preference despite capacitance limitations.
- Gallium Nitride:HEMT and Schottky architectures achieve sub-0.5 pF capacitance for 5G millimeter-wave signal paths. Concentrated epiwafer supply from single-source substrate manufacturers creates procurement vulnerability for telecommunications-grade devices.
- Hybrid Solutions:Stacked silicon and ceramic architectures combine clamping speed with energy absorption.
- Others:Silicon carbide protection devices face thermal mismatch constraints limiting high-temperature automotive adoption.
Silicon commands current revenue concentration; Gallium Nitride climbs the fastest as telecommunications infrastructure deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's GB standards framework anchors procurement patterns in the dominant geography. Domestic semiconductor packaging capacity expansion shortens lead times for board-level TVS diode integration. Shenzhen and Dongguan electronics clusters drive seasonal demand cycles for smartphone protection components.
China
Domestic semiconductor backend capacity scaling accelerates TVS diode procurement for consumer electronics manufacturers. GB/T 17626.2 standard alignment with IEC methodologies adds dual certification layers for local OEMs. Shenzhen-based smartphone assemblers restructure qualification workflows to parallel-process domestic and export compliance tracks.
United States
FCC Part 15 emissions rules mandate ESD immunity compliance for electronic equipment market access. Detroit automotive OEMs compress AEC-Q101 qualification timelines to synchronize with EV platform launches. Michigan and Ohio electronics corridors concentrate battery management system protection procurement.
Germany
EU Electromagnetic Compatibility Directive 2014/30/EU shapes suppressor performance thresholds for industrial automation. Stuttgart OEMs mandate second-source qualification for all protection components across electrified powertrains. Bavaria and Baden-Württemberg automotive clusters prioritize silicon-based solutions with established AEC-Q101 certification paths.
South Korea
Hyundai-Kia tier suppliers establish preferred supplier agreements to bypass distribution lead times. MFDS-equivalent automotive safety frameworks extend to electronics subsystem reliability standards. Seoul-Gyeonggi automotive electronics cluster secures direct foundry allocation for high-reliability protection arrays.
India
PLI scheme subsidies for mobile phone and component production create localized demand for multilayer ceramic TVS arrays. BIS certification requirements add domestic testing layers atop IEC methodologies for locally manufactured devices. Maharashtra and Tamil Nadu electronics manufacturing zones attract protection component assembly investments.
ESD Suppressors Market Competitive Landscape
Captive silicon capacity holders and catalog-distribution specialists split the market along qualification-tier lines. Consolidation concentrates among automotive-grade suppliers with AEC-Q101 certification portfolios, while consumer electronics procurement fragments across Asia-Pacific distributor networks. Two archetypes dominate: integrated device manufacturers with foundry partnerships, and component specialists with ceramic varistor heritage. Competitive moves center on backward integration into silicon epitaxy and geographic expansion through India PLI scheme participation.
Within the captive-capacity tier, Littelfuse and ON Semiconductor occupy positions secured through silicon foundry partnerships. Vishay Intertechnology anchors European industrial demand through its broad protection portfolio. Murata Manufacturing exemplifies the ceramic-based specialist archetype with concentrated smartphone board-level integration expertise.
| Leading Market Players |
|---|
| Littelfuse |
| Nexperia |
| Vishay Intertechnology |
| ON Semiconductor |
| STMicroelectronics |
| Texas Instruments |
| Murata Manufacturing |
| TDK Corporation |
| Bourns |
| Others |
Supply & Pricing Matrix
The Shanghai-Shenzhen express freight corridor channels silicon wafer shipments from foundry partners to backend packaging houses, with transport cost fluctuations amplifying price spreads between AEC-Q101 automotive grades and catalog-distribution consumer components. This logistics backbone concentrates pricing power among captive-capacity holders while forcing tier-two suppliers into spot-market silicon procurement with compressed margin structures.
Pricing Analysis
The customization-premium spread separates configured-to-order AEC-Q101 automotive TVS diodes from standard-catalog consumer-grade arrays, with certification-level and volume scale as the primary price differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels stratifies procurement: premium tiers command automotive-grade silicon with extended temperature qualification, standard tiers serve industrial automation through European distribution, and economy tiers address high-volume smartphone board-level integration. Pricing pressure stems from silicon wafer cost volatility in 200mm and 300mm substrates, compressing margins for discrete protection manufacturers without captive foundry partnerships. Electronics manufacturers in Dongguan exhibit highest price sensitivity due to seasonal demand compression, while automotive OEMs in Stuttgart and Detroit prioritize qualification reliability over unit cost.
Supply Chain Analysis
Supplier-financing facilities from Taiwan-based silicon foundries extend 90-day payment terms to qualified automotive tier suppliers, anchoring working capital structures across the procurement chain. Geographic supply concentrates in Taiwan for epitaxial silicon processing, China for backend packaging and test, and South Korea for gallium nitride epiwafer development. Raw material dependencies include high-purity silicon wafers, zinc oxide ceramic powders for varistor production, and single-source gallium nitride substrates for telecommunications-grade devices. Single-source vulnerability in gallium nitride epiwafer supply creates procurement risk for sub-0.5 pF capacitance suppressors. Distribution runs through consolidated Asia-Pacific distributor networks for consumer electronics, while automotive tiers secure direct foundry allocation through preferred supplier agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where qualification engineering and AEC-Q101 certification support contracts expand faster than discrete component hardware sales. Recurring-revenue layers from second-source qualification documentation and thermal modeling services outpace unit shipment growth across automotive verticals.
For Market Incumbents: Insulate automotive-grade margin structures through backward integration into silicon epitaxy capacity in Taiwan and China, securing die supply against foundry pricing volatility. Deepen AEC-Q101 Rev-E certification portfolios to exploit timeline compression pressures facing EV platform launches from Detroit to Stuttgart. Channel control through direct allocation agreements with Hyundai-Kia tier suppliers in South Korea defends position against emerging compound semiconductor substitutes. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized mobile phone manufacturing zones, where localized multilayer ceramic TVS array demand outpaces domestic supply capacity. Target telecommunications infrastructure OEMs specifying sub-0.5 pF gallium nitride devices for 5G millimeter-wave base stations, a segment where single-source epiwafer supply creates incumbent vulnerability. Pursue technical partnership routes with Shenzhen-based smartphone assemblers restructured for parallel GB/T 17626.2 and IEC certification workflows. For Investors and Strategic Acquirers: Ceramic varistor specialists with established MLCC-adjacent production infrastructure and European industrial automation relationships offer acquisition targets with defensible niche positioning. Long-term viability across the analysis window hinges on material science roadmaps bridging silicon dominance with wide-bandgap emergence. Monitor gallium nitride substrate supply diversification as the critical inflection signal: successful second-source qualification for telecommunications-grade epiwafers would reshape competitive dynamics and compress incumbent pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Epitaxy | Captive wafer supply secures AEC-Q101 automotive grades against foundry pricing volatility from Taiwan partners. |
| Dual Certification Workflow Restructuring | Parallel GB/T 17626.2 and IEC processing accelerates Shenzhen OEM qualification for domestic and export markets. |
| Gallium Nitride Substrate Supply Diversification | Second-source epiwafer procurement reduces telecommunications-grade suppressor vulnerability to single-source concentration. |
| PLI Scheme Manufacturing Localization | India electronics manufacturing subsidies attract multilayer ceramic TVS assembly investments in Maharashtra zones. |
| Direct Foundry Allocation Agreements | Hyundai-Kia tier suppliers in South Korea bypass distribution lead times through preferred supplier partnerships. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with silicon foundry procurement directors, automotive tier supplier quality engineers, and telecommunications OEM component specialists; and secondary validation through IEC standard documentation, SEC filings from listed protection device manufacturers, customs trade data for silicon wafer imports, and AEC-Q101 certification registry databases. Bottom-up and top-down triangulation cross-checked unit shipment estimates against foundry capacity disclosures and end-use equipment production forecasts.
Forecast inputs encompassed product type segmentation across TVS diodes, varistors, arrays and filters; application tiers spanning consumer electronics, automotive devices, industrial equipment and telecommunications; technology roadmaps for silicon, gallium nitride and hybrid architectures; and end-user procurement channel structures. CAGRs were derived from regression analysis of historical qualification cycle compression and EV platform proliferation rates, with cross-segment elasticity modeling for material substitution scenarios.
Stress conditions across silicon wafer pricing volatility, gallium nitride substrate supply disruption, and AEC-Q101 timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about foundry capacity expansion and automotive electrification penetration. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Global Inflation Device Market
Detection and Regulation Devices
Global Tunnel Diode Detectors Market
Detection and Regulation Devices
Digital Metal Detector Market
Detection and Regulation Devices
US Pin and Sleeve Devices Market
Detection and Regulation Devices
Antistatic Device for Ultrapure Water Market
Detection and Regulation Devices
Global Label-Free Detection Market
Detection and Regulation Devices
Explosive Detectors Market
Detection and Regulation Devices
Portable Radar Detectors Market
Detection and Regulation Devices
Global Wireless Gas Detection Market
Detection and Regulation Devices
X-Ray Detectors Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Global Surge Protection Devices Market
Detection and Regulation Devices
Null Detector Market
Detection and Regulation Devices
Surge Suppression IC Market
Detection and Regulation Devices
Global Gas Sensors Market
Detection and Regulation Devices
Hydrogen Detection Transmitters Market