
 Europe Electric Insulator Market | 2026-2036
Europe Electric Insulator Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Insulator Market Intelligence
Modular composite insulator configurations is broadening buyer choice across European transmission procurement. Siemens Energy leverages in-house silicone housing production to control composite quality from compound to finished assembly. PFISTERER Holding AG anchors its position through specialized high-voltage termination systems for cross-border interconnectors. LAPP Insulators GmbH differentiates via deep expertise in porcelain bell designs for heritage grid infrastructure across Central Europe.
Europe electric insulators are non-conductive devices, typically manufactured from porcelain, glass, or polymer composites with silicone rubber housings, engineered to mechanically support and electrically isolate conductors in power systems rated from low voltage through extra high voltage. Their primary purpose is preventing current leakage to ground while withstanding mechanical loads, thermal cycling, and environmental contamination across decades of service life. Composite and polymer product types are capturing the fastest growth as silicone rubber housing technology improves pollution performance and reduces weight for overhead installations. Extra high voltage ratings command concentrated investment as submarine cable landings and offshore wind export corridors multiply across the North and Baltic Seas.
CE marking under the EU Construction Products Regulation and REACH compliance through ECHA govern material composition and chemical safety for insulator housings and fittings sold across member states. The EU Green Deal's electrification targets and F-Gas Regulation phase-down are jointly pressuring manufacturers toward polymer alternatives with lower embodied carbon and eliminated SF6-adjacent supply chains. Stakeholders must monitor how the EU AI Act's predictive maintenance requirements will reshape insulator condition monitoring and replacement scheduling protocols.
Market Dynamics
Grid modernization across German transmission networks is accelerating composite insulator procurement as TenneT and 50Hertz replace porcelain assemblies with silicone rubber alternatives. The EU Green Deal's electrification mandates are reshaping material specifications and performance standards across member states.
Growth Catalysts
- EU Green Deal electrification mandates:Binding targets for renewable integration are forcing transmission operators to upgrade corridor capacity, directly stimulating demand for extra high voltage composite insulators rated above 420 kV.
- Offshore wind interconnection scaling:France and Spain are deploying submarine cable landings at unprecedented rates, requiring specialized termination systems and pollution-resistant housing designs for marine environments.
- Silicone rubber housing technology:Improved hydrophobicity and reduced weight are displacing glass and porcelain in overhead line retrofit programs, cutting installation labor and helicopter transport costs.
Market Restraints
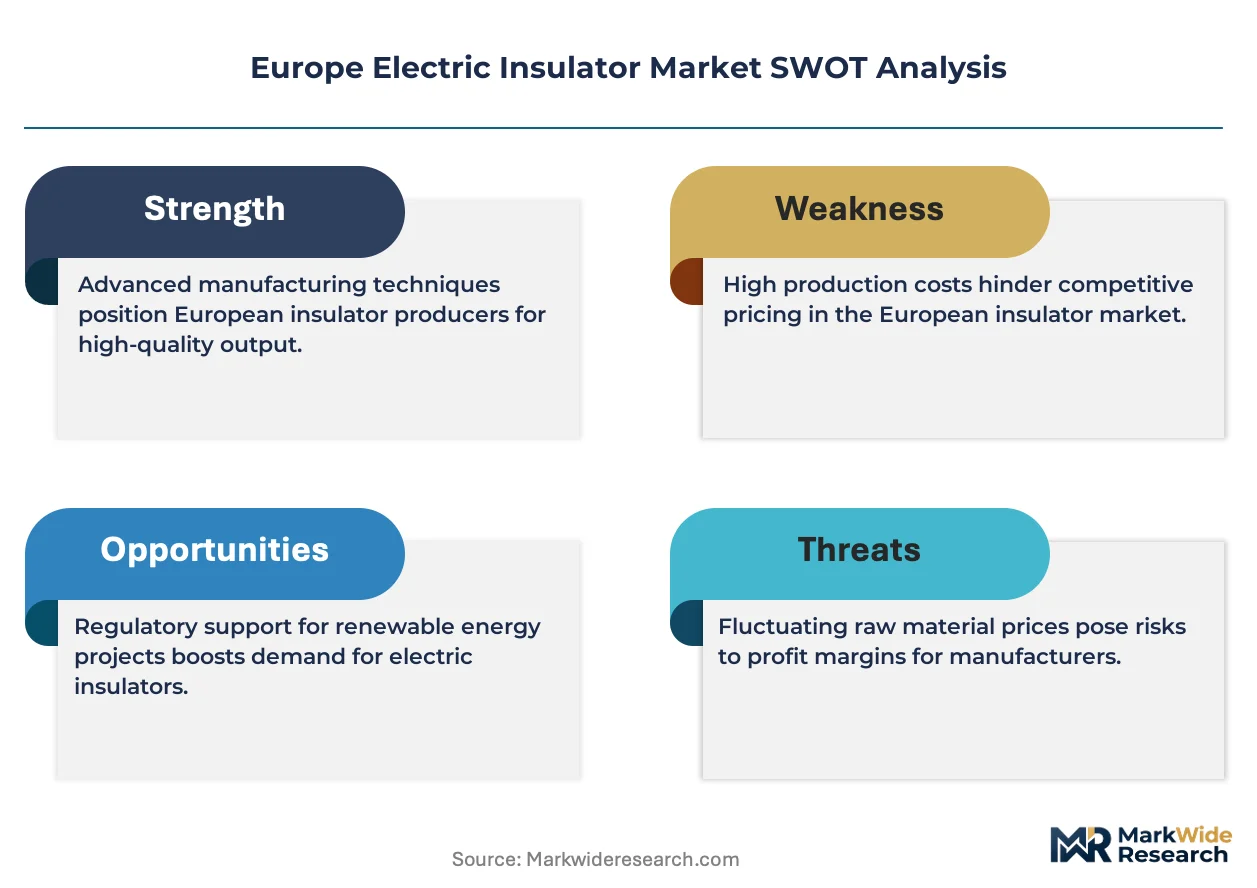
- Raw material concentration:High-grade alumina for porcelain cores and silicone feedstock for polymer housings concentrate supply among a limited set of specialty chemical producers, creating input cost volatility.
- REACH compliance burden:ECHA registration requirements for novel polymer formulations extend product development cycles and raise barriers for housing compound innovations.
- Technical limitation in extreme cold:Silicone rubber stiffening below minus 40 degrees Celsius restricts deployment latitude in Nordic transmission networks without supplemental heating systems.
Strategic Opportunities
- Spanish offshore wind export corridors:The planned 3 GW floating wind capacity in the Canary Islands and Cantabrian coast requires purpose-built submarine cable terminations and platform-mounted insulator assemblies.
- EU AI Act predictive maintenance:Condition monitoring mandates for critical infrastructure will create demand for sensor-integrated composite insulators with embedded fiber optic strain measurement.
- Digital twin convergence:Integration of finite element modeling with real-time weather data is enabling predictive replacement scheduling, opening service revenue streams for manufacturers with analytics capabilities.
Industry Challenges
- High-voltage testing infrastructure scarcity:Few European laboratories maintain test bays rated above 800 kV for type approval of extra high voltage designs, creating certification bottlenecks for new entrants.
- Heritage grid integration complexity:Porcelain bell hardware from the 1960s-1980s requires custom adapter fittings for composite replacements, fragmenting procurement and raising project engineering costs.
- SF6 phase-down supply chain reconfiguration:F-Gas Regulation elimination of sulfur hexafluoride in switchgear adjacent to insulator assemblies is forcing redesign of interface geometries and sealing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Insulator Market |
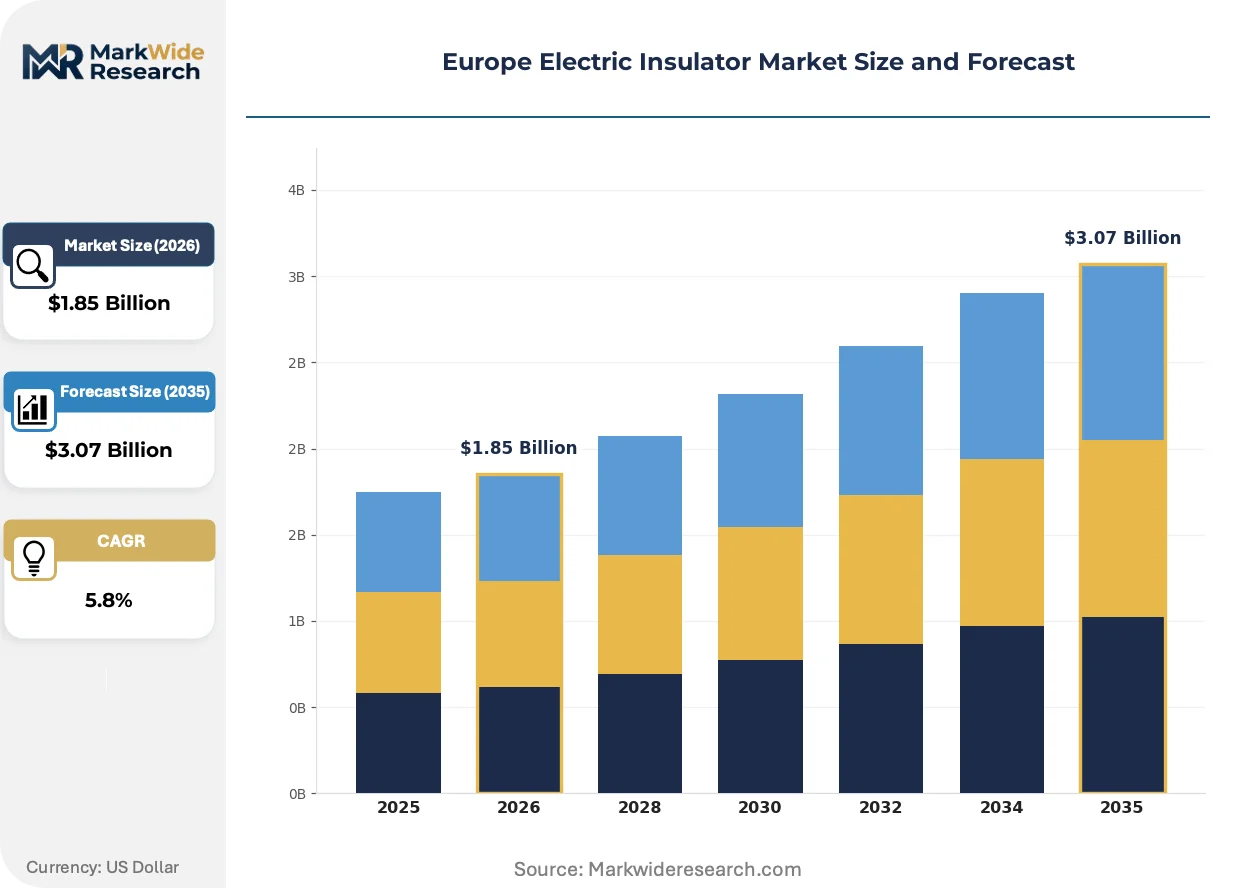
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.07 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcelain, Glass, Composite, Polymer Installation Type: Overhead, Underground, Indoor, Outdoor Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage End User: Utilities, Manufacturing, Transportation, Renewable Energy |
| Companies Covered | Siemens Energy, PFISTERER Holding AG, LAPP Insulators GmbH, INAEL Electrical Systems, General Electric, Hitachi Energy Ltd., TE Connectivity, GIPRO GmbH, NGK INSULATORS, LTD., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Insulator Market Strategic Shifts & Innovations
Material science advances and regulatory digitization are converging to redefine insulator performance metrics and procurement protocols across European transmission networks.
Silicone rubber housing formulations with nano-filled tracking resistance additives are unifying pollution performance and mechanical durability in a single material platform. Transmission operators in Italy and Greece are specifying these grades for coastal contamination zones previously requiring glass or glazed porcelain. This unification is compressing the traditional three-material procurement split into a polymer-dominant standard, simplifying inventory and reducing failure mode diversity.
The EU F-Gas Regulation phase-down is eliminating sulfur hexafluoride adjacent supply chains, forcing insulator manufacturers to redesign interfaces for vacuum and dry air switchgear. Housing compound suppliers must now validate thermal expansion matching with aluminum and copper terminals rather than SF6-filled enclosures. Extra high voltage composite assemblies for offshore substations are experiencing the most acute redesign pressure as original equipment manufacturers accelerate SF6-free platform commitments.
Aggregated procurement through European transmission system operator consortiums is consolidating buyer power and compressing supplier margins. TenneT, RTE, and National Grid ESO now coordinate framework agreements for standardized 420 kV composite line post insulators, displacing bilateral negotiations. This concentration is most visible in North Sea offshore wind export corridor tenders, where multi-buyer joint procurement is extracting volume discounts and extended warranty terms from housing manufacturers.
Europe Electric Insulator Market Segmentation
Segmentation in the Europe Electric Insulator Market reveals how capital intensity, technical specifications, and regulatory pressures fragment procurement patterns across transmission and distribution networks. Understanding these divisions helps suppliers align housing compound formulations, testing protocols, and warranty structures with buyer risk profiles and grid modernization timelines.
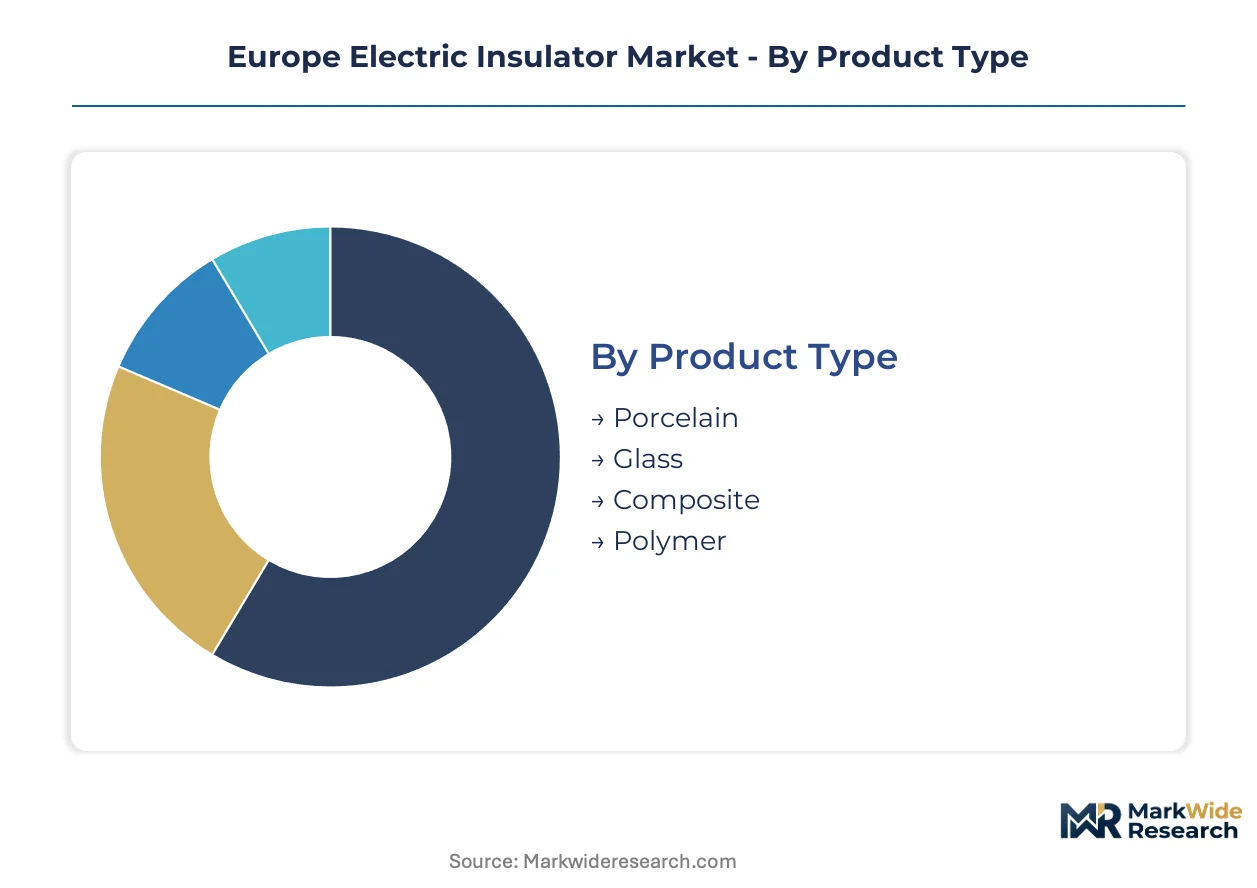
Product Type:
Capital intensity varies sharply across material platforms, with composite and polymer formulations demanding specialized silicone compounding infrastructure while porcelain requires high-temperature kiln investments.
- Composite:Silicone rubber housings with fiberglass cores dominate new procurement in German and French transmission corridors. Hydrophobic surface properties and reduced weight are displacing traditional materials in North Sea offshore wind export projects where helicopter installation costs matter.
- Polymer:Thermoplastic housing variants with tracking-resistant additives are gaining traction in Italian coastal zones with severe salt contamination. REACH compliance for novel formulations extends development cycles but opens differentiation paths beyond commodity silicone grades.
- Porcelain:Alumina-based ceramic insulators retain installed base dominance in Central European heritage grids from the 1970s-1980s, requiring custom adapter hardware for composite retrofits.
- Glass:Toughened glass discs persist in high-voltage strings for 400 kV+ lines in Spain and Portugal where thermal shock resistance and visual inspection simplicity outweigh polymer weight advantages.
Composite absorbs the bulk of installed capacity; polymer is expanding most quickly.
Installation Type:
Application environment dictates housing geometry, sealing requirements, and pollution performance specifications across the four installation modes.
- Overhead:Suspension and tension assemblies for transmission towers constitute the volume base, with silicone rubber composite posts replacing porcelain in RTE and TenneT corridor upgrades. Weight reduction cuts helicopter transport costs for remote Alpine and Pyrenean crossings.
- Outdoor:Substation bushing and apparatus insulators face the most acute F-Gas Regulation redesign pressure as SF6-free switchgear proliferates. Thermal expansion matching with dry air and vacuum enclosures now governs housing compound selection.
- Underground:Cable termination systems for submarine landings in French and Spanish offshore wind projects require specialized stress cone geometries and marine-grade sealing against saltwater ingress.
- Indoor:Switchgear integration insulators for manufacturing and data center substations emphasize compact profiles and standardized bushing dimensions for OEM equipment slots.
Overhead retains the largest installed base; outdoor applications are climbing the fastest amid substation electrification mandates.
Voltage Rating:
Testing infrastructure scarcity and certification complexity concentrate supplier power at the highest voltage tiers.
- Extra High Voltage:Ratings above 420 kV for cross-border interconnectors and offshore export corridors command specialized composite designs with multiple silicone sheds and optimized electric field grading. Few European laboratories maintain 800 kV+ test bays, creating certification bottlenecks.
- High Voltage:72.5 kV to 420 kV ratings cover the bulk of transmission network procurement, with standardized 420 kV line posts now subject to aggregated TSO consortium purchasing.
- Medium Voltage:Distribution network applications from 1 kV to 72.5 kV emphasize cost efficiency and inventory standardization across municipal utilities.
- Low Voltage:Secondary distribution and service entrance insulators face commodity pricing pressure with minimal differentiation beyond basic mechanical and electrical ratings.
High Voltage carries the greatest procurement volume; Extra High Voltage is gaining share fastest on offshore wind interconnection scaling.
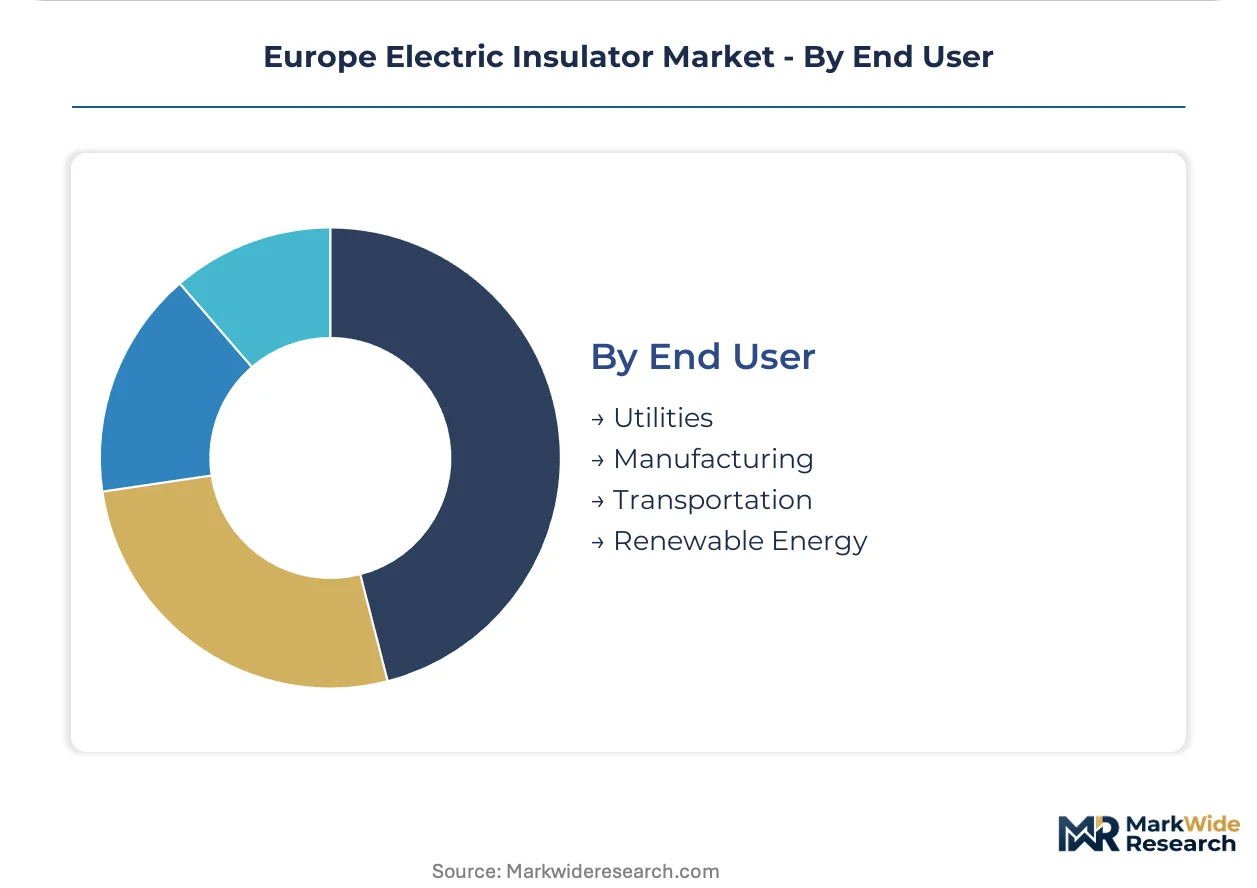
End User:
Buyer sophistication and technical specification authority vary dramatically across the four demand segments.
- Utilities:Transmission system operators in Germany, France, and Spain drive standard-setting through framework agreements and joint procurement, consolidating supplier relationships around proven composite housing manufacturers.
- Renewable Energy:Offshore wind developers in the North and Baltic Seas demand purpose-built termination systems with marine pollution resistance and platform-mounted assembly compatibility.
- Manufacturing:Industrial substation operators prioritize indoor apparatus bushings with compact footprints and OEM interchangeability for maintenance continuity.
- Transportation:Railway electrification and metro traction networks require vibration-resistant designs with specialized mechanical load ratings for catenary support.
Utilities dominate procurement volume; renewable energy is expanding most quickly on EU Green Deal capacity targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of high-voltage composite insulators concentrates in Germany and France, while demand spreads across North Sea offshore wind corridors and Alpine transmission crossings. Consumption patterns diverge between mature grid replacement markets and electrification-driven expansion zones.
Germany
TenneT and 50Hertz drive composite insulator procurement through corridor modernization and offshore wind export cable landings. The EU Green Deal mandates accelerate 420 kV line upgrades across Bavarian and North Rhine-Westphalian transmission networks. Siemens Energy anchors manufacturing in Nuremberg, supplying silicone rubber assemblies for North Sea grid connections.
France
RTE coordinates framework agreements for standardized extra high voltage insulators as offshore wind capacity targets reshape procurement volumes. The EU F-Gas Regulation pressures interface redesigns for SF6-free switchgear integration across substations in Île-de-France and Hauts-de-France. Specialized termination systems for submarine cable landings concentrate manufacturing expertise around Lyon and Grenoble industrial clusters.
Spain
Floating wind projects in the Canary Islands and Cantabrian coast create demand for marine-grade insulator assemblies and platform-mounted configurations. National renewable integration targets align with EU electrification mandates, accelerating 400 kV corridor upgrades through Aragon and Castile-León. Red Eléctrica coordinates procurement for cross-border interconnectors with France and Portugal.
Italy
Terna specifies nano-filled silicone formulations for coastal contamination zones in Sicily and Apulia, unifying pollution performance and mechanical durability. REACH compliance requirements extend development cycles for novel polymer compounds tested at Milan-area laboratories. Alpine crossing retrofits in Lombardy and Piedmont prioritize weight reduction for helicopter installation logistics.
United Kingdom
National Grid ESO aggregates procurement through consortium frameworks with continental TSOs, consolidating buyer power for North Sea offshore wind export corridors. The UK AI Act's predictive maintenance requirements reshape condition monitoring specifications for Scottish and English transmission networks. Submarine cable terminations for Dogger Bank and Hornsea projects concentrate demand in Northeast England manufacturing zones.
Europe Electric Insulator Market Key Industry Players
The competitive structure tilts toward integrated electrical equipment manufacturers with captive silicone compounding capabilities. Procurement consolidation through TSO consortiums compresses margins for standalone housing suppliers while favoring vendors with in-house finite element modeling and 800 kV testing infrastructure. Three archetypes dominate: diversified energy technology conglomerates with full vertical control, specialized high-voltage component specialists, and heritage porcelain manufacturers defending installed base replacement cycles. Competitive moves center on aggregated framework bidding and polymer formulation differentiation.
Among Germany-based integrated manufacturers, Siemens Energy and LAPP Insulators GmbH exemplify contrasting strategic positions—one leveraging full energy-system integration, the other defending heritage grid expertise. Swiss-incorporated PFISTERER Holding AG anchors the high-voltage termination specialist tier. Japanese NGK INSULATORS, LTD. represents the ceramic-to-polymer transition archetype, while US-headquartered General Electric and Hitachi Energy Ltd. compete through global project execution scale.
| Leading Market Players |
|---|
| Siemens Energy |
| PFISTERER Holding AG |
| LAPP Insulators GmbH |
| INAEL Electrical Systems |
| General Electric |
| Hitachi Energy Ltd. |
| TE Connectivity |
| GIPRO GmbH |
| NGK INSULATORS, LTD. |
| Others |
Cost & Logistics Intelligence
Silicone rubber housing technology migration is simultaneously compressing manufacturing cost curves and concentrating supply leverage among compounders with captive polymerization capabilities. This dual effect reshapes procurement economics as transmission system operators aggregate purchasing power while specialty chemical feedstock scarcity props input cost volatility.
Pricing Analysis
Margin tightening in extra high voltage tiers reflects aggregated procurement through TenneT-RTE-National Grid ESO consortium frameworks. Three-tier pricing structure across premium certified, standard tested, and economy qualified levels separates 800 kV test-bay access from basic 420 kV ratings. Cost-down pressure on porcelain retrofits accelerates because heritage grid adapter engineering fragments order volumes. Municipal utilities in medium voltage distribution exhibit highest price sensitivity; offshore wind developers accept premium positioning for marine-grade termination systems.
Supply Chain Analysis
EU Green Deal domestic-content preferences for critical infrastructure procurement are reshaping sourcing patterns toward European silicone compounders and German fiberglass core manufacturers. Geographic supply concentration centers on Germany, France, and Switzerland for finished assemblies, with high-grade alumina for porcelain cores drawing from Spain and Italy. Raw material dependencies rest on silicone feedstock, E-glass roving, and alumina powder. Single-source vulnerability concentrates in 800 kV test bay capacity at Milan, Lyon, and Berlin laboratories. Distribution runs through TSO framework agreements and OEM direct supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of 800 kV testing infrastructure props pricing power for certified suppliers while constraining new entrant expansion. This capacity bottleneck sustains margin premiums for incumbents with captive laboratory access.
For Market Incumbents: Deepen backward integration into silicone housing compound production to defend margin position against specialty chemical feedstock volatility. Secure long-term test bay reservation agreements at Berlin and Milan facilities to lock out emerging competitors. Prioritize embedded fiber optic sensor development ahead of EU AI Act predictive maintenance mandates.
For New Entrants and Emerging Players: The premium-economy price gap in medium voltage distribution creates white-space opportunity for standardized composite post designs without full extra high voltage certification. Target Italian coastal utilities specifying nano-filled polymer formulations for salt contamination zones. Pursue licensing partnerships with established compounders rather than greenfield REACH registration cycles.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified energy equipment conglomerates seeking insulator technology for offshore wind integration. Long-term viability hinges on SF6-free switchgear interface redesign capabilities and AI-enabled condition monitoring IP. Watch for inflection in aggregated TSO procurement volume thresholds that trigger supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Compound Backward Integration | Captive housing production insulates Siemens Energy from ECHA feedstock registration delays. |
| 800 kV Test Bay Capacity Expansion | Additional high-voltage infrastructure unlocks extra high voltage certification revenue for PFISTERER. |
| Submarine Termination System Development | Marine-grade assemblies capture Spanish and French offshore wind export corridor demand. |
| Sensor-Embedded Composite Platform Launch | Fiber optic strain measurement aligns with EU AI Act predictive maintenance requirements. |
| Heritage Grid Adapter Hardware Program | Custom porcelain-to-composite fittings defend LAPP Insulators' Central European installed base. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with transmission planning officers, silicone compound procurement leads, high-voltage testing laboratory directors, and offshore wind EPC contractors combined with bottom-up triangulation against top-down grid investment databases. Secondary sources included ECHA REACH registration databases, EU Green Deal implementation progress reports, TSO procurement disclosure filings, and submarine cable project development trackers.
Reconciliation of unit shipment data from compounders, value aggregation from TSO framework agreements, and capacity utilization rates from testing laboratories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass material platform, voltage rating tier, installation environment, and end-user buyer archetype. CAGRs derived from polynomial trend fitting to disclosed procurement volumes, adjusted for electrification mandate acceleration scenarios and F-Gas Regulation implementation timelines.
Inputs from laboratory certification records and TSO procurement disclosures were available through the study window; gaps in proprietary silicone formulation cost structures introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions regarding EU Green Deal target achievement rates and offshore wind capacity commissioning schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
High Voltage Insulator Market
Electrical Equipment
Insulator Market
Electrical Equipment
High Efficiency Low Voltage Aluminum Motors Market
Electrical Equipment
Pad-Mounted Transformer Market
Electrical Equipment
Medium Voltage Transformer Market
Electrical Equipment
North America Circuit Breakers Market
Electrical Equipment
Vacuum Circuit Breaker Market
Electrical Equipment
Laminated Busbar Market
Electrical Equipment
Air Circuit Breaker Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
United Kingdom Thermal Protector Market
Electrical Equipment
Industrial Plugs and Sockets Market
Electrical Equipment
Motor Protection Devices Market
Electrical Equipment
MCB and MCCB Market
Electrical Equipment
Magnetic Contactors Market
Electrical Equipment
Global Electric Plugs and Sockets Market