
 Electrical Sub Panels Market | 2026-2036
Electrical Sub Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Sub Panels Market Foresight
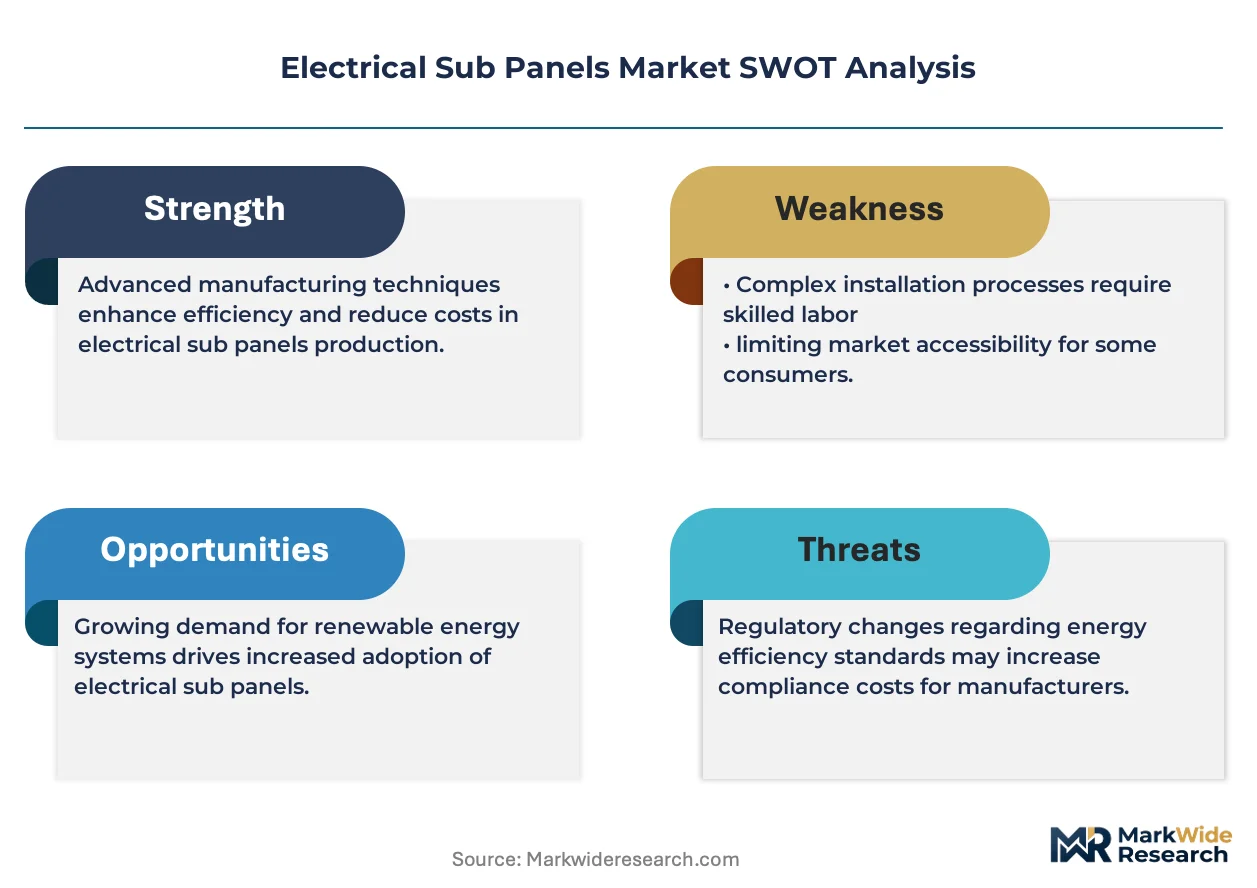
UL 67 and IEC 61439 certification tiers is rotating demand toward premium-specification sub panels with enhanced fault containment and arc-flash resistance. Schneider Electric leverages captive supply of copper busbar and molded-case circuit breaker platforms to sustain margin control. Siemens AG anchors European project engineering through localized panel-board fabrication in Germany and Poland. ABB Ltd competes on digital integration, embedding power-monitoring modules directly into enclosure designs.
Electrical sub panels are secondary distribution assemblies that receive power from a main service panel and redistribute it to branch circuits through busbar conductors and overcurrent-protective devices, typically rated between 60 and 400 amperes depending on load aggregation requirements. Flush mount configurations dominate residential retrofits where aesthetic integration with finished walls reduces installation friction, while weatherproof enclosures command premium positioning in outdoor and semi-outdoor industrial settings where NEMA 3R and IP65 ratings prevent moisture ingress. Load center sub panels with integrated meter sockets are capturing share in commercial build-outs where landlords require tenant-level billing granularity.
Federal, state, and municipal electrical codes—including the NEC administered by the National Fire Protection Association, OSHA workplace safety standards, and local Authority Having Jurisdiction inspections—shape product compliance burdens and create barriers for uncertified imports. The EPA's evolving stance on electrical equipment lifecycle and copper recycling is pressuring manufacturers toward modular, serviceable designs with reduced material intensity. Stakeholders must monitor how amendments to busbar ampacity tables and arc-energy reduction requirements in forthcoming code cycles reshape specification minimums and retrofit obligations.
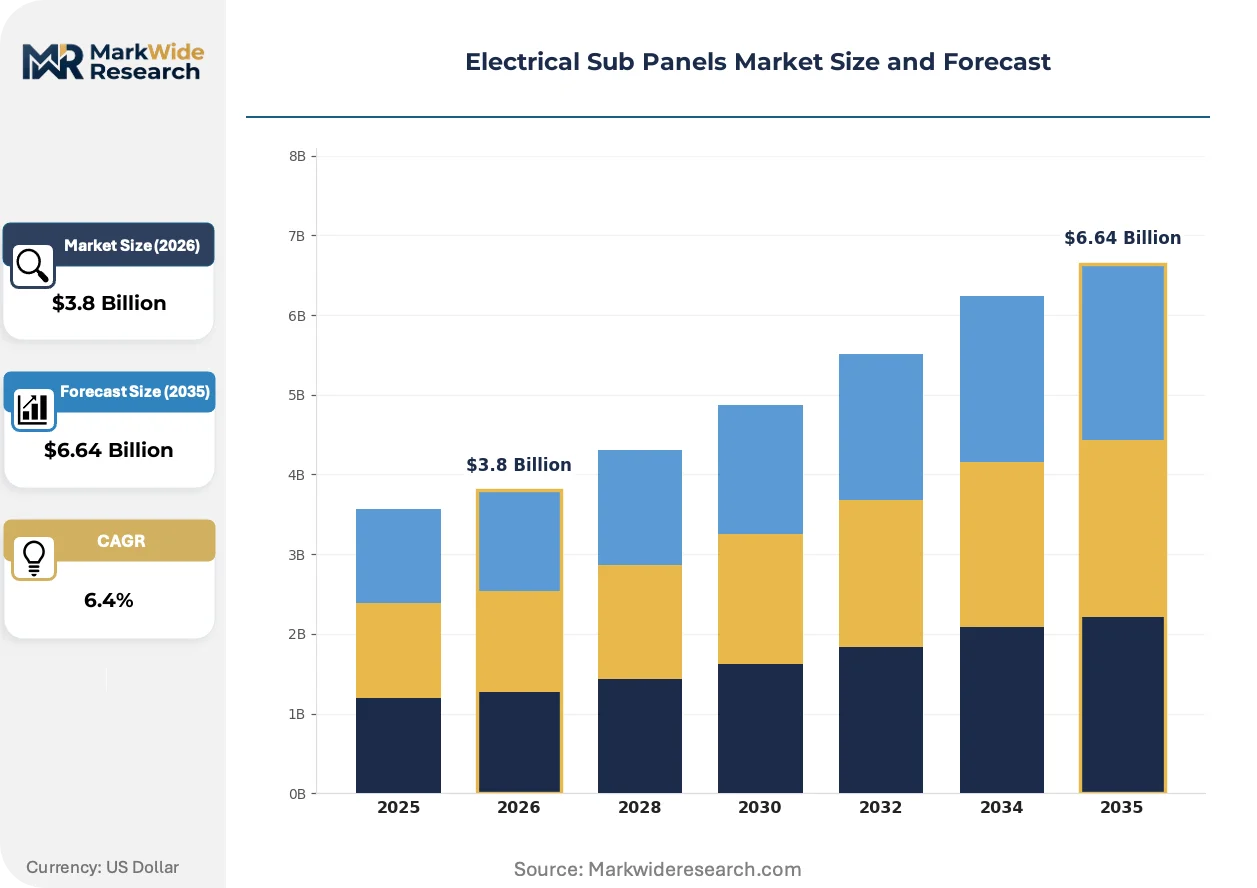
Market Dynamics
Hyperscale data center construction across the United States is compressing specification cycles and forcing busbar ampacity upgrades that ripple through distribution equipment supply chains. This concentration of demand in high-amperage segments is restructuring how manufacturers allocate fabrication capacity and certification resources.
Growth Catalysts
- NEC Article 408.36:Mandatory arc-energy reduction provisions in the National Electrical Code are compelling facility upgrades across commercial and industrial installations, expanding replacement demand for fault-rated sub panels.
- Copper busbar supply consolidation:Captive smelting and rolling capacity at major electrical equipment manufacturers is stabilizing input costs and shortening lead times for high-amperage panelboard assemblies.
- Texas-Arizona-Virginia data center corridor:Hyperscale facility clustering in these three states is concentrating procurement volume for 400-ampere distribution assemblies with integrated metering.
Market Restraints
- Copper price volatility:LME copper futures swings above 15% annually are compressing margins for fabricators without hedging programs or backward integration into primary metal sourcing.
- Enclosure steel supply concentration:Domestic cold-rolled steel capacity constraints and import tariff exposure are extending lead times for NEMA 3R and 4X weatherproof housings.
- Busbar ampacity derating requirements:Temperature correction factors in NEC Table 310.16 are forcing oversizing of conductors in high-ambient installations, increasing material intensity per panel.
Strategic Opportunities
- Digital power monitoring convergence:Integration of IoT-enabled energy metering with sub panel enclosures is creating premium positioning for contractors serving LEED-certified commercial build-outs.
- Tenant submetering mandates:Municipalities including New York City and Seattle are requiring granular electrical billing for multi-tenant buildings, expanding demand for load centers with integrated meter sockets.
- Modular serviceable design:EPA copper recycling guidelines are favoring manufacturers offering field-replaceable busbar segments and breaker mounting systems over sealed disposable units.
Industry Challenges
- UL 67 certification backlog:Testing laboratory capacity constraints are extending product approval timelines by 8-12 weeks, delaying commercialization of redesigned arc-resistant enclosures.
- Electrician workforce shortages:Journeyman training program enrollment declines in Texas and Arizona are constraining installation velocity for large-scale data center electrical contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Sub Panels Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Mount, Flush Mount, Weatherproof, Load Center Application: Residential, Commercial, Industrial, Institutional Component: Busbar, Circuit Breaker, Enclosure, Meter Installation Type: Indoor, Outdoor, Semi-Outdoor, Wall-Mounted |
| Companies Covered | Schneider Electric, Siemens AG, ABB Ltd, Eaton Corporation, General Electric Company, Legrand SA, Mitsubishi Electric Corporation, Honeywell International Inc., Larsen & Toubro Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Sub Panels Market Shifts & Advancements
Busbar material substitution and digital monitoring integration are compressing traditional product lifecycles while code amendments accelerate replacement schedules across installed bases.
Aluminum alloy busbar with tin-plated terminations is displacing traditional copper conductors in 60-225 ampere residential and light commercial sub panels. Homebuilders in Arizona and Texas are specifying aluminum to offset material cost inflation without derating circuit capacity. This substitution is compressing copper-dependent fabricators into premium industrial segments while opening mid-market share to aluminum-capable suppliers.
The EPA's evolving stance on electrical equipment lifecycle management is pressuring manufacturers toward modular, serviceable designs with reduced material intensity. Proposed amendments to copper recycling thresholds would mandate disassembly-friendly construction methods and standardized breaker mounting systems. Panelboard assemblers serving federal and municipal contracts are pre-emptively redesigning enclosures to maintain specification eligibility.
Specification authority is migrating from electrical contractors to data center engineering firms with standardized design libraries. These firms are consolidating vendor lists around manufacturers offering digital power monitoring integration and 10-year warranty programs, marginalizing traditional distribution channels. This concentration is most visible in Northern Virginia, where hyperscale developers have reduced qualified sub panel suppliers from twelve to four over the past specification cycle.
Electrical Sub Panels Market Segmentation
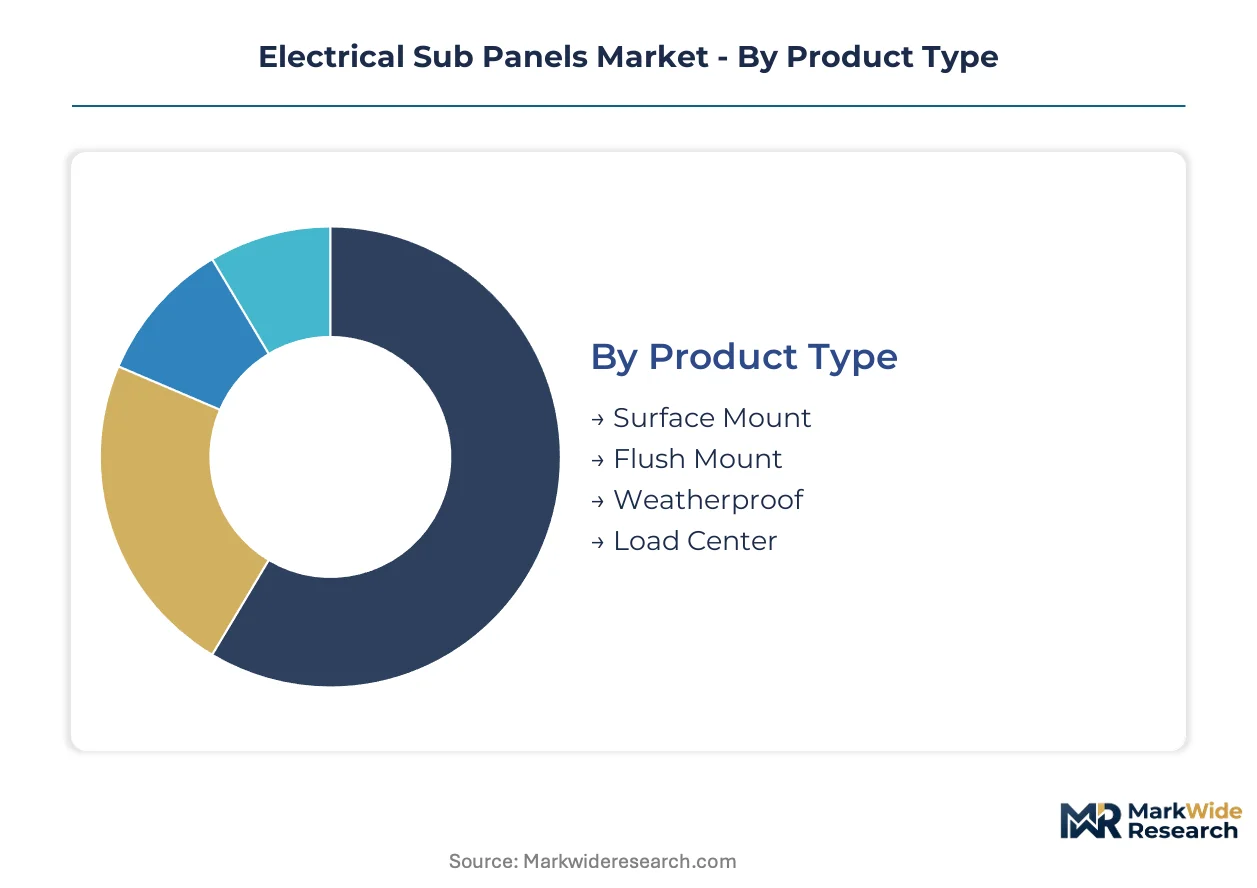
Segmentation in electrical sub panels reveals how specification authority migrates across installation contexts. Product architecture, application environment, and component sourcing each create distinct competitive arenas with divergent margin profiles and certification requirements.
Product Type:
Domestic fabrication concentrates in flush mount and load center variants serving residential retrofits and commercial build-outs. Export demand centers on weatherproof and surface mount configurations for industrial infrastructure in climates with extreme temperature or moisture exposure.
- Flush Mount:Recessed enclosure design integrates with finished wall surfaces in residential basements and utility rooms. Demand clusters in Texas and Arizona suburban developments where homebuilders prioritize aesthetic integration. NEC Article 408.36 arc-energy provisions are accelerating replacement of legacy flush mount panels in older housing stock.
- Weatherproof:NEMA 3R and IP65-rated housings seal against moisture ingress for outdoor and semi-outdoor industrial deployment. Procurement concentrates in Virginia data center campuses requiring exterior distribution points withstanding humidity and temperature cycling. Premium positioning reflects stainless steel or powder-coated aluminum enclosure costs.
- Surface Mount:Surface-applied boxes dominate garage and workshop installations where wall cavity depth is constrained. Standard specification for light commercial tenant improvements.
- Load Center:Integrated meter socket configurations enable landlord tenant billing granularity. Municipal submetering mandates in New York City and Seattle are expanding specification volume.
Flush mount commands the established base. The steepest expansion runs through weatherproof.
Application:
Cost tier stratification separates specification requirements across application segments. Industrial and institutional deployments demand premium fault-rated assemblies with extended warranties, while residential and commercial applications tolerate standard-grade certification tiers.
- Industrial:Heavy-load manufacturing and processing facilities specify 225-400 ampere assemblies with copper busbar and molded-case circuit breaker platforms. OSHA workplace safety standards and NFPA arc-flash compliance create specification barriers for uncertified imports. Demand concentrates in Arizona semiconductor fabrication and Texas petrochemical corridors.
- Commercial:Multi-tenant office and retail build-outs specify load centers with integrated metering for lease compliance. LEED certification requirements are embedding IoT-enabled power monitoring as a specification baseline in Northern Virginia and Austin developments.
- Residential:Single-family and multi-family housing drives volume in 60-200 ampere flush mount and surface mount configurations. Homebuilder cost pressure is accelerating aluminum busbar substitution in entry-level housing.
- Institutional:Schools, hospitals, and government facilities mandate UL 67 certification with enhanced fault containment. Federal procurement guidelines favor modular, serviceable designs meeting EPA copper recycling thresholds.
Residential maintains volume leadership. Industrial is gaining share fastest through data center and manufacturing capacity expansion.
Component:
Supply concentration varies sharply across component categories. Captive busbar and breaker production at major manufacturers stabilizes input costs, while third-party enclosure and meter sourcing exposes lead time volatility.
- Busbar:Copper and aluminum alloy conductors distribute power across panel phases. Tin-plated aluminum is displacing copper in 60-225 ampere residential segments, while industrial specifications retain copper for thermal performance. Temperature correction factors in NEC Table 310.16 are forcing oversizing in high-ambient Arizona and Texas installations.
- Circuit Breaker:Molded-case and miniature circuit breakers provide overcurrent protection with trip characteristics matched to load profiles. Schneider Electric and Siemens AG captive breaker platforms sustain margin control and specification loyalty.
- Enclosure:Cold-rolled steel and aluminum housings provide NEMA-rated environmental protection. Domestic steel capacity constraints are extending lead times for NEMA 3R and 4X weatherproof variants.
- Meter:Integrated socket and digital monitoring modules enable tenant billing and energy management. Municipal submetering mandates are embedding meter sockets as standard in commercial load centers.
Circuit breaker commands specification authority. Busbar is climbing the fastest through material substitution dynamics.
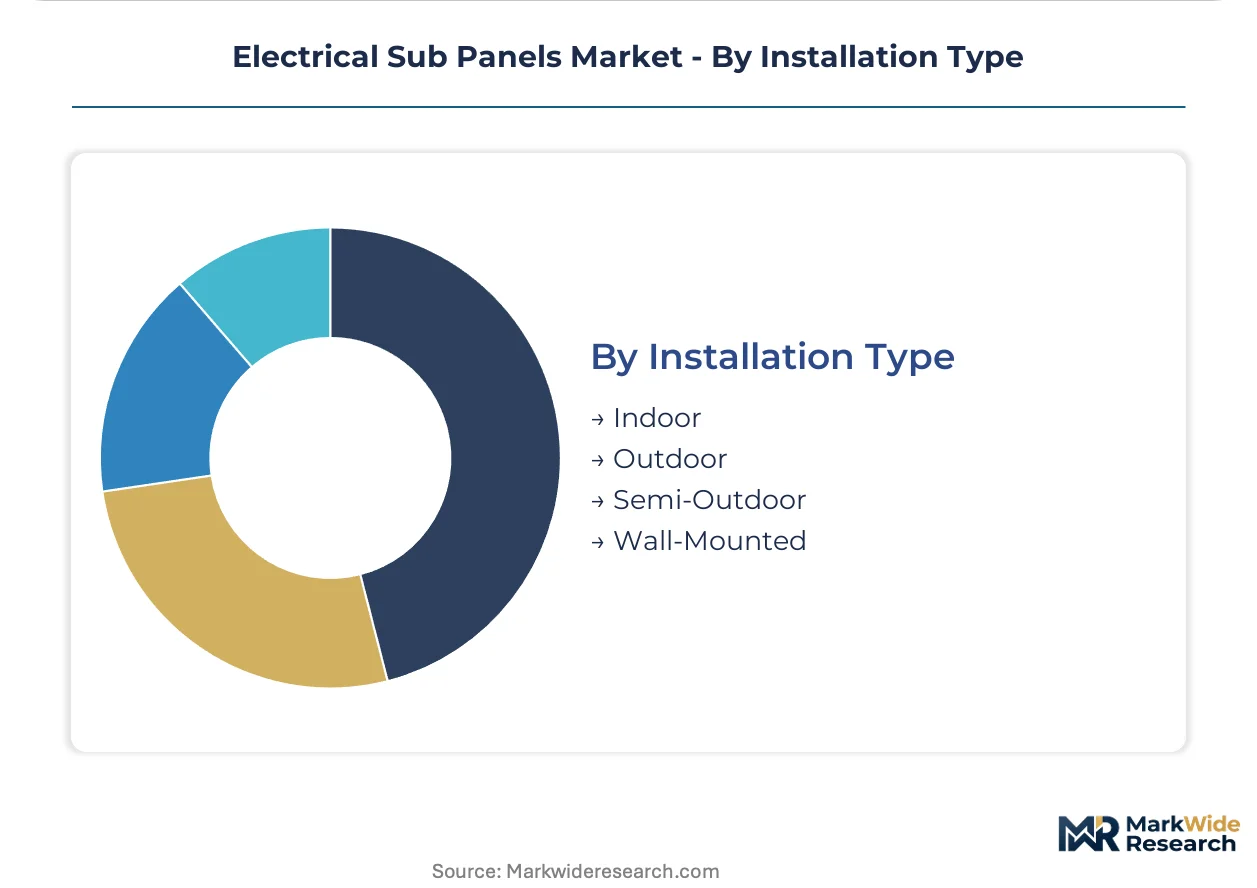
Installation Type:
Customer type and volume patterns separate installation contexts. Contractor-driven residential and commercial work favors indoor wall-mounted simplicity, while owner-engineered industrial and institutional projects specify outdoor and semi-outdoor resilience.
- Outdoor:Freestanding or pad-mounted assemblies withstand direct environmental exposure for utility interconnection and campus distribution. NEMA 3R and 4X ratings command premium positioning. Virginia and Arizona data center campuses are standardizing outdoor primary distribution nodes.
- Indoor:Climate-controlled environment installation dominates residential retrofits and commercial tenant improvements. Flush mount and surface mount configurations optimize for wall integration and service access.
- Semi-Outdoor:Covered but unconditioned spaces such as parking structures and loading docks require moisture-resistant housings without full outdoor hardening. Growing specification in Texas logistics and distribution facilities.
- Wall-Mounted:Structural attachment methods vary by enclosure weight and seismic requirements. Standard specification for residential and light commercial up to 200 amperes.
Indoor maintains the installed base. Outdoor is expanding most quickly through data center and utility-scale solar interconnection growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in electrical sub panels tilt toward import dependence in markets lacking domestic fabrication capacity, while copper busbar supply consolidation in select geographies reshapes export competitiveness. The United States absorbs premium high-amperage assemblies from European and Asian fabricators even as Texas and Arizona data center corridors expand local procurement.
United States
Hyperscale data center construction in Texas, Virginia, and Arizona compresses specification cycles for 400-ampere distribution assemblies. NEC Article 408.36 arc-energy reduction provisions mandate facility upgrades across commercial and industrial installations. Northern Virginia's Loudoun County hosts the densest concentration of data center electrical contracts, reducing qualified sub panel suppliers from twelve to four over the past specification cycle.
Germany
Industrial automation and renewable energy integration sustain demand for IEC 61439-certified panelboards with enhanced fault containment. The EU Green Deal's electrical equipment lifecycle requirements pressure manufacturers toward modular, serviceable designs. Siemens AG anchors European project engineering through localized panel-board fabrication in Germany and Poland, serving industrial corridors across the Rhine-Ruhr and Bavaria.
China
Domestic data center build-out and smart grid infrastructure expansion concentrate procurement for high-amperage sub panels in Beijing-Tianjin-Hebei and Yangtze River Delta clusters. GB standards alignment with IEC frameworks streamlines export certification for aluminum busbar configurations. Shanghai and Shenzhen manufacturing bases supply cost-optimized assemblies to Southeast Asian and African markets.
India
Commercial real estate growth and multi-tenant office build-outs in Mumbai and Bangalore expand specification volume for load centers with integrated metering. BIS certification requirements and CEA electrical safety regulations create compliance barriers for uncertified imports. Larsen & Toubro Limited leverages domestic fabrication capacity to serve institutional and infrastructure projects across Maharashtra and Karnataka.
Japan
Earthquake-resistant enclosure specifications and METI energy efficiency guidelines shape product requirements for industrial and commercial installations. Kanto and Kansai manufacturing clusters concentrate precision fabrication for premium fault-rated assemblies. Mitsubishi Electric Corporation serves domestic semiconductor fabrication and automotive plant upgrades with localized supply chains.
Electrical Sub Panels Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and geographic coverage dimensions, producing a tiered structure where scale-driven conglomerates share terrain with regional fabricators. Publicly traded electrical equipment majors control premium industrial segments through captive breaker and busbar production, while private specialists capture mid-market residential share via aluminum substitution strategies. Two strategic archetypes dominate: vertically integrated conglomerates with smelting-to-assembly control, and modular design specialists targeting EPA recycling compliance. Competitive moves concentrate on backward integration into copper processing and digital monitoring module partnerships.
Within the conglomerate tier, Schneider Electric and Siemens AG exemplify scale-driven positioning through European-anchored fabrication networks and captive supply chain control. ABB Ltd occupies a distinct vector emphasizing digital integration archetypes. Among Asia-Pacific-based fabricators, Mitsubishi Electric Corporation represents precision industrial specialization. These three named entities illustrate how competitive positioning stratifies across certification tier, material substitution capability, and geographic project engineering presence rather than converging on uniform product strategies.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens AG |
| ABB Ltd |
| Eaton Corporation |
| General Electric Company |
| Legrand SA |
| Mitsubishi Electric Corporation |
| Honeywell International Inc. |
| Larsen & Toubro Limited |
| Others |
Supply & Pricing Matrix
Project-based electrical contracting with take-or-pay clauses locks in copper busbar allocation and price visibility for hyperscale data center developers across Texas and Arizona, insulating procurement teams from LME copper volatility while exposing fabricators to fixed-cost absorption risk.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the electrical sub panels market. Price differentiation hinges on UL 67 certification tier and copper versus aluminum busbar specification, with premium fault-rated assemblies commanding sustained margin premiums. Cost compression in residential flush mount segments is intensifying because homebuilder procurement consolidation favors aluminum substitution. Residential contractors exhibit highest price sensitivity, while data center engineering firms demonstrate lowest sensitivity due to specification authority migration toward integrated digital monitoring bundles.
Supply Chain Analysis
Port congestion along the Shanghai-Los Angeles trade lane is extending inbound logistics cycles for cold-rolled steel enclosure components destined for NEMA 3R weatherproof assembly. Supply concentrates in China, Germany, and the United States for precision-fabricated panelboard housings, with raw material dependencies centering on copper cathode, cold-rolled steel coil, and molded-case circuit breaker platforms. Single-source vulnerability runs through captive breaker production at Schneider Electric and Siemens AG. Distribution runs through electrical wholesalers and direct project engineering channels serving contractor and owner-engineered procurement archetypes respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrical sub panels market functions as a regulatory entrenchment story where NEC code compliance creates formidable switching costs for facility operators and specification lock-in for approved vendors.
For Market Incumbents: Fortify specification authority through backward integration into copper smelting and rolling capacity, mirroring Schneider Electric's captive busbar supply model. Deepen certification investment in UL 67 arc-resistant enclosure variants to exploit testing laboratory capacity constraints that delay rival product approvals. Prioritize channel control over electrical contractor relationships in Texas and Arizona where journeyman workforce shortages constrain installation velocity and favor established supplier networks. For New Entrants and Emerging Players: Anchor in aluminum alloy busbar fabrication for 60-225 ampere residential segments where homebuilder cost pressure has displaced copper specifications in Arizona and Texas suburban developments. Target commercial load center configurations with integrated meter sockets for municipal submetering compliance in New York City and Seattle. Pursue go-to-market positioning through digital power monitoring module partnerships that satisfy LEED certification requirements without requiring full vertical integration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers offering 10-year warranty programs and field-replaceable busbar segments aligned with EPA copper recycling guidelines. Long-term viability favors acquisition targets with modular serviceable design capabilities and established relationships with hyperscale data center engineering firms. Monitor NEC amendment cycles for arc-energy reduction provisions as the critical inflection signal that accelerates replacement demand across installed commercial and industrial bases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Processing | Captive smelting capacity insulates margin control against LME price volatility for high-amperage assemblies. |
| Digital Power Monitoring Integration | IoT-enabled metering modules embed specification preference for LEED-certified commercial build-outs in Northern Virginia. |
| Modular Serviceable Design Redesign | Field-replaceable busbar segments maintain federal procurement eligibility under evolving EPA recycling thresholds. |
| Certification Fast-Track Investment | UL 67 pre-submission programs compress approval timelines amid testing laboratory capacity constraints. |
| Regional Fabrication Footprint Expansion | Localized panelboard production in Poland and Germany anchors Siemens AG's European project engineering presence. |
Research Methodology
Desk research of NEC code amendment filings, EPA electrical equipment lifecycle guidelines, and hyperscale data center permitting databases preceded structured interviews with electrical contractor purchasing managers, data center engineering firm specification leads, UL certification engineers, and copper busbar procurement directors. Primary fieldwork captured specification authority migration patterns and installation velocity constraints across Texas, Arizona, and Virginia corridors. Secondary validation drew from National Electrical Manufacturers Association shipment data, customs records for enclosure steel imports, and utility interconnection filings. Bottom-up panelboard volume estimates triangulated against top-down construction spending allocations.
Variance decomposition across product type, application environment, component sourcing, and installation context dimensions shaped the analytical framework over the projection horizon. Modeled segmentation captured flush mount versus weatherproof versus load center architectures, residential versus industrial versus commercial end-use splits, and copper versus aluminum busbar material substitution dynamics. CAGRs were derived from installation base replacement schedules, code amendment compliance deadlines, and data center construction pipeline tracking. Industry-specific forecast inputs incorporated NEC Article 408.36 arc-energy reduction adoption curves and municipal submetering mandate rollout timelines.
Underlying assumptions cover copper price stabilization within historical volatility bands and sustained hyperscale data center investment intensity across the Texas-Arizona-Virginia corridor, with deviation risk concentrated in tariff escalation for cold-rolled steel enclosure components and electrician workforce shortage persistence in high-growth installation markets. Forecasts reflect these documented assumptions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Earth Leakage Circuit Breakers Market
Electrical Equipment
Europe Electric Drives Market
Electrical Equipment
Low Voltage Circuit Breakers Market
Electrical Equipment
Cable Distribution Cabinets Market
Electrical Equipment
Magnetic Contactors Market
Electrical Equipment
Electrical Measuring Instrument Market
Electrical Equipment
DC Contactor Market
Electrical Equipment
Motor Control Centers (MMC) Market
Electrical Equipment
Global Cooling Fan Market
Electrical Equipment
Low Voltage Motor Control Centers Market
Electrical Equipment
Axial Fans Market
Electrical Equipment
Europe Circuit Breakers Market
Electrical Equipment
Copper and Aluminum Terminal Blocks Market
Electrical Equipment
Passover Humidifiers Market
Electrical Equipment
Contactors Market
Electrical Equipment
Electrical Steel Coatings Market