
 SPG Microstimulator System Market | 2026-2036
SPG Microstimulator System Market Size, Share, and Industry Trends Forecast 2026-2036
SPG Microstimulator System Market Analytics
Class III implant-grade biocompatibility is collapsing the gap between preclinical validation and commercial reimbursement for SPG microstimulators. Medtronic leverages its neuromodulation infrastructure to sustain dominant positioning in invasive peripheral nerve stimulation. Boston Scientific anchors its portfolio through specialized headache disorder programs that compete directly with pharmaceutical prophylaxis. Abbott differentiates via integrated diagnostic-stimulation platforms that occupy the premium tier of hospital procurement evaluations.
The SPG microstimulator system comprises miniaturized pulse generators and lead assemblies designed for percutaneous or surgical placement adjacent to the sphenopalatine ganglion, typically operating at frequencies between 20-120 Hz with charge-balanced biphasic waveforms to modulate parasympathetic outflow for craniofacial pain conditions. Its primary commercial purpose centers on providing reversible, dose-titrable neuromodulation for refractory cluster headache and migraine variants where pharmacotherapy fails. Implantable devices command the deepest margin pools due to surgical service bundling and long-term maintenance contracts, while wearable stimulators represent the fastest-expanding category as ambulatory pain management protocols gain institutional acceptance. Electrical stimulation technology leads absolute volume, though hybrid systems integrating optical feedback are attracting R&D concentration from device manufacturers seeking differentiation beyond pulse-parameter refinement.
FDA breakthrough device designation and the EU Medical Device Regulation reshape competitive timelines by accelerating review pathways while imposing clinical evidence requirements that favor well-capitalized developers. The European Medicines Agency coordinates with notified bodies under MDR to enforce post-market surveillance for active implantable devices, tightening market access for entrants lacking robust quality management systems. Stakeholders must monitor reimbursement coding decisions at CMS and parallel authorities, as category III CPT coding status for SPG procedures will determine whether hospital adoption converts to sustainable revenue or stalls in pilot-program limbo.
Market Dynamics
Class III implant-grade biocompatibility standards are compressing the validation-to-reimbursement timeline for SPG microstimulators, forcing manufacturers to front-load clinical evidence generation before FDA breakthrough pathway submissions.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways for peripheral nerve stimulation platforms reduce commercialization timelines from typical PMA cycles.
- Cluster Headache Treatment Centers:Specialized German neurological institutes are expanding implantable neurostimulation protocols for refractory craniofacial pain.
- Charge-Balanced Biphasic Waveforms:Advances in parasympathetic outflow modulation at 20-120 Hz frequencies improve therapeutic efficacy over first-generation devices.
Market Restraints
- Category III CPT Coding Uncertainty:CMS reimbursement status for SPG procedures remains unresolved, creating hospital procurement hesitation.
- Implant-Grade Titanium Supply Concentration:Biocompatible casing materials face sourcing constraints from limited qualified suppliers.
- Surgical Service Bundling Requirements:Implantable systems demand integrated operating room contracts that exclude standalone device vendors.
Strategic Opportunities
- Wearable Ambulatory Protocols:Non-implantable SPG stimulators for outpatient pain management represent the fastest-expanding device category.
- EU MDR Harmonization:Post-market surveillance alignment creates pathway for notified body certifications spanning multiple member states.
- Optical Feedback Integration:Hybrid systems combining electrical stimulation with real-time neural monitoring attract R&D investment from differentiated manufacturers.
Industry Challenges
- Neurostimulation Specialist Surgeon Availability:Percutaneous SPG placement requires fellowship-trained otolaryngologists and pain physicians in short supply.
- Long-Term Maintenance Contract Complexity:Battery replacement and lead revision services demand specialized field engineering infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SPG Microstimulator System Market |
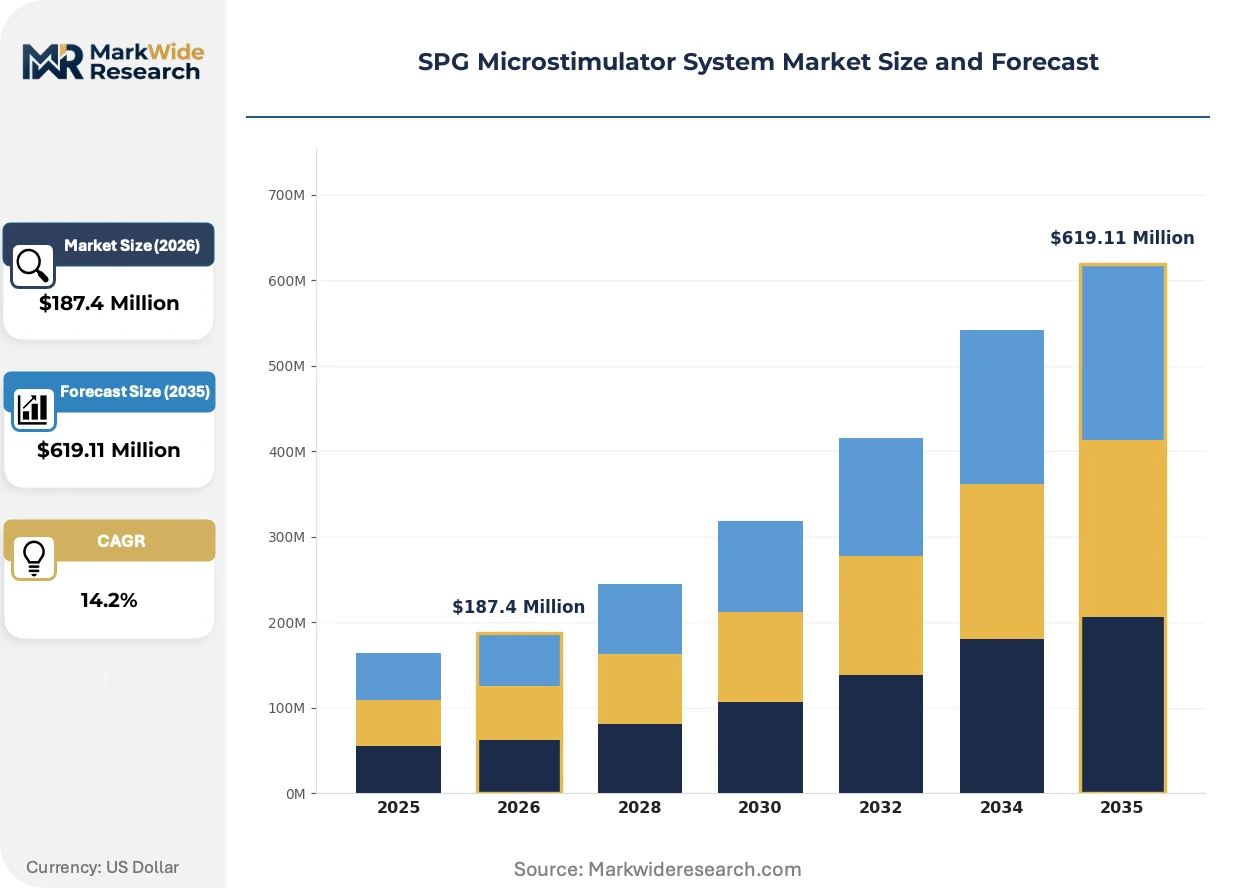
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Devices, Handheld Stimulators, Wearable Stimulators, Accessories End User: Hospitals, Clinics, Outpatient Surgical Centers, Research Institutions Application: Pain Management, Neurological Disorders, Rehabilitation, Diagnostics Technology: Electrical Stimulation, Magnetic Stimulation, Optical Stimulation, Hybrid Systems |
| Companies Covered | Autonomic Technologies, Inc., Theranica Bio-Electronics Ltd., ElectroCore LLC, SPR Therapeutics LLC, Pulsante, Inc, Medtronic, Boston Scientific, Abbott, Nevro Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SPG Microstimulator System Market Evolving Landscape
Neuromodulation hardware is converging with diagnostic sensing capabilities, reshaping how headache disorders are managed across academic medical centers and community hospitals.
Miniaturized pulse generators with integrated power management circuits are miniaturizing implant footprints below 3 cubic centimeters. Academic medical centers in Cleveland and Houston are piloting these reduced-form-factor devices for same-day surgical discharge protocols. The compression of generator size is enabling percutaneous placement techniques that displace open surgical approaches.
The EU Medical Device Regulation enforces clinical evidence requirements for active implantable devices that exceed previous directive standards. Notified bodies under MDR coordination with EMA are demanding post-market surveillance data that favors developers with established quality management systems. Implantable SPG systems face the steepest compliance burden, while wearable alternatives navigate lower-risk classification pathways.
Hospital procurement evaluations now weight integrated diagnostic-stimulation platforms more heavily than standalone pulse generators. Academic medical centers are unbundling device selection from surgical service contracts, creating direct purchasing relationships with manufacturers. This pattern is most visible in United States headache disorder programs competing with pharmaceutical prophylaxis for refractory patient populations.
SPG Microstimulator System Market Segmentation
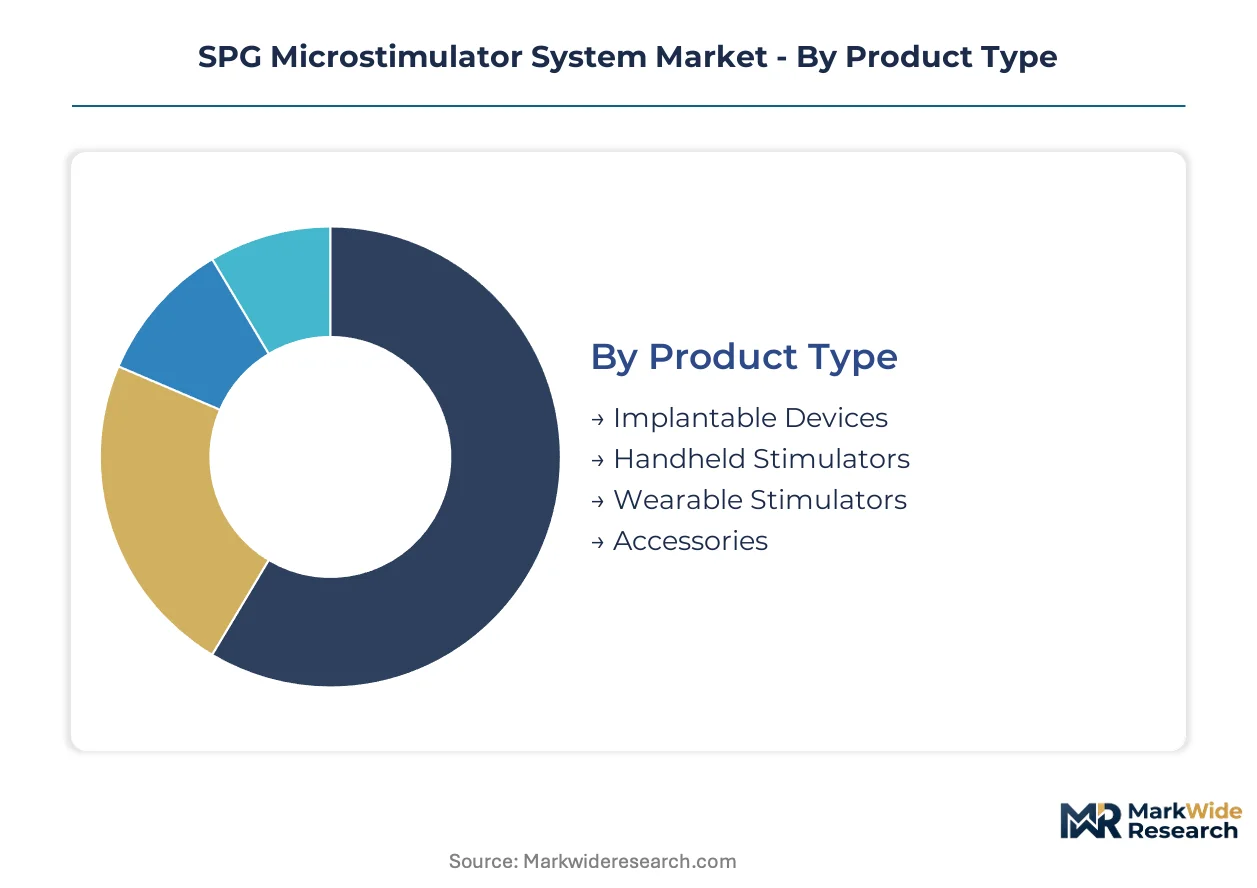
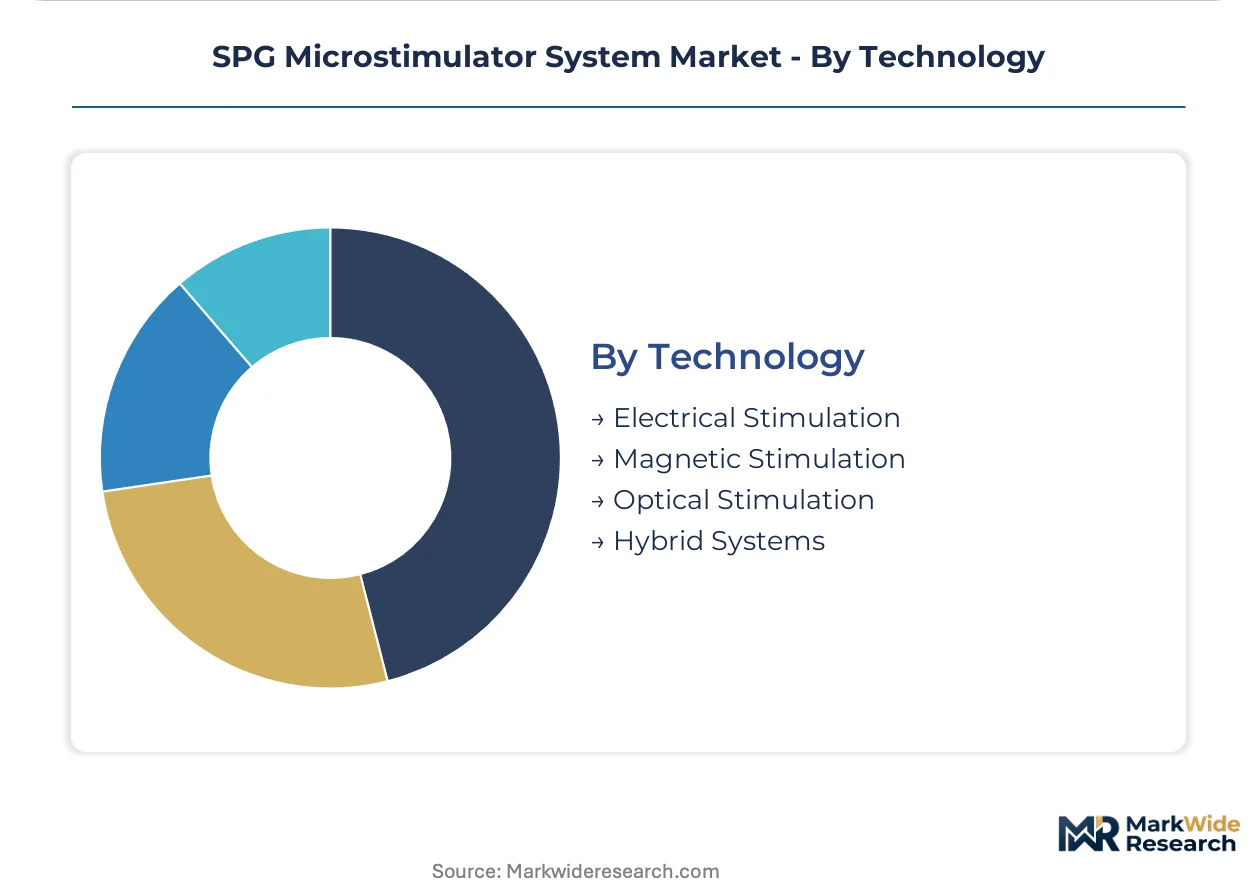
SPG microstimulator segmentation reveals distinct regulatory pathways and margin structures across device categories. Product classification determines whether systems face Class III PMA scrutiny or streamlined 510(k) clearance, fundamentally shaping commercialization economics.
Product Type:
FDA device classification tiers create divergent evidence requirements and reimbursement timelines across form factors.
- Implantable Devices:Miniaturized pulse generators with titanium biocompatible casings operate at 20-120 Hz frequencies for parasympathetic modulation. Cleveland Clinic and Houston Methodist anchor surgical adoption for refractory cluster headache protocols, though Category III CPT coding uncertainty stalls hospital procurement.
- Wearable Stimulators:Non-invasive external units with adhesive electrode arrays enable ambulatory pain management without surgical infrastructure. German neurological institutes are expanding these protocols fastest as outpatient neurostimulation gains institutional acceptance.
- Handheld Stimulators:Physician-administered percutaneous devices for clinic-based SPG targeting.
- Accessories:Lead assemblies, battery modules, and surgical placement kits supporting system maintenance.
Established volume favors Implantable Devices; emerging adoption favors Wearable Stimulators.
End User:
Procurement authority concentrates in settings with integrated surgical service bundling and specialized neuromodulation infrastructure.
- Hospitals:Academic medical centers with fellowship-trained otolaryngology and pain medicine programs dominate implantable system placement. These institutions negotiate direct purchasing relationships with manufacturers as service contracts unbundle from device selection.
- Clinics:Headache disorder specialty practices compete directly with pharmaceutical prophylaxis for refractory patient populations.
- Outpatient Surgical Centers:Same-day discharge protocols for reduced-form-factor generators are expanding addressable volume.
- Research Institutions:Clinical trial recruitment sites for FDA breakthrough pathway submissions.
Revenue concentration sits with Hospitals; volume expansion is climbing the fastest at Outpatient Surgical Centers.
Application:
Clinical indication determines reimbursement coding viability and addressable patient population scale.
- Pain Management:Refractory cluster headache and chronic migraine variants represent the primary commercial indication. SPG modulation delivers reversible, dose-titrable therapy where pharmacotherapy fails.
- Neurological Disorders:Autonomic dysregulation and craniofacial neuralgias constitute secondary indications with emerging evidence bases.
- Rehabilitation:Post-surgical recovery and trauma-related pain protocols.
- Diagnostics:SPG block procedures for headache subtype differentiation.
Current revenue anchors to Pain Management; steepest expansion trajectory is gaining share fastest in Neurological Disorders.
Technology:
Modality selection drives differentiation beyond pulse-parameter refinement as hardware converges with sensing capabilities.
- Electrical Stimulation:Charge-balanced biphasic waveforms dominate absolute volume with established safety profiles and reimbursement familiarity. Medtronic's neuromodulation infrastructure sustains positioning in this modality.
- Hybrid Systems:Integrated electrical stimulation with real-time optical feedback attracts R&D concentration from manufacturers seeking premium tier placement in hospital procurement evaluations.
- Magnetic Stimulation:Non-contact neuromodulation for patients contraindicated for implantable leads.
- Optical Stimulation:Emerging optogenetic approaches for targeted neural circuit modulation.
Technology maturity favors Electrical Stimulation; differentiation investment favors Hybrid Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Implant-grade titanium suppliers and specialized neurostimulation surgical centers cluster in three countries. Regulatory pathways diverge sharply between FDA breakthrough designation in the United States and EMA-MDR harmonization in Europe. Reimbursement coding decisions at national health technology assessment bodies will determine which geographies sustain commercial scale.
United States
Cleveland Clinic and Houston Methodist anchor clinical trial recruitment for SPG-targeted therapies. FDA breakthrough device designation compresses commercialization timelines for peripheral nerve stimulation platforms. Category III CPT coding uncertainty at CMS stalls hospital procurement beyond academic medical centers.
Germany
Cluster headache treatment centers in Berlin and Munich expand implantable neurostimulation protocols for refractory craniofacial pain. BfArM coordinates with notified bodies under EU MDR to enforce post-market surveillance for active implantable devices. Bavarian neurological institutes pilot wearable ambulatory protocols fastest in Europe.
Switzerland
Swissmedic maintains stringent clinical evidence requirements for Class III implantable devices that exceed baseline EU standards. Zurich and Geneva academic hospitals concentrate procurement authority for integrated diagnostic-stimulation platforms. The country's precision manufacturing base supplies biocompatible casing materials to device developers.
United Kingdom
NICE technology appraisals determine reimbursement viability for SPG microstimulator procedures in NHS England. London headache disorder specialty practices compete with pharmaceutical prophylaxis for refractory patient populations. The MHRA's post-Brexit regulatory autonomy creates parallel submission requirements for market access.
Japan
PMDA review pathways for neuromodulation devices emphasize long-term safety data from domestic patient populations. Tokyo and Osaka academic medical centers concentrate surgical expertise for percutaneous SPG placement. METI industrial policy supports domestic manufacturers developing hybrid electrical-optical stimulation systems.
SPG Microstimulator System Market Competitive Landscape
Concentration sits with diversified neuromodulation conglomerates possessing integrated surgical service bundling capabilities. The vendor base stratifies across three tiers: implantable device specialists with PMA track records, wearable stimulator entrants leveraging 510(k) pathways, and diagnostic-integrated platform developers seeking premium hospital procurement placement. Dominant competitive moves include M&A to acquire neurostimulation specialist surgeon networks and backward integration into implant-grade titanium supply.
Within the diversified medical technology tier, Medtronic, Boston Scientific, and Abbott occupy positions shaped by pre-existing neuromodulation infrastructure. Medtronic represents the archetype of surgical service bundling dominance. Boston Scientific exemplifies competition with pharmaceutical prophylaxis through specialized headache disorder programs. Abbott sits within the premium-tier vector via integrated diagnostic-stimulation platforms.
| Leading Market Players |
|---|
| Autonomic Technologies, Inc. |
| Theranica Bio-Electronics Ltd. |
| ElectroCore LLC |
| SPR Therapeutics LLC |
| Pulsante, Inc |
| Medtronic |
| Boston Scientific |
| Abbott |
| Nevro Corporation |
| Others |
Value Network & Pricing Analysis
Hybrid electrical-optical stimulation architectures are displacing pure electrical systems as the dominant R&D investment target, simultaneously shifting supply geography toward precision photonics manufacturing clusters and compressing pricing premiums for legacy pulse-generator platforms. This substitution dynamic concentrates bargaining power with buyers capable of qualifying multi-modal device platforms.
Pricing Analysis
FDA breakthrough device designation dictates the pricing tier structure across implantable SPG systems, with Class III PMA-track devices commanding premium positioning against 510(k) wearable alternatives. Price differentiation rests on biocompatibility certification grade and surgical service bundling depth. Cost compression in the wearable category is intensifying because German outpatient protocols are expanding addressable volume without OR infrastructure. Academic medical centers exhibit lowest price sensitivity; standalone clinics face acute procurement hesitation.
Supply Chain Analysis
Switzerland and Germany anchor implant-grade titanium casing production for Class III devices, while Taiwan and South Korea feed precision semiconductor components for pulse-generator miniaturization. The supply chain draws from concentrated biocompatible alloy suppliers and specialized cleanroom fabrication facilities. Single-source vulnerability in medical-grade titanium sourcing creates exposure to qualified supplier capacity constraints. Distribution runs through integrated surgical service contracts at academic medical centers and direct purchasing relationships unbundled from OR vendor agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fellowship-trained otolaryngologist and pain physician scarcity constrains surgical capacity expansion, making surgeon network control the decisive competitive moat for scalable SPG microstimulator deployment.
For Market Incumbents: Compound defensive positioning through backward integration into implant-grade titanium supply and captive training pipelines for percutaneous placement specialists. Emerging wearable stimulator entrants threaten premium-tier hospital procurement relationships by unbundling device selection from surgical service contracts. Priority investment in hybrid electrical-optical platform development preserves differentiation beyond pulse-parameter refinement. For New Entrants and Emerging Players: Post-market surveillance infrastructure gaps among established players create white-space for quality-management-system-native developers seeking EU MDR harmonization pathways. Wearable ambulatory protocols in German neurological institutes represent the most penetrable adoption vector. Target same-day discharge protocol enablement as the go-to-market anchor for reduced-form-factor generators. For Investors and Strategic Acquirers: The market sits at a regulatory-pathway-consolidation phase that favors developers with established PMA track records and breakthrough designation experience. Long-term viability hinges on reimbursement coding resolution at CMS and parallel national authorities. Acquisition target archetype: notified body-certified developers with hybrid platform pipelines. Signal to watch: Category III CPT coding decisions converting hospital pilot programs to sustainable revenue.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Pathway Submission | Accelerated review compresses commercialization timelines for peripheral nerve stimulation platforms. |
| EU MDR Notified Body Certification | Post-market surveillance alignment enables multi-member state market access for active implantable devices. |
| Hospital System Partnership | Direct purchasing relationships with Cleveland and Houston academic centers anchor clinical trial recruitment. |
| Software Companion Development | Integrated diagnostic-stimulation platforms occupy premium tier in procurement evaluations against pharmaceutical prophylaxis. |
| Reimbursement Strategy | Category III CPT coding pursuit at CMS determines whether adoption converts to sustainable revenue or stalls. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with device development executives, regulatory affairs leads, hospital purchasing committee members, and GPO contracts managers; and secondary validation through FDA 510(k) and PMA filings, EU MDR notified body documentation, CMS reimbursement coding databases, and hospital procurement contract records. Bottom-up and top-down triangulation cross-validated volume estimates across product type, end user, application, and technology segmentation dimensions.
Across the projection horizon, the analytical framework modeled implantable versus wearable device splits, surgical service bundling versus unbundled procurement patterns, and electrical versus hybrid stimulation modality adoption curves. CAGRs were derived from patient population epidemiology, procedure volume trajectories at anchor institutions, and reimbursement pathway probability-weighted scenarios. Forecast inputs incorporated FDA breakthrough designation velocity and EU MDR compliance cost burdens.
Forecasts assume regulatory continuity in FDA breakthrough pathways and EU MDR enforcement regimes; material policy shifts at CMS or BfArM would require re-modeling. Specific risks include Category III CPT coding denial, implant-grade titanium supply disruption, and wearable stimulator reclassification to higher-risk tiers. Recalibration cycles align with material shifts in reimbursement determinations and notified body certification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Arthroscopy Market
Medical Devices
Pneumatic Nebulizers Market
Medical Devices
Artificial Disc Market
Medical Devices
Australia Aesthetic Devices Market
Medical Devices
Global Thoracic Drainage Devices Market
Medical Devices
Airway Management Devices Market
Medical Devices
Cryosurgery Devices Market
Medical Devices
Global Subdermal Contraceptive Implants Market
Medical Devices
Global Vaginal Sling Market
Medical Devices
Lung Preservation Systems Market
Medical Devices
Global Transcatheter Embolization and Occlusion Devices Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
Ultrasound Probe Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
North America General Surgical Devices Market
Medical Devices
Non- Resorbable Cranial Fixation System Market