
 Lower Limb Prosthetics Market | 2026-2036
Lower Limb Prosthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Lower Limb Prosthetics Market Analytics
Leasing-based procurement for high-ankle carbon fiber feet is reconfiguring competitive access for mid-tier orthopedic clinics. Ottobock SE leverages its captive financing arm to lock in multi-year hospital contracts across Germany and the United States. Össur sustains R&D intensity through dedicated myoelectric labs in Iceland and Sweden. College Park Industries anchors its position with thermoplastic foot-ankle systems built at scale in Michigan.
Lower limb prosthetics are electromechanical or passive mechanical devices replacing anatomical structures from the hip through the foot, typically incorporating carbon fiber springs, titanium pylons, or lithium-ion powered microprocessor knees to restore gait kinematics and load bearing. Their primary purpose is to return ambulatory function to persons with amputation or congenital limb deficiency. Transtibial sockets and carbon fiber feet dominate unit volume due to lower fitting complexity and faster rehabilitation timelines. Bionic prosthetics command the fastest expansion as myoelectric knee-ankle coordination improves, though mechanical systems still occupy the bulk of reimbursed volume in emerging markets. Rehabilitation centers represent a concentrated margin pool where gait training bundling lifts lifetime account value per patient.
The FDA governs 510(k) clearance for microprocessor limbs, while the CMS National Coverage Determination shapes whether myoelectric knees qualify for fee-for-service reimbursement in the United States. ISO 10328 defines structural test methods for lower limb prosthetic components, forcing manufacturers to validate fatigue resistance before market entry. Stakeholders must monitor how FDA breakthrough device designations for neural-controlled sockets reshape the competitive boundary between conventional and bionic systems.
Market Dynamics
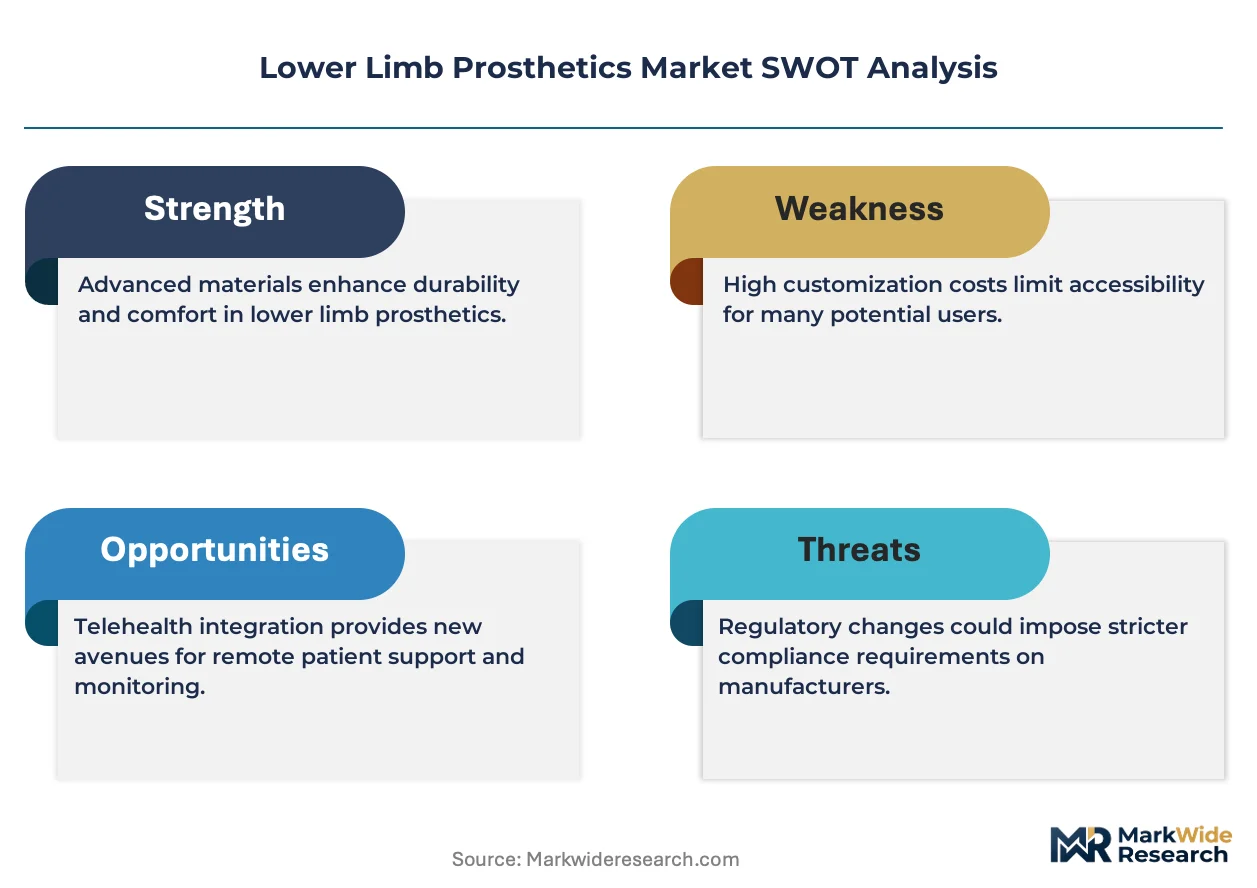
Hospital procurement departments are consolidating device budgets around microprocessor-controlled knee systems as FDA and CMS reimbursement criteria tighten, forcing manufacturers to validate clinical outcomes before contract eligibility.
Growth Catalysts
- VA Health System Expansion:The United States Department of Veterans Affairs channels substantial volume into advanced prosthetic systems, creating predictable demand pipelines for bionic knee-ankle coordination technologies.
- ISO 10328 Structural Validation:Standardized fatigue testing protocols enable component manufacturers to enter multiple regulatory jurisdictions with single validation datasets, compressing time-to-revenue.
- Myoelectric Laboratory Infrastructure:Dedicated R&D facilities in Iceland and Sweden advance neural-controlled socket interfaces, accelerating the translation of academic research into reimbursable clinical products.
Market Restraints
- Titanium Pylon Supply Concentration:Aerospace-grade titanium sourcing clusters in a limited number of specialty foundries, exposing prosthetic manufacturers to input price volatility and allocation risk.
- CMS National Coverage Determination Friction:Fee-for-service reimbursement restrictions on myoelectric knees create administrative burden that delays patient access and extends sales cycles for providers.
- Mechanical System Substitution:Passive carbon fiber feet and transtibial sockets retain dominant unit volume in price-sensitive emerging markets, limiting addressable market expansion for premium electromechanical systems.
Strategic Opportunities
- Leasing-Based Procurement Models:Captive financing arms enable multi-year hospital contract lock-in for high-ankle carbon fiber feet, reconfiguring competitive access for mid-tier orthopedic clinics.
- FDA Breakthrough Device Designation:Neural-controlled socket technologies receiving expedited review pathways can reshape competitive boundaries between conventional mechanical and bionic prosthetic categories.
- Rehabilitation Center Bundling:Gait training service integration with device provision lifts lifetime account value per patient, creating margin pools beyond hardware sales alone.
Industry Challenges
- Prosthetist Training Pipeline Constraints:Specialized fitting expertise for microprocessor limb systems requires extended clinical residencies, creating bottlenecks that limit installation capacity.
- 510(k) Clearance Timeline Variability:FDA premarket notification review periods for electromechanical components fluctuate based on predicate device availability, complicating product launch planning.
- Socket Interface Standardization Delays:Incompatible proprietary mounting systems across manufacturers force redundant inventory carrying costs for prosthetic clinics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lower Limb Prosthetics Market |
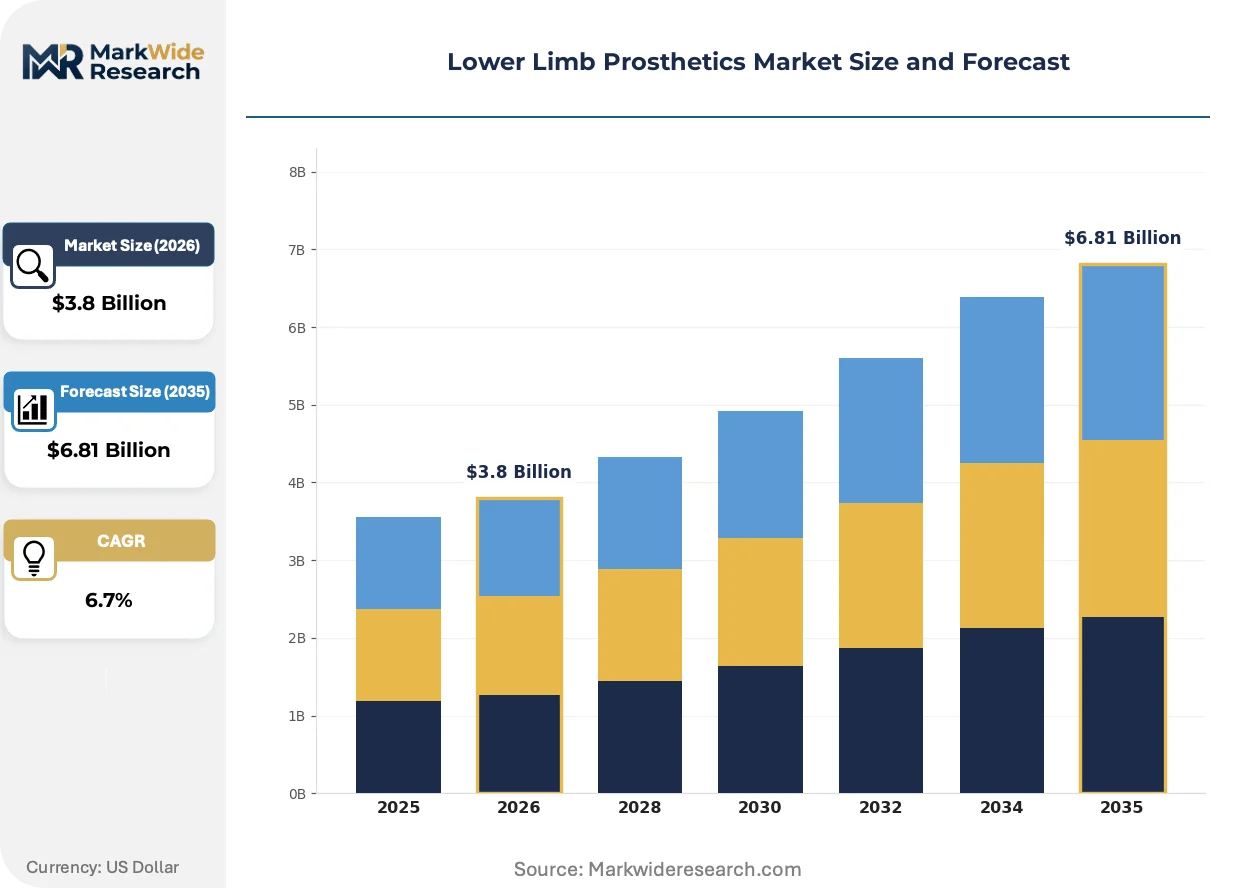
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transfemoral, Transtibial, Foot Prosthesis, Hip Disarticulation Material: Carbon Fiber, Aluminum, Thermoplastic, Composite Technology: Bionic Prosthetics, Mechanical Prosthetics, Myoelectric Prosthetics, Conventional Prosthetics End User: Hospitals, Rehabilitation Centers, Orthopedic Clinics, Home Care |
| Companies Covered | Blatchford, Steeper Group, Ottobock SE, Enovis, Endolite, Össur, College Park Industries, Hanger Clinic, Fillauer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lower Limb Prosthetics Market Evolving Landscape
Active reshaping of this market centers on the convergence of electromechanical control systems with traditional passive mechanics, creating hybrid architectures that bridge reimbursement categories and patient functional requirements.
Microprocessor knee-ankle coordination systems are hybridizing passive carbon fiber spring energy return with powered stance-phase control. Rehabilitation centers in the United States are adopting these hybrid platforms at accelerating pace to serve transitional amputees. This technology fusion compresses the historical segmentation between mechanical and bionic prosthetic categories, forcing manufacturers to develop dual-capability product architectures.
Europe's Medical Device Regulation (MDR) intensifies post-market surveillance obligations for electromechanical limb components. Manufacturers must now maintain clinical follow-up registries that track device performance across patient populations. Knee systems with software-driven control algorithms face the steepest compliance burden, prompting some suppliers to delay EU market entry until predicate data accumulates.
Orthopedic clinics are unbundling gait training from hardware procurement, creating separate service contracts that decouple device selection from rehabilitation provider choice. This disintermediation disrupts traditional manufacturer-clinic bundling arrangements. The United States exhibits the most visible manifestation, where private payer prior authorization requirements increasingly separate prosthetic device codes from therapy billing codes.
Lower Limb Prosthetics Market Segmentation
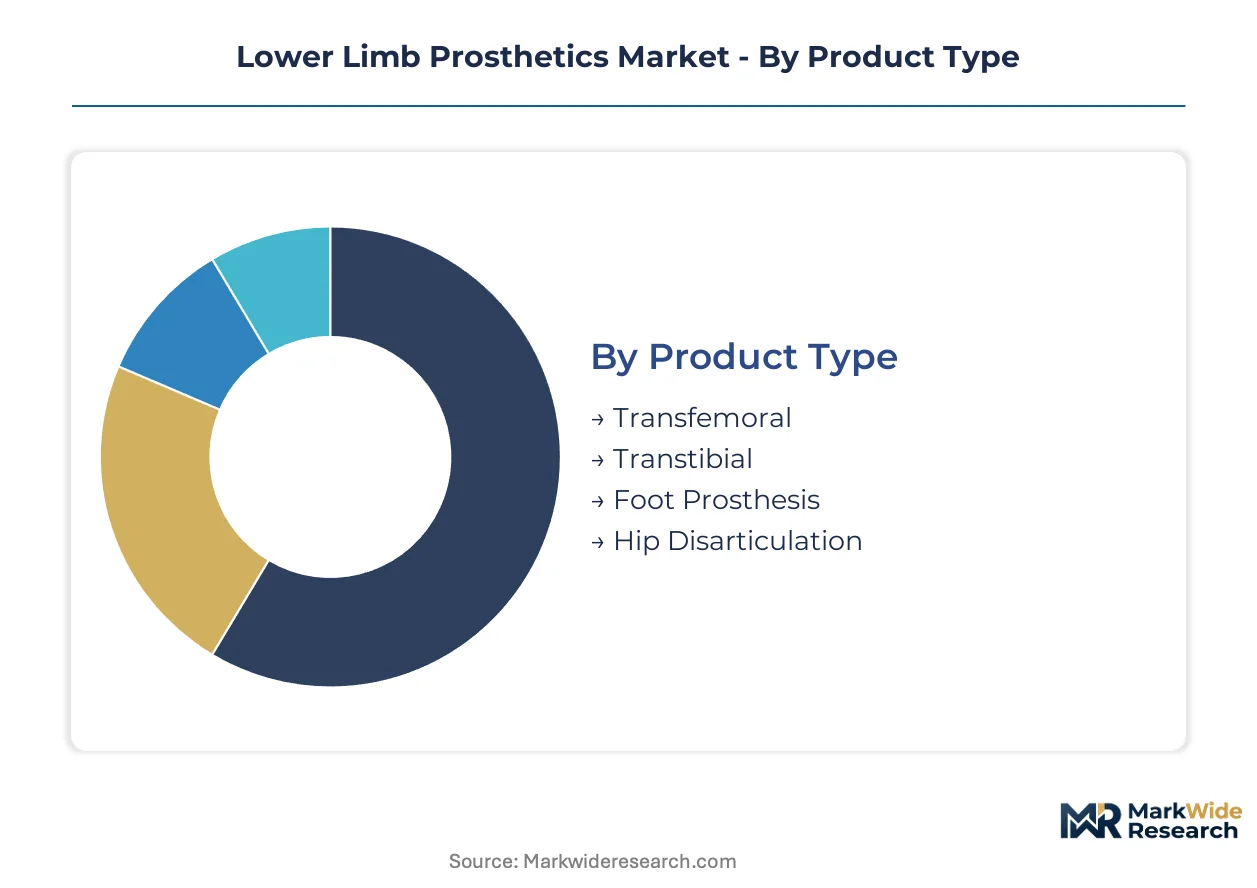
Lower limb prosthetics fragment across four structural dimensions that determine reimbursement pathways, manufacturing scale, and clinical adoption velocity. Product type governs socket engineering complexity and rehabilitation timelines. Material selection drives weight-bearing performance and insurance tier qualification. Technology tier separates passive mechanical systems from powered bionic platforms with divergent regulatory burdens. End-user channel dictates procurement contract structures and lifetime patient value capture.
Product Type:
Mature transfemoral and transtibial systems anchor reimbursed volume, while hip disarticulation represents an emerging frontier for specialized socket engineering.
- Transfemoral:Above-knee systems incorporate ischial weight-bearing sockets and either mechanical four-bar knees or microprocessor-controlled hydraulic units. Demand concentrates in United States VA health system contracts where microprocessor knee qualification criteria are tightening, forcing manufacturers to validate gait biomechanics before contract eligibility.
- Transtibial:Below-knee configurations dominate unit throughput with patellar tendon-bearing sockets paired to carbon fiber or thermoplastic feet. Rehabilitation centers in Germany and the United States fit these systems at accelerating pace due to shorter fitting timelines and faster ambulatory recovery trajectories.
- Foot Prosthesis:Modular ankle-foot systems span energy-storage carbon fiber springs to passive multi-axial designs for uneven terrain adaptation.
- Hip Disarticulation:Complete lower limb replacement requiring custom ischial-ramus containment sockets and specialized knee control linkages for limited patient populations.
Transtibial systems handle the majority of throughput; bionic transfemoral configurations are climbing the fastest on share as microprocessor coordination improves.
Material:
Cost tier separates aerospace-grade composites from commodity metals, with thermoplastic positioning as the mid-market bridge for price-sensitive procurement.
- Carbon Fiber:Woven epoxy-matrix composites deliver superior energy return-to-weight ratios for dynamic ambulation. Demand concentrates in high-activity patient segments and competitive athletics applications where deflection cycling durability justifies premium reimbursement tiers.
- Thermoplastic:Injection-molded polypropylene and copolymer variants enable scalable production of foot-ankle modules at cost points accessible to emerging market clinics. College Park Industries anchors manufacturing in Michigan with thermoplastic systems built for volume contract fulfillment.
- Aluminum:Extruded and machined alloy pylons provide corrosion-resistant structural members for saltwater exposure and pediatric growth-adjustable configurations.
- Composite:Hybrid fiber-reinforced polymer matrices combining glass and carbon fibers for intermediate stiffness and impact resistance in rugged-use environments.
Carbon fiber captures premium contract value; thermoplastic is expanding most quickly into mid-tier orthopedic clinic procurement.
Technology:
Application urgency separates emergency mechanical fitting from elective bionic upgrade pathways, with myoelectric interfaces representing the highest-margin clinical frontier.
- Mechanical Prosthetics:Passive systems with friction knees and rubber bumpers dominate emerging market volume where reimbursement constraints limit electromechanical access. ISO 10328 structural validation enables single-test market entry across multiple regulatory jurisdictions.
- Bionic Prosthetics:Powered knee-ankle coordination with lithium-ion energy storage and terrain-adaptive algorithms commands fastest expansion in United States private payer and VA channels. Össur sustains R&D intensity through dedicated myoelectric laboratories in Iceland and Sweden.
- Myoelectric Prosthetics:Surface electrode-controlled limb systems translating residual muscle signals into joint actuation, currently concentrated in upper limb applications with lower limb translation accelerating.
- Conventional Prosthetics:Historical wood-and-leather constructions persisting in humanitarian and low-resource settings with minimal regulatory oversight.
Mechanical systems retain dominant unit volume; bionic platforms are gaining share fastest as FDA breakthrough device designations accelerate neural-controlled socket commercialization.
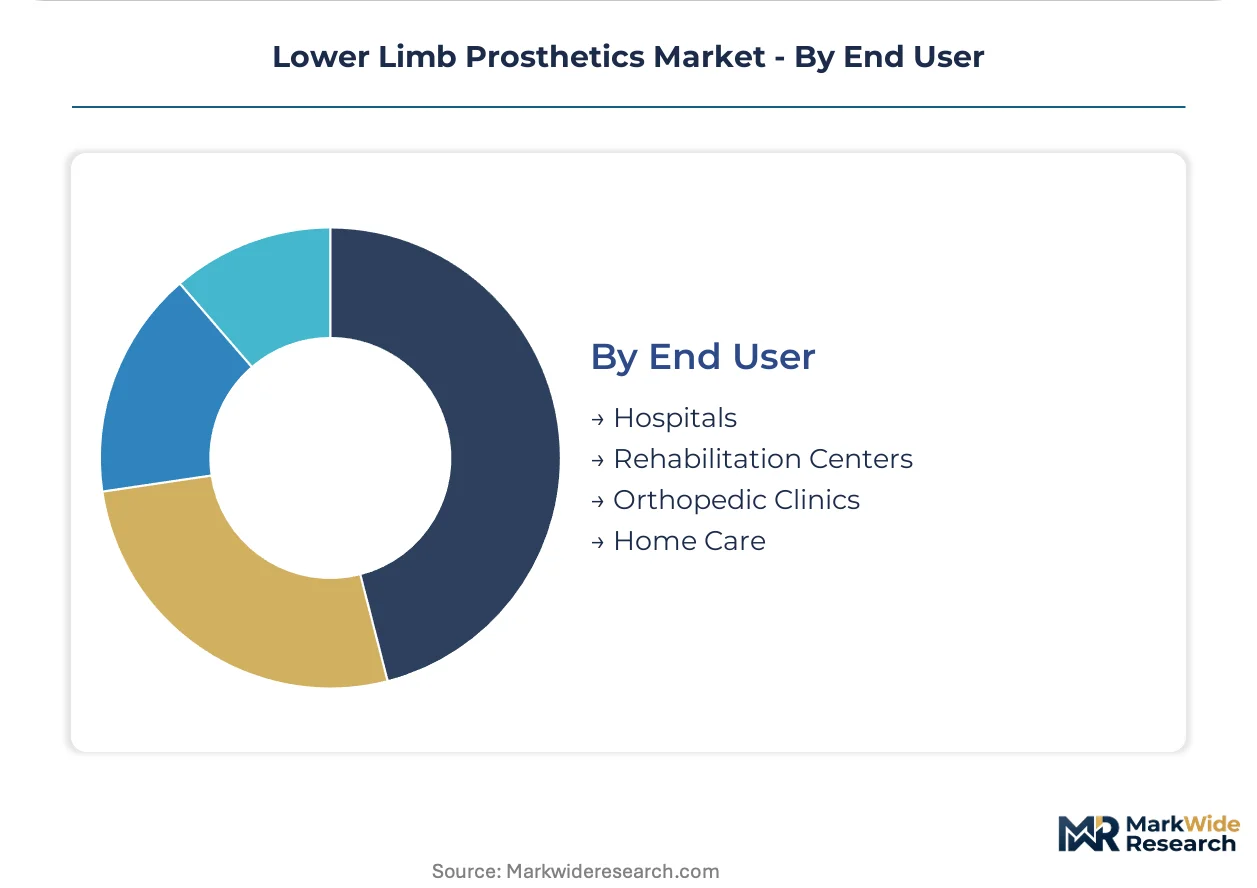
End User:
Customer type determines procurement leverage, with hospital systems consolidating device budgets while home care channels fragment purchasing authority.
- Hospitals:Acute care and surgical centers with centralized procurement departments negotiating multi-year device contracts. Ottobock SE leverages captive financing arms to lock in these relationships across Germany and the United States.
- Rehabilitation Centers:Specialized gait training facilities bundling device provision with therapy services to lift lifetime account value per patient. These centers represent concentrated margin pools where functional outcome metrics justify premium technology adoption.
- Orthopedic Clinics:Community-based prosthetist practices with fragmented purchasing power and inventory carrying constraints from incompatible proprietary socket mounting systems.
- Home Care:Direct-to-patient channels emerging in private-pay segments for socket maintenance supplies and cosmetic covering replacements outside reimbursed fitting cycles.
Hospitals handle the majority of throughput; rehabilitation centers are expanding most quickly as gait training unbundling creates separate service contract opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policy intensity varies sharply across national health systems, with public procurement frameworks determining access velocity for microprocessor-controlled limb systems. Government veteran affairs programs and national insurance schemes represent the dominant demand channels, while regulatory validation requirements create divergent market entry timelines for electromechanical component suppliers.
United States
The Department of Veterans Affairs channels substantial device volume through centralized procurement contracts, creating predictable demand pipelines for advanced knee-ankle coordination technologies. FDA 510(k) clearance timelines for electromechanical components fluctuate based on predicate device availability, complicating product launch scheduling for manufacturers. Rehabilitation centers in Michigan and California are unbundling gait training from hardware procurement, creating separate service contract structures that reshape traditional manufacturer-clinic relationships.
Germany
Statutory health insurance funds maintain generous reimbursement schedules for microprocessor limbs, sustaining above-average adoption rates for bionic knee systems relative to European peers. The national medical device regulator enforces ISO 10328 structural validation protocols that enable component manufacturers to enter multiple EU jurisdictions with single test datasets. Industrial clusters in North Rhine-Westphalia host captive financing operations that lock in multi-year hospital contracts for high-ankle carbon fiber feet.
Japan
PMDA marketing approval pathways for powered prosthetic components emphasize clinical follow-up registries that track long-term gait biomechanics outcomes. METI industrial policy directs research subsidies toward myoelectric interface development, accelerating translation of academic neural-control research into reimbursable products. Manufacturing concentration in the Nagoya-Chubu corridor supplies precision titanium pylons to domestic prosthetic fabricators facing aerospace-grade metal sourcing constraints.
United Kingdom
NHS England procurement frameworks are consolidating device budgets around microprocessor knee systems with validated functional outcome metrics, tightening contract eligibility criteria. MHRA post-market surveillance obligations intensify for software-driven control algorithms, prompting some suppliers to delay UK market entry until predicate clinical data accumulates. The Steeper Group anchors domestic fabrication capacity in Leeds, serving both NHS contracts and private payer channels with differentiated product tiers.
Sweden
County council procurement consortia negotiate centralized contracts for electromechanical limb systems, compressing price points for microprocessor knees through volume aggregation. The national social insurance agency coordinates rehabilitation benefit structures that bundle device provision with gait training services, lifting lifetime patient value capture for integrated providers. Össur operates dedicated myoelectric laboratories in Reykjavik and Stockholm, advancing neural-controlled socket interfaces for eventual lower limb translation.
Lower Limb Prosthetics Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated manufacturers with captive financing capabilities and multi-year hospital contract lock-in mechanisms. Strategic archetypes divide between scale-driven component fabricators with thermoplastic molding expertise, myoelectric R&D specialists with dedicated laboratory infrastructure, and full-limb system integrators with prosthetist training networks. Dominant competitive moves include backward integration into aerospace-grade titanium sourcing and geographic expansion through rehabilitation center acquisition.
Among European-integrated system suppliers, Ottobock SE and Össur occupy positions that exemplify divergent R&D localization strategies. The former leverages German captive financing arms to secure multi-year procurement contracts, while the latter sustains innovation intensity through Nordic laboratory concentration. Blatchford and Steeper Group represent UK-based fabrication specialists with NHS contract anchoring. College Park Industries exemplifies the mid-tier thermoplastic scale player with Michigan manufacturing concentration.
| Leading Market Players |
|---|
| Blatchford |
| Steeper Group |
| Ottobock SE |
| Enovis |
| Endolite |
| Össur |
| College Park Industries |
| Hanger Clinic |
| Fillauer |
| Others |
Value Network & Pricing Analysis
Aerospace-grade titanium sourcing concentrates in specialty foundries clustered across Japan and Germany, anchoring margin pools in downstream electromechanical knee assembly where pylon cost pass-through determines contract competitiveness. This upstream concentration forces manufacturers to absorb volatility or push pricing adjustments through multi-year hospital procurement cycles.
Pricing Analysis
Certification level creates the primary spread between premium FDA 510(k)-cleared microprocessor knees and standard ISO 10328-validated mechanical systems. Three-tier pricing structure across premium, standard, and economy levels separates bionic platforms with myoelectric interfaces from carbon fiber feet and aluminum pylon configurations. Pricing pressure stems from CMS reimbursement restrictions on myoelectric knees that compress provider margins and extend sales cycles. Orthopedic clinics exhibit highest price sensitivity due to fragmented purchasing power and inventory carrying constraints, while VA health system contracts demonstrate lowest sensitivity given centralized budget allocation.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for carbon fiber pre-preg and lithium-ion battery cells used in powered knee systems. Manufacturing draws from Germany for precision hydraulic components, Iceland and Sweden for myoelectric R&D hardware, and Michigan for thermoplastic foot-ankle molding. Single-source vulnerability persists in aerospace-grade titanium pylon supply where specialty foundry capacity constraints create allocation bottlenecks. Distribution runs through hospital procurement departments and rehabilitation center networks with multi-year contract lock-in mechanisms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gait training service bundling expands faster than hardware sales alone, creating recurring revenue layers that lift lifetime account value per patient beyond device margins. This service-attach dynamic reconfigures competitive positioning around outcome-based contracts rather than transactional procurement.
For Market Incumbents: Pre-empt emerging myoelectric laboratory specialists by securing exclusive prosthetist training pipeline capacity before neural-controlled socket interfaces achieve FDA breakthrough device designation. Backward integration into aerospace-grade titanium sourcing defends against pylon cost volatility that threatens microprocessor knee margins. Lock in multi-year rehabilitation center partnerships with captive financing arms to prevent gait training unbundling from eroding hardware attach rates.
For New Entrants and Emerging Players: Build out thermoplastic foot-ankle manufacturing scale to serve mid-tier orthopedic clinics in price-sensitive emerging markets where mechanical systems retain dominant unit volume. Target transtibial socket configurations with shorter fitting timelines and faster rehabilitation trajectories that bypass incumbent prosthetist training bottlenecks. Pursue direct-to-clinic distribution models that circumvent hospital procurement department consolidation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed rehabilitation center networks seeking platform consolidation to capture gait training service margins. Five-to-ten year viability hinges on reimbursement policy stability for microprocessor limbs rather than hardware commoditization risk. Monitor FDA breakthrough device designation velocity for neural-controlled sockets as the inflection signal separating bionic platform winners from mechanical system incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS National Coverage Determination alignment accelerates myoelectric knee patient access and shortens sales cycles. |
| Hospital System Partnership | Multi-year procurement contracts with VA health systems create predictable demand pipelines for bionic platforms. |
| CE Marking Pathway | MDR compliance for software-driven knee algorithms enables EU market entry with single validation datasets. |
| Software Companion Development | Gait training apps bundled with microprocessor knees lift lifetime account value per patient beyond hardware margins. |
| Backward Integration | Captive titanium pylon production insulates margin compression from aerospace-grade metal allocation constraints. |
Research Methodology
Cross-validation between prosthetist practice interviews and CMS reimbursement database analysis anchors the qualitative findings on procurement behavior shifts. Primary fieldwork engaged prosthetist clinic owners, hospital purchasing committee members, VA contracts administrators, and biomedical engineering directors across the United States, Germany, and Sweden. Secondary sources incorporated FDA 510(k) clearance records, ISO 10328 structural test filings, hospital GPO contract databases, and prosthetic component trade flow data. Bottom-up demand modeling triangulated against top-down reimbursement expenditure estimates.
Calibration against historical microprocessor knee adoption curves and mechanical system replacement cycles shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type, material grade, technology tier, and end-user channel with regional regulatory cluster overlays. CAGRs derived from fitted adoption S-curves for bionic platforms and linear extrapolation for mature mechanical categories. Industry-specific inputs incorporated prosthetist training pipeline capacity constraints and FDA review timeline variability.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated manufacturers with captive financing arms would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
3D Printed Medical Devices Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Global Ileostomy Market
Medical Devices
Hydrogel Contact Lenses Market
Medical Devices
Ventricular Restoration Systems Market
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
Patellar Implant Market
Medical Devices
Drug Device Combination Products Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
Saudi Arabia Aesthetic Devices Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
Table-Top Autorefractor Market
Medical Devices
Portable Medical Electronic Products Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
United Kingdom Respiratory Devices Market
Medical Devices
Medical Goggle Market