
 Ventilator Breathing Circuit Market | 2026-2036
Ventilator Breathing Circuit Market Size, Share, and Industry Trends Forecast 2026-2036
Ventilator Breathing Circuit Market Insights
Single-use polymer engineering is tilting ventilator breathing circuit production toward higher-grade silicone and polyurethane formulations. GE Healthcare leverages captive polymer compounding to sustain margin control across heated circuit lines. Medtronic anchors North American hospital supply contracts through centralized procurement relationships. Dräger competes on European home care channels with modular circuit platforms that reduce ventilator changeover time.
A ventilator breathing circuit constitutes the closed-loop conduit assembly connecting a mechanical ventilator to a patient's airway, typically comprising inspiratory and expiratory limbs with humidity delivery ports and pressure-monitoring lines, manufactured through extrusion molding and leak-tested to ISO 5367 standards for gas flow resistance and compliance. Disposable circuits dominate hospital procurement due to cross-contamination protocols, while heated circuits capture premium positioning in long-term acute care where airway conditioning prevents mucus plugging. PVC retains volume leadership in material selection, though polyurethane extends into neonatal applications demanding greater flexibility and lower compression volume.
FDA 510(k) clearance requirements and EU MDR Class IIa designation enforce biocompatibility testing and clinical evidence thresholds that lengthen time-to-market for new circuit designs. ISO 5367 and IEC 60601-1-8 standards govern connector interoperability and alarm integration, directly influencing R&D allocation across manufacturers. Stakeholders must monitor evolving EPA and ECHA restrictions on phthalate plasticizers in PVC circuits, as material substitution timelines will reshape supplier qualification and cost structures ahead of regulatory deadlines.
Market Dynamics
FDA and EU MDR Class IIa designation timelines are compressing product development cycles as manufacturers reallocate R&D toward biocompatibility validation and clinical evidence generation ahead of clearance deadlines.
Growth Catalysts
- EU MDR sterility mandates:Disposable heated circuits capture premium positioning in German and French tertiary hospitals as infection control protocols tighten replacement frequency.
- Silicone polymer advancement:Higher-grade formulations reduce compression volume in neonatal circuits, expanding addressable indications in pediatric intensive care.
- China critical care infrastructure:Provincial hospital expansion in Sichuan and Guangdong accelerates ventilator procurement and circuit replacement rates.
Market Restraints
- Phthalate substitution costs:EPA and ECHA restrictions on DEHP plasticizers in PVC circuits force material requalification and supplier auditing expenses.
- Polymer supply concentration:Medical-grade silicone resin production clusters in Germany and Japan, exposing converters to geographic disruption risk.
- ISO 5367 testing burden:Gas flow resistance and connector interoperability validation extends time-to-market for modular circuit designs.
Strategic Opportunities
- Home care channel expansion:Dräger's modular platforms in European markets demonstrate reduced ventilator changeover time, opening reimbursement pathways for long-term acute care discharge.
- Polyurethane neonatal penetration:Lower compression volume specifications address unmet flexibility requirements in premature infant ventilation.
- Centralized procurement consolidation:North American hospital supply contracts favor vendors with captive polymer compounding and volume scale.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 cytotoxicity and sensitization studies face laboratory backlog, delaying FDA 510(k) submission timelines.
- Legacy ventilator interoperability:Alarm integration per IEC 60601-1-8 requires firmware adaptation across installed base of heterogeneous ICU equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ventilator Breathing Circuit Market |
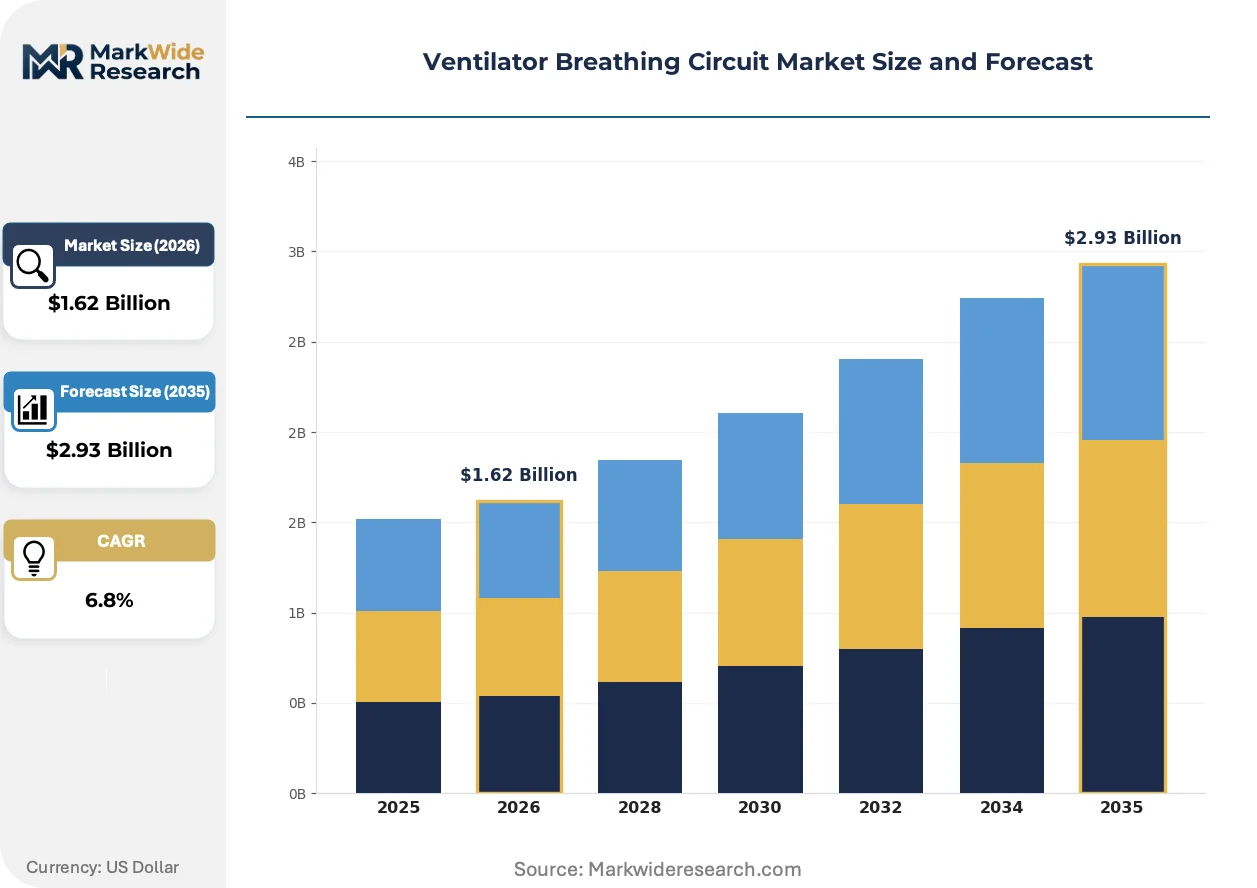
| Market Size in 2026 | $1.62 Billion |
| Market Size in 2035 | $2.93 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Circuits, Disposable Circuits, Heated Circuits, Non-Heated Circuits End User: Hospitals, Home Care, Rehabilitation Centers, Long-Term Care Facilities Material: Silicone, PVC, Polyurethane, Latex Connection Type: Corrugated, Smoothbore, Spiral, Others |
| Companies Covered | GE Healthcare, Getinge, Medtronic, ResMed, Philips Healthcare, Smiths Medical, Hamilton Medical, Vyaire Medical, Dräger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ventilator Breathing Circuit Market Trends and Innovations
Sensor-embedded circuit architectures and heated-wire control systems are converging to enable real-time airway conditioning feedback, compressing the gap between mechanical ventilation and physiological demand.
Micro-pressure transducer integration into expiratory limbs is digitizing flow monitoring accuracy in long-term acute care settings. Tertiary hospitals in the United States are piloting these configurations to reduce mucus plugging incidents. The technology is digitizing clinical workflow by enabling predictive maintenance alerts and automated humidity adjustment protocols.
REACH Annex XVII phthalate restrictions are forcing PVC compounders to validate citrate-based plasticizer alternatives ahead of 2025 sunset dates. German converters face reformulation costs and migration testing burdens. Heated circuit manufacturers serving neonatal segments are accelerating polyurethane adoption to preempt regulatory non-compliance exposure.
Hospital procurement departments are consolidating ventilator breathing circuit sourcing through multi-year enterprise agreements that bundle disposable and heated configurations. Group purchasing organizations in the United States are displacing spot-buying patterns with committed volume contracts. This concentration is most visible in IDN-affiliated tertiary centers where standardization across facilities reduces clinical training overhead.
Ventilator Breathing Circuit Market Segmentation
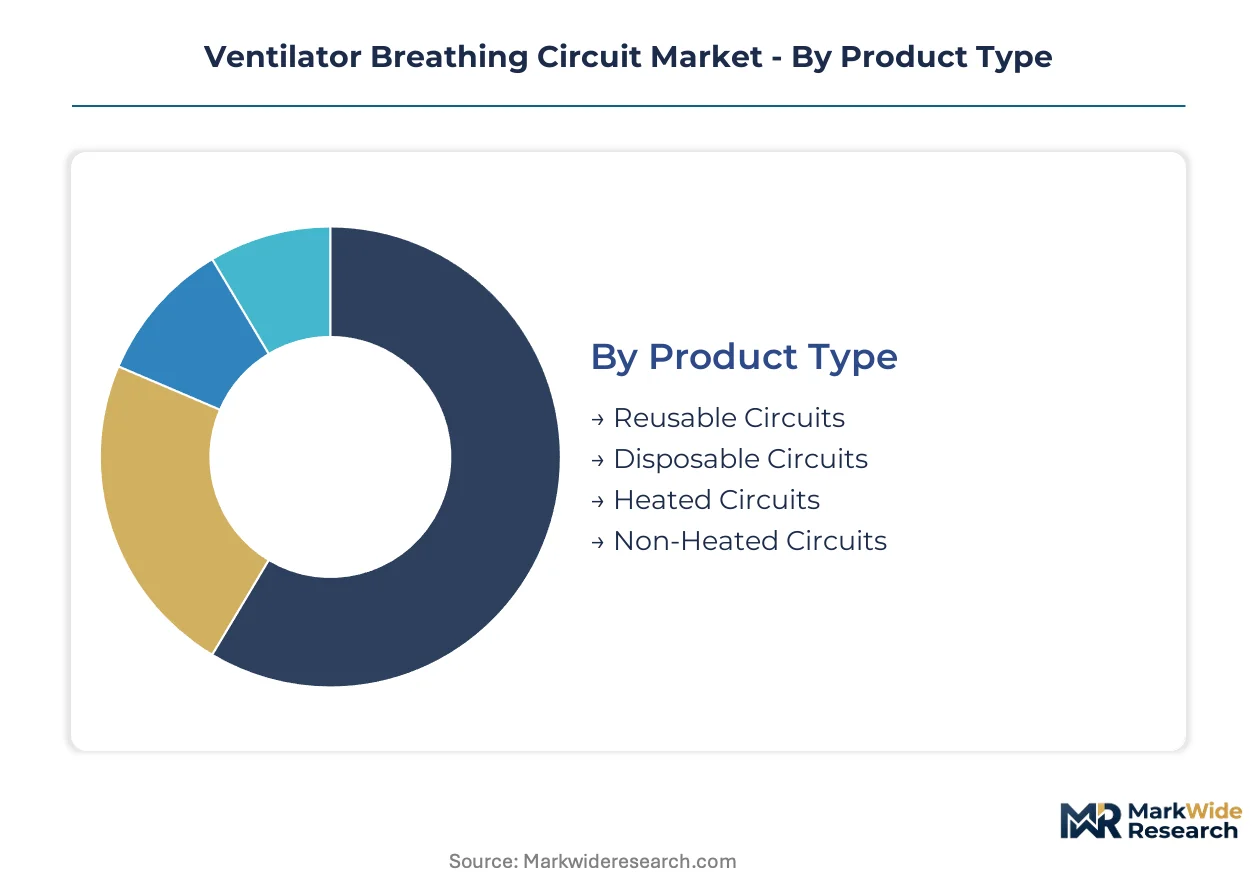
Segmentation in ventilator breathing circuits reveals how procurement priorities diverge across clinical settings and patient acuity levels. Product durability, sterility protocols, and airway conditioning requirements reshape vendor positioning and service contract structures.
Product Type:
After-sales-service intensity varies sharply across product lifecycles, with reusable circuits demanding preventive maintenance programs and disposable lines requiring rapid replenishment logistics.
- Disposable Circuits:Single-use polymer assemblies eliminate cross-contamination risk in ICU environments. Demand concentrates in United States tertiary hospitals where Joint Commission infection control audits drive replacement frequency.
- Heated Circuits:Integrated heating elements maintain conditioned gas delivery through inspiratory limbs, reducing rainout and mucus plugging. Long-term acute care facilities in Germany favor these configurations for ventilator-dependent patients with extended weaning timelines.
- Reusable Circuits:Autoclavable silicone constructions withstand repeated sterilization cycles, serving resource-constrained settings with centralized reprocessing infrastructure.
- Non-Heated Circuits:Standard polymer tubing without active conditioning elements addresses cost-sensitive procurement in emerging market hospitals with passive humidification protocols.
Disposable circuits hold the largest share; momentum sits with heated circuits.
End User:
Cost tier stratification separates capital-intensive hospital systems from reimbursement-constrained home care channels, reshaping pricing architectures and distribution models.
- Hospitals:Tertiary ICU departments drive specification authority through centralized value-analysis committees. China provincial hospital expansion in Sichuan and Guangdong accelerates ventilator procurement and circuit replacement rates.
- Home Care:Portable ventilator configurations demand lightweight, compact circuit designs with simplified interfaces for caregiver operation. European reimbursement pathways in France and Germany support discharge from long-term acute care to home settings.
- Rehabilitation Centers:Weaning-focused ventilation protocols require circuits compatible with progressive ventilator liberation strategies and respiratory therapy training programs.
- Long-Term Care Facilities:Skilled nursing environments balance infection control with cost containment, favoring disposable circuits in ventilator-dependent resident populations.
Hospitals dominate volume; home care is expanding most quickly.
Material:
Supply concentration for medical-grade polymers in Germany and Japan exposes converters to geographic disruption risk, influencing material substitution timelines.
- Silicone:Platinum-cured formulations deliver biocompatibility and thermal stability across autoclave cycles. Neonatal applications in pediatric intensive care demand low compression volume specifications.
- PVC:Plasticized polyvinyl chloride retains cost leadership through high-volume extrusion, though EPA and ECHA restrictions on DEHP plasticizers force citrate-based alternative validation.
- Polyurethane:Thermoplastic elastomer constructions offer superior flexibility and kink resistance for mobile ventilator applications and premature infant ventilation.
- Latex:Natural rubber components persist in legacy equipment interfaces despite allergen concerns, serving replacement part demand for installed base maintenance.
PVC holds the largest share; polyurethane shows the steepest expansion trajectory.
Connection Type:
Volume concentration in corrugated configurations reflects legacy equipment compatibility requirements and established clinical training patterns across respiratory therapy departments.
- Corrugated:Ribbed polymer construction permits axial flexibility and crush resistance in high-traffic ICU environments. Standardization across ventilator brands reduces inventory complexity for United States hospital supply chains.
- Smoothbore:Uniform internal diameter minimizes flow resistance and turbulent gas delivery, supporting precise pressure control in neonatal and pediatric ventilation.
- Spiral:Reinforced helical structure prevents kinking during patient repositioning and transport ventilation scenarios.
- Others:Specialized connector geometries address proprietary ventilator interfaces and custom anesthesia machine configurations.
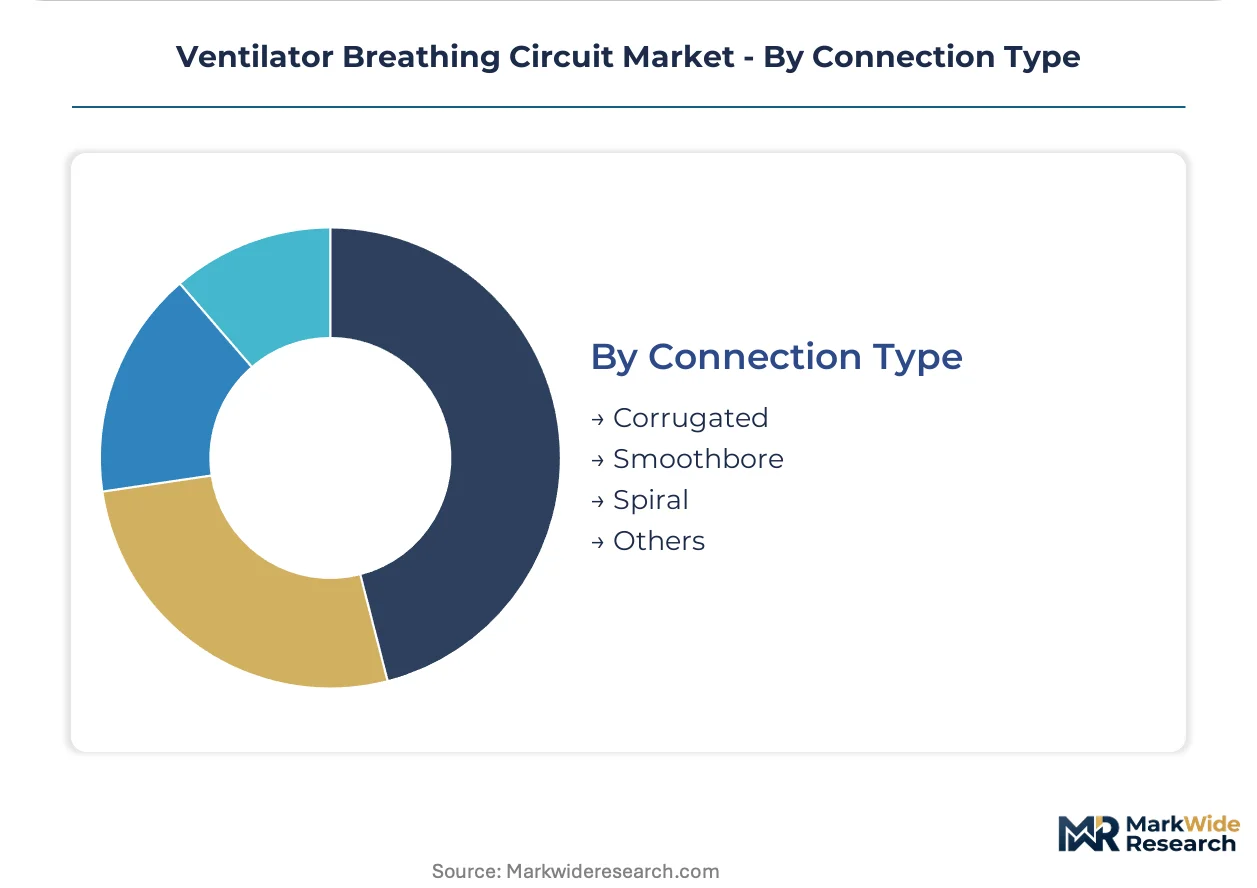
Corrugated connections hold the largest share; smoothbore configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in tertiary care systems concentrate demand across four major economies. Each geography exhibits distinct regulatory timelines and infrastructure investment patterns that reshape circuit replacement rates.
United States
Joint Commission infection control audits drive replacement frequency in tertiary ICUs. FDA 510(k) clearance requirements enforce biocompatibility testing thresholds that extend time-to-market for new designs. The Southeast hospital corridor accelerates ventilator procurement as IDN-affiliated centers standardize circuit configurations across facilities.
Germany
Long-term acute care facilities favor heated circuits for ventilator-dependent patients with extended weaning timelines. ECHA REACH Annex XVII phthalate restrictions force PVC compounders to validate citrate-based alternatives ahead of regulatory deadlines. Medical-grade silicone resin production clusters in Bavaria expose converters to geographic concentration risk.
China
Provincial hospital expansion in Sichuan and Guangdong accelerates ventilator procurement and circuit replacement rates. NMPA biocompatibility standards align with international ISO 10993 frameworks, streamlining import substitution pathways. The Yangtze River Delta hosts polymer compounding infrastructure serving domestic circuit manufacturers.
Japan
Pediatric intensive care units demand low compression volume specifications for neonatal applications. PMDA Class II device designation requires clinical evidence generation comparable to EU MDR thresholds. The Kansai region maintains specialized silicone formulation capabilities for medical device supply chains.
France
Home care reimbursement pathways support discharge from long-term acute care to residential settings. ANSM post-market surveillance requirements tighten sterility assurance documentation for disposable circuits. The Île-de-France hospital network pilots sensor-embedded architectures for real-time airway conditioning feedback.
Ventilator Breathing Circuit Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent procurement pathways. The market exhibits tiered consolidation where diversified medical device conglomerates anchor hospital supply contracts while regional fabricators serve spot-buying patterns. Three archetypes dominate: polymer-integrated manufacturers with captive compounding, modular platform specialists targeting home care channels, and disposable-focused converters optimizing high-volume extrusion. Competitive moves center on centralized procurement consolidation and material substitution ahead of phthalate regulatory deadlines.
Among diversified healthcare conglomerates, GE Healthcare, Medtronic, and Dräger occupy positions spanning multiple archetypes. GE Healthcare exemplifies polymer-integrated manufacturing through captive compounding infrastructure. Medtronic anchors North American hospital supply relationships through scale-driven contract positioning. Dräger represents modular platform specialization with European home care channel penetration. These three entities collectively illustrate how vertical integration, procurement consolidation, and channel-specific product architectures define competitive differentiation in circuit supply.
| Leading Market Players |
|---|
| GE Healthcare |
| Getinge |
| Medtronic |
| ResMed |
| Philips Healthcare |
| Smiths Medical |
| Hamilton Medical |
| Vyaire Medical |
| Dräger |
| Others |
Pricing and Supply Chain Analysis
Bavaria's medical-grade silicone resin production cluster anchors polymer supply for heated circuit manufacturers, with capacity utilization rates directly transmitting into downstream pricing power for converters serving neonatal and long-term acute care segments. German compounders leverage this geographic concentration to enforce index-linked contracts that pass through phthalate substitution costs under REACH Annex XVII compliance timelines.
Pricing Analysis
Cost-plus contracts with medical-grade silicone indexation dominate procurement between German polymer compounders and circuit converters, creating pricing stratification across premium, standard, and economy tiers based on biocompatibility certification grade and heated-wire integration complexity. Price differentiation hinges on ISO 10993 cytotoxicity validation status and captive compounding capability, with margins tightening in standard PVC lines due to citrate-based plasticizer migration testing burdens. Hospital GPOs in the United States exhibit highest price sensitivity through committed volume tendering, while neonatal intensive care units demonstrate lowest sensitivity given performance-critical specifications.
Supply Chain Analysis
Export controls on medical-grade silicone precursor technologies limit flow from German and Japanese specialty chemical manufacturers to converters in China and Southeast Asia, compressing supply options for platinum-cured formulations. Raw material dependencies center on silicone resin, polyurethane thermoplastic elastomers, and DEHP-free plasticizer compounds, with single-source vulnerability concentrated in Bavarian resin production. Distribution runs through hospital supply chain intermediaries and GPO contract managers in North America, direct-to-facility logistics in Germany, and provincial distributor networks in China's Sichuan and Guangdong hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ventilator breathing circuit demand sits in early-cycle expansion as sensor-embedded architectures and real-time airway conditioning feedback protocols penetrate long-term acute care and home care channels ahead of reimbursement pathway maturation.
For Market Incumbents: Pre-empt polyurethane substitution momentum by accelerating captive compounding capacity in medical-grade silicone to defend margin position against emerging entrants exploiting phthalate regulatory deadlines. Secure centralized procurement relationships with IDN-affiliated tertiary centers through multi-year enterprise agreements bundling disposable and heated configurations. Invest in ISO 5367 testing infrastructure to compress modular circuit design time-to-market against sensor-embedded platform specialists. For New Entrants and Emerging Players: Home care channels in France and Germany represent the most penetrable entry point, where portable ventilator configurations demand lightweight polyurethane circuits with simplified caregiver interfaces. Target neonatal intensive care units in Japan's Kansai region with low compression volume specifications that incumbent PVC converters cannot address without material requalification. Pursue reimbursement strategy partnerships with long-term acute care discharge coordinators to bypass hospital supply contract lock-in. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified healthcare conglomerates seeking to divest non-core respiratory device components ahead of EU MDR compliance cost concentration. Five-to-ten-year viability favors polymer-integrated specialists with backward control over silicone compounding and established GPO contract anchoring. Monitor NMPA import substitution acceleration in China's Yangtze River Delta as the signal for domestic converter consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Biocompatibility validation accelerates market access for heated circuit platforms in United States tertiary ICUs. |
| CE Marking under EU MDR Class IIa | Sterility assurance documentation opens German and French hospital procurement channels to modular designs. |
| Hospital System Partnership | IDN-affiliated centers standardize circuit configurations across facilities, reducing clinical training overhead. |
| Software Companion Development | Predictive maintenance alerts and automated humidity adjustment digitize workflow in long-term acute care. |
| Reimbursement Strategy | European home care pathways support discharge economics for ventilator-dependent patients with extended weaning timelines. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with respiratory therapy directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and customs records for medical-grade polymer trade flows. Bottom-up triangulation across circuit replacement rates by ICU bed capacity and top-down reconciliation against ventilator installed base estimates anchored volume and value outputs.
Forecast inputs incorporated product type segmentation across disposable, heated, reusable, and non-heated configurations; material grade tiering for silicone, PVC, and polyurethane; and regional regulatory cluster differentiation across FDA, EU MDR, NMPA, and PMDA jurisdictions. CAGRs derived from elasticity modeling of replacement frequency against infection control protocol tightening and critical care infrastructure expansion throughout the projection horizon. Industry-specific inputs included phthalate substitution timeline assumptions and sensor-embedded architecture adoption curves in long-term acute care.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, polymer commodity pricing, or reimbursement pathway maturation would shift the trajectory. Forecasts reflect documented assumptions on regulatory deadline adherence and supply chain geographic concentration persistence. Material shifts in EPA or ECHA phthalate restriction enforcement timelines, or breakthroughs in biodegradable polymer formulations, would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Extremities Market
Medical Devices
Urology Guidewires Market
Medical Devices
North America Electroencephalography Devices Market
Medical Devices
Single-Use Assemblies Market
Medical Devices
Additional Defibrillator Accessories (AED) Market
Medical Devices
Italy Ophthalmic Devices Market
Medical Devices
IVF Time-Lapse Imaging Devices Market
Medical Devices
Medical Manifolds Market
Medical Devices
Saudi Arabia Ophthalmic Devices Market
Medical Devices
Global Artificial Organs and Bionics Market
Medical Devices
China Artificial Organs and Bionic Implants Market
Medical Devices
Global Dermatoscope Market
Medical Devices
Global Orthopedic Surgical Robots Market
Medical Devices
Asia-Pacific Smart Medical Devices Market
Medical Devices
Vascular Closure Device (VCD) Market
Medical Devices
Ultrasonic Medical Nebulizer Market