
 Microcirculation Microscope Market | 2026-2036
Microcirculation Microscope Market Size, Share, and Industry Trends Forecast 2026-2036
Microcirculation Microscope Market Analytics
Direct sales channels for high-end microcirculation systems is narrowing as manufacturers consolidate relationships with specialized medical distributors. Carl Zeiss leverages its established ophthalmology networks to cross-sell capillary imaging platforms into dermatology practices. Thermo Fisher Scientific anchors its position through integrated life science workflows that bundle microscopy with reagent consumables. Olympus Corporation competes by emphasizing open-architecture software that integrates with existing hospital PACS infrastructure.
A microcirculation microscope optically visualizes blood flow through capillary networks using magnification ranges typically spanning 40x to 1000x, often employing epi-illumination or transillumination techniques with dedicated CCD or CMOS sensors for real-time capture. Its primary purpose lies in quantifying tissue perfusion, angiogenesis patterns, and microvascular dysfunction for clinical diagnostics and preclinical research. Fluorescence microscopy dominates current installed bases due to mature dye-based contrast protocols, while near-infrared microscopy is gaining fastest among segments as clinicians seek label-free hemoglobin oxygenation mapping. Portable systems concentrate margin pools in ambulatory and point-of-care settings where space constraints and workflow flexibility command pricing premiums over benchtop configurations.
The FDA's 510(k) pathway for optical diagnostic devices shapes product development timelines and predicate selection strategies for US-bound manufacturers, while ISO 13485 quality management certification operates as a baseline market access requirement across jurisdictions. The EU Medical Device Regulation imposes stricter clinical evidence thresholds for Class IIa optical instruments, lengthening conformity assessment durations for fluorescence and multi-photon platforms. Stakeholders must monitor evolving reimbursement codes for microvascular diagnostics in major healthcare systems, as coding recognition determines hospital capital allocation priorities and replacement cycle timing.
Market Dynamics
Near-infrared microscopy is migrating from preclinical research into clinical diagnostics, compressing development cycles as manufacturers race to validate label-free hemoglobin oxygenation mapping against established fluorescence protocols. This technological pivot is reshaping R&D allocation across the installed base.
Growth Catalysts
- EU Medical Device Regulation (MDR):Stricter clinical evidence thresholds for Class IIa optical instruments are accelerating consolidation among manufacturers capable of funding extended conformity assessments.
- Chronic wound assessment protocols:Dermatology clinics in Germany are standardizing non-invasive capillary imaging for diabetic ulcer monitoring, creating dedicated procurement streams for portable systems.
- METI-backed precision medical initiatives:Japan's domestic production subsidies are expanding manufacturing capacity for advanced microscopy platforms targeting point-of-care deployment.
Market Restraints
- CMOS sensor supply concentration:Specialty image sensor fabrication clusters in Taiwan and South Korea create single-source vulnerability for high-sensitivity detection modules.
- FDA 510(k) predicate drift:Tightening optical diagnostic guidance is lengthening US market entry timelines as manufacturers struggle to identify acceptable predicate devices.
- Fluorescence dye cost volatility:Indocyanine green and fluorescein sodium pricing fluctuations squeeze margin pools in installed-base service contracts.
Strategic Opportunities
- Reimbursement code expansion:Emerging microvascular diagnostic categories in Japan's universal health coverage system would unlock hospital capital allocation for replacement cycles.
- Ambulatory surgery center penetration:Underdeveloped point-of-care imaging infrastructure in US outpatient settings offers first-mover positioning for portable platform vendors.
- Open-architecture PACS integration:Software interoperability with existing hospital infrastructure is creating differentiation avenues against closed-system incumbents.
Industry Challenges
- ISO 13485 quality management certification:Multi-jurisdictional audit complexity extends time-to-market for mid-cap manufacturers lacking dedicated regulatory affairs functions.
- Laboratory information system integration:Legacy hospital IT infrastructure requires costly middleware development for real-time microcirculation data streaming.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microcirculation Microscope Market |
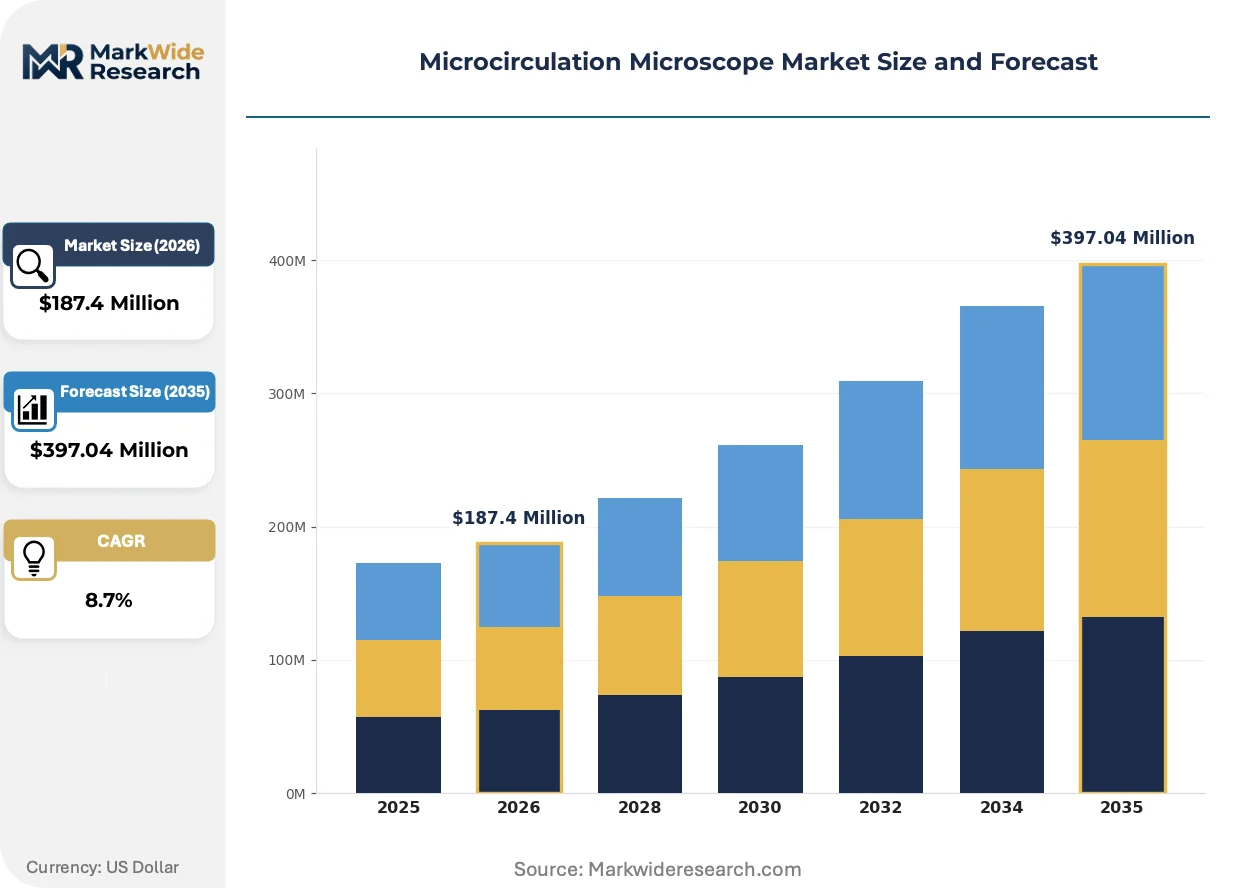
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In Vivo Microscopes, In Vitro Microscopes, Portable Systems, Imaging Solutions Technology: Fluorescence Microscopy, Near-Infrared Microscopy, Digital Imaging, Multi-Photon Microscopy End User: Research Institutions, Hospitals, Diagnostic Laboratories, Pharmaceutical Companies Application: Microcirculation Analysis, Cancer Research, Hemodynamics Study, Tissue Perfusion Assessment |
| Companies Covered | JEOL, Carl Zeiss, Thermo Fisher Scientific, Danaher Corporation, Brunel Microscopes, Microvision Medical, Biobase Biodustry, Olympus Corporation, Nikon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microcirculation Microscope Market Evolving Landscape
Label-free imaging modalities are displacing contrast-dependent workflows across both research and clinical settings, compressing per-procedure costs while demanding new algorithmic capabilities for signal interpretation.
Speckle contrast imaging is migrating from neuroscience applications into dermatology and plastic surgery suites, where reconstructive specialists adopt it for post-operative flap monitoring. Academic medical centers in the US and Germany are validating its equivalence to laser Doppler methods. The technology is migrating from experimental toward reimbursable status, forcing fluorescence platform vendors to defend installed bases through software upgrades rather than hardware replacement.
The EU Medical Device Regulation's 2021 recast imposes annual post-market surveillance reporting for Class IIa optical instruments, elevating clinical affairs headcount requirements for CE-marked manufacturers. Notified bodies in Germany and the Netherlands are extending review timelines for multi-photon platforms lacking sufficient predicate equivalence documentation. Fluorescence microscopy vendors with mature quality systems are absorbing these costs more readily than emerging competitors, widening the compliance gap between established and challenger firms.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, treating preventive maintenance and software updates as separately negotiable line items. German university hospitals pioneered this shift during 2022-2023 budget restructuring, and the practice is diffusing through Nordic and Benelux health systems. Olympus Corporation and Carl Zeiss have responded with modular service tiering, while smaller vendors face margin compression on attach rates previously subsidizing hardware pricing.
Microcirculation Microscope Market Segmentation
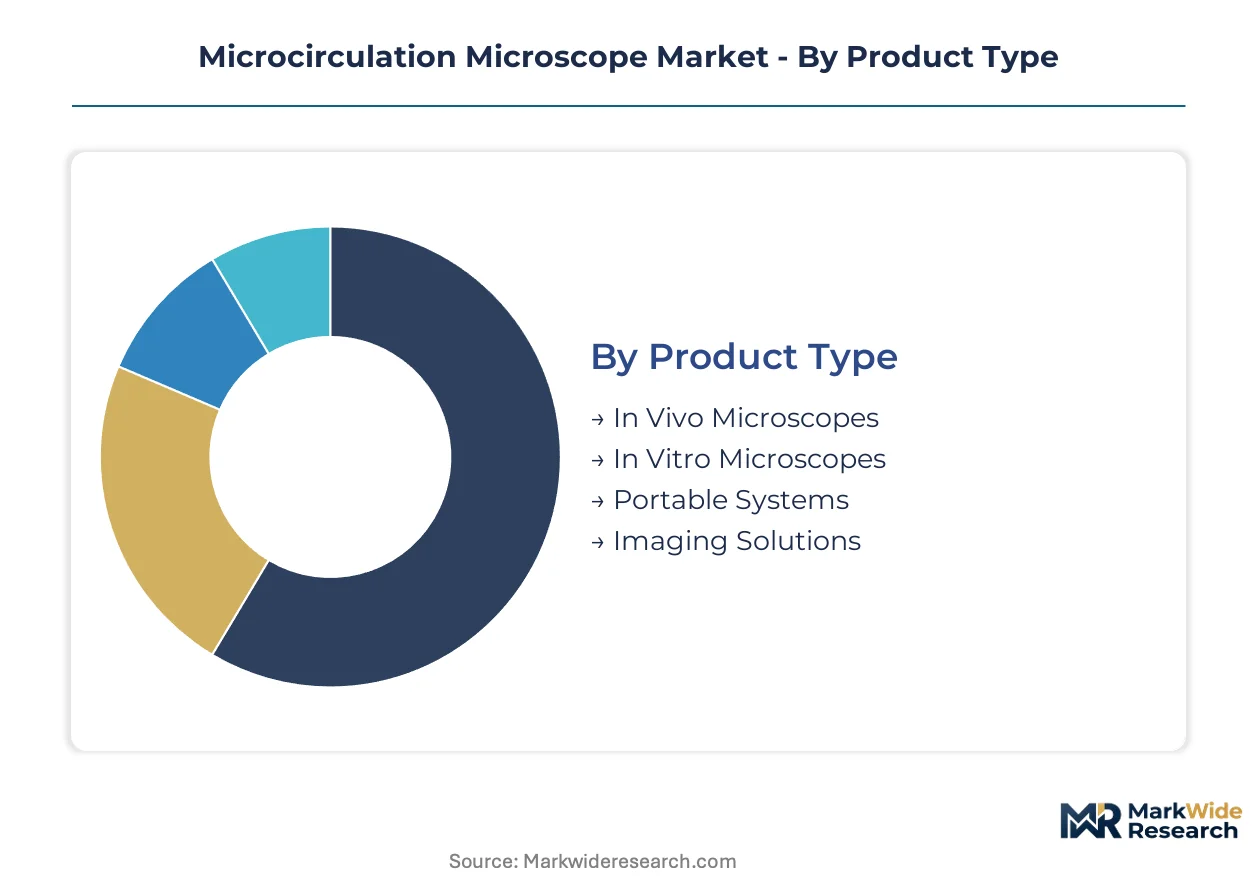
Segmentation in microcirculation microscopy reveals how technology specialization and deployment context determine pricing power and replacement cycles. Product architecture, imaging modality, clinical versus research use, and tissue application each create distinct competitive arenas with different margin structures.
Product Type:
Cost tier separates installed base economics from new purchase dynamics across the four product configurations.
- In Vivo Microscopes:These systems integrate fiber-optic probes with high-speed cameras for real-time blood flow visualization in living subjects. German dermatology clinics are expanding procurement for chronic wound protocols, though capital committees now unbundle service contracts from hardware purchases.
- Portable Systems:Battery-powered units with wireless data transmission enable point-of-care deployment in ambulatory settings. Japanese METI-backed manufacturing subsidies are expanding domestic production capacity for these platforms targeting clinic-based diabetic ulcer monitoring.
- In Vitro Microscopes:Benchtop configurations for isolated tissue specimens and cell culture assays.
- Imaging Solutions:Software and hardware packages for image acquisition, processing, and analysis workflows.
In Vivo Microscopes holds installed capacity. Portable Systems is rotating up the share rankings.
Technology:
Application maturity divides established dye-dependent methods from emerging label-free alternatives with different validation requirements.
- Near-Infrared Microscopy:Label-free hemoglobin oxygenation mapping eliminates contrast agent costs and regulatory complications. The technology is compressing development cycles as manufacturers race clinical validation against fluorescence benchmarks in US academic medical centers.
- Fluorescence Microscopy:Mature dye-based contrast protocols dominate current installed bases with established reimbursement pathways. Indocyanine green and fluorescein sodium pricing volatility squeezes margin pools in service contracts across hospital systems.
- Digital Imaging:CMOS and CCD sensor-based capture with computational enhancement algorithms.
- Multi-Photon Microscopy:Deep tissue penetration using pulsed infrared lasers for reduced phototoxicity.
Fluorescence Microscopy holds installed capacity. Near-Infrared Microscopy is climbing the fastest among the four technology platforms.
End User:
Customer type determines procurement authority, budget source, and replacement cycle timing across institutional categories.
- Hospitals:Capital equipment committees control purchasing with separate line-item negotiation for preventive maintenance and software updates. German university hospitals pioneered this unbundling during budget restructuring, with Nordic and Benelux systems now adopting similar practices.
- Research Institutions:Grant-funded acquisitions prioritize open-architecture software for PACS integration and algorithmic flexibility. US academic medical centers are validating speckle contrast imaging equivalence to laser Doppler methods for post-operative flap monitoring studies.
- Diagnostic Laboratories:High-throughput processing facilities with standardized protocols and regulatory compliance requirements.
- Pharmaceutical Companies:Preclinical drug development and toxicology screening operations with dedicated imaging infrastructure.
Hospitals hold installed capacity. Research Institutions is rotating up the share rankings.
Application:
Volume concentration in chronic disease management creates procurement stability compared to exploratory research uses.
- Microcirculation Analysis:Direct capillary network visualization for perfusion quantification and angiogenesis pattern assessment. Standardization of non-invasive imaging for diabetic ulcer monitoring in German dermatology clinics is creating dedicated procurement streams with predictable replacement timing.
- Tissue Perfusion Assessment:Post-surgical flap monitoring and reconstructive surgery outcome evaluation. Speckle contrast imaging is migrating from neuroscience into plastic surgery suites, forcing fluorescence vendors to defend positions through software upgrades rather than hardware replacement.
- Cancer Research:Tumor angiogenesis studies and anti-vascular therapeutic efficacy evaluation.
- Hemodynamics Study:Blood flow dynamics research in cardiovascular and microvascular disease models.
Microcirculation Analysis holds installed capacity. Tissue Perfusion Assessment is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's central role in precision medical device distribution across Central Europe, while Japan's precision medical device corridor leverages the Port of Yokohama for component import and finished goods export.
United States
Ambulatory surgery centers in Texas and Florida are expanding point-of-care imaging infrastructure for post-operative flap monitoring. The FDA's updated Class II medical device guidance tightens predicate selection requirements for optical diagnostic equipment seeking 510(k) clearance. Academic medical centers in Boston and Baltimore validate speckle contrast imaging equivalence to laser Doppler methods for reconstructive surgery protocols.
Germany
Dermatology clinics in Munich and Hamburg standardize non-invasive capillary imaging for diabetic ulcer assessment, creating dedicated procurement streams for portable systems. The EU Medical Device Regulation imposes annual post-market surveillance reporting for Class IIa optical instruments, extending notified body review timelines. University hospitals in North Rhine-Westphalia pioneered unbundled service contract negotiations during 2022-2023 budget restructuring.
Japan
Domestic production of advanced microscopy platforms concentrates in Nagoya and Osaka under METI-backed precision medical initiatives. The PMDA oversees quality management certification for optical diagnostic devices entering the universal health coverage system. Manufacturing subsidies expand capacity for clinic-based diabetic ulcer monitoring systems targeting point-of-care deployment.
China
Research institutions in Shanghai and Beijing prioritize open-architecture software for PACS integration in microcirculation analysis workflows. The NMPA regulates Class II medical device registration for fluorescence and near-infrared platforms. Yangtze River Delta fabrication clusters supply CMOS sensors for high-sensitivity detection modules, though specialty sensor production remains concentrated in Taiwan and South Korea.
United Kingdom
London and Cambridge academic medical centers drive adoption of label-free hemoglobin oxygenation mapping for preclinical research applications. The MHRA operates post-Brexit medical device regulations aligned with EU MDR clinical evidence thresholds. NHS procurement committees treat preventive maintenance and software updates as separately negotiable line items, diffusing German unbundling practices.
Microcirculation Microscope Market Competitive Landscape
On the supply side, the industry is consolidating around established optical instrumentation conglomerates with diversified life science portfolios and specialized microscopy pure-plays with deep domain expertise. Three archetypes dominate: diversified conglomerates leveraging cross-selling networks, precision optics specialists with vertically integrated manufacturing, and emerging platform vendors emphasizing software interoperability. Strategic moves concentrate on modular service tiering to defend attach rates and open-architecture PACS integration to displace closed-system incumbents.
Among diversified instrumentation conglomerates, Carl Zeiss and Thermo Fisher Scientific exemplify scale-driven positioning through established distribution networks and bundled life science workflows. Olympus Corporation occupies a distinct tier emphasizing software differentiation for hospital infrastructure integration. JEOL represents the precision optics specialist archetype with heritage in electron microscopy extending into optical diagnostic platforms. Nikon Corporation sits within the imaging technology tier, drawing on sensor and optical design competencies. Danaher Corporation anchors the life science tools conglomerate position through portfolio breadth across diagnostic and research applications.
| Leading Market Players |
|---|
| JEOL |
| Carl Zeiss |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Brunel Microscopes |
| Microvision Medical |
| Biobase Biodustry |
| Olympus Corporation |
| Nikon Corporation |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta fabrication clusters anchor CMOS sensor supply for high-sensitivity detection modules, concentrating upstream leverage among Taiwan and South Korean foundries. This geographic concentration feeds into pricing power dynamics across portable and benchtop system tiers, with downstream buyers facing limited alternative sourcing for specialized image sensors.
Pricing Analysis
Volume-discount tiering structures stratify across premium fluorescence platforms, mid-range digital imaging systems, and economy-grade portable units. Certification grade under ISO 13485 and FDA 510(k) clearance status drive price differentiation alongside after-sales service bundling. Cost compression in economy tiers intensifies because hospital procurement committees now unbundle preventive maintenance contracts from capital equipment purchases. Research institutions exhibit lowest price sensitivity due to grant-funded acquisition authority, while ambulatory surgery centers demonstrate highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Specialty image sensor fabrication draws from Taiwan, South Korea, and Japan for high-sensitivity CMOS and CCD modules. Optical component sourcing rests on German precision optics, Japanese lens assemblies, and Chinese aluminum housings. Single-source vulnerability concentrates in Taiwan foundry capacity for medical-grade sensors. Distribution runs through specialized medical device distributors with established ophthalmology and dermatology clinic relationships, consolidating channel control among incumbent optical conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment replacement cycles in hospital systems are accelerating as post-pandemic capital budgets recover, creating cyclical uplift for microscopy platform vendors. This recovery window favors positioning ahead of reimbursement code expansions in major health systems.
For Market Incumbents: Entrench installed base positions through modular service tiering that preserves attach rates against unbundling procurement practices. Accelerate backward integration into CMOS sensor sourcing to mitigate Taiwan foundry concentration risk. Prioritize open-architecture PACS integration investments to defend against software-native challengers threatening hospital infrastructure compatibility.
For New Entrants and Emerging Players: Build out ambulatory surgery center penetration in Texas and Florida where point-of-care imaging infrastructure remains underdeveloped. Target portable system deployments for diabetic ulcer monitoring protocols in German dermatology clinics. Pursue regulatory fast-track strategies through FDA breakthrough device designation for label-free near-infrared platforms.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to divest non-core microscopy assets amid portfolio rationalization. Five-to-ten year viability hinges on software differentiation and recurring revenue attach rates rather than hardware shipment volumes. Monitor PMDA reimbursement code decisions for microvascular diagnostics as inflection indicator for Japanese hospital capital allocation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment timelines determine competitive entry sequencing for fluorescence platforms. |
| Hospital System Partnership | German university hospital procurement committees unbundle service contracts, demanding flexible engagement models. |
| Software Companion Development | Open-architecture PACS integration creates differentiation against closed-system incumbents like Olympus. |
| Reimbursement Strategy | Japan's universal health coverage coding recognition unlocks predictable replacement cycle timing. |
| FDA Submission | 510(k) predicate selection strategies shape US market entry timelines for near-infrared microscopy platforms. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR notified body documentation, and METI subsidy disclosures preceded structured interviews with hospital biomedical engineers, dermatology clinic procurement leads, and optical device regulatory affairs specialists. Primary fieldwork with GPO contracts managers and precision medical device distributors was cross-checked against secondary validation from CMS Medicare reimbursement databases and PMDA approval records. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Assumptions held fixed across the projection horizon include regulatory pathway stability for Class II optical devices and continued METI domestic production subsidies. Segmentation dimensions modeled encompass product architecture, imaging modality, end-user institution type, and tissue application. CAGRs were derived from replacement cycle analysis and penetration rate trajectories. Industry-specific forecast inputs incorporated CMOS sensor supply capacity constraints and fluorescence dye cost volatility patterns.
Stress conditions across reimbursement code adoption timing, EU MDR notified body review duration, and Taiwan foundry capacity allocation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions with acknowledged sensitivity to regulatory enforcement intensity and supply chain disruption scenarios. Cross-checking against hospital capital expenditure surveys and medical device import trade data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Disability Devices Market
Medical Devices
France Anesthesia Devices Market
Medical Devices
Global Pneumatic Tourniquets Market
Medical Devices
Double-Lumen Biliary Catheters Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
Global Spinal Motion Preservation Device Market
Medical Devices
Active Implantable Devices Market
Medical Devices
Hair Removal Devices Market
Medical Devices
Self-Injections Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
Global Glucometer Market
Medical Devices
Needle-Free Drug Delivery Devices Market
Medical Devices
North America Pen Needles Market
Medical Devices
Vascular Closure Device (VCD) Market
Medical Devices
Implantable Pulse Generator Market
Medical Devices
Rhinoplasty Implants Market