
 Leadless Pacemakers Market | 2026-2036
Leadless Pacemakers Market Size, Share, and Industry Trends Forecast 2026-2036
Leadless Pacemakers Market Analytics
Implant procedure revenue is fragmenting between conventional transvenous workflows and single-session leadless deployments. Medtronic PLC leverages its Micra platform to dominate catheter-based delivery training across United States teaching hospitals. Abbott Laboratories anchors its competitiveness through structural heart portfolio cross-selling into electrophysiology suites. Boston Scientific Corporation sustains R&D intensity in miniaturized power management for next-generation leadless architectures.
Leadless pacemakers are self-contained cardiac rhythm devices implanted directly into the right ventricle via femoral venous access, eliminating transvenous leads and subcutaneous generator pockets through catheter-based delivery systems measuring under 2 cubic centimeters. Their primary purpose is to reduce lead-related complications including fracture, infection, and extraction morbidity in patients requiring permanent pacing. Single-chamber devices occupy the dominant commercial position due to established reimbursement pathways and simplified implant technique, while dual-chamber systems represent the fastest-growing segment as atrioventricular synchrony algorithms mature. Wireless telemetry technology leads innovation investment, though battery-powered architectures still capture the majority of installed procedures across cardiology clinics and hospitals.
FDA premarket approval and EU MDR conformity assessment shape product development timelines, with both agencies demanding extended follow-up data for novel leadless indications. The EU AI Act and FDA software-as-medical-device guidance are beginning to influence automated rhythm detection algorithms embedded in leadless systems. Stakeholders must monitor evolving reimbursement decisions from CMS and Germany's G-BA, as these determine whether dual-chamber leadless pacing expands beyond research protocols into standard-of-care coverage.
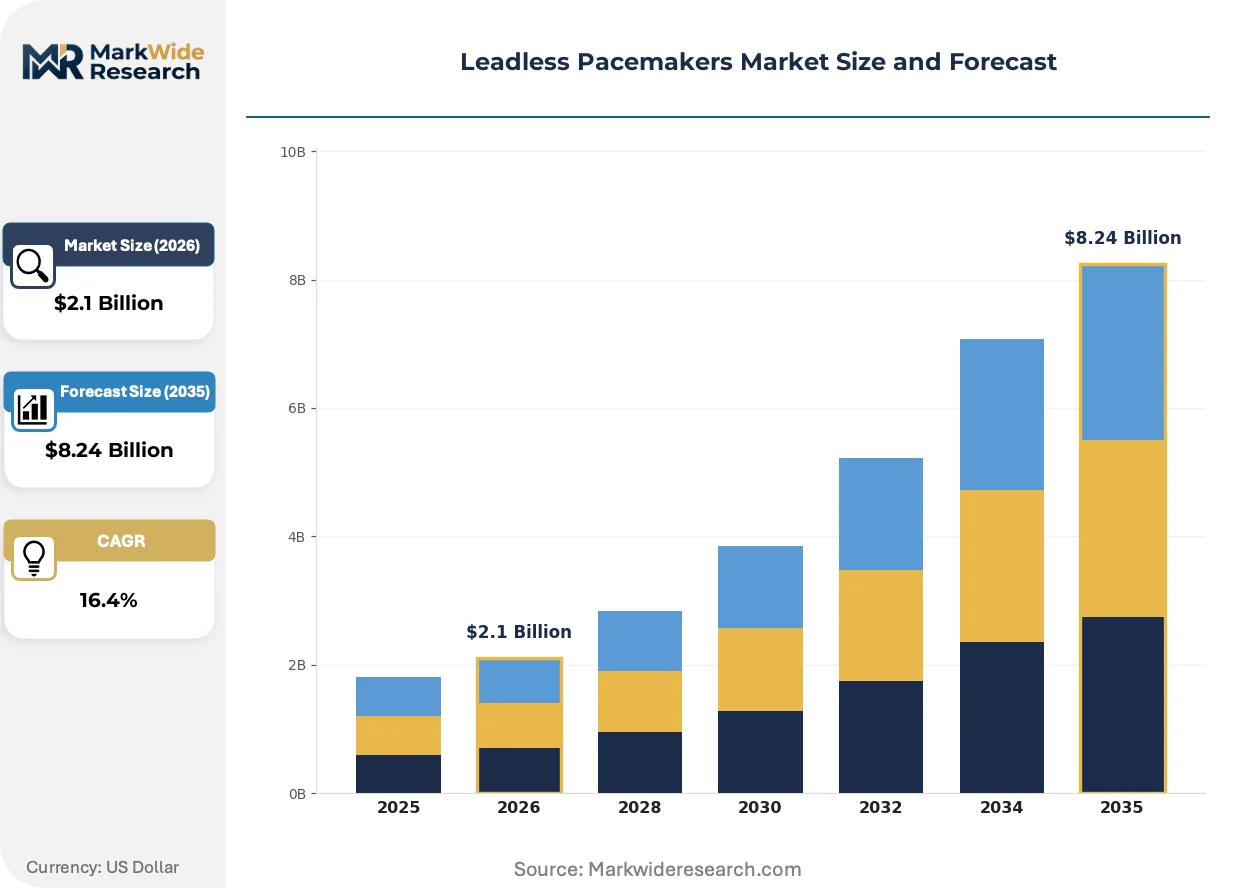
Market Dynamics
The transition from transvenous to catheter-based implant workflows is compressing procedure times and redistributing revenue across device manufacturers, hospital systems, and specialized training programs. This structural shift rewards platforms that integrate delivery system miniaturization with real-time procedural guidance.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways compress premarket timelines for novel leadless indications, enabling faster commercial access for dual-chamber systems in United States tertiary centers.
- Catheter Lab Expansion:Hospital capital investment in Germany and Japan creates dedicated electrophysiology infrastructure that justifies inventory stocking for single-session leadless deployments.
- Lead-Related Complication Avoidance:Elimination of transvenous leads and subcutaneous pockets reduces extraction morbidity, driving preference shifts in patient populations with prior device infections or vascular access limitations.
Market Restraints
- Device Retrieval Complexity:Long-term leadless extraction requires specialized snare techniques and laser sheaths, creating procedural risk profiles that temper adoption in older patient cohorts.
- Single-Chamber Limitations:Absence of atrioventricular synchrony in dominant commercial devices restricts addressable indications to ventricular pacing alone, excluding patients requiring atrial support.
- Reimbursement Uncertainty:CMS and Germany's G-BA have not established distinct payment tiers for dual-chamber leadless systems, constraining provider willingness to absorb premium device costs.
Strategic Opportunities
- Dual-Chamber Algorithm Maturation:Wireless communication between separate atrial and ventricular implants represents unclaimed white space, with first-mover advantage accruing to platforms solving inter-device synchronization.
- Extended Battery Architectures:Miniaturized power management and energy harvesting from cardiac motion could eliminate replacement intervals, transforming total cost-of-ownership calculations for payers.
- EU MDR Conformity Acceleration:Streamlined CE marking pathways under the Medical Device Regulation create faster European commercialization timelines for manufacturers with robust clinical follow-up data.
Industry Challenges
- Electrophysiologist Training Bottlenecks:Catheter-based delivery demands femoral venous access proficiency and fluoroscopic guidance skills that general cardiologists rarely maintain, limiting implant volume scalability.
- Long-Term Surveillance Infrastructure:Wireless telemetry requires patient compliance with remote monitoring protocols and clinic investment in cloud-based rhythm analysis platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leadless Pacemakers Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $8.24 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Chamber, Dual-Chamber, Biventricular, Adaptive End User: Cardiology Clinics, Hospitals, Outpatient Surgical Centers, Home Healthcare Technology: Wireless, Battery-Powered, Energy-Harvesting, Miniaturized Application: Atrial Fibrillation, Bradycardia, Heart Failure, Others |
| Companies Covered | Medtronic PLC, Abbott Laboratories, Boston Scientific Corporation, Biotronik SE & Co. KG, EBR Systems, Inc., MicroPort Scientific Corporation, Lepu Medical Technology Co., Ltd, Osypka AG, Integer Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leadless Pacemakers Market Evolving Landscape
Wireless telemetry architectures and automated rhythm detection algorithms are compressing the gap between implantable devices and external monitoring systems. These converging capabilities are redefining what constitutes a complete pacing solution.
Sensor-integrated leadless systems are virtualizing traditional follow-up workflows. Accelerometers and minute ventilation sensors embedded in right ventricular implants capture hemodynamic data previously requiring external Holter monitors. United States electrophysiology suites are adopting these platforms for heart failure monitoring adjuncts. This sensor fusion is virtualizing the boundary between pacing and diagnostic cardiology, enabling single-device strategies that displace separate implantable loop recorders.
The EU AI Act and FDA software-as-medical-device guidance are reshaping algorithm validation requirements. Automated arrhythmia detection embedded in leadless systems now demands prospective clinical evidence of diagnostic accuracy. Device manufacturers are responding by structuring premarket submissions around machine-learning performance metrics rather than hardware specifications alone. European notified bodies are applying heightened scrutiny to training data representativeness, particularly for atrial fibrillation detection in elderly populations.
Hospital procurement committees are consolidating vendor relationships around integrated cardiovascular portfolios. Electrophysiology suites increasingly source leadless platforms from manufacturers with complementary structural heart or electrophysiology ablation offerings. United States academic medical centers are negotiating enterprise contracts that bundle device procurement with catheter lab staffing and training support. This consolidation favors suppliers with breadth across rhythm management and interventional cardiology.
Leadless Pacemakers Market Segmentation
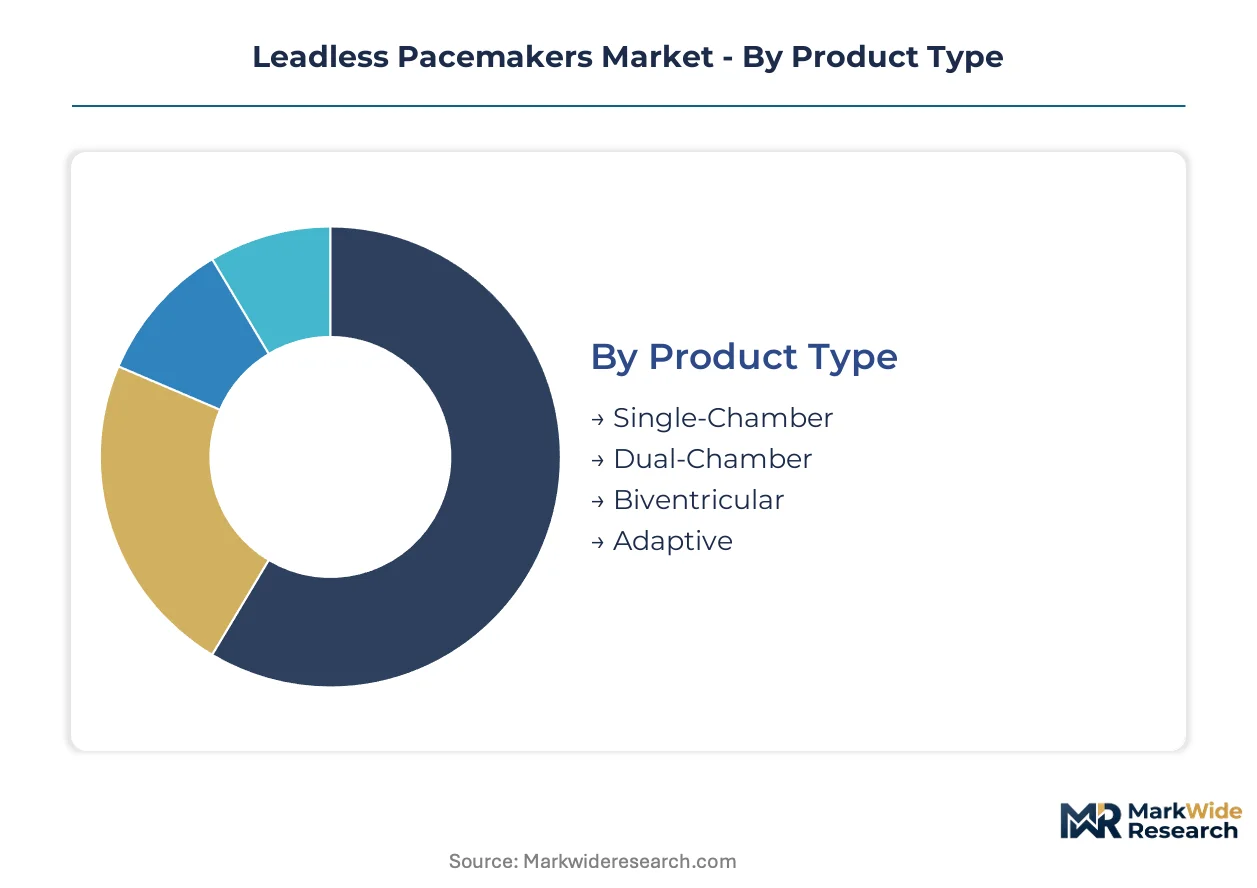
Segmentation in leadless pacemakers reveals how clinical adoption patterns diverge across patient acuity, reimbursement pathways, and implant site capabilities. Understanding these divides helps manufacturers align R&D investment with addressable procedure volumes and margin profiles.
Product Type:
Mature single-chamber systems dominate commercial throughput while dual-chamber architectures represent the emerging frontier for atrioventricular synchrony.
- Single-Chamber:Self-contained right ventricular implants deliver VVI pacing through catheter-based femoral access. Tertiary cardiac centers in the United States and Germany concentrate demand here, driven by established CMS and G-BA reimbursement codes that minimize financial risk for hospitals.
- Dual-Chamber:Separate atrial and ventricular units communicate wirelessly to restore AV synchrony. Japanese electrophysiology suites and select United States academic medical centers are early adopters, constrained by premium device costs and evolving regulatory evidence requirements for inter-device synchronization reliability.
- Biventricular:Specialized configurations for cardiac resynchronization therapy.
- Adaptive:Algorithm-driven rate response systems adjusting to patient activity.
Single-Chamber handles the majority of throughput; Dual-Chamber is the fastest mover on share.
End User:
Implant site economics vary sharply between capital-intensive hospital catheter labs and ambulatory settings seeking lower fixed-cost alternatives.
- Hospitals:Comprehensive electrophysiology suites with fluoroscopy, anesthesia support, and 24-hour recovery monitoring. United States health systems and German university hospitals anchor volume, justified by high-throughput tertiary referral patterns and dedicated device inventory amortization.
- Cardiology Clinics:Outpatient facilities with procedural capabilities for low-complexity implants. Concentrated in United States metropolitan markets with favorable ambulatory surgical center reimbursement, these sites favor single-session workflows that minimize overhead.
- Outpatient Surgical Centers:Standalone facilities optimized for same-day discharge protocols.
- Home Healthcare:Remote monitoring and follow-up services for implanted patients.
Hospitals capture the dominant share of implant volume; Cardiology Clinics are expanding most quickly where ambulatory reimbursement permits.
Technology:
Power architecture choices determine replacement intervals, patient compliance burdens, and long-term total cost of ownership calculations.
- Battery-Powered:Proven lithium chemistry systems with finite 10-12 year lifespans. Currently installed across the majority of active procedures in cardiology clinics and hospitals, constrained by retrieval complexity when replacement becomes necessary.
- Wireless:Telemetry-enabled remote monitoring and communication protocols. United States electrophysiology suites prioritize these platforms for cloud-based rhythm surveillance, though patient adherence to transmission schedules varies.
- Energy-Harvesting:Experimental systems capturing cardiac motion or thermal gradients to extend functional life indefinitely.
- Miniaturized:Sub-2 cubic centimeter form factors enabling less invasive delivery.
Battery-Powered handles the majority of throughput; Energy-Harvesting holds the steepest expansion trajectory contingent on clinical validation.
Application:
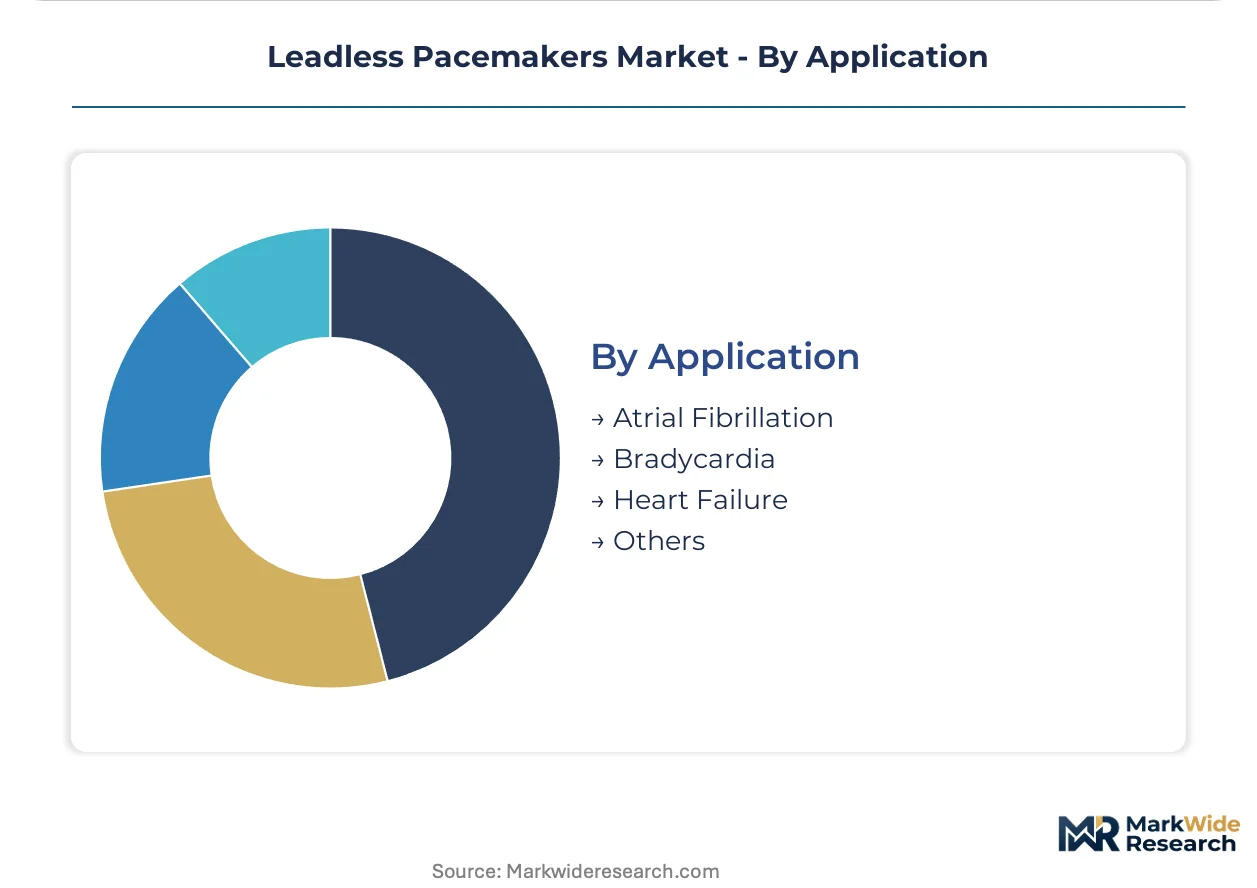
Indication severity shapes device selection, with bradycardia representing the established entry point and heart failure applications demanding more complex therapeutic algorithms.
- Bradycardia:Symptomatic slow heart rate requiring ventricular rate support. United States Medicare beneficiaries and German statutory insurance populations drive volume, with single-chamber devices sufficient for most AV-conduction-block presentations.
- Atrial Fibrillation:Rhythm control and ventricular rate management in AF patients. Japanese cardiac centers concentrate demand here, particularly where anticoagulation status complicates transvenous lead placement.
- Heart Failure:Advanced pacing strategies for hemodynamic optimization.
- Others:Niche indications including post-operative temporary pacing and congenital heart disease.
Bradycardia handles the majority of throughput; Heart Failure is gaining share fastest as sensor-integrated diagnostics expand device utility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States tertiary centers absorb premium device costs with minimal volume sensitivity, while Japanese and German procurement committees enforce rigorous cost-effectiveness thresholds that compress margins for dual-chamber systems.
United States
CMS reimbursement pathways for single-chamber leadless devices stabilize hospital procurement budgets across Medicare Advantage populations. FDA breakthrough device designation compresses premarket review timelines for novel dual-chamber indications. Tertiary cardiac centers in Cleveland, Houston, and Minneapolis anchor implant volume through dedicated electrophysiology fellowship programs.
Germany
G-BA health technology assessment protocols demand incremental cost-effectiveness ratios below EUR 50,000 per quality-adjusted life year for dual-chamber leadless expansion. EU MDR conformity assessment under Notified Body TÜV SÜD accelerates CE marking timelines for manufacturers with robust post-market surveillance data. University hospitals in Berlin, Munich, and Heidelberg concentrate catheter lab investment for single-session leadless workflows.
Japan
PMDA pharmaceutical and medical device agency review cycles for leadless pacemakers average 14 months, slower than FDA pathways but faster than historical Japanese benchmarks. METI industrial policy supports domestic manufacturing partnerships for miniaturized battery architectures. Cardiac centers in Tokyo, Osaka, and Nagoya prioritize leadless implants for anticoagulated atrial fibrillation patients with transvenous access limitations.
United Kingdom
NICE technology appraisal guidance for leadless pacing remains provisional pending dual-chamber randomized trial data, constraining NHS England commissioning decisions. MHRA post-Brexit regulatory autonomy permits streamlined recognition of FDA-approved devices through reliance procedures. Specialist commissioning hubs in London, Manchester, and Birmingham ration device allocation to patients with prior lead extraction complications.
China
NMPA innovative medical device designation reduces registration timelines to 12-18 months for leadless systems with domestic clinical trial data. MIIT industrial policy channels subsidies toward catheter lab infrastructure in tier-2 cities. Provincial medical procurement consortia in Guangdong, Jiangsu, and Beijing negotiate volume-based pricing that undercuts imported device premiums by 30-40 percent.
Leadless Pacemakers Market Competitive Landscape
Capability concentration sits with diversified cardiovascular conglomerates; scale advantage sits with rhythm management specialists. The vendor base organizes into three tiers: integrated device manufacturers with structural heart cross-selling leverage, pure-play electrophysiology platforms, and emerging regional challengers. Strategic moves center on catheter lab training program captivity and dual-chamber algorithm patent positioning.
Among diversified cardiovascular conglomerates, Medtronic PLC and Abbott Laboratories exemplify integrated platform strategies that bundle leadless procurement with structural heart and ablation portfolios. Boston Scientific Corporation occupies a specialist position within electrophysiology suite vendor relationships. Biotronik SE & Co. KG anchors European market presence through German manufacturing and CE marking pathway expertise. These three entities represent distinct competitive archetypes: training infrastructure captivity, portfolio bundling leverage, and regional regulatory proximity.
| Leading Market Players |
|---|
| Medtronic PLC |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Biotronik SE & Co. KG |
| EBR Systems, Inc. |
| MicroPort Scientific Corporation |
| Lepu Medical Technology Co., Ltd |
| Osypka AG |
| Integer Holdings Corporation |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Swiss micromachining suppliers for catheter delivery systems determines both pricing tier spreads and supply chain shape, compressing margins for dual-chamber architectures while amplifying premium capture for manufacturers with captive component production.
Pricing Analysis
Device retrieval service contracts drive lifetime value calculations across United States hospital systems. Three-tier pricing structure across premium dual-chamber, standard single-chamber, and economy retrieval-assurance levels stratifies procurement committees. Cost compression in the economy tier is intensifying because German G-BA reimbursement delays force providers to absorb upfront device premiums. Academic medical centers exhibit lowest price sensitivity; ambulatory surgical centers in United States metropolitan markets demonstrate highest sensitivity due to fixed reimbursement ceilings.
Supply Chain Analysis
Lithium primary cell feedstock draws from Japan, South Korea, and China, with cathode material processing concentrated in Chinese industrial parks. Miniaturized capacitor assemblies and biocompatible titanium housings represent critical component dependencies. Single-source vulnerability sits with Swiss precision catheter manufacturers serving Medtronic and Abbott delivery platforms. Distribution runs through hospital procurement consortia and GPO contracts rather than direct manufacturer-to-site relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Leadless pacemakers constitute a platform-economics inflection where catheter lab training infrastructure and wireless telemetry ecosystems determine competitive moats, with interoperability between atrial and ventricular units reshaping vendor lock-in dynamics.
For Market Incumbents: Harden catheter lab training captivity through exclusive fellowship partnerships at Cleveland Clinic, Houston Methodist, and Heidelberg University Hospital. Deepen backward integration into lithium primary cell manufacturing to offset Korean supplier concentration. Lock in GPO contract extensions before dual-chamber CMS reimbursement clarity emerges.
For New Entrants and Emerging Players: Build out wireless synchronization IP portfolios targeting the inter-device communication white space between separate atrial and ventricular implants. Concentrate clinical trial investment in Japanese anticoagulated AF populations where transvenous access limitations create addressable need. Pursue hospital system risk-sharing agreements that align device pricing with complication avoidance outcomes.
For Investors and Strategic Acquirers: EU MDR dual-chamber CE marking reshapes the acquisition landscape by validating synchronization algorithms for European commercialization. Target electrophysiology software platforms with FDA breakthrough-designated rhythm detection modules. Watch FDA premarket approval timelines for dual-chamber systems as the inflection signal for reimbursement expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pursuit | Accelerated review compresses time-to-revenue for dual-chamber algorithms in United States tertiary centers. |
| CE Marking Pathway Optimization | EU MDR conformity under TÜV SÜD unlocks German hospital procurement committees for premium device tiers. |
| Hospital System Partnership | Enterprise contracts with United States academic medical centers bundle device procurement with catheter lab staffing. |
| Software Companion Development | Cloud-based rhythm surveillance platforms embedded with AI detection satisfy FDA software-as-medical-device guidance. |
| Reimbursement Strategy | CMS and G-BA dual-chamber coding advocacy determines whether AV synchrony expands beyond research protocols. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA premarket approval databases, EU MDR notified body declarations, and hospital GPO contract filings. Electrophysiologists, biomedical engineers, catheter lab directors, and GPO contracts managers provided procedural volume and procurement decision frameworks. SEC 10-K rhythm management segment disclosures and CMS Medicare claims data furnished bottom-up triangulation against top-down market sizing.
Forecast inputs include implant volume trajectories across single-chamber and dual-chamber product types, catheter lab capacity expansion in Germany and Japan, and reimbursement pathway evolution for AV synchrony indications. Segmentation dimensions span product architecture, end-user site economics, power management technology, and bradycardia versus heart failure application severity. CAGRs derive from procedure volume elasticity modeling against device replacement intervals and penetration rate assumptions for anticoagulated patient populations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese NMPA-designated domestic manufacturers or energy-harvesting technology specialists would shift outcomes. Cross-checking against PMDA approval timelines and METI industrial policy disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bone Cement Mixers Market
Medical Devices
Artificial Disc Replacement Market
Medical Devices
Bone Conduction Hearing Devices Market
Medical Devices
IoT Medical Devices Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
Mhealth (Mobile Health) Devices Market
Medical Devices
Bluetooth Hearing Aids Market
Medical Devices
Occlusion Balloon Catheter Market
Medical Devices
Printed Electronics in Healthcare Market
Medical Devices
Interventional Oncology Devices Market
Medical Devices
Smart Mask Market
Medical Devices
Nonablative Laser Resurfacing Devices Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Nerve Ablation Devices Market
Medical Devices
Germany Respiratory Devices Market
Medical Devices
Aerosol Drug Delivery Devices Market