
 Asia-Pacific Medical Device Regulatory Affairs Market | 2026-2036
Asia-Pacific Medical Device Regulatory Affairs Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Medical Device Regulatory Affairs Market Analytics
Multinational manufacturers is collapsing as the dominant buyer archetype, while domestic Asia-Pacific device makers are gaining procurement share. Shenzhen Mindray Bio-Medical Electronics anchors its regulatory strategy through in-house compliance teams across multiple jurisdictions. IQVIA Inc. competes by leveraging outsourced regulatory consulting networks spanning Japan, Australia, and Southeast Asia.
Asia-Pacific medical device regulatory affairs encompasses the specialized professional services and internal functions that ensure medical technologies meet jurisdictional safety, efficacy, and quality standards before commercial distribution, including dossier preparation, clinical evaluation documentation, and post-market surveillance systems. The field requires deep expertise in region-specific technical documentation formats such as Japan's STED (Summary Technical Documentation) and Australia's Essential Principles compliance declarations. Consulting services within the service type segment lead current revenue generation due to recurring demand for regulatory strategy and submission planning. Compliance Management functions are expanding fastest as manufacturers respond to tightened PMDA and TGA inspection protocols.
Japan's PMDA, Australia's TGA, and China's NMPA collectively shape market access timelines through divergent documentation requirements and inspection cadences that force manufacturers to maintain parallel regulatory workstreams. The TGA's alignment with EU MDR technical standards creates pathway efficiencies for companies already holding CE Mark certifications. Stakeholders must monitor how China's NMPA accelerates its international harmonization agenda through GB standard revisions and whether Japan's Sakigake designation system expands beyond pharmaceuticals into device categories.
Market Dynamics
Japan's PMDA QMS ordinance revisions and Australia's TGA framework updates are forcing manufacturers to rebuild compliance infrastructure from the ground up, collapsing legacy single-jurisdiction regulatory models across the Asia-Pacific region.
Growth Catalysts
- China's NMPA international harmonization:GB standard revisions accelerate domestic manufacturers' access to foreign markets, expanding demand for cross-border regulatory dossier preparation.
- Sakigake designation expansion:Japan's fast-track approval pathway is extending from pharmaceuticals into priority device categories, compressing time-to-market for innovative technologies.
- Software as a Medical Device (SaMD):AI-enabled diagnostic tools trigger new submission categories across PMDA, TGA, and NMPA jurisdictions, creating specialized consulting demand.
Market Restraints
- Parallel regulatory workstreams:Divergent STED formats between Japan's PMDA and Australia's Essential Principles declarations force redundant documentation costs.
- Qualified regulatory talent scarcity:Deep expertise in multi-jurisdiction submission strategies concentrates in Tokyo, Sydney, and Shanghai, driving salary inflation.
- Inspection cadence misalignment:Unsynchronized PMDA and TGA audit schedules disrupt manufacturing operations and strain quality management systems.
Strategic Opportunities
- Southeast Asia regulatory greenfield:Vietnam, Indonesia, and Thailand lack mature device approval frameworks, creating first-mover advantage for outsourced compliance services.
- EU MDR alignment leverage:TGA's technical standard convergence with European requirements enables CE Mark holders to penetrate Australian markets with minimal incremental investment.
- Post-market surveillance digitization:Real-world evidence collection platforms address tightened PMDA vigilance reporting mandates.
Industry Challenges
- Legacy quality system retrofitting:PMDA's 2022 QMS ordinance requires manufacturers to revalidate entire manufacturing processes, not just documentation.
- Cross-functional regulatory talent gaps:Professionals combining clinical evaluation expertise with software validation knowledge remain scarce across the region.
- Submission strategy fragmentation:NMPA's evolving international reference country acceptance criteria force repeated dossier restructuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Medical Device Regulatory Affairs Market |
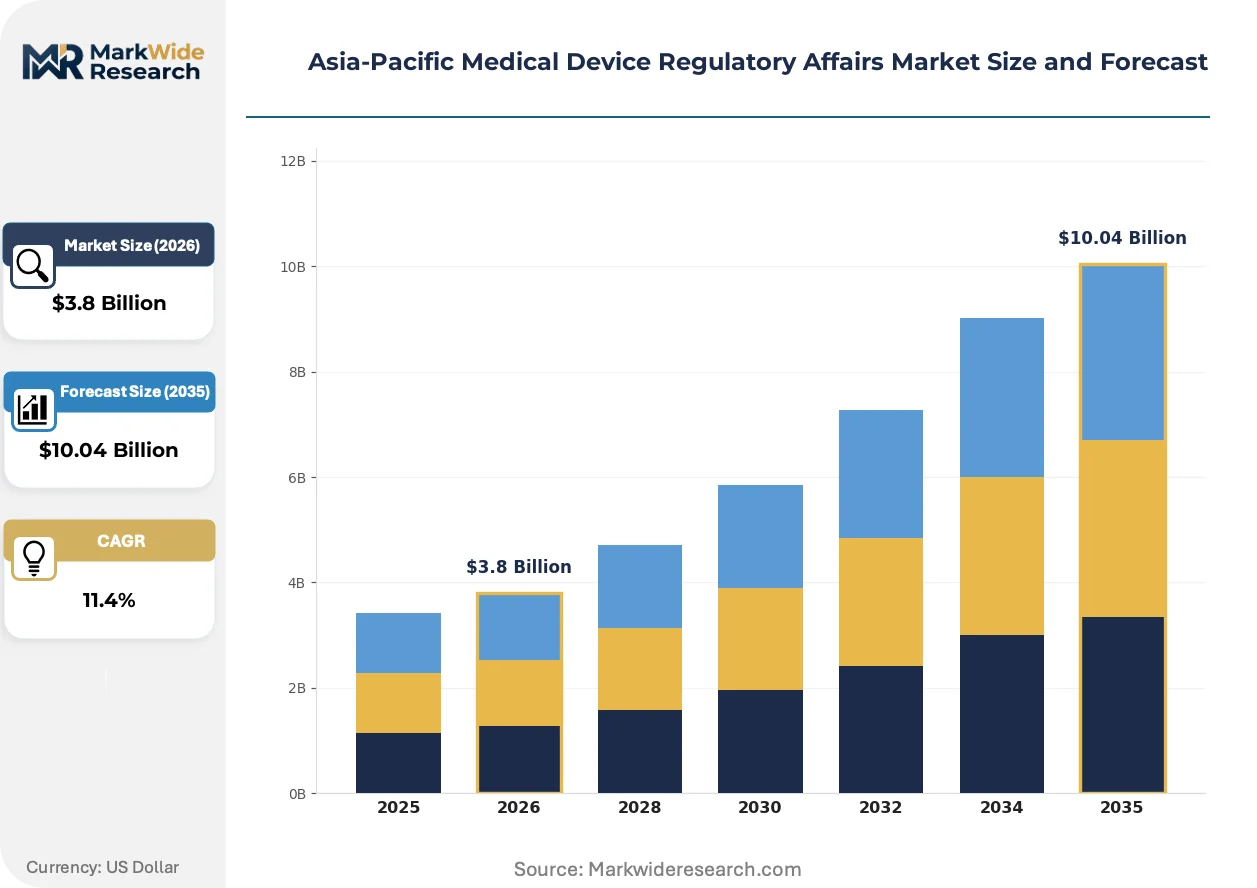
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Compliance Management, Quality Assurance, Training Device Type: In-Vitro Diagnostics, Surgical Instruments, Imaging Equipment, Therapeutic Devices End User: Hospitals, Clinics, Manufacturers, Regulatory Bodies Regulatory Framework: FDA, CE Mark, TGA, PMDA |
| Companies Covered | ICON plc, IQVIA Inc., Laboratory Corporation of America Holdings, Integer Holdings, Medtronic, Nipro Corporation, Shimadzu Corporation, Shenzhen Mindray Bio-Medical Electronics, Terumo Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Medical Device Regulatory Affairs Market Evolving Landscape
Regulatory technology platforms are compressing submission preparation timelines while divergent national frameworks force manufacturers into specialized jurisdictional expertise rather than harmonized global strategies.
Artificial intelligence-powered document generation tools are supplanting manual dossier assembly processes. Mid-sized device manufacturers in South Korea and Taiwan adopt these platforms fastest to offset limited in-house regulatory headcount. The technology is supplanting traditional consulting engagement models by embedding compliance logic directly into product development workflows.
Japan's PMDA Sakigake designation system is expanding eligibility criteria to capture breakthrough medical devices alongside pharmaceuticals. Manufacturers gain priority consultation and accelerated review timelines, though evidence requirements remain stringent. Cardiovascular and neurology device categories dominate current Sakigake approvals as sponsors build Japan-first regulatory strategies.
Domestic Asia-Pacific manufacturers now bypass multinational distributors to secure direct regulatory representation in target markets. Shenzhen and Singapore-based sponsors establish captive compliance teams in Tokyo and Sydney rather than relying on third-party importers. This channel disintermediation concentrates regulatory risk internally while capturing margin previously allocated to distribution partners.
Asia-Pacific Medical Device Regulatory Affairs Market Segmentation
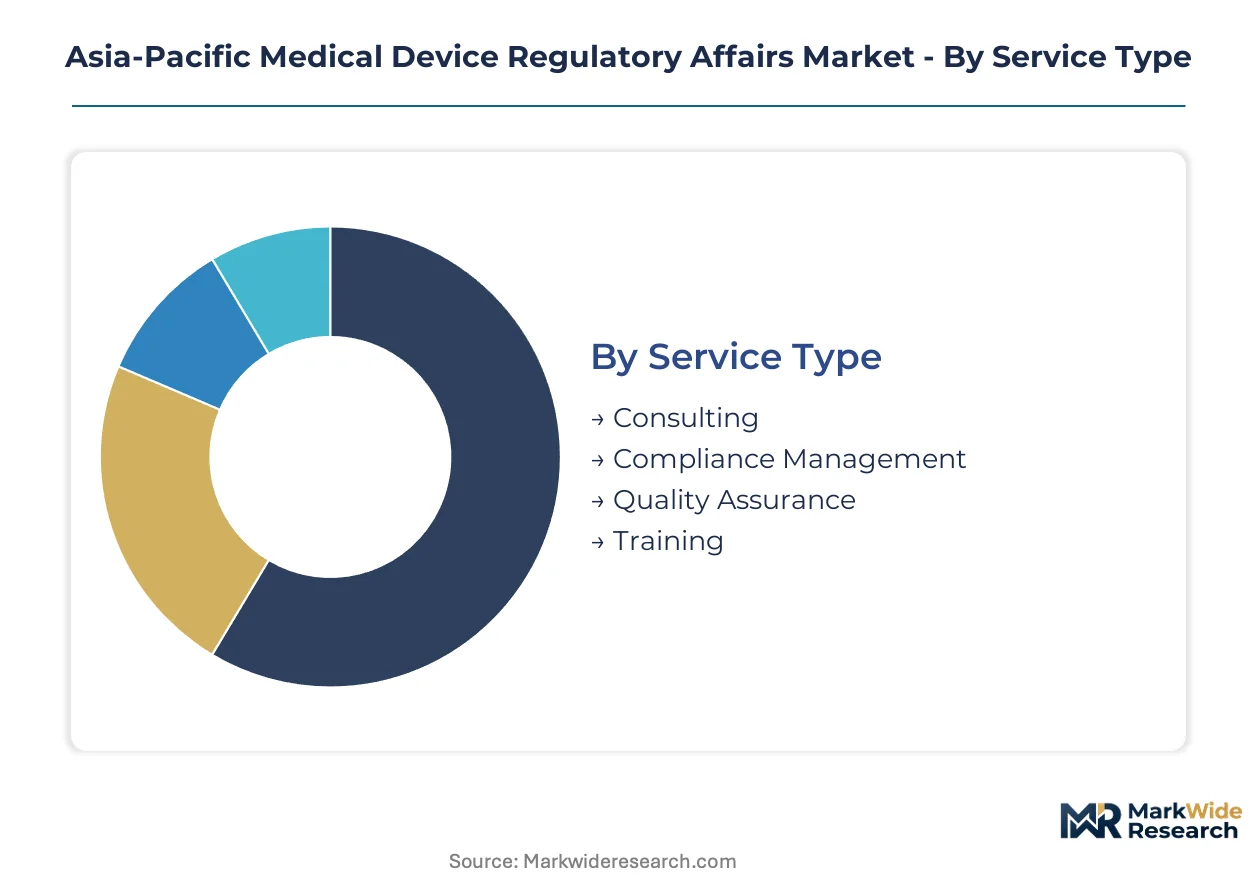
Regulatory affairs procurement across Asia-Pacific fragments across service modalities, device categories, and jurisdictional frameworks. Each segment carries distinct margin profiles and talent requirements that reshape vendor positioning.
Service Type:
Consulting commands premium pricing through specialized expertise in multi-jurisdiction dossier preparation, while compliance management functions scale through recurring audit support contracts.
- Consulting:Strategic advisory spanning submission pathway selection, clinical evaluation planning, and regulator negotiation. Demand concentrates in Tokyo and Shanghai as domestic manufacturers build Japan-first and China-export strategies simultaneously.
- Compliance Management:Ongoing quality system maintenance, inspection readiness, and post-market surveillance execution. Australia's TGA and Japan's PMDA are expanding inspection cadences, forcing manufacturers to retain dedicated compliance infrastructure year-round rather than project-based engagement.
- Quality Assurance:Technical documentation review, risk management file maintenance, and supplier qualification audits.
- Training:Workforce certification in STED preparation, Essential Principles alignment, and QMS ordinance implementation.
Consulting holds installed capacity. Compliance Management is rotating up the share rankings.
Device Type:
Complexity gradients across device categories determine regulatory spend intensity, with software-enabled systems driving specialized consulting demand.
- In-Vitro Diagnostics:Analytical performance validation, reference standard traceability, and clinical agreement studies dominate dossier preparation. China's NMPA is accelerating approval timelines for domestic IVD manufacturers targeting ASEAN markets, expanding cross-border regulatory workload.
- Surgical Instruments:Biocompatibility testing coordination, sterilization validation, and mechanical safety documentation. South Korea's MFDS and Australia's TGA are tightening essential principles compliance for reusable instrument categories.
- Imaging Equipment:Electromagnetic compatibility certification, radiation safety filings, and software lifecycle documentation.
- Therapeutic Devices:Clinical evidence generation, risk-benefit analysis, and post-market clinical follow-up protocols.
In-Vitro Diagnostics anchors current revenue. Therapeutic Devices are climbing the fastest as breakthrough designations expand.
End User:
Procurement authority is shifting from hospital procurement offices toward manufacturer regulatory departments with direct budget control.
- Manufacturers:Internal regulatory affairs functions, captive compliance teams, and outsourced consulting relationships. Shenzhen and Singapore-based sponsors are establishing direct Tokyo and Sydney representation, bypassing distributor intermediaries.
- Hospitals:Institutional review board coordination, investigator-initiated study compliance, and adverse event reporting systems.
- Clinics:Point-of-care device registration support and import license maintenance.
- Regulatory Bodies:Technical standards development, guidance document drafting, and harmonization initiative participation.
Manufacturers dominate contract value. Regulatory Bodies are gaining procurement influence through standards-setting mandates.
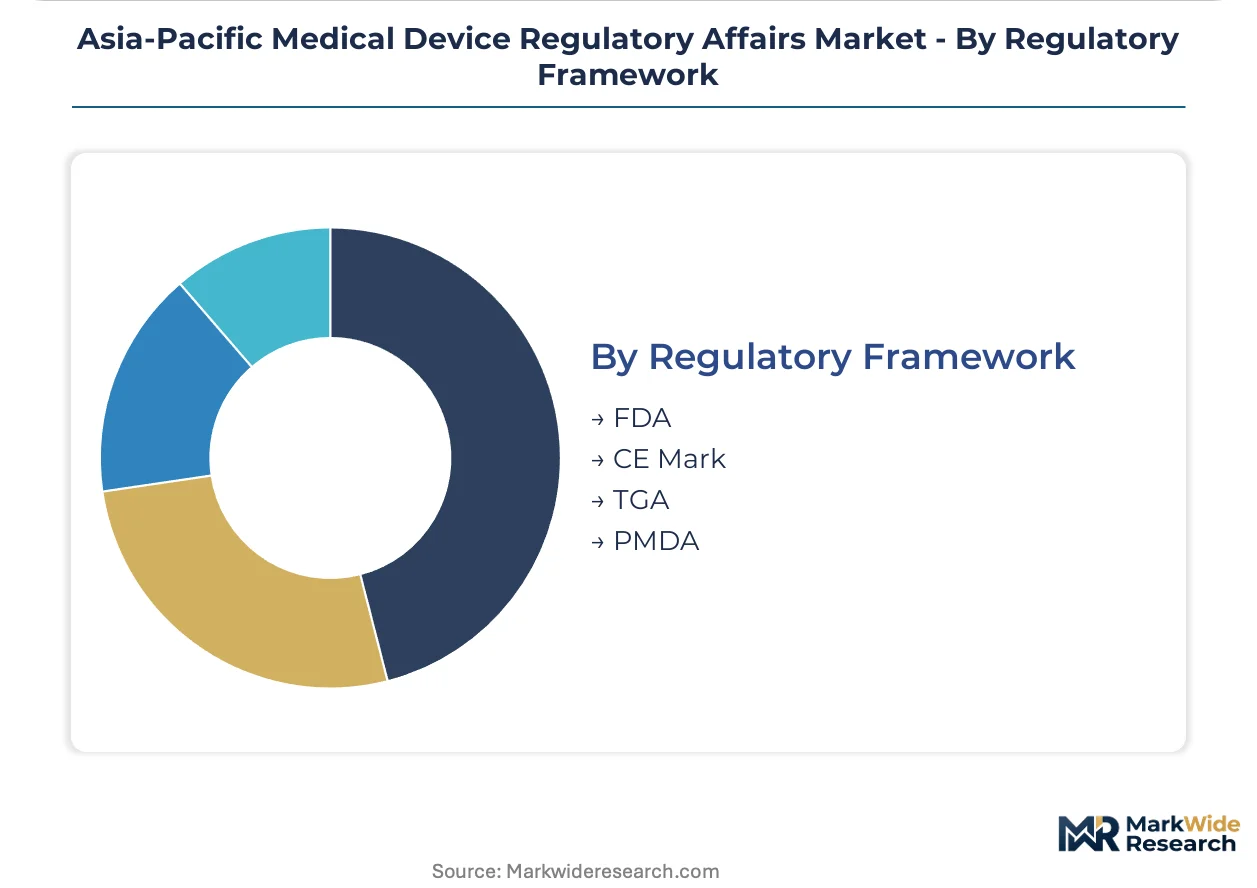
Regulatory Framework:
Jurisdictional divergence forces parallel workstream maintenance, with framework-specific expertise commanding salary premiums.
- PMDA:Japan's STED format, QMS ordinance compliance, and Sakigake fast-track navigation. Domestic manufacturers in China and South Korea are prioritizing PMDA approval as a credibility signal for broader Asia-Pacific expansion.
- TGA:Essential Principles declarations, EU MDR alignment leverage, and post-market vigilance systems. CE Mark holders exploit technical standard convergence to penetrate Australian markets with minimal incremental documentation.
- FDA:510(k) pathway navigation, PMA preparation, and establishment registration maintenance for US market access.
- CE Mark:Technical documentation compilation, notified body selection, and MDR transition compliance.
PMDA holds installed capacity. TGA is rotating up the share rankings through EU alignment efficiencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic Asia-Pacific device manufacturers now command the largest procurement share, displacing multinational distributors as the primary buyers of regulatory services across Japan, China, Australia, South Korea, and Southeast Asian markets.
Japan
PMDA's Sakigake fast-track designation is compressing approval timelines for cardiovascular and neurology devices. Tokyo-based sponsors are building captive compliance teams to navigate STED format requirements and QMS ordinance revisions. Osaka's medical device cluster is generating concentrated demand for regulatory consulting as domestic manufacturers prioritize Japan-first strategies.
China
NMPA's international harmonization agenda through GB standard revisions is accelerating domestic manufacturers' foreign market access strategies. Shenzhen's electronics corridor is spawning dedicated regulatory affairs departments within device makers targeting ASEAN expansion. Shanghai's biotech hub is driving cross-border dossier preparation demand as sponsors seek simultaneous PMDA and TGA approvals.
Australia
TGA's alignment with EU MDR technical standards is enabling CE Mark holders to penetrate Australian markets with minimal incremental documentation. Sydney's regulatory consulting sector is expanding inspection readiness services as PMDA and TGA audit cadences tighten. Melbourne's medical technology precinct is attracting direct regulatory representation from Asia-Pacific sponsors bypassing distributor intermediaries.
South Korea
MFDS is tightening essential principles compliance for reusable surgical instrument categories. Seoul's device manufacturers are prioritizing PMDA approval as a credibility signal for broader regional expansion. Busan's industrial medical cluster is developing specialized SaMD submission capabilities as AI-enabled diagnostic tools trigger new regulatory categories.
Singapore
The city-state's regulatory framework is serving as a launchpad for Southeast Asian market access. Domestic sponsors are establishing Tokyo and Sydney representation through Singapore-based holding structures. The biomedical manufacturing precinct is concentrating software validation expertise as SaMD submissions proliferate across PMDA, TGA, and NMPA jurisdictions.
Asia-Pacific Medical Device Regulatory Affairs Market Competitive Landscape
Player mix skews toward diversified contract research organizations and captive regulatory functions within large device manufacturers, creating a bifurcated structure with limited mid-tier specialist presence. Tier-one CROs leverage pan-Asia-Pacific consulting networks to capture multi-jurisdiction submission planning contracts. Captive compliance teams at major device makers are internalizing quality system maintenance and inspection readiness functions. Competitive moves center on geographic expansion into Southeast Asian greenfield markets and technology licensing for AI-powered document generation platforms.
Among Asia-Pacific-based device manufacturers, Shenzhen Mindray Bio-Medical Electronics exemplifies the captive compliance archetype through direct regulatory representation in Tokyo and Sydney. IQVIA Inc. occupies a position within the outsourced consulting tier, leveraging networks spanning Japan, Australia, and Southeast Asia. ICON plc represents the diversified CRO model competing across submission strategy and clinical evaluation planning. Laboratory Corporation of America Holdings anchors the North American-origin service provider segment competing for Asia-Pacific market access contracts.
| Leading Market Players |
|---|
| ICON plc |
| IQVIA Inc. |
| Laboratory Corporation of America Holdings |
| Integer Holdings |
| Medtronic |
| Nipro Corporation |
| Shimadzu Corporation |
| Shenzhen Mindray Bio-Medical Electronics |
| Terumo Corporation |
| Others |
Value Network & Pricing Analysis
AI-powered document generation platforms are displacing traditional consulting engagement models across the Asia-Pacific medical device regulatory affairs market, simultaneously compressing submission preparation timelines and redistributing pricing power toward technology-enabled vendors in Tokyo, Sydney, and Singapore. This substitution dynamic collapses legacy project-based fee structures while concentrating supply geography around jurisdictions with mature software validation ecosystems.
Pricing Analysis
Current-generation AI-enabled regulatory platforms command premium positioning against prior-generation manual dossier assembly services and next-generation integrated compliance ecosystems still in pilot phases. Consulting services operate on project-based transactional pricing, while compliance management functions increasingly migrate toward recurring subscription models. Price differentiation rests on certification depth—PMDA Sakigake pathway expertise versus standard submission support—and geographic coverage breadth spanning Japan, Australia, and China. Cost compression in mid-tier consulting is intensifying because domestic manufacturers internalize routine documentation functions. Domestic Asia-Pacific device makers exhibit highest price sensitivity as they build first regulatory capabilities, while multinational sponsors with established captive teams demonstrate lowest sensitivity to per-project fees.
Supply Chain Analysis
Regulatory talent inventory concentrates in Tokyo, Sydney, and Shanghai with 8-12 week lead times for specialized PMDA STED expertise, compressing to 4-6 weeks for TGA Essential Principles compliance. Supply draws from Japan's PMDA-experienced consultant pool, Australia's TGA-aligned quality system auditors, and China's NMPA-focused dossier specialists. Raw capability inputs include clinical evaluation expertise, software validation knowledge, and multi-jurisdiction submission strategy experience. Single-source vulnerability runs through Tokyo-based Sakigake pathway specialists as demand outpaces training pipeline output. Distribution runs through direct captive team establishment by major device manufacturers, supplemented by outsourced consulting networks spanning Southeast Asian greenfield markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific medical device regulatory affairs market sits at a platform-economics inflection where AI-powered document generation ecosystems are interoperating with product development workflows, collapsing traditional consulting margins while creating new value capture opportunities for technology-enabled compliance infrastructure.
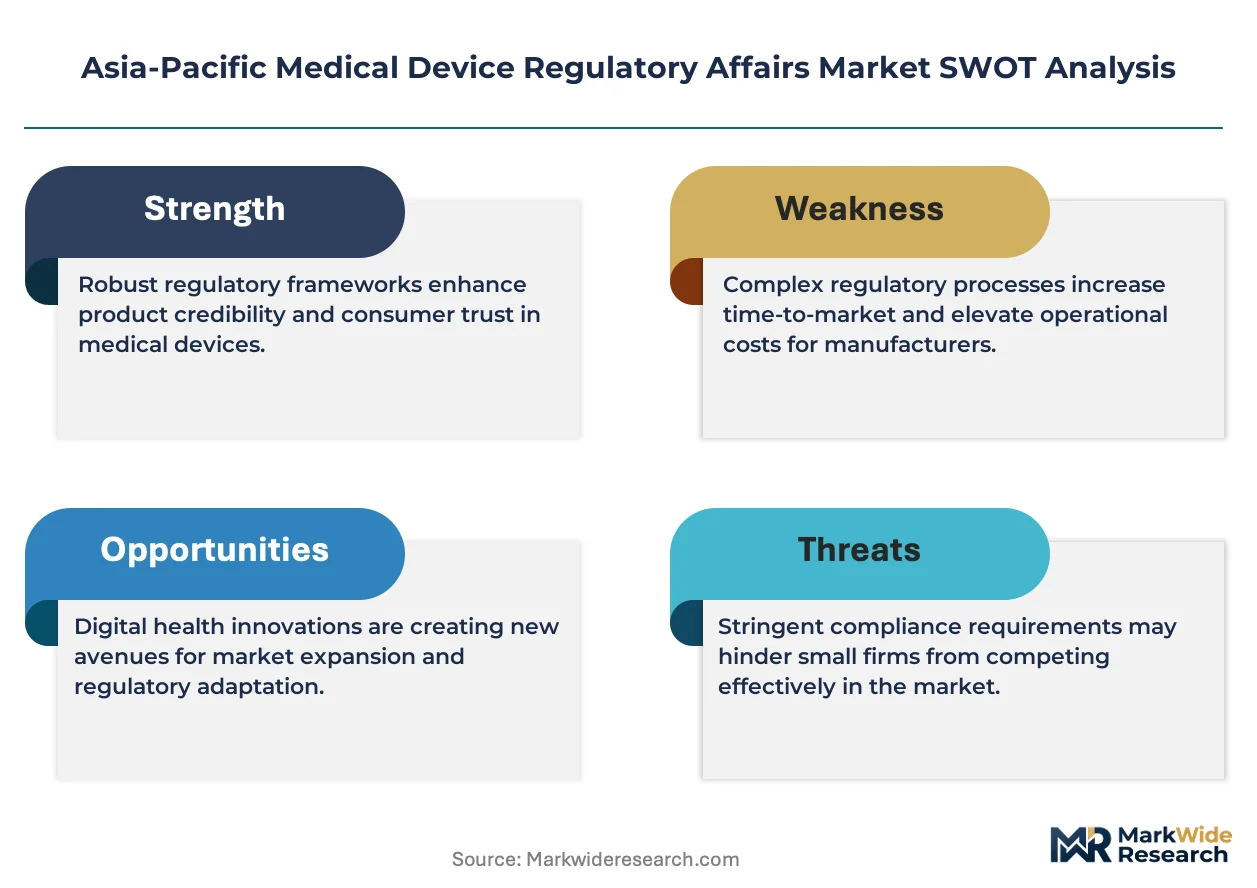
For Market Incumbents: Secure PMDA Sakigake pathway expertise through targeted certification investment in Tokyo-based talent pools, as domestic manufacturers prioritize Japan-first regulatory strategies that compress time-to-market for cardiovascular and neurology devices. Consolidate compliance management relationships into multi-year audit support contracts before AI platforms commoditize routine documentation functions. Vertical integration into software validation capabilities addresses cross-functional talent scarcity combining clinical evaluation with SaMD expertise. For New Entrants and Emerging Players: Lead with Southeast Asian regulatory greenfield opportunities in Vietnam, Indonesia, and Thailand where mature device approval frameworks remain underdeveloped and first-mover advantage accrues to outsourced compliance services. Target AI-enabled diagnostic tool manufacturers in South Korea and Taiwan seeking specialized SaMD submission capabilities across PMDA, TGA, and NMPA jurisdictions simultaneously. Go-to-market angle centers on embedding regulatory logic directly into product development workflows rather than post-hoc consulting engagement. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified CROs with pan-Asia-Pacific consulting networks and proprietary AI document generation platforms. Long-term viability over the next decade hinges on technology-enabled scale rather than headcount-based consulting models. Acquisition target archetype combines PMDA/TGA dual expertise with software validation capabilities. Signal to watch is NMPA's evolving international reference country acceptance criteria, which could force repeated dossier restructuring and elevate demand for adaptive regulatory technology infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Document Generation Platform | Compresses PMDA STED preparation timelines while embedding compliance logic into Shenzhen and Seoul manufacturer workflows. |
| PMDA Sakigake Pathway Investment | Captures priority consultation access for cardiovascular device sponsors building Japan-first regulatory strategies. |
| Southeast Asia Regulatory Greenfield Expansion | Establishes first-mover compliance services in Vietnam and Indonesia before mature framework development. |
| Software Validation Capability Buildout | Addresses SaMD submission demand across TGA, PMDA, and NMPA as AI diagnostic tools trigger new categories. |
| EU MDR Alignment Leverage Program | Enables CE Mark holders to penetrate Australian markets through TGA technical standard convergence with minimal incremental documentation. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs directors, quality system managers, PMDA submission specialists, and hospital procurement officers across Japan, China, Australia, and South Korea; and secondary validation through PMDA approval databases, TGA Essential Principles guidance documents, NMPA GB standard filings, and GPO contract repositories. Bottom-up triangulation across service type procurement patterns and top-down reconciliation against device manufacturer regulatory spend disclosures anchored volume and value estimates.
Across the analysis window, the forecasting framework modeled service type segmentation—consulting, compliance management, quality assurance, and training—alongside device category complexity gradients from surgical instruments through software-enabled therapeutic systems. CAGRs derived from regression analysis of historical approval timeline compression, regulatory headcount expansion rates at major device manufacturers, and technology adoption curves for AI-powered document generation platforms. Industry-specific inputs included PMDA inspection cadence expansion schedules and TGA-EU MDR alignment implementation milestones.
Underlying assumptions cover sustained NMPA international harmonization momentum and stable PMDA QMS ordinance enforcement intensity, with deviation risk concentrated in China's evolving reference country acceptance criteria and Japan's Sakigake designation expansion beyond cardiovascular and neurology categories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pectus Bar System Market
Medical Devices
Medical Devices Clinical Trials Market
Medical Devices
MRI-Compatible IV Infusion Pump Systems Market
Medical Devices
Central Venous Catheter Market
Medical Devices
Electrosurgery Devices Market
Medical Devices
Europe Biopsy Devices Market
Medical Devices
Oxygen Conserving Devices Market
Medical Devices
Cardiac Ablation Devices Market
Medical Devices
Global Operating Microscopes Market
Medical Devices
Catheter Securement Devices Market
Medical Devices
Global Insulin Pumps Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Subdural Electrodes Market
Medical Devices
Global Portable Ultrasound Equipment Market
Medical Devices
South Africa Aesthetic Devices Market
Medical Devices
Nerve Stimulators Market