
 Global Angiography Devices Market | 2026-2036
Global Angiography Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Angiography Devices Market Foresight
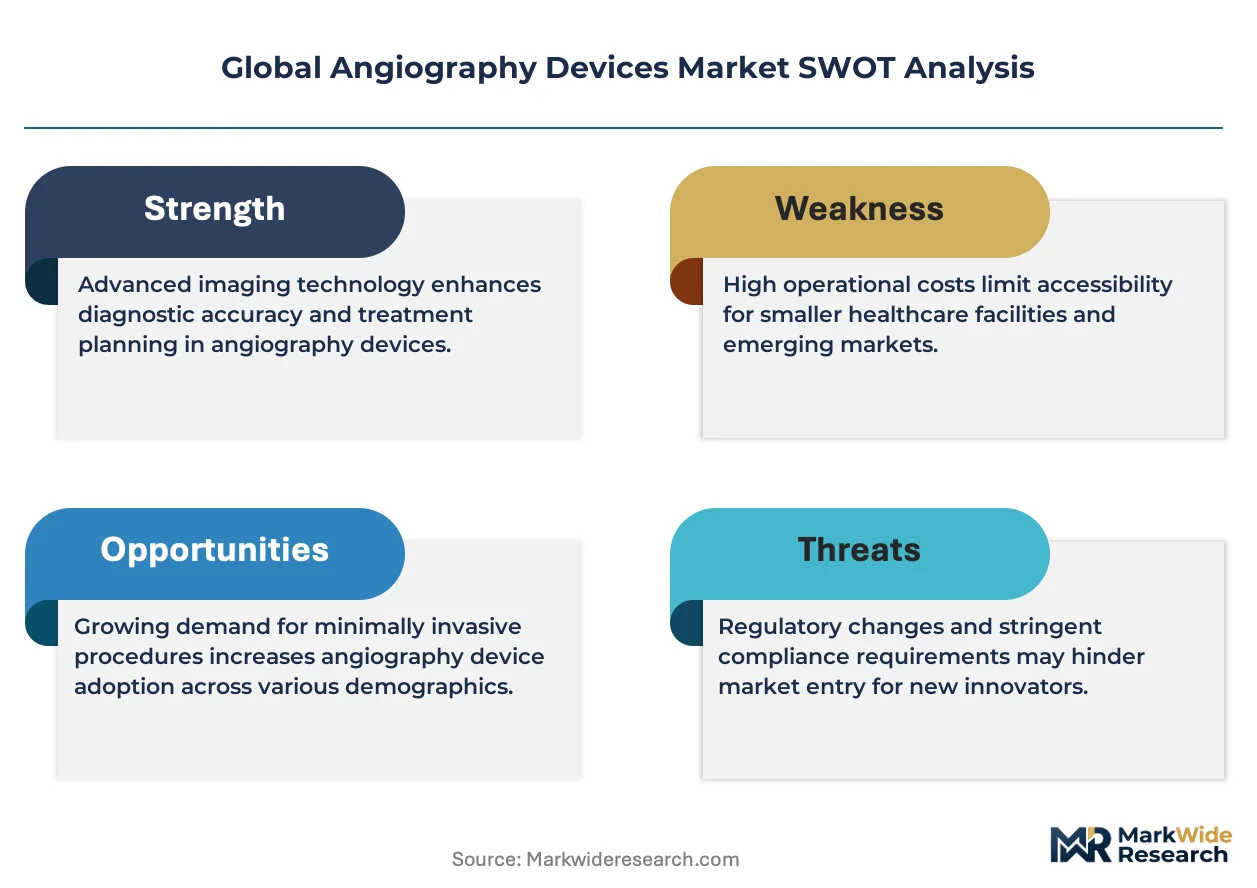
Interventional cardiologist and radiographer shortages in tertiary hospitals is reorganizing capital deployment toward automated angiography platforms with reduced operator dependence. Siemens Healthineers AG leverages integrated imaging-therapy workflows to sustain installed-base loyalty across European university hospitals. GE Healthcare anchors its position through proprietary detector technology and dense service networks in North American metropolitan markets. Canon Medical Systems Corporation specializes in compact floor-mounted systems that occupy space-constrained catheterization labs in Asian urban centers.
Angiography devices comprise X-ray-based imaging systems, injectable catheters, vascular guidewires, and iodinated contrast media that enable real-time visualization of blood vessel anatomy during diagnostic and interventional procedures. These systems operate at 80-120 kV tube potential with flat-panel detectors capturing 30 frames per second to guide percutaneous coronary and neurovascular interventions. Digital subtraction angiography systems retain dominant installed-base share while magnetic resonance angiography segments gain traction in radiation-sensitive pediatric and renal patient populations. Contrast media formulations face margin compression as generic isosmolar agents compete with premium iodixanol alternatives in European procurement tenders.
FDA 510(k) clearance timelines and EU MDR technical documentation requirements shape product development cycles and market access costs for device manufacturers. Japan's PMDA enforces stringent post-market surveillance protocols that extend validation periods for novel angiography software algorithms. China's NMPA accelerates review pathways for domestically manufactured flat-panel detectors under innovation medical device designation. Stakeholders must monitor reimbursement recalibrations for outpatient catheterization procedures and synthetic catheter material sourcing constraints.
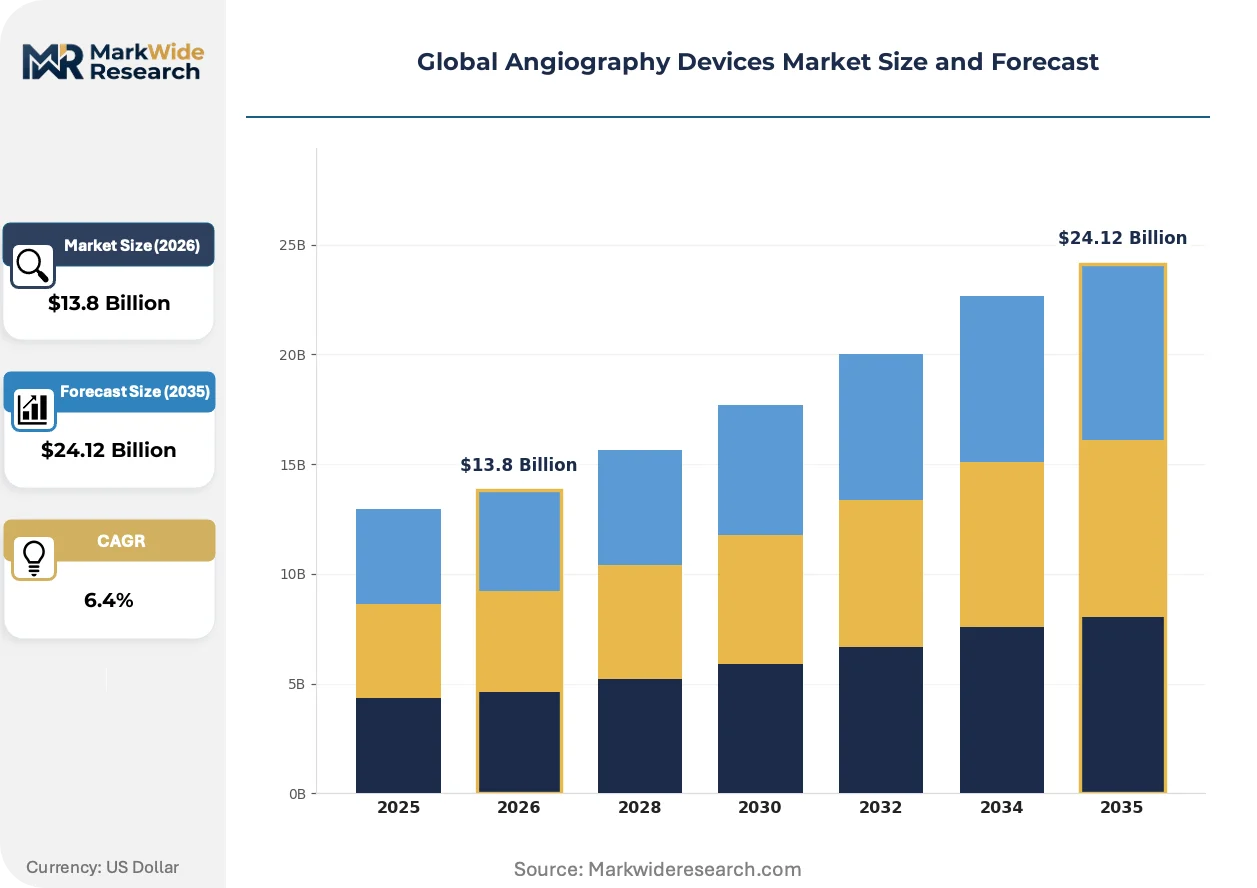
Market Dynamics
Interventional cardiologist shortages across tertiary hospitals are forcing capital deployment toward automated angiography platforms with reduced operator dependence, compressing procurement cycles for conventional manual systems.
Growth Catalysts
- EU MDR compliance mandates:Stricter CE marking requirements under the EU Medical Device Regulation are accelerating replacement of legacy systems in German and French university hospitals.
- Flat-panel detector technology:Direct conversion cesium iodide detectors are expanding diagnostic accuracy in high-volume catheterization labs across the United States and Japan.
- Aging demographics in developed markets:Cardiovascular disease prevalence in populations over 65 is sustaining procedure volumes in the United States, Germany, and Japan.
Market Restraints
- Iodinated contrast media cost volatility:Supply concentration for iodixanol active pharmaceutical ingredients in Indian and Chinese chemical manufacturers creates input price uncertainty.
- FDA 510(k) pathway friction:Extended premarket notification timelines for novel software algorithms delay commercialization of AI-assisted image reconstruction features.
- Magnetic resonance angiography substitution:Radiation-free vascular imaging is capturing pediatric and renal-sensitive patient segments in European pediatric centers.
Strategic Opportunities
- China NMPA innovation pathways:Accelerated review designations for domestically manufactured flat-panel detectors create regulatory tailwinds for local production.
- Neurovascular intervention expansion:Mechanical thrombectomy procedure growth is driving demand for biplane angiography configurations in stroke centers.
- Compact floor-mounted systems:Space-constrained catheterization labs in Asian urban centers favor mobile C-arm alternatives to ceiling-suspended installations.
Industry Challenges
- Radiographer workforce gaps:Specialized interventional imaging technologist shortages in tertiary hospitals limit utilization rates of installed angiography suites.
- EU MDR technical documentation burden:Clinical evidence requirements for legacy device recertification are consuming regulatory affairs bandwidth at mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Angiography Devices Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
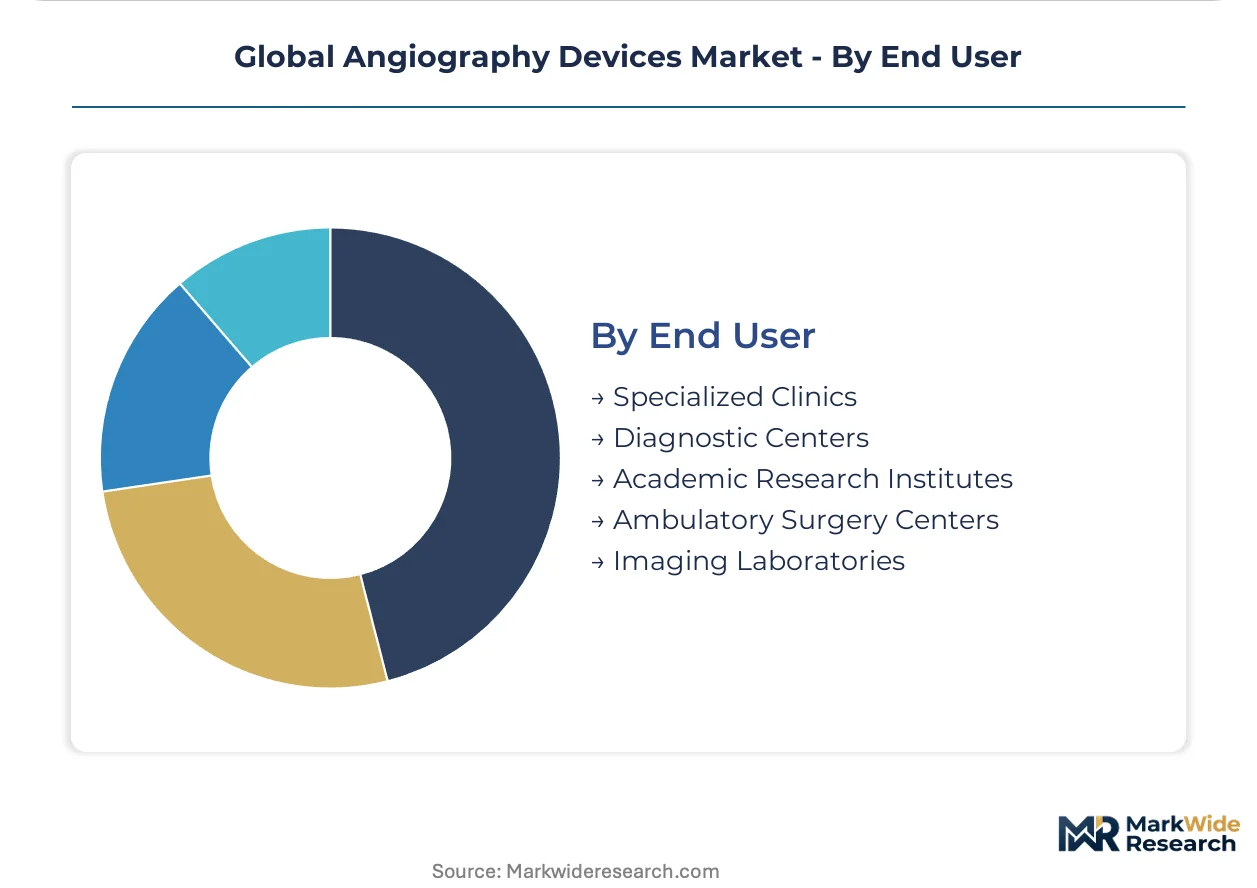
| Segmentation | Product Type: Systems, Catheters, Accessories, Imaging Software, Contrast Media Technology: Digital Subtraction Angiography, Fluoroscopy, Computed Tomography Angiography, Magnetic Resonance Angiography, Optical Coherence Tomography Application: Cardiovascular Diagnosis, Neurovascular Imaging, Peripheral Vascular Assessment, Oncology, Interventional Radiology End User: Specialized Clinics, Diagnostic Centers, Academic Research Institutes, Ambulatory Surgery Centers, Imaging Laboratories |
| Companies Covered | GE Healthcare, Siemens Healthineers AG, Koninklijke Philips NV, Canon Medical Systems Corporation, Boston Scientific Corporation, Medtronic PLC, Shimadzu Corporation, AngioDynamics Inc., Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Angiography Devices Market Shifts & Advancements
Automation and artificial intelligence are restructuring how angiography systems capture, process, and guide interventional decisions, shifting competitive advantage toward integrated workflow platforms.
Photon-counting detector technology is bifurcating the installed base between premium digital subtraction systems and conventional energy-integrating platforms. Tertiary cardiac centers in the United States and Germany are prioritizing these detectors for complex coronary interventions despite capital cost premiums. The technology is bifurcating procurement budgets, forcing mid-tier hospitals into extended replacement cycles or refurbished equipment markets.
Japan's PMDA post-market surveillance protocols are extending validation periods for novel angiography software algorithms beyond comparable FDA timelines. Manufacturers must maintain extended clinical follow-up databases for AI-assisted stent positioning features before commercial release. Japanese stroke centers are responding by consolidating procurement around established vendors with proven algorithm track records.
Service contract unbundling is fragmenting how hospitals acquire maintenance and software upgrade commitments for angiography platforms. Independent service organizations are capturing aftermarket service volumes in North American metropolitan markets previously dominated by original equipment manufacturers. This shift is most pronounced in multi-hospital systems seeking to standardize service costs across mixed-vendor installed bases.
Global Angiography Devices Market Segmentation
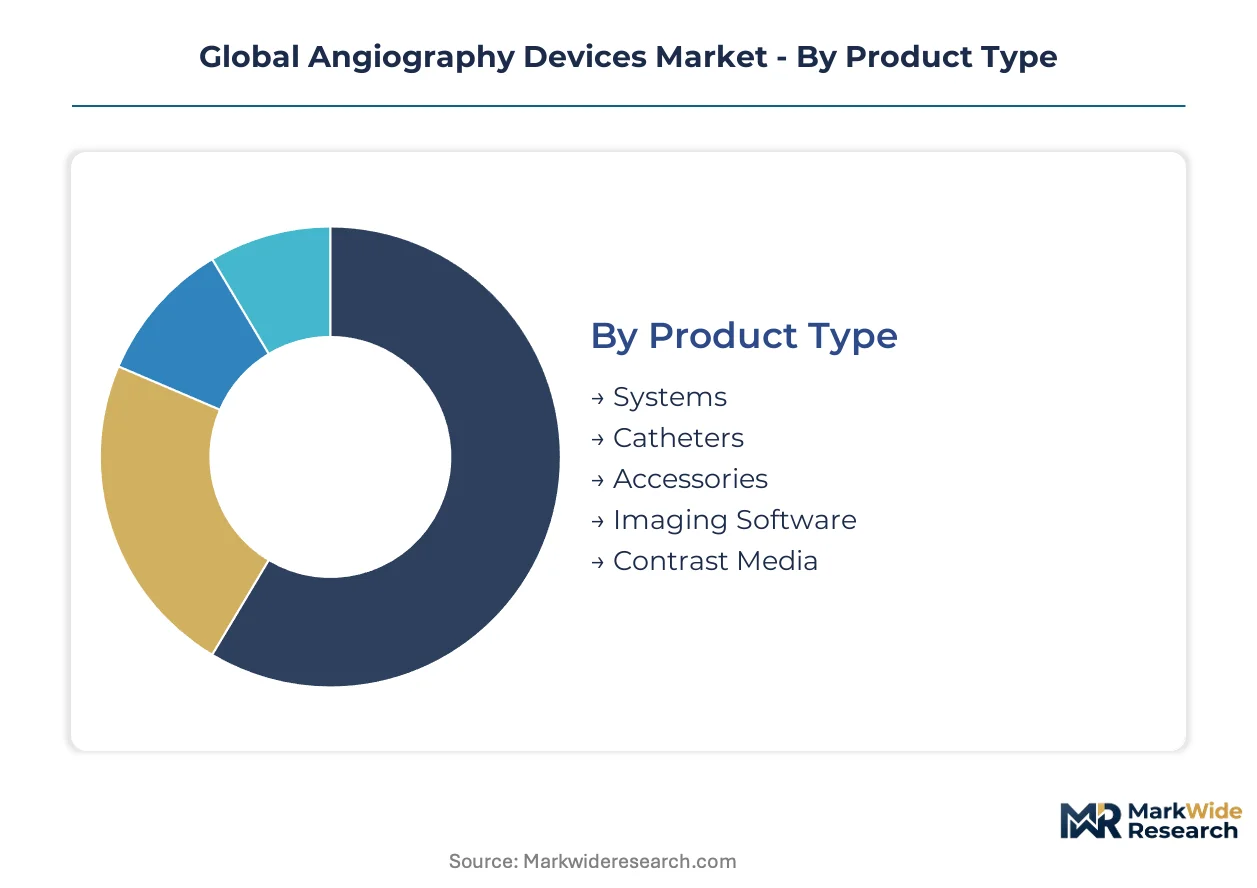
Angiography device segmentation reveals how regulatory pathways, clinical workflows, and capital deployment priorities fragment procurement decisions across healthcare systems. Each dimension carries distinct compliance burdens and reimbursement implications that reshape vendor strategies.
Product Type:
FDA 510(k) clearance timelines and EU MDR technical documentation requirements create divergent market access costs across hardware versus consumable categories.
- Systems:Ceiling-mounted and floor-mounted C-arm configurations operate at 80-120 kV tube potential with flat-panel detectors capturing 30 frames per second. German university hospitals and Japanese stroke centers are prioritizing photon-counting detector upgrades despite capital premiums.
- Catheters:Injectable catheters with hydrophilic coatings and variable stiffness profiles enable vascular navigation during percutaneous coronary interventions. Demand concentrates in United States cardiac catheterization laboratories where procedure volumes sustain high-volume disposable consumption.
- Accessories:Vascular guidewires, manifold sets, and pressure transducers complement core system utilization.
- Imaging Software:AI-assisted image reconstruction and stent positioning algorithms face extended PMDA validation periods in Japan.
- Contrast Media:Iodinated formulations encounter margin compression as generic isosmolar agents compete with premium iodixanol in European procurement tenders.
Established volume favors Systems; emerging adoption favors Imaging Software.
Technology:
Detector physics and radiation exposure profiles segment procurement between premium digital subtraction platforms and radiation-sensitive alternatives.
- Digital Subtraction Angiography:Energy-integrating and photon-counting detectors retain dominant installed-base share through real-time bone and soft-tissue subtraction. United States tertiary cardiac centers are bifurcating budgets toward premium configurations while mid-tier hospitals extend replacement cycles.
- Fluoroscopy:Continuous X-ray imaging at reduced dose rates supports interventional guidance in cost-constrained settings. Asian urban catheterization labs favor mobile C-arm fluoroscopy systems where space constraints preclude ceiling-suspended installations.
- Computed Tomography Angiography:Non-invasive vascular assessment with multi-detector row scanners captures outpatient diagnostic volumes.
- Magnetic Resonance Angiography:Radiation-free imaging gains traction in European pediatric centers and renal-sensitive patient populations where iodinated contrast contraindications apply.
- Optical Coherence Tomography:Intravascular imaging at near-infrared wavelengths provides microstructural plaque characterization during coronary interventions.
Digital Subtraction Angiography commands current procurement budgets; Magnetic Resonance Angiography climbs the fastest among radiation-avoidant segments.
Application:
Procedure reimbursement stability and clinical workforce availability determine capital allocation across diagnostic and interventional service lines.
- Cardiovascular Diagnosis:Coronary angiography and fractional flow reserve assessment dominate procedure volumes in aging populations. United States, Germany, and Japan sustain replacement cycles through stable outpatient catheterization reimbursement.
- Neurovascular Imaging:Mechanical thrombectomy for acute ischemic stroke drives biplane angiography configuration demand. Japanese stroke centers are consolidating procurement around established vendors with proven algorithm track records.
- Peripheral Vascular Assessment:Lower-extremity runoff studies and renal artery interventions address diabetic and hypertensive patient populations.
- Oncology:Tumor embolization and transarterial chemoembolization procedures require specialized angiography suites with cone-beam CT capability.
- Interventional Radiology:Cross-specialty procedural convergence expands utilization beyond traditional cardiology departments.
Cardiovascular Diagnosis retains the largest installed base; Neurovascular Imaging shows the steepest expansion trajectory from stroke center network growth.
End User:
Capital intensity and service contract structures fragment procurement authority between integrated health systems and independent diagnostic facilities.
- Specialized Clinics:Dedicated cardiovascular and neurovascular intervention centers concentrate high-complexity procedures. United States metropolitan markets are seeing independent service organizations capture aftermarket service volumes previously dominated by original equipment manufacturers.
- Diagnostic Centers:Outpatient imaging facilities prioritize throughput optimization and rapid patient turnover. China's NMPA innovation pathways for domestically manufactured flat-panel detectors are accelerating procurement of cost-optimized systems in these settings.
- Academic Research Institutes:Clinical trial infrastructure and training programs sustain demand for premium configurations with research software modules.
- Ambulatory Surgery Centers:Same-day discharge protocols favor compact systems with reduced facility infrastructure requirements.
- Imaging Laboratories:High-volume screening operations emphasize workflow automation and technologist productivity.
Specialized Clinics anchor current revenue concentration; Ambulatory Surgery Centers are gaining share fastest from site-of-care migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Angiography device consumption patterns diverge sharply between developed markets prioritizing premium detector upgrades and emerging economies optimizing for space-constrained installations. Procedure reimbursement stability and regulatory pathway efficiency determine replacement cycle velocity across national healthcare systems.
United States
Tertiary cardiac centers drive demand for photon-counting detector configurations despite capital premiums. FDA 510(k) clearance timelines shape commercialization schedules for AI-assisted image reconstruction features. The Cleveland Clinic and Mayo Clinic anchor procurement concentration in the Midwest, consolidating around vendors with dense service networks.
Germany
University hospitals accelerate replacement of legacy systems under EU MDR compliance mandates. CE marking technical documentation requirements consume regulatory bandwidth at mid-tier manufacturers. The Rhine-Ruhr metropolitan cluster sustains Europe's densest concentration of interventional imaging suites, with Charité Berlin anchoring academic demand.
Japan
Stroke centers consolidate procurement around established vendors with proven algorithm track records. PMDA post-market surveillance protocols extend validation periods for novel angiography software beyond FDA timelines. Tokyo and Osaka metropolitan areas concentrate biplane angiography installations for mechanical thrombectomy procedures.
China
Domestic flat-panel detector manufacturers gain share through NMPA innovation pathway accelerations. Space-constrained catheterization labs in tier-one cities favor compact floor-mounted systems over ceiling-suspended alternatives. The Yangtze River Delta medical device cluster drives localization of detector production for cost-optimized procurement.
India
Private hospital chains expand interventional cardiology capacity in Delhi-NCR and Mumbai metropolitan regions. CDSCO medical device registration timelines create market access friction for novel system configurations. Hyderabad's medical technology corridor attracts assembly operations for refurbished equipment serving mid-tier hospital budgets.
Global Angiography Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in angiography device supply. The upper tier commands installed-base loyalty through dense service networks and proprietary detector technology, while mid-tier competitors compete on capital cost and regional regulatory familiarity. Two strategic archetypes dominate: integrated imaging-therapy workflow providers and compact system specialists for space-constrained installations. Competitive moves concentrate on unbundling service contracts to capture aftermarket volumes and accelerating regulatory submissions through jurisdiction-specific pathway optimization.
Among diversified health technology conglomerates, GE Healthcare, Siemens Healthineers AG, and Canon Medical Systems Corporation occupy positions spanning detector technology, system integration, and geographic service density. These entities exemplify the integrated-tier archetype through their simultaneous presence across imaging hardware, software algorithms, and maintenance infrastructure. Their collective footprint shapes procurement standards in tertiary hospitals across the United States, Germany, and Japan.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers AG |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Boston Scientific Corporation |
| Medtronic PLC |
| Shimadzu Corporation |
| AngioDynamics Inc. |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
Ninety-to-one-hundred-twenty-day lead times for cesium iodide flat-panel detectors concentrate pricing power with Japanese and German component suppliers, compressing margins for mid-tier system assemblers while elevating premium-tier vendor margins through captive supply control.
Pricing Analysis
Long-term service contracts dominate procurement in United States hospital systems, with multi-year maintenance and software upgrade bundles separating premium vendors from standard-tier competitors. Price differentiation rests on photon-counting detector certification grades and FDA 510(k) clearance tier status. Cost compression in standard-tier systems intensifies as Chinese flat-panel manufacturers expand NMPA-certified production. Ambulatory surgery centers exhibit highest price sensitivity; tertiary cardiac centers demonstrate lowest sensitivity due to reimbursement stability.
Supply Chain Analysis
Strategic stockpiling of iodinated contrast media active pharmaceutical ingredients characterizes procurement at European university hospitals facing Indian and Chinese supply concentration. Component sourcing draws from Japan for detector crystals, Germany for precision tube assemblies, and China for generic flat-panel substrates. Single-source vulnerability concentrates in isosmolar contrast agent precursors from select Indian chemical manufacturers. Distribution runs through original equipment manufacturer service networks and independent service organizations competing in North American metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract unbundling expands recurring revenue faster than hardware sales, with independent service organizations capturing aftermarket volumes previously locked by original equipment manufacturers.
For Market Incumbents: Compound installed-base loyalty through dense detector refurbishment networks and proprietary software algorithm roadmaps. Magnetic resonance angiography substitution in pediatric segments threatens digital subtraction installed bases. Vertical integration into cesium iodide crystal production secures supply priority during input shortages. For New Entrants and Emerging Players: Differentiate on compact floor-mounted configurations optimized for space-constrained Asian urban catheterization labs. China's NMPA innovation pathway offers the most penetrable regulatory entry point. Hospital system partnership models bypass direct capital purchase barriers through equipment-as-a-service structures. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized angiography software divisions. Long-term viability centers on algorithm-enabled workflow platforms rather than commodity hardware. Monitor PMDA validation period extensions as inflection indicator for Japanese market consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation requirements consume mid-tier manufacturer regulatory bandwidth. |
| Hospital System Partnership | Multi-hospital standardization contracts reduce procurement friction across mixed-vendor installed bases. |
| Software Companion Development | AI-assisted stent positioning algorithms extend validation periods under Japanese PMDA protocols. |
| Reimbursement Strategy | Outpatient catheterization procedure coding stability sustains replacement cycles in United States markets. |
| FDASubmission | 510(k) clearance timelines for novel detector configurations shape commercialization schedules. |
Research Methodology
Initial hypotheses were tested against primary input from interventional cardiologists, hospital biomedical engineers, GPO contracts managers, and regulatory affairs leads at device manufacturers and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates triangulated with top-down capital expenditure patterns across the analysis window.
Variance decomposition across product type, technology platform, application specialty, and end-user facility tier informed the analytical framework. CAGRs derived from installed-base replacement cycles, procedure volume trajectories, and capital budget elasticity modeling. Photon-counting detector adoption curves and NMPA pathway acceleration effects served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside stable reimbursement conditions and unaltered regulatory timelines would require recalibration. Practitioners should keep alternative scenarios live as EU MDR enforcement intensity and PMDA algorithm validation protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Hemodialysis Catheters Market
Medical Devices
Disposable Medicine Measuring Cups Market
Medical Devices
Intravascular Temperature Management Systems Market
Medical Devices
Global Portable Ventilators Market
Medical Devices
Nasal Implant Market
Medical Devices
Pharmaceutical Robots Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
Skin Revitalizing Handheld Devices Market
Medical Devices
Photorejuvenation Devices Market
Medical Devices
US Medical Bionic Implants & Artificial Organs Market
Medical Devices
Cervical Disc Prosthesis Market
Medical Devices
Sinus Irrigation Systems Market
Medical Devices
Interlaminar Device Market
Medical Devices
Intubation Accessories Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
Intermittent Catheters Market