
 Global Intra-Cranial Pressure (ICP) Monitor Market | 2026-2036
Global Intra-Cranial Pressure (ICP) Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intra-Cranial Pressure (ICP) Monitor Market Foresight
Neurosurgical centers are expanding their ICP monitoring capabilities faster than emergency departments as complex cranial procedures migrate to dedicated facilities. Medtronic leverages its broad neurosurgery portfolio to anchor hospital supply contracts across North America. Integra LifeSciences specializes in differentiated catheter technologies that sustain premium positioning in critical care settings. Sophysa competes through focused European manufacturing and direct service relationships with academic medical centers.
Intra-cranial pressure monitoring encompasses invasive and non-invasive systems that measure cerebrospinal fluid dynamics or parenchymal pressure, typically employing fiberoptic transducers or microelectromechanical sensors with accuracy thresholds within 1-2 mmHg for clinical decision-making in traumatic brain injury management. Fiberoptic technology leads in margin pools due to superior drift stability and biocompatibility profiles, while wireless transmission architectures represent the fastest-growing segment as hospitals prioritize reduced infection risk and enhanced patient mobility. Parenchymal monitors occupy the largest installed base among product types, though intraventricular systems retain dominance in academic neurosurgery where cerebrospinal fluid drainage integration remains essential.
FDA premarket notification pathways and EU MDR Class III device requirements shape product development timelines and clinical evidence burdens for manufacturers seeking market access. Japan's PMDA enforces stringent biocompatibility testing protocols that extend registration cycles for foreign device suppliers. Stakeholders must monitor evolving reimbursement thresholds for invasive neuromonitoring across Medicare, NHS England, and Japan's MHLW fee schedules as these determine hospital capital allocation priorities.
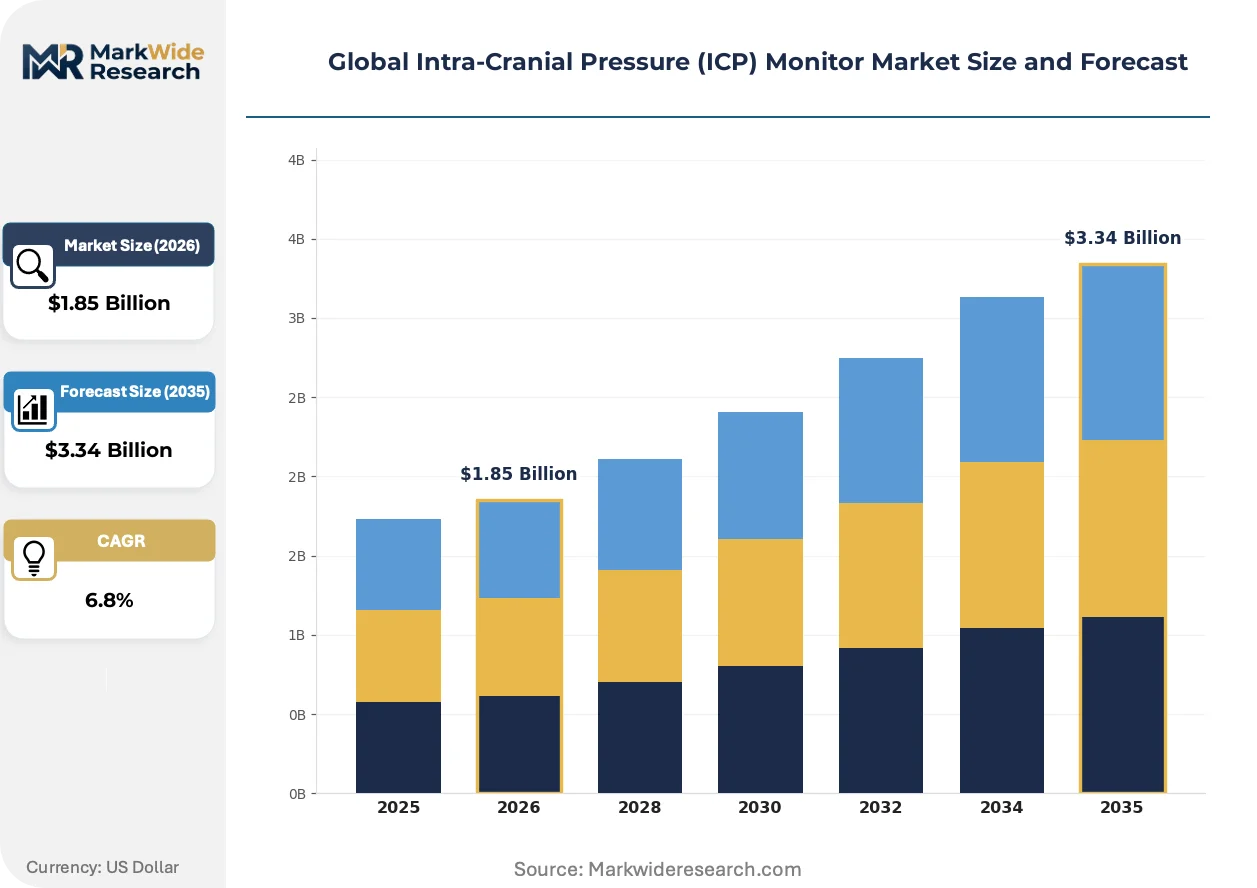
Market Dynamics
Fiberoptic transducer miniaturization is compressing catheter manufacturing costs while EU MDR Class III implantable device requirements extend clinical trial timelines for neurosurgical equipment suppliers.
Growth Catalysts
- EU MDR harmonization:Streamlined conformity assessment pathways for Class III neuromonitoring devices accelerate market access for qualified manufacturers across Germany, France, and Italy.
- Neurotrauma center consolidation:Tertiary referral networks in the United States concentrate high-acuity cranial procedures, concentrating demand for precision ICP systems at specialized surgical hubs.
- Wireless telemetry architectures:Bluetooth Low Energy and proprietary RF protocols eliminate tethered connections, reducing catheter-related infection risk during extended neurocritical care monitoring.
Market Restraints
- Silica fiber supply concentration:Specialty optical fiber production clusters in Japan and Germany create input vulnerability for catheter manufacturers dependent on biocompatible glass formulations.
- PMDA biocompatibility testing protocols:Extended cytotoxicity and sensitization studies for implantable neurosurgical devices delay Japanese registration cycles by 18-24 months relative to FDA 510(k) pathways.
- Non-invasive ICP estimation:Transcranial Doppler and optic nerve sheath diameter ultrasound methods threaten invasive monitor volumes in emergency department triage settings where catheter placement delays treatment.
Strategic Opportunities
- India neurocritical care expansion:Greenfield neurosurgery units in Delhi, Mumbai, and Bangalore seek cost-optimized ICP monitoring platforms as trauma center accreditation standards tighten.
- Artificial intelligence integration:Machine learning algorithms processing continuous ICP waveforms enable automated cerebral autoregulation assessment, creating differentiated analytics revenue streams.
- Home-based rehabilitation monitoring:Portable wireless ICP systems address post-craniotomy patient surveillance needs during step-down care, extending product lifecycle value beyond acute hospitalization.
Industry Challenges
- Neurocritical care specialist shortage:Fellowship-trained intensivists capable of interpreting complex ICP waveform patterns remain scarce outside academic medical centers in the United States and Western Europe.
- Legacy EMR integration complexity:Proprietary data formats from competing catheter manufacturers obstruct seamless flow of ICP trends into hospital electronic medical record systems, requiring costly interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intra-Cranial Pressure (ICP) Monitor Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraventricular, Subdural, Epidural, Parenchymal, Fiberoptic Technology: Microelectromechanical Sensors, Digital Signal Processing, Wireless Transmission, Optical Fiber, Pneumatic Application: Traumatic Brain Injury, Hydrocephalus, Brain Tumor, Stroke, Neurosurgery End User: Neurosurgical Centers, Critical Care Units, Emergency Departments, Rehabilitation Clinics, Specialty Hospitals |
| Companies Covered | Medtronic, Integra LifeSciences, RAUMEDIC AG, Sophysa, Spiegelberg GmbH & Co. KG, Natus Medical, Codman Neuro, GE Healthcare, Philips Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intra-Cranial Pressure (ICP) Monitor Market Shifts & Advancements
Digital signal processing and materials science advances are transforming catheter performance benchmarks while regulatory science evolution reshapes evidence requirements for implantable neuromonitoring platforms.
MEMS-based piezoresistive pressure sensors are automating drift correction in parenchymal monitors through real-time temperature compensation algorithms. Neurosurgical departments at academic medical centers in Germany and Japan are piloting these solid-state alternatives to fiberoptic transducers for extended monitoring protocols. The technology is automating calibration workflows that previously required bedside clinician intervention every 72 hours.
EU MDR post-market surveillance mandates now require systematic collection of real-world performance data for Class III implantable devices across their entire commercial lifecycle. Manufacturers must maintain active implant registries tracking device survival, explant causes, and patient outcomes. French and Italian notified bodies are enforcing these requirements most stringently, delaying certificates of conformity for suppliers with immature vigilance systems.
Hospital procurement committees are consolidating neurosurgical device contracts under value-analysis frameworks that bundle ICP monitors with cranial access kits and dural closure products. This purchasing pattern concentrates vendor selection authority at integrated delivery networks in the United States, displacing individual surgeon preference item decisions. The shift is most pronounced in California and Texas health systems pursuing supply chain standardization across multiple neurosurgical sites.
Global Intra-Cranial Pressure (ICP) Monitor Market Segmentation
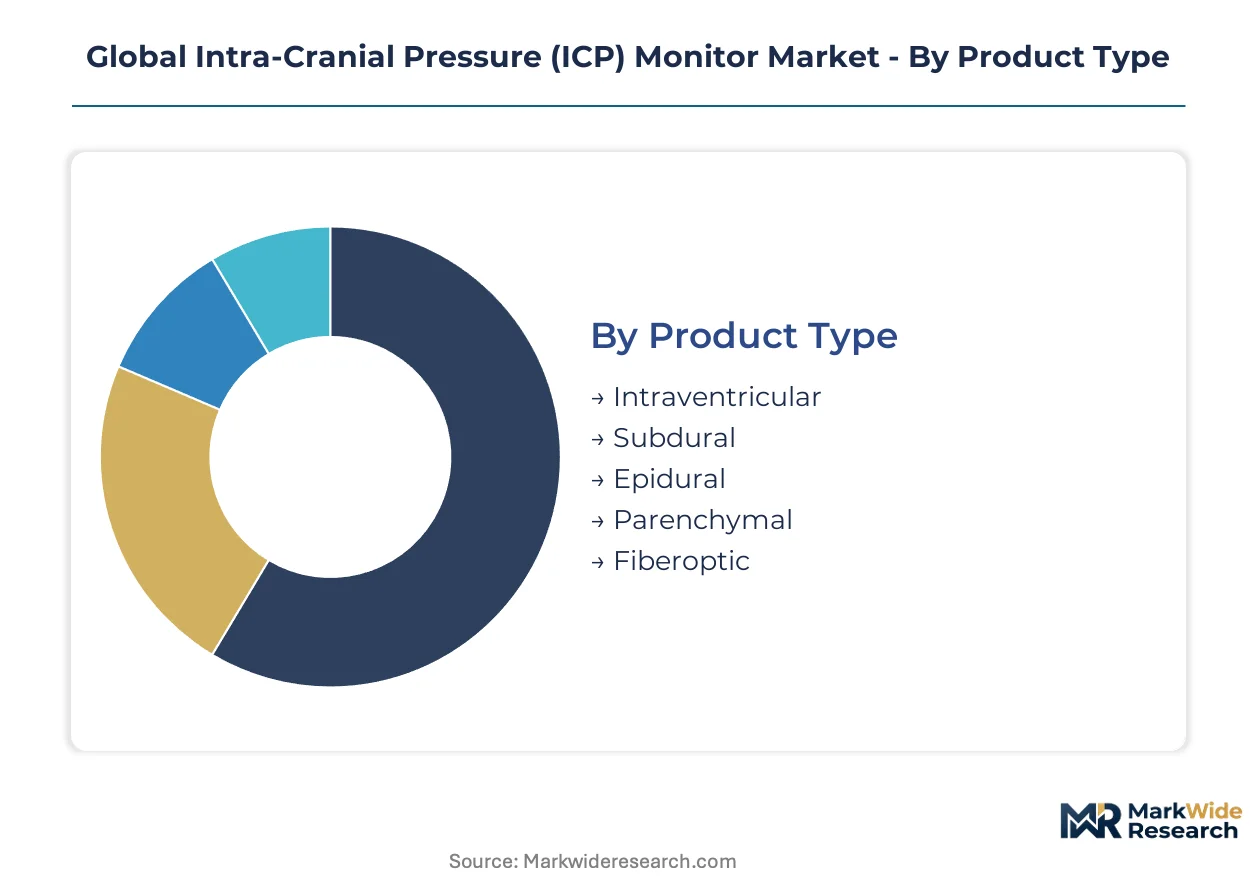
ICP monitor procurement varies sharply by clinical setting and technical requirements. Product specifications, connectivity architectures, and end-user workflows create distinct demand clusters that manufacturers must address through differentiated positioning.
Product Type:
Neurosurgeons select catheter placement based on cerebrospinal fluid access needs and monitoring duration requirements.
- Parenchymal:Solid-state microsensors embedded directly into brain tissue deliver continuous pressure readings without ventricular cannulation. Neurosurgical centers in the United States and Germany favor these systems for extended traumatic brain injury protocols where catheter stability over 7-14 days proves essential.
- Fiberoptic:Silica-based transducers with superior drift stability dominate high-acuity settings requiring sub-millimeter precision. Academic medical centers in Japan prioritize these systems for research-grade waveform acquisition despite premium pricing.
- Intraventricular:Catheters placed within cerebral ventricles enable simultaneous pressure monitoring and CSF drainage. These systems retain primacy in hydrocephalus management.
- Subdural:Placement between dural layers offers intermediate invasiveness for short-term postoperative surveillance.
- Epidural:Extra-dural positioning reduces hemorrhage risk but sacrifices accuracy, limiting use to screening applications.
Volume sits with parenchymal systems; growth tilts toward fiberoptic as drift tolerance standards tighten.
Technology:
Signal fidelity and infection risk trade-offs determine technology selection across hospital capital budgets.
- Wireless Transmission:Bluetooth Low Energy and proprietary RF protocols eliminate bedside tethering, reducing catheter-related infection pathways. Critical care units in California and Texas health systems are standardizing these architectures for step-down care transitions.
- Optical Fiber:Biocompatible glass formulations deliver thermal stability and electromagnetic immunity for intraoperative MRI compatibility. German and Japanese catheter manufacturers maintain captive supply relationships with specialty fiber producers.
- Microelectromechanical Sensors:Silicon-based piezoresistive elements enable automated temperature compensation.
- Digital Signal Processing:On-chip algorithms filter artifact and enable waveform pattern recognition.
- Pneumatic:Air-filled pressure transmission systems persist in cost-sensitive markets despite calibration demands.
Optical fiber commands premium positioning; wireless transmission is gaining share fastest through infection control priorities.
Application:
Pathophysiology dictates monitoring duration, accuracy thresholds, and integration with therapeutic interventions.
- Traumatic Brain Injury:Guidelines mandate ICP monitoring for severe TBI with Glasgow Coma Scale scores below 9, driving sustained demand for multi-day continuous surveillance. Level I trauma centers in the United States, Germany, and Japan anchor procurement volumes.
- Hydrocephalus:Chronic CSF dynamics management requires ventricular access systems with drainage integration. Pediatric neurosurgery units represent concentrated demand for programmable shunt-compatible monitors.
- Brain Tumor:Perioperative monitoring during craniotomy and post-resection edema surveillance creates episodic demand tied to surgical schedules.
- Stroke:Hemorrhagic conversion and malignant edema protocols drive emergency department triage applications.
- Neurosurgery:Broad category encompassing elective cranial procedures with standardized postoperative monitoring protocols.
Traumatic brain injury anchors installed base; hydrocephalus applications show steepest expansion trajectory through pediatric specialty center growth.
End User:
Facility capabilities and reimbursement structures fragment purchasing authority across care continuums.
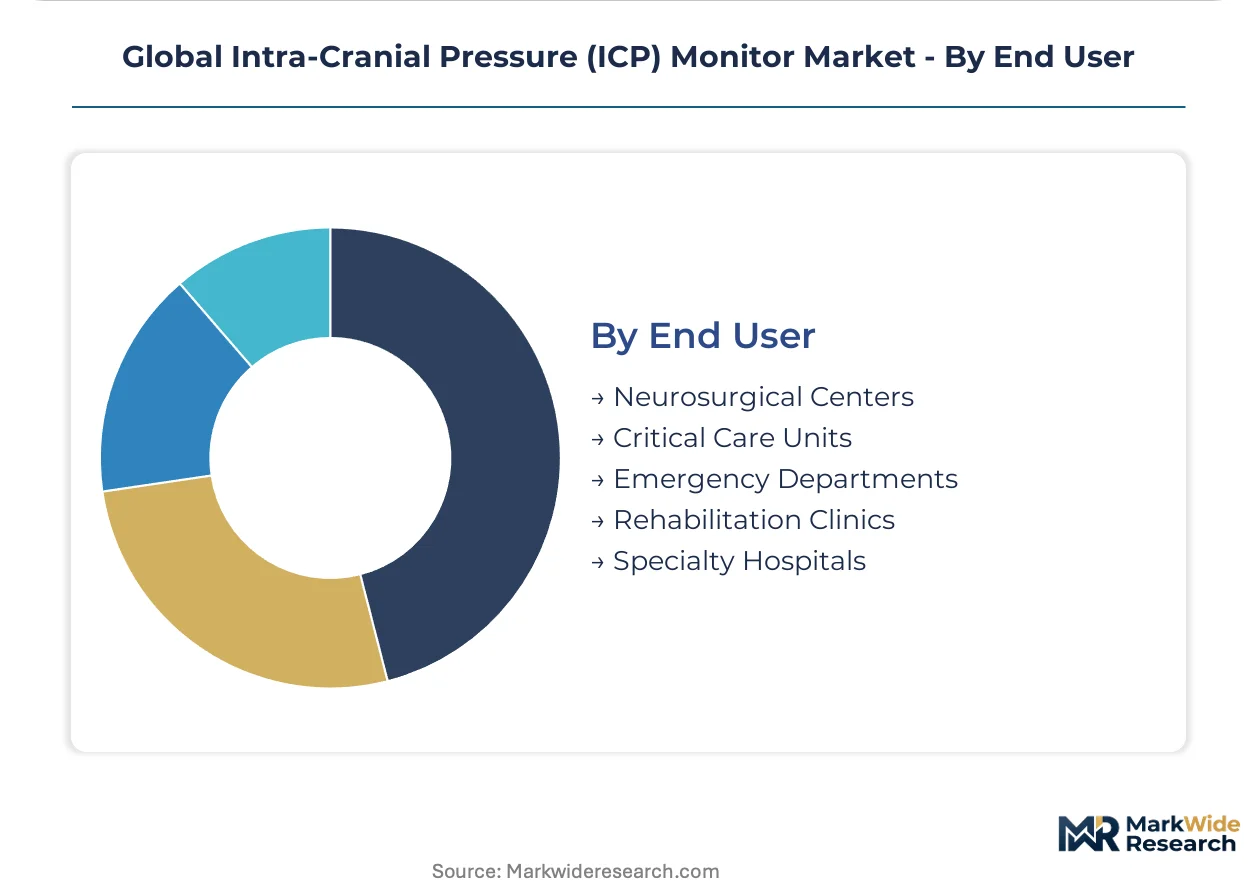
- Neurosurgical Centers:Dedicated cranial procedure facilities concentrate high-acuity cases and command premium technology procurement budgets. Tertiary referral networks in the United States and Germany consolidate demand at these specialized hubs.
- Critical Care Units:Neurointensive care environments require continuous waveform monitoring with EMR integration and automated alarm systems.
- Emergency Departments:Triage settings prioritize rapid deployment and non-invasive screening alternatives.
- Rehabilitation Clinics:Post-acute facilities seek portable monitoring for delayed complications.
- Specialty Hospitals:Cancer centers and pediatric institutions drive niche applications.
Neurosurgical centers capture premium tier; critical care units represent volume expansion opportunity through step-down protocol standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized neurosurgical zones in the United States, Germany, and Japan concentrate ICP monitor procurement through tertiary trauma networks. FDA premarket pathways and EU MDR Class III requirements shape regional access timelines. Academic medical centers in these markets anchor premium technology adoption.
United States
Level I trauma centers in California, Texas, and the Northeast corridor drive multi-day continuous monitoring demand for severe traumatic brain injury protocols. FDA 510(k) premarket notification pathways maintain streamlined access for fiberoptic and wireless systems relative to EU and Japanese regulators. Integrated delivery networks in Texas and California are consolidating neurosurgical device contracts under value-analysis frameworks.
Germany
Tertiary neurotrauma networks in Bavaria and North Rhine-Westphalia concentrate high-acuity cranial procedures requiring research-grade waveform precision. EU MDR Class III implantable device requirements extend clinical trial timelines, though notified bodies in Germany offer established conformity assessment pathways. Academic medical centers in Munich and Heidelberg pilot MEMS-based piezoresistive alternatives to fiberoptic transducers.
Japan
PMDA biocompatibility testing protocols enforce extended cytotoxicity and sensitization studies that delay registration cycles by 18-24 months versus FDA pathways. Kanto and Kansai regions host the densest concentrations of neurosurgical centers with wireless telemetry adoption priorities. Specialty optical fiber supply relationships with domestic glass manufacturers create input advantages for Japanese catheter producers.
India
Greenfield neurosurgery units in Delhi, Mumbai, and Bangalore seek cost-optimized ICP monitoring platforms as trauma center accreditation standards tighten. CDSCO medical device registration requirements are harmonizing with international standards, though state-level procurement fragmentation persists. Maharashtra and Karnataka host emerging critical care equipment distribution networks serving private hospital chains.
United Kingdom
NHS England reimbursement thresholds for invasive neuromonitoring determine hospital capital allocation priorities across neurosurgical centers in London and the Midlands. MHRA post-Brexit regulatory alignment with EU MDR maintains device approval pathway continuity. Academic medical centers in London and Manchester concentrate pediatric hydrocephalus monitoring demand.
Global Intra-Cranial Pressure (ICP) Monitor Market Competitive Landscape
Top-tier vendors anchor hospital supply contracts across North America and Western Europe, while mid-tier specialists compete through differentiated catheter technologies and regional service relationships. The vendor base clusters around three strategic archetypes: diversified medical technology conglomerates with broad neurosurgery portfolios, focused neuromonitoring specialists with premium positioning in critical care, and regional manufacturers leveraging direct academic medical center relationships. Dominant competitive moves include strategic partnerships for wireless telemetry integration and portfolio diversification into cranial access kits.
Among diversified medical technology conglomerates, Medtronic leverages its broad neurosurgery portfolio to anchor supply contracts, while Integra LifeSciences occupies a position exemplifying differentiated catheter technology focus. Sophysa represents the European manufacturing specialist archetype with direct service relationships. These three companies illustrate the competitive structure: scale-driven contract consolidation, technology-driven premium positioning, and region-focused manufacturing proximity.
| Leading Market Players |
|---|
| Medtronic |
| Integra LifeSciences |
| RAUMEDIC AG |
| Sophysa |
| Spiegelberg GmbH & Co. KG |
| Natus Medical |
| Codman Neuro |
| GE Healthcare |
| Philips Healthcare |
| Others |
Supply & Pricing Matrix
EU MDR post-market surveillance mandates for Class III implantable devices gate qualified supply access and sustain premium-tier pricing for catheter manufacturers with mature vigilance systems. Hospitals in Germany and France pay structural premiums for fiberoptic systems with full lifecycle traceability, while cost-optimized buyers in India source pneumatic alternatives with compressed documentation packages.
Pricing Analysis
Lead-time-driven pricing stratification rewards manufacturers with captive silica fiber supply and punishes spot-market dependent competitors. Three-tier pricing structure across premium fiberoptic, standard MEMS-based, and economy pneumatic levels separates academic medical centers from community hospitals from emerging market greenfield units. Price differentiation hinges on drift stability certification grade and bundled after-sales service contracts. Cost compression in the economy tier intensifies because Indian and Southeast Asian distributors consolidate procurement volumes under single-source agreements. Emergency departments exhibit highest price sensitivity; neurosurgical centers in Japan and Germany demonstrate lowest sensitivity due to research-grade waveform requirements.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German specialty optical fiber producers whose biocompatible glass formulations anchor fiberoptic catheter manufacturing. Raw material dependencies encompass high-purity silica fiber, MEMS-grade silicon wafers, and biocompatible catheter polymers. Manufacturing concentration in Germany, Japan, and the United States creates tariff exposure risk for cross-border component flows. Distribution runs through integrated delivery networks in Texas and California, regional distributors serving European academic clusters, and direct service relationships with Indian private hospital chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty optical fiber production capacity constraints prop pricing power for incumbent catheter manufacturers with backward-integrated supply or long-term offtake agreements. Qualified biocompatible glass supply scarcity sustains margin premiums across the analysis window.
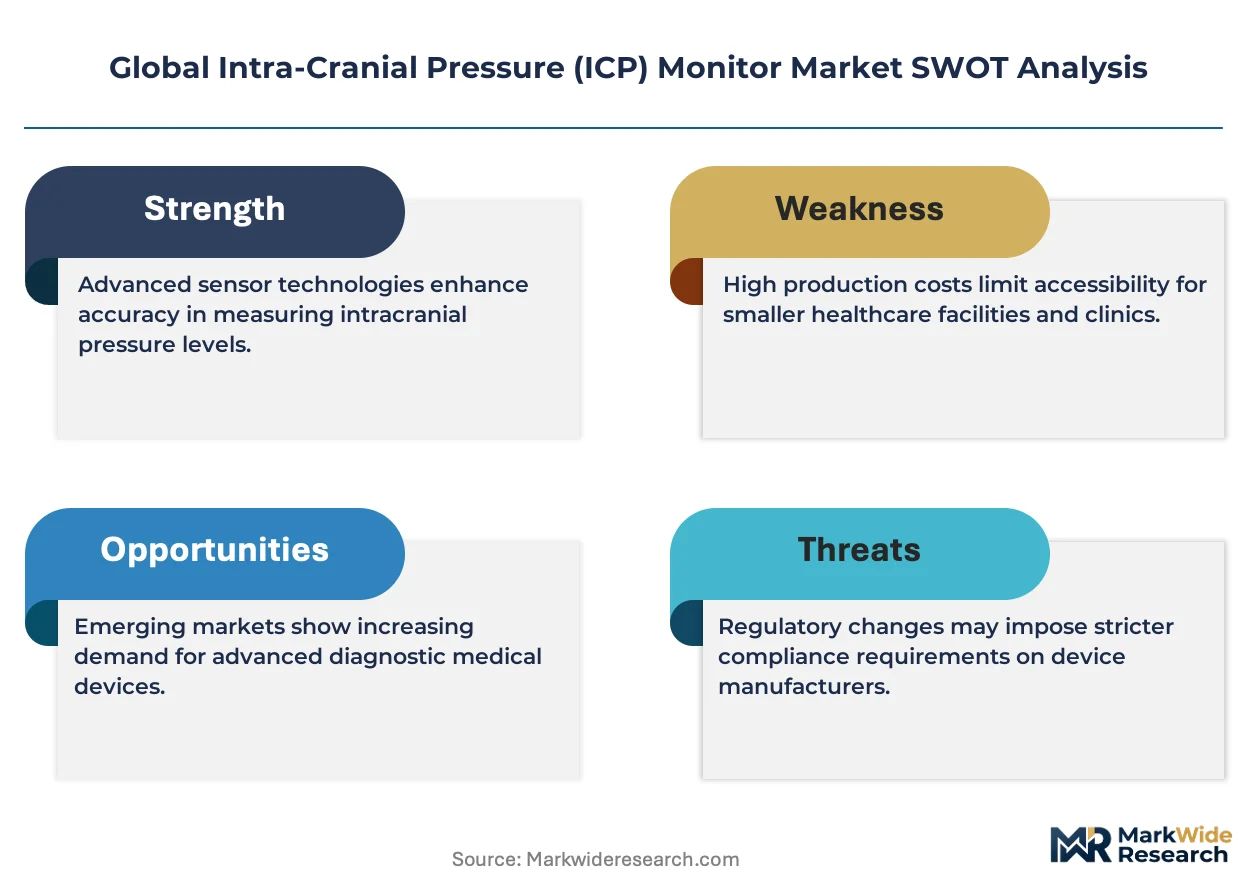
For Market Incumbents: Cement supply contract consolidation at integrated delivery networks in California and Texas before non-invasive ICP estimation technologies erode emergency department catheter volumes. Prioritize captive supply relationships with Japanese fiber producers or in-house silica drawing capability to defend input cost position against spot market volatility. For New Entrants and Emerging Players: Distributors serving India's greenfield neurosurgery units in Delhi and Bangalore offer the most penetrable channel for cost-optimized wireless telemetry platforms. Target trauma center accreditation mandates in Maharashtra and Karnataka as regulatory tailwinds. Pursue white-label manufacturing partnerships with established European component suppliers to bypass PMDA and FDA registration cycle disadvantages. For Investors and Strategic Acquirers: First wireless ICP monitor securing NHS England reimbursement approval is the leading indicator that home-based rehabilitation monitoring will shift from pilot to scalable revenue stream. Acquisition target archetype: mid-tier MEMS sensor specialists with automated temperature compensation IP and existing CE marking. Monitor EU MDR certificate of conformity issuance delays at French and Italian notified bodies as supply-constraint signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Wireless Telemetry | Streamlined premarket pathway accelerates US hospital system adoption versus EU MDR timelines. |
| CE Marking Pathway Under EU MDR | Class III implantable device certification enables German and French academic medical center procurement. |
| Hospital System Partnership | Integrated delivery network contracts in Texas consolidate vendor selection authority and displace surgeon preference items. |
| Software Companion Development | Machine learning waveform analytics create differentiated revenue streams beyond hardware sales. |
| Reimbursement Strategy | NHS England and Japan MHLW fee schedule alignment determines capital allocation at tertiary neurotrauma networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with neurosurgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers validated demand-side assumptions. FDA 510(k) clearances, EU MDR technical documentation, PMDA approval summaries, and hospital procurement databases supplied secondary validation. Bottom-up catheter shipment estimates and top-down neurosurgical procedure volumes were triangulated to reconcile market size outputs.
Data-stream reconciliation across product type, technology architecture, application pathology, and end-user facility tier enabled segmentation-level forecasting. Traumatic brain injury protocol guidelines, hydrocephalus shunt replacement rates, and pediatric specialty center expansion trajectories informed volume projections. CAGRs were derived from fitted growth curves calibrated to historical regulatory approval lags and reimbursement timeline patterns. Wireless telemetry adoption curves and MEMS sensor penetration rates supplied industry-specific forecast inputs across the projection horizon.
Caveats apply where PMDA biocompatibility testing protocol revisions or EU MDR notified body capacity constraints could materially shift the outlook. Forecasts reflect assumptions regarding sustained silica fiber supply stability and continued Level I trauma center consolidation in the United States. Deviation in wireless ICP monitor reimbursement approval timelines at NHS England or Japan's MHLW would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Digital Phoropter Market
Medical Devices
Transcranial Doppler Ultrasounds System Market
Medical Devices
Canada Minimally Invasive Surgery Devices Market
Medical Devices
Global Active Implantable Medical Devices Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Electroencephalogram (EEG) Caps Market
Medical Devices
Global Holter ECG Market
Medical Devices
Global Robotic Wheelchairs Market
Medical Devices
Nephrostomy Catheters Market
Medical Devices
US External Counterpulsation Devices Market
Medical Devices
Below-The-Knee Implants Market
Medical Devices
Spain Contraceptive Devices Market
Medical Devices
Ligament Stabilizers Market
Medical Devices
Electrical Stimulation Devices (Esds) Market
Medical Devices
Cannula Market
Medical Devices
Intravenous Transportation System Market