
 Russia Automotive Composites Market | 2026-2036
Russia Automotive Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Automotive Composites Market Analytics
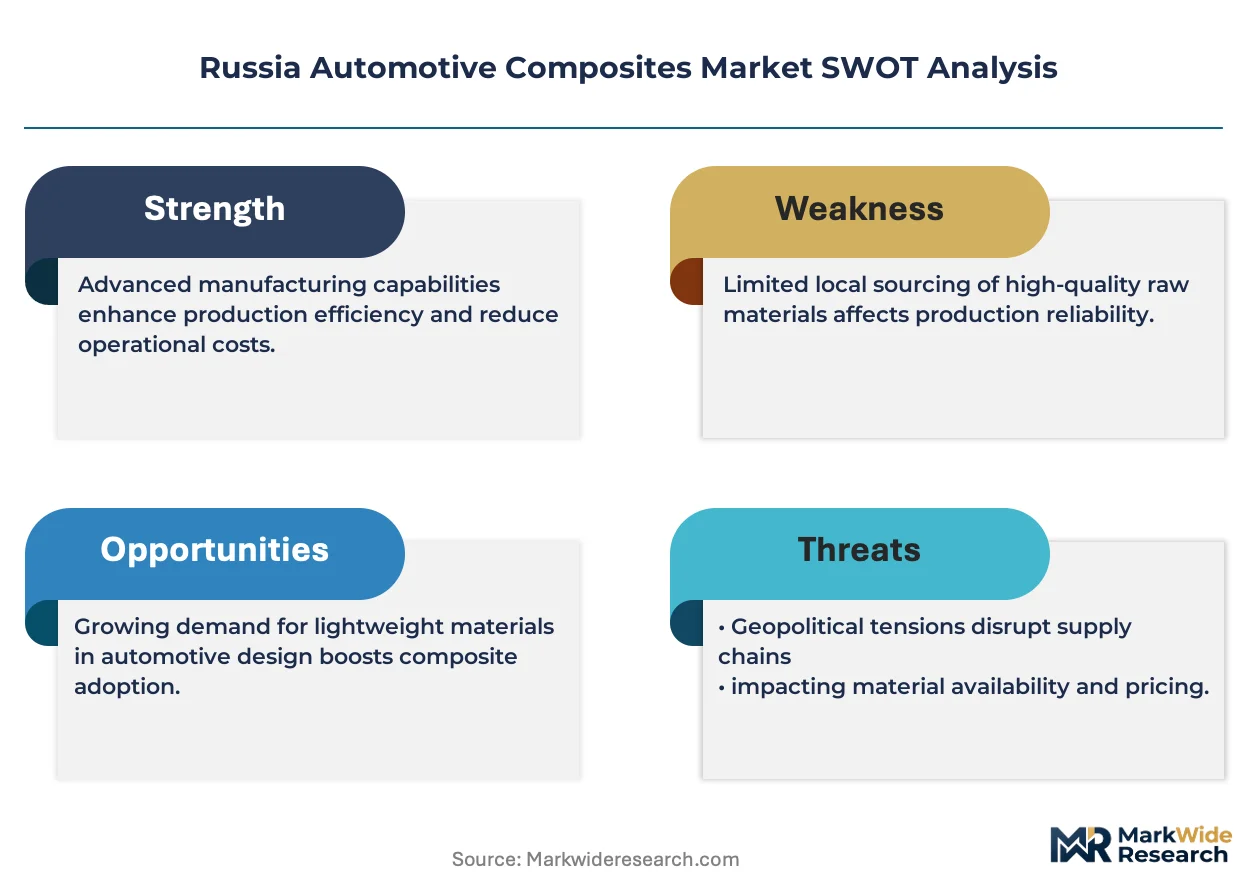
Multi-source procurement from European and Asian resin suppliers is hardening as Russian converters adapt to trade flow disruptions. BASF Group leverages its polymer compounding heritage to sustain thermoplastic composite supply lines into the market. Teijin Group anchors carbon fiber prepreg availability through specialized distribution arrangements. Base Group competes on localized glass fiber processing capacity serving domestic tier-1 suppliers.
Automotive composites are engineered material systems combining reinforcing fibers with polymer matrices to achieve strength-to-weight ratios exceeding conventional metals, typically manufactured through resin transfer molding or automated fiber placement to produce parts with specific stiffness targets measured in gigapascals. Their primary purpose is mass reduction in vehicle platforms where every kilogram eliminated improves fuel efficiency and payload capacity. Glass fiber formulations occupy the volume tier due to cost accessibility for interior components and non-structural body panels, while carbon fiber concentrates in premium structural parts where performance thresholds justify material expense. Thermoplastic processing stages are gaining traction against thermoset alternatives because cycle times compress and recyclability aligns with emerging producer responsibility frameworks.
Russia's national technical regulation authority enforces EAEU vehicle safety and environmental standards that prescribe material flammability and emissions thresholds, directly shaping composite formulation choices and supplier qualification pathways. The country's standardization body maintains GOST-R certification requirements for automotive materials that foreign producers must navigate for market access, creating compliance barriers that favor established players with local testing relationships. Stakeholders must monitor how evolving EAEU harmonization with UN vehicle regulations reshapes material approval timelines and whether domestic substitution programs redirect procurement toward locally certified fiber and resin sources.
Market Dynamics
Domestic lightweighting mandates from Russia's Ministry of Industry and Trade are forcing passenger vehicle OEMs to substitute aluminum and steel with fiber-reinforced polymers in structural applications, compressing material certification timelines and reshaping supplier qualification pathways across the Moscow-Tatarstan corridor.
Growth Catalysts
- EAEU Technical Regulations:Harmonized vehicle safety standards are mandating mass reduction targets that directly specify composite material adoption thresholds for structural components.
- Kaluga Assembly Zone:Concentrated vehicle production in this industrial cluster is generating localized demand for just-in-time composite part delivery from tier-1 processors.
- Thermoplastic Processing:Faster cycle times and recyclability alignment with emerging producer responsibility frameworks are pulling converters away from thermoset alternatives.
Market Restraints
- Import Dependency:Carbon fiber prepreg supply concentrates among Asian and European producers, exposing Russian converters to trade flow disruptions and currency volatility.
- GOST-R Certification:Foreign material suppliers face extended testing protocols at Russian accreditation bodies, creating qualification backlogs that favor incumbent domestic processors.
- High-Performance Resin Costs:Epoxy and thermoplastic matrix prices fluctuate with petrochemical feedstock indices, compressing margins for tier-2 component fabricators.
Strategic Opportunities
- St. Petersburg Supplier Cluster:Underdeveloped carbon fiber recycling infrastructure presents white space for closed-loop material recovery services serving the region's glass fiber processors.
- Electric Vehicle Platforms:Battery enclosure and thermal management applications are opening new specification pathways for flame-retardant composite formulations.
- Domestic Substitution Programs:Import substitution directives are redirecting state procurement toward locally certified fiber and resin sources, creating preferential market access.
Industry Challenges
- Automated Fiber Placement Expertise:Shortages of technicians trained in AFP programming and tape laying operations are constraining production scale-up at tier-1 converters.
- Multi-Material Joining:Dissimilar material interfaces between composites and legacy steel subframes require new adhesive and mechanical fastening protocols that lack standardized test methods.
- Supply Chain Reconfiguration:Redirecting resin procurement from European to Asian suppliers demands reformulation validation cycles that extend product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Automotive Composites Market |
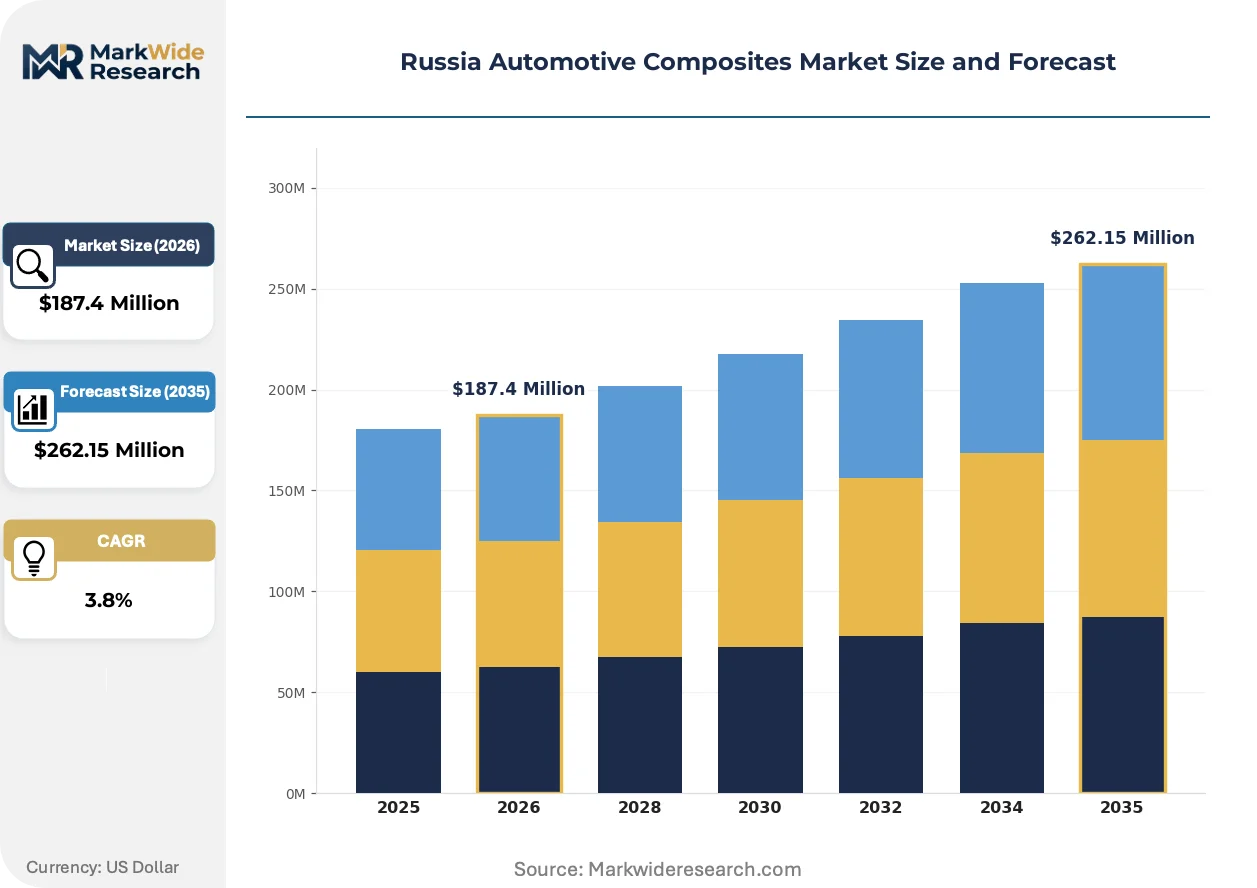
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber, Glass Fiber, Natural Fiber, Hybrid Composites Application: Body Panels, Interior Components, Structural Parts, Engine Covers Manufacturing Stage: Prepreg, Thermoset, Thermoplastic, Infusion End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Teijin Group, Base Group, BASF Group, Cytec Industries, Far-UK, Gurit, 3B-Fiberglass, Delphi Technologies, NSG Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Automotive Composites Market Evolving Landscape
Thermoplastic composite systems are displacing thermoset dominance in Russian automotive applications, while regulatory pressure on recyclability and evolving OEM procurement models are compressing traditional supply relationships. Three developments are restructuring competitive positioning.
Continuous fiber-reinforced thermoplastic (CFRTP) tapes are integrating into structural automotive components through automated fiber placement and compression molding hybrid processes. AvtoVAZ and GAZ Group are piloting CFRTP door modules and underbody shields to achieve 40-50% mass reduction versus stamped steel. This technology is integrating recycled carbon fiber feedstocks from aerospace scrap streams, collapsing raw material cost premiums and enabling circular economy claims for export-bound vehicle platforms.
EAEU Technical Regulation 018/2011 on vehicle safety is tightening flammability and emissions thresholds for interior materials, directly constraining composite formulation choices. The regulation's 2024 amendments introduced stricter volatile organic compound limits that disqualify certain epoxy-based laminates from cabin applications. Russian OEMs are responding by accelerating thermoplastic polyurethane and polypropylene matrix qualifications with domestic compounders to maintain GOST-R compliance without supply interruption.
OEM technical teams are consolidating supplier panels around full-service material-system providers capable of design, simulation, and recycling take-back. This behavior compresses the traditional tier-1/tier-2 pyramid into direct converter-OEM relationships, marginalizing pure fabrication houses. The shift is most visible in the Moscow-Tatarstan corridor, where Kamaz and UAZ have reduced qualified composite suppliers from twelve to four partners offering integrated lifecycle services.
Russia Automotive Composites Market Segmentation
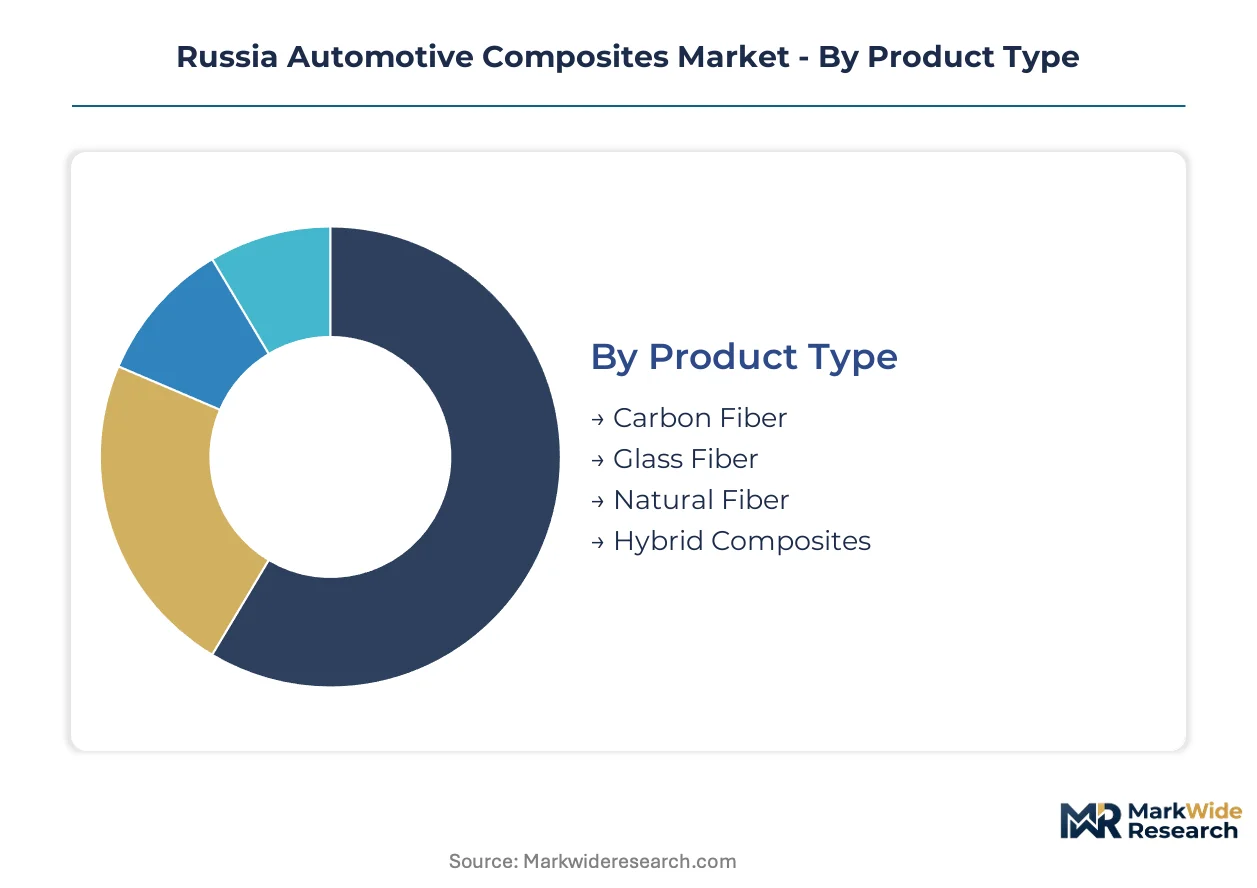
Segmentation reveals how material specifications, manufacturing capabilities, and customer procurement power stratify Russia's automotive composites landscape. Each axis exposes distinct margin structures and qualification barriers that shape competitive positioning.
Product Type:
Reinforcement fiber selection dictates performance thresholds and cost baselines across Russian vehicle platforms.
- Carbon Fiber:High-modulus PAN-based and pitch-based fibers deliver tensile strength exceeding 3,500 MPa for structural load-bearing applications. Demand concentrates around Kamaz heavy-duty truck frames and premium passenger vehicle platforms in the Moscow-Tatarstan corridor, where mass reduction mandates justify material premiums against aluminum alternatives.
- Glass Fiber:E-glass and S-glass rovings dominate volume consumption through chopped strand mat and woven fabric formats. Kaluga assembly zone OEMs specify glass-reinforced polypropylene for non-structural body panels and interior substrates, leveraging established supply relationships with St. Petersburg compounders to compress logistics costs.
- Natural Fiber:Flax and hemp fiber reinforcements serve interior trim applications with lower mechanical requirements. AvtoVAZ sources these from domestic agricultural processors for door panel substrates under import substitution programs.
- Hybrid Composites:Glass-carbon blends balance cost and performance in semi-structural applications. Tier-1 suppliers in Tatarstan deploy these for battery enclosure prototypes on emerging electric vehicle platforms.
Mature deployment sits with Glass Fiber. Newer deployment is concentrated in Hybrid Composites.
Application:
Component function determines material specification rigor and OEM direct engagement intensity.
- Body Panels:Hoods, fenders, and roof modules require Class A surface finish compatibility and impact resistance validation. GAZ Group qualifies thermoplastic composites for UAZ Hunter replacement panels at its Nizhny Novgorod facilities, targeting 30% mass reduction versus steel stampings.
- Interior Components:Dashboard carriers, door modules, and seat structures prioritize flammability compliance under EAEU Technical Regulation 018/2011. Moscow-based OEMs accelerate thermoplastic polyurethane qualifications to meet tightened volatile organic compound limits.
- Structural Parts:Floor pans, cross-members, and crash structures demand stiffness-to-weight optimization. These applications face the steepest GOST-R certification timelines due to safety-critical classification.
- Engine Covers:Thermal management and acoustic insulation drive specification. Camouflaged military vehicle variants from Ural Automotive Plant specify these for infrared signature reduction.
Volume concentration rests with Interior Components. Specification intensity peaks at Structural Parts.
Manufacturing Stage:
Process technology selection shapes cycle economics and recyclability positioning against regulatory pressure.
- Thermoplastic:Polypropylene and polyamide matrix systems enable sub-60-second cycle times and end-of-life recyclability. Kaluga OEMs favor these for high-volume interior production, aligning with emerging producer responsibility frameworks.
- Thermoset:Epoxy and polyester resin systems retain dominance in structural applications requiring elevated temperature resistance. Extended cure cycles constrain throughput at tier-2 fabricators serving the aftermarket channel.
- Prepreg:Resin-impregnated fiber sheets support automated fiber placement for complex geometries. Aerospace scrap feedstock integration is collapsing raw material premiums for carbon fiber variants.
- Infusion:Vacuum-assisted resin transfer molding serves low-to-medium volume body panel production. St. Petersburg processors deploy these for bus and specialty vehicle manufacturers with irregular demand patterns.
Process transition is accelerating toward Thermoplastic. Infusion retains niche positioning in specialty vehicle supply.
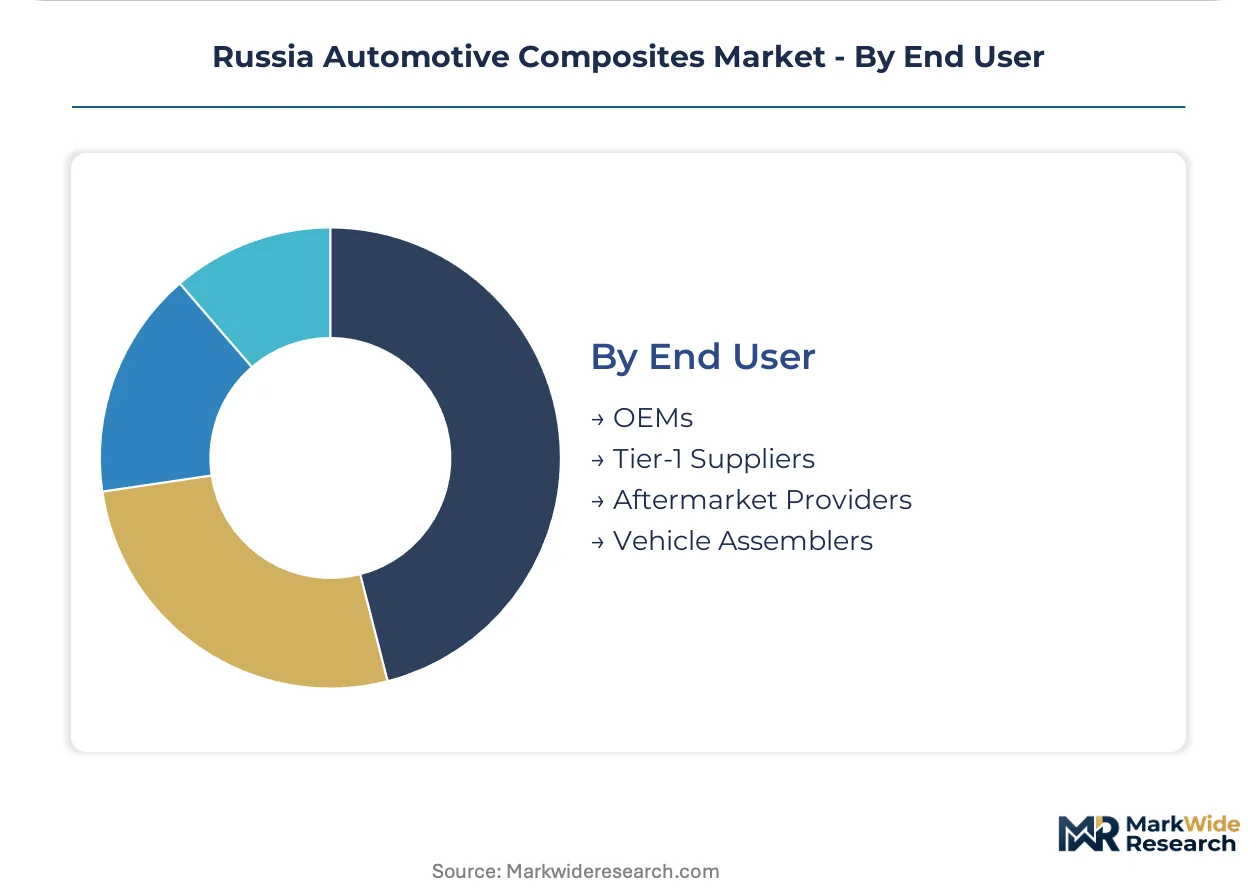
End User:
Customer scale and integration depth fragment procurement behavior across the value chain.
- OEMs:AvtoVAZ, GAZ Group, and Kamaz maintain direct material qualifications and design authority. These entities are consolidating supplier panels around full-service providers capable of simulation, testing, and recycling take-back.
- Tier-1 Suppliers:Component integrators like Base Group manage converter relationships and just-in-time logistics. Their procurement power is hardening as OEMs push material cost accountability downstream.
- Aftermarket Providers:Independent repair and customization shops source through distributor networks with limited specification control. Currency volatility disrupts their resin procurement planning.
- Vehicle Assemblers:Contract manufacturers for foreign brands in special economic zones operate under distinct material approval pathways. Their supply relationships remain tethered to parent company global specifications.
Specification authority centralizes with OEMs. Operational flexibility concentrates at Tier-1 Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Passenger vehicle OEMs in the Moscow-Tatarstan corridor concentrate composite demand for structural lightweighting, while St. Petersburg and Kaluga anchor supplier infrastructure. Domestic substitution programs and EAEU technical regulations reshape procurement geography across Russian industrial zones.
Central Russia
AvtoVAZ and GAZ Group operations in Togliatti and Nizhny Novgorod drive thermoplastic composite qualifications for door modules and underbody shields. The Ministry of Industry and Trade enforces lightweighting mandates that specify mass reduction targets for structural components. Moscow-based engineering centers coordinate material testing protocols with EAEU harmonization requirements.
Volga Region
Kamaz heavy-duty truck manufacturing in Naberezhnye Chelny consumes high-modulus carbon fiber for frame applications. EAEU Technical Regulation 018/2011 prescribes flammability thresholds that constrain interior material selection. Tatarstan's tier-1 supplier cluster processes hybrid glass-carbon blends for emerging electric vehicle battery enclosures.
Northwestern Russia
St. Petersburg compounders supply glass-reinforced polypropylene to Kaluga assembly zone OEMs under just-in-time logistics contracts. GOST-R certification requirements at Russian accreditation bodies create qualification backlogs for foreign resin suppliers. The city's supplier cluster lacks closed-loop carbon fiber recovery infrastructure despite processing volume concentration.
Kaluga Oblast
Vehicle assemblers in this special economic zone operate under distinct material approval pathways tethered to parent company global specifications. Domestic substitution directives redirect state procurement toward locally certified fiber sources. Regional converters face currency volatility exposure on imported carbon fiber prepreg shipments.
Ural Region
Ural Automotive Plant specifies composite engine covers for infrared signature reduction in camouflaged military variants. The region's distance from resin supply corridors elevates logistics costs for tier-2 fabricators. Local processors rely on vacuum-assisted resin transfer molding for irregular-demand specialty vehicle production.
Russia Automotive Composites Market Competitive Landscape
Supplier panel consolidation dominates the current landscape as OEM technical teams compress traditional tier-1/tier-2 hierarchies into direct converter relationships. The market structure stratifies around full-service material-system providers, pure fabrication houses, and resin compounders with localized processing capacity. Three archetypes occupy distinct positions: integrated lifecycle service providers, regional glass fiber processors, and specialized carbon fiber distributors. Technology licensing and backward integration into polymer compounding represent the dominant competitive moves.
Among Asian and European material suppliers, Teijin Group and BASF Group exemplify the integrated service archetype through specialized distribution arrangements and polymer compounding heritage respectively. Base Group occupies a position within the regional processor tier, anchoring localized glass fiber capacity serving domestic tier-1 suppliers. These three entities represent contrasting strategic postures: global material science depth, supply line continuity, and domestic processing scale.
| Leading Market Players |
|---|
| Teijin Group |
| Base Group |
| BASF Group |
| Cytec Industries |
| Far-UK |
| Gurit |
| 3B-Fiberglass |
| Delphi Technologies |
| NSG Group |
| Others |
Value Network & Pricing Analysis
Carbon fiber prepreg landed costs from Asian and European producers cascade through three distinct pricing tiers before reaching Russian tier-1 converters, with currency hedging premiums and GOST-R certification fees accumulating at each handoff to create spreads between spot procurement and long-term contract rates.
Pricing Analysis
Volume concentration in glass-reinforced polypropylene separates from margin capture in carbon fiber structural laminates. Price differentiation rests on GOST-R certification tier and thermoplastic processing capability, with qualified domestic compounders commanding premiums over import-reliant competitors. Pricing pressure stems from petrochemical feedstock index volatility compressing epoxy matrix margins. Aftermarket providers exhibit highest price sensitivity due to currency exposure on spot resin purchases, while OEMs with consolidated supplier panels absorb cost fluctuations through annual contract renegotiations.
Supply Chain Analysis
Workforce availability constraints in Tatarstan and St. Petersburg processing clusters are elevating labor premiums for automated fiber placement technicians. Supply concentrates in Germany, China, and South Korea for carbon fiber feedstocks, while domestic glass fiber roving production anchors in St. Petersburg. Raw material dependencies span PAN precursor, epoxy resins, and thermoplastic polypropylene compounds. Single-source vulnerability on aerospace-grade carbon fiber prepreg exposes converters to trade flow disruptions. Distribution runs through tier-1 integrators with just-in-time contracts to Kaluga and Moscow-Tatarstan assembly zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EAEU Technical Regulation 018/2011 constructs a cost-of-compliance moat that rewards players with established GOST-R certification relationships and penalizes speculative entrants lacking local testing infrastructure.
For Market Incumbents: To counter supplier panel consolidation by AvtoVAZ and Kamaz, deepen backward integration into polymer compounding capacity in the St. Petersburg cluster and secure captive resin supply lines insulated from currency volatility. Prioritize thermoplastic recycling infrastructure investment to meet emerging producer responsibility frameworks and defend qualification status with OEMs consolidating around lifecycle service providers. For New Entrants and Emerging Players: Capture underdeveloped carbon fiber recycling white space in the St. Petersburg supplier cluster, where closed-loop material recovery services remain absent despite processing volume concentration. Target electric vehicle battery enclosure applications in Tatarstan, where hybrid glass-carbon specifications are proliferating without entrenched incumbent relationships. Lead with GOST-R certification sponsorship programs to compress qualification timelines against established players. For Investors and Strategic Acquirers: OEM technical team consolidation from twelve to four qualified composite suppliers is the leading indicator that full-service material-system providers will command scarcity premiums over pure fabrication houses. Position acquisition screening around domestic processors with thermoplastic compounding heritage and existing EAEU regulatory relationships. Monitor Kaluga assembly zone electric vehicle platform ramp rates as the inflection signal for structural composite demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive resin supply secures margin insulation from petrochemical index volatility and trade disruption. |
| GOST-R Certification Sponsorship Programs | Accelerated qualification pathways compress market entry timelines for foreign material suppliers. |
| Thermoplastic Recycling Infrastructure Buildout | Closed-loop recovery capabilities align with EAEU producer responsibility frameworks and OEM sustainability mandates. |
| Automated Fiber Placement Technician Training | Workforce pipeline development alleviates production scale-up constraints at tier-1 converters. |
| Electric Vehicle Battery Enclosure Qualification | Flame-retardant composite specifications for thermal management open new OEM direct engagement pathways. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured primary interviews with tier-1 supplier procurement directors, OEM platform engineers, thermoplastic compounding plant managers, and EAEU certification body technical leads. Bottom-up vehicle production forecasts triangulated against top-down composite content-per-vehicle estimates derived from Ministry of Industry and Trade lightweighting mandate compliance documentation.
Data-stream reconciliation across vehicle registration databases, resin import manifests, and tier-1 supplier capacity announcements generated volume and value outputs across the projection horizon. Segmentation modeling incorporated reinforcement fiber type, manufacturing process technology, application function, and end-user procurement tier. CAGRs were derived from regression analysis against historical substitution rates of aluminum and steel in structural applications, with sensitivity testing on EAEU regulatory amendment timelines and domestic substitution program funding levels.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EAEU-UN regulation harmonization pace and carbon fiber prepreg trade corridor stability. Forecasts reflect documented assumptions regarding OEM platform electrification roadmaps and state procurement directive enforcement intensity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Bicycle Front Hub Market
Vehicle Components
Asia-Pacific Industrial Brakes Market
Vehicle Components
Freight Railcar Parts Market
Vehicle Components
Trailer Spindles Market
Vehicle Components
Bicycle Chain Tensioner Market
Vehicle Components
Global Air Spring Components Market
Vehicle Components
Digital Tire Inflator Market
Vehicle Components
Trailer Surge Brake Market
Vehicle Components
Motor Monitoring Market
Vehicle Components
Global Automotive Steering Torque Sensor Market
Vehicle Components
Cylindrical Roller Bearings Market
Vehicle Components
EV Connectors Market
Vehicle Components
Mobility Aids and Transportation Equipment Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Refrigerated Trailer Hinges Market
Vehicle Components
Automotive Sensors Market