
 Bicycle Frames Market | 2026-2036
Bicycle Frames Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Frames Market Intelligence
Advanced proficiency in carbon fiber composite engineering and automated layup processes is rotating the competitive landscape away from traditional metalworking skills. This shift favors manufacturers with deep material science capabilities. Giant Manufacturing Co. Ltd. leverages its extensive manufacturing scale in Taiwan to control production costs across multiple material types. Trek Bicycle Corporation differentiates through its proprietary OCLV Carbon technology and strong dealer network in the United States. Meanwhile, Specialized Bicycle Components competes on high-performance designs targeting the professional cyclist segment.
A bicycle frame is the main structural component of a bicycle, serving as the chassis to which all other parts are attached. Its design dictates the vehicle's handling characteristics, with materials selected based on desired stiffness-to-weight ratios and vibration damping properties. Carbon fiber frames command the high-margin professional and enthusiast road segments, prized for their low weight. In contrast, aluminum and steel materials continue to dominate the high-volume mountain and hybrid frame types due to their durability and lower production costs.
Product safety and performance are governed by international standards like ISO 4210, which specifies safety requirements for bicycles. Manufacturers must also comply with regional regulations such as the EU's General Product Safety Regulation and specific mandates from the U.S. Consumer Product Safety Commission (CPSC). These frameworks ensure structural integrity and rider safety. Future market positioning will hinge on a manufacturer's ability to navigate raw material price volatility while investing in sustainable production processes.
Market Dynamics
The primary structural force is the pivot from traditional metal fabrication towards advanced material science. Expertise in automated carbon fiber layup and composite engineering is now the central axis of competition, displacing legacy metalworking skills across high-margin segments.
Growth Catalysts
- Pro-Cycling Policies:Government incentives and dedicated cycling infrastructure in European nations like Germany and the Netherlands stimulate demand for commuter and urban bicycles.
- Urban Commuter Demand:A shift toward sustainable urban transport solutions is driving consistent demand from commuters for lightweight and durable frame designs.
- Automated Layup Technology:Innovations in automated carbon fiber layup are reducing manufacturing costs, making high-performance frames accessible to a wider enthusiast segment.
Market Restraints
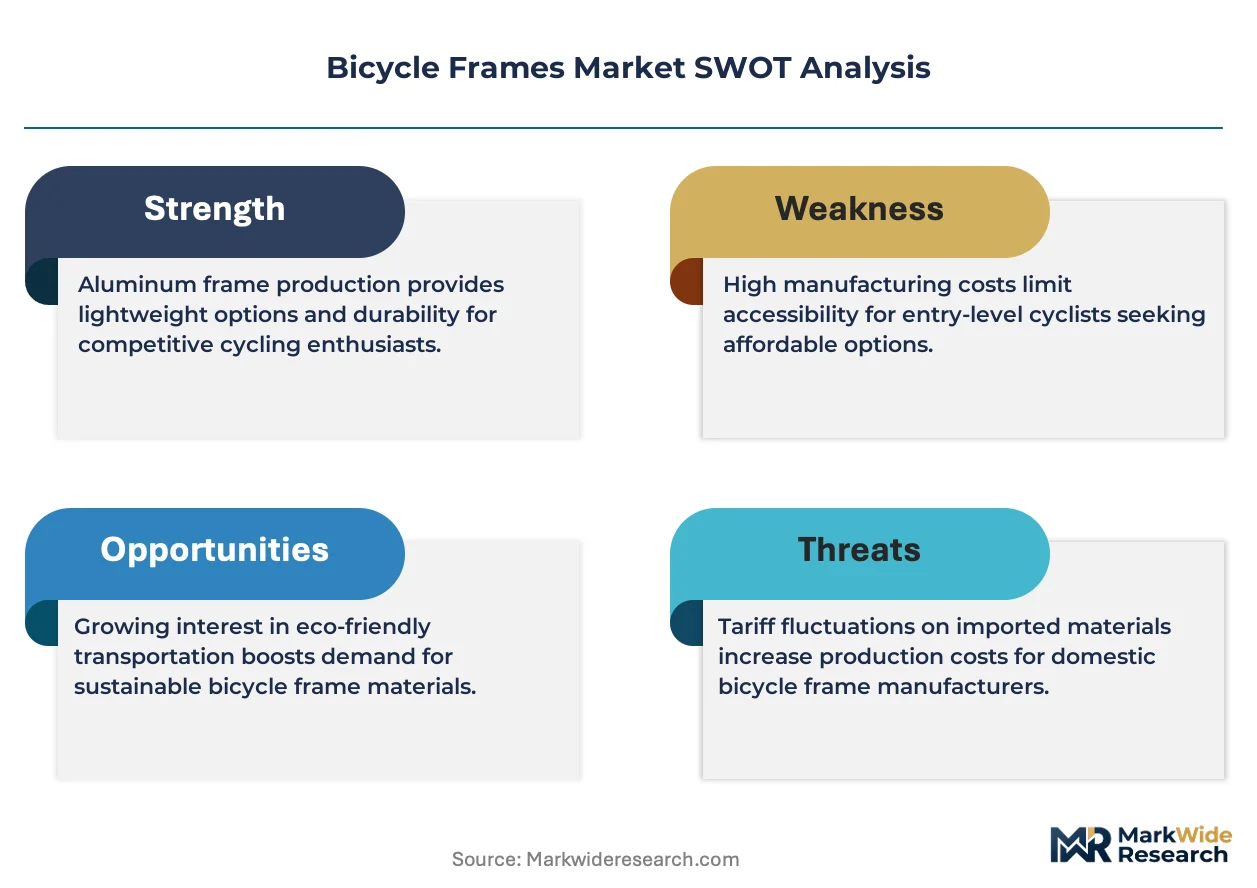
- Input Cost Volatility:Price fluctuations for carbon fiber and aluminum alloys directly compress manufacturer margins and complicate production planning.
- Geographic Production Risk:Heavy reliance on manufacturing hubs in Taiwan and China exposes the supply chain to geopolitical tensions and logistical disruptions.
- Fragmented Safety Standards:Navigating disparate safety regulations, from ISO 4210 to CPSC rules, increases compliance costs and delays market entry.
Strategic Opportunities
- E-Bike Frame Platforms:E-bike growth in North America creates demand for new frame platforms engineered to manage motor torque and battery integration.
- Urban Logistics Segment:A commercial market is emerging for specialized, durable frames designed for cargo bikes in last-mile delivery fleets.
- Integrated Smart Frames:Embedding sensors for performance and safety data directly into carbon frames opens a new high-margin product category for connected bicycles.
Industry Challenges
- Composite Engineering Talent Gap:A scarcity of engineers and technicians with expertise in advanced composites and automated layup machinery constrains production scaling for high-end frames.
- High Capital Expenditure:The significant upfront investment required for automated fiber placement machines and high-pressure molding equipment creates a high barrier to entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bicycle Frames Market |
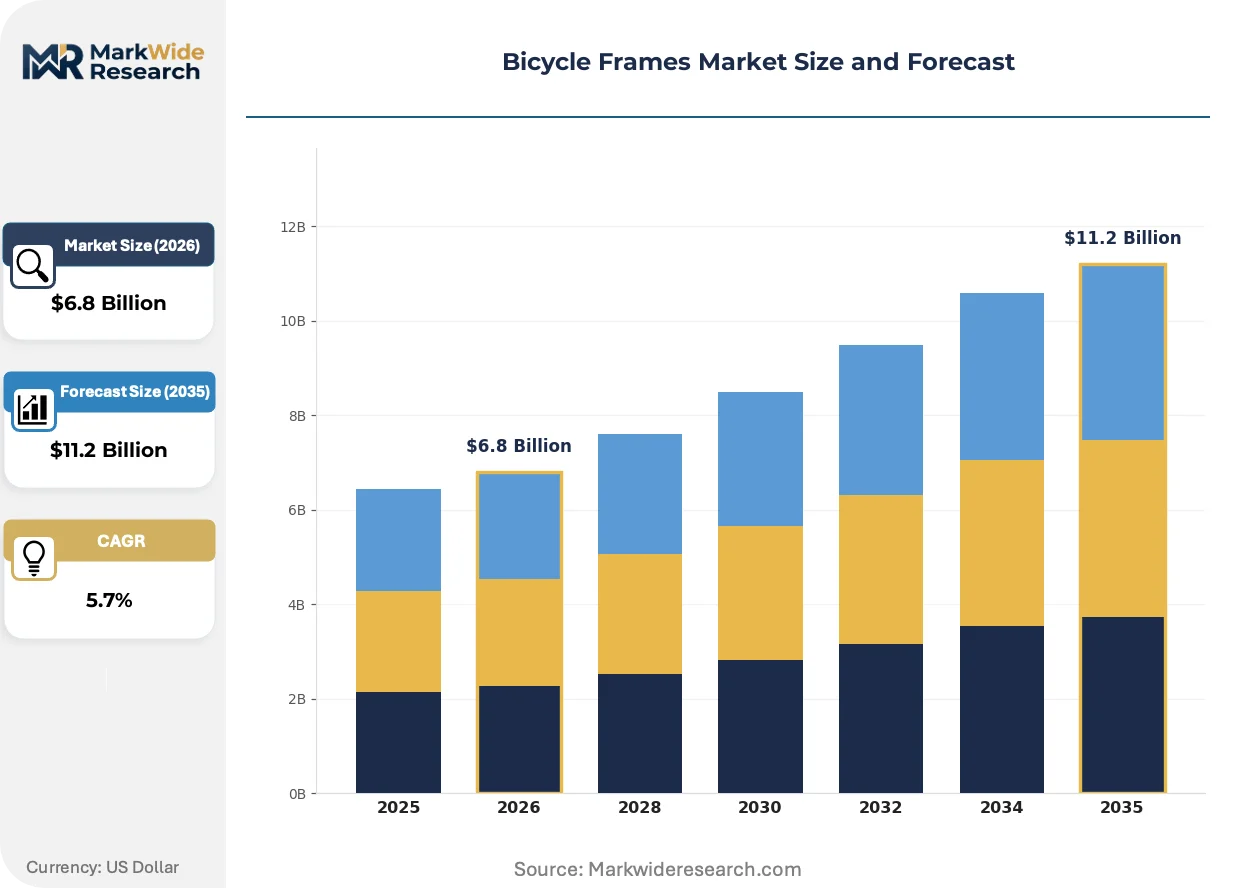
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Aluminum, Carbon Fiber, Steel, Titanium, Bamboo Frame Type: Mountain, Road, Hybrid, Cruiser, Folding End User: Professional Cyclists, Recreational Riders, Commuters, Delivery Personnel Distribution Channel: Specialty Stores, Online Retailers, Sports Outlets, Department Stores |
| Companies Covered | Scott Sports SA, Merida Industry Co. Ltd., Giant Manufacturing Co. Ltd., Cervelo Cycles, Bianchi, Trek Bicycle Corporation, Cannondale Bicycle Corporation, Santa Cruz Bicycles, Specialized Bicycle Components, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Frames Market Strategic Shifts & Innovations
Material science advancements and manufacturing automation are altering frame design possibilities and production economics. This evolution enables lighter, more complex geometries while shifting competitive advantage from traditional metalworking toward composite engineering expertise.
Additive manufacturing, using processes like selective laser melting for titanium, allows for rapid prototyping and complex, bespoke geometries. High-performance and custom frame builders are adopting this for creating unique lugs and dropouts. This capability for on-demand customization is fragmenting the premium market, creating a new tier of hyper-personalized bicycles apart from mass-produced models.
The European Union's Corporate Sustainability Reporting Directive (CSRD) imposes mandatory disclosure on supply chain environmental impacts. This forces manufacturers to quantify and report the carbon footprint of materials like aluminum and carbon fiber. Consequently, frame producers are prioritizing suppliers with certified low-carbon processes and investing in life-cycle assessment capabilities to ensure compliance and maintain European market access.
A notable shift in acquisition patterns involves corporate and municipal clients favoring leasing or subscription services over outright fleet purchases. This model challenges the traditional dealer sales channel, creating an opening for manufacturers offering integrated fleet management and maintenance. The trend is most pronounced in European cities with mature bike-share programs and corporate mobility incentives.
Bicycle Frames Market Segmentation
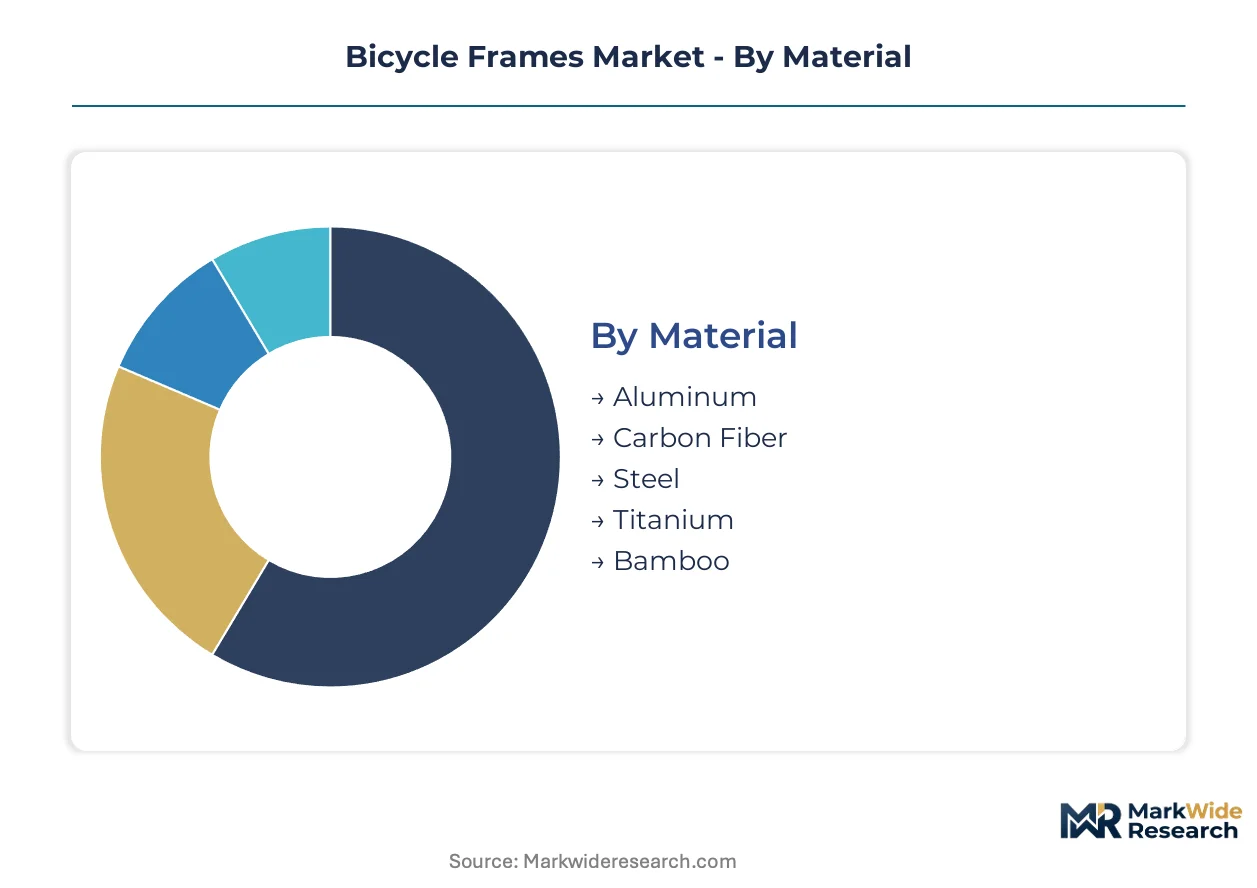
The bicycle frames market is highly stratified, reflecting diverse material science, manufacturing processes, and end-user requirements. Understanding these distinct segments allows manufacturers to tailor product development, optimize material selection, and target specific consumer groups effectively. Each category delineates unique competitive dynamics and growth trajectories within the broader industry.
Material:
Margin pools within the material segment are heavily concentrated in advanced composites, reflecting the premium pricing associated with performance and lightweight characteristics.
- Carbon Fiber:These frames utilize advanced composite layups, often incorporating aerospace-grade fibers for optimal stiffness-to-weight ratios and vibration damping. Demand is concentrating in high-performance road and gravel segments, driven by professional racing and enthusiast pursuit of speed and comfort.
- Aluminum:Fabricated from various aluminum alloys, these frames offer a balance of light weight, durability, and cost-effectiveness through hydroforming and welding techniques. Demand remains robust in the high-volume mountain and hybrid bicycle categories, supported by their resilience for everyday use and lower production costs.
- Steel:Known for its strength, durability, and vibration-damping properties, steel frames are often favored for touring, commuting, and custom builds.
- Titanium:Prized for its exceptional strength-to-weight ratio, corrosion resistance, and unique ride quality, titanium frames cater to a niche premium market.
- Bamboo:An eco-friendly and sustainable option, bamboo frames offer natural vibration damping and a distinctive aesthetic for specialized markets.
Aluminum holds installed capacity. Carbon Fiber is rotating up the share rankings.
Frame Type:
The cost tier for bicycle frames varies significantly by type, with specialized performance designs commanding higher price points due to advanced engineering and material inputs.
- Road:Characterized by lightweight construction, aerodynamic profiles, and stiff geometries, these frames are engineered for speed and efficiency on paved surfaces. Demand for road frames is strong among competitive cyclists and endurance enthusiasts across European nations, particularly Germany and the Netherlands, where cycling infrastructure is highly developed.
- Mountain:Built for rugged terrain, mountain bike frames feature robust construction, suspension compatibility, and geometries optimized for stability and control. This segment sees consistent demand from recreational riders and adventure sports participants, benefiting from the durability required for off-road conditions.
- Hybrid:Combining features of road and mountain bikes, hybrid frames offer versatility for urban commuting and light trail riding.
- Cruiser:Designed for comfort and casual riding, cruiser frames typically feature relaxed geometries and upright seating positions.
- Folding:These frames incorporate hinges or couplers, allowing for compact storage and portability, popular with urban commuters in densely populated cities.
The urban commuter segment drives demand for hybrid frames. Professional racing fuels specialized road frame innovation.
End User:
Volume in the bicycle frames market is primarily driven by the broad recreational and commuter segments, while professional users represent a high-value, lower-volume niche.
- Commuters:This segment requires durable, comfortable, and often accessory-compatible frames for daily transportation in urban environments. Demand is particularly high in European cities, where government incentives and cycling infrastructure support sustainable urban transport solutions.
- Recreational Riders:Seeking frames that balance comfort, versatility, and affordability for leisure rides and fitness activities, this large segment values reliability over extreme performance. The growth of cycling as a health and wellness activity sustains consistent demand for these frames.
- Professional Cyclists:Demanding the lightest, stiffest, and most aerodynamic frames, this segment prioritizes cutting-edge technology and marginal performance gains.
- Delivery Personnel:Requiring robust and often cargo-capable frames, this segment focuses on durability and load-bearing capacity for last-mile logistics.
Recreational riders constitute the largest customer type. Delivery personnel represent a rapidly expanding customer base.
Distribution Channel:
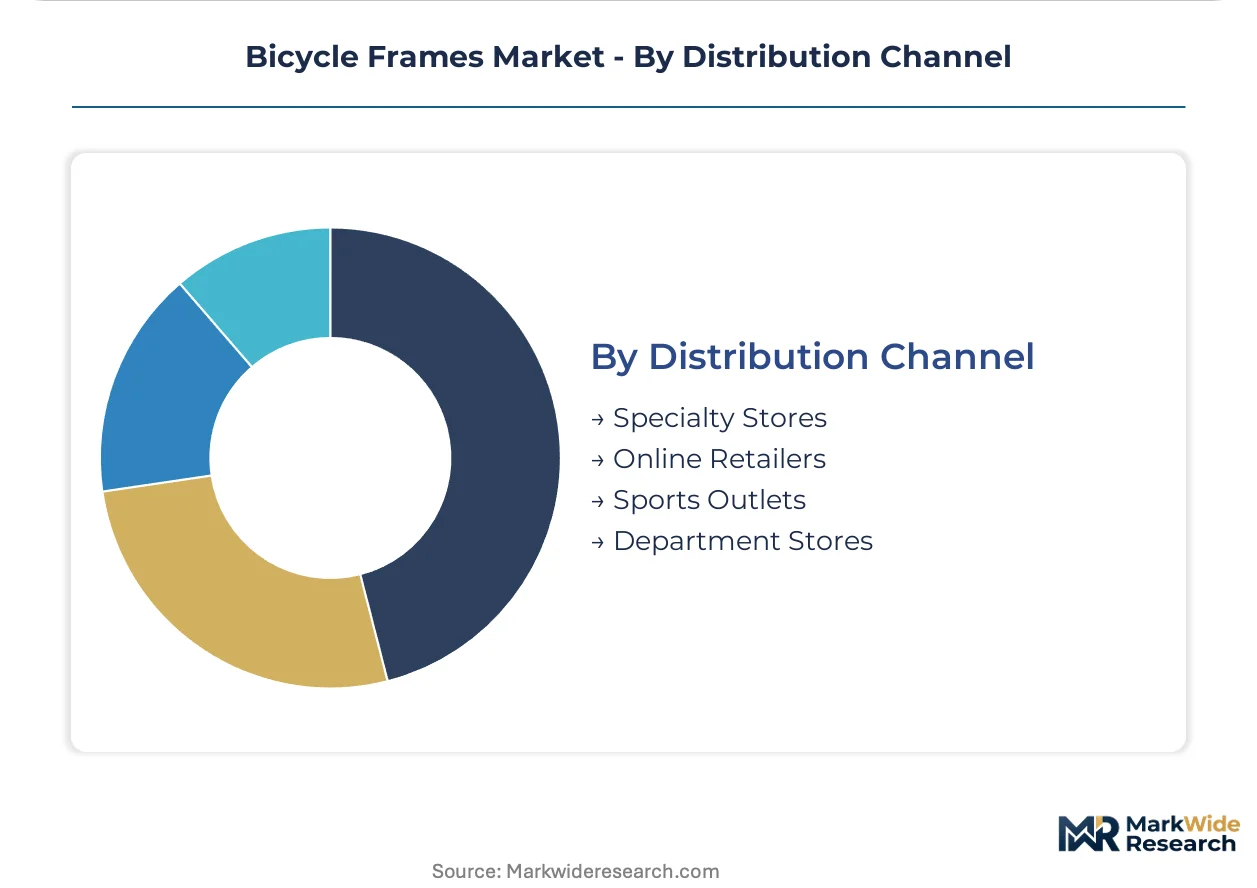
Customer type preferences significantly influence the choice of distribution channel, with specialized channels catering to informed enthusiasts and broader channels serving general consumers.
- Specialty Stores:These outlets offer expert advice, fitting services, and a curated selection of high-performance and premium frames, appealing to serious cyclists. They remain critical for sales of high-margin carbon fiber and custom-built frames, providing personalized customer engagement.
- Online Retailers:Offering convenience, competitive pricing, and a wide selection, online platforms attract price-sensitive consumers and those seeking specific models not readily available locally. This channel is expanding rapidly, driven by digital commerce trends and direct-to-consumer strategies.
- Sports Outlets:Large retail chains specializing in sporting goods offer a range of entry-level to mid-range bicycle frames, targeting general fitness and family consumers.
- Department Stores:These broad retailers typically carry basic and budget-friendly bicycle frames, serving a casual consumer base looking for recreational options.
Online retailers are a significant supply concentration point. Specialty stores maintain a crucial supply role for premium products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global bicycle frames market exhibits varied consumption patterns, with European nations prioritizing sustainable urban transport while Asian countries focus on large-scale manufacturing. This geographic split influences demand drivers and regulatory frameworks across key regions. Different regulatory environments also shape material adoption and production strategies.
Germany
Urban commuters in Germany seek durable and lightweight frames for daily transport, driven by environmental consciousness. Government incentives, including extensive cycling infrastructure investments, stimulate consistent demand for advanced frame types. Major cities like Berlin actively promote cycling, fostering innovation in commuter-focused frame designs and related services.
Netherlands
Dutch consumers prioritize hybrid frames for their versatility in urban commuting and recreational use. The national cycling policy emphasizes safety and accessibility, further boosting frame demand. Utrecht, a leading cycling city, showcases integrated urban planning that supports high bicycle usage.
United States
E-bike frame platforms represent a significant demand driver in the United States, alongside enthusiast road segments. The U.S. Consumer Product Safety Commission (CPSC) sets stringent safety requirements for all bicycle frames sold domestically. California's tech hubs are exploring integrated smart frames, embedding sensors for performance and safety data.
China
China's market is characterized by high-volume production of aluminum and steel frames for mountain and hybrid bikes. The dual carbon goals influence manufacturing practices, pushing for more sustainable production processes. Industrial clusters in Shenzhen concentrate on efficient, large-scale frame fabrication for global export.
Taiwan
Taiwan remains a critical manufacturing hub, specializing in high-quality carbon fiber and aluminum frames for global brands. The Taiwan External Trade Development Council promotes advanced manufacturing technologies and export capabilities. Taichung, a major bicycle industry cluster, leads in precision engineering and automated layup processes.
Bicycle Frames Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the bicycle frames market. The competitive structure is tiered, separating high-volume manufacturers from niche performance-oriented brands and custom fabricators. Strategic archetypes include cost-efficient mass producers leveraging global supply chains, technology innovators focusing on advanced materials, and design-centric premium brands. Companies pursue portfolio diversification into e-bike platforms and strategic partnerships to strengthen their market positions.
Manufacturers with extensive manufacturing scale, such as Giant Manufacturing Co. Ltd., a Taiwan-based entity, control production costs across multiple material types and frame categories. Trek Bicycle Corporation, a US-based entity, exemplifies differentiation through proprietary OCLV Carbon technology and a robust dealer network. Specialized Bicycle Components, another US-based company, competes on high-performance designs, targeting the professional cyclist segment with advanced geometries and material science. These entities anchor distinct segments of the market.
| Leading Market Players |
|---|
| Scott Sports SA |
| Merida Industry Co. Ltd. |
| Giant Manufacturing Co. Ltd. |
| Cervelo Cycles |
| Bianchi |
| Trek Bicycle Corporation |
| Cannondale Bicycle Corporation |
| Santa Cruz Bicycles |
| Specialized Bicycle Components |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for carbon fiber secure material access and provide price visibility for high-performance frame manufacturers. These contracts mitigate input cost volatility for specialized bicycle frame production.
Pricing Analysis
Long-term offtake agreements for advanced composites define pricing for premium carbon fiber frames. Price differentiation stems from OCLV Carbon technology and brand reputation among enthusiasts. Pricing softness reflects competitive pressure from automated layup technology making high-performance frames more accessible. Recreational riders exhibit the most price sensitivity, while professional cyclists are the least.
Supply Chain Analysis
Taiwan and China anchor bicycle frame production, specializing in high-quality carbon fiber and high-volume aluminum frames respectively. The supply chain relies on raw materials like aerospace-grade carbon fiber and various aluminum alloys. Geographic production risk exposes the industry to geopolitical tensions and logistical disruptions. Downstream distribution runs primarily through specialty stores and online retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story, driven by increasing adoption of sustainable urban transport solutions. The shift towards e-bike platforms and cargo bikes for last-mile delivery further accelerates demand.
For Market Incumbents:Shield core carbon fiber frame margins by vertically integrating automated layup processes to control costs. Invest in proprietary OCLV Carbon technology to counter emerging composite engineering specialists. Develop robust compliance frameworks for ISO 4210 and CPSC regulations against potential product safety challenges. Expand into e-bike frame platforms to mitigate risks from traditional bicycle market saturation.
For New Entrants and Emerging Players:Anchor in the urban logistics segment by developing specialized, durable cargo bike frames for last-mile delivery fleets. Target European cities with mature bike-share programs for initial market penetration. Offer integrated fleet management and maintenance services as a key go-to-market strategy. Leverage additive manufacturing for rapid prototyping and bespoke frame customization.
For Investors and Strategic Acquirers:Mid-cap composite engineering specialists with proprietary automated layup technology represent attractive acquisition targets for long-term growth. These firms offer advanced material science capabilities crucial for future frame innovation. Look for companies demonstrating strong compliance with CSRD and ISO 4210 standards. A signal to watch is the increasing adoption rate of integrated smart frames in premium segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Automated Carbon Fiber Layup | This reduces manufacturing costs for high-performance frames, making them accessible to a wider enthusiast segment. |
| Develop E-Bike Frame Platforms | Addresses demand for new frame designs engineered to manage motor torque and battery integration in North America. |
| Secure Long-Term Raw Material Contracts | Mitigates input cost volatility for carbon fiber and aluminum alloys, stabilizing production planning for manufacturers. |
| Expand into Urban Logistics Frame Segment | Capitalizes on emerging commercial demand for durable cargo bike frames in last-mile delivery fleets. |
| Implement Life-Cycle Assessment Capabilities | Ensures compliance with the EU's Corporate Sustainability Reporting Directive and maintains European market access. |
Research Approach
Findings reconcile primary fieldwork against secondary review of industry reports, government regulations, and corporate disclosures. Primary interviews engaged bicycle frame engineers, procurement leads at major brands, specialty store owners, and urban planning officials. This approach ensured bottom-up market insights were validated against top-down industry trends. Volume and value data were triangulated across these diverse sources.
Segmentation dimensions modeled include material type, frame type, end-user, distribution channel, and regional demand patterns. The analytical framework projects growth trajectories across the analysis window, deriving compound annual growth rates from historical trends and future outlooks. Key forecast inputs included raw material price forecasts and government spending on cycling infrastructure.
Material uncertainties — including geopolitical shifts and unforeseen technological breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding market dynamics and regulatory environments. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Tow Tractor Market
Vehicle Components
UK Automotive Glass Fiber Composites Market
Vehicle Components
Global Undercarriage Components Market
Vehicle Components
Latin America Two-Wheeler Components Market
Vehicle Components
Spark Plug Accessories Market
Vehicle Components
Industrial Gearbox Market
Vehicle Components
Automotive Aftermarket Shock Absorbers Market
Vehicle Components
Italy Automotive Glass Fiber Composites Market
Vehicle Components
Suction Road Sweeper Market
Vehicle Components
Off-Highway Diesel Engine Market
Vehicle Components
Bus and Coach Suspension Bearing Components Market
Vehicle Components
Exhaust Gas Recirculation (EGR) Valve Market
Vehicle Components
Motorcycle Connectors Market
Vehicle Components
Rear-Wheel Steering Actuator Systems for SUVs Market
Vehicle Components
Trailer Terminal Tractor Market
Vehicle Components
Snowplows Market