
 Railroad Equipment Manufacturing Market | 2026-2036
Railroad Equipment Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Railroad Equipment Manufacturing Market Outlook
The EU Green Deal's transport decarbonization targets is recalibrating procurement criteria across European rail networks. CRRC Corporation Limited leverages its integrated manufacturing footprint to dominate high-speed rolling stock exports. Siemens Mobility anchors its competitive position through deep R&D investment in autonomous signaling platforms. Alstom differentiates via hydrogen train technology leadership and established maintenance service contracts.
Railroad equipment manufacturing encompasses the production of rolling stock, track components, signaling apparatus, and maintenance machinery built to precise gauge, axle load, and interoperability specifications. Locomotives and freight cars constitute the largest revenue pools, though margin concentration is shifting toward rail maintenance machines as asset life-extension demand rises. Electric technology segments are capturing disproportionate investment flows, while diesel platforms face accelerated obsolescence risk from tightening emission protocols. Government entities and logistics providers represent divergent buyer archetypes, with the former prioritizing fleet electrification and the latter demanding payload optimization.
The EPA enforces Tier 4 locomotive emission standards in the United States, while the EU F-Gas Regulation and ECHA REACH framework constrain refrigerant and material choices across European supply chains. China's MIIT and GB standards govern domestic rolling stock certification, creating segmented market access conditions. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs increasingly determine competitive viability in cross-border tenders.
Market Dynamics
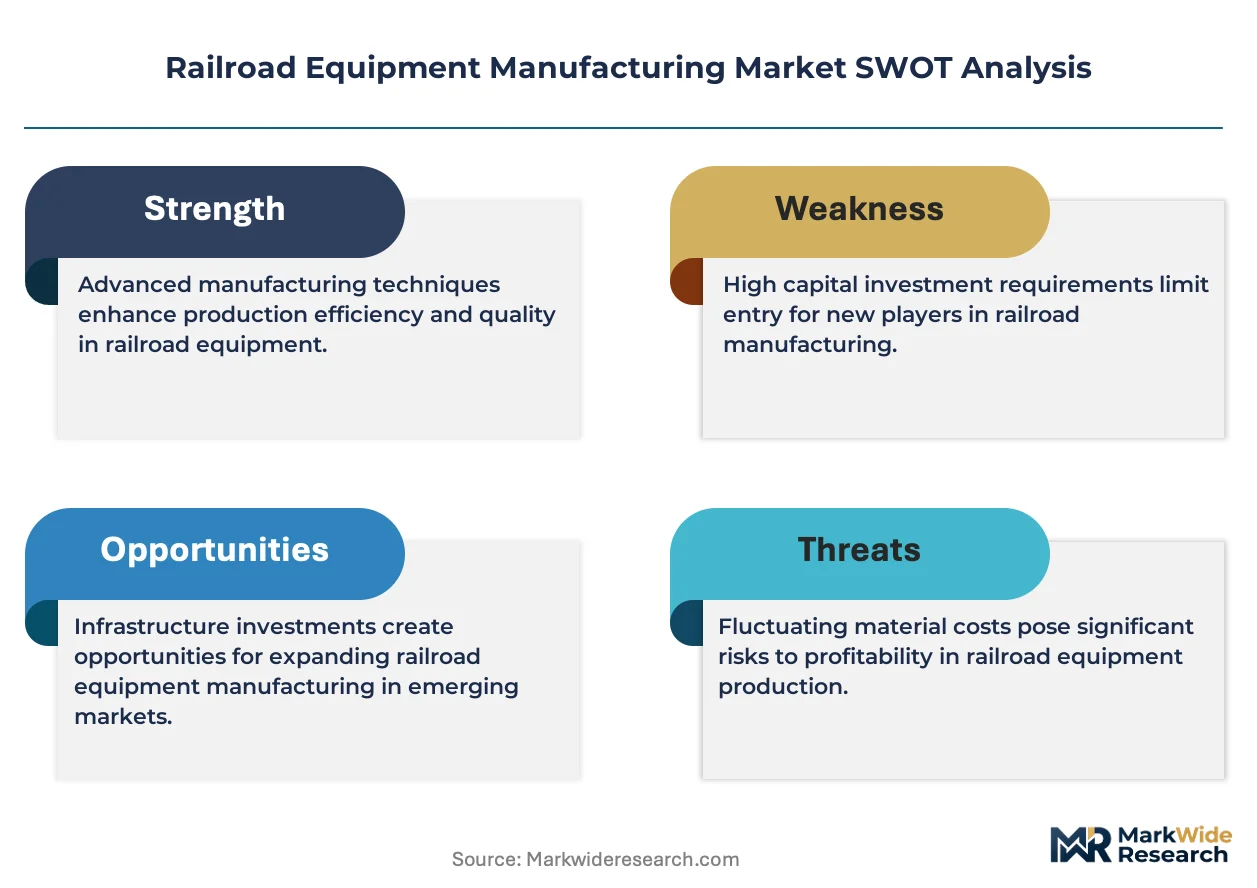
The EPA Tier 4 locomotive emission standards are forcing freight rail operators to retire diesel platforms prematurely, redirecting capital toward battery-electric and hydrogen fuel cell alternatives. This regulatory compression is restructuring procurement priorities across North American freight networks.
Growth Catalysts
- EPA Tier 4 mandates:Freight operators in the United States face compliance deadlines that accelerate fleet renewal cycles and expand addressable demand for low-emission rolling stock.
- Hydrogen fuel cell locomotives:Alstom's Coradia iLint deployments in Germany demonstrate commercial viability and validate procurement budgets for zero-emission regional services.
- Rail infrastructure stimulus:Dedicated funding packages in China, the United States, and Germany concentrate demand for new rolling stock and track modernization equipment.
Market Restraints
- Specialized steel and aluminum input costs:Rolling stock manufacturers face margin pressure from volatile commodity pricing for high-strength alloys and electrical steel laminations.
- Supply concentration in China:CRRC Corporation's dominance of high-speed train exports creates dependency risk for non-Chinese operators seeking alternative suppliers.
- Battery energy density limitations:Current lithium-ion chemistries constrain range and payload capacity for heavy-haul freight electrification, preserving diesel dependence in long-haul segments.
Strategic Opportunities
- India's Dedicated Freight Corridors:The country's freight corridor expansion creates demand for specialized electric locomotives and heavy-axle-load wagons outside established supplier relationships.
- EU Green Deal transport decarbonization:The European Commission's binding emission reduction targets mandate fleet electrification and hydrogen adoption by 2050.
- Digital twin convergence with predictive maintenance:Siemens Mobility integrates sensor telemetry with AI-driven asset management to unbundle service contracts from equipment sales.
Industry Challenges
- Electrical engineering talent scarcity:Battery system integration and power electronics expertise shortages delay hydrogen and electric locomotive development timelines.
- GB standards certification complexity:China's MIIT certification requirements create extended approval cycles for foreign manufacturers seeking domestic market access.
- Legacy signaling system interoperability:European Rail Traffic Management System migration demands backward compatibility investments that strain R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railroad Equipment Manufacturing Market |
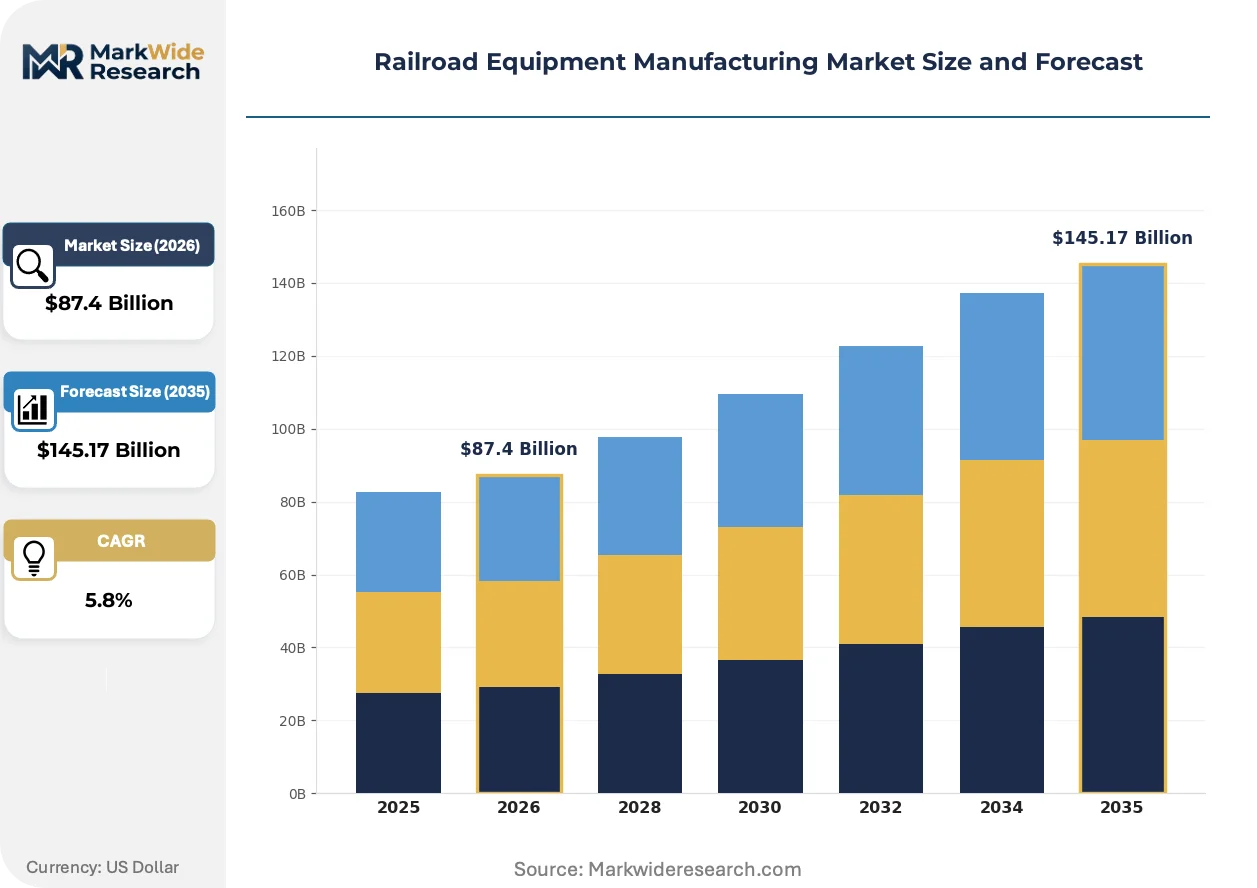
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $145.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Locomotives, Freight Cars, Passenger Coaches, Rail Maintenance Machines Technology: Electric, Diesel, Hybrid, Autonomous Systems End User: Rail Operators, Government Entities, Private Companies, Logistics Providers Application: Freight Transport, Passenger Transport, Infrastructure Maintenance, Signal Systems |
| Companies Covered | CRRC Corporation Limited, Alstom, Siemens Mobility, Wabtec Corporation, Stadler Rail AG, CAF, Knorr-Bremse, Hitachi Rail, Hyundai Rotem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railroad Equipment Manufacturing Market Strategic Shifts
Autonomous signaling and predictive maintenance platforms are compressing operational expenditure models for freight and passenger operators. Battery chemistry advances and hydrogen storage improvements are redefining range-performance tradeoffs in rolling stock procurement.
Autonomous train operation technology is automating signaling decision-making across urban metro and mainline freight corridors. Deutsche Bahn and SNCF pilot projects in Germany and France validate reduced headway requirements and crew cost structures. This automation is enabling 24-hour operations on corridors previously limited by driver shift regulations and labor agreements.
The EU F-Gas Regulation constrains refrigerant choices in passenger car HVAC systems and forces redesign of thermal management architectures. Rolling stock manufacturers must substitute hydrofluorocarbon-based systems with natural refrigerants or closed-loop heat pumps. European passenger operators face compressed retrofit timelines as the regulation phases down high-global-warming-potential gases through 2030.
Freight rail operators in North America now unbundle locomotive procurement from multi-decade maintenance contracts. Class I railroads negotiate performance-based service agreements separately from capital equipment purchases. This purchasing pattern shift concentrates in the United States, where Union Pacific and BNSF Railway demand lifecycle cost transparency rather than bundled vendor lock-in.
Railroad Equipment Manufacturing Market Segmentation
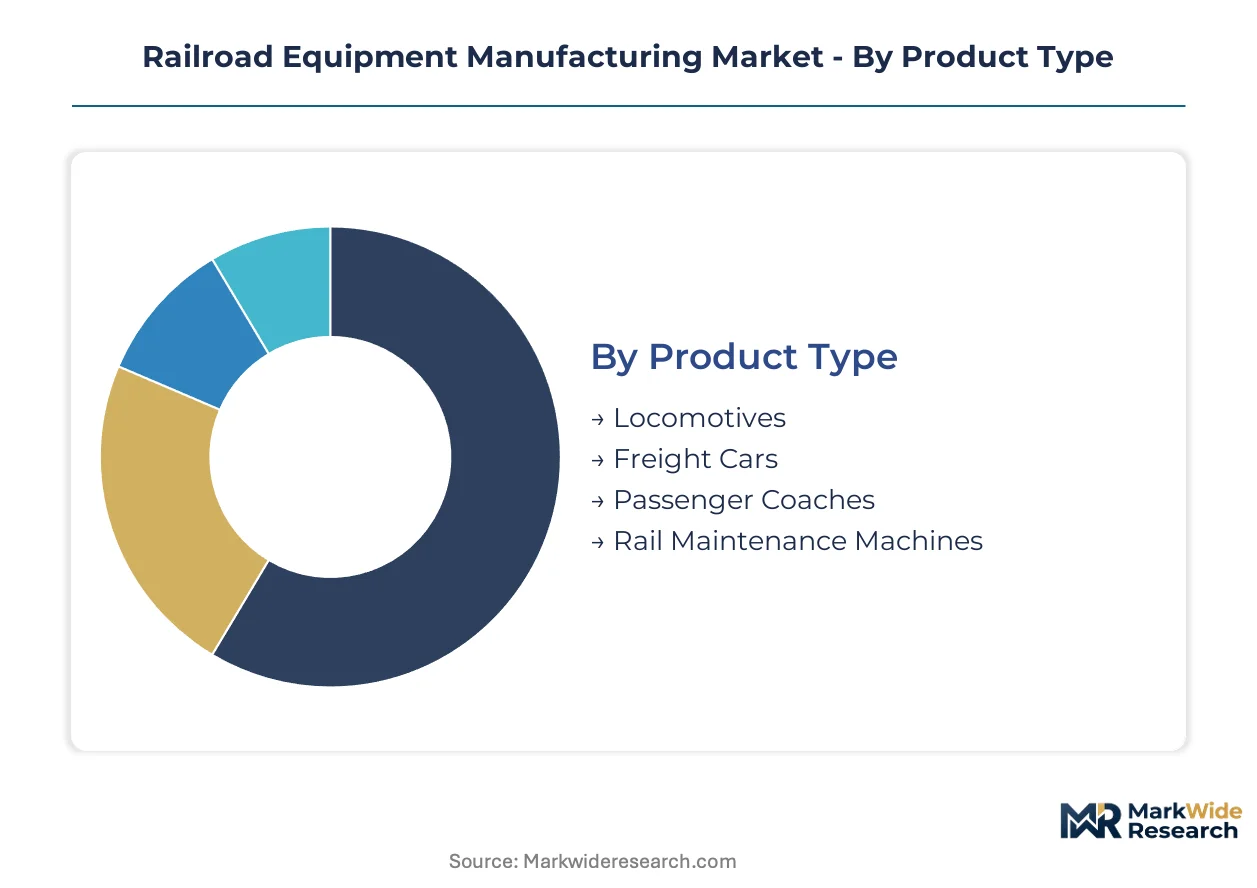
Railroad equipment procurement decisions diverge sharply between freight operators maximizing payload economics and government buyers prioritizing emission compliance. Technology choices now override traditional product specifications as battery-electric and hydrogen platforms reshape capital allocation frameworks.
Product Type:
Freight rail operators in North America and China anchor procurement volume around haulage efficiency and axle-load ratings, while European networks emphasize interoperability standards for cross-border passenger service.
- Locomotives:Diesel-electric traction dominates heavy-haul freight in the United States under EPA Tier 4 compliance deadlines, though hydrogen fuel cell variants from Alstom and Siemens Mobility are capturing dedicated regional passenger contracts in Germany. Procurement budgets are bifurcating between emission-compliant diesel replacements and zero-emission pilot deployments.
- Freight Cars:High-strength steel and aluminum alloy construction enables heavier axle loads for bulk commodity transport across Union Pacific and BNSF Railway networks. Demand concentrates in gondolas and covered hoppers for agricultural and energy sector logistics.
- Passenger Coaches:Double-decker configurations and lightweight composite materials serve Deutsche Bahn and SNCF high-frequency corridors. HVAC system redesigns under EU F-Gas Regulation mandate natural refrigerant adoption.
- Rail Maintenance Machines:Automated track inspection vehicles and tamping equipment address asset life-extension demand as infrastructure age exceeds design specifications across legacy networks.
Volume sits with Freight Cars; growth tilts toward Rail Maintenance Machines.
Technology:
Powertrain selection now determines market access eligibility as jurisdictional emission protocols harden, with procurement committees weighting total cost of ownership over capital expenditure.
- Electric:Overhead catenary and third-rail systems serve urban metro density in China and Japan, where MIIT and METI standards accelerate domestic manufacturing scale. Battery-electric variants are penetrating regional passenger routes under 200 kilometers.
- Diesel:EPA Tier 4 and EU Stage V compliance costs have compressed margin structures for traditional locomotive builders, though long-haul freight segments retain diesel dependence where electrification infrastructure remains uneconomic.
- Hybrid:Diesel-battery configurations offer interim emission reduction for switching yards and short-line operators facing capital constraints for full electrification.
- Autonomous Systems:Driverless operation platforms from Siemens Mobility and Hitachi Rail are deploying on Singapore Metro and Paris Metro lines, reducing headway intervals and crew cost structures.
Electric platforms command the largest installed base; Autonomous Systems are expanding most quickly.
End User:
Procurement authority fragmentation between state-owned infrastructure and private logistics operators creates divergent specification requirements and contract structures.
- Rail Operators:Deutsche Bahn, SNCF, and Amtrak prioritize fleet standardization and maintenance service bundling. Their procurement specifications increasingly mandate digital twin integration and predictive maintenance capabilities.
- Government Entities:China's Ministry of Transport and India's Ministry of Railways direct infrastructure stimulus toward domestic manufacturing preference and technology transfer requirements.
- Private Companies:Mining and industrial conglomerates in Australia and Brazil procure specialized heavy-haul equipment outside standard catalog specifications.
- Logistics Providers:Intermodal operators such as Maersk and DHL demand wagon fleet flexibility for multimodal container routing across European corridors.
Government Entities anchor procurement volume; Logistics Providers are gaining specification influence fastest.
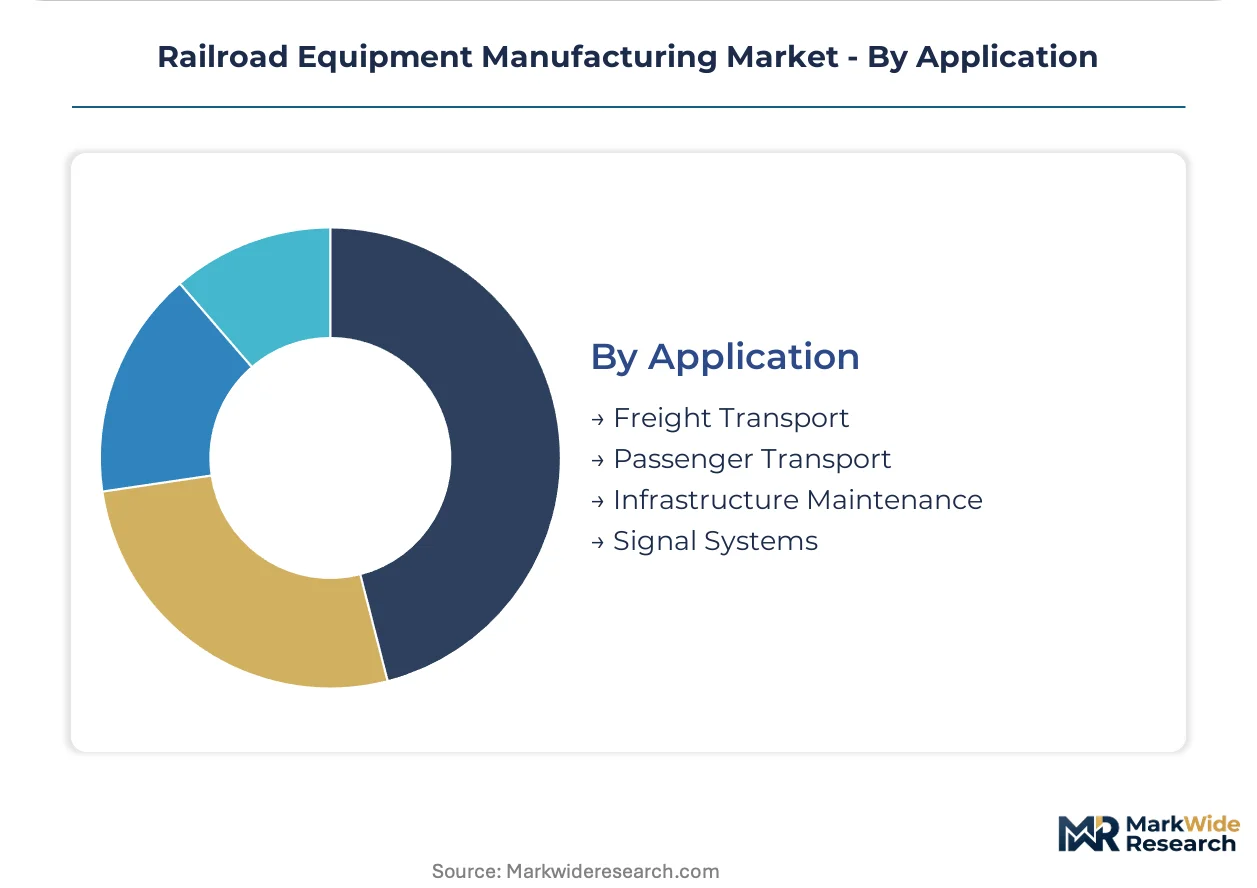
Application:
Operational use case determines equipment duty cycles, maintenance intervals, and regulatory exposure across divergent network topologies.
- Freight Transport:Bulk commodity and intermodal container movements drive demand for high-axle-load wagons and distributed power locomotive configurations across North American Class I networks.
- Passenger Transport:High-speed rolling stock from CRRC Corporation and Alstom serves corridor density between Chinese megacities and European capital connections.
- Infrastructure Maintenance:Track renewal and inspection equipment demand rises as deferred maintenance backlogs accumulate across aging networks in the United States and United Kingdom.
- Signal Systems:European Rail Traffic Management System migration and Communications-Based Train Control deployment in urban metros require backward-compatible signaling hardware.
Freight Transport dominates equipment shipments; Infrastructure Maintenance is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qingdao anchors rolling stock manufacturing concentration through CRRC Corporation's integrated production complex, while regulatory divergence across major economies fragments procurement standards and compliance architectures.
United States
Class I freight operators including Union Pacific and BNSF Railway accelerate diesel locomotive retirements under EPA Tier 4 mandates. The Infrastructure Investment and Jobs Act directs federal rail modernization funding toward low-emission fleet transitions. Manufacturing activity clusters in Pennsylvania's rail equipment corridor and Illinois industrial zones serving Midwest freight density.
China
MIIT certification requirements and GB standards govern domestic rolling stock procurement for high-speed corridor expansion between Beijing, Shanghai, and Guangzhou. The Ministry of Transport directs infrastructure stimulus toward domestic manufacturing preference and technology localization. Production gravity concentrates in Qingdao, Changchun, and Zhuzhou industrial clusters supplying both domestic and export markets.
Germany
Deutsche Bahn's fleet electrification targets under EU Green Deal transport decarbonization mandates accelerate hydrogen and battery-electric locomotive procurement. The KBA enforces EU Stage V emission compliance across regional rail networks. Manufacturing and R&D activity concentrates in Berlin-Brandenburg and Bavaria, with Siemens Mobility and Alstom anchoring signaling and rolling stock development.
India
The Dedicated Freight Corridor Corporation expands electrified heavy-haul routes between Delhi and Mumbai, creating demand for specialized electric locomotives and high-axle-load wagons. The Ministry of Railways implements domestic content requirements under Make in India procurement rules. Industrial activity clusters in Uttar Pradesh's rail manufacturing zones and Tamil Nadu's component supply corridors.
Japan
METI standards and JIS certification govern Shinkansen fleet renewal and urban metro automation deployments. The Ministry of Land, Infrastructure, Transport and Tourism prioritizes autonomous train operation pilots for labor-constrained regional lines. Manufacturing and technology development concentrates in Kanto and Kansai industrial belts, with Hitachi Rail anchoring signaling and rolling stock integration.
Railroad Equipment Manufacturing Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology integration depth and service contract bundling. The market exhibits tiered consolidation with integrated manufacturers controlling high-speed and signaling segments while specialized component suppliers occupy maintenance and brake system niches. Three archetypes dominate: state-linked rolling stock integrators, European engineering conglomerates with signaling depth, and North American freight-focused equipment suppliers. Competitive moves concentrate on hydrogen technology licensing partnerships and predictive maintenance platform unbundling from hardware sales.
Within the state-linked integrator tier, CRRC Corporation Limited exemplifies vertical manufacturing scope spanning complete train systems. Among European engineering conglomerates, Siemens Mobility and Alstom occupy positions differentiated by autonomous signaling versus hydrogen propulsion specialization. These three anchors represent divergent strategic postures: captive domestic market scale, R&D-intensive technology leadership, and service-integrated solution bundling respectively.
| Leading Market Players |
|---|
| CRRC Corporation Limited |
| Alstom |
| Siemens Mobility |
| Wabtec Corporation |
| Stadler Rail AG |
| CAF |
| Knorr-Bremse |
| Hitachi Rail |
| Hyundai Rotem |
| Others |
Value Chain & Pricing Dynamics
EPA Tier 4 emission compliance gates qualified supplier access for North American freight operators while segmenting pricing tiers between emission-certified and legacy diesel platforms. Premium procurement budgets attach to hydrogen and battery-electric locomotive configurations as fleet renewal programs redirect capital toward zero-emission alternatives.
Pricing Analysis
Lifecycle cost transparency anchors value-based pricing as Union Pacific and BNSF Railway unbundle equipment procurement from multi-decade maintenance contracts. Three-tier pricing structure across premium, standard, and economy levels reflects EPA Tier 4 certification status, hydrogen technology readiness, and predictive maintenance service bundling. Cost compression in diesel-electric platforms intensifies because margin structures face regulatory compliance burden and commodity alloy volatility. Logistics providers exhibit highest price sensitivity due to payload optimization mandates, while government entities prioritize emission performance over capital expenditure minimization.
Supply Chain Analysis
Electrical steel laminations and high-strength aluminum alloys rest on concentrated mining and smelting capacity across China, Russia, and Australia. Specialized traction motor components and power electronics feed from Japanese and German precision manufacturing clusters. Single-source vulnerability in rare earth permanent magnet supply creates procurement risk for traction motor assemblers seeking dual-qualified vendors. Distribution runs through OEM direct sales for Class I railroads and regional distributor networks for maintenance equipment and component aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized electrical engineering talent scarcity constrains hydrogen locomotive development capacity, propping premium-tier pricing for qualified manufacturers. Supply-side bottlenecks in battery system integration expertise limit competitive entry and sustain margin structures for incumbent technology leaders.
For Market Incumbents: Deepen backward integration into electrical steel and permanent magnet supply through captive offtake agreements with Australian and Chinese rare earth processors. Expand hydrogen technology licensing partnerships to monetize R&D investment while containing development timeline risk from engineering talent shortages. Fortify maintenance service contract retention through predictive maintenance platform deployment that raises switching costs for Deutsche Bahn and SNCF operators.
For New Entrants and Emerging Players: Begin with India's Dedicated Freight Corridor procurement windows where domestic content requirements under Make in India rules create entry pathways outside established CRRC and European supplier relationships. Target rail maintenance machine segments where asset life-extension demand climbs fastest and technical barriers concentrate in sensor integration rather than propulsion system mastery. Pursue joint development agreements with Indian state-owned manufacturing zones to satisfy localization mandates.
For Investors and Strategic Acquirers: Alstom's Coradia iLint hydrogen deployment scale-up in Germany is the leading indicator that zero-emission regional service economics have crossed commercial viability thresholds. Long-term viability over the coming decade hinges on hydrogen infrastructure buildout pace and electrolyzer cost curves rather than rolling stock manufacturing scale. Acquisition targets should emphasize autonomous signaling software specialists with ETCS compatibility depth and established European rail operator relationships. Watch for Deutsche Bahn fleet electrification tender announcements as inflection signals for hydrogen locomotive demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Locomotive Technology Licensing | Alstom's German deployments validate commercial viability and redirect procurement budgets. |
| Predictive Maintenance Platform Integration | Siemens Mobility unbundles service contracts from equipment sales through AI-driven asset management. |
| Domestic Manufacturing Localization | India's Make in India rules create procurement pathways outside established supplier relationships. |
| Autonomous Signaling System Development | Deutsche Bahn and SNCF pilot projects validate reduced headway and crew cost structures. |
| Rare Earth Supply Chain Backward Integration | Permanent magnet dependency creates vulnerability for traction motor assemblers seeking dual sourcing. |
Study Parameters
Document review covered customs and trade data, EPA emission compliance filings, EU transport decarbonization policy documents, and MIIT certification records, complemented by interviews with fleet procurement directors at North American Class I railroads, rolling stock engineering leads at European manufacturers, maintenance operations managers at Deutsche Bahn and SNCF, and hydrogen technology specialists at Alstom and Siemens Mobility. Secondary validation drew from railway operator annual reports, infrastructure stimulus appropriation records, and steel and aluminum commodity pricing indices. Bottom-up equipment shipment tallies and top-down infrastructure investment flows were triangulated to constrain volume estimates.
Cross-referencing historical fleet renewal cycles against panel input from procurement executives anchored the projection framework across the analysis window. Segmentation modeling incorporated product type, technology architecture, end-user procurement authority, and application duty cycle dimensions. CAGRs were derived from equipment replacement timelines under emission compliance deadlines and infrastructure stimulus disbursement schedules. Forecast inputs included hydrogen storage cost improvement curves, battery energy density advancement trajectories, and rail freight modal share elasticity to fuel price movements.
Regulatory enforcement variance, commodity alloy price spikes, and hydrogen infrastructure buildout delays are the dominant revision risks to modeled equipment demand. Forecasts reflect assumptions about emission mandate adherence timelines and stimulus fund deployment efficiency. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Electric Vehicle Parts and Components Market
Vehicle Components
Automotive Wheel Speed Sensor Market
Vehicle Components
Wheel Speed Sensor Market
Vehicle Components
Global Automotive Rain, Light, Humidity Sensor Market
Vehicle Components
Vehicle-To-X Products Market
Vehicle Components
Motorcycle Monoshock Suspension Market
Vehicle Components
Anchorage Connector Market
Vehicle Components
North America Forklift Rental Market
Vehicle Components
Cross Roller Bearings Market
Vehicle Components
Automotive Brake Valves Market
Vehicle Components
Mining Vehicle AC Kits Market
Vehicle Components
Bicycle Accessories Market
Vehicle Components
Mobility Aids and Transportation Equipment Market
Vehicle Components
Vehicle Trailer Hitch Market
Vehicle Components
Steering Column Module Market
Vehicle Components
Electric Wheelbarrow Market