
 Saudi Arabia Car Rental and Leasing Market | 2026-2036
Saudi Arabia Car Rental and Leasing Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Car Rental and Leasing Market Analytics
Premium fleet offerings and commodity daily rentals is decoupling as Saudi corporate clients demand telematics-enabled vehicles while budget tourists prioritize lowest rates. Lumi Rental Co. leverages its government partnerships to anchor large-scale leasing contracts with public sector entities. Theeb Rent A Car dominates the domestic short-term segment through extensive branch networks across secondary cities. Hanco Automotive specializes in commercial vehicle leasing, sustaining contract logistics operators with tailored maintenance-inclusive packages.
Car rental and leasing denotes the commercial provision of vehicle access through time-bound contracts, encompassing daily rentals with full-service maintenance and multi-year operating leases where the lessor retains asset ownership and residual risk. Fleet management systems integrate GPS tracking, fuel monitoring, and automated scheduling to optimize vehicle utilization for corporate clients. Short-term rental generates the highest transaction frequency but thinner margins, while long-term leasing captures deeper customer relationships and predictable revenue streams. Corporate clients represent the most structured demand pool, with government agencies and tourism segments expanding through Vision 2030 infrastructure and entertainment investments.
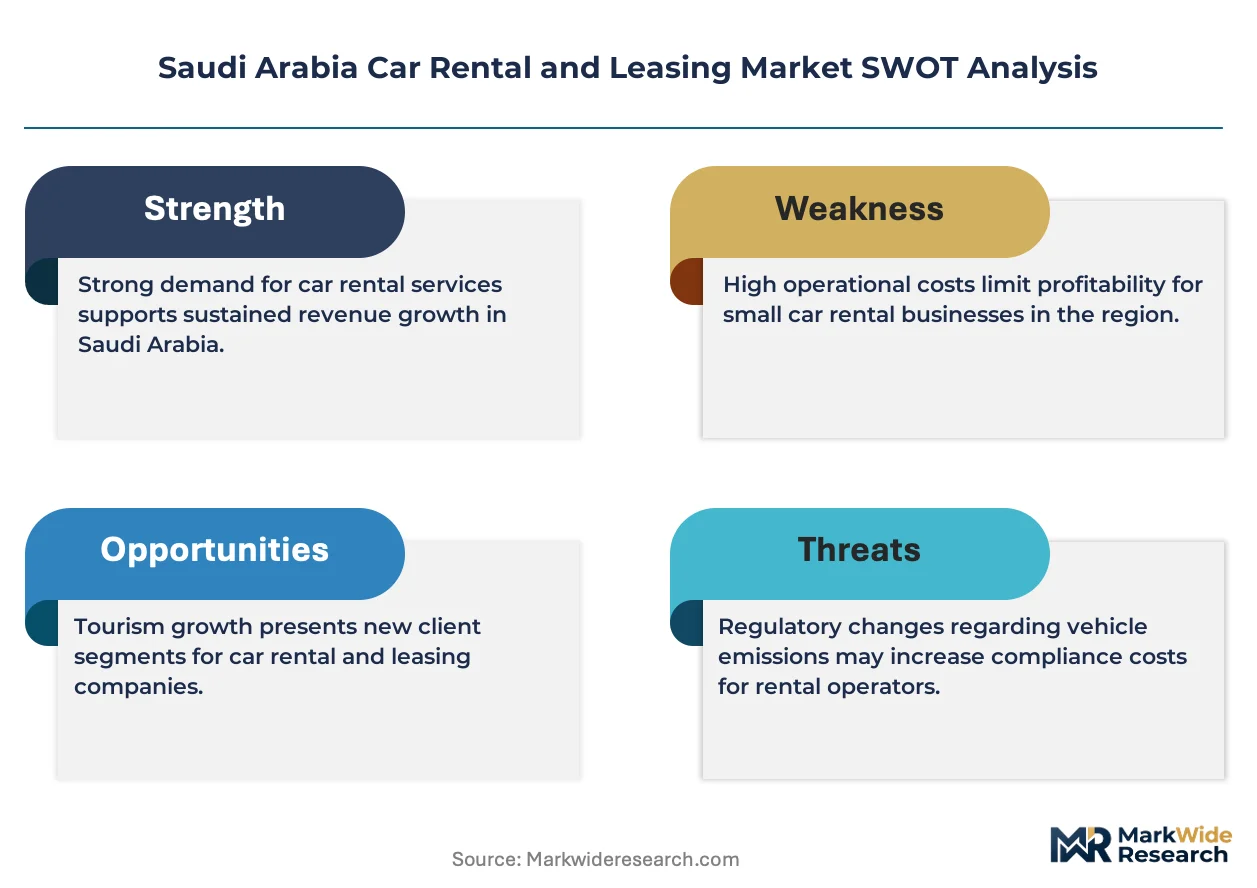
SAMA, the Saudi Central Bank, governs lease financing structures and consumer protection standards, while the Ministry of Municipal and Rural Affairs regulates commercial operating permits across municipal jurisdictions. The General Authority for Competition enforces pricing transparency and anti-monopoly provisions, shaping how rental operators structure fleet procurement and customer contracts. Stakeholders must monitor evolving electric vehicle adoption mandates and charging infrastructure rollouts that will reshape fleet composition decisions and capital deployment timelines.
Market Dynamics
SAMA's Islamic leasing regulations are restructuring how Saudi fleet operators finance vehicle acquisitions, decoupling credit access from conventional interest-based structures and unlocking corporate demand previously constrained by Sharia compliance requirements.
Growth Catalysts
- Vision 2030 Infrastructure Buildout:Mega-project construction across NEOM and Red Sea developments is generating sustained demand for commercial vehicle leasing among logistics contractors and equipment suppliers.
- Telematics Integration Mandates:Fleet management systems combining GPS tracking with fuel monitoring are becoming standard procurement requirements for Saudi government contracts.
- Expatriate Workforce Mobility:Riyadh and Jeddah's concentrated expatriate populations sustain high utilization rates for short-term rental fleets serving rotational employment patterns.
Market Restraints
- Residual Value Volatility:Accelerated depreciation of internal combustion engine fleets under emerging EV transition policies compresses lessor profitability on multi-year contracts.
- Charging Infrastructure Gaps:Sparse fast-charging networks outside Riyadh and Jeddah limit electric fleet deployment to urban corridors, constraining nationwide service expansion.
- Import Duty Exposure:Heavy reliance on fully built-up vehicle imports subjects fleet procurement costs to customs tariff fluctuations and currency exchange pressures.
Strategic Opportunities
- Secondary City Penetration:Dammam, Abha, and Tabuk exhibit underdeveloped rental infrastructure relative to their growing business travel volumes and domestic tourism flows.
- EV Fleet Leasing Pilots:SAMA's green finance incentives and Saudi Energy Efficiency Center mandates create regulatory tailwinds for electric vehicle operating lease structures.
- Maintenance-Inclusive Packaging:Integration of predictive maintenance software with leasing contracts addresses corporate procurement teams' total cost of ownership optimization priorities.
Industry Challenges
- Telematics Talent Scarcity:Fleet operators face acute shortages of data analysts capable of translating GPS and fuel monitoring outputs into utilization optimization strategies.
- Multi-Platform Integration Complexity:Legacy reservation systems require expensive middleware development to connect with emerging mobility-as-a-service aggregators and corporate travel management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Car Rental and Leasing Market |
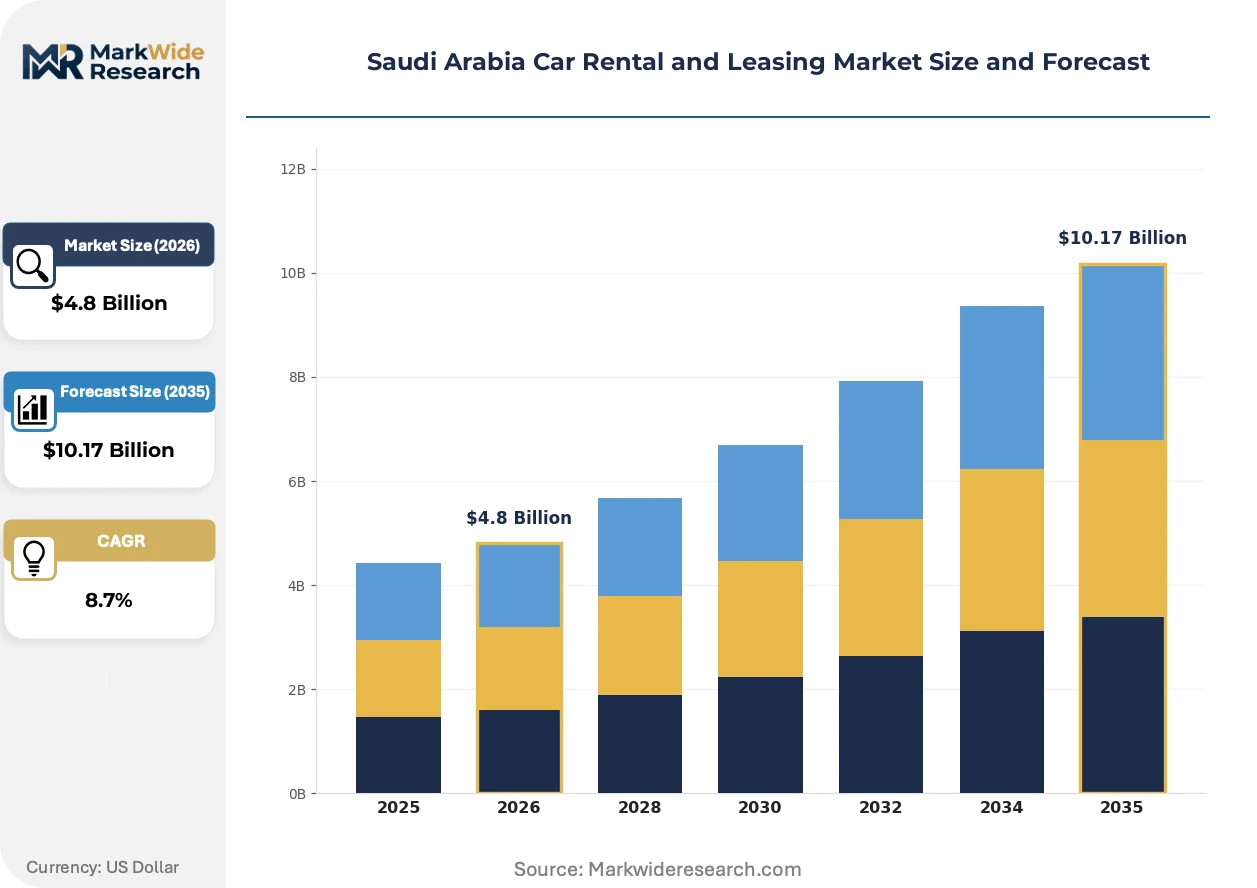
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Short-term Rental, Long-term Leasing, Chauffeur Services, Car Sharing Vehicle Type: Sedans, SUVs, Vans, Luxury Cars Customer Type: Corporate Clients, Tourists, Government Agencies, Individuals Distribution Channel: Online Platforms, Travel Agencies, Direct Sales, Brokers |
| Companies Covered | Hanco Automotive, Lumi Rental Co., Hertz Corporation, Key Car Rental, Sixt SE, Budget Rent-A-Car (United Intl. Transportation Co.), Theeb Rent A Car, Strong Rent a Car, Avis Budget Group Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Car Rental and Leasing Market Evolving Landscape
Digital fleet management platforms are compressing operational decision cycles while regulatory pressure on carbon intensity reshapes asset composition strategies across Saudi leasing portfolios.
Connected vehicle telematics is expanding into predictive maintenance and dynamic pricing models. Logistics operators and government fleet managers are adopting these systems at accelerating rates, driven by procurement mandates requiring real-time utilization reporting. The technology is expanding into residual value forecasting and automated lease restructuring, compressing traditional asset management timelines.
SAMA's consumer finance regulations now explicitly permit Ijara structures that separate vehicle ownership from usage rights without interest components. This regulatory shift enables Islamic banks to compete directly with conventional lessors for corporate fleet contracts. Large construction and logistics firms are restructuring existing credit facilities to align with Sharia-compliant frameworks, particularly in Riyadh-based government contracting.
Corporate procurement teams are consolidating vendor relationships around integrated mobility solutions rather than discrete rental transactions. Single-source fleet management contracts displace fragmented arrangements with multiple short-term rental providers. This concentration is most visible among Saudi Aramco contractors and Vision 2030 project operators seeking unified billing and standardized telematics reporting.
Saudi Arabia Car Rental and Leasing Market Segmentation
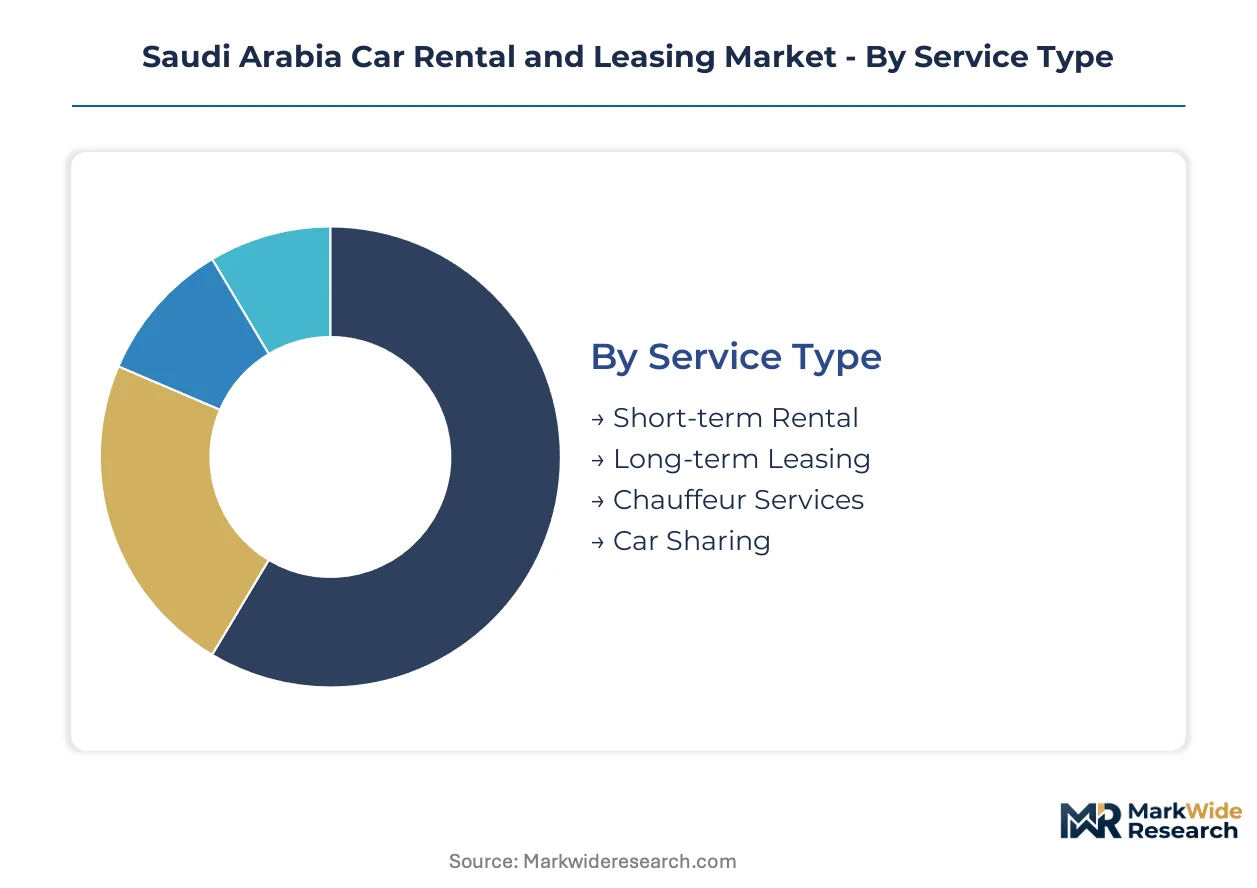
Saudi Arabia's car rental and leasing market fragments across service models, vehicle classes, and procurement channels that each carry distinct margin profiles and capital intensity requirements. Understanding these divisions reveals where telematics investments and Islamic financing structures generate competitive separation.
Service Type:
Standalone service offerings dominate transaction volume while embedded fleet solutions capture deeper enterprise relationships and longer contract tenures.
- Short-term Rental:Daily and weekly vehicle access with full maintenance coverage and roadside assistance. Riyadh and Jeddah airports generate the highest transaction density, driven by business travel corridors and Umrah pilgrimage flows. Fleet turnover pressures and thin margins force operators toward utilization optimization software.
- Long-term Leasing:Multi-year operating leases where lessors retain residual risk and asset ownership. Corporate logistics firms and Vision 2030 contractors concentrate demand here, prioritizing predictable cost structures and telematics-enabled fleet oversight.
- Chauffeur Services:Driver-inclusive mobility packages targeting executive transport and hospitality sectors.
- Car Sharing:Hourly access models with app-based booking and automated vehicle retrieval.
Short-term rental leads volumes today; long-term leasing is gaining share fastest through corporate consolidation trends.
Vehicle Type:
Cost tier stratification separates premium fleet investments from standardized procurement, with each tier demanding distinct maintenance protocols and residual value management strategies.
- Sedans:Mid-size passenger vehicles optimized for fuel efficiency and urban maneuverability. Corporate account managers and government procurement teams favor this category for routine staff transport, with SAMA's Islamic leasing regulations expanding access among Sharia-sensitive clients.
- SUVs:Higher-ground-clearance vehicles suited to desert terrain and family mobility requirements. Domestic tourism operators and expatriate residents in Riyadh sustain elevated utilization rates, particularly during seasonal temperature extremes.
- Vans:Commercial cargo configurations serving last-mile logistics and construction crew transport.
- Luxury Cars:Premium-brand vehicles targeting diplomatic protocols and high-net-worth individual segments.
Sedans anchor fleet composition by unit count; SUVs are expanding most quickly through tourism infrastructure investments.
Customer Type:
Customer maturity levels vary sharply, with institutional procurement teams demanding integrated telematics reporting while individual renters prioritize price transparency and digital convenience.
- Corporate Clients:Structured fleet demand from logistics operators, construction firms, and energy sector contractors. NEOM and Red Sea Development project operators are consolidating vendor relationships around single-source contracts with unified billing and standardized GPS reporting requirements.
- Tourists:Inbound leisure and religious visitors accessing vehicles through airport counters and hotel partnerships. Jeddah's proximity to Makkah and Madinah generates concentrated seasonal demand spikes around Hajj and Ramadan periods.
- Government Agencies:Public sector procurement through centralized tendering processes and framework agreements.
- Individuals:Expatriate residents and Saudi nationals seeking personal mobility without ownership commitment.
Corporate clients command the deepest contract values; tourist segment volumes fluctuate most severely with pilgrimage calendars.
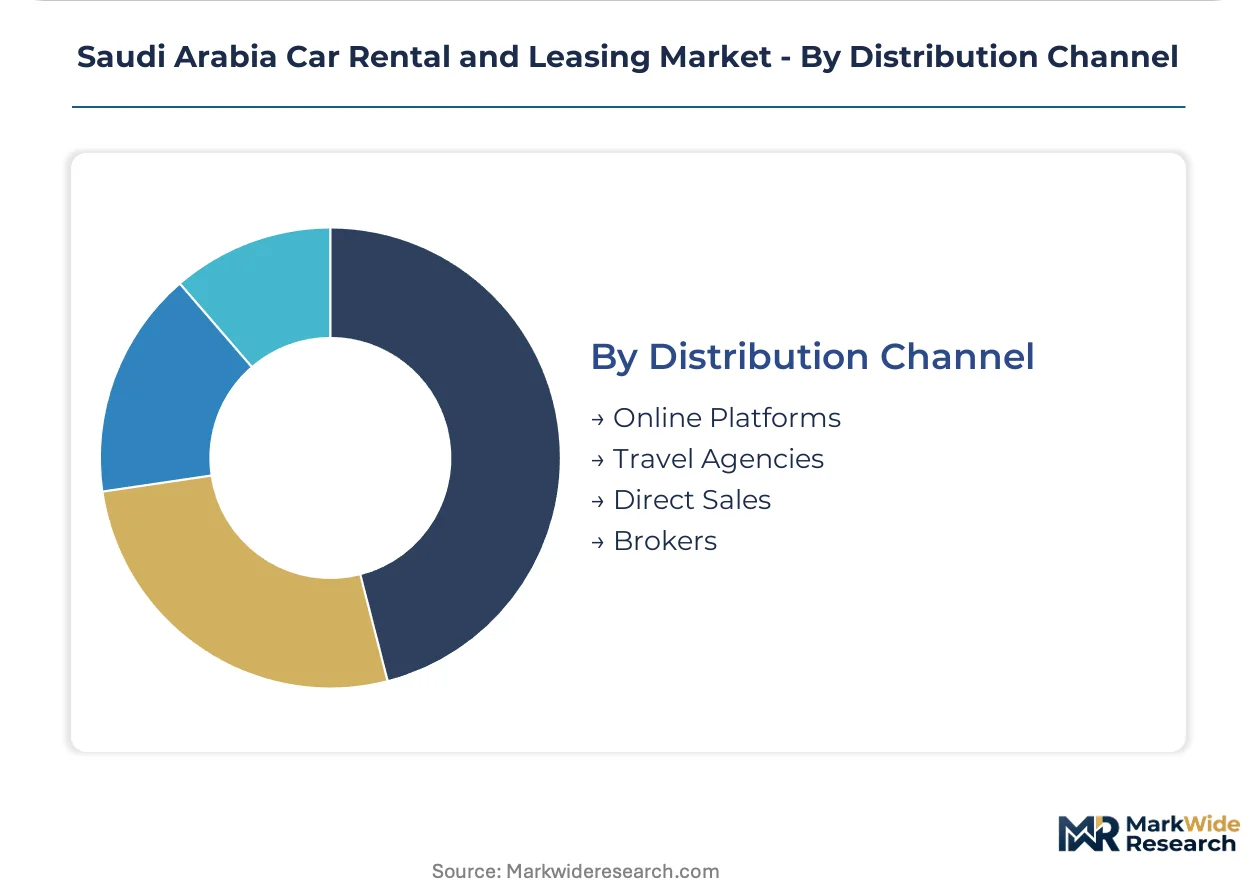
Distribution Channel:
Channel concentration reflects digital adoption gradients across customer demographics, with platform integration costs creating barriers for mid-size operators.
- Online Platforms:Direct booking engines and mobile applications with real-time availability and dynamic pricing. Corporate travel management platforms and mobility-as-a-service aggregators are forcing legacy reservation system upgrades.
- Travel Agencies:Intermediary bookings bundled with accommodation and flight packages. International tour operators serving European and Asian inbound markets maintain established relationships with Riyadh-based fleet operators.
- Direct Sales:Branch counter transactions and corporate account management teams.
- Brokers:Independent intermediaries matching fleet availability with specialized requirements.
Online platforms capture the steepest expansion trajectory; travel agencies retain strength in packaged pilgrimage tourism.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Expatriate logistics coordinators and construction project managers concentrate in Saudi Arabia's primary economic corridors, anchoring fleet demand across distinct operational zones with varying infrastructure maturity and regulatory exposure.
Riyadh
Government procurement teams and corporate headquarters clusters generate the densest long-term leasing contracts in the Kingdom. SAMA's Islamic leasing regulations enable Sharia-compliant fleet financing for public sector contractors headquartered here. King Abdullah Financial District and Diriyah Gate developments concentrate Vision 2030 project offices demanding telematics-enabled vehicle oversight.
Jeddah
Umrah pilgrimage flows and Red Sea tourism investments sustain the highest short-term rental transaction velocity nationwide. The Saudi Tourism Authority's licensing frameworks for transport operators shape fleet compliance requirements. King Abdulaziz International Airport and the Jeddah Islamic Port corridor anchor logistics contractor mobility needs.
Eastern Province
Aramco contractor ecosystems and petrochemical supply chain operators require specialized commercial vehicle leasing with hazardous materials transport certifications. The Ministry of Municipal and Rural Affairs regulates operating permits across Dammam, Khobar, and Jubail industrial zones. Ras Tanura and Jubail Industrial City concentrate energy sector fleet procurement.
NEOM Northwest
Mega-project construction camps and linear city infrastructure development generate demand for rugged-terrain vehicle fleets and crew transport solutions. NEOM's autonomous vehicle pilot programs and sustainability mandates reshape lessor asset specifications. The Oxagon and Trojena zones anchor early-phase contractor mobilization.
Asir and Tabuk
Domestic tourism expansion and agricultural logistics networks drive underpenetrated rental market development. The Saudi Energy Efficiency Center's regional green transport incentives support EV fleet pilot deployments. Abha Regional Airport and Tabuk's northern logistics corridor exhibit growing business travel volumes relative to available fleet infrastructure.
Saudi Arabia Car Rental and Leasing Market Competitive Landscape
Capital-heavy fleet owners compete with asset-light platform operators for customer relationships, creating a tiered structure where vehicle ownership scale separates market positions. The vendor base concentrates around three strategic archetypes: government-aligned lessors securing public sector framework agreements, airport-centric daily rental specialists optimizing utilization through location density, and commercial vehicle fleet managers serving logistics contractors with maintenance-inclusive contracts. Competitive moves center on telematics platform integration and secondary city branch expansion.
Within the government-contractor tier, Lumi Rental Co. and Hanco Automotive occupy positions shaped by public sector procurement relationships. Theeb Rent A Car exemplifies the domestic short-term specialist archetype, while international license holders including Hertz Corporation and Sixt SE represent the global brand positioning segment.
| Leading Market Players |
|---|
| Hanco Automotive |
| Lumi Rental Co. |
| Hertz Corporation |
| Key Car Rental |
| Sixt SE |
| Budget Rent-A-Car (United Intl. Transportation Co.) |
| Theeb Rent A Car |
| Strong Rent a Car |
| Avis Budget Group Inc. |
| Others |
Value Network & Pricing Analysis
Fully built-up vehicle import duties cascade through Saudi fleet procurement costs, compressing lessor margins on economy-tier daily rentals while premium long-term leases absorb tariff volatility through multi-year contract structures. SAMA's Islamic leasing regulations redistribute financing costs across Sharia-compliant Ijara structures, decoupling pricing tiers from conventional interest-rate exposure and enabling rate competition between Islamic banks and traditional lessors.
Pricing Analysis
Bundled maintenance-inclusive packages versus unbundled base-rate rentals split the Saudi market into divergent margin profiles. Three-tier pricing structure across premium, standard, and economy levels reflects telematics integration depth and residual risk allocation, with corporate fleet contracts commanding premium positioning through GPS-enabled utilization reporting. Price differentiation hinges on after-sales service bundling and certification tier—government framework agreements require SAMA-compliant financing structures that filter out non-Islamic operators. Pricing pressure stems from residual value volatility on internal combustion engine fleets as EV transition policies accelerate depreciation schedules. Budget tourists and pilgrimage segments exhibit highest price sensitivity, while NEOM contractors and Aramco suppliers prioritize total cost of ownership predictability over rate minimization.
Supply Chain Analysis
Seafreight costs from Japanese, South Korean, and German OEM assembly plants dominate landed vehicle costs for Saudi fleet operators, with Red Sea port congestion periodically amplifying inventory carrying expenses. Fleet procurement draws from fully built-up imports rather than local assembly, tethering lessor cost structures to customs tariff fluctuations and riyal-dollar exchange rate movements. Semiconductor shortages for telematics modules and advanced driver-assistance systems create single-source vulnerability through concentrated Tier 1 supplier relationships. Distribution runs through Riyadh and Jeddah hub-and-spoke networks, with secondary city coverage requiring expensive branch infrastructure or third-party agency partnerships that dilute margin capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi fleet operators face margin expansion through telematics-enabled utilization optimization and premium-tier corporate contract consolidation, with cost-down pressure from residual value risk transfer to OEM partners reshaping competitive economics.
For Market Incumbents: Extend telematics platform integration into predictive maintenance and dynamic pricing capabilities, consolidating fragmented corporate relationships around single-source fleet management contracts. Defend against asset-light mobility-as-a-service aggregators by anchoring government framework agreements through SAMA-compliant Ijara structures, while backward integration into captive maintenance facilities captures aftermarket revenue streams currently leaking to third-party service networks. For New Entrants and Emerging Players: AI-powered fleet optimization software offers entry wedge into mid-size logistics operators lacking in-house data science capabilities. Secondary city coverage gaps in Dammam, Abha, and Tabuk present penetrable white-space, particularly for EV fleet pilots leveraging Saudi Energy Efficiency Center incentives. Go-to-market positioning should emphasize maintenance-inclusive total cost of ownership guarantees rather than competing on headline daily rates. For Investors and Strategic Acquirers: Consolidation pressure builds where telematics talent scarcity and legacy system replacement costs strand sub-scale operators without platform integration capabilities. Long-term viability favors lessors with government contracting relationships and Islamic financing licensing that insulates from conventional credit cycle exposure. Acquisition target archetype: regional specialists with dense secondary city branch networks and untapped corporate account pipelines. Signal to watch: NEOM autonomous vehicle pilot procurement decisions that will reshape fleet specification requirements across Vision 2030 contractor ecosystems.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | GPS-enabled utilization reporting satisfies SAMA procurement mandates for government contractors. |
| Islamic Leasing License Acquisition | Ijara structuring capability unlocks public sector framework agreements previously closed to conventional lessors. |
| EV Fleet Pilot Deployment | Saudi Energy Efficiency Center incentives offset charging infrastructure gaps in Riyadh-Jeddah corridors. |
| Secondary City Branch Expansion | Abha and Tabuk underpenetration relative to domestic tourism growth creates first-mover positioning. |
| Predictive Maintenance Software Development | AI-driven service scheduling addresses corporate procurement teams' total cost of ownership priorities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with fleet operations directors, SAMA regulatory affairs specialists, corporate procurement managers at logistics and construction firms, and telematics platform engineers with secondary validation through customs import data, Saudi Central Bank consumer finance disclosures, vehicle registration databases, and Vision 2030 project procurement announcements. Bottom-up fleet size estimates and top-down market sizing approaches triangulated to constrain projection variance.
Comparable historical periods anchored the forecast window against pre-pandemic utilization baselines and post-recovery contract restructuring patterns. Segmentation modeling spanned service type, vehicle class, customer archetype, and distribution channel dimensions, with propulsion architecture and telematics integration depth added as industry-specific forecast inputs. CAGRs derived from trend extrapolation moderated by regulatory inflection points and infrastructure buildout schedules.
The model holds under stable customs tariff regimes and sustained Vision 2030 capital deployment; deviation in EV mandate acceleration or riyal exchange rate volatility would shift fleet procurement timelines and lessor profitability assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Vehicle Radiator Market
Vehicle Components
Global Motorcycle Chain Sprocket Market
Vehicle Components
Wheel Speed Sensor Market
Vehicle Components
Global Car Accessories Market
Vehicle Components
Air Suspension Market
Vehicle Components
Steering Tie Rod Market
Vehicle Components
Grille Guard Market
Vehicle Components
Steering Column Cowls Market
Vehicle Components
Tow Tractor Market
Vehicle Components
Bicycle Chain Tensioner Market
Vehicle Components
Italy Automotive Composites Market
Vehicle Components
Asia-Pacific Industrial Brakes Market
Vehicle Components
Portable Truck Access System Market
Vehicle Components
Gas Station Equipment Market
Vehicle Components
South Africa Automotive Thermoplastic Polymer Composites Market
Vehicle Components
GCC Automotive Connectors Market