
 Terminal Tractors Market | 2026-2036
Terminal Tractors Market Size, Share, and Industry Trends Forecast 2026-2036
Terminal Tractors Market Analysis
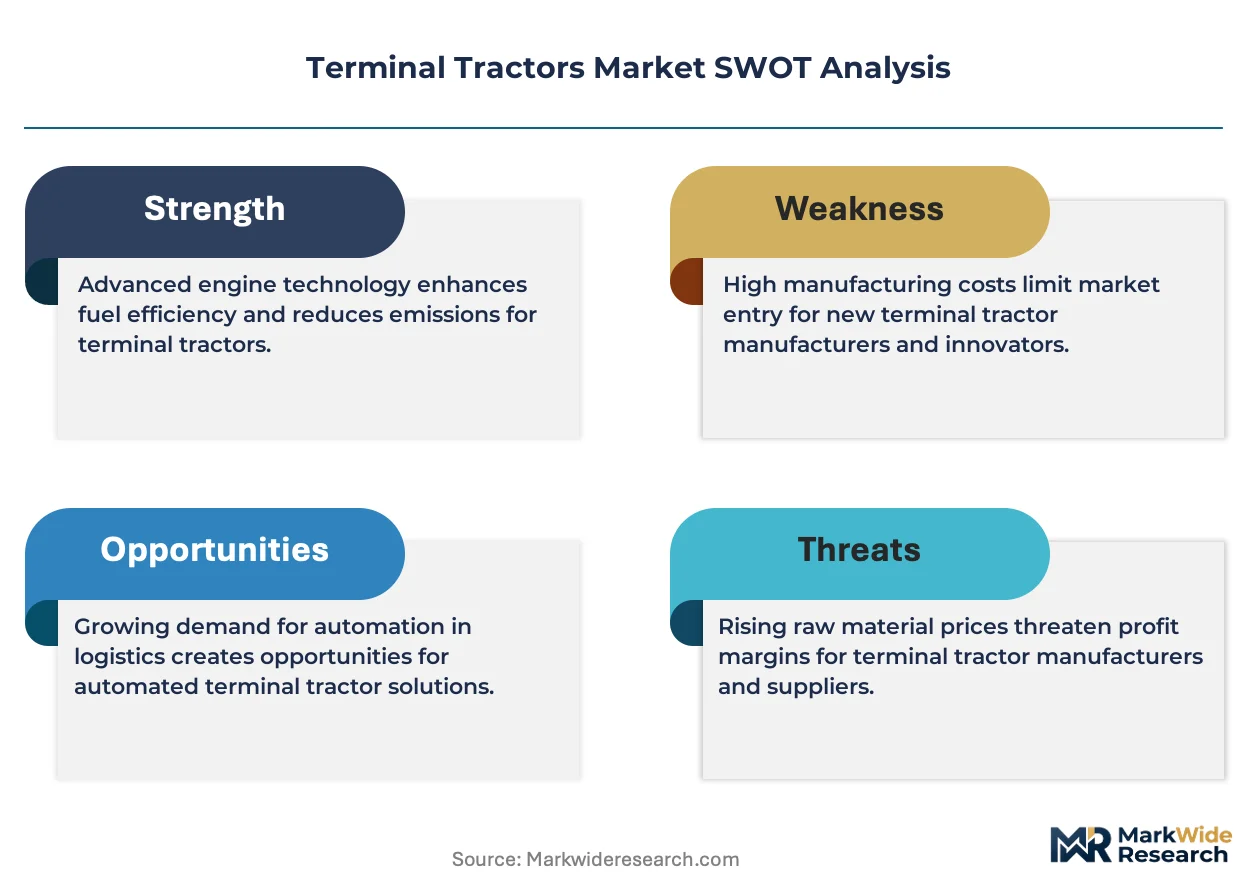
Buyer concentration at major container ports is decoupling from traditional equipment procurement patterns as independent logistics providers gain yard-handling contracts. Kalmar leverages its port automation integration to sustain long-term service agreements with terminal operators. Terberg Special Vehicles anchors European electric traction development through dedicated low-emission product lines. Capacity Trucks competes aggressively on North American manufacturing scale and rapid custom-build turnaround.
Terminal tractors are heavy-duty, low-speed vehicles engineered for horizontal cargo movement within confined port, distribution, and industrial yard environments, typically rated at drawbar pull capacities exceeding 50,000 pounds and designed for continuous duty cycles exceeding 20 hours daily. Their primary function involves repositioning semi-trailers and container chassis between gate, storage, and vessel loading zones without over-the-road licensing requirements. Electric product types now command the fastest expansion trajectory as battery energy density improvements enable single-shift operation without opportunity charging, while diesel variants retain dominance in heavy-load transport applications exceeding 50 tons where charging infrastructure remains undeveloped. Logistics providers represent the most fragmented and fastest-growing end-user category as e-commerce fulfillment networks decentralize inland container handling away from traditional port boundaries.
EPA Tier 4 Final and upcoming California Air Resources Board off-road regulations are accelerating electric and hybrid terminal tractor qualification programs, while EU Green Deal emissions benchmarks under REACH compliance frameworks reshape European procurement specifications toward lifecycle carbon accounting. OSHA and ISO 3691-4 safety standards govern autonomous operation trials, creating compliance complexity for ports piloting driverless yard movements. Stakeholders must monitor regulatory divergence between zero-emission mandates and charging infrastructure deployment timelines to align capital commitments with operational readiness.
Market Dynamics
Electric traction systems are restructuring capital deployment patterns as port operators confront phased zero-emission mandates without matching charging infrastructure rollout schedules. Battery-electric terminal tractors now dominate qualification programs, yet diesel variants retain operational relevance in heavy-load corridors where grid capacity lags regulatory deadlines.
Growth Catalysts
- EPA Tier 4 Final compliance deadlines:Off-road diesel equipment emissions standards are accelerating fleet replacement cycles at US container terminals, compressing procurement timelines for cleaner alternatives.
- Battery energy density improvements:Lithium-ion cell chemistry advances now enable single-shift electric operation without opportunity charging, eliminating prior productivity penalties.
- California port cluster mandates:Long Beach and Los Angeles terminal operators face the strictest zero-emission equipment requirements, creating concentrated demand pull for electric variants.
Market Restraints
- Charging infrastructure capital requirements:Megawatt-scale shore power installations at marine terminals demand grid interconnection upgrades that outpace utility approval timelines.
- Heavy-load diesel dependence:Container chassis exceeding 50 tons drawbar pull requirements exceed current electric motor and battery thermal management capabilities.
- REACH lifecycle carbon accounting:European procurement specifications now penalize equipment with embedded carbon footprints that favor regional manufacturing over imports.
Strategic Opportunities
- India port modernization:Sagarmala infrastructure investments are expanding container handling capacity at Jawaharlal Nehru Port and Mundra, creating first-mover positioning for electric fleet suppliers.
- Autonomous yard operation trials:ISO 3691-4 safety standard compliance is enabling pilot programs for driverless terminal tractors in closed-loop environments.
- Logistics provider channel expansion:E-commerce fulfillment networks are decentralizing inland container handling, fragmenting buyer concentration away from traditional port operators.
Industry Challenges
- Technician skill gaps:High-voltage battery system diagnostics and thermal management repair capabilities remain scarce in port maintenance workforces.
- Regulatory divergence complexity:Misaligned zero-emission mandate timelines between EPA, California Air Resources Board, and EU Green Deal frameworks complicate multi-jurisdictional fleet standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Terminal Tractors Market |
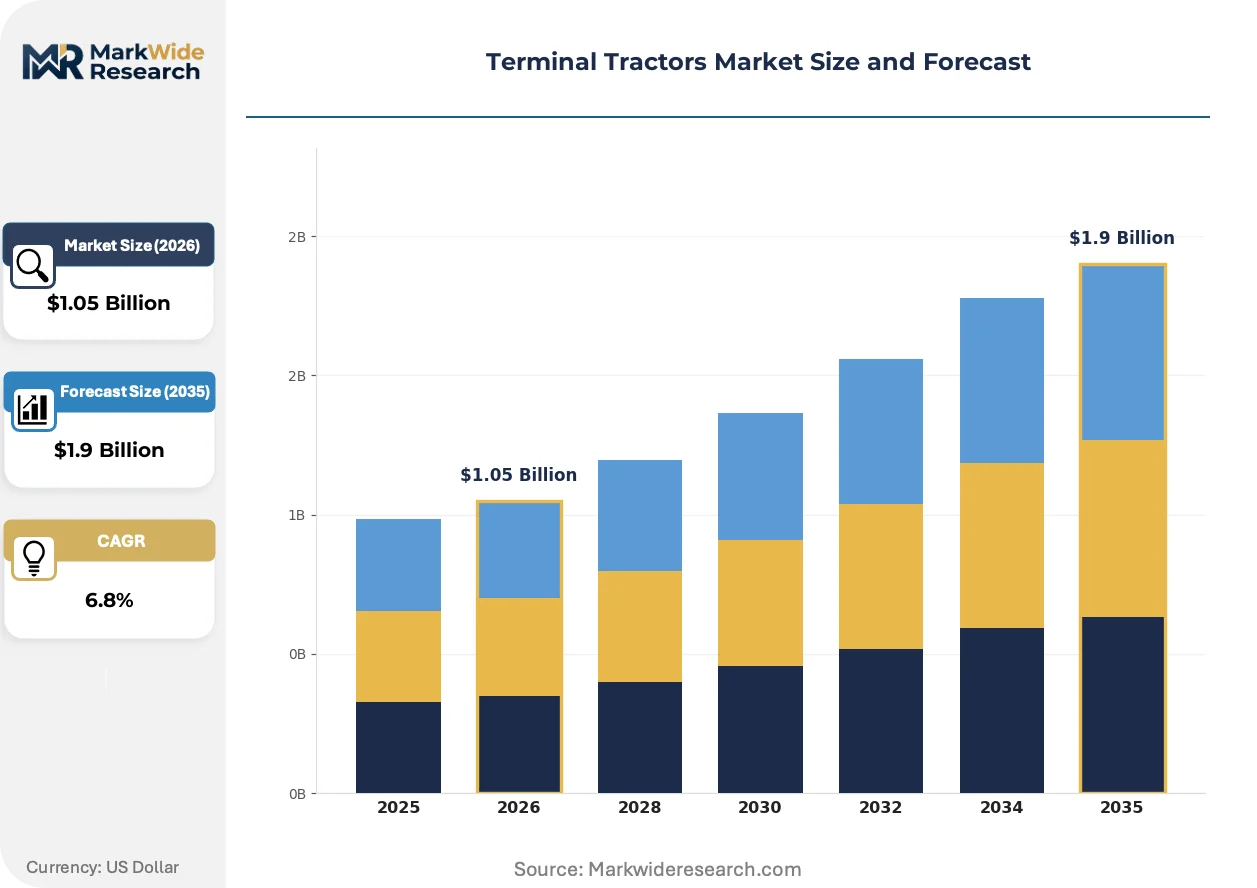
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.9 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Diesel, Hybrid, LPG End User: Logistics Providers, Ports, Distribution Centers, Manufacturing Facilities Handling Capacity: Under 15 Tons, 15-30 Tons, 30-50 Tons, Over 50 Tons Application: Container Handling, Yard Operations, Cross-Docking, Heavy Load Transport |
| Companies Covered | Kalmar, Terberg Special Vehicles, Capacity Trucks, TICO Tractors, MAFI Transport-Systeme GmbH, Konecranes, Hyster-Yale Group, Autocar, CVS Ferrari, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Terminal Tractors Market Emerging Trajectories
Electrification and automation are converging to redefine yard equipment economics, shifting competitive advantage from engine performance to software-integrated energy management and predictive maintenance capabilities.
Lithium iron phosphate battery chemistry is absorbing thermal stability requirements for continuous-duty port operations while reducing cobalt supply chain exposure. Third-party logistics operators at Rotterdam and Hamburg terminals are adopting this chemistry fastest, drawn by fire safety ratings that satisfy insurer requirements. The technology is absorbing capital that previously flowed to diesel hybrid alternatives, compressing the addressable market for transitional powertrains.
EU Green Deal emissions benchmarks under REACH compliance frameworks are reshaping European procurement specifications toward lifecycle carbon accounting rather than tailpipe metrics alone. Equipment financiers now embed carbon intensity scores into lease pricing structures. Heavy-load transport applications exceeding 40 tons drawbar pull face the steepest cost adjustments, redirecting demand toward lighter container configurations.
Service contract unbundling is fragmenting traditional manufacturer-captive maintenance relationships at North American ports. Independent service providers with high-voltage certification are capturing preventive maintenance volumes that OEMs previously retained. California's port cluster exhibits this pattern most acutely, where specialized battery technicians command premium labor rates that alter total cost of ownership calculations.
Terminal Tractors Market Segmentation
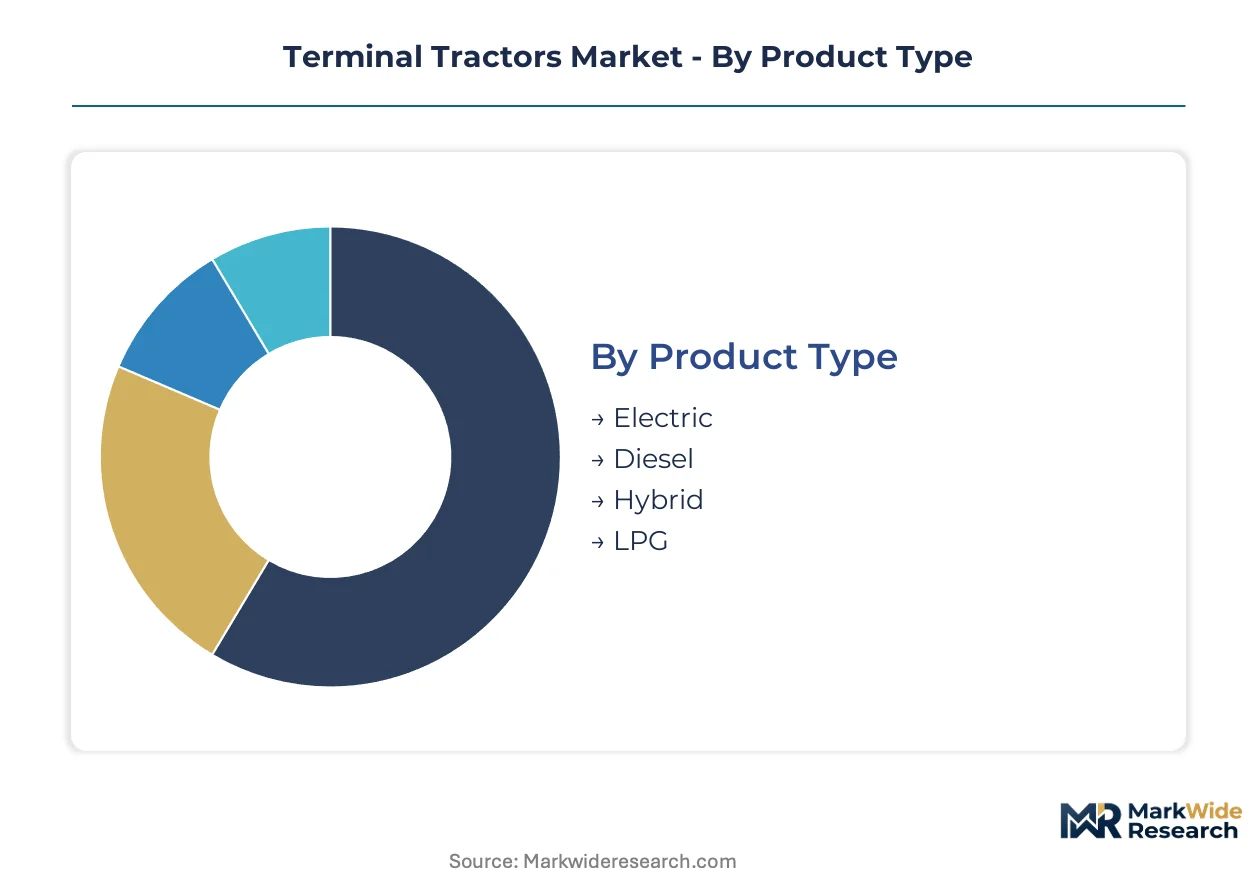
Segmentation in terminal tractors reveals how regulatory pressure and operational intensity fragment demand across powertrain technologies and load specifications. Procurement patterns diverge sharply between port operators facing zero-emission mandates and inland logistics providers prioritizing acquisition cost over compliance.
Product Type:
Supply concentration tilts toward electric traction as battery pack manufacturers scale lithium iron phosphate production for port duty cycles.
- Electric:Battery-electric terminal tractors deploy lithium-ion packs with energy densities now supporting single-shift operation without opportunity charging. California's Long Beach and Los Angeles port cluster drives concentrated demand as CARB mandates eliminate diesel alternatives for yard operations. The technology commands the steepest expansion trajectory across all powertrain categories.
- Diesel:Compression-ignition engines rated for Tier 4 Final compliance retain dominance in heavy-load corridors exceeding 50 tons where grid interconnection lags regulatory deadlines. EPA enforcement at US Gulf Coast and Southeast Atlantic terminals sustains replacement demand despite electrification pressure.
- Hybrid:Diesel-electric architectures blend combustion range with electric yard maneuvering, finding niche adoption at mid-size ports with intermittent heavy-load requirements.
- LPG:Propane-fueled variants serve transitional procurement at facilities with existing fueling infrastructure and moderate load demands below 30 tons.
Today's leader: Diesel. Tomorrow's challenger: Electric.
End User:
Customer type determines contract structure, with port operators favoring long-term service agreements while logistics providers prioritize capital flexibility.
- Logistics Providers:Third-party operators at e-commerce fulfillment networks and inland container depots represent the most fragmented demand pool. Decentralized yard handling away from traditional port boundaries accelerates procurement fragmentation across North American and European distribution corridors.
- Ports:Marine terminal operators concentrate buying power through fleet-scale electrification programs tied to zero-emission mandates. California, Rotterdam, and Hamburg exhibit the most advanced qualification timelines.
- Distribution Centers:Retail and wholesale fulfillment facilities deploy terminal tractors for cross-dock trailer repositioning, with demand scaling alongside warehouse automation investments.
- Manufacturing Facilities:Automotive and heavy equipment plants utilize yard tractors for inbound parts and outbound finished goods movement, favoring diesel variants for all-weather reliability.
Volume concentrates with Ports. Growth velocity favors Logistics Providers.
Handling Capacity:
Load specification directly determines powertrain feasibility, with thermal management constraints creating a hard ceiling for electric traction at upper weight tiers.
- Under 15 Tons:Light-duty chassis repositioning at distribution centers and manufacturing yards suits battery-electric operation with minimal cooling requirements. European logistics hubs adopt this segment fastest under EU Green Deal procurement specifications.
- 15-30 Tons:Standard container chassis handling represents the volume core of terminal tractor demand, with electric variants now achieving cost parity on total ownership metrics at California ports.
- 30-50 Tons:Heavy container configurations and loaded chassis push electric motor thermal limits, sustaining diesel hybrid interest at facilities with mixed load profiles.
- Over 50 Tons:Maximum drawbar pull applications exceed current battery and motor capabilities, preserving diesel dominance in specialized heavy-load transport corridors.
Mid-range capacity commands current investment. Extreme loads resist electrification.
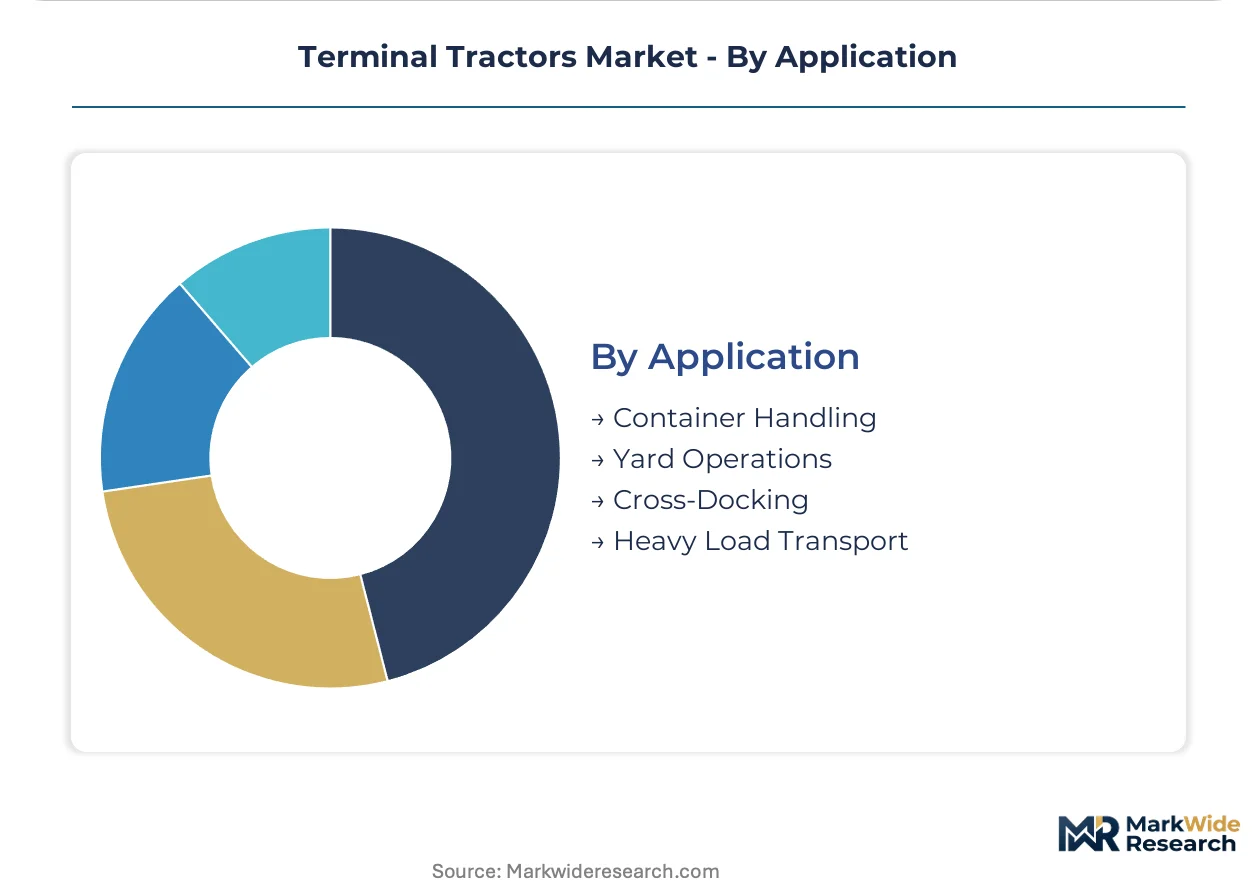
Application:
Operational intensity and duty cycle predictability shape equipment specification, with continuous-use applications justifying higher capital expenditure for electric traction.
- Container Handling:Vessel-to-gate chassis movement at marine terminals demands 20-plus hour daily duty cycles, favoring electric variants where charging infrastructure supports opportunity charging during vessel berthing intervals.
- Yard Operations:Storage zone repositioning and chassis stacking require precise low-speed maneuvering, applications where electric motor torque characteristics outperform diesel responsiveness.
- Cross-Docking:Rapid trailer transfer at distribution facilities prioritizes uptime reliability over emissions profile, sustaining diesel preference at inland facilities without grid investment.
- Heavy Load Transport:Specialized chassis and oversized container movement exceeding standard weight ratings retains diesel dependence due to traction motor thermal constraints.
Yard Operations lead electric penetration. Heavy Load Transport remains diesel-captive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys stricter EPA enforcement than Germany applies EU Green Deal benchmarks, yet both jurisdictions accelerate electric terminal tractor procurement through diverging regulatory mechanisms. China and India expand container handling capacity faster than charging infrastructure deployment, creating procurement timing mismatches. Brazil's port privatization programs attract equipment financing that European lenders now condition on lifecycle carbon disclosures.
United States
California's Long Beach and Los Angeles port cluster drives concentrated electric fleet demand as CARB mandates eliminate diesel alternatives for yard operations. EPA Tier 4 Final compliance deadlines compress procurement timelines at Gulf Coast and Southeast Atlantic terminals. The Pacific Northwest ports of Seattle and Tacoma pilot autonomous yard operation trials under OSHA and ISO 3691-4 safety frameworks.
Germany
Hamburg and Bremerhaven terminal operators qualify battery-electric tractors under REACH lifecycle carbon accounting specifications that penalize embedded manufacturing footprints. EU Green Deal emissions benchmarks reshape procurement toward regional manufacturing over imports. The country's national automotive regulator KBA oversees type-approval processes for autonomous operation permits in closed-loop port environments.
China
Ningbo-Zhoushan and Shanghai port authorities expand container throughput capacity under national dual carbon goals that mandate equipment electrification timelines. The Ministry of Ecology and Environment (MEE) enforces GB standards for off-road diesel emissions that accelerate fleet replacement cycles. Yangtze River Delta ports concentrate demand for heavy-load diesel variants where grid interconnection lags regulatory deadlines.
India
Jawaharlal Nehru Port and Mundra terminal operators modernize yard handling capacity through Sagarmala infrastructure investments that create first-mover positioning for electric fleet suppliers. The Central Electricity Authority (CEA) coordinates grid upgrade approvals that outpace port electrification procurement schedules. Gujarat and Maharashtra port clusters exhibit the fastest equipment demand expansion across South Asian container handling facilities.
Brazil
Santos and Paranaguá port privatization programs attract international equipment financiers that now embed carbon intensity scores into lease pricing structures. ANVISA, the national health and industrial regulator, oversees occupational safety standards for yard equipment operation. São Paulo state logistics corridors sustain diesel tractor demand where charging infrastructure deployment remains underdeveloped.
Terminal Tractors Market Vendor Landscape
European producers anchor one tier; North American specialists hold manufacturing scale advantages in rapid custom-build turnaround. The vendor base consolidates around port automation integrators, dedicated low-emission product line developers, and high-volume fabricators with flexible configuration capabilities. Three archetypes dominate: automation-integrated solution providers, electric traction technology specialists, and scale-driven manufacturing houses. Competitive moves concentrate on strategic partnerships for charging infrastructure bundling and geographic expansion into Indian port modernization programs.
Within the automation-integrated tier, Kalmar and Konecranes represent port equipment conglomerates that sustain long-term service agreements through yard automation system integration. Terberg Special Vehicles, a Dutch specialist, exemplifies dedicated electric traction development through low-emission product line concentration. Among North American fabricators, Capacity Trucks and TICO Tractors occupy positions that compete on manufacturing scale and rapid custom-build turnaround for regional port operators.
| Leading Market Players |
|---|
| Kalmar |
| Terberg Special Vehicles |
| Capacity Trucks |
| TICO Tractors |
| MAFI Transport-Systeme GmbH |
| Konecranes |
| Hyster-Yale Group |
| Autocar |
| CVS Ferrari |
| Others |
Supply Flow & Price Mechanics
Battery chemistry standardization around lithium iron phosphate is compressing cost curves while concentrating procurement leverage among pack manufacturers serving port duty cycles. This technology transition simultaneously reduces cobalt supply chain exposure and shifts pricing power toward vertically integrated cell producers with captive cathode material sourcing.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for battery-electric terminal tractors as cell oversupply runs through the heavy-duty vehicle tier. Three-tier pricing structure across premium automation-integrated, standard electric, and economy diesel-retrofit levels separates Kalmar and Konecranes service-bundled offerings from Terberg's dedicated low-emission lines and Capacity Trucks' rapid-turn fabrications. Cost compression in the standard electric tier is intensifying because lithium iron phosphate cell prices have fallen faster than charging infrastructure capital can be amortized. Logistics providers at inland container depots exhibit the highest price sensitivity, while marine terminal operators facing CARB mandates accept premium positioning for zero-emission qualification.
Supply Chain Analysis
Regional distribution centers for battery pack assembly concentrate in China, South Korea, and Germany, with hub-and-spoke patterns feeding port equipment fabricators in North America and Europe. Cell production draws from Chilean lithium, Indonesian nickel, and Chinese graphite processing, creating geographic concentration risk at multiple refining stages. Single-source vulnerability for high-voltage inverter modules sourced from German and Japanese automotive Tier 1s presents the most acute supply chain risk for electric terminal tractor production. Distribution runs through OEM-captive service networks at major port clusters, though independent high-voltage certified providers are fragmenting aftermarket parts flows in California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The terminal tractors market compounds steadily as port electrification mandates create predictable replacement cycles across major container handling facilities worldwide. Regulatory compliance deadlines provide demand visibility that supports long-dated capital commitments from operators and suppliers alike.
For Market Incumbents: Acquire high-voltage battery diagnostics capabilities to defend service contract retention against independent providers capturing California preventive maintenance volumes. Consolidate charging infrastructure partnerships at Gulf Coast and Southeast Atlantic terminals before EPA Tier 4 Final deadlines compress procurement timelines. Backward integration into lithium iron phosphate pack assembly insulates margin structures from cell price volatility while satisfying REACH lifecycle carbon accounting for European port tenders.
For New Entrants and Emerging Players: Digital-channel routes through third-party logistics operator procurement platforms offer the lowest friction entry path for electric terminal tractor qualification. Target India's Jawaharlal Nehru Port and Mundra modernization programs where Sagarmala infrastructure investments outpace established supplier relationships. Position around rapid-charging interoperability as the primary go-to-market angle, leveraging CEA grid coordination delays to capture first-mover positioning before incumbent charging bundling solidifies.
For Investors and Strategic Acquirers: Roll-up economics work for independent high-voltage service specialists because technician certification scarcity creates local monopoly pricing power at California and Rotterdam port clusters. The terminal tractors segment offers five-to-ten year visibility through mandate-driven replacement cycles rather than discretionary capital expenditure volatility. Watch for CARB zero-emission deadline acceleration as the signal indicating whether electric penetration timelines compress ahead of charging infrastructure readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Megawatt-scale shore power bundling with CEA grid approvals secures port operator lock-in at Indian terminals. |
| High-Voltage Service Network Acquisition | Independent battery technician certification captures preventive maintenance volumes OEMs previously retained in California. |
| Lithium Iron Phosphate Supply Agreement | Cathode chemistry standardization reduces thermal management costs while satisfying EU Green Deal lifecycle requirements. |
| Autonomous Yard Operation Pilot | ISO 3691-4 compliance trials at Pacific Northwest ports establish regulatory pathway for driverless deployment. |
| Backward Integration into Pack Assembly | In-house battery integration insulates margin structures from cell price volatility and REACH carbon accounting penalties. |
Methodological Framework
Direct dialogue with terminal operations managers, fleet procurement directors, high-voltage maintenance technicians, port authority environmental compliance officers, and battery system integration engineers grounded qualitative findings. Secondary validation drew from EPA enforcement notices, CARB regulatory filings, EU Green Deal implementation documents, Sagarmala infrastructure progress reports, and customs trade data for yard equipment imports. Bottom-up equipment deployment estimates triangulated against top-down port throughput capacity projections across the analysis window.
Segmentation outputs reflect powertrain technology, handling capacity tier, end-user archetype, and regional regulatory cluster as the core modeling dimensions throughout the projection horizon. CAGRs were derived from equipment replacement cycle analysis weighted by mandate compliance deadlines and infrastructure deployment readiness. Forecast inputs incorporated battery energy density improvement curves, grid interconnection approval timelines, and autonomous operation regulatory pathway progression.
The model assumes a particular technology adoption path; alternative pathways for hydrogen fuel cell terminal tractors would alter the outlook if electrolyzer cost curves compress faster than battery pack economics. Forecasts reflect documented assumptions around charging infrastructure capital availability and utility approval timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Project Logistics Market
Logistics and Shipping
UK Freight Forwarding Market
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
Saudi Arabia Integrated Cold Chain Logistics Market
Logistics and Shipping
Latin America Freight Forwarding Market
Logistics and Shipping
Internet of Things (IoT) in Logistics Market
Logistics and Shipping
Middle East and Africa Freight & Logistics Market
Logistics and Shipping
Latin America Contract Logistics Market
Logistics and Shipping
ASEAN Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Vietnam Freight and Logistics Market
Logistics and Shipping
North America Last Mile Delivery Market
Logistics and Shipping
China Same Day Delivery Market
Logistics and Shipping
Repositioning and Offloading Market
Logistics and Shipping
China Freight and Logistics Market
Logistics and Shipping
Europe Automotive Logistics Market
Logistics and Shipping
Intralogistics Containers Market