
 Charge Air Coolers Market | 2026-2036
Charge Air Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
Charge Air Coolers Market Outlook
The capital-intensity divergence between integrated heat exchanger specialists and component assemblers is collapsing as bar-plate manufacturing and vacuum brazing capabilities become table stakes. MAHLE GmbH leverages captive aluminum foundry capacity to control raw material flow from ingot to finished core. Valeo SA sustains R&D intensity across air-to-water architectures for hybrid powertrains. Dana Incorporated anchors North American commercial vehicle demand through direct OEM supply agreements.
Charge air coolers are heat exchangers that reduce compressed air temperature between the turbocharger and engine intake manifold, typically constructed from aluminum alloy tubes and fins with operating pressure ratings exceeding 3.5 bar to prevent detonation and enable higher charge densities. Air-to-water configurations now lead product type evolution because water's superior heat capacity permits more compact packaging for downsized engines. Aluminum dominates material selection for cost-weight balance, though stainless steel gains traction in marine applications where salt corrosion degrades standard alloys. The aftermarket supplier channel shows structural expansion potential as turbocharger penetration in aging vehicle fleets extends replacement cycles.
EPA emission standards in the United States, Euro 7 regulations across European Union member states, and China's Stage VI standards administered by MEE collectively mandate tighter NOx control that forces OEMs toward higher boost pressures and thus larger, more efficient cooling surfaces. OEMs must certify charge air cooler thermal effectiveness as part of whole-engine type approval, creating compliance barriers for unvalidated suppliers. Stakeholders should monitor how electrification timelines reshape turbocharger deployment strategies across passenger and commercial vehicle portfolios.
Market Dynamics
Turbocharger penetration in downsized gasoline and diesel powertrains is forcing thermal management system redesigns across OEM engineering departments. Euro 7 emission standards and EPA Tier 3 compliance timelines are compressing development cycles for charge air cooler suppliers.
Growth Catalysts
- Euro 7 Standards:The European Union's tightened NOx limits mandate higher boost pressures, expanding aluminum heat exchanger surface area requirements in Stuttgart and Wolfsburg engineering centers.
- Air-to-Water Architecture:Water's superior heat capacity enables packaging density gains for hybrid powertrain compartments, accelerating adoption in German passenger vehicle platforms.
- China Stage VI:MEE-administered emission rules in Beijing and Shanghai are extending turbocharger deployment to domestic commercial vehicle fleets, creating incremental cooler demand.
Market Restraints
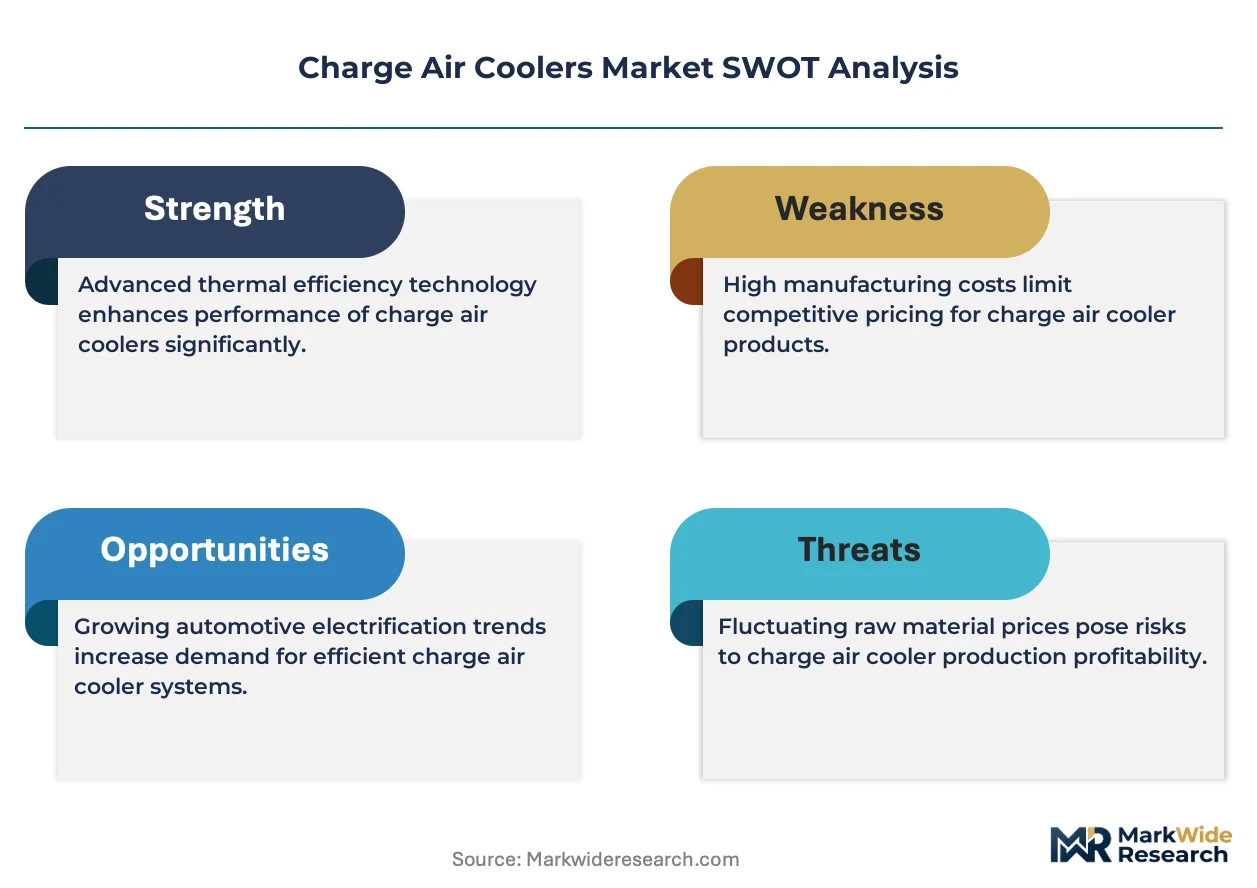
- Aluminum Price Volatility:LME aluminum ingot fluctuations compress margin buffers for vacuum brazing specialists without captive foundry operations.
- Brazing Equipment Concentration:Vacuum furnace manufacturing concentrates among German and Austrian capital equipment suppliers, creating capex bottlenecks for new market entrants.
- Electric Powertrain Substitution:Battery-electric vehicle deployment in Norwegian and Dutch markets eliminates turbocharger-dependent thermal management systems entirely.
Strategic Opportunities
- India Commercial Vehicle Fleet:BIS emission timelines and Delhi-Mumbai industrial corridor freight expansion create underpenetrated demand for bar-plate cooler architectures.
- Marine Salt Corrosion Segment:Stainless steel core configurations for Baltic and North Sea vessel operators command premium positioning above standard aluminum offerings.
- Aftermarket Channel Digitization:Direct-to-fleet e-procurement platforms for aging European turbocharged vehicle pools compress replacement cycle intermediation.
Industry Challenges
- Vacuum Brazing Technician Scarcity:Specialized aluminum alloy joining expertise concentrates in Swabian and Upper Austrian industrial clusters, constraining production scaling.
- OEM Thermal Validation Timelines:Whole-engine type approval certification cycles for EPA and KBA compliance extend eighteen to twenty-four months, freezing design specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Charge Air Coolers Market |
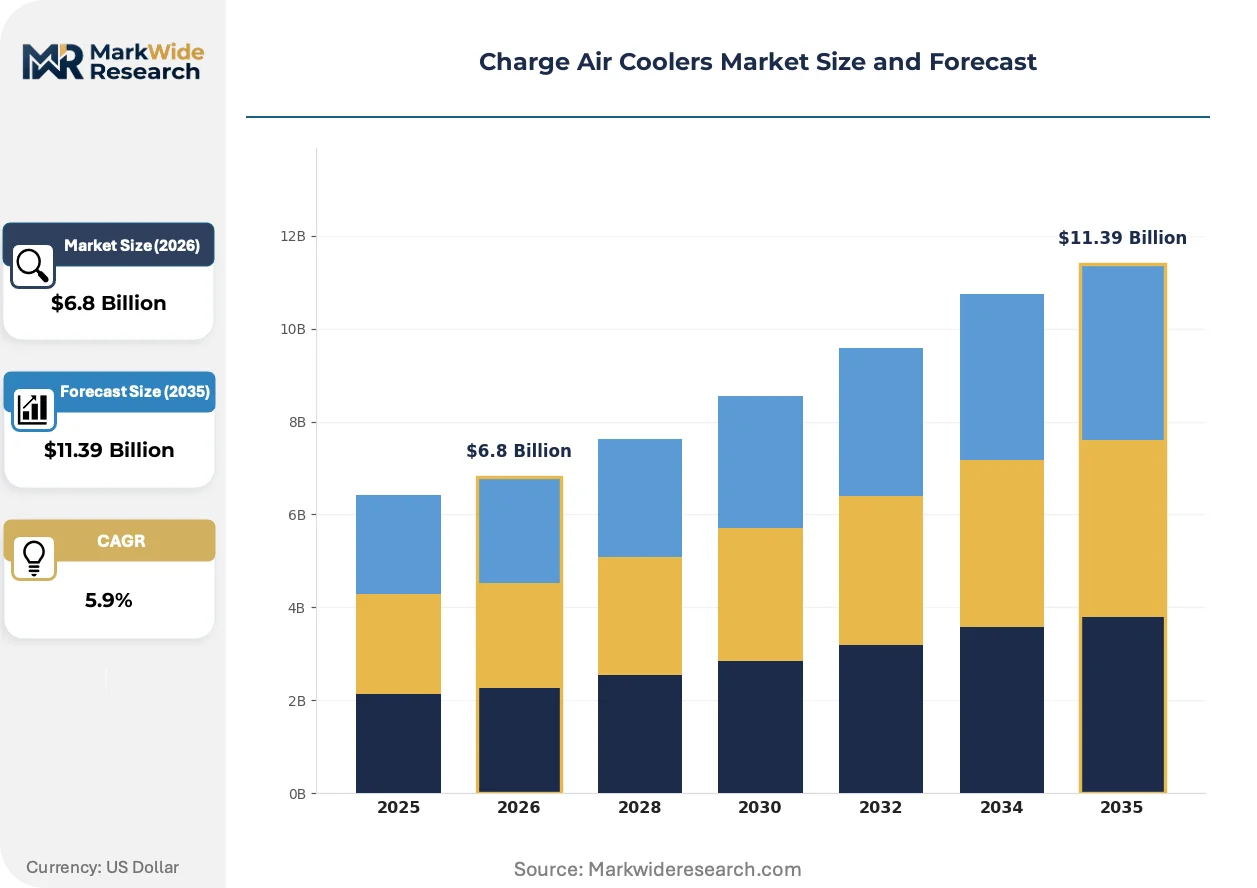
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-to-Air, Air-to-Water, Liquid-to-Air, Liquid-to-Water Material: Aluminum, Copper, Stainless Steel, Composites Application: Automotive, Commercial Vehicles, Heavy Machinery, Marine End User: OEMs, Aftermarket Suppliers, Dealerships, Maintenance Providers |
| Companies Covered | MAHLE GmbH, Valeo SA, Dana Incorporated, Modine Manufacturing Company, T.RAD Co., Ltd., Denso Corporation, Hanon Systems, BorgWarner Inc., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Charge Air Coolers Market Strategic Shifts
Material science advances and regulatory calibration requirements are restructuring competitive capability requirements across the charge air cooler supply base. Product evolution now centers on thermal effectiveness per unit volume rather than absolute cooling capacity.
Air-to-water charge air coolers is supplanting traditional air-to-air configurations in European hybrid powertrain programs. Stuttgart-based OEM thermal engineering teams are specifying water-cooled architectures for compact transverse engine bays. The technology is supplanting legacy fin-and-tube designs by enabling charge temperatures below forty degrees Celsius in packaging volumes reduced by sixty percent.
EPA Tier 3 and Euro 7 harmonization efforts are converging test protocols for thermal effectiveness verification across Atlantic regulatory jurisdictions. OEM powertrain certification departments must now submit identical cooler performance datasets to NHTSA and KBA authorities. Commercial vehicle segments in Michigan and Lower Saxony face the steepest compliance cost escalation as dual-jurisdiction validation becomes mandatory.
Fleet procurement departments are consolidating supplier relationships around thermal system integrators capable of simultaneous intercooler and radiator program management. Direct OEM contracting is replacing tier-two module supplier intermediation in North American and German commercial vehicle channels. This concentration pattern is most visible in long-haul freight operators across the I-75 corridor and Rhine-Ruhr logistics hubs.
Charge Air Coolers Market Segmentation
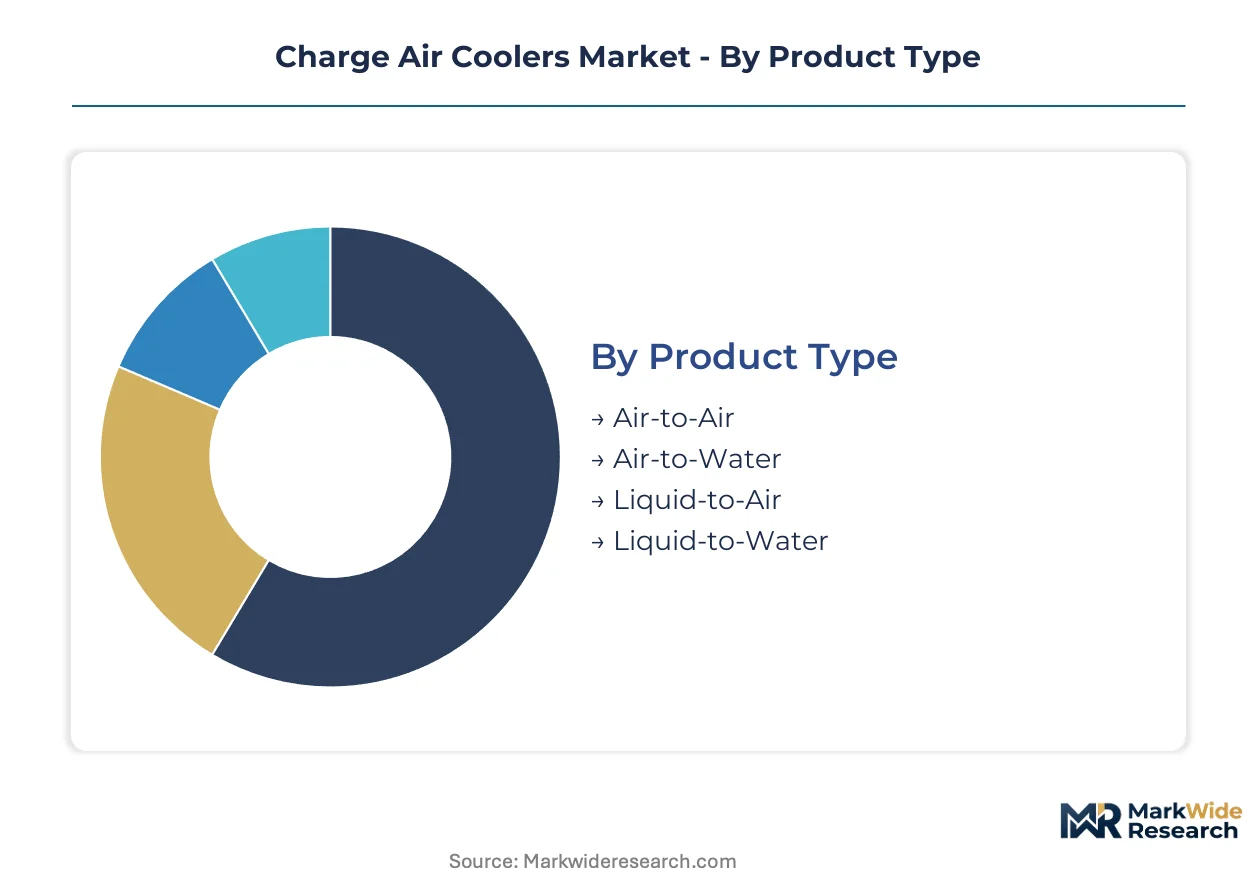
Charge air cooler procurement decisions diverge sharply across thermal system architectures, with regulatory pressure on NOx emissions forcing OEMs to match specific cooler types to powertrain packaging constraints. Material selection and distribution channel strategy further stratify supplier relationships based on fleet scale and replacement cycle predictability.
Product Type:
Euro 7 and EPA Tier 3 standards differentiate cooler architectures by thermal effectiveness thresholds and packaging density requirements.
- Air-to-Air:Traditional fin-and-tube aluminum constructions dominate legacy commercial vehicle platforms across Michigan and Lower Saxony freight corridors. Stuttgart engineering centers specify these for cost-sensitive long-haul applications where underhood volume permits larger frontal area.
- Air-to-Water:Water's superior heat capacity enables sixty percent packaging volume reduction for hybrid powertrain compartments. Wolfsburg-based OEM thermal teams specify these architectures for compact transverse engine bays requiring charge temperatures below forty degrees Celsius.
- Liquid-to-Air:Secondary cooling loops for high-performance diesel applications in German premium passenger segments.
- Liquid-to-Water:Emerging dual-loop configurations for next-generation electrified turbocharging systems.
Established volume favors Air-to-Air; emerging adoption favors Air-to-Water.
Material:
Cost-weight tradeoffs and corrosion resistance define material selection across marine and on-road applications.
- Aluminum:Vacuum-brazed bar-plate cores from captive foundry operations balance thermal conductivity with weight reduction. MAHLE GmbH and Valeo SA production lines in Germany and France concentrate on aluminum for European passenger vehicle platforms.
- Stainless Steel:Salt corrosion resistance commands premium positioning for Baltic and North Sea vessel operators. Dana Incorporated marine product lines specify austenitic grades for commercial fishing fleets operating in high-chloride environments.
- Copper:Limited specialty applications in legacy industrial equipment with established brazing infrastructure.
- Composites:Experimental polymer-aluminum hybrid cores for weight-critical aerospace derivative programs.
Aluminum captures current production scale; stainless steel expands most quickly in marine niche segments.
Application:
Turbocharger penetration rates and duty cycle severity segment demand by thermal load profile.
- Automotive:Downsized gasoline and diesel powertrains across German and US passenger platforms drive specification for compact air-to-water architectures. Stuttgart and Wolfsburg engineering clusters define thermal effectiveness benchmarks for global OEM supply agreements.
- Commercial Vehicles:Long-haul freight operators along the I-75 corridor and Rhine-Ruhr logistics hubs require durable air-to-air configurations with extended service intervals. Direct OEM contracting replaces tier-two module supplier intermediation in North American and German channels.
- Heavy Machinery:Construction and mining equipment in China's industrial zones specify reinforced core constructions for high-dust operating environments.
- Marine:Baltic and North Sea operators prioritize corrosion-resistant configurations for saltwater exposure.
Automotive platforms drive technology evolution; commercial vehicles anchor replacement demand stability.
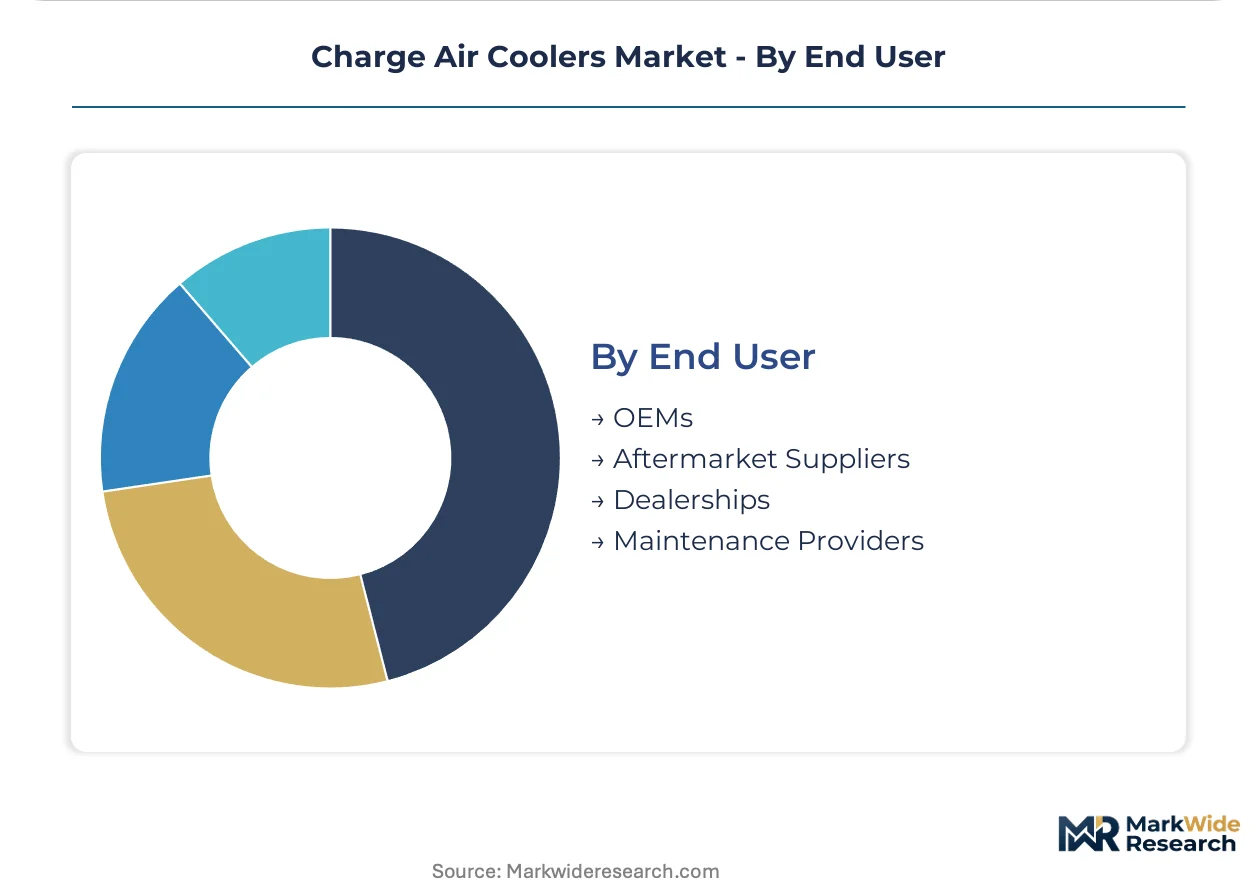
End User:
Procurement scale and technical validation requirements stratify supplier relationships across direct and aftermarket channels.
- OEMs:Whole-engine type approval certification cycles with NHTSA and KBA extend eighteen to twenty-four months, freezing design specifications and creating compliance barriers for unvalidated suppliers. Direct supply agreements concentrate among thermal system integrators capable of simultaneous intercooler and radiator program management.
- Aftermarket Suppliers:Digitized e-procurement platforms for aging European turbocharged vehicle pools compress replacement cycle intermediation. Fleet procurement departments consolidate relationships around suppliers with cross-border logistics capabilities.
- Dealerships:Authorized service networks for warranty-compliant replacement in branded maintenance programs.
- Maintenance Providers:Independent repair facilities serving commercial vehicle operators outside OEM service agreements.
OEMs control specification authority; aftermarket suppliers gain share through fleet digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering centers command premium pricing for validated charge air cooler architectures, while Chinese foundry operations compete on aluminum bar-plate unit economics. This asymmetry shapes procurement patterns across passenger vehicle and commercial fleet channels.
Germany
Stuttgart and Wolfsburg anchor European powertrain thermal engineering, with KBA certification timelines extending eighteen to twenty-four months for whole-engine type approval. Euro 7 standards mandate higher boost pressures and expanded aluminum heat exchanger surface area. Baden-Württemberg's Swabian industrial cluster concentrates vacuum brazing technician expertise, constraining production scaling for new entrants.
United States
EPA Tier 3 compliance harmonizes with European test protocols, forcing dual-jurisdiction validation for Michigan-based OEM powertrain departments. The I-75 freight corridor sustains demand for durable air-to-air configurations in long-haul commercial vehicles. NHTSA submission requirements freeze design specifications, creating compliance barriers for unvalidated suppliers seeking direct OEM contracts.
China
Beijing and Shanghai commercial vehicle fleets drive turbocharger penetration under MEE-administered Stage VI emission rules. Domestic bar-plate manufacturing scales rapidly, though vacuum furnace equipment concentrates among German and Austrian capital equipment suppliers. Yangtze River Delta industrial zones host emerging foundry operations competing on aluminum unit cost.
India
BIS emission timelines and Delhi-Mumbai industrial corridor freight expansion create underpenetrated demand for charge air cooler architectures. Commercial vehicle fleet procurement concentrates in Maharashtra and Gujarat manufacturing hubs. The country's national automotive regulator mandates thermal effectiveness verification as part of powertrain certification, extending supplier validation cycles.
Japan
METI industrial policy supports hybrid powertrain thermal management system development, with air-to-water architectures gaining specification in compact transverse engine bays. Kansai and Chubu industrial regions host precision aluminum fabricators serving domestic OEM engineering centers. JIS standards govern material specifications for vacuum-brazed bar-plate cores in passenger vehicle applications.
Charge Air Coolers Market Competitive Environment
Concentration sits with integrated thermal system specialists possessing captive aluminum foundry capacity and established KBA-NHTSA validation histories. The supplier base stratifies between multi-product thermal integrators and single-line charge air cooler fabricators. Two archetypes dominate: vertically integrated heat exchanger conglomerates controlling raw material flow from ingot to finished core, and component assemblers dependent on external aluminum supply. Competitive moves center on backward integration into foundry operations and strategic partnerships with vacuum furnace equipment manufacturers.
Among European-based thermal integrators, MAHLE GmbH and Valeo SA exemplify the vertically integrated archetype, anchoring supply relationships through in-house aluminum production capabilities. Dana Incorporated represents the North American commercial vehicle specialist model, occupying a position shaped by direct OEM contracting patterns. These three entities illustrate how geographic clustering around Stuttgart, Paris-region, and Michigan engineering centers reinforces competitive positioning through proximity to specification authority.
| Leading Market Players |
|---|
| MAHLE GmbH |
| Valeo SA |
| Dana Incorporated |
| Modine Manufacturing Company |
| T.RAD Co., Ltd. |
| Denso Corporation |
| Hanon Systems |
| BorgWarner Inc. |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
Aluminum ingot substitution for copper in bar-plate core fabrication simultaneously redistributes foundry capacity toward German and Austrian vacuum brazing clusters while compressing margin buffers for assemblers lacking captive smelter access. This material pivot concentrates pricing power among vertically integrated thermal specialists capable of controlling alloy flow from ingot to finished core.
Pricing Analysis
The customization-premium spread separates air-to-water configured-to-order architectures for hybrid powertrains from standard air-to-air commodity configurations. Three-tier pricing structure across premium, standard, and economy levels reflects KBA-NHTSA dual-certification status, captive foundry ownership, and volume scale. Pricing pressure stems from LME aluminum volatility and Chinese bar-plate unit cost competition. Fleet procurement departments in commercial vehicle channels exhibit highest price sensitivity; marine stainless steel specifications command lowest elasticity due to salt corrosion imperatives.
Supply Chain Analysis
Inbound logistics costs from Yangtze River Delta foundries to European vacuum furnace operators fluctuate with container availability on Asia-North Europe trade lanes. Raw material sourcing concentrates on German and Austrian aluminum smelters, Chinese bar-plate extrusion facilities, and Japanese precision tube suppliers. The supply chain draws from vacuum brazing equipment manufacturing concentrated in Swabian and Upper Austrian industrial clusters, creating single-source vulnerability for new entrants. Distribution runs through direct OEM contracting for passenger vehicle platforms and tier-one thermal system integrators for commercial vehicle channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Euro 7 emission standards are forcing a technological inflection in thermal management architectures, compressing development cycles and consolidating specification authority around validated suppliers. This regulatory compression creates asymmetric growth opportunities across incumbent defense, entrant differentiation, and acquisition targeting strategies.
For Market Incumbents: Consolidate backward integration into captive aluminum foundry operations to defend margin position against Chinese bar-plate unit cost competition. Expand vacuum brazing technician training pipelines in Swabian and Upper Austrian clusters to overcome production scaling constraints. Secure dual KBA-NHTSA validation histories before EPA-Euro 7 harmonization tightens compliance barriers. For New Entrants and Emerging Players: Differentiate on air-to-water architecture specialization for hybrid powertrain compartments where Stuttgart and Wolfsburg engineering teams specify compact packaging solutions. Target India's Delhi-Mumbai industrial corridor commercial vehicle fleet expansion where BIS emission timelines create underpenetrated demand for durable bar-plate configurations. Pursue direct fleet e-procurement partnerships to bypass entrenched tier-two module supplier intermediation. For Investors and Strategic Acquirers: Euro 7 implementation reshapes the acquisition landscape toward vertically integrated thermal specialists with established KBA-NHTSA validation histories and captive aluminum smelter access. Long-term viability over the next decade hinges on regulatory certification moats rather than manufacturing scale alone. Monitor EPA Tier 3-Euro 7 harmonization progress as the signal for accelerated consolidation among unvalidated component assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Aluminum Foundry Acquisition | Secures raw material flow control from ingot to finished core against LME volatility. |
| Vacuum Brazing Technician Apprenticeship Expansion | Addresses production scaling constraints in Swabian and Upper Austrian industrial clusters. |
| Dual KBA-NHTSA Certification Investment | Creates compliance moat as EPA-Euro 7 harmonization mandates identical performance datasets. |
| Air-to-Water Architecture R&D Partnership | Aligns with Wolfsburg and Stuttgart hybrid powertrain specification trends for compact packaging. |
| India Commercial Vehicle Fleet Direct Contracting | Captures BIS emission timeline demand along Delhi-Mumbai freight corridor expansion. |
Study Parameters
Desk research of SEC 10-K filings, OEM powertrain engineering disclosures, and EPA-Euro 7 regulatory harmonization documents preceded structured interviews with thermal system procurement directors, vacuum brazing equipment manufacturers, and fleet maintenance operations managers. Primary fieldwork across Stuttgart, Wolfsburg, and Michigan engineering centers triangulated with customs trade data and aluminum ingot flow records. Bottom-up volume modeling and top-down value estimation converged through iterative validation.
Variance decomposition across product type, material grade, application severity, and end-user channel dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level adoption curves weighted by OEM platform deployment timelines and aftermarket replacement cycle elasticity. Forecast inputs incorporated turbocharger penetration rates in downsized powertrains and electrification substitution scenarios for battery-electric vehicle deployment.
The analysis sits within stated boundaries; outcomes outside sustained Euro 7-EPA Tier 3 regulatory enforcement or accelerated battery-electric vehicle substitution would require recalibration. Forecasts reflect documented assumptions regarding aluminum price stability, vacuum furnace equipment availability, and OEM thermal validation timeline continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Gas-Powered Chainsaw Market
Vehicle Components
Throttle Cable Market
Vehicle Components
North America Forklift Rental Market
Vehicle Components
4x4 Vehicle Parts and Accessories Market
Vehicle Components
Cylindrical Roller Bearings Market
Vehicle Components
Forestry Trailers Market
Vehicle Components
Seating and Positioning Belts Market
Vehicle Components
Bicycle Components Aftermarket Market
Vehicle Components
Trailer Surge Brake Market
Vehicle Components
5th Wheel Hitches Market
Vehicle Components
Chassis Leveling Valves Market
Vehicle Components
Steel and Rubber Tracks Market
Vehicle Components
Crank Case Ventilation Valve Market
Vehicle Components
Bus and Coach Suspension Bearing Components Market
Vehicle Components
Tail Lifts Market
Vehicle Components
HCV Suspension System Market