
 Global Automotive Terminal Market | 2026-2036
Global Automotive Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Terminal Market Analysis
The EU Green Deal is pivoting automotive terminal procurement toward low-carbon copper and recyclable plastic housings. TE Connectivity leverages its European stamping footprint to supply OEMs with REACH-compliant product lines. Yazaki Corporation anchors high-volume harness terminal production across Japanese and Southeast Asian assembly plants. Sumitomo Electric Industries differentiates through continuous casting expertise that reduces conductor resistance in high-voltage applications.
Automotive terminals are electromechanical interface devices that establish current paths between wires, PCBs, and components, typically manufactured from copper alloys with tin or silver plating and formed through progressive die stamping or machining. Their primary purpose is ensuring reliable electrical continuity amid vibration, thermal cycling, and corrosion across vehicle lifecycles. Blade terminals dominate ICE vehicle harness architectures due to standardized mating geometries, while socket terminals capture expanding share in battery electric platforms where sealed high-current interfaces resist moisture ingress. Copper material grades command premium positioning as conductivity specifications tighten for 800V architectures, whereas aluminum terminals gain traction where mass reduction outweighs ohmic loss penalties.
The EPA tailpipe rules and China's MIIT dual carbon goals are forcing terminal suppliers to document embodied carbon in raw material sourcing. NHTSA crashworthiness standards shape terminal retention force specifications to prevent electrical failures during collision events. REACH substance restrictions limit certain cadmium and lead platings, redirecting plating chemistry investments toward tin-bismuth and nickel-palladium systems. Stakeholders must monitor evolving voltage tier definitions across OEM platforms to align terminal ampacity portfolios with electrification roadmaps.
Market Dynamics
Voltage tier migration across OEM electrification roadmaps is compressing terminal specification cycles, forcing suppliers to dual-source copper grades and aluminum alloys while maintaining legacy 12V/48V portfolios.
Growth Catalysts
- MIIT Dual Carbon Goals:China's manufacturing mandates accelerate high-conductivity terminal adoption across NEV powertrain assembly lines, tightening material traceability requirements for domestic suppliers.
- 800V Platform Rollouts:Premium EV architectures demand silver-plated copper terminals with enhanced thermal cycling resistance, pulling investment toward precision stamping capabilities.
- East Asian Manufacturing Corridors:Concentrated harness production across Japan, South Korea, and eastern China generates procurement scale that justifies dedicated terminal tooling investments.
Market Restraints
- Copper Price Volatility:LME copper fluctuations compress margin buffers for stamped terminal producers locked into annual OEM supply agreements.
- Plating Chemistry Transition Costs:REACH substance restrictions on cadmium and lead platings force capital redeployment toward tin-bismuth and nickel-palladium systems without immediate price recovery mechanisms.
- Aluminum Conductivity Penalties:Ohmic loss trade-offs limit aluminum terminal penetration in high-current battery interfaces despite mass reduction benefits.
Strategic Opportunities
- India PLI Scheme for Auto Components:Domestic manufacturing incentives create localized terminal production capacity to serve emerging EV assembly clusters around Chennai and Pune.
- Battery Recycling Integration:Closed-loop copper recovery from end-of-life EV packs is converging with virgin material procurement, reshaping terminal feedstock economics.
- Sealed High-Current Interfaces:IP67-rated socket terminal designs capture expanding share in electric commercial vehicle platforms where moisture ingress resistance commands premium positioning.
Industry Challenges
- Progressive Die Stamping Talent Scarcity:Tooling design expertise for high-speed copper alloy forming concentrates among aging workforces in Japan and Germany, constraining capacity expansion.
- Dual Certification Burden:Simultaneous NHTSA crashworthiness validation and ECHA REACH compliance extends product qualification timelines for multi-region terminal portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Terminal Market |
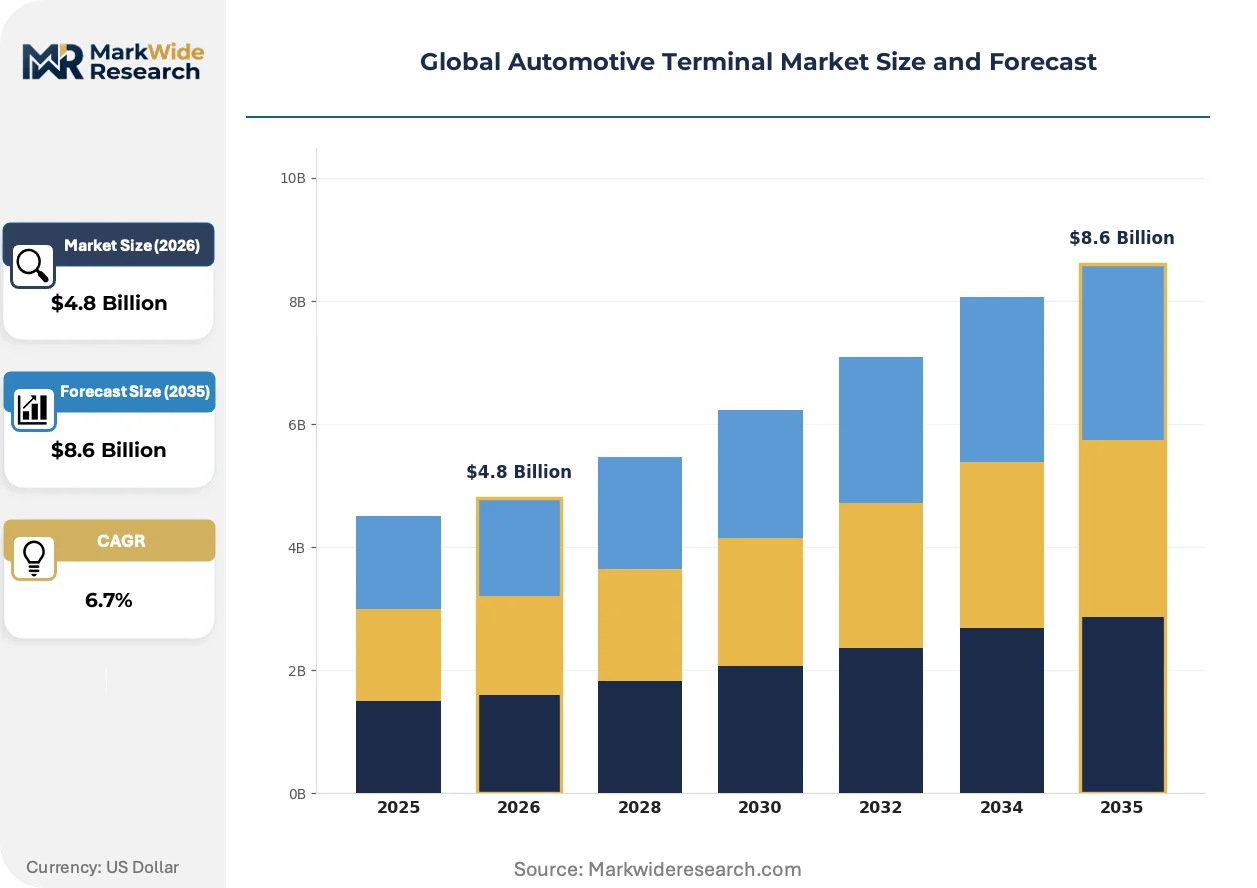
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blade Terminals, Ring Terminals, Socket Terminals, Spade Terminals Material: Copper, Aluminum, Brass, Plastic Connection Type: Crimp Connectors, Solder Connectors, Screw Connectors, Push-On Connectors End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | TE Connectivity, Lear Corporation, Aptiv PLC, Yazaki Corporation, Sumitomo Electric Industries, Furukawa Electric, Molex, PKC Group, Keats Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Terminal Market Emerging Trajectories
Terminal architecture evolution is splitting along voltage tier lines, with 800V systems demanding fundamentally different material stacks and sealing geometries than legacy 12V harness components.
Laser-welded terminal joints are converging with ultrasonic wire splicing in battery pack assembly, eliminating mechanical crimp points that fatigue under thermal cycling. Cell manufacturers in South Korea and China are adopting these processes at scale for their latest platform generations. The structural consequence is a compression in traditional blade terminal demand within high-voltage zones, even as 12V auxiliary circuits sustain conventional stamped interfaces.
The EU Green Deal's embodied carbon disclosure requirements are forcing terminal suppliers to document Scope 3 emissions from Chilean copper mines through European stamping operations. OEM procurement teams in Germany and France now weight carbon intensity alongside unit cost in supplier scorecards. High-volume harness assemblers are responding by qualifying recycled-content copper grades that maintain conductivity specifications.
Consolidated procurement through tier-one harness suppliers is displacing direct OEM-terminal manufacturer relationships across mid-volume vehicle platforms. Japanese and European wiring harness specialists now specify terminal geometries and plating chemistries unilaterally, compressing supplier visibility into end-use applications. This concentration is most visible in Southeast Asian assembly plants where Yazaki and Sumitomo Electric anchor regional sourcing decisions.
Global Automotive Terminal Market Segmentation
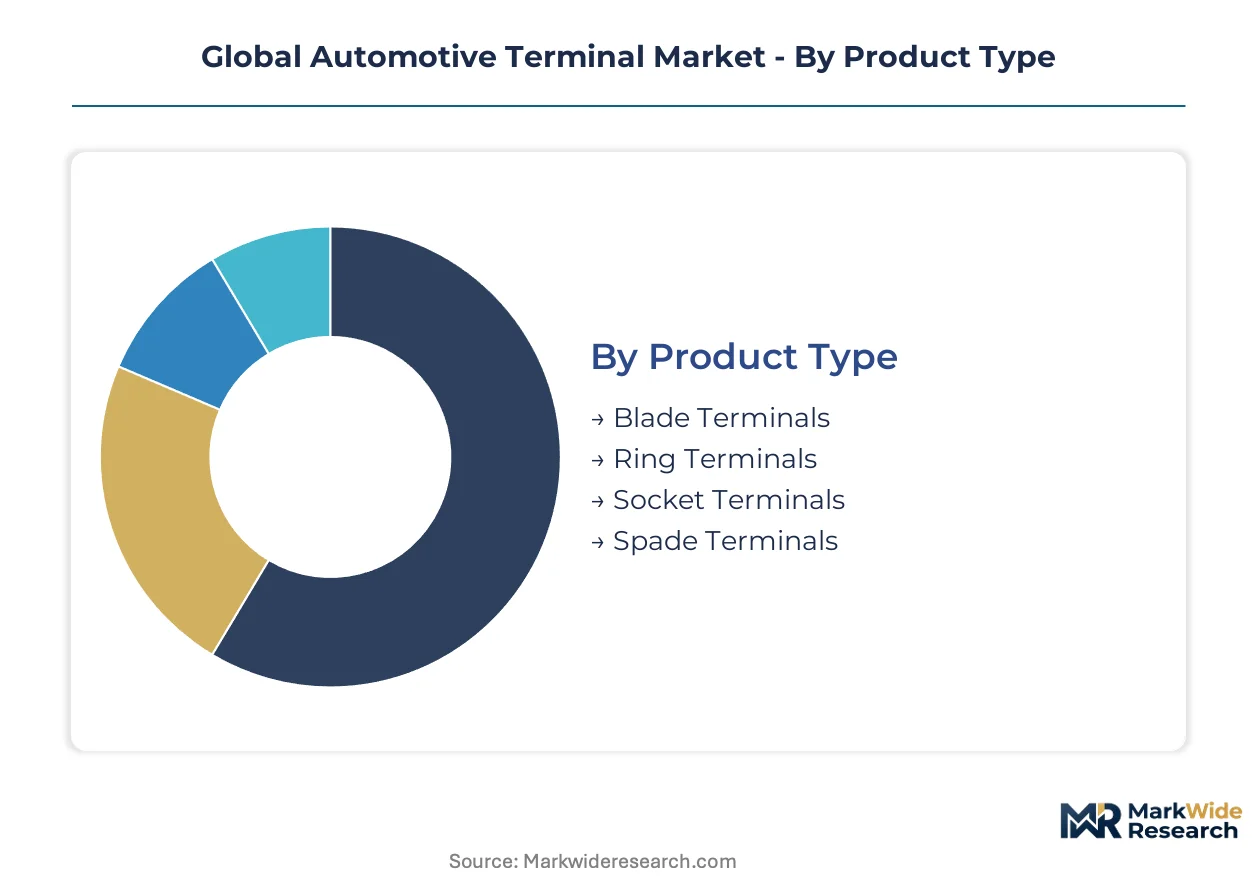
Automotive terminal procurement splits along voltage tier lines, with 800V architectures demanding fundamentally different material stacks than legacy 12V systems. Suppliers must maintain parallel production streams across copper grades, aluminum alloys, and plating chemistries to serve divergent OEM electrification roadmaps.
Product Type:
Blade and socket formats concentrate production capacity across East Asian stamping corridors, with tooling investments tracking OEM platform voltage migrations.
- Blade Terminals:Stamped copper alloy strips with tin or silver plating form the backbone of ICE vehicle harness architectures. TE Connectivity anchors high-volume production across European stamping plants to serve legacy 12V/48V portfolios amid declining ICE volumes.
- Socket Terminals:Sealed cylindrical interfaces with enhanced retention geometry capture expanding share in battery electric platforms. South Korean cell manufacturers specify IP67-rated variants for high-current battery pack connections where moisture ingress resistance commands premium positioning.
- Ring Terminals:Circular eyelet designs secure ground connections in chassis and powertrain assemblies.
- Spade Terminals:Flat forked configurations enable quick-disconnect applications in auxiliary circuits and sensor harnesses.
Blade terminals absorb the bulk of installed capacity; socket terminals are expanding most quickly.
Material:
Conductivity specifications tighten with voltage tier escalation, forcing dual-sourcing strategies across copper grades and aluminum alloys.
- Copper:Oxygen-free high-conductivity grades dominate 800V architectures where ohmic losses compound across powertrain interfaces. Chinese NEV mandates accelerate traceability requirements for Chilean mine-to-terminal carbon disclosure.
- Aluminum:Mass-reduction benefits drive adoption in non-critical current paths despite conductivity penalties. European OEMs specify aluminum for auxiliary harness segments where voltage drop tolerances permit material substitution.
- Brass:Lower-cost copper-zinc alloys serve cost-sensitive 12V applications with relaxed conductivity requirements.
- Plastic:Glass-filled nylon and PBT housings provide electrical isolation and mechanical retention in connector assemblies.
Copper commands the dominant share of material procurement value; aluminum is climbing the fastest as mass reduction targets intensify.
Connection Type:
Assembly process automation favors crimp and laser-weld methods, displacing solder and screw configurations in high-volume production.
- Crimp Connectors:Mechanical compression joints dominate harness assembly through automated applicator systems. Japanese wiring harness specialists specify precision crimp geometries that withstand NHTSA crashworthiness validation for collision-event retention.
- Solder Connectors:Fused metal joints persist in repair applications and low-volume specialty assemblies.
- Screw Connectors:Threaded mechanical retention serves battery service disconnects and field-replaceable modules.
- Push-On Connectors:Quick-mating interfaces accelerate assembly line throughput for sensor and lighting circuits.
Crimp connectors retain the largest installed base; push-on configurations are gaining share fastest in modular assembly architectures.
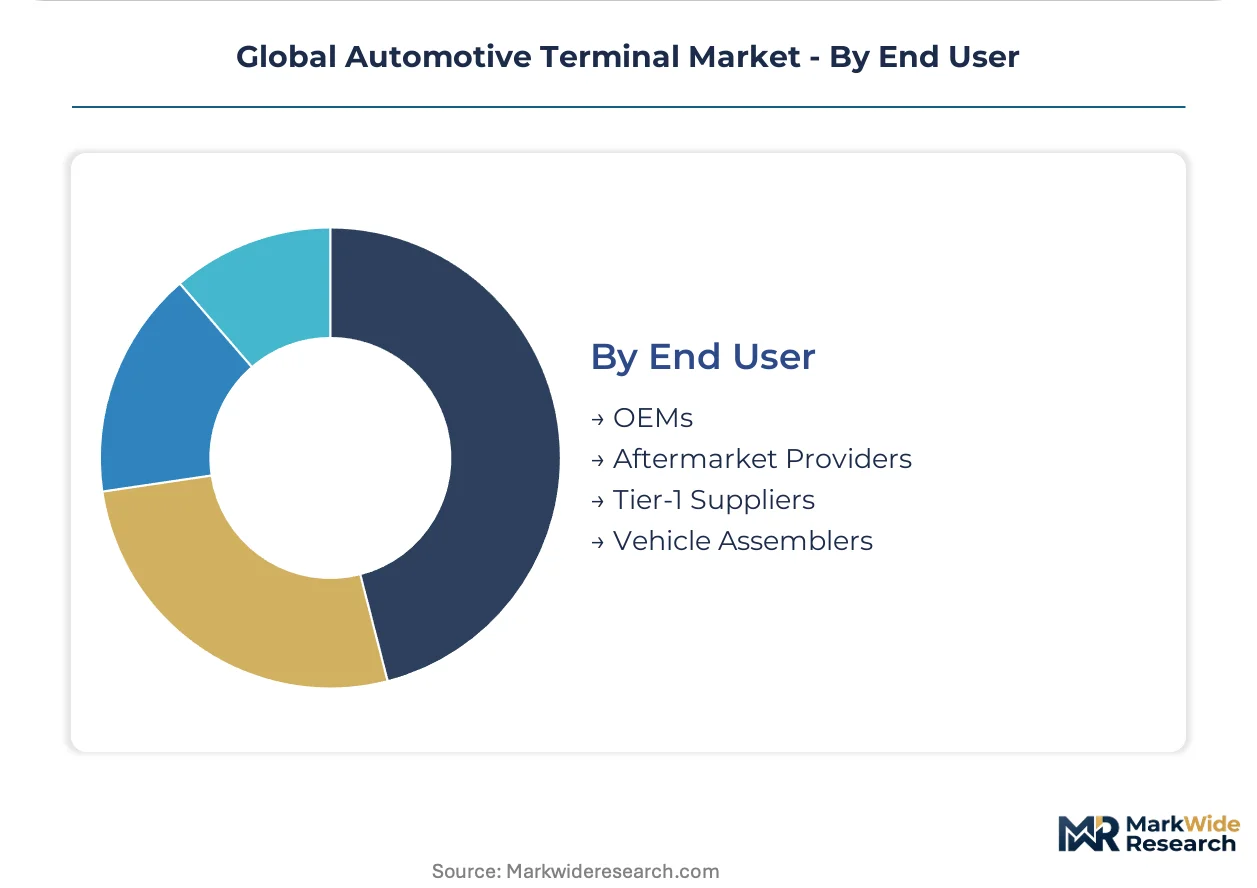
End User:
Procurement authority is consolidating through tier-one harness suppliers, compressing direct OEM-terminal manufacturer relationships.
- Tier-1 Suppliers:Wiring harness specialists now unilaterally specify terminal geometries and plating chemistries. Yazaki and Sumitomo Electric anchor regional sourcing decisions across Southeast Asian assembly plants, consolidating demand concentration.
- OEMs:Direct procurement persists for high-voltage battery interface terminals where platform-specific designs require collaborative development.
- Aftermarket Providers:Independent distributors serve repair and replacement demand through standardized terminal kits.
- Vehicle Assemblers:Contract manufacturers rely on harness supplier specifications for terminal procurement in outsourced production arrangements.
Tier-1 suppliers absorb the bulk of terminal procurement volume; OEM direct sourcing is expanding most quickly for 800V platform development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing corridors generate the bulk of terminal production capacity, while European and North American markets absorb high-value specialized output. China, Japan, and South Korea anchor supply-side concentration through integrated harness assembly ecosystems.
China
MIIT dual carbon goals and NEV production quotas accelerate high-conductivity terminal procurement across domestic powertrain lines. GB standards and SAMR compliance rules tighten material traceability for Chilean copper imports. The Yangtze River Delta corridor, spanning Shanghai and Suzhou, concentrates stamping capacity to serve BYD and CATL battery pack assembly.
Japan
Precision stamping expertise for 800V architectures sustains export-oriented terminal production amid domestic EV transition. METI technology roadmaps and JIS standards govern plating chemistry specifications for automotive connectors. The Chubu region around Nagoya anchors Yazaki and Sumitomo Electric harness operations with captive terminal tooling investments.
Germany
OEM procurement teams weight embodied carbon alongside unit cost in supplier scorecards under EU Green Deal disclosure mandates. ECHA REACH restrictions on cadmium platings redirect chemistry investments toward tin-bismuth systems. Bavaria and Baden-Württemberg host TE Connectivity stamping plants serving Mercedes-Benz and BMW electrification platforms.
United States
EPA tailpipe rules and NHTSA crashworthiness standards shape terminal retention force specifications for collision-event electrical integrity. The Inflation Reduction Act domestic content provisions incentivize North American copper sourcing for EV tax credit eligibility. Michigan and Ohio assembly corridors concentrate harness procurement for Detroit Three electrification programs.
South Korea
Cell manufacturers specify IP67-rated socket terminals for high-current battery pack connections on latest platform generations. MFDS-equivalent automotive standards and KBA-aligned export requirements govern plating durability testing. The Busan-Ulsan industrial belt concentrates Hyundai-Kia supplier parks with integrated terminal-to-harness production flows.
Global Automotive Terminal Market Vendor Landscape
The competitive structure tilts toward diversified electrical component conglomerates with captive harness relationships. Japanese and European players anchor high-volume production through integrated supply chains with tier-one wiring specialists. Three archetypes dominate: precision stamping specialists with continuous casting expertise, diversified interconnect conglomerates with multi-region footprints, and regional harness-integrated fabricators serving single OEM ecosystems. Capacity expansion and plating chemistry transitions constitute the dominant competitive moves as voltage tier migrations compress specification cycles.
Within the diversified conglomerate tier, TE Connectivity, Yazaki Corporation, and Sumitomo Electric occupy positions that exemplify integrated production from raw material procurement through harness assembly. These entities represent archetypes of regional production anchoring, with European, Japanese, and East Asian geographic concentrations respectively. Lear Corporation and Aptiv PLC sit within the tier-one supplier vector, reflecting the consolidation of procurement authority through wiring harness specialists. The presence of Molex and Furukawa Electric indicates specialty-grade positioning for high-voltage sealing applications. Keats Manufacturing and PKC Group exemplify mid-scale regional fabricators serving concentrated OEM supply agreements.
| Leading Market Players |
|---|
| TE Connectivity |
| Lear Corporation |
| Aptiv PLC |
| Yazaki Corporation |
| Sumitomo Electric Industries |
| Furukawa Electric |
| Molex |
| PKC Group |
| Keats Manufacturing |
| Others |
Supply Flow & Price Mechanics
Tier-1 harness supplier consolidation across East Asian manufacturing corridors concentrates procurement leverage, compressing terminal manufacturers into long-term offtake contracts with limited price renegotiation windows. This buyer concentration anchors a contract-based pricing model where annual volume commitments lock suppliers into fixed copper alloy costs despite LME volatility.
Pricing Analysis
Margin tightening in stamped copper terminals traces to simultaneous copper price volatility and plating chemistry transition costs without pass-through mechanisms. Three-tier pricing structure across silver-plated high-voltage, tin-plated standard, and brass economy terminals reflects conductivity grade and certification tier differentiation. Cost-down pressure on aluminum terminal variants accelerates as European OEMs prioritize mass reduction targets. Aftermarket distributors exhibit highest price sensitivity, while OEM direct procurement for 800V platforms accepts premium positioning for traceable low-carbon copper grades.
Supply Chain Analysis
Container freight rate fluctuations from Chilean copper concentrate ports to East Asian stamping corridors compound raw material cost uncertainty for terminal producers. Supply concentration centers on Japan, South Korea, and eastern China for precision stamping capacity, with Chile and Peru anchoring copper concentrate feedstock. The supply chain draws from oxygen-free copper billets, tin-bismuth plating chemistries, and glass-filled nylon housings. Single-source vulnerability concentrates in progressive die tooling design expertise concentrated among aging workforces in Nagoya and Stuttgart. Distribution runs through captive harness supplier networks rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
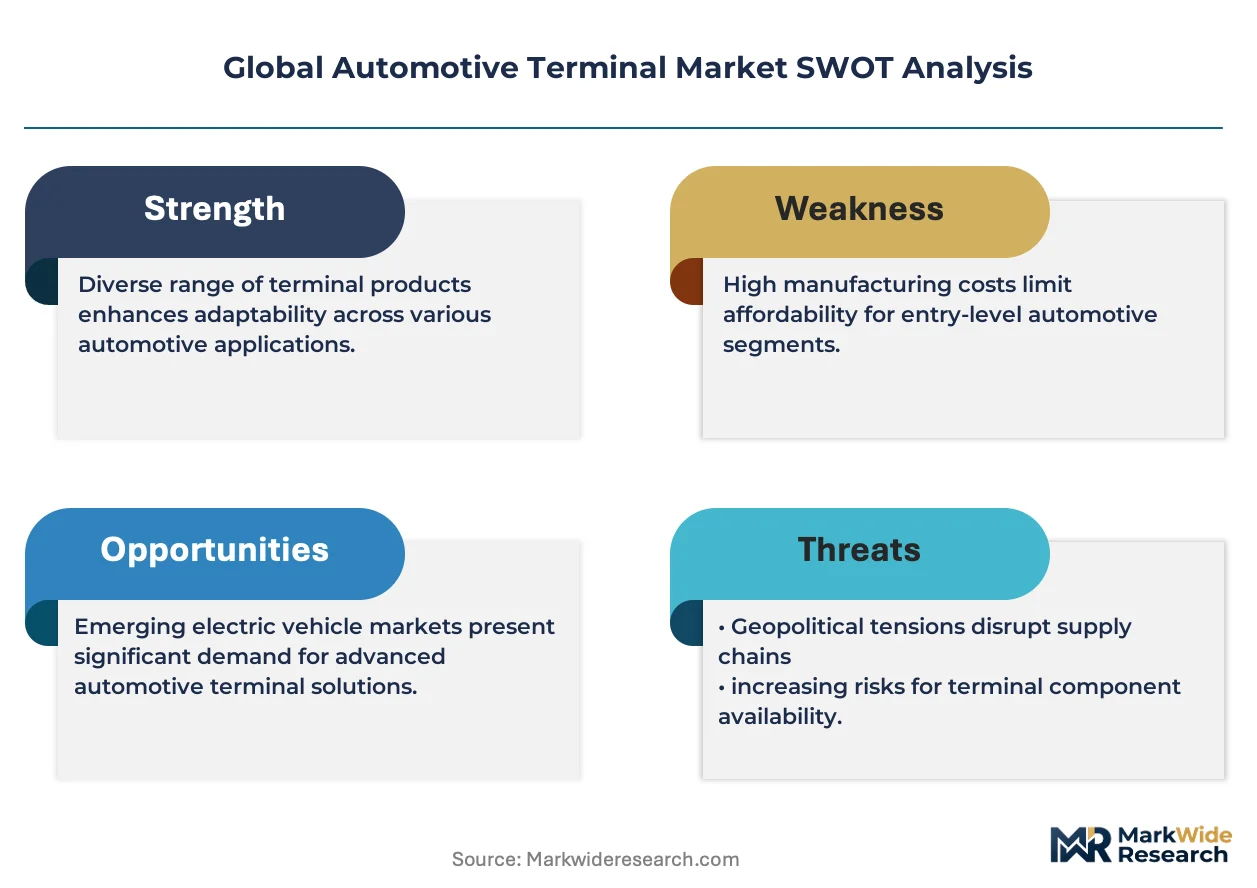
The Global Automotive Terminal Market functions as a cost-of-compliance arena where ECHA REACH substance restrictions on cadmium and lead platings erect technical barriers that favor incumbent players with capital reserves for chemistry transitions.
For Market Incumbents: Lock in long-term offtake agreements with Chilean copper producers to secure low-carbon traceability documentation required under EU Green Deal procurement scorecards. Backward integration into continuous casting operations reduces conductor resistance variability for 800V platform qualification. Defend against progressive die stamping talent scarcity by acquiring specialized tooling firms in Japan's Chubu region. For New Entrants and Emerging Players: Enter via India's PLI scheme for auto components, where domestic manufacturing incentives support localized terminal production for emerging EV assembly clusters around Chennai and Pune. Target sealed IP67-rated socket terminal segments for electric commercial vehicle platforms, where moisture ingress resistance specifications command premium positioning absent entrenched supplier relationships. Pursue qualification partnerships with South Korean cell manufacturers seeking second-source validation for high-current battery interfaces. For Investors and Strategic Acquirers: The window for entry favors precision stamping specialists with captive continuous casting capabilities and established OEM platform engineering relationships. Mid-scale regional fabricators serving single-OEM ecosystems in Southeast Asia represent consolidation targets as tier-1 harness suppliers compress supplier bases. Watch for inflection signals in 800V platform rollout acceleration across German and Chinese OEM electrification roadmaps.| Strategic Initiative | Industry Significance |
|---|---|
| Plating Chemistry Transition | REACH-compliant tin-bismuth systems open German and French OEM procurement channels previously closed to cadmium-dependent suppliers. |
| Continuous Casting Capacity Expansion | In-house oxygen-free copper billet production reduces conductor resistance variability for 800V architecture qualification. |
| India Manufacturing Footprint | PLI scheme incentives enable cost-competitive supply to emerging EV assembly clusters around Chennai and Pune. |
| Battery Recycling Integration | Closed-loop copper recovery from end-of-life EV packs converges with virgin procurement under EU Green Deal circularity mandates. |
| Progressive Die Tooling Acquisition | Specialized forming expertise acquisition in Japan and Germany addresses talent scarcity constraining capacity expansion. |
Methodological Framework
Multi-period observation of OEM electrification roadmap disclosures, voltage tier migration timelines, and tier-1 harness supplier procurement patterns anchored the trend analysis, supplemented by interviews with terminal manufacturer engineering directors, OEM platform electrification leads, tier-1 wiring harness procurement managers, and copper alloy smelter technical sales teams. Secondary validation drew from ECHA REACH substance restriction filings, MIIT NEV production quota announcements, SEC 10-K supply chain disclosures, and IHS Markit vehicle production databases. Bottom-up terminal demand modeling triangulated against top-down automotive electrical content projections.
The input-output matrix framework mapped copper alloy consumption rates against vehicle electrification penetration curves across the projection horizon. Segmentation dimensions modeled included voltage tier, terminal format, material grade, plating chemistry, and regional production cluster. CAGRs derived from regression analysis of historical terminal content per vehicle against OEM platform electrification commitments. Industry-specific forecast inputs incorporated 800V architecture rollout schedules and MIIT dual carbon compliance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper price volatility extremes and regulatory acceleration scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Strut Bar Market
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
Automotive Trailer Drawbar Market
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
Automotive Throttle Body Assembly Market
Automotive Assemblies
Automotive Tensioner Market
Automotive Assemblies
Automotive Roof Rails Market
Automotive Assemblies
Car Body Kit Market
Automotive Assemblies
Automotive Cell Vent Spacer Market
Automotive Assemblies
Half-Shaft Assemblies Market
Automotive Assemblies
Automotive Armrest Market
Automotive Assemblies
Automotive Die-Stamping Equipment Market
Automotive Assemblies
Automotive Die Casting Market
Automotive Assemblies
Automotive Grille Market
Automotive Assemblies
Automotive Structural Sheet Market
Automotive Assemblies
Automotive Roof Rack Market