
 Repetitive Transcranial Magnetic Stimulation Market | 2026-2036
Repetitive Transcranial Magnetic Stimulation Market Size, Share, and Industry Trends Forecast 2026-2036
Repetitive Transcranial Magnetic Stimulation Market Analytics
European device manufacturers is broadening the supply base for precision magnetic coil assemblies. BrainsWay leverages deep transcranial stimulation protocols to differentiate its H-coil architecture in psychiatric settings. MagVenture sustains manufacturing scale through captive production of stimulator electronics at its Danish facilities. Neuronetics anchors the North American installed base with integrated practice management software bundled to its NeuroStar systems.
Repetitive transcranial magnetic stimulation deploys rapidly alternating magnetic fields through insulated coils to induce focal electrical currents in cortical neurons, typically operating at frequencies between 1 Hz and 20 Hz with field strengths of 1.5 to 2 Tesla. The technology serves primarily as a non-invasive neuromodulation therapy for pharmacoresistant major depressive disorder and expanding pain management protocols. Tabletop devices occupy the dominant revenue position in hospitals where capital budgets accommodate fixed installations, while portable devices represent the fastest-expanding category as clinics seek flexible deployment across multiple treatment rooms. Depression treatment commands the largest application share, though pain relief applications are gaining protocol approvals in rehabilitation centers.
FDA 510(k) pathways govern device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for neuromodulation systems seeking CE marking. Japan's PMDA maintains distinct technical standards for magnetic stimulator safety that constrain direct product portability from Western markets. Stakeholders must monitor reimbursement code expansions and real-world evidence mandates that will determine which delivery modes achieve sustainable clinical adoption.
Market Dynamics
Magnetic coil precision engineering is concentrating manufacturing capability among specialized European suppliers, while psychiatric clinic networks in the United States and Germany drive protocol standardization through volume purchasing power.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined clearance for iterative coil designs reduces time-to-market for device manufacturers targeting treatment-resistant depression protocols.
- German rehabilitation center expansion:Bundled reimbursement codes for pain management applications extend rTMS beyond psychiatric settings into orthopedic and neurological rehabilitation.
- H-coil architecture differentiation:Deep transcranial stimulation protocols enable penetration beyond superficial cortical layers, opening obsessive-compulsive disorder and smoking cessation indications.
Market Restraints
- Copper and rare-earth magnet cost volatility:Coil assembly materials face commodity price swings that compress hardware margins for tabletop device manufacturers.
- Danish electronics production concentration:Captive stimulator circuit manufacturing in limited facilities creates supply vulnerability for precision pulse generators.
- PMDA technical standard divergence:Japan's distinct magnetic field safety thresholds force hardware redesigns that fragment production runs and inflate certification costs.
Strategic Opportunities
- Portable device category emergence:Lightweight, battery-operated systems enable clinic deployment across multiple treatment rooms without fixed infrastructure investment.
- EU Medical Device Regulation real-world evidence pathways:Post-market clinical follow-up mandates create competitive advantage for manufacturers with established patient registries.
- Neurological application expansion:Stroke rehabilitation and migraine prophylaxis protocols gain traction in Japanese university hospitals seeking non-pharmacological alternatives.
Industry Challenges
- Neurophysiologist training pipeline constraints:Specialized operators capable of motor threshold determination and coil positioning remain scarce relative to installed base expansion.
- MDR technical documentation burden:Clinical evaluation report requirements for CE marking extend certification timelines and demand dedicated regulatory affairs capacity.
- Legacy practice management integration:Workflow software from incumbent North American vendors creates switching friction for clinics considering alternative hardware platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Repetitive Transcranial Magnetic Stimulation Market |
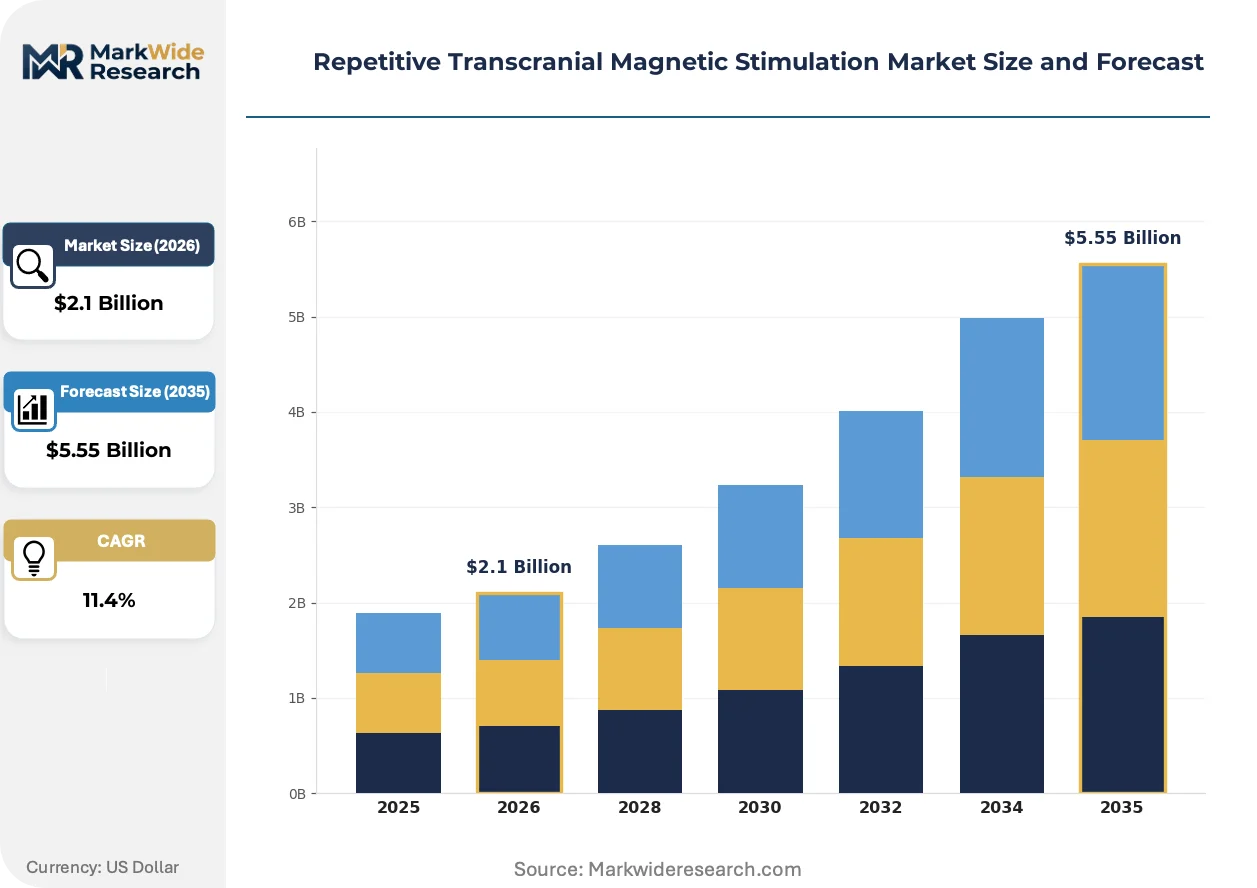
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Tabletop Devices, Wearable Systems, Fixed Installations End User: Hospitals, Clinics, Research Institutions, Rehabilitation Centers Application: Depression Treatment, Anxiety Management, Pain Relief, Cognitive Enhancement Delivery Mode: Outpatient, Inpatient, Home-based, Group Therapy |
| Companies Covered | BrainsWay, MagVenture, Neuronetics, Magstim, Nexstim, eNeura, Soterix Medical, Neurosoft, neurocare group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Repetitive Transcranial Magnetic Stimulation Market Evolving Landscape
Neuromodulation hardware is pivoting toward software-defined treatment protocols that enable real-time parameter adjustment based on electroencephalography feedback, compressing the gap between research configurations and clinical deployment.
Deep transcranial magnetic stimulation is consolidating psychiatric market positioning through H-coil architectures that achieve subcortical targeting without surgical intervention. Academic medical centers in Israel and the United States are adopting these systems for obsessive-compulsive disorder trials. The technology is consolidating competitive differentiation around anatomical specificity rather than pulse frequency alone.
EU Medical Device Regulation clinical evidence requirements are tightening market access for neuromodulation systems seeking CE marking. Manufacturers must now submit post-market surveillance plans and periodic safety update reports that exceed previous directive obligations. Small and mid-sized device developers face consolidation pressure as technical documentation costs escalate.
Clinic procurement is fragmenting across equipment financing models that separate hardware acquisition from maintenance and software subscription commitments. Independent psychiatric practices in the United States increasingly favor operating lease structures over capital purchases. Germany's rehabilitation chains are negotiating bundled service agreements that shift uptime risk to manufacturers.
Repetitive Transcranial Magnetic Stimulation Market Segmentation
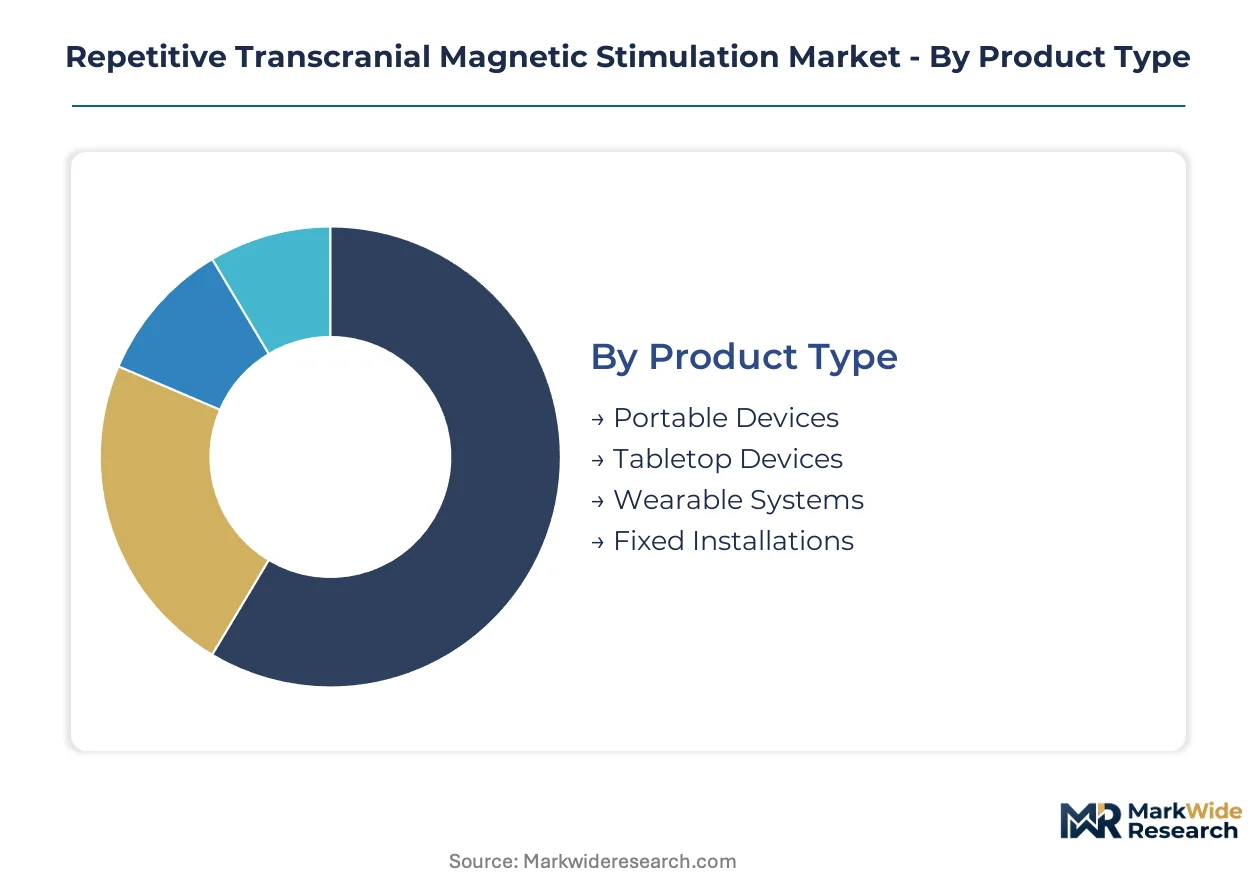
Repetitive transcranial magnetic stimulation equipment spans a customization spectrum from standardized fixed installations to patient-specific protocol configurations. Device manufacturers compete across four distinct dimensions where technical specifications, reimbursement pathways, and clinical workflow requirements fragment purchasing decisions.
Product Type:
Standardized hardware platforms dominate high-volume psychiatric deployments, while modular configurations address emerging portable and wearable demand.
- Tabletop Devices:Stationary systems integrate precision pulse generators with articulating coil arms for motor threshold mapping. Hospitals in the United States prioritize these units for dedicated TMS suites where capital budgets accommodate fixed infrastructure.
- Portable Devices:Battery-operated stimulators with reduced field strength enable deployment across multiple treatment rooms. Clinics in Germany favor these systems for flexible scheduling in bundled rehabilitation programs.
- Fixed Installations:Hardwired electromagnetic arrays serve high-throughput academic medical centers with dedicated shielding requirements.
- Wearable Systems:Emerging lightweight coil assemblies target home-based maintenance protocols under remote physician supervision.
Leading the category by volume: Tabletop Devices. Growing fastest: Portable Devices.
End User:
Purchasing sophistication varies sharply across institutional settings, with reimbursement maturity determining hardware acquisition timelines.
- Hospitals:Academic medical centers in Japan deploy deep transcranial stimulation systems for obsessive-compulsive disorder trials under PMDA oversight. Capital procurement committees require extensive safety documentation.
- Clinics:Independent psychiatric practices in the United States drive portable device adoption through operating lease structures that minimize upfront investment.
- Rehabilitation Centers:German orthopedic facilities integrate rTMS into multimodal pain management protocols under statutory health insurance reimbursement.
- Research Institutions:Israeli university hospitals pioneer H-coil applications for smoking cessation through investigator-initiated studies.
Procurement volume concentrates in Hospitals. Steepest expansion trajectory: Clinics.
Application:
Protocol standardization lags furthest in emerging indications where evidence generation remains active.
- Depression Treatment:FDA-cleared protocols for pharmacoresistant major depressive disorder anchor installed base justification. United States psychiatric clinics achieve predictable reimbursement through established CPT codes.
- Pain Relief:Rehabilitation centers in Germany leverage bundled diagnosis-related group payments for chronic pain rTMS protocols. Coil positioning protocols differ substantially from psychiatric applications.
- Anxiety Management:Off-label utilization in academic settings precedes formal regulatory submissions for generalized anxiety disorder.
- Cognitive Enhancement:Wellness-oriented applications face limited insurance coverage and concentrate in direct-pay clinic models.
Depression Treatment commands installed base dominance. Pain Relief exhibits the fastest protocol expansion.
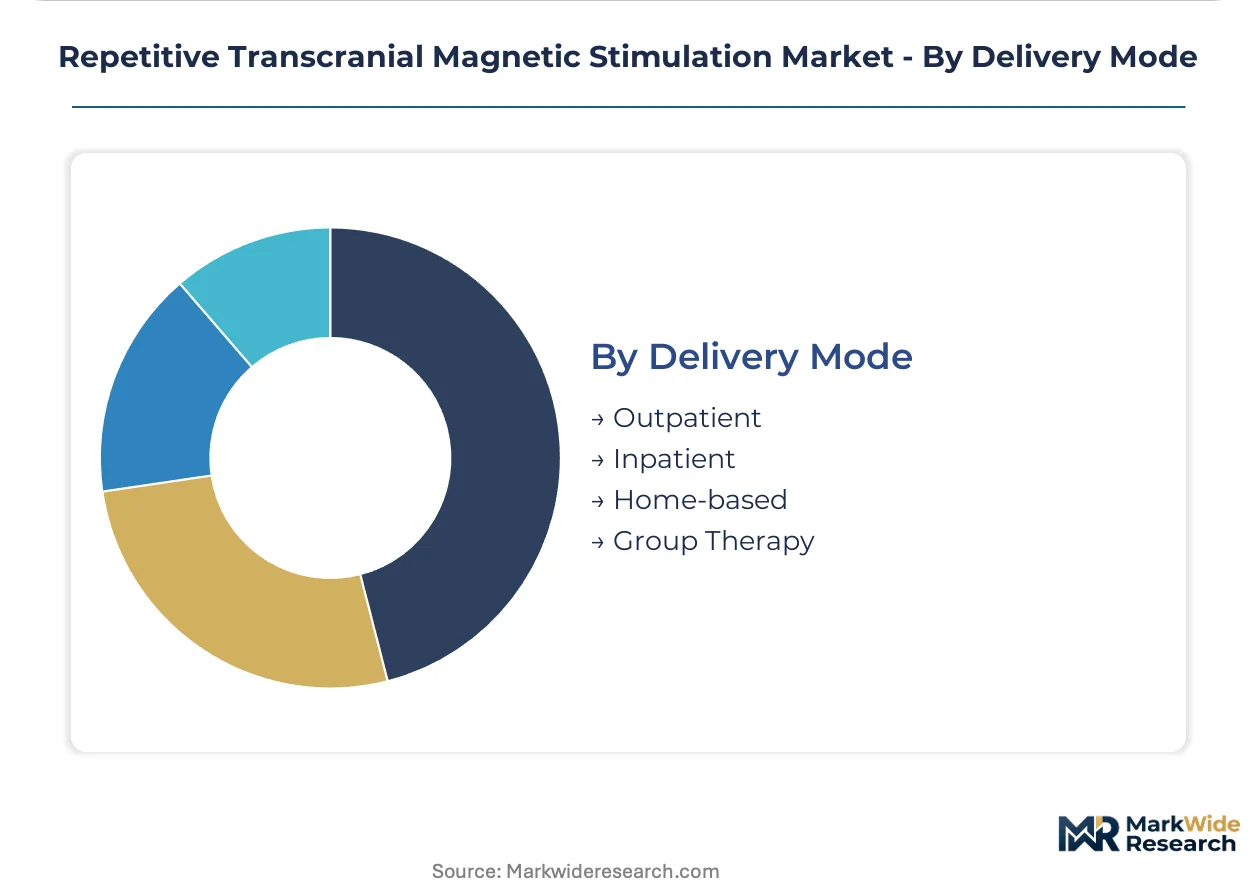
Delivery Mode:
Site-of-care migration pressures hardware specifications toward ambulatory-compatible designs.
- Outpatient:Scheduled clinic visits sustain the majority of treatment-resistant depression protocols. United States reimbursement frameworks favor this setting with established professional fee schedules.
- Inpatient:Acute psychiatric units deploy rTMS for rapid symptom stabilization in severe depressive episodes. Japanese university hospitals lead protocol development for this setting.
- Home-based:Supervised wearable system trials in Israel test remote monitoring feasibility for maintenance therapy.
- Group Therapy:Cost-sharing models in German rehabilitation chains experiment with simultaneous multi-patient delivery.
Outpatient delivery maintains volume leadership. Home-based models are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper refining capacity in northern Chile and rare-earth magnet processing in Jiangxi Province supply coil assembly feedstocks that concentrate device manufacturing in Denmark, Israel, and the United States. Psychiatric clinic networks and academic medical centers in these markets drive protocol standardization through volume purchasing power.
United States
Independent psychiatric practices in Texas and Florida deploy portable devices through operating lease structures that minimize capital expenditure. FDA 510(k) pathways streamline iterative coil design clearances for treatment-resistant depression protocols. Boston's academic medical centers pioneer deep transcranial stimulation applications for obsessive-compulsive disorder under investigator-initiated trials.
Germany
Orthopedic rehabilitation chains in Bavaria and North Rhine-Westphalia integrate rTMS into bundled pain management protocols under statutory health insurance reimbursement. EU Medical Device Regulation clinical evidence requirements extend certification timelines for neuromodulation systems seeking CE marking. Berlin's university hospitals coordinate multi-center stroke rehabilitation trials with Japanese counterparts.
Japan
University hospitals in Tokyo and Osaka deploy deep transcranial stimulation systems for obsessive-compulsive disorder under PMDA oversight with distinct magnetic field safety thresholds. METI technical standards constrain direct product portability from Western markets, forcing hardware redesigns. Nagoya's medical device clusters specialize in precision pulse generator components for domestic manufacturers.
Israel
Academic medical centers in Tel Aviv and Haifa pioneer H-coil applications for smoking cessation through investigator-initiated studies with remote monitoring components. The national digital health infrastructure supports wearable system trials for home-based maintenance therapy. Jerusalem's neurotechnology clusters attract venture funding for software-defined treatment protocols.
Denmark
Captive stimulator electronics production concentrates in Copenhagen-area facilities that supply precision pulse generators to European device manufacturers. Danish manufacturing scale depends on copper coil assemblies sourced through specialized European suppliers. Aarhus's medical technology corridor hosts regulatory affairs capacity dedicated to MDR technical documentation.
Repetitive Transcranial Magnetic Stimulation Market Competitive Landscape
Global majors compete with regional champions across regulatory clearance capabilities and psychiatric clinic network relationships. The vendor base separates into three tiers: integrated system vendors with practice management software bundles, specialized coil architecture developers, and contract manufacturers of stimulator electronics. Consolidation pressure intensifies as EU Medical Device Regulation documentation costs escalate and FDA 510(k) pathway acceleration favors iterative design capabilities. Dominant competitive moves include strategic partnerships with academic medical centers for real-world evidence generation and geographic expansion through distributor relationships in German rehabilitation chains.
Within the integrated system tier, Neuronetics anchors North American installed base positioning through bundled workflow software. Among specialized coil developers, BrainsWay exemplifies deep transcranial stimulation differentiation through H-coil architecture. MagVenture occupies a position within the European manufacturing archetype with captive Danish production of stimulator electronics. These three companies represent distinct strategic postures: software-integrated service models, anatomical targeting specialization, and vertical manufacturing control.
| Leading Market Players |
|---|
| BrainsWay |
| MagVenture |
| Neuronetics |
| Magstim |
| Nexstim |
| eNeura |
| Soterix Medical |
| Neurosoft |
| neurocare group |
| Others |
Value Network & Pricing Analysis
Neurophysiologist training concentrations in Copenhagen and Boston create labor-cost differentials that widen pricing-tier spreads between premium integrated systems and economy portable configurations. Magnetic coil winding specialists command wage premiums that feed into hardware margin structures across Danish and Israeli manufacturing facilities.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium-tier tabletop systems from unbundled portable alternatives where clinics absorb service risk. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, CE marking tier under MDR, and software companion depth. Cost compression in economy portable devices is intensifying because battery-operated stimulators face component standardization pressure. Independent psychiatric practices in Texas and Florida exhibit highest price sensitivity through operating lease preferences, while Japanese university hospitals demonstrate lowest sensitivity given PMDA-mandated safety documentation requirements.
Supply Chain Analysis
Refurbishment flows for precision pulse generators and coil assemblies concentrate in Copenhagen-area facilities that extend equipment lifecycle for European clinic networks. Copper refining in Chile and rare-earth magnet processing in China feed coil assembly production anchored in Denmark and Israel. Single-source vulnerability persists in Danish captive electronics manufacturing where stimulator circuit production rests on limited facilities. Distribution runs through specialized medical device distributors in German rehabilitation chains and direct sales forces in United States psychiatric networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over precision magnetic coil manufacturing and neurophysiologist training pipelines determines margin sustainability.
For Market Incumbents: Hedge against portable device commoditization by deepening software-defined protocol differentiation and securing exclusive H-coil architecture licensing. Lock in Danish and Israeli coil winding capacity through long-term supply agreements before MDR documentation costs trigger supplier consolidation. Defend installed base positioning through practice management workflow integration that raises switching costs for United States psychiatric clinics evaluating alternative hardware platforms. For New Entrants and Emerging Players: Capture white-space in home-based wearable maintenance protocols where Israeli remote monitoring infrastructure and German statutory reimbursement experimentation create favorable entry conditions. Target pain relief applications in German orthopedic rehabilitation chains where bundled diagnosis-related group payments reduce upfront pricing sensitivity. Pursue investigator-initiated trial partnerships with Tel Aviv academic medical centers to generate real-world evidence without full regulatory submission burdens. For Investors and Strategic Acquirers: Re-rating potential sits with specialized coil architecture developers given FDA 510(k) pathway acceleration for iterative designs and expanding obsessive-compulsive disorder protocol approvals. Long-term viability over the five-to-ten year window favors manufacturers with established patient registries that satisfy EU Medical Device Regulation post-market surveillance mandates. Monitor PMDA technical standard harmonization discussions as the inflection signal for Japanese market entry cost reduction.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | CE marking pathway acceleration for neuromodulation systems seeking European market access under tightened clinical evidence requirements. |
| Precision Coil Manufacturing Scale-Up | Captive production capacity in Danish facilities secures stimulator electronics supply for European device manufacturers facing commodity volatility. |
| Deep Transcranial Stimulation Protocol Expansion | H-coil architecture differentiation opens obsessive-compulsive disorder and smoking cessation indications beyond depression treatment. |
| Portable Device Battery Technology Partnership | Lightweight power systems enable clinic deployment flexibility across multiple treatment rooms without fixed infrastructure investment. |
| Neurophysiologist Training Pipeline Development | Specialized operator certification programs address scarcity of clinicians capable of motor threshold determination and coil positioning. |
Research Methodology
Document review covered FDA 510(k) filings, EU Medical Device Regulation technical documentation, PMDA safety standards, and hospital procurement databases, complemented by interviews with psychiatric clinic administrators, biomedical engineers, GPO contracts managers, and regulatory affairs specialists. Secondary validation drew from CMS Medicare reimbursement data, statutory health insurance framework documents, and medical device trade flow records. Bottom-up installed base estimates and top-down market sizing triangulated through cross-reference with manufacturer production disclosures.
Segment-level projections across product type, end user, application, and delivery mode dimensions were generated through adoption curve modeling and reimbursement pathway maturity scoring. CAGRs were derived from logistic growth function calibration against historical penetration rates in comparable neuromodulation modalities. Forecast inputs incorporated neurophysiologist training pipeline capacity constraints and MDR certification timeline distributions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PMDA standard harmonization progress and copper commodity price trajectories. Practitioners should monitor FDA 510(k) clearance velocity for novel coil geometries and German rehabilitation chain bundled procurement announcements for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Canada Varicose Vein Treatment Devices Market
Medical Devices
Veterinary X-Ray Illuminators Market
Medical Devices
Parenteral Feeding Devices Market
Medical Devices
Robotics-Assisted Telesurgery Market
Medical Devices
Ophthalmic Ultrasound Devices Market
Medical Devices
Nerve Repair and Regeneration Market
Medical Devices
Global Stroke Assistive Devices Market
Medical Devices
Global Vitreoretinal Surgery Devices Market
Medical Devices
Gracey Curette Market
Medical Devices
Sweden Respiratory Devices Market
Medical Devices
Tracheobronchial Suction Catheters Market
Medical Devices
Knee Reconstruction Devices Market
Medical Devices
Phakic Intraocular Lenses (IOL) Market
Medical Devices
Endoscopic Mucosal Resection Device Market
Medical Devices
Non-Destructive Medical Technologies Market
Medical Devices
Enteral Stents Market