
 Brazil Minimally Invasive Surgery Devices Market | 2026-2036
Brazil Minimally Invasive Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Minimally Invasive Surgery Devices Market Outlook
Market Dynamics
Equipment leasing and pay-per-procedure financing is fragmenting the competitive landscape for high-cost robotic and laparoscopic platforms in Brazil. Medtronic leverages its broad catheter and stapler portfolio to sustain presence across public and private channels. Intuitive Surgical anchors the robotic surgery segment through its installed base of da Vinci systems in tertiary hospitals. Siemens Healthineers competes by integrating imaging systems with navigation software for complex minimally invasive procedures.
Technology and Segmentation
Minimally invasive surgery devices encompass precision instruments designed for insertion through small incisions or natural orifices, typically requiring diameters under 12 millimeters and compatibility with carbon dioxide insufflation systems to maintain operative visibility. These tools reduce tissue trauma, blood loss, and recovery time compared to open surgical approaches. Laparoscopy leads procedure volume across gynecology and general surgery applications, while robotic surgery captures premium positioning in urologic and cardiac interventions where stereotactic navigation enhances precision. Endoscopes and surgical staplers concentrate margin pools in the product type dimension due to recurring replacement cycles and disposable component attach rates.
Regulatory Environment
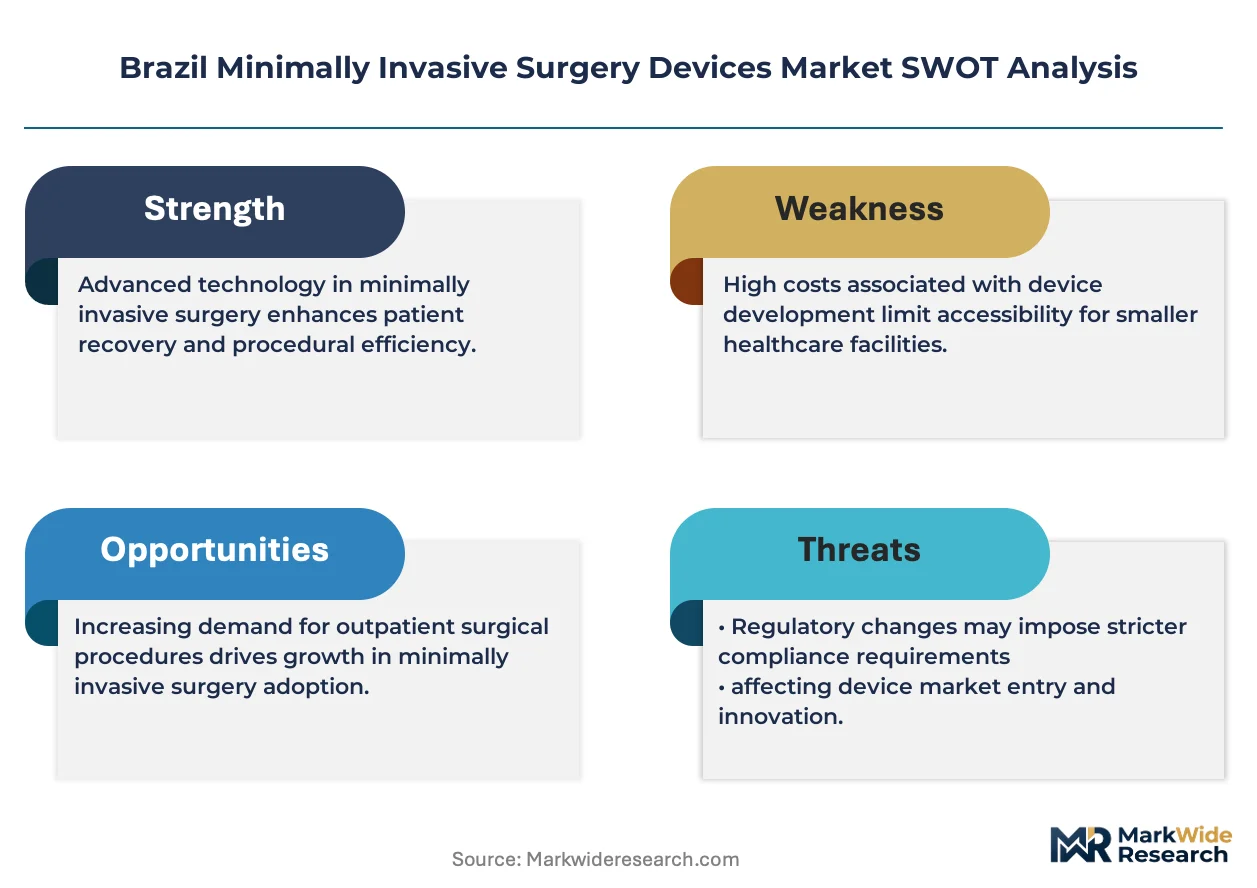
ANVISA governs medical device registration and post-market surveillance for minimally invasive surgery devices in Brazil, with specific requirements for sterile single-use instruments and reusable device reprocessing validation. The Brazilian Health Regulatory Agency's alignment with Mercosur harmonization protocols shapes import pathways for multinational manufacturers. ISO 13485 certification and INMETRO conformity assessments create baseline compliance thresholds for market access. Stakeholders must monitor ANVISA's pending updates to software-as-a-medical-device regulations, as algorithm-driven surgical navigation tools trigger new classification debates that will reshape competitive requirements.
Market Dynamics
Equipment leasing and pay-per-procedure financing is fragmenting the competitive landscape for high-cost robotic and laparoscopic platforms across Brazil's public and private hospital networks.
Growth Catalysts
- ANVISA Registration Pathways:Compressed approval timelines for imported laparoscopic instruments accelerate market entry for multinational manufacturers serving state health procurement consortiums.
- Metropolitan Procedure Concentration:São Paulo's private hospital chains and academic medical centers generate the highest minimally invasive surgery volumes, anchoring demand for advanced platforms.
- Carbon Dioxide Insufflation Compatibility:Instruments requiring diameters under 12 millimeters align with established surgical infrastructure, reducing adoption friction across gynecology and general surgery departments.
Market Restraints
- Capital Intensity:Robotic surgery platforms demand substantial upfront investment, restricting installed base expansion beyond tertiary hospitals and limiting penetration in municipal health networks.
- Import Dependency:Sterile single-use instruments and precision components concentrate supply in European and North American manufacturing clusters, exposing buyers to currency volatility and logistics disruptions.
- Reprocessing Validation Burden:ANVISA requirements for reusable device sterilization protocols create compliance overhead that slows equipment turnover cycles in public facilities.
Strategic Opportunities
- Northeast Regional Expansion:Underpenetrated state health networks in Pernambuco and Ceará present whitespace for leasing models that bypass capital expenditure constraints.
- Software-as-a-Medical-Device Classification:ANVISA's pending algorithm-driven surgical navigation regulations will create first-mover advantages for navigation-integrated imaging platforms.
- Academic Medical Center Partnerships:Training and proctoring service bundles tied to robotic system placements secure long-term consumable attach rates in high-volume surgical corridors.
Industry Challenges
- Specialized Surgeon Training Pipeline:Robotic and advanced laparoscopic credentialing programs remain concentrated in São Paulo and Rio de Janeiro, constraining platform utilization in secondary cities.
- INMETRO Conformity Assessment Timelines:Electromechanical safety testing for powered staplers and energy devices extends certification cycles, delaying product launches against competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Minimally Invasive Surgery Devices Market |
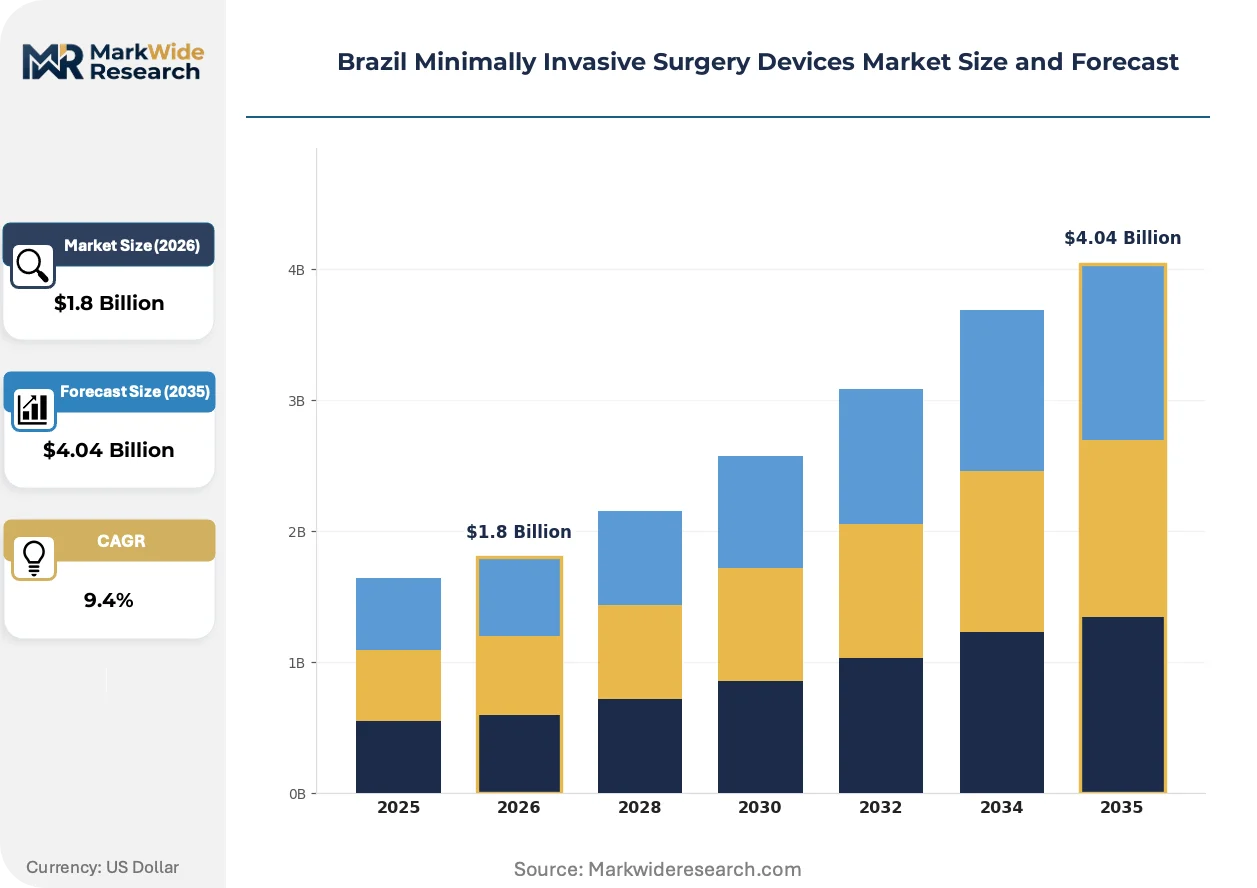
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
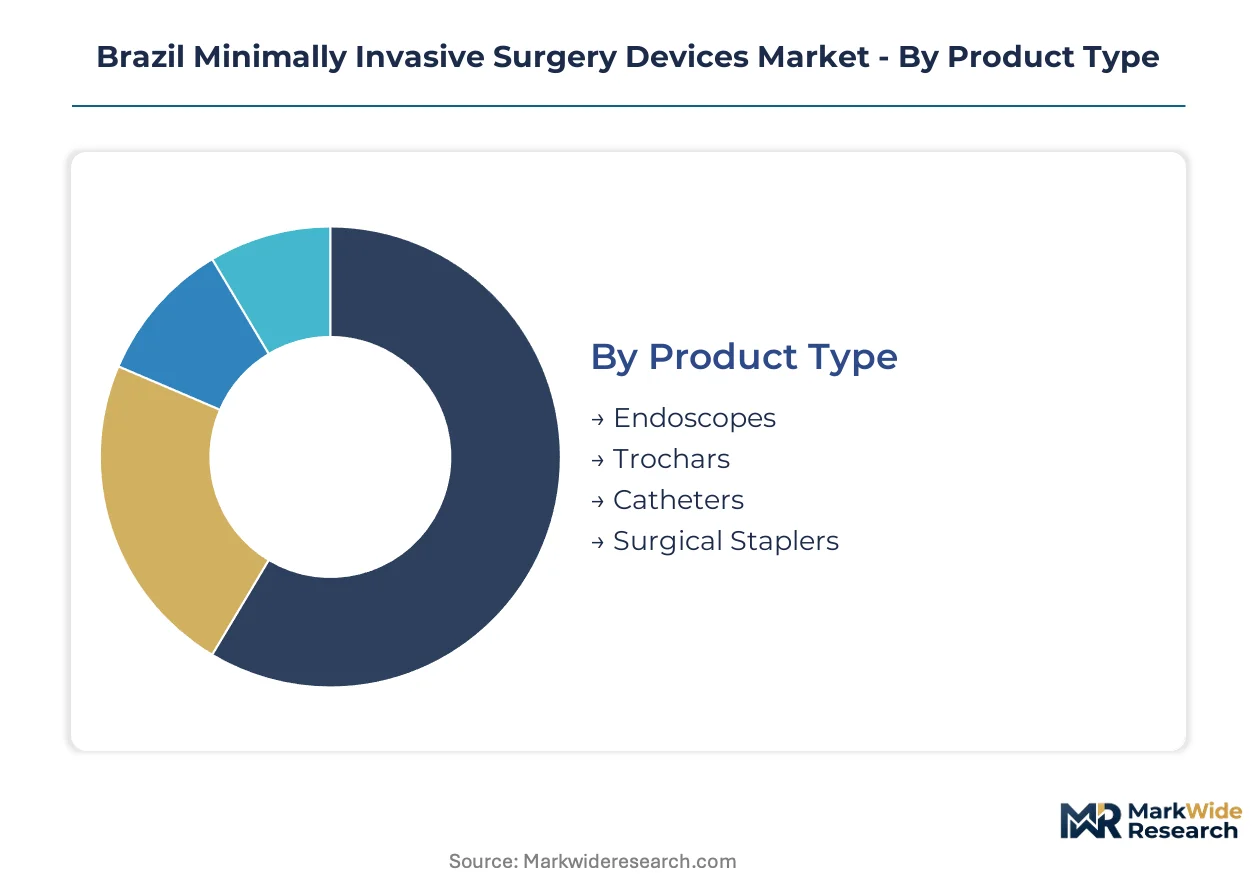
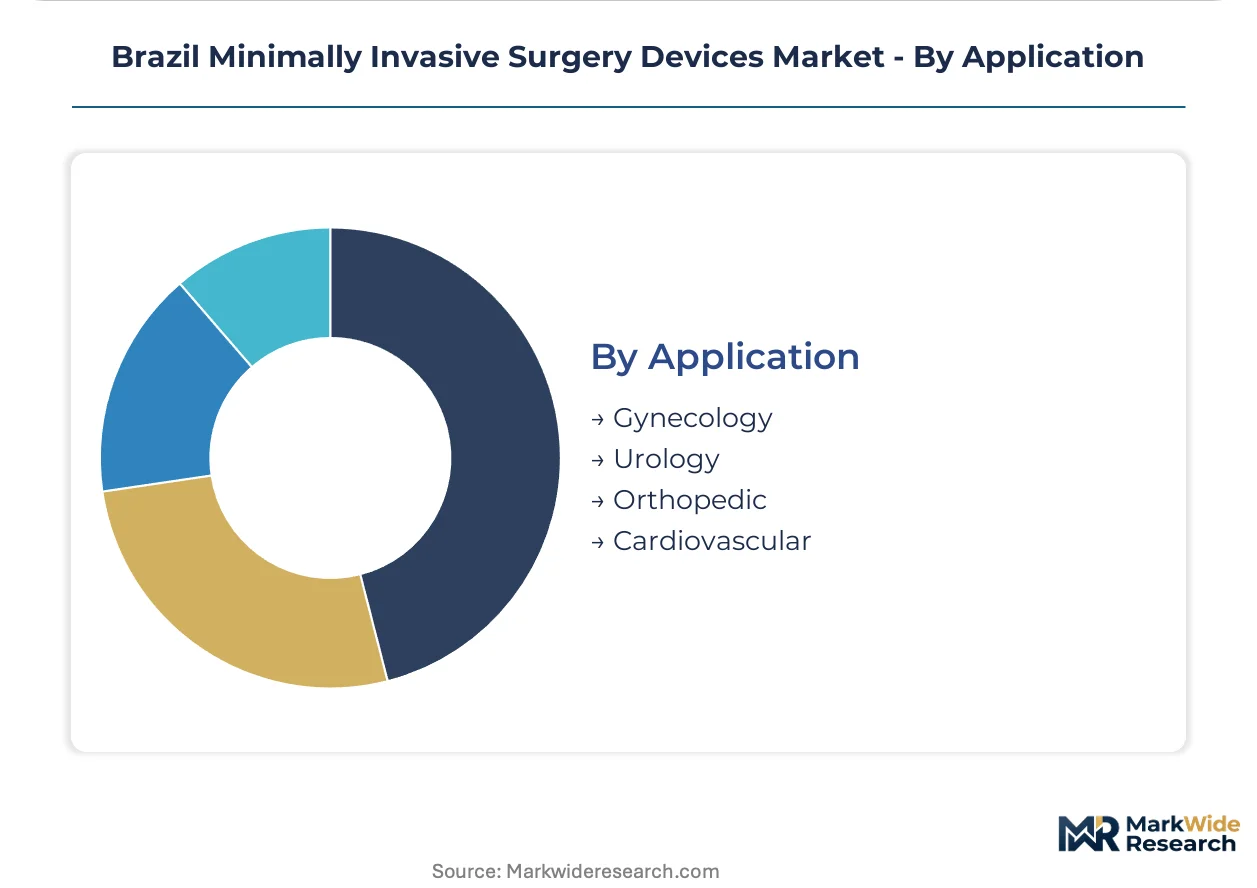
| Segmentation | Product Type: Endoscopes, Trochars, Catheters, Surgical Staplers Technology: Robotic Surgery, Laparoscopy, Stereotactic Navigation, Imaging Systems End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialty Centers Application: Gynecology, Urology, Orthopedic, Cardiovascular |
| Companies Covered | Medtronic, Intuitive Surgical, Siemens Healthineers, Abbott Laboratories, Zimmer Biomet, GE Healthcare, Olympus Corporation, Smith & Nephew, Stryker Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Minimally Invasive Surgery Devices Market Strategic Shifts
Digital integration and alternative financing architectures are restructuring how surgical platforms reach Brazilian healthcare providers, compressing traditional equipment procurement cycles.
Telepresence-assisted surgical mentoring is virtualizing the expertise transfer model between academic centers and community hospitals. Tertiary institutions in São Paulo now deploy remote proctoring for complex robotic procedures, collapsing the geographic distance between training hubs and expanding surgical sites. This virtualization enables faster credentialing pipelines without requiring physical specialist relocation.
ANVISA's alignment with Mercosur harmonization protocols is reshaping import documentation requirements for multinational manufacturers. Simplified technical dossier recognition across member states reduces redundant testing burdens, accelerating registration timelines for sterile single-use instrument portfolios. Brazilian distributors are consolidating logistics networks to capitalize on these streamlined pathways.
Hospital purchasing cooperatives are aggregating demand across state networks to negotiate volume-based robotic surgery access. Public procurement consortiums in Minas Gerais and Rio Grande do Sul now bundle procedure minimums with equipment leases, displacing traditional capital purchase models. This aggregation concentrates negotiating leverage with platform vendors while spreading fixed costs across broader patient populations.
Brazil Minimally Invasive Surgery Devices Market Segmentation
Segmentation in Brazil's minimally invasive surgery devices market reveals how procurement patterns, clinical workflows, and regulatory pathways concentrate value across distinct product and customer dimensions. Understanding these divides exposes where leasing models, training investments, and ANVISA registration strategies yield differential returns.
Product Type:
Cost tier stratification across instruments determines margin capture and replacement cycle economics for Brazilian distributors serving public and private channels.
- Endoscopes:Fiber-optic and video-based visualization systems with rigid or flexible configurations enable operative visibility through natural orifices or small incisions. São Paulo's academic medical centers anchor replacement demand for 4K and 3D-enabled platforms as training programs expand. ANVISA's sterilization validation requirements for reusable scopes create compliance overhead that slows turnover in municipal hospitals.
- Surgical Staplers:Disposable linear and circular stapling devices with titanium or polymer cartridges deliver tissue approximation and hemostasis in laparoscopic procedures. Private hospital chains in Rio de Janeiro and Belo Horizonte drive premium attach rates for powered variants with integrated cutting mechanisms. Supply concentration in European manufacturing clusters exposes buyers to currency volatility.
- Trochars:Access ports with blunt or bladeless tips establish pneumoperitoneum and instrument entry channels.
- Catheters:Flexible delivery conduits for irrigation, suction, or device deployment in minimally invasive fields.
Surgical staplers hold installed capacity. Endoscopes are rotating up the share rankings.
Technology:
Application intensity across surgical specialties shapes platform selection, with precision requirements and reimbursement levels driving technology tier adoption.
- Robotic Surgery:Telemanipulation platforms with articulated instruments and 3D visualization enable tremor-filtered precision in confined anatomical spaces. Tertiary hospitals in São Paulo's metropolitan corridor concentrate installed base expansion for urologic and cardiac procedures. Capital intensity restricts penetration beyond state capital networks.
- Laparoscopy:Manual instrument systems with carbon dioxide insufflation compatibility support tissue manipulation through 5-12 millimeter ports. General surgery and gynecology departments across Minas Gerais and Rio Grande do Sul generate highest procedure volumes. Equipment leasing models are fragmenting competitive access.
- Stereotactic Navigation:Image-guided positioning systems align instruments with preoperative planning data.
- Imaging Systems:Intraoperative visualization hardware including C-arms and ultrasound consoles.
Laparoscopy holds installed capacity. Robotic surgery is rotating up the share rankings.
End User:
Customer type concentration determines purchasing authority, with procurement consortiums aggregating demand across facility networks.
- Hospitals:Tertiary and secondary acute care facilities with dedicated surgical suites and anesthesia support. Public hospital procurement consortiums in state health networks are expanding access to robotic platforms through volume-based equipment leases. São Paulo and Rio de Janeiro anchor highest capital investment.
- Ambulatory Surgical Centers:Same-day procedure facilities with streamlined recovery protocols and lower overhead structures. Private equity-backed chains in southeastern Brazil drive laparoscopic cholecystectomy and hernia repair volumes. Pay-per-procedure financing aligns equipment costs with utilization.
- Clinics:Office-based or limited-procedure settings with basic endoscopic capabilities.
- Specialty Centers:Disease-focused facilities concentrating urologic, gynecologic, or orthopedic interventions.
Hospitals hold installed capacity. Ambulatory surgical centers are rotating up the share rankings.
Application:
Volume distribution across clinical specialties reflects demographic disease burden and surgeon training pipeline availability.
- Gynecology:Hysterectomy, myomectomy, and endometriosis procedures via laparoscopic and robotic access routes. São Paulo's private hospital chains generate highest volumes for minimally invasive hysterectomy, with da Vinci platforms anchoring premium positioning. Training program concentration sustains utilization.
- Urology:Prostatectomy, nephrectomy, and reconstructive procedures demanding precision in pelvic and retroperitoneal spaces. Robotic surgery captures dominant share in radical prostatectomy due to nerve-sparing requirements. Academic medical centers credential regional referral patterns.
- Orthopedic:Arthroscopic joint procedures and minimally invasive fracture fixation.
- Cardiovascular:Valve repair, coronary bypass, and structural heart interventions via thoracoscopic or robotic access.
Gynecology holds installed capacity. Urology is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's import dependency for precision surgical instruments shapes regional demand distribution, with foreign exchange volatility concentrating procurement power in southeastern metropolitan corridors while state health networks in peripheral regions face access constraints.
São Paulo
Private hospital chains and academic medical centers in São Paulo's metropolitan corridor generate the highest minimally invasive surgery volumes nationwide. ANVISA's compressed approval timelines for imported laparoscopic instruments accelerate market entry for multinational manufacturers serving this cluster. Tertiary hospitals in the capital anchor installed base expansion for robotic surgery platforms.
Minas Gerais
Public hospital procurement consortiums in Minas Gerais aggregate demand across state health networks to negotiate volume-based robotic surgery access. Equipment leasing models displace traditional capital purchases, spreading fixed costs across broader patient populations. Belo Horizonte's secondary hospitals drive laparoscopic procedure volumes in general surgery and gynecology departments.
Rio de Janeiro
Private equity-backed ambulatory surgical centers in Rio de Janeiro concentrate pay-per-procedure financing for laparoscopic cholecystectomy and hernia repair. INMETRO conformity assessment timelines for powered staplers extend certification cycles, delaying product launches. The metropolitan area's training programs sustain surgeon credentialing pipelines.
Rio Grande do Sul
State health networks in Rio Grande do Sul bundle procedure minimums with equipment leases through purchasing cooperatives. Portuense Alegre's hospital consortiums negotiate consolidated procurement for disposable instrument portfolios. Currency exposure from European manufacturing clusters complicates supply planning for sterile single-use components.
Pernambuco
Underpenetrated state health networks in Pernambuco present whitespace for leasing models that bypass capital expenditure constraints. Recife's emerging surgical corridors lack robotic platform density, constraining complex procedure referral patterns. Northeast regional expansion depends on telepresence-assisted mentoring from southeastern training hubs.
Brazil Minimally Invasive Surgery Devices Market Competitive Environment
On the supply side, the industry is consolidating around multinational platform vendors with broad instrument portfolios and regional distributors with logistics consolidation capabilities. Equipment leasing and pay-per-procedure financing fragment competitive access across public and private channels. Strategic archetypes include integrated platform vendors with recurring consumable revenue, imaging-system integrators with navigation software bundles, and regional distributors with ANVISA registration expertise. Dominant competitive moves encompass academic medical center partnerships securing long-term training contracts and logistics network consolidation capitalizing on Mercosur harmonization protocols.
Among multinational platform vendors, Medtronic and Intuitive Surgical exemplify contrasting archetypes in Brazil's minimally invasive surgery landscape. Medtronic leverages its broad catheter and stapler portfolio to sustain presence across public procurement consortiums and private hospital chains. Intuitive Surgical anchors the robotic surgery segment through its installed base of da Vinci systems in tertiary hospitals, with training and proctoring service bundles securing consumable attach rates. Siemens Healthineers occupies a position integrating imaging systems with navigation software for complex procedures, competing on digital workflow convergence rather than standalone instrument sales.
| Leading Market Players |
|---|
| Medtronic |
| Intuitive Surgical |
| Siemens Healthineers |
| Abbott Laboratories |
| Zimmer Biomet |
| GE Healthcare |
| Olympus Corporation |
| Smith & Nephew |
| Stryker Corporation |
| Others |
Value Chain & Pricing Dynamics
São Paulo's distributor consolidation corridor concentrates procurement leverage for multinational instrument portfolios, translating upstream manufacturing scale into tiered pricing power across Brazilian hospital networks. ANVISA registration timelines and INMETRO conformity burdens feed into landed cost structures that stratify final pricing.
Pricing Analysis
Public hospital procurement consortiums anchor a contract-based long-term offtake model with volume-scaled discounts. Pricing stratifies across premium, standard, and economy tiers based on sterilization validation burden and brand certification lineage. Cost compression in the economy tier is intensifying because municipal health networks aggregate demand through purchasing cooperatives. Public procurement managers exhibit highest price sensitivity; private academic medical centers demonstrate lowest sensitivity due to training program subsidies.
Supply Chain Analysis
Currency volatility between Brazil and European manufacturing clusters dominates supply chain risk exposure for sterile single-use instruments. Production concentrates in Germany, Switzerland, and the United States for precision laparoscopic components and robotic surgery platforms. Raw material dependencies span medical-grade stainless steel, polymer resins for disposable cartridges, and fiber-optic bundles for visualization systems. Distribution runs through regional distributors with ANVISA registration expertise serving state health networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's minimally invasive surgery devices market functions as a defensive-moat arena where ANVISA regulatory entrenchment creates substantial switching costs for hospital procurement committees.
For Market Incumbents: Harden installed base protection by embedding training and proctoring service bundles that lock in consumable attach rates. Deepen backward integration into sterile single-use instrument manufacturing to offset currency exposure from European supply clusters. Capacity addition in São Paulo's metropolitan corridor reinforces proximity to highest-volume surgical sites. For New Entrants and Emerging Players: Northeast regional state health networks in Pernambuco and Ceará represent the most penetrable entry point for leasing models that bypass capital expenditure constraints. Municipal hospitals in secondary cities lack robotic platform density and credentialing infrastructure. A software-as-a-medical-device navigation bundle tied to existing imaging hardware offers the lowest-friction go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional distributors with ANVISA registration expertise and consolidated logistics networks. Long-term viability hinges on capturing recurring consumable revenue streams rather than episodic equipment sales. Watch ANVISA's pending algorithm-driven surgical navigation regulations as the signal for first-mover classification advantages.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Pathway Acceleration | Compressed timelines for multinational manufacturers serving state procurement consortiums compress competitive windows. |
| Hospital System Partnership | Academic medical center training contracts secure long-term consumable attach rates in high-volume corridors. |
| Software Companion Development | Navigation-integrated imaging platforms capture first-mover positioning pending ANVISA algorithm regulations. |
| Reimbursement Strategy | Alignment with SUS procedural coding determines access expansion across public health networks. |
| Geographic Expansion | Northeast regional leasing models bypass capital constraints in underpenetrated state health systems. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and ANVISA regulatory affairs specialists. Secondary validation drew from hospital procurement databases, GPO contract filings, ANVISA registration records, and CMS-equivalent SUS reimbursement schedules. Bottom-up procedure volume estimates and top-down equipment installed base analysis were triangulated to anchor market sizing.
Calibration against historical ANVISA approval trajectories and equipment placement patterns shaped the analytical framework across the projection horizon. Segmentation dimensions encompassed product type tiers, technology platforms, end-user facility categories, and application-specific procedure volumes. CAGRs were derived from fitted adoption curves incorporating surgeon training pipeline expansion and procurement consortium formation timelines. Forecast inputs included carbon dioxide insufflation infrastructure penetration and telepresence-assisted mentoring virtualization rates.
Macroeconomic conditions sit as an overlay; deviation in BRL-EUR exchange rates or SUS budget allocation trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding ANVISA regulatory pathway stability and Mercosur harmonization protocol continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Artificial Implants Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Mexico General Surgical Devices Market
Medical Devices
MIS Sacroiliac Joint Fusion Market
Medical Devices
Portable Medical Devices Market
Medical Devices
Hemodialysis Catheters Market
Medical Devices
Thrombectomy System Market
Medical Devices
Wearable Bioelectronic Skin Patches Market
Medical Devices
Hysterectomy Devices Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
North America Electroencephalography Devices Market
Medical Devices
South Korea ECG Market
Medical Devices
Pressure Mapping Systems in Healthcare Market
Medical Devices
Life Science and Chemical Instruments Market
Medical Devices
Neurovascular Catheters Market
Medical Devices
Intravenous Stopcock Market