
 Neurovascular Devices Market | 2026-2036
Neurovascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Neurovascular Devices Market Analysis
Next-generation flow diversion specifications is unwinding competitive dynamics across the neurovascular landscape. Medtronic leverages its integrated neuroscience platform to sustain catheter and coil development pipelines. Stryker anchors its position through dedicated stroke care capital equipment bundled with thrombectomy devices. Penumbra differentiates via aspiration-based clot retrieval systems that occupy a distinct technology tier from stent retrievers.
Neurovascular devices encompass implantable and interventional instruments—typically constructed from nitinol, platinum-tungsten alloys, or braided cobalt-chromium mesh—engineered to restore cerebral blood flow, occlude aneurysms, or remove thromboembolic material through minimally invasive endovascular access. Thrombectomy devices command the largest revenue pool due to time-critical stroke intervention protocols, while flow diversion technology represents the fastest-expanding segment as surgeons adopt aneurysm treatments that preserve parent artery patency. Coil embolization remains mature with stable procedural economics, whereas balloon catheters concentrate margin opportunities in carotid artery revascularization cases.
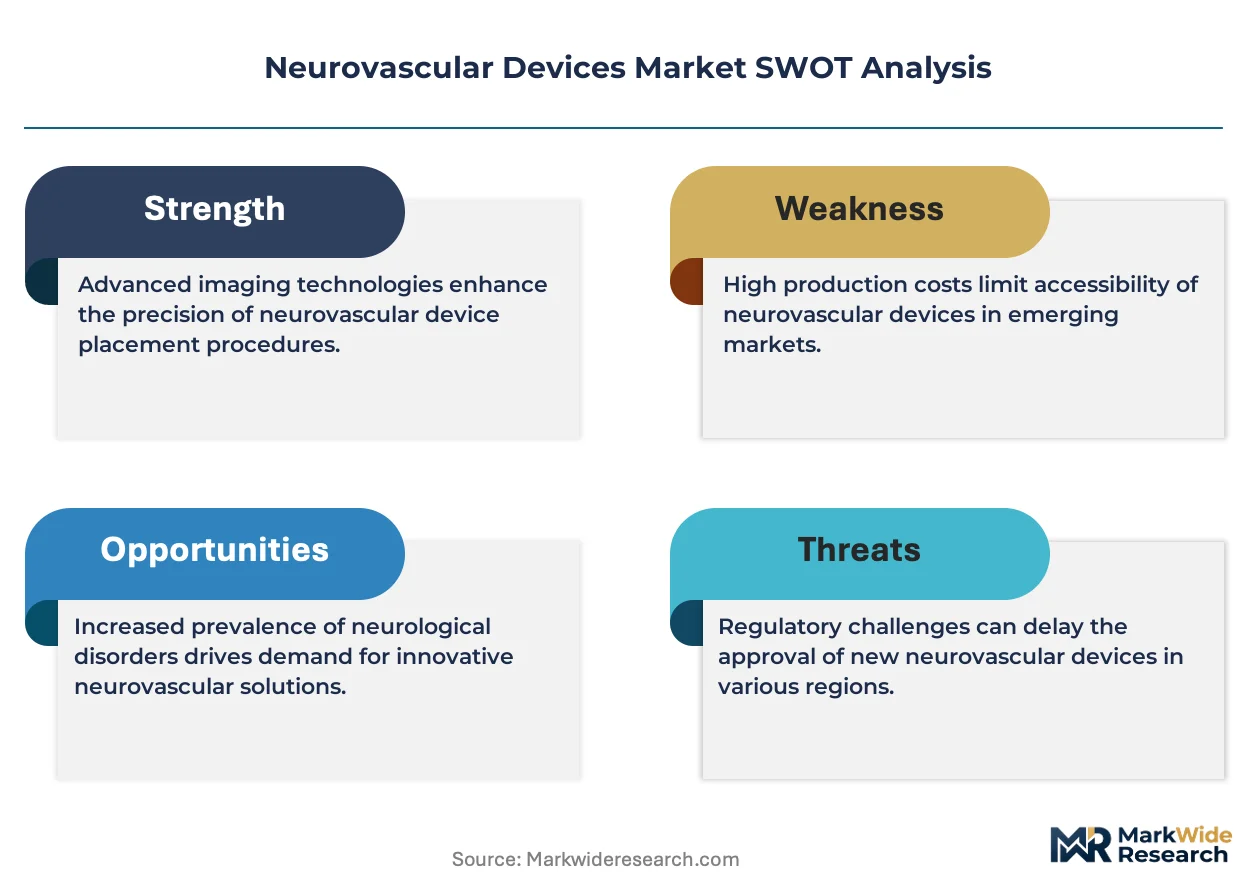
The FDA breakthrough device program compresses premarket review timelines for novel stroke interventions, while the EU MDR recertification burden is reshaping competitive access across European hospitals. Japan's PMDA Sakigake designation accelerates first-in-country approvals for mechanical thrombectomy platforms, creating asymmetric launch windows. Stakeholders must monitor how reimbursement granularity for stroke severity tiers influences capital allocation between thrombectomy hardware and adjunctive imaging systems.
Market Dynamics
Mechanical thrombectomy protocol standardization in stroke centers is compressing device procurement cycles and forcing hardware-software bundling decisions across hospital capital committees.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited premarket review timelines compress commercialization pathways for flow diversion platforms, accelerating physician training program rollouts.
- Japan's PMDA Sakigake Framework:Priority review status for mechanical thrombectomy systems creates first-mover advantages in aging demographic markets with high procedural volume potential.
- Nitinol Braiding Automation:Advanced laser-cut stent manufacturing reduces unit production costs while improving radial force consistency in aneurysm bridging applications.
Market Restraints
- Platinum-Tungsten Alloy Concentration:Supply chain vulnerability concentrates in specialized foundry capacity, exposing coil embolization device margins to precious metal price volatility.
- EU MDR Recertification Burden:Clinical evidence requirements for legacy flow diverters are extending renewal timelines and raising compliance costs for mid-tier manufacturers.
- Microcatheter Tip Precision Limits:Sub-millimeter diameter constraints restrict deliverability in tortuous distal vasculature, capping addressable aneurysm anatomies.
Strategic Opportunities
- India's Stroke Center Expansion:Greenfield interventional neurology programs in tier-2 cities create first-installation demand for integrated thrombectomy suites without legacy equipment displacement.
- Aspiration-First Protocol Convergence:Hybrid clot retrieval workflows combining direct aspiration with stent retriever backup are opening technology licensing partnerships between device categories.
- Telestroke Network Integration:Hub-and-spoke diagnostic connectivity mandates are embedding device selection algorithms into purchasing decisions at spoke hospitals.
Industry Challenges
- Interventional Neuroradiologist Training Pipeline:Fellowship program capacity constraints limit procedural volume scaling even where device availability expands.
- Image-Guidance System Interoperability:Proprietary software protocols between angiography platforms and thrombectomy devices force redundant capital expenditure in multi-vendor environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurovascular Devices Market |
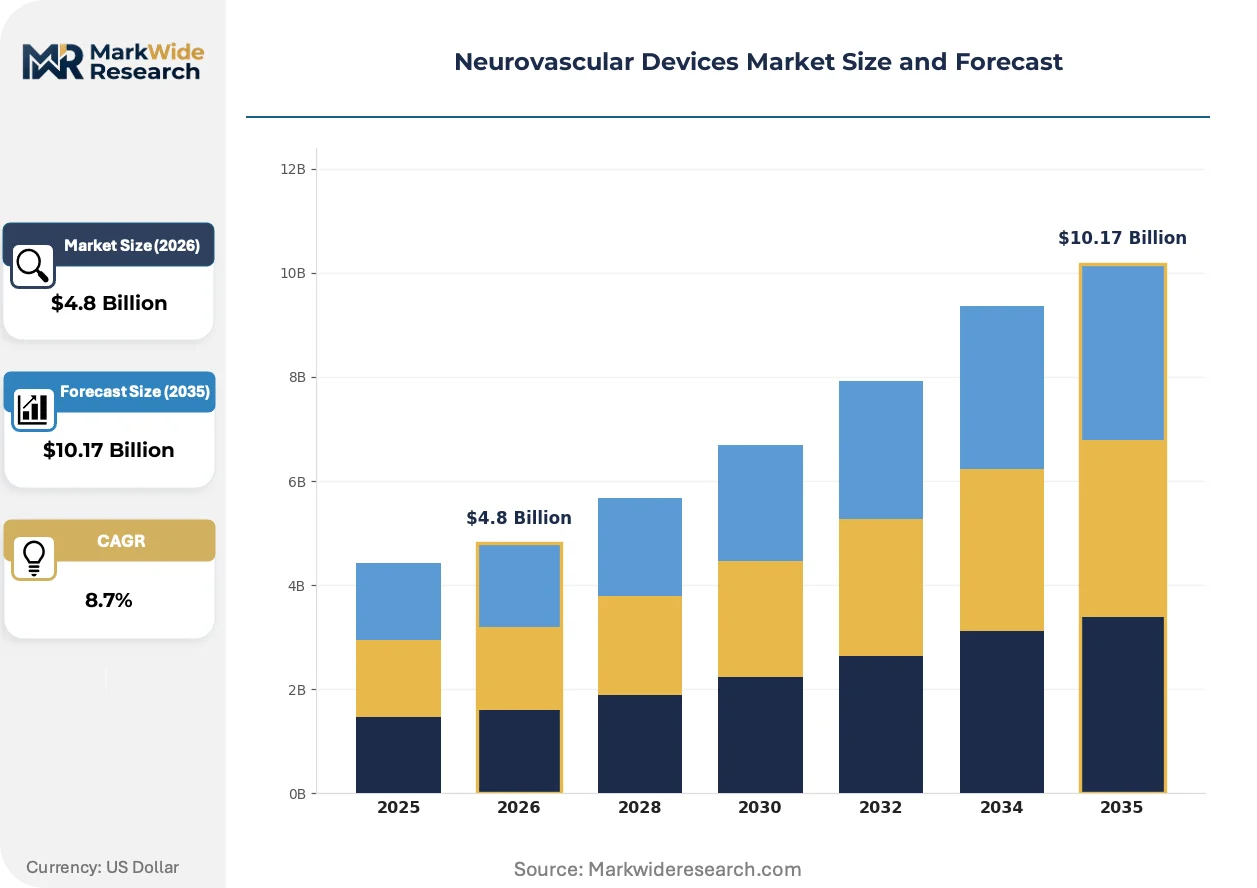
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Coils, Balloon Catheters, Thrombectomy Devices End User: Hospitals, Outpatient Facilities, Emergency Departments, Specialty Clinics Technology: Mechanical Thrombectomy, Flow Diversion, Intravenous Thrombolysis, Stent Retrieval Application: Aneurysm Treatment, Stroke Management, Arteriovenous Malformations, Carotid Artery Disease |
| Companies Covered | Medtronic, Stryker, Penumbra, Johnson & Johnson, Terumo Corporation, MicroVention, Acandis GmbH, Asahi Intecc, Merit Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurovascular Devices Market Emerging Trajectories
Device intelligence integration and procedural workflow compression are redefining competitive differentiation beyond standalone mechanical performance metrics.
Bioactive surface coatings on flow diverters are supplanting bare metal mesh in large and giant aneurysm cases. Academic medical centers in Germany and the United States are adopting polymer-modified devices at accelerating cadence despite premium positioning. The shift is supplanting traditional coil-plus-stent reconstruction protocols and collapsing the addressable market for standalone embolization coils in complex anatomies.
EU MDR post-market surveillance requirements are mandating real-world evidence collection through national stroke registries. Device manufacturers must now fund longitudinal outcome studies as a condition of continued market access. Flow diversion platforms face the steepest evidence burden given their novel mechanism and extended follow-up timelines.
Hospital purchasing committees are consolidating neurovascular device procurement under value-analysis frameworks that weight total procedure cost against ninety-day outcome metrics. Bundled payment pilots in Medicare stroke care are replacing fee-for-service device reimbursement in select US markets. This behavioral pivot concentrates contract awards at integrated delivery networks with sufficient case volume to absorb outcome risk.
Neurovascular Devices Market Segmentation
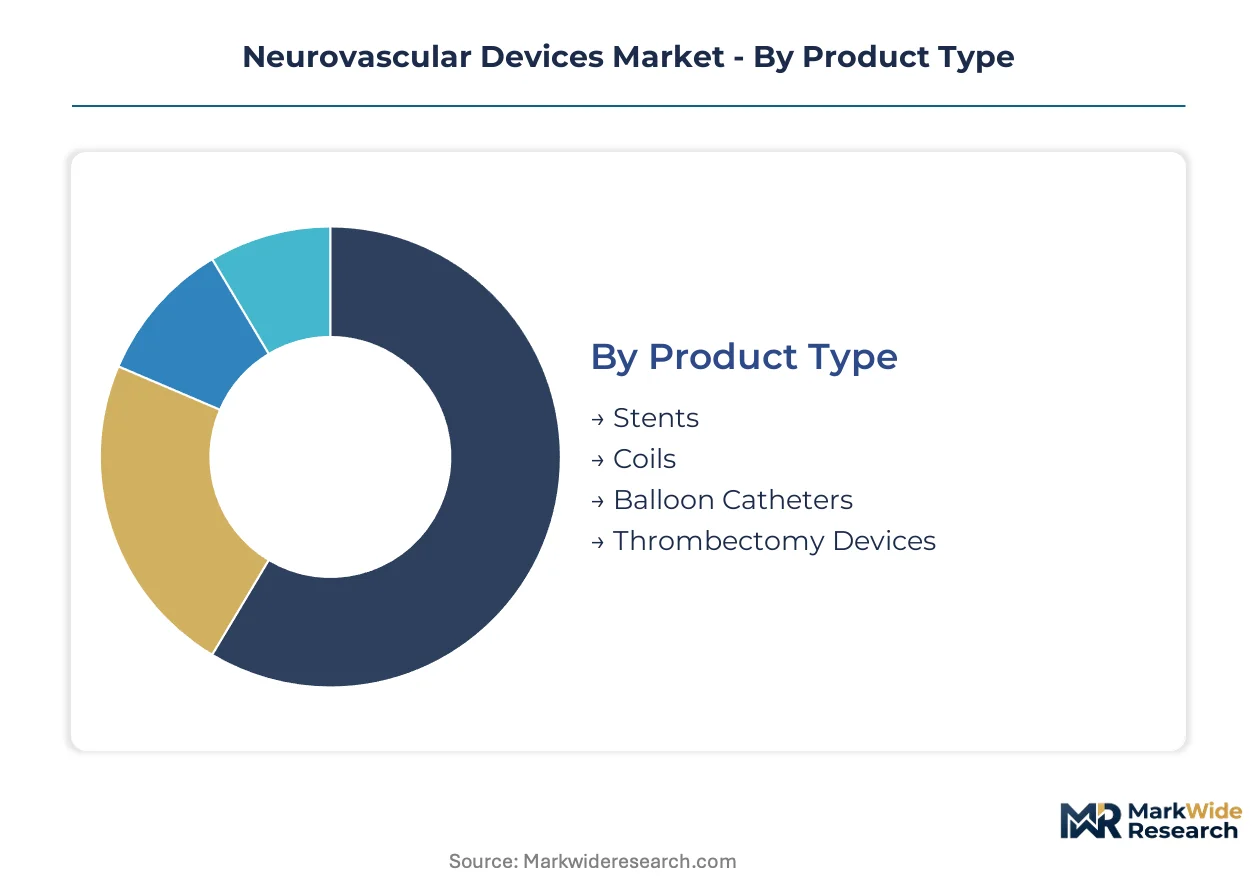
Device procurement in neurovascular care follows distinct channel logic. Hospital capital committees bundle thrombectomy hardware with imaging systems, while outpatient facilities prioritize single-use disposables with minimal capital footprint.
Product Type:
Channel distribution varies sharply by capital intensity and sterilization requirements. Thrombectomy systems flow through integrated stroke center contracts, while coils and balloons distribute via distributor networks serving mixed surgical volumes.
- Thrombectomy Devices:Aspiration catheters and stent retrievers constructed from nitinol and platinum-tungsten alloys enable mechanical clot extraction in acute ischemic stroke. Demand concentrates in US comprehensive stroke centers where door-to-device time protocols mandate 24/7 device availability. FDA breakthrough designation accelerates commercialization timelines for next-generation platforms.
- Stents:Laser-cut nitinol or cobalt-chromium mesh constructs maintain vessel patency in carotid revascularization and aneurysm bridging. German tertiary hospitals lead adoption of flow-diverting stent variants, driven by reimbursement clarity for complex aneurysm anatomies previously managed with open surgery.
- Coils:Platinum-tungsten filament devices deliver aneurysm occlusion through catheter-based deployment. Japan's aging demographic sustains procedural volume in established coil-embolization protocols.
- Balloon Catheters:Compliant and non-compliant balloon systems enable angioplasty and flow control during stent deployment. Outpatient angiography suites in India favor disposable balloon platforms for cost-sensitive carotid interventions.
By volume, coils lead due to mature aneurysm treatment protocols. By growth pace, thrombectomy devices are climbing the fastest as stroke center certification expands.
End User:
Capital allocation patterns separate high-acuity settings from ambulatory environments. Emergency departments prioritize device readiness over cost optimization, while specialty clinics negotiate procedure-specific bundles.
- Hospitals:Comprehensive stroke centers and tertiary neurosurgical units maintain dedicated interventional suites with multimodal device inventories. US integrated delivery networks consolidate purchasing across hub-and-spoke systems.
- Emergency Departments:Frontline stroke triage locations require immediate device access for time-critical thrombectomy decisions. Japan's PMDA Sakigake framework prioritizes device approvals for emergency deployment scenarios.
- Outpatient Facilities:Ambulatory surgical centers perform elective aneurysm embolization and diagnostic angiography. EU MDR recertification burdens disproportionately impact mid-tier outpatient operators with limited clinical affairs resources.
- Specialty Clinics:Dedicated interventional neuroradiology practices concentrate elective flow diversion and complex reconstruction cases. German university hospitals anchor this segment through fellowship training pipelines.
By procedure count, hospitals dominate. By expansion rate, emergency departments are gaining share fastest as pre-hospital stroke triage networks mature.
Technology:
Technology selection tracks physician training background and aneurysm morphology. Mechanical platforms displace pharmacological approaches in eligible stroke populations, while flow diversion challenges traditional reconstructive methods.
- Mechanical Thrombectomy:Direct aspiration and stent-retriever systems achieve revascularization in large-vessel occlusion. US stroke protocols now mandate mechanical first-line therapy for anterior circulation strokes.
- Flow Diversion:Braided mesh constructs redirect blood flow from aneurysm sacs while preserving parent artery patency. Pipeline embolization devices from US manufacturers anchor this segment through specialized training programs.
- Intravenous Thrombolysis:Systemic tPA administration remains adjunctive for patients outside mechanical thrombectomy windows. German stroke units maintain hybrid protocols combining IV thrombolysis with rescue mechanical intervention.
- Stent Retrieval:Self-expanding stent systems entrap and extract thrombus through integrated deployment-retrieval cycles. Japanese procedural volume concentrates in high-volume academic centers with dedicated stroke fellows.
By installed base, mechanical thrombectomy leads. By technology transition velocity, flow diversion is expanding most quickly as surgeons adopt parent artery preservation strategies.
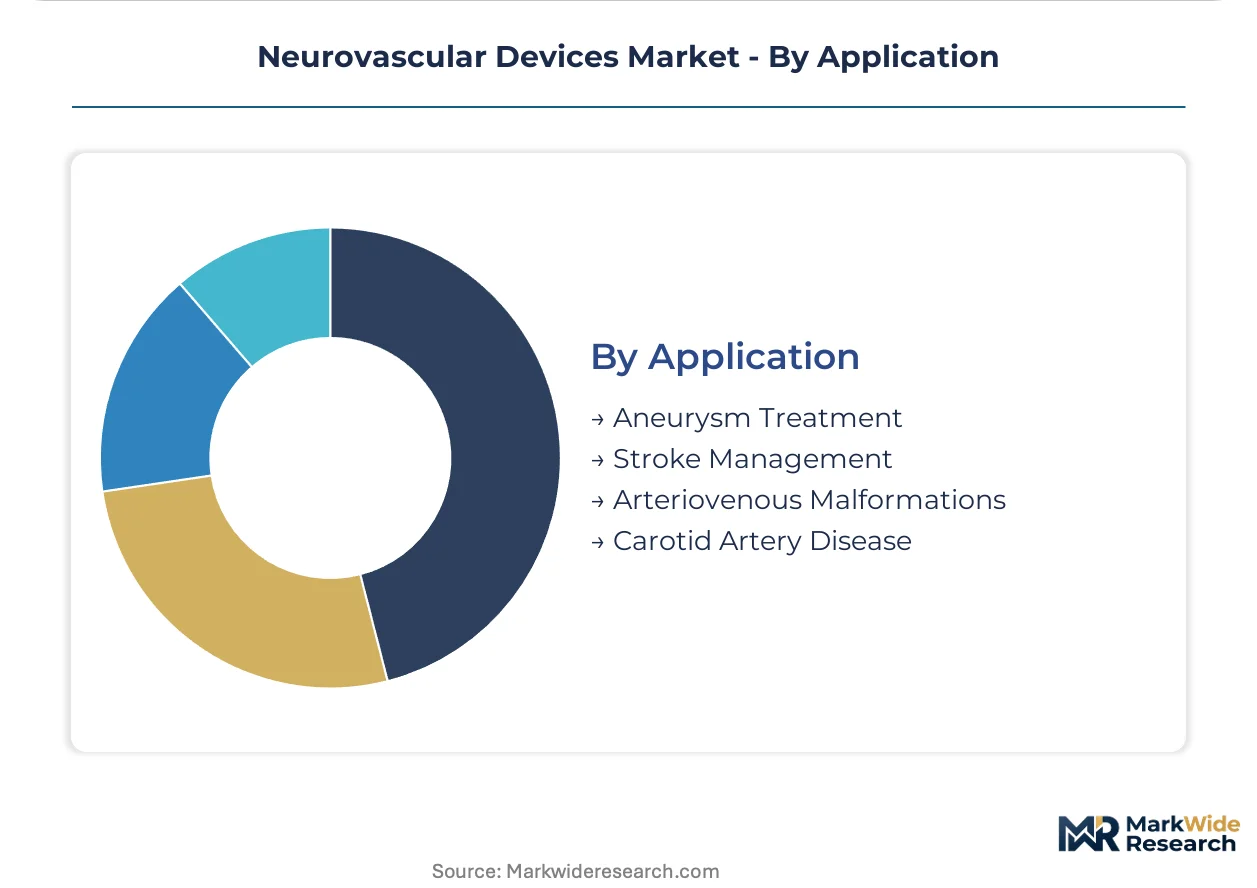
Application:
Clinical indication shapes device specification and reimbursement pathway. Stroke management commands premium pricing due to time-critical logistics, while aneurysm treatment supports scheduled elective workflows.
- Stroke Management:Acute ischemic and hemorrhagic stroke interventions demand device platforms optimized for rapid deployment. US Medicare bundled payment pilots concentrate volume at comprehensive stroke centers with proven outcome metrics.
- Aneurysm Treatment:Saccular, fusiform, and giant aneurysm management spans coiling, stent-assisted coiling, and flow diversion. German neurovascular societies publish treatment algorithms guiding device selection by morphology class.
- Carotid Artery Disease:Stenosis revascularization employs stent and balloon platforms with cerebral embolic protection. Indian tier-2 cities drive procedural growth as interventional neurology programs greenfield without legacy surgical infrastructure.
- Arteriovenous Malformations:Complex tangle embolization requires liquid embolic agents and microcatheter precision. Japanese academic centers concentrate this low-volume, high-complexity application.
By revenue concentration, stroke management leads. By procedural expansion, carotid artery disease is gaining share fastest as screening penetration rises in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in neurovascular devices tilt toward net-import dependence in most major markets, with specialized manufacturing of nitinol braiding and platinum-tungsten alloys concentrating in select industrial clusters. The United States, Germany, and Japan anchor procurement volumes through comprehensive stroke center networks and clear reimbursement pathways.
United States
Medicare bundled payment pilots for stroke care concentrate device procurement at comprehensive stroke centers with proven outcome metrics. The FDA breakthrough device designation compresses premarket review timelines for flow diversion platforms. The Boston-Cambridge corridor anchors neurotechnology R&D clusters where academic medical centers pilot next-generation thrombectomy protocols.
Germany
Reimbursement clarity for complex aneurysm anatomies sustains procedural volume in tertiary neurosurgical units. The EU MDR recertification burden reshapes competitive access, with clinical evidence requirements extending renewal timelines for legacy flow diverters. University hospitals in Bavaria and North Rhine-Westphalia lead adoption of polymer-modified flow diversion devices.
Japan
Aging demographics drive sustained demand for mechanical thrombectomy systems in acute stroke management. The PMDA Sakigake designation accelerates first-in-country approvals for novel platforms, creating asymmetric launch windows. Tokyo and Osaka academic medical centers concentrate high-volume procedural expertise through dedicated interventional neuroradiology fellowship pipelines.
India
Greenfield interventional neurology programs in tier-2 cities generate first-installation demand for integrated thrombectomy suites without legacy equipment displacement. The country's national pharmaceutical regulator oversees device import licensing through a centralized approval framework. Hyderabad and Bengaluru clusters attract medical device manufacturing investments targeting cost-sensitive catheter production.
China
Domestic stroke center expansion drives procurement of mechanical thrombectomy hardware alongside angiography systems. The NMPA manages premarket approval timelines for imported and locally manufactured flow diversion devices. Shanghai and Beijing tertiary hospitals anchor clinical trial networks generating real-world evidence for novel aneurysm treatment platforms.
Neurovascular Devices Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity tiers, with publicly traded multinationals commanding integrated stroke center contracts while private specialists occupy niche technology segments. The vendor base stratifies into three tiers: diversified medical technology conglomerates with neuroscience platforms, dedicated neurovascular device specialists, and regional catheter manufacturers serving cost-sensitive markets. Dominant competitive moves include hardware-software bundling in hospital capital committees and strategic partnerships between aspiration catheter and stent retriever developers.
Within the diversified conglomerate tier, Medtronic and Stryker occupy positions defined by integrated platform breadth, while Penumbra exemplifies the specialized device archetype through distinct technology positioning. Johnson & Johnson and Terumo Corporation represent additional listed anchors with varying degrees of neurovascular focus. Acandis GmbH sits within the European specialist fabricator segment, with its German corporate structure signaling regional engineering concentration. Merit Medical Systems anchors the mid-scale interventional portfolio tier, spanning vascular access alongside neurovascular applications.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Penumbra |
| Johnson & Johnson |
| Terumo Corporation |
| MicroVention |
| Acandis GmbH |
| Asahi Intecc |
| Merit Medical Systems |
| Others |
Supply Flow & Price Mechanics
Specialized nitinol braiding capacity utilization above eighty percent in German and Japanese precision foundries anchors both supply concentration and price floors for flow diversion mesh and thrombectomy stent components. Scale economies in laser-cut stent manufacturing compress unit costs for tier-one manufacturers while raising capital barriers for mid-tier entrants seeking FDA breakthrough pathway qualification.
Pricing Analysis
Hospital capital committees anchor contract pricing through bundled stroke-suite procurement combining thrombectomy hardware with angiography systems. Three-tier pricing structure across premium polymer-coated flow diverters, standard bare-metal stents, and economy coil platforms reflects FDA breakthrough designation status and reimbursement tier alignment. Pricing pressure stems from Medicare bundled payment pilots compressing device margins at comprehensive stroke centers. Emergency departments demonstrate lowest price sensitivity due to time-critical protocols, while outpatient ambulatory surgical centers in India negotiate aggressively on single-use disposable costs.
Supply Chain Analysis
Platinum-tungsten alloy foundry concentration in Japan and Germany underwrites coil embolization device supply security for Western manufacturers. Nitinol raw material sourcing draws from specialized titanium-nickel smelters in the United States and China, with braided mesh fabrication concentrating in Irish and Swiss precision manufacturing clusters. Single-source vulnerability in sub-millimeter microcatheter tipping equipment exposes deliverability constraints for distal vasculature applications. Distribution runs through GPO-negotiated hospital contracts in North America and direct-to-tertiary-hospital relationships in European stroke center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fellowship-trained interventional neuroradiologist scarcity constrains procedural volume scaling even where device availability expands, making human capital retention the decisive competitive variable across all strategic archetypes.
For Market Incumbents: Shield installed base position through captive supply agreements with nitinol braiding specialists and exclusive training program partnerships with academic medical centers. Lock in comprehensive stroke center contracts via hardware-software bundling before EU MDR recertification burdens eliminate mid-tier competitors. Vertical integration into polymer coating technology for next-generation flow diverters defends margin position against bare-metal commoditization. For New Entrants and Emerging Players: Lead with aspiration-first thrombectomy platform licensing to penetrate India's tier-2 greenfield stroke centers without legacy equipment displacement costs. Target emergency department spoke hospitals in telestroke networks where device selection algorithms embed purchasing decisions. Pursue PMDA Sakigake pathway prioritization for asymmetric first-mover windows in Japanese aging demographic markets. For Investors and Strategic Acquirers: European flow diversion specialists with EU MDR clinical evidence packages already submitted represent the most defensible acquisition profile for sustained market access. Long-term viability hinges on reimbursement granularity for stroke severity tiers rather than device innovation cycles alone. Monitor FDA breakthrough designation grant velocity as the signal indicating regulatory pathway efficiency and commercialization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pursuit | Expedited premarket review compresses commercialization timelines for novel flow diversion platforms. |
| Hospital System Partnership | Comprehensive stroke center contracts bundle thrombectomy hardware with angiography capital equipment. |
| Reimbursement Strategy | Medicare bundled payment pilots concentrate volume at centers with proven ninety-day outcome metrics. |
| CE Marking Pathway | EU MDR post-market surveillance mandates real-world evidence collection through national stroke registries. |
| Software Companion Development | Telestroke network integration embeds device selection algorithms into spoke hospital purchasing decisions. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) and PMA filings, EU MDR technical documentation databases, and PMDA Sakigake approval records. Interviews with interventional neuroradiologists, hospital purchasing committee chairs, biomedical engineers at comprehensive stroke centers, and GPO contracts managers inform demand-side validation. Top-down market sizing triangulates against bottom-up procedure volume estimates derived from Medicare claims data and national stroke registry extracts.
Segmentation dimensions modeled include product type, end-user facility category, technology platform, and clinical application across the analysis window. CAGRs derive from logistic diffusion curves fitted to procedural adoption rates by stroke center certification tier. Forecast inputs incorporate interventional neuroradiologist fellowship pipeline capacity, reimbursement policy trajectory, and nitinol raw material price elasticity assumptions.
Forecasts assume regulatory continuity in FDA breakthrough designation criteria, EU MDR clinical evidence requirements, and Japan's PMDA Sakigake framework; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as bundled payment pilot expansion and telestroke network maturation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Positive Air Pressure Devices Market
Medical Devices
Anesthesia Circuits Market
Medical Devices
Mechanical Chest Compression System Market
Medical Devices
Biodegradable Stents Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
Cryoablation Devices Market
Medical Devices
Medical Electronics Market
Medical Devices
Global Joint Replacement Device Market
Medical Devices
France Respiratory Devices Market
Medical Devices
Deep Brain Stimulator Market
Medical Devices
Medical LED Headlight Market
Medical Devices
Global Surgical Microscopes Market
Medical Devices
Skin Rejuvenation Devices Market
Medical Devices
Europe Wearable Medical Devices Market
Medical Devices
Dialysis Device and Concentrates Market