
 North America Neurostimulation Devices Market | 2026-2036
North America Neurostimulation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Neurostimulation Devices Market Analytics
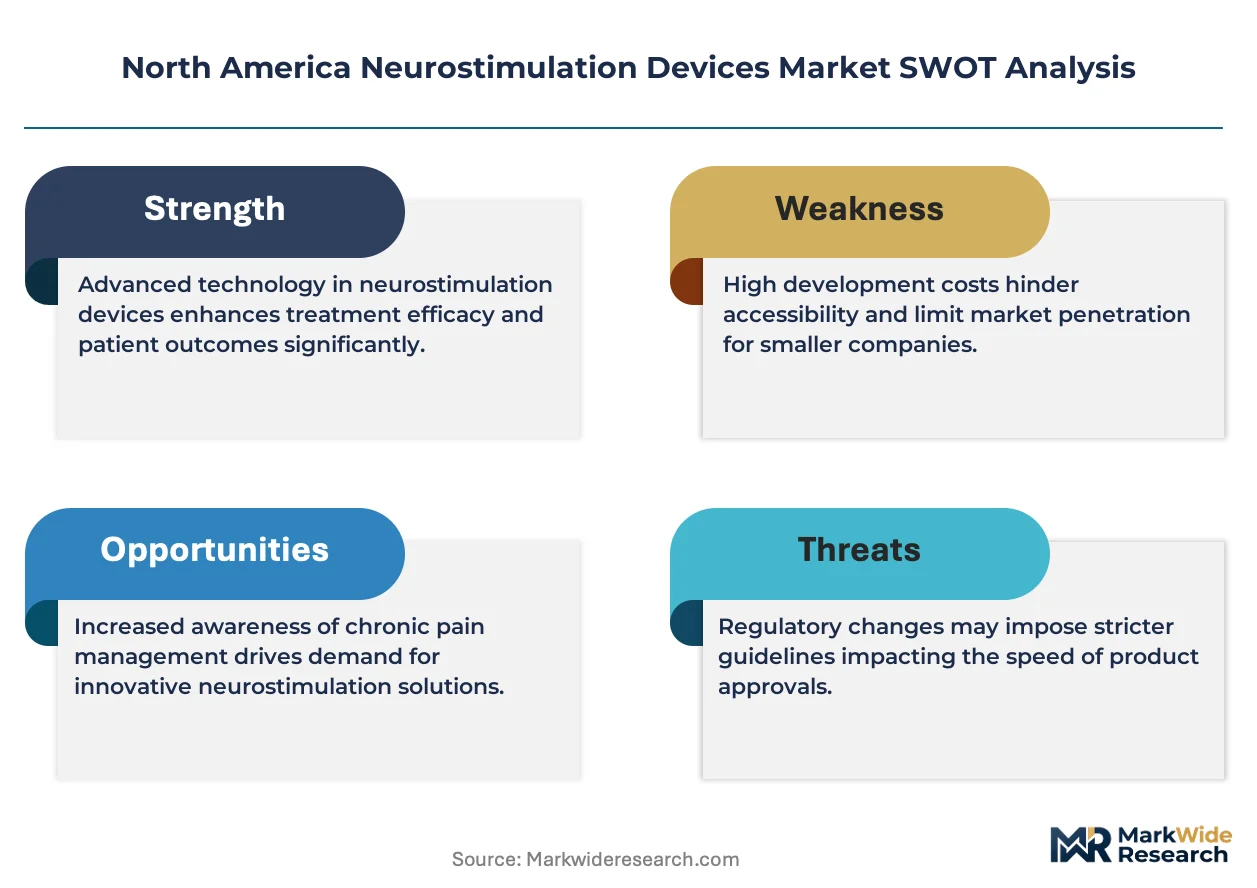
Single-source component sourcing is repositioning toward dual-qualified supply chains across the North America neurostimulation landscape. Medtronic leverages its captive manufacturing footprint to secure implantable pulse generator supply. Boston Scientific Corporation anchors its competitive stance through proprietary lead technologies. Abbott Laboratories differentiates via directional stimulation programming platforms.
Neurostimulation devices deliver targeted electrical impulses to neural tissue through implanted or external systems, typically operating at frequencies between 2 Hz and 10 kHz with pulse widths adjustable from 60 to 450 microseconds to modulate pain signaling or restore motor function. Spinal cord stimulators occupy the largest installed base among product categories, reflecting decades of chronic pain reimbursement infrastructure. Deep brain stimulators represent the fastest-growing segment as indications expand beyond Parkinson's disease into obsessive-compulsive disorder and epilepsy. Pain management applications command the deepest margin pools due to favorable ambulatory surgical center economics and repeat procedure volumes.
FDA premarket approval pathways and ISO 14155 clinical investigation standards govern device commercialization, with the former mandating randomized controlled trials for novel neuromodulation indications. Health Canada and the FDA jointly influence North American harmonization through the Medical Device Single Audit Program, reducing redundant quality system inspections. Stakeholders must monitor CMS national coverage determination revisions for dorsal root ganglion stimulation and peripheral nerve targets.
Market Dynamics
FDA breakthrough device designations are compressing review timelines for novel neuromodulation platforms while pain management clinics accelerate service line expansion across the Northeast corridor.
Growth Catalysts
- CMS Reimbursement Expansion:National coverage determinations for dorsal root ganglion stimulation and peripheral nerve targets are unlocking ambulatory surgical center economics.
- Chronic Pain Prevalence:Aging demographics across the United States and Canada are expanding the addressable patient pool for spinal cord stimulator implantation.
- Closed-Loop Feedback Systems:Adaptive stimulation algorithms that automatically adjust output based on neural response are shortening patient programming visits.
Market Restraints
- Precious Metal Input Volatility:Platinum-iridium electrode alloys and titanium implantable pulse generator housings expose manufacturers to commodity price swings.
- Single-Source Lead Suppliers:Concentrated manufacturing of multi-contact percutaneous leads in specific geographies creates supply vulnerability.
- Surgical Site Infection Protocols:Hospital antimicrobial stewardship programs are extending pre-implant screening timelines and complicating patient selection.
Strategic Opportunities
- Canadian Market Underpenetration:Provincial reimbursement harmonization for deep brain stimulation in movement disorders lags US Medicare coverage depth.
- Psychiatric Indication Expansion:FDA breakthrough pathways for obsessive-compulsive disorder and treatment-resistant depression represent new addressable segments.
- Remote Programming Platforms:Cloud-based patient management systems are enabling asynchronous clinician-patient interaction outside traditional clinic visits.
Industry Challenges
- Neurophysiology Talent Scarcity:Specialized field clinical engineers capable of intraoperative neurophysiological monitoring are concentrated in major academic medical centers.
- IP Thicket Navigation:Dense patent landscapes around current steering algorithms and electrode geometries complicate new platform development.
- Legacy System Integration:Magnetic resonance imaging conditional labeling requirements force hardware refresh cycles incompatible with prior implant generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Neurostimulation Devices Market |
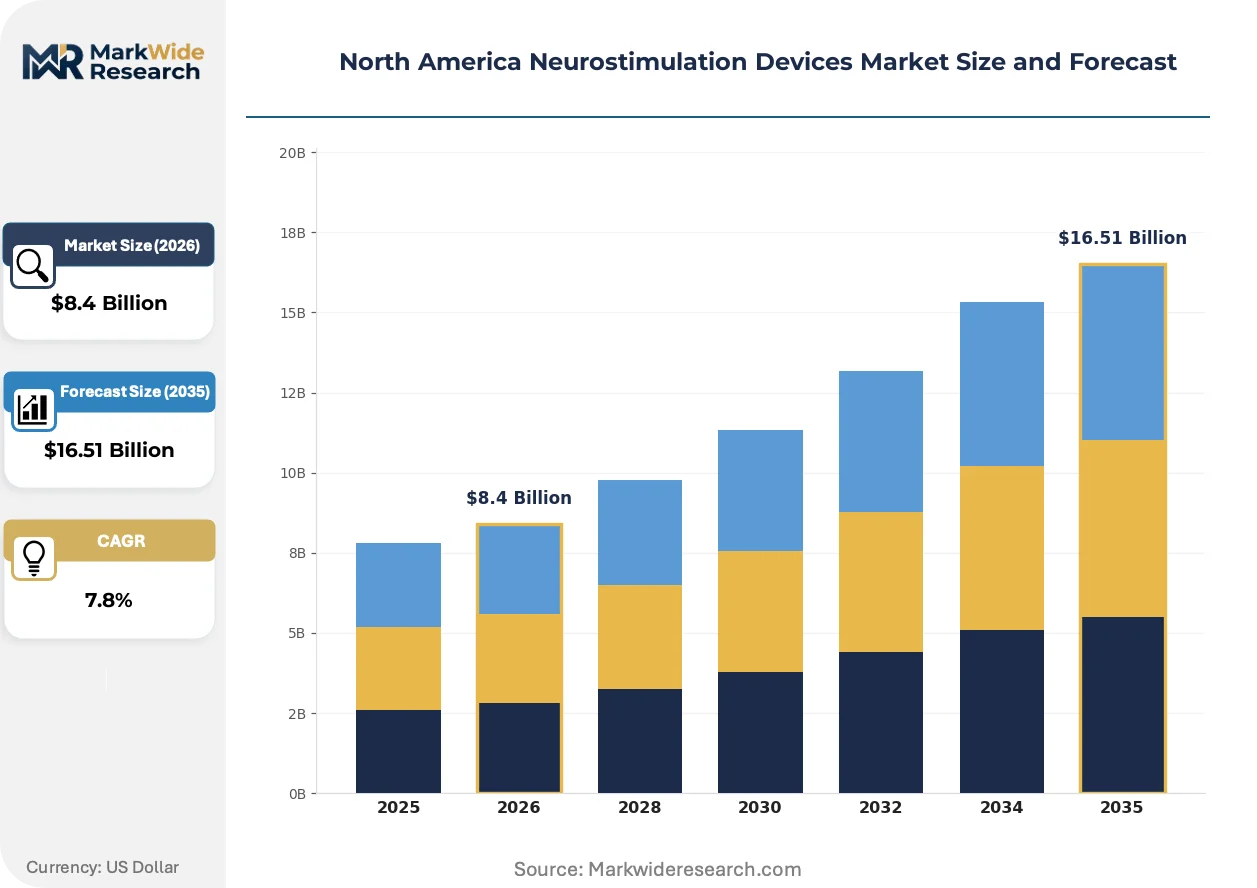
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spinal Cord Stimulators, Deep Brain Stimulators, Sacral Nerve Stimulators, Vagus Nerve Stimulators Application: Pain Management, Epilepsy, Depression, Movement Disorders End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Technology: Electrical Stimulation, Magnetic Stimulation, Chemical Stimulation, Others |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott Laboratories, Nevro Corp, LivaNova, Synapse Biomedical Inc, NeuroPace Inc, Nalu Medical Inc, ElectroCore Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Neurostimulation Devices Market Evolving Landscape
Directional stimulation programming and battery chemistry advances are redefining competitive differentiation while regulatory harmonization efforts streamline cross-border commercialization.
Battery technology is expanding into lithium-ion cell architectures with wireless inductive charging capabilities. Pain management clinics and hospital outpatient departments are adopting these systems to eliminate surgical battery replacement procedures. The shift is expanding into extended device longevity segments previously served by primary cell technologies.
FDA premarket approval harmonization with Health Canada through the Medical Device Single Audit Program is reducing redundant quality system inspections. Manufacturers now face unified audit schedules rather than separate US and Canadian regulatory examinations. Deep brain stimulator platforms targeting movement disorders are experiencing the most pronounced timeline compression from this alignment.
Physician ownership in ambulatory surgical centers is reshaping site-of-service economics for spinal cord stimulator trials and permanent implants. Hospital-based outpatient departments are losing volume to physician-owned facilities with streamlined scheduling and dedicated neuromodulation nursing staff. Texas, Florida, and Arizona are exhibiting the most visible migration of procedural volume away from traditional hospital settings.
North America Neurostimulation Devices Market Segmentation
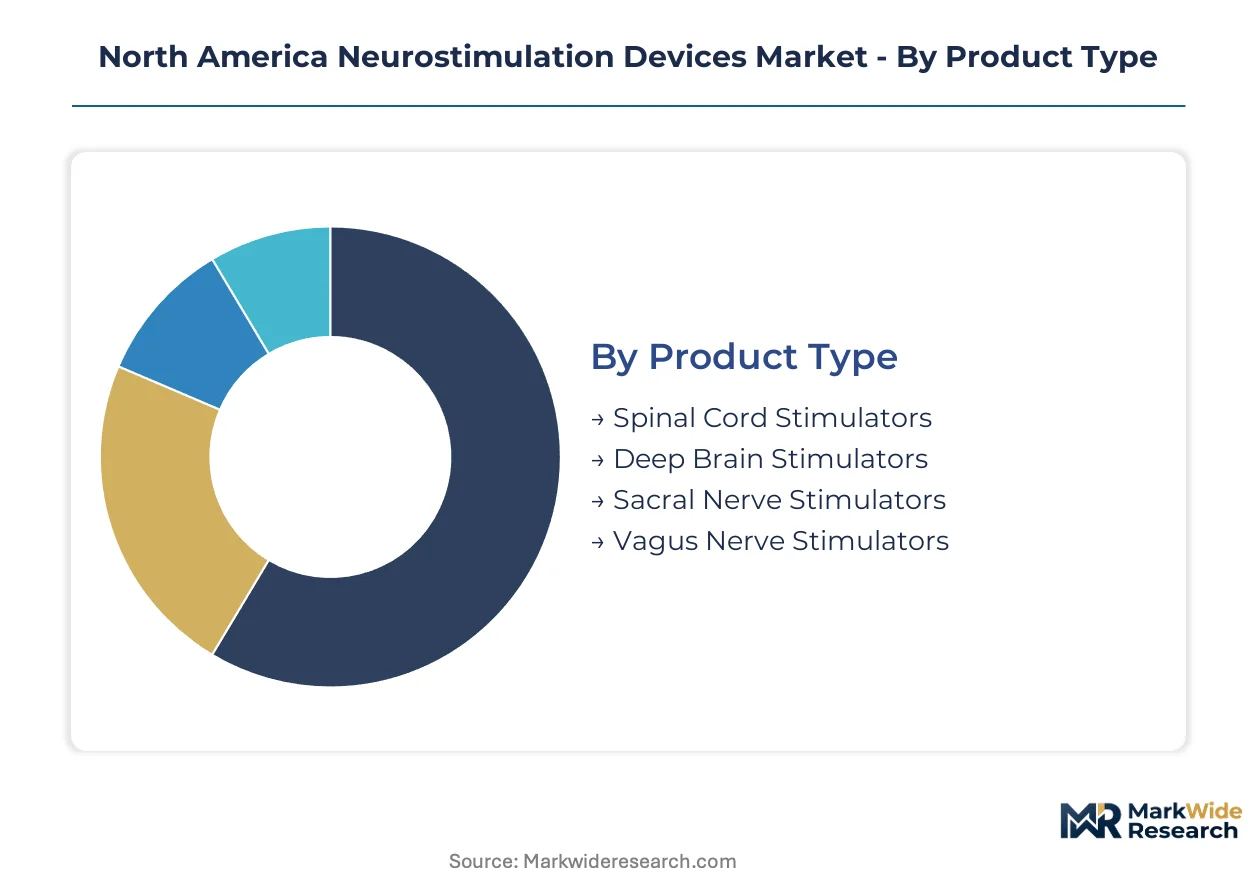
Neurostimulation device manufacturers navigate divergent regulatory pathways across product categories, with implantable pulse generators facing FDA premarket approval while external magnetic systems clear through 510(k) notification. Segmentation strategy directly determines reimbursement eligibility, surgical site economics, and patient selection protocols across the North American landscape.
Product Type:
FDA premarket approval requirements vary sharply by implant depth and tissue contact duration, with intracranial systems commanding the most extensive clinical trial obligations.
- Spinal Cord Stimulators:Percutaneous and paddle lead configurations deliver epidural electrical impulses at 2-10 kHz frequencies for chronic intractable pain. Demand clusters in ambulatory surgical centers across Texas and Florida where physician ownership drives site-of-service migration. CMS national coverage determinations for dorsal root ganglion variants are expanding addressable procedures.
- Deep Brain Stimulators:Bilateral electrode arrays targeting subthalamic nucleus or globus pallidus interna for movement disorders require stereotactic surgical placement with intraoperative neurophysiological monitoring. Canadian provincial reimbursement harmonization lags US Medicare coverage depth, creating underpenetration in Ontario and Quebec relative to comparable US metropolitan markets.
- Sacral Nerve Stimulators:Implantable pulse generator systems modulate S3 nerve root activity for urinary and fecal incontinence.
- Vagus Nerve Stimulators:Left cervical vagal trunk implantation for treatment-resistant epilepsy and emerging psychiatric indications.
Spinal cord stimulators sit at the top of the volume ranking, with deep brain stimulators climbing the fastest.
Application:
Reimbursement depth and procedure margin structure diverge substantially across therapeutic areas, with chronic pain commanding favorable ambulatory surgical center economics.
- Pain Management:Failed back surgery syndrome and complex regional pain syndrome represent primary indications for spinal cord and dorsal root ganglion stimulation. Northeast corridor pain clinics from Boston to Philadelphia anchor clinical adoption through academic medical center referral networks. Repeat procedure volumes including trial-to-permanent conversions and device replacements sustain recurring revenue streams.
- Epilepsy:Responsive neurostimulation and vagus nerve stimulation serve drug-resistant patient populations with discrete seizure foci or multifocal presentation.
- Depression:Treatment-resistant depression indications are gaining FDA breakthrough device designation momentum for deep brain stimulation platforms.
- Movement Disorders:Parkinson's disease, essential tremor, and dystonia constitute established deep brain stimulator indications with expanding age-eligible populations.
Pain management captures the deepest margin pools, while psychiatric applications are gaining share fastest.
End User:
Site-of-service economics and staffing requirements determine competitive positioning across delivery settings, with specialized nursing capabilities becoming a scarce differentiator.
- Hospitals:Academic medical centers concentrate intraoperative neurophysiological monitoring talent and complex revision procedures. Hospital-based outpatient departments are losing volume to physician-owned alternatives with streamlined scheduling.
- Clinics:Pain management clinics are expanding dedicated neuromodulation service lines with proprietary nursing staff.
- Home Care:Remote programming platforms enable asynchronous clinician-patient interaction for device parameter adjustment.
- Rehabilitation Centers:Post-implant programming and patient training for external magnetic or chemical stimulation systems.
Clinics lead procedural volume expansion, with home care platforms showing the steepest adoption trajectory.
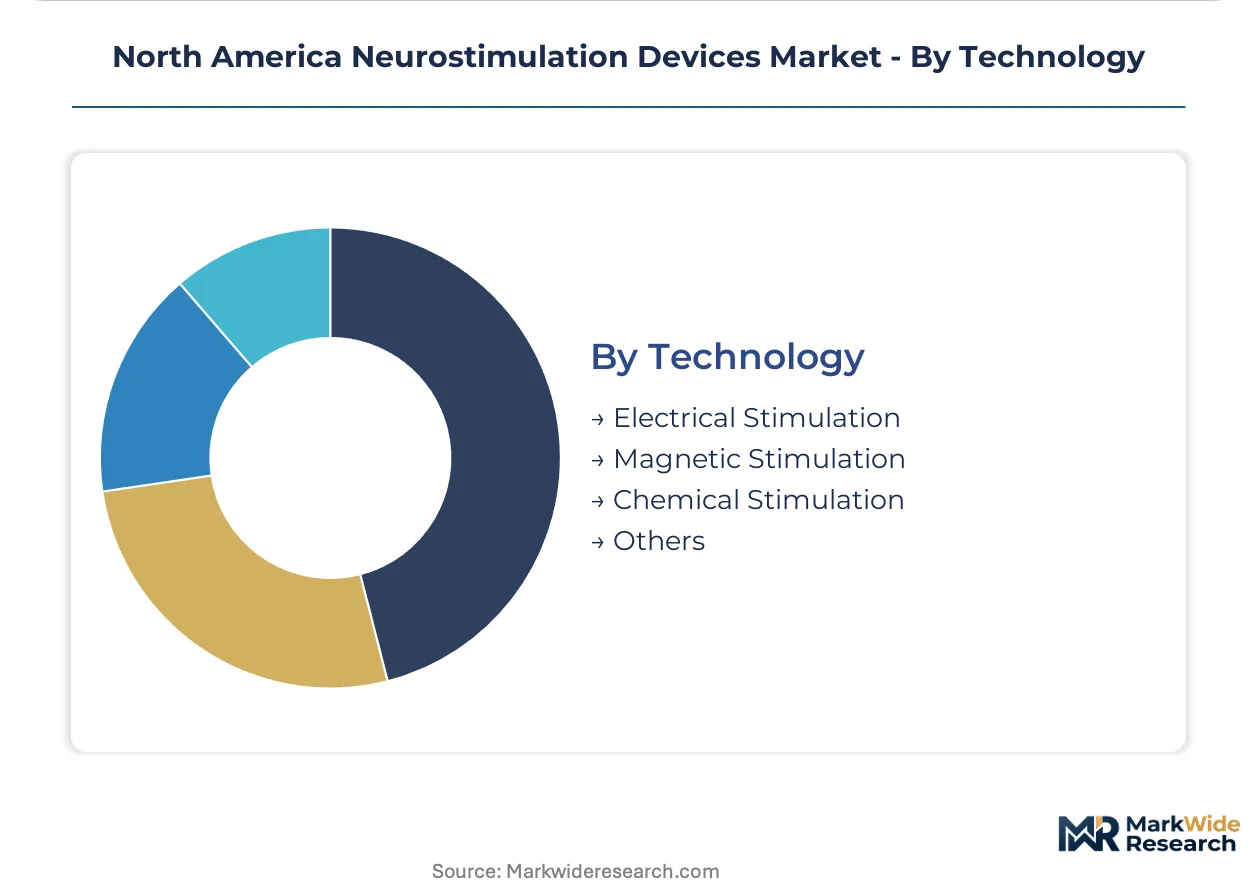
Technology:
Energy delivery modality determines regulatory classification, manufacturing complexity, and competitive moat durability across the technology landscape.
- Electrical Stimulation:Implantable pulse generators with lithium-ion cell architectures and wireless inductive charging eliminate surgical battery replacement. Directional stimulation programming and closed-loop feedback algorithms are shortening patient programming visits.
- Magnetic Stimulation:Transcranial magnetic stimulation systems for depression and obsessive-compulsive disorder operate outside permanent implant regulations.
- Chemical Stimulation:Infusion-based neuromodulation for targeted drug delivery applications.
- Others:Emerging optical and ultrasonic stimulation platforms in preclinical development.
Electrical stimulation dominates installed base and revenue concentration, with magnetic stimulation expanding most quickly in outpatient mental health settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Northeast corridor from Boston to Philadelphia anchors clinical adoption through academic medical center referral networks. Pain management clinics are expanding service lines across the United States while Canadian provincial reimbursement harmonization lags US Medicare coverage depth.
United States
Pain management clinics across Texas and Florida are driving site-of-service migration toward physician-owned ambulatory surgical centers. FDA breakthrough device designations compress review timelines for novel neuromodulation platforms. The Northeast corridor concentrates intraoperative neurophysiological monitoring talent and complex revision procedures.
Canada
Provincial reimbursement harmonization for deep brain stimulation in movement disorders creates underpenetration in Ontario and Quebec relative to comparable US metropolitan markets. Health Canada and the FDA jointly influence North American harmonization through the Medical Device Single Audit Program. Toronto and Vancouver academic medical centers anchor limited clinical adoption.
Mexico
Private hospital chains in Mexico City and Monterrey are expanding neuromodulation service lines for medical tourism and domestic affluent patients. COFEPRIS regulatory pathways for implantable devices remain less streamlined than FDA premarket approval timelines. Guadalajara medical clusters concentrate limited deep brain stimulator placement capabilities.
North America Neurostimulation Devices Market Competitive Landscape
Global majors compete with regional champions across technology licensing and captive manufacturing footprints. The vendor base concentrates around three large diversified conglomerates with captive supply chains and a fragmented tier of neuromodulation specialists. Strategic archetypes include diversified medical technology conglomerates, pure-play neuromodulation innovators, and external peripheral nerve stimulation entrants. Dominant competitive moves span proprietary lead technology development and directional stimulation programming platform differentiation.
Within the diversified conglomerate tier, Medtronic leverages its captive manufacturing footprint to secure implantable pulse generator supply while Boston Scientific Corporation anchors competitive positioning through proprietary lead technologies. Abbott Laboratories exemplifies platform differentiation via directional stimulation programming capabilities. Among pure-play specialists, Nevro Corp and NeuroPace Inc occupy positions focused on closed-loop feedback systems and responsive neurostimulation algorithms respectively. LivaNova represents the cardiac-neuromodulation crossover archetype with vagus nerve stimulation capabilities.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Nevro Corp |
| LivaNova |
| Synapse Biomedical Inc |
| NeuroPace Inc |
| Nalu Medical Inc |
| ElectroCore Inc |
| Others |
Value Network & Pricing Analysis
Premium-mid-economy pricing differentiation across implantable pulse generators and external trial systems manifests in dual supply chain configurations, with FDA PMA-tracked platforms commanding captive manufacturing footprints while 510(k)-cleared alternatives draw from contract assembly networks in Mexico and Costa Rica. This bifurcation concentrates margin capture among diversified conglomerates with in-house electrode alloy production, while price competition intensifies in the percutaneous lead segment where offshore component sourcing dominates.
Pricing Analysis
Platinum-iridium electrode alloy volatility passes through to implantable pulse generator pricing, with manufacturers indexing long-term supply agreements to London Metal Exchange benchmarks. Price differentiation hinges on MRI conditional labeling tier and proprietary directional steering algorithms, with premium platforms capturing three-to-fourfold multiples over standard pulse generators. Cost compression in the trial-to-permanent conversion segment is intensifying because ambulatory surgical center ownership models are squeezing device margins to capture facility fees. Hospital purchasing committees exhibit the sharpest price sensitivity, while physician-owned surgery centers prioritize programming efficiency and battery longevity over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with multi-contact percutaneous lead manufacturing concentrated in Costa Rica, Malaysia, and selected US medical device corridors. Raw material dependencies center on titanium implantable pulse generator housings, lithium-ion cell architectures for rechargeable systems, and platinum-iridium electrode alloys. Tariff exposure on precision-machined titanium components from specific Southeast Asian trade corridors threatens margin stability for non-vertically integrated assemblers. Distribution runs through GPO-contracted hospital supply chains and direct-to-ambulatory surgical center logistics networks, with regional warehousing in Texas and Florida supporting site-of-service migration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA breakthrough device designation momentum functions as a regulatory compounder, accelerating review timelines for closed-loop feedback platforms and compressing competitive windows for conventional open-loop systems.
For Market Incumbents: Cement proprietary lead technology moats through backward integration into electrode alloy processing and expanded Costa Rican manufacturing capacity. Defend against responsive neurostimulation entrants by accelerating Health Canada harmonization submissions before provincial reimbursement gaps close. Priority rests on locking multi-year GPO contracts with integrated delivery networks across the Northeast corridor.
For New Entrants and Emerging Players: FDA breakthrough pathway momentum for psychiatric indications opens a window for deep brain stimulation platforms targeting treatment-resistant depression and obsessive-compulsive disorder. Canadian provincial reimbursement harmonization lags create the most penetrable geography, with Ontario and Quebec academic medical centers underserved relative to comparable US markets. Go-to-market execution should anchor in cloud-based remote programming platforms that enable asynchronous clinician-patient interaction outside traditional clinic infrastructure.
For Investors and Strategic Acquirers: Consolidation pressure builds where closed-loop algorithm capabilities concentrate in pure-play specialists lacking captive manufacturing footprints. Long-term viability favors platforms with rechargeable battery architectures and psychiatric indication expansion pipelines. Acquisition target archetype: neuromodulation innovators with FDA breakthrough designations but incomplete commercial infrastructure. Signal to watch: CMS national coverage determination revisions for dorsal root ganglion stimulation and peripheral nerve targets as volume inflection triggers.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Pathway Submission | Accelerates review timelines for novel closed-loop feedback algorithms in movement disorders. |
| Health Canada Harmonization Filing | Unlocks provincial reimbursement depth in Ontario and Quebec for deep brain stimulator platforms. |
| Hospital System Partnership | Secures GPO contract access across integrated delivery networks in the Northeast corridor. |
| Software Companion Development | Enables cloud-based remote programming platforms for asynchronous patient management. |
| Reimbursement Strategy | Positions for CMS national coverage determination expansion into dorsal root ganglion targets. |
Research Methodology
Bottom-up ambulatory surgical center procedural volume modeling reconciled against top-down implantable pulse generator shipment tracking forms the analytical core of this study. Primary interviews with pain management clinic medical directors, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers were validated against secondary sources including FDA PMA and 510(k) filing databases, CMS national coverage determination archives, and Health Canada Medical Device Establishment License records. Triangulation across these inputs ensures segmentation integrity across product type, application, and end-user dimensions.
Historical trendline analysis of spinal cord stimulator trial-to-permanent conversion rates and deep brain stimulator age-eligible population expansion underpins the projection framework. The analytical model segments across implant depth, energy delivery modality, therapeutic indication, and site-of-service setting throughout the forecast period. CAGRs were derived from regression analysis of procedure volume growth, device replacement cycles, and emerging indication penetration curves. Industry-specific inputs include intraoperative neurophysiological monitoring talent distribution and provincial reimbursement harmonization timelines.
Revisions become necessary when FDA premarket approval timelines extend beyond breakthrough pathway benchmarks, platinum-iridium commodity volatility exceeds historical bands, or ambulatory surgical center ownership regulations shift materially. Forecasts reflect assumptions around CMS coverage expansion and Health Canada MDSAP audit harmonization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Nephrostomy Devices Market
Medical Devices
Pacemaker Devices Market
Medical Devices
China Anesthesia Devices Market
Medical Devices
Global Veress Needle Market
Medical Devices
Genitourinary Prosthetics Market
Medical Devices
Global Gastric Balloons Market
Medical Devices
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Surgical Smart Glasses Market
Medical Devices
Physiotherapy Laser Wrist Watch Market
Medical Devices
Neuro Medical Devices Market
Medical Devices
Global Abutment Implants Market
Medical Devices
Epistaxis Devices Market
Medical Devices
APAC AMH Market
Medical Devices
Europe Surgical Microscopes Market
Medical Devices
Esophagoscopes and Gastroscopes Market
Medical Devices
Canada Ultrasound Devices Market