
 Touch Screen Module Market | 2026-2036
Touch Screen Module Market Size, Share, and Industry Trends Forecast 2026-2036
Touch Screen Module Market Outlook
Automotive-grade durability specifications is redrawing procurement priorities across the touch screen module industry. Samsung Display leverages vertical integration from glass substrate to finished module, sustaining cost advantages in high-volume capacitive production. BOE Technology anchors supply for domestic Chinese automotive OEMs, while TPK Holding specializes in projected-capacitive solutions for industrial and medical applications.
A touch screen module integrates a transparent sensor substrate, controller IC, and cover lens into a functional input-output assembly, typically specified by transmittance exceeding 85 percent and surface hardness of 9H pencil rating. Capacitive modules dominate volume due to multi-touch responsiveness in smartphones and tablets, while infrared and optical variants retain structural positions in kiosks and large-format interactive displays where environmental sealing takes priority. Haptic feedback technology captures expanding margin pools as automotive displays integrate tactile confirmation for safety-critical controls.
FCC certification governs electromagnetic emissions from controller electronics in United States-bound modules, while EU REACH and RoHS frameworks restrict hazardous substances in adhesives and conductive coatings. China's GB standards and MIIT technical regulations mandate reliability testing protocols for domestic-deployed touch interfaces. Stakeholders must monitor evolving automotive functional-safety requirements as touch modules migrate from infotainment to instrument-cluster and climate-control applications.
Market Dynamics
Automotive functional-safety migration is restructuring procurement specifications across the touch screen module industry. Electric vehicle cabins now demand touch interfaces that withstand vibration, temperature cycling, and electromagnetic interference while maintaining optical clarity.
Growth Catalysts
- EU REACH compliance:Material disclosure mandates for display laminates are accelerating supplier consolidation toward certified coating providers. OEMs favor pre-qualified module vendors with established hazardous-substance documentation.
- Capacitive multi-touch responsiveness:Smartphone and tablet manufacturers continue specifying projected-capacitive architectures for gesture recognition. This technology standard sustains volume production economics for glass-substrate suppliers.
- China domestic supply chain concentration:BOE Technology and Tianma Microelectronics anchor captive production for local automotive OEMs. Indigenous module capacity reduces import dependency and shortens logistics lead times.
Market Restraints
- Indium tin oxide supply concentration:Sputtering target manufacturing clusters in East Asia create single-source vulnerability for transparent conductive layer deposition. Price volatility in rare earth processing affects cost predictability.
- Automotive qualification timelines:AEC-Q100 reliability testing extends product development cycles to 18-24 months. This certification friction delays revenue recognition for new module designs.
- Optical bonding yield losses:Vacuum lamination of cover glass to sensor substrates generates 8-12 percent scrap rates at volume. This technical limitation compresses margins for mid-tier module assemblers.
Strategic Opportunities
- India automotive manufacturing expansion:Domestic EV production incentives under the PLI scheme create demand for localized touch module assembly. Tier-1 suppliers can establish captive bonding facilities near Chennai and Pune clusters.
- Haptic feedback convergence:Integration of piezoelectric actuators with capacitive sensors enables tactile confirmation for safety-critical controls. This technology pairing commands premium positioning in instrument-cluster applications.
- Japan METI carbon-neutrality roadmap:Subsidies for low-emission display manufacturing equipment incentivize retrofit of existing module production lines. Equipment suppliers benefit from upgrade cycles at aging fabs.
Industry Challenges
- Controller IC firmware talent scarcity:Embedded software engineers with capacitive sensing algorithm expertise command compensation premiums. Recruitment bottlenecks delay product development schedules.
- FCC Part 15 certification complexity:Electromagnetic emissions testing for United States-bound modules requires specialized anechoic chamber access. Test queue backlogs extend time-to-market by 6-10 weeks.
- Legacy resistive touch replacement integration:Industrial equipment retrofit projects face mechanical compatibility constraints with existing bezel designs. Custom cover-lens engineering adds non-recurring engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Touch Screen Module Market |
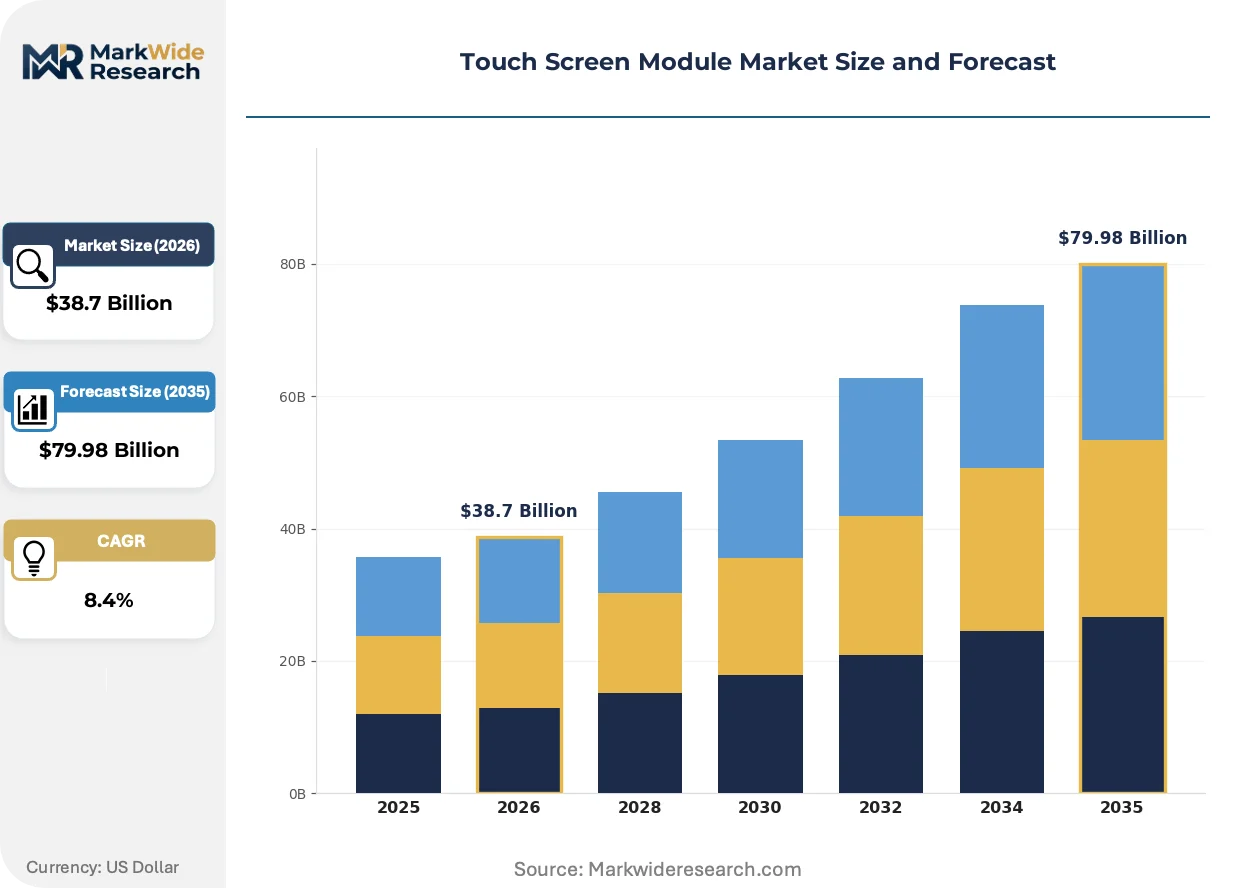
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive, Resistive, Infrared, Optical Technology: Multi-Touch, Single-Touch, Haptic Feedback, Gesture Recognition Application: Smartphones, Tablets, Industrial Equipment, Automotive Displays End User: Consumer Electronics, Medical Devices, Retail Kiosks, Gaming Consoles |
| Companies Covered | Samsung Display, LG Display, Tianma Microelectronics, TPK Holding, Nissha Printing, 3M Touch Systems, Sharp Corporation, BOE Technology, O-Film Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Touch Screen Module Market Strategic Shifts
Module architectures are compressing toward single-chip integration while cover-lens materials diversify beyond chemically strengthened glass. These shifts respond to automotive weight-reduction mandates and foldable-display mechanical requirements.
Silver nanowire transparent conductors are replacing indium tin oxide in flexible touch sensors for curved automotive center consoles. Tier-1 suppliers in South Korea and Germany are qualifying nanowire-coated film laminates for 2026 model-year vehicles. This conductor technology is miniaturizing sensor trace widths below 5 microns, enabling narrower bezel designs and expanded active display area.
EPA electronics standards evolution in the United States is tightening reporting requirements for per- and polyfluoroalkyl substances in display adhesives. Module manufacturers must reformulate optical bonding chemistries to maintain market access. Automotive-grade suppliers with pre-validated alternative adhesive platforms capture qualification priority from OEMs accelerating 2027 product cycles.
Direct procurement from module specialists is displacing tiered distribution through display integrators among mid-volume industrial OEMs. Buyers in medical imaging and kiosk manufacturing now specify controller firmware customization at the module level. This channel restructuring concentrates in North America and Western Europe where technical sales support justifies disintermediation economics.
Touch Screen Module Market Segmentation
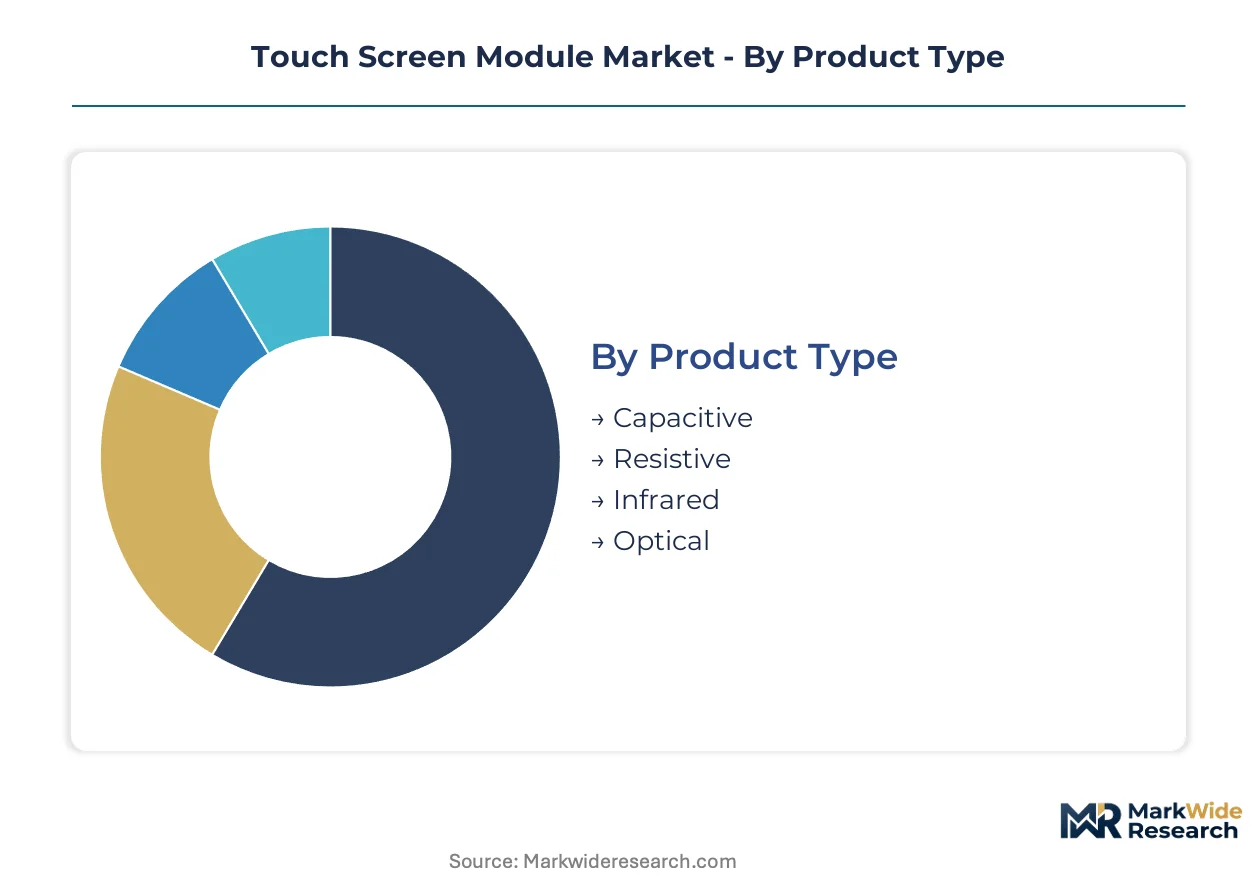
Touch screen module procurement varies sharply across application contexts. Specification requirements for optical clarity, environmental sealing, and electromagnetic compatibility create distinct segment boundaries that reshape supplier selection criteria.
Product Type:
Capacitive architectures face substitution pressure from emerging silver nanowire conductors, while resistive modules confront displacement by force-sensing alternatives in industrial settings.
- Capacitive:Projected-capacitive sensors using indium tin oxide or silver nanowire transparent conductors deliver multi-touch responsiveness with transmittance exceeding 85 percent. Demand concentrates in smartphone manufacturing clusters in China and South Korea, where glass-substrate supply integration sustains cost advantages for high-volume OEMs.
- Resistive:Pressure-sensitive membrane stacks comprising top and bottom conductive layers separated by spacer dots function through physical deformation. Industrial equipment retrofit projects in Germany and Japan retain demand for resistive durability in gloved-operation environments, though capacitive alternatives are displacing share in new equipment designs.
- Infrared:LED emitter-detector arrays frame display perimeters to detect touch interruptions without surface overlay.
- Optical:Camera-based touch detection enables scale-free sizing for large-format interactive displays in retail and museum installations.
Capacitive retains volume leadership; optical holds the steepest expansion curve in large-format deployments.
Technology:
Cost tier stratification separates premium haptic-enabled modules from commodity single-touch alternatives, with firmware development intensity driving margin differentiation.
- Multi-Touch:Controller ICs processing simultaneous contact points enable pinch-zoom and rotation gestures through mutual-capacitance scanning. Tablet manufacturers in Taiwan and mainland China specify ten-point recognition as baseline, with automotive OEMs now adopting similar specifications for center-console interfaces.
- Haptic Feedback:Piezoelectric actuator integration with capacitive sensors generates localized tactile confirmation without mechanical button travel. Automotive instrument-cluster applications in Germany and the United States command premium positioning as safety-critical controls migrate to touch interfaces.
- Single-Touch:Simplified controller firmware reduces bill-of-materials cost for cost-constrained applications.
- Gesture Recognition:Proximity-sensing extensions enable hover detection and air-gesture interpretation.
Multi-touch dominates unit economics; haptic feedback captures the widest margin expansion.
Application:
Volume concentration in mobile devices creates procurement scale advantages that automotive and industrial segments cannot replicate without qualification timeline tradeoffs.
- Smartphones:Ultra-narrow bezel specifications and under-display sensor integration drive cover-lens processing innovation. Chinese OEMs BOE Technology and Tianma Microelectronics anchor domestic supply chains, while South Korean fabs serve premium tier requirements for foldable-display mechanical compliance.
- Automotive Displays:AEC-Q100 reliability testing mandates 18-24 month qualification cycles for vibration, temperature cycling, and electromagnetic immunity. Tier-1 suppliers in Germany and Japan are qualifying silver nanowire laminates for curved center-console designs in 2026 model-year vehicles.
- Tablets:Education and enterprise fleet deployments sustain mid-volume demand with durability specifications.
- Industrial Equipment:Environmental sealing ratings and gloved-operation compatibility prioritize resistive or thick-glove-capacitive variants.
Smartphone applications generate procurement scale; automotive displays present the steepest specification escalation.
End User:
Customer type segmentation reveals divergent firmware customization requirements, with medical and gaming applications demanding specialized controller algorithms that commodity consumer electronics procurement cannot support.
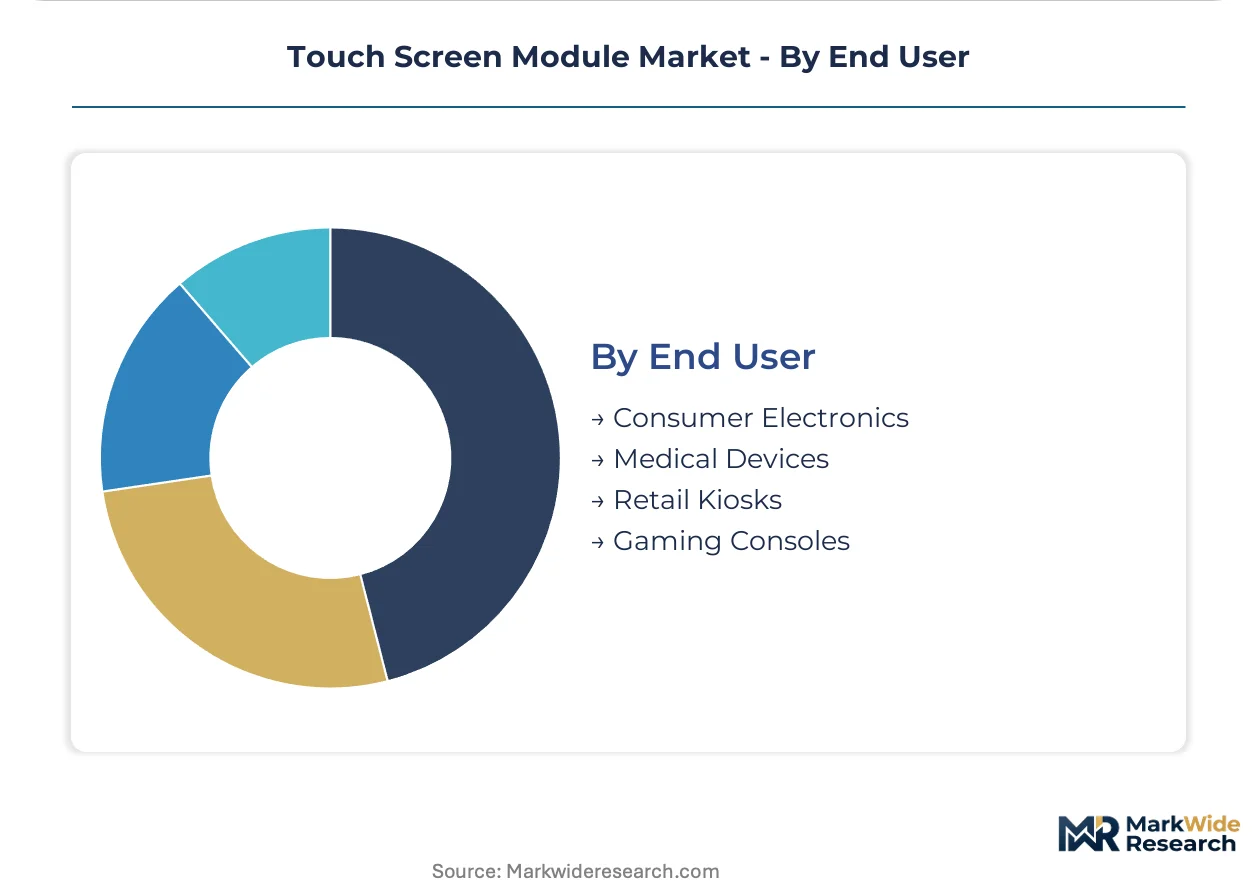
- Consumer Electronics:High-volume smartphone and tablet OEMs drive standardization toward projected-capacitive architectures with minimal bezel width. Supply concentration in China reduces logistics lead times for domestic brands while export-oriented manufacturers navigate FCC Part 15 certification queues for United States market access.
- Medical Devices:IEC 60601 electromagnetic compatibility and liquid-resistance sealing requirements necessitate dedicated controller firmware with false-touch rejection algorithms. Imaging equipment manufacturers in the United States and Germany now specify module-level customization, disintermediating traditional display integrator channels.
- Retail Kiosks:Large-format durability and vandal-resistance specifications favor infrared or surface-capacitive alternatives.
- Gaming Consoles:Low-latency response and pressure-sensitivity requirements drive specialized controller IC selection.
Consumer electronics anchors procurement volume; medical devices deliver the highest per-unit technical premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Automotive OEMs in Germany and Japan absorb premium pricing for AEC-Q100-certified modules, while Chinese smartphone manufacturers drive aggressive cost compression through domestic glass-substrate integration.
China
BOE Technology and Tianma Microelectronics anchor captive production for local EV brands and smartphone OEMs. MIIT technical regulations mandate reliability testing protocols for domestic-deployed touch interfaces. The Yangtze River Delta and Pearl River Delta clusters concentrate glass-substrate processing, controller IC assembly, and optical bonding operations within 200-kilometer logistics radii.
Germany
Automotive tier-1 suppliers qualify silver nanowire laminates for curved center-console designs in premium EV platforms. ECHA REACH compliance mandates hazardous-substance documentation for display adhesives and conductive coatings. The Baden-Württemberg and Bavaria industrial corridors host module qualification labs serving Mercedes-Benz, BMW, and Volkswagen procurement teams.
United States
Medical imaging and kiosk manufacturers specify module-level firmware customization, disintermediating traditional display integrators. FCC Part 15 certification governs electromagnetic emissions from controller electronics, with test queue backlogs extending time-to-market. The Pacific Northwest and Greater Boston clusters concentrate haptic feedback R&D for automotive instrument-cluster applications.
South Korea
Samsung Display leverages backward integration from glass substrate to finished module, sustaining cost advantages in high-volume capacitive production. The country's national electronics regulator enforces electromagnetic compatibility standards aligned with international IEC frameworks. The Seoul Capital Area and Busan-Ulsan corridor host vertically integrated fabs supplying foldable-display mechanical compliance solutions.
Japan
Nissha Printing and Sharp Corporation occupy positions in projected-capacitive and optical bonding specializations. METI carbon-neutrality roadmap subsidies incentivize retrofit of aging module production lines with low-emission equipment. The Kansai/Osaka and Chubu/Nagoya manufacturing belts concentrate precision lamination tooling and sputtering target processing for transparent conductive layers.
Touch Screen Module Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the touch screen module industry. The market structure consolidates around three tiers: vertically integrated display fabs with captive glass supply, specialized touch sensor laminators serving automotive qualification timelines, and mid-scale assemblers competing on optical bonding yield rates. Strategic differentiation concentrates on AEC-Q100 pre-certification investments, silver nanowire conductor adoption timelines, and haptic feedback actuator integration capabilities.
Within the vertically integrated tier, Samsung Display and BOE Technology exemplify scale-driven archetypes with in-house substrate production. TPK Holding occupies a specialist position in projected-capacitive solutions for industrial and medical applications requiring extended qualification support. These three anchors represent the competitive spectrum from commodity volume to premium customization.
| Leading Market Players |
|---|
| Samsung Display |
| LG Display |
| Tianma Microelectronics |
| TPK Holding |
| Nissha Printing |
| 3M Touch Systems |
| Sharp Corporation |
| BOE Technology |
| O-Film Tech |
| Others |
Value Chain & Pricing Dynamics
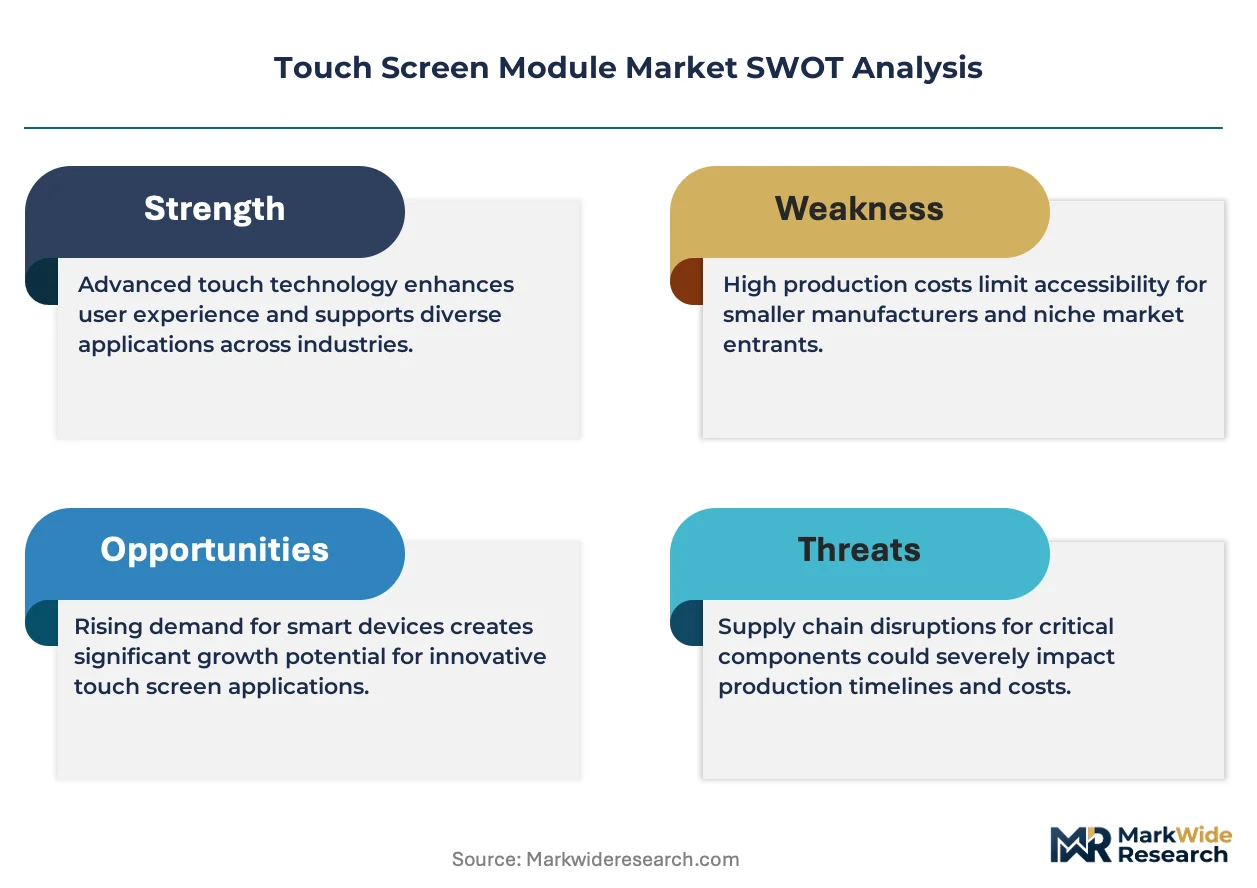
Long-term offtake contracts for indium tin oxide sputtering targets lock in supply access and price visibility for automotive-grade module manufacturers, insulating qualified vendors from spot market volatility while binding them to AEC-Q100 certification investments that OEMs demand under evolving EPA electronics standards.
Pricing Analysis
EU REACH compliance dictates the pricing tier structure across the touch screen module industry, separating premium automotive-grade suppliers with pre-validated adhesive platforms from commodity assemblers facing reformulation costs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Pricing pressure stems from optical bonding yield losses compressing margins for mid-tier assemblers. Chinese smartphone OEMs exhibit highest price sensitivity; German automotive tier-1 suppliers absorb premiums for AEC-Q100 pre-certification.
Supply Chain Analysis
Just-in-time inventory strategies dominate smartphone module procurement, while automotive manufacturers maintain strategic stockpiles of AEC-Q100-qualified components to buffer 18-24 month qualification timelines. Supply concentrates in China, South Korea, and Japan for glass substrate processing, controller IC fabrication, and sputtering target manufacturing. The chain draws from indium tin oxide, silver nanowire conductive films, and piezoelectric actuator materials. Single-source vulnerability in East Asian sputtering target clusters poses structural risk. Distribution runs through tier-1 display integrators for consumer electronics, with direct procurement displacing intermediaries in medical and industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Touch screen module demand sits in early-cycle expansion as automotive functional-safety migration extends touch interfaces from infotainment to instrument-cluster and climate-control applications, creating specification escalation tailwinds for qualified suppliers.
For Market Incumbents: Fortify AEC-Q100 pre-certification portfolios and deepen backward integration into cover-lens processing to defend against silver nanowire conductor substitution and emerging haptic feedback specialists. Prioritize captive bonding facility investments near Chennai and Pune to capture India PLI scheme automotive manufacturing expansion before qualification timelines lock out late entrants. For New Entrants and Emerging Players: Anchor in India automotive module assembly white space created by domestic EV production incentives, targeting tier-1 supplier partnerships for localized optical bonding. Medical imaging equipment manufacturers in the United States present penetrable demand for module-level firmware customization with disintermediation economics. Lead with controller IC algorithm expertise as technical differentiation against commodity assemblers. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated display fabs with captive glass supply and established automotive qualification relationships, as these archetypes capture margin expansion from haptic feedback convergence and foldable-display mechanical compliance requirements. Watch silver nanowire laminate qualification timelines at German and Japanese tier-1 suppliers as inflection signal for conductor technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Pre-Certification Investment | Mercedes-Benz and BMW procurement teams prioritize pre-qualified module vendors with established hazardous-substance documentation under ECHA REACH mandates. |
| Silver Nanowire Conductor Adoption | South Korean and German tier-1 suppliers qualify nanowire-coated film laminates for 2026 model-year curved center-console designs. |
| Haptic Feedback Integration | Piezoelectric actuator pairing with capacitive sensors commands premium positioning in German and United States automotive instrument-cluster applications. |
| India Captive Bonding Facility | PLI scheme incentives create localized assembly demand near Chennai and Pune automotive manufacturing clusters. |
| Direct Procurement Channel | Medical imaging OEMs in the United States and Germany now specify module-level customization, disintermediating traditional display integrators. |
Study Parameters
Initial hypotheses were tested against primary input from automotive tier-1 supplier procurement officers, touch sensor R&D directors, display module plant managers, and medical equipment biomedical engineers and refined through secondary validation against SEC 10-K filings, MIIT technical regulation disclosures, customs trade data for glass substrate and controller IC flows, and AEC-Q100 reliability testing documentation. Bottom-up build from segment-level bill-of-materials analysis triangulated with top-down demand modeling from vehicle production and smartphone shipment databases.
Variance decomposition across product type, technology tier, application segment, and end-user category dimensions structured the analytical framework over the projection horizon. CAGRs derived from logistic adoption curves for automotive functional-safety migration and foldable-display penetration rates. Industry-specific inputs included AEC-Q100 qualification timeline distributions, silver nanowire laminate yield improvement trajectories, and haptic feedback actuator cost-down curves.
Decision-makers should treat outputs as directional under assumptions of sustained automotive electrification capex and REACH compliance timeline adherence; material deviation would warrant model refresh. Specific risk factors include indium supply disruption from rare earth processing volatility, FCC Part 15 certification queue extensions, and controller IC firmware talent scarcity delaying product development. Revision becomes warranted when automotive touch interface specification escalation crosses thresholds that obsolete non-haptic-enabled module architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Low Power Next Generation Display Market
Display Technologies
Global Next Generation Display Market
Display Technologies
8K Display Resolution Market
Display Technologies
Projector Screen Market
Display Technologies
Large Industrial Displays Market
Display Technologies
Touch and Display Integration IC for Tablet Market
Display Technologies
Display Material Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
Global Wearable Display Market
Display Technologies
Global Magic Wall Interactive Surface Market
Display Technologies
Screenless Display Market
Display Technologies
4K Drawing Tablet with Screen Market
Display Technologies
Global Display Market
Display Technologies
Surface-Conduction Electron-Emitter Display (SED) Market
Display Technologies
Holographic Display Market
Display Technologies
Glass-Free HD 3D Display Market