
 Die Spacer Market | 2026-2036
Die Spacer Market Size, Share, and Industry Trends Forecast 2026-2036
Die Spacer Market Insights
East Asian specialty materials producers is restructuring capacity allocation toward thinner, thermally stable die spacer formulations. 3M leverages its polymer science portfolio to sustain leadership in high-tolerance electronic bonding applications. Saint-Gobain anchors European supply through engineered ceramic-polymer composites that address thermal expansion mismatches in automotive power modules. Rogers Corporation differentiates via dedicated R&D intensity in gel-based spacers optimized for 5G base station chipsets.
A die spacer is a precision-engineered interlayer material, typically 25–200 micrometers in thickness, that maintains uniform gap distance between semiconductor dies or between a die and substrate during adhesive bonding and underfill processes. The composition spans acrylic and silicone polymers, silicone gels, synthetic rubbers, and fiber-reinforced composites, selected primarily for controlled compressibility, dielectric stability, and thermal conductivity matching. Polymer and composite formulations command the dominant share of current volume due to their processability in high-speed pick-and-place assembly lines, while gel segments are gaining fastest traction in advanced packaging where stress absorption during thermal cycling prevents die cracking. Aerospace and marine applications remain comparatively mature pockets with slower specification turnover but above-average margin pools tied to qualification cycles and long-term supplier agreements.
EPA guidelines govern volatile organic compound emissions from adhesive manufacturing facilities in the United States, while REACH restricts candidate substance use in polymer formulations sold across European Union member states. Japan's METI enforces JIS standards for electronic component reliability that indirectly shape die spacer performance benchmarks through downstream customer specifications. Buyers should monitor how semiconductor fabrication subsidies in the United States, European Union, Japan, and South Korea redirect supply chain geography and qualification timelines for spacer materials.
Market Dynamics
Heterogeneous integration in semiconductor packaging is compressing die spacer thickness tolerances below 25 micrometers while multiplying thermal cycling stress, forcing materials suppliers to engineer compressible interlayers that absorb mechanical load without sacrificing dielectric stability.
Growth Catalysts
- Heterogeneous Integration Architectures:Advanced packaging facilities in Taiwan and South Korea are specifying ultra-thin die spacers for chiplet-based AI accelerators and high-bandwidth memory stacks, pulling demand toward thermally matched polymer-ceramic composites.
- EPA VOC Emission Controls:Tightened volatile organic compound limits on adhesive manufacturing facilities in the United States are accelerating solvent-free spacer formulation development, qualifying water-based acrylic systems for high-volume pick-and-place lines.
- Automotive Power Module Expansion:Electric vehicle inverter production in Germany and Japan is sourcing fiber-reinforced die spacers that manage thermal expansion mismatches between silicon carbide dies and copper substrates under 150°C continuous operation.
Market Restraints
- Specialty Silicone Feedstock Concentration:Precursor supply for high-purity silicone gel spacers concentrates among three Japanese chemical conglomerates, exposing buyers to allocation risk during semiconductor demand surges.
- REACH Candidate List Expansion:ECHA's periodic addition of polymer additives to Substances of Very High Concern forces reformulation cycles that extend qualification timelines by 12-18 months for European-bound electronics assemblies.
- Thickness-Tolerance Equipment Bottleneck:Slitting and lamination equipment capable of holding ±2 micrometer uniformity across 300mm widths is captive to a narrow base of Japanese and German capital equipment suppliers, constraining capacity scaling.
Strategic Opportunities
- United States Fab Subsidies:CHIPS Act incentives for domestic semiconductor fabrication in Arizona, Texas, and New York are creating qualified supplier opportunities for die spacer producers willing to establish localized compounding and slitting operations.
- 5G Base Station Thermal Management:Massive MIMO radio deployments in India and Southeast Asia are specifying gel-based stress-absorbing spacers for gallium nitride power amplifiers, opening volume demand outside traditional computing centers.
- EU Green Deal Material Circularity:Emerging design-for-recycling mandates for electronic assemblies are creating first-mover advantage for spacer developers offering thermally de-bondable or solvent-reversible adhesive interlayers.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:Compounding operations require chemists fluent in both polymer rheology and semiconductor packaging thermal-mechanical modeling, a skill intersection that remains underdeveloped in technical training programs.
- Automotive AEC-Q100 Qualification Burden:Power module suppliers demand 1,000-hour high-temperature operating life validation data that extends new product introduction cycles to 24-36 months, compressing returns on R&D investment.
- Cleanroom Contamination Protocols:Sub-50 micrometer spacer production requires ISO Class 5 manufacturing environments that add 40-60% to fixed cost bases compared to standard industrial adhesive operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Die Spacer Market |
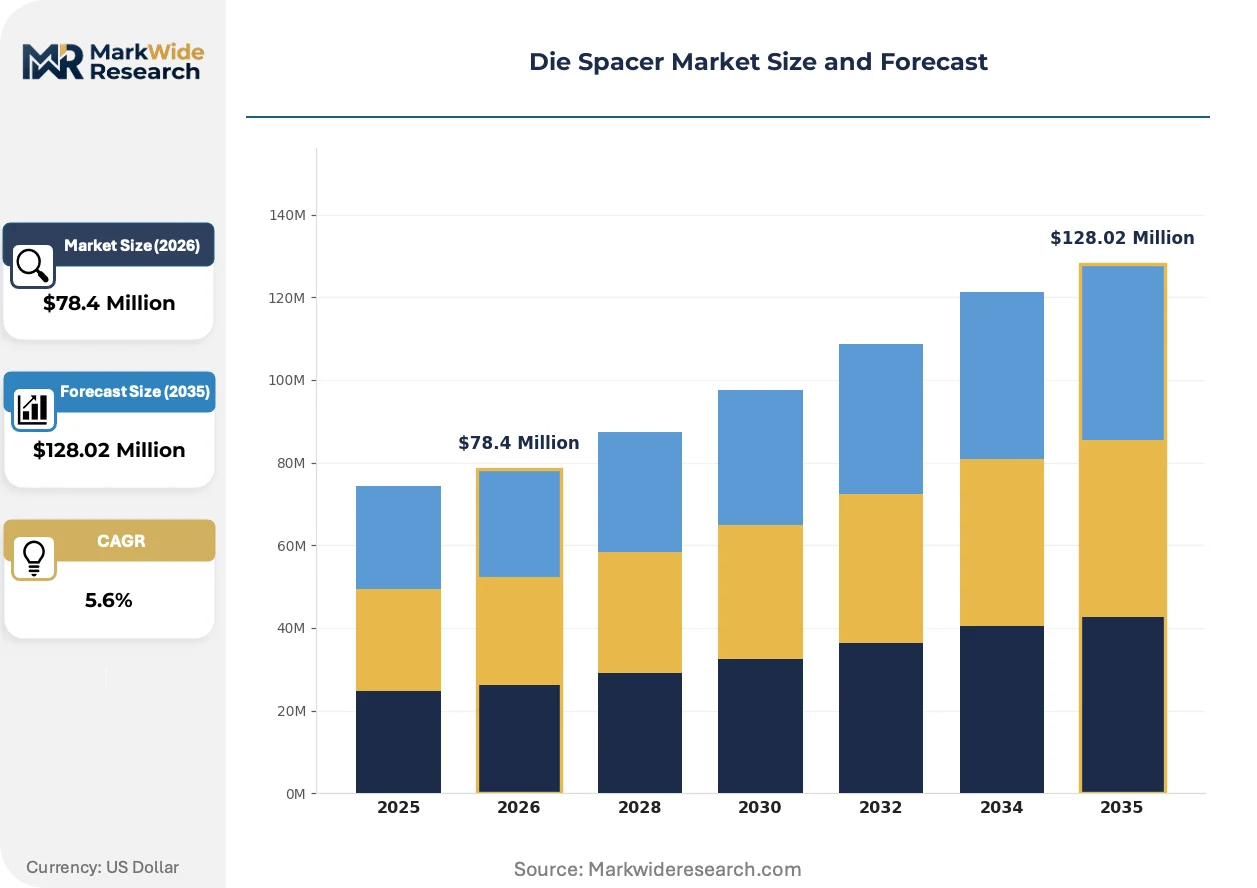
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $128.02 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer, Gel, Rubber, Composites Application: Automobile, Electronics, Aerospace, Marine End User: Manufacturers, R&D Institutions, Distributors, Contractors Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | 3M, Saint-Gobain, Rogers Corporation, Lohmann, Asahi Kasei, Amorim Cork Solutions, Alkegen, Systems Protection, Wingtai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Die Spacer Market Trends and Innovations
Active materials engineering is displacing conventional commodity interlayers with functionally graded compositions that simultaneously manage thermal, mechanical, and electrical interface requirements in single-layer architectures.
Silicone gel formulations with tunable compressibility profiles are modularizing the die spacer category by enabling a single material grade to span multiple gap thicknesses and stress regimes. Automotive inverter manufacturers in Japan are adopting these gels at accelerated qualification paces. The technology is modularizing supplier-customer relationships around platform material agreements rather than part-number-specific sourcing.
REACH substance disclosure requirements are tightening upstream chemical traceability obligations for polymer formulations sold across European Union member states. Electronics assemblers now demand full bill-of-materials documentation extending to sub-0.1% concentration thresholds. Medical device and automotive power module segments are responding by pre-qualifying spacer grades with ECHA-registered substance portfolios to avoid supply interruption.
Consolidated procurement functions at Taiwanese and South Korean semiconductor packaging houses are compressing supplier qualification cycles while extending volume commitment horizons. Direct material specification authority is migrating from tier-two adhesive converters to tier-one OSATs and IDMs, displacing distributor-led technical selection. This concentration is most visible in Hsinchu and Seoul metropolitan area manufacturing clusters serving AI accelerator tape-out schedules.
Die Spacer Market Segmentation
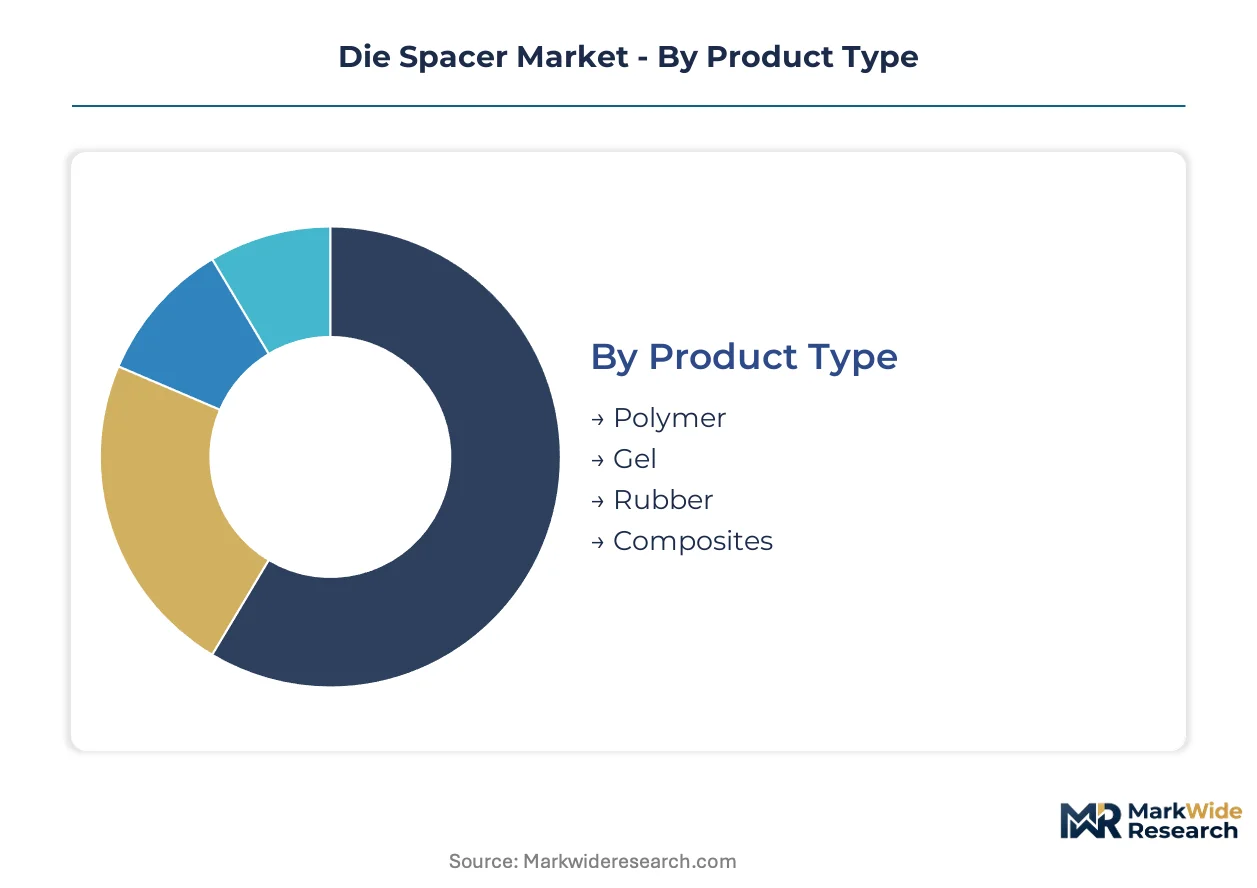
Die spacer procurement patterns diverge sharply across material chemistries, end-use thermal requirements, and customer technical capabilities. Segmentation reveals where formulation complexity commands premium positioning versus where commoditized supply dominates.
Product Type:
Capital intensity peaks in composite and gel segments, where cleanroom manufacturing infrastructure and precision slitting equipment lock out smaller compounders.
- Polymer:Acrylic and silicone polymer formulations deliver controlled compressibility in 25-100 micrometer thicknesses for high-speed pick-and-place lines. Electronics manufacturers in Taiwan and South Korea specify these grades for heterogeneous integration packaging where dielectric stability must hold across thermal cycling. Most installed capacity flows through Polymer. Expansion is steepest in Gel.
- Gel:Tunable compressibility profiles enable single material platforms to span multiple gap thicknesses and stress regimes. Japanese automotive inverter manufacturers accelerated qualification paces for silicone gel spacers managing thermal expansion mismatches in silicon carbide power modules.
- Rubber:Synthetic rubber interlayers serve mature aerospace and marine bonding applications with slower specification turnover but extended qualification cycles.
- Composites:Fiber-reinforced ceramic-polymer hybrids address 150°C continuous operation in electric vehicle inverters, requiring substantial upfront investment in lamination and thermal testing infrastructure.
Polymer retains volume leadership through electronics packaging scale. Gel climbs fastest as advanced packaging architectures multiply stress-absorption requirements.
Application:
Margin structures invert across segments: automotive and electronics chase qualification-heavy premium tiers while aerospace and marine harvest long-term agreement stability.
- Electronics:AI accelerator and high-bandwidth memory packaging in Taiwanese OSAT facilities specifies ultra-thin die spacers below 25 micrometer tolerances. Heterogeneous integration architectures multiply thermal cycling stress, pulling demand toward thermally matched polymer-ceramic composites.
- Automobile:Electric vehicle inverter production in Germany and Japan sources fiber-reinforced spacers managing thermal expansion mismatches between silicon carbide dies and copper substrates. AEC-Q100 qualification demands 1,000-hour high-temperature operating life validation, extending new product introduction cycles to 24-36 months.
- Aerospace:Mature specification environments with above-average margin pools tied to long-term supplier agreements and extended recertification timelines.
- Marine:Comparable maturity to aerospace, with slower technology turnover and stable procurement patterns through defense and commercial shipbuilding channels.
Electronics channels the highest absolute volume. Automotive posts the steepest specification upgrade trajectory as power module thermal requirements intensify.
End User:
Technical specification authority concentrates differently across customer types, with direct manufacturers capturing increasingly dominant material selection influence.
- Manufacturers:Tier-one semiconductor packaging houses and automotive power module producers now hold direct specification authority, displacing distributor-led technical selection. Consolidated procurement functions in Hsinchu and Seoul metropolitan areas compress supplier qualification cycles while extending volume commitment horizons.
- R&D Institutions:Materials science laboratories and university-industry partnerships pilot next-generation spacer formulations, particularly thermally de-bondable interlayers for EU Green Deal circularity compliance.
- Distributors:Technical selection role eroding as OSATs and IDMs internalize material specification authority, though regional inventory positioning remains relevant for smaller contract manufacturers.
- Contractors:Sub-tier electronics assemblers rely on distributor technical support for grade selection, particularly in emerging 5G base station deployments across India and Southeast Asia.
Manufacturers command specification gravity. R&D institutions drive fastest formulation innovation cycles.
Distribution Channel:
Channel economics split between high-touch technical selling for qualified grades and transactional efficiency for standardized formulations.
- Direct Sales:Dominates qualified polymer and gel grades for semiconductor packaging, with technical field engineers co-developing slitting specifications and cleanroom handling protocols alongside Taiwanese and South Korean OSATs.
- Wholesale:Channels standardized rubber and composite grades to automotive tier suppliers and aerospace contractors through regional distribution centers.
- Online:Emerging for sample procurement and small-volume orders from R&D institutions, though qualified production volumes remain offline due to technical support requirements.
- Retail:Minimal presence limited to maintenance-repair-operations segments in marine and legacy industrial applications.
Direct sales captures qualified grade premium. Wholesale handles highest absolute tonnage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting die spacer compounding capacity toward jurisdictions with streamlined chemical registration protocols and semiconductor fabrication subsidies. Manufacturers are relocating slitting operations to align with CHIPS Act incentives in the United States and equivalent programs in East Asia, compressing qualification timelines for advanced packaging supply chains.
United States
CHIPS Act subsidies for domestic semiconductor fabrication in Arizona, Texas, and New York are creating qualified supplier opportunities for die spacer producers establishing localized compounding operations. EPA volatile organic compound emission controls on adhesive manufacturing facilities are accelerating solvent-free formulation development. Greater Phoenix and Austin metropolitan areas concentrate new cleanroom production investments serving Intel and TSMC advanced packaging facilities.
Taiwan
Heterogeneous integration packaging for AI accelerators and high-bandwidth memory stacks is pulling demand toward ultra-thin die spacers below 25 micrometer tolerances. METI-equivalent industrial standards through downstream customer specifications shape performance benchmarks for materials suppliers. Hsinchu Science Park anchors the highest concentration of OSAT procurement functions, with consolidated technical specification authority migrating from distributors to tier-one packaging houses.
South Korea
High-bandwidth memory production and chiplet-based AI accelerator packaging are specifying thermally matched polymer-ceramic composite spacers. Government semiconductor fabrication subsidies redirect supply chain geography toward domestic material qualification. Seoul metropolitan area manufacturing clusters serve Samsung and SK Hynix tape-out schedules with compressed supplier qualification cycles and extended volume commitments.
Germany
Electric vehicle inverter production sources fiber-reinforced die spacers managing thermal expansion mismatches in silicon carbide power modules under 150°C continuous operation. REACH candidate list expansions force reformulation cycles extending qualification timelines for European-bound electronics assemblies. Bavaria and Baden-Württemberg concentrate automotive power module supply chains with AEC-Q100 validation requirements.
Japan
Silicone gel spacer qualification for automotive inverter applications is accelerating as silicon carbide power module deployment intensifies. METI enforces JIS standards for electronic component reliability that indirectly shape die spacer performance benchmarks. Kyushu and Nagoya industrial corridors host concentrated precursor supply for high-purity silicone gel formulations among chemical conglomerates.
Die Spacer Market Competitive Landscape
East Asian producers anchor the high-volume tier for electronics packaging applications; European and North American specialists hold premium positioning in automotive and aerospace qualification-heavy segments. The vendor base separates into consolidated polymer science conglomerates, engineered materials specialists with ceramic-polymer composite portfolios, and regional compounders serving distributor channels. Three archetypes dominate: diversified chemical conglomerates leveraging polymer science breadth, engineered materials specialists with thermal-mechanical modeling capabilities, and regional converters with slitting equipment access. Competitive moves concentrate on geographic expansion through CHIPS Act-aligned facility investments and portfolio diversification into gel-based stress-absorbing formulations.
Among diversified materials conglomerates, 3M and Saint-Gobain occupy positions spanning multiple die spacer chemistries and end-use qualifications. 3M represents the polymer science archetype with electronic bonding application breadth, while Saint-Gobain exemplifies engineered ceramic-polymer composite specialization for thermal expansion management. Rogers Corporation sits within the dedicated R&D intensity tier, with positioning in gel-based spacer development for telecommunications and computing applications. These three anchors demonstrate how competitive differentiation flows from material science depth rather than scale alone.
| Leading Market Players |
|---|
| 3M |
| Saint-Gobain |
| Rogers Corporation |
| Lohmann |
| Asahi Kasei |
| Amorim Cork Solutions |
| Alkegen |
| Systems Protection |
| Wingtai |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between AEC-Q100 automotive-qualified spacers and standard industrial grades manifests in parallel pricing and sourcing configurations. Premium tiers command three-tier pricing structure across automotive, advanced packaging, and industrial economy levels while drawing from Japanese and German precision equipment networks, whereas commodity polymer grades price through distributor markups anchored in Taiwanese compounding clusters.
Pricing Analysis
Distributor margins compress most severely in standardized polymer die spacers where Taiwanese OSATs negotiate direct-to-manufacturer discounts bypassing wholesale channels. Price differentiation hinges on cleanroom certification tier and thermal cycling performance grade, with automotive AEC-Q100 validation commanding substantial premiums over industrial specifications. Cost compression in commodity acrylic formulations is intensifying because REACH-driven reformulation cycles extend supplier qualification timelines. Contract manufacturers in India and Southeast Asia exhibit highest price sensitivity, while German automotive power module producers prioritize thermal performance over unit economics.
Supply Chain Analysis
Regional distribution centers in Hsinchu, Seoul, and Nagoya operate hub-and-spoke patterns feeding precision slitting operations to advanced packaging facilities. Geographic supply concentration centers on Taiwan, South Korea, and Japan for high-purity silicone gel precursors and ±2 micrometer tolerance lamination equipment. Raw material dependencies draw from specialty silicone feedstocks, ceramic fiber reinforcements, and water-based acrylic resin systems. Single-source vulnerability concentrates among three Japanese chemical conglomerates controlling high-purity silicone precursor supply. Distribution runs through direct technical sales for qualified grades and wholesale channels for standardized rubber and composite formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Die spacer procurement has shifted toward late-cycle quality specifications as heterogeneous integration architectures demand sub-25 micrometer tolerances and 1,000-hour thermal validation data. This quality migration favors incumbents with established cleanroom infrastructure and automotive qualification portfolios.
For Market Incumbents: To counter silicone precursor supply concentration risk, secure backward integration into specialty resin compounding or establish dual-source agreements with Japanese chemical conglomerates. Prioritize capacity addition in Greater Phoenix and Austin metropolitan areas to align with CHIPS Act semiconductor fabrication subsidies, while extending AEC-Q100 validation coverage to capture automotive power module specification authority from tier-two adhesive converters. For New Entrants and Emerging Players: Begin with gel-based spacer formulations for 5G base station gallium nitride power amplifiers in India and Southeast Asia, where technical specification authority remains fragmented among regional contractors. Target thermally de-bondable interlayers for EU Green Deal circularity compliance as the most penetrable innovation segment. Pursue platform material agreements with Japanese automotive inverter manufacturers rather than part-number-specific sourcing relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where cleanroom manufacturing infrastructure and precision slitting equipment create insurmountable barriers for regional compounders. Long-term viability favors engineered materials specialists with ceramic-polymer composite capabilities and established thermal-mechanical modeling competencies. Acquisition targets should demonstrate qualified supplier status with at least one tier-one OSAT or automotive power module producer. Monitor CHIPS Act facility announcement timelines as the critical inflection signal for domestic United States supply chain repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO Class 5 manufacturing infrastructure captures premium qualification tiers from semiconductor packaging houses in Hsinchu. |
| Backward Integration into Silicone Precursors | In-house production of high-purity gel formulations mitigates allocation risk from Japanese chemical conglomerates during demand surges. |
| AEC-Q100 Certification Investment | Automotive validation protocols unlock 24-36 month supply agreements with German and Japanese electric vehicle inverter producers. |
| Water-Based Acrylic Formulation Development | Solvent-free systems qualify for EPA VOC emission controls while maintaining pick-and-place line compatibility. |
| Regional Distribution Hub Establishment | Hub-and-spoke logistics in Seoul metropolitan area compress lead times for Samsung and SK Hynix tape-out schedules. |
Research Methodology
Coverage spans East Asian electronics manufacturing clusters, European automotive power module corridors, and United States CHIPS Act incentive zones, with primary inputs from each region combining structured interviews with semiconductor packaging procurement directors, automotive tier-one supplier material engineers, and specialty chemical R&D directors. Secondary validation draws from SEC filings of engineered materials specialists, Japan Chemical Industry Association trade statistics, and EPA enforcement action databases. Bottom-up segment sizing triangulates against top-down semiconductor packaging equipment spend estimates.
Rate-of-change decomposition separates volume expansion from specification upgrade effects across the analysis window. The analytical framework models material chemistry, end-use thermal requirement, and customer technical capability dimensions alongside geographic production hub clustering. CAGRs derive from installed base replacement cycles and heterogeneous integration adoption curves. Forecast inputs incorporate semiconductor fabrication subsidy disbursement timelines and REACH candidate list expansion schedules.
Caveats apply where ECHA substance restrictions or EPA guideline revisions could materially shift qualification timelines and reformulation costs. Forecasts reflect assumptions about cleanroom capacity scaling and silicone precursor supply elasticity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Silicon on Insulator Market
Semiconductor Devices
Voltage Controlled Oscillators Market
Semiconductor Devices
Europe Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Ferroelectric FET Market
Semiconductor Devices
Amorphous-Semiconductor Devices Market
Semiconductor Devices
Europe Power Transistor Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
ADC & DAC In Quantum Computing Market
Semiconductor Devices
APAC Semiconductor Device for Processing Applications Market
Semiconductor Devices
Global Probe Card Market
Semiconductor Devices
Leadframes Market
Semiconductor Devices
Power Transistor Market
Semiconductor Devices
Field Effect General Purpose Transistors Market
Semiconductor Devices
Silicon Carbide Semiconductor Devices Market
Semiconductor Devices
Global Inp Wafer Market
Semiconductor Devices
Wttx Market