
 Surface-Conduction Electron-Emitter Display (SED) Market | 2026-2036
Surface-Conduction Electron-Emitter Display (SED) Market Size, Share, and Industry Trends Forecast 2026-2036
Surface-Conduction Electron-Emitter Display (SED) Market Analytics
Buyer concentration in the healthcare and medical imaging sector is rebalancing as hospital procurement networks consolidate purchasing authority while specialized clinics fragment into smaller buying units. Samsung Display leverages its semiconductor fabrication heritage to sustain electron-emitter precision manufacturing. Canon anchors its position through captive research in surface-conduction physics. Toshiba competes by maintaining legacy cathode-ray engineering expertise that informs SED thermal management.
Surface-Conduction Electron-Emitter Display technology employs nanometer-scale electron emitters deposited on a substrate to excite phosphors without heated filaments, achieving luminance efficiency exceeding conventional cathode-ray architectures. The manufacturing process requires vacuum-sealed glass panels with sub-micron emitter patterning through photolithography or inkjet deposition, producing displays intended for high-contrast, wide-viewing-angle applications where color fidelity and response time supersede cost minimization. Consumer electronics applications remain mature with limited volume expansion, while medical imaging segments attract margin pools due to stringent diagnostic calibration requirements. Professional displays occupy a transitional position where field-emission alternatives and liquid-crystal backplanes compete for upgrade budgets in broadcasting and command-center environments.
Japan's METI enforces standby power regulations that SED developers must satisfy for domestic commercialization, while the country's JIS standards govern electromagnetic compatibility in display equipment. The EPA Energy Star program in the United States shapes export-oriented product specifications through efficiency benchmarking that SED manufacturers navigate for North American medical and professional display access. Stakeholders must monitor how field-emission and organic light-emitting diode technologies converge or diverge in performance-per-watt metrics to determine whether SED retains defensible positioning in premium display niches.
Market Dynamics
Japan's METI energy-efficiency mandates are compressing development timelines for vacuum-sealed display architectures, forcing manufacturers to prioritize phosphor-excitation efficiency over incremental pixel-density gains.
Growth Catalysts
- Diagnostic calibration mandates:Healthcare facilities in Japan and South Korea require high-fidelity imaging displays that exceed liquid-crystal color-gamut specifications.
- Photolithography precision gains:Sub-micron emitter patterning advances from semiconductor fabrication are transferring directly to SED substrate manufacturing.
- East Asian research infrastructure:Concentrated electron-emission expertise in Tsukuba and Daejeon accelerates prototype-to-production cycles for medical-grade panels.
Market Restraints
- Vacuum-sealed glass input costs:Borosilicate substrate pricing volatility constrains margin flexibility for panel assemblers.
- Single-region phosphor supply:Rare-earth element processing concentrates in Chinese refining corridors, creating geographic vulnerability.
- Organic light-emitting diode substitution:Self-emissive OLED architectures achieve comparable contrast ratios at thinner form factors for portable diagnostic equipment.
Strategic Opportunities
- Underpenetrated surgical navigation:Operating-room displays in German university hospitals remain tethered to legacy cathode-ray tube color standards.
- Japan's carbon-neutrality roadmap:METI subsidies for low-power display technologies create procurement preference for electron-emission panels in public healthcare infrastructure.
- Inkjet deposition convergence:Printing-based emitter patterning is expanding into roll-to-roll manufacturing formats previously reserved for liquid-crystal backplanes.
Industry Challenges
- Vacuum-physics engineering scarcity:Specialized technicians capable of maintaining sub-10^-6 Torr sealing processes command premium compensation in Osaka and Suwon manufacturing clusters.
- Electromagnetic compatibility certification:JIS C 61000-6-2 testing timelines extend commercialization schedules for new panel form factors by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface-Conduction Electron-Emitter Display (SED) Market |
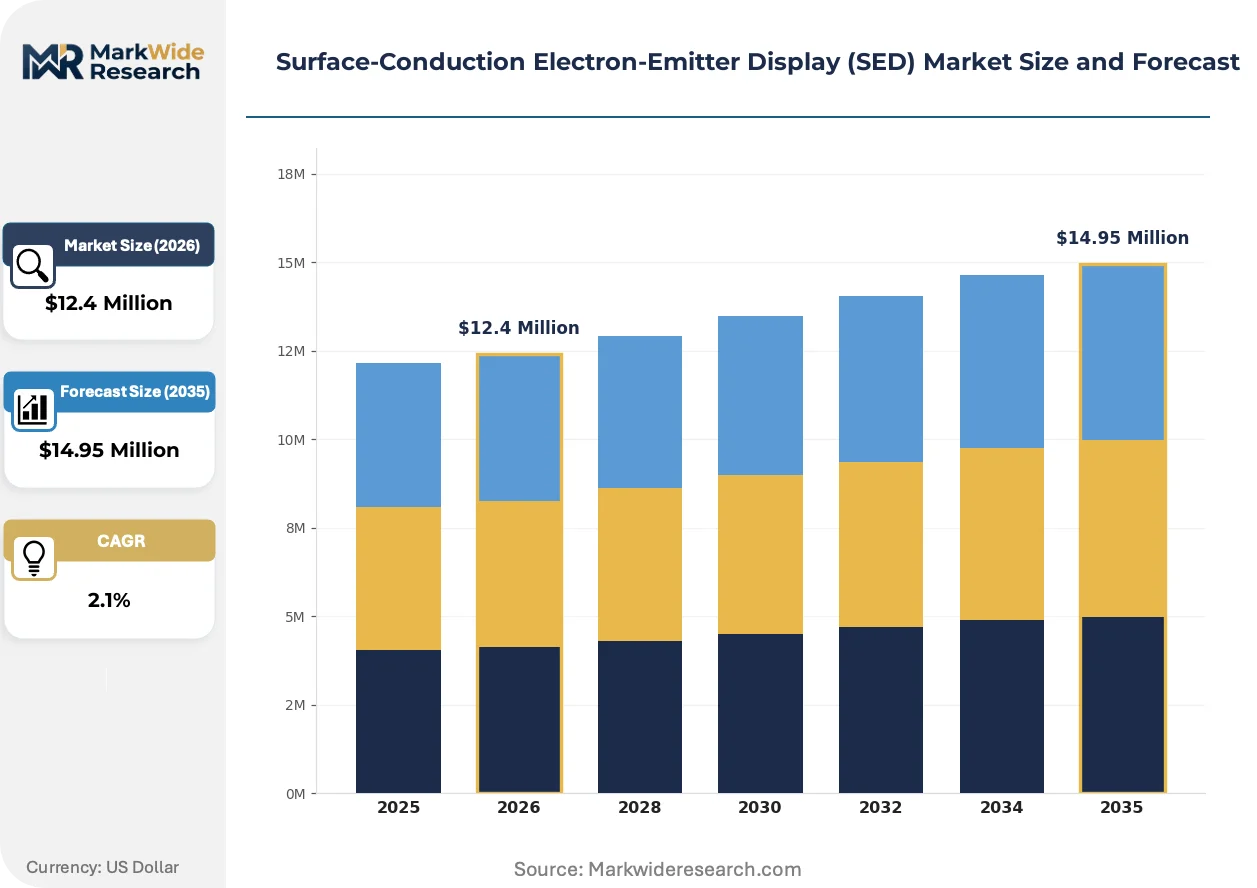
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $14.95 Million |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer Electronics, Professional Displays, Digital Signage, Home Theatre Systems Technology: Field Emission, Cathode Ray, Liquid Crystal, Organic Light Emitting Diode End User: Commercial, Residential, Educational, Healthcare Application: Entertainment, Advertising, Information Display, Medical Imaging |
| Companies Covered | Samsung Display, LG Display, Sharp Corporation, BOE Technology Group, Innolux Corporation, AUO Corporation, Sony Group Corporation, Canon, Toshiba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface-Conduction Electron-Emitter Display (SED) Market Evolving Landscape
Electron-emission architectures are bifurcating between premium medical imaging and legacy industrial monitoring, with manufacturing process innovation determining which applications retain economic viability.
Nanometer-scale surface-conduction emitters are expanding into diagnostic radiology suites where luminance stability across 50,000-hour operational lifespans outweighs acquisition cost sensitivity. Japanese university hospitals in Tokyo and Osaka are adopting these panels for mammography review stations. The technology is expanding into a defensible niche between liquid-crystal precision limits and field-emission display commercialization delays.
Japan's METI standby power regulations now require sub-1-watt consumption in display-off states, compelling redesigns of electron-emission driver circuits. Domestic manufacturers must recertify existing product lines under amended technical criteria released through the Agency for Natural Resources and Energy. Medical display exporters targeting Japanese procurement networks are prioritizing compliance over North American Energy Star benchmarking.
Hospital procurement networks are consolidating purchasing authority through regional health system alliances in Kanagawa and Aichi prefectures. Specialized diagnostic clinics fragment into independent buying units with shorter replacement cycles. This concentration-fragmentation tension is most visible in South Korea, where Samsung Medical Center's centralized tendering contrasts with Seoul's proliferating ophthalmology practices specifying individual display units.
Surface-Conduction Electron-Emitter Display (SED) Market Segmentation
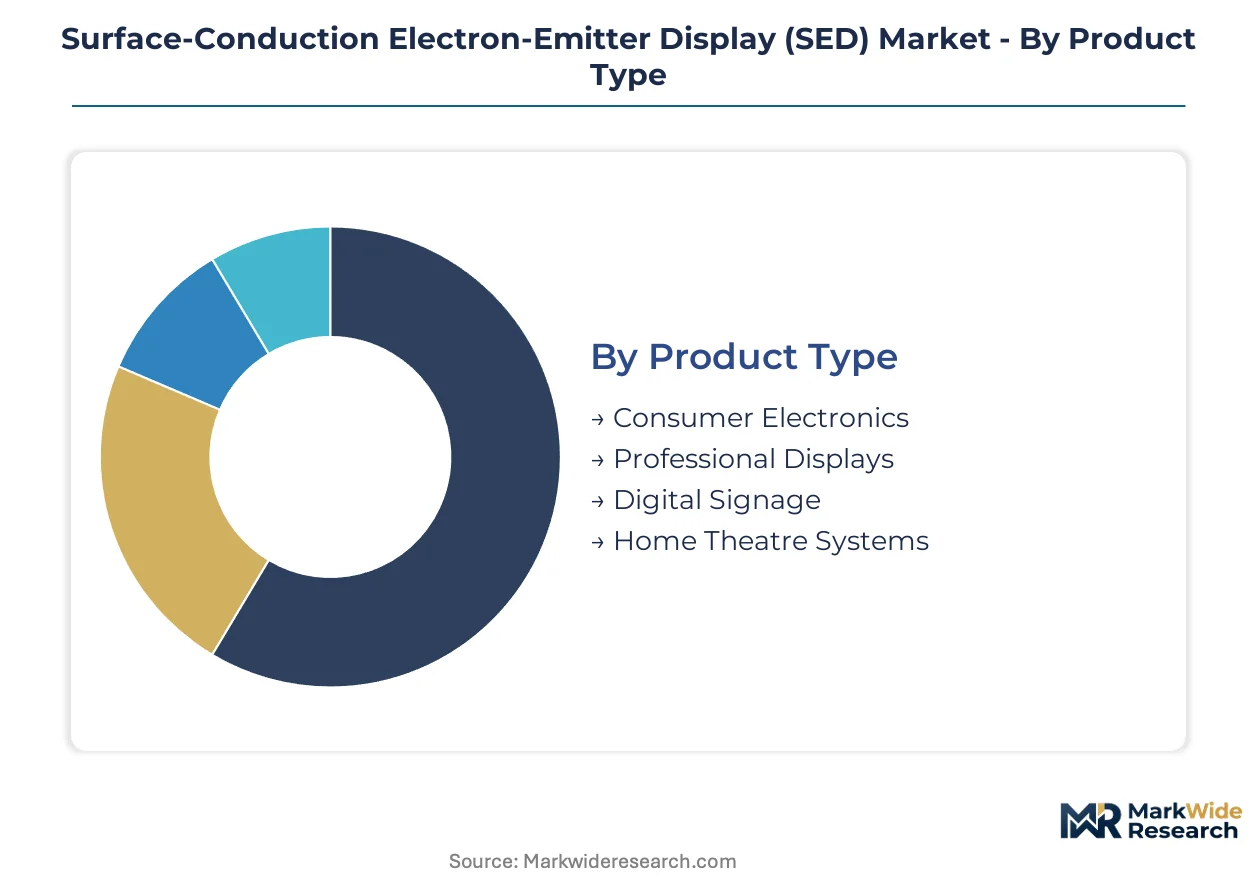
Surface-Conduction Electron-Emitter Display market segmentation reveals how electron-emission architectures compete differently across fidelity requirements, power constraints, and procurement authority structures. Buyers sort into distinct value pools based on diagnostic calibration needs versus cost minimization priorities.
Product Type:
Cost tier differentiation separates premium medical-grade panels from volume-oriented consumer alternatives.
- Consumer Electronics:Standard-definition television applications employ simplified emitter arrays with reduced phosphor-excitation precision. Demand concentrates in Japanese collector markets where cathode-ray nostalgia sustains niche volume for legacy format compatibility.
- Professional Displays:Broadcasting control rooms and command centers specify wide-gamut color reproduction with 50,000-hour luminance stability. South Korean network infrastructure procurement favors these panels for master monitor applications where liquid-crystal response latency fails.
- Digital Signage:Commercial advertising installations prioritize daylight-visible brightness over color accuracy.
- Home Theatre Systems:Enthusiast segments in Osaka and Tokyo seek vacuum-display contrast ratios for film-originated content.
Professional Displays lead volumes today; Digital Signage is gaining share fastest.
Technology:
Application context determines which emission physics satisfy power-efficiency mandates versus image-quality thresholds.
- Field Emission:Cold-cathode architectures achieve higher electron-beam current density than surface-conduction alternatives. Medical imaging procurement in Tsukuba research corridors favors this technology for mammography review stations requiring sub-pixel precision.
- Cathode Ray:Heated-filament electron guns dominate legacy industrial monitoring infrastructure. German university hospitals maintain these displays for surgical navigation color standard continuity despite METI efficiency penalties.
- Liquid Crystal:Backlit thin-film transistor panels compete on form factor and manufacturing scale.
- Organic Light Emitting Diode:Self-emissive architectures threaten SED positioning in portable diagnostic equipment where thickness constraints dominate.
Field Emission anchors medical-grade revenue; Organic Light Emitting Diode is expanding most quickly in mobile applications.
End User:
Customer type fragmentation shapes procurement cycle length and specification authority concentration.
- Healthcare:Hospital procurement networks in Kanagawa and Aichi prefectures consolidate tendering authority through regional health system alliances. Diagnostic calibration mandates from Japan's PMDA drive specification of electron-emission panels for radiology review.
- Commercial:Corporate display installations prioritize total cost of ownership over color fidelity metrics.
- Residential:Individual consumers in South Korea and Japan purchase through specialized electronics retailers with extended replacement cycles.
- Educational:University research laboratories in Daejeon specify SED panels for electron-physics demonstration equipment.
Healthcare dominates premium pricing; Educational procurement shows steepest expansion trajectory.
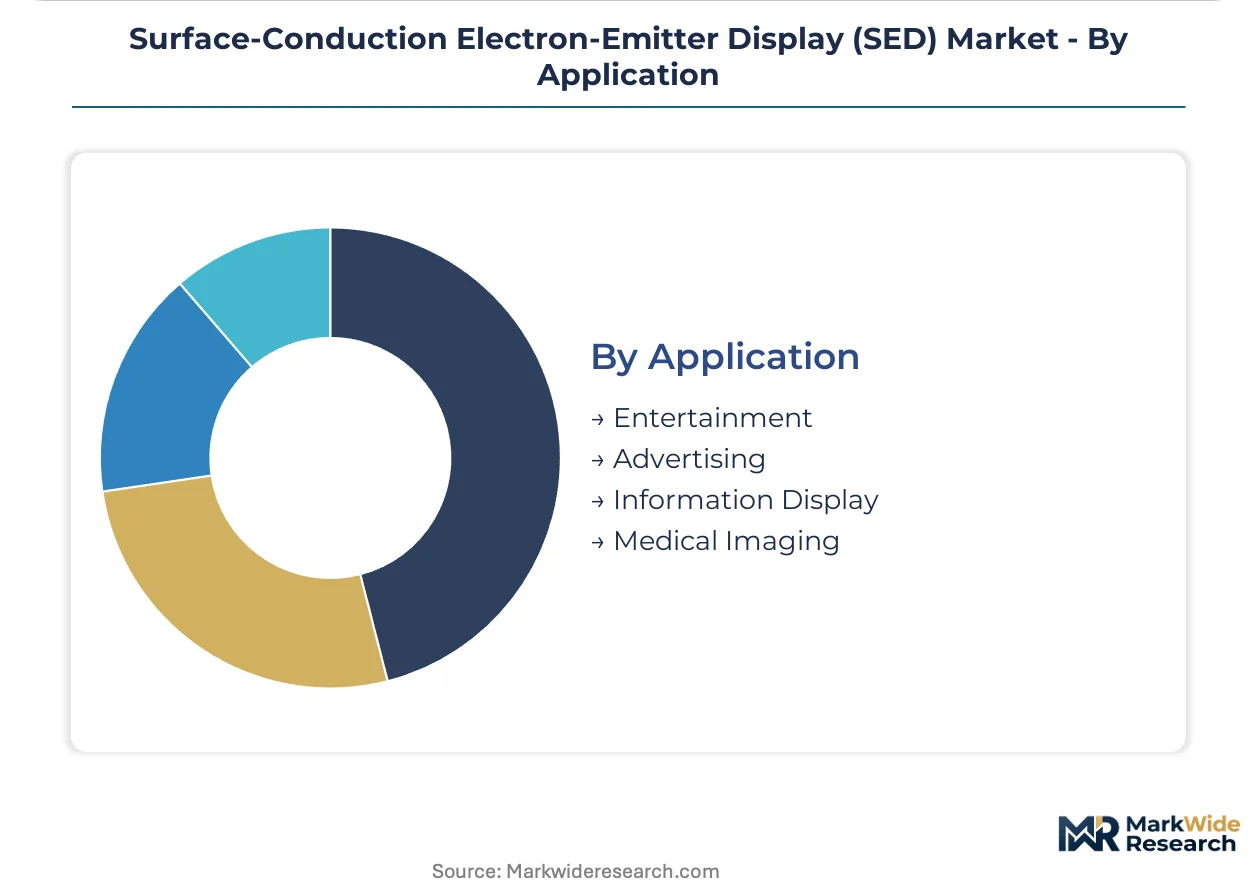
Application:
Volume scale versus margin concentration splits manufacturing priorities across use cases.
- Medical Imaging:Diagnostic radiology suites require luminance stability certification exceeding liquid-crystal capabilities. Tokyo university hospitals specify these panels for mammography review where color consistency across 50,000-hour lifespans outweighs acquisition cost.
- Entertainment:Home theatre and broadcast monitoring applications seek vacuum-display contrast performance.
- Advertising:Digital out-of-home networks prioritize brightness and durability over color gamut.
- Information Display:Transit and public venue applications demand reliability in continuous-operation environments.
Medical Imaging commands highest unit margins; Information Display generates largest shipment volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan concentrates electron-emission research infrastructure and regulatory shaping power, while South Korea leverages semiconductor fabrication heritage for precision manufacturing scale-up.
Japan
Hospital procurement networks in Kanagawa and Aichi prefectures consolidate tendering authority through regional health system alliances. METI standby power regulations now mandate sub-1-watt consumption in display-off states, compelling driver circuit redesigns. Tsukuba research corridors accelerate prototype-to-production cycles for medical-grade panels.
South Korea
Samsung Medical Center's centralized tendering contrasts with Seoul's proliferating ophthalmology practices specifying individual display units. The national MFDS calibration standards drive specification of high-fidelity imaging displays. Daejeon electron-physics laboratories supply specialized technicians for vacuum-sealing processes.
United States
EPA Energy Star benchmarking shapes export-oriented product specifications for North American medical display access. Hospital procurement consolidation in the Northeast Corridor rebalances purchasing authority toward regional networks. Research partnerships in Greater Boston explore phosphor-excitation efficiency improvements.
Germany
University hospitals in Bavaria and North Rhine-Westphalia maintain surgical navigation displays tethered to legacy cathode-ray tube color standards. The KBA-equivalent medical device regulator enforces electromagnetic compatibility testing extending commercialization timelines. Industrial clusters in Baden-Württemberg supply precision glass substrate fabrication.
China
Rare-earth element processing concentrates refining corridors creating geographic vulnerability for phosphor supply chains. MIIT energy-efficiency standards for display technologies shape product development trajectories for export manufacturers. Yangtze River Delta fabrication facilities produce borosilicate substrates with volatile pricing.
Surface-Conduction Electron-Emitter Display (SED) Market Competitive Landscape
Japanese producers anchor the premium medical-grade tier; South Korean specialists hold scale-driven manufacturing positions. The vendor base concentrates around electron-emitter precision capabilities and vacuum-physics engineering heritage. Three archetypes dominate: semiconductor-fabrication heritage players, captive research laboratories with surface-conduction physics depth, and legacy cathode-ray engineering specialists. Competitive moves center on strategic partnerships for phosphor supply security and technology licensing for inkjet deposition convergence.
Within the heritage-electronics tier, Samsung Display, Canon, and Toshiba occupy distinct positioning vectors. Samsung Display exemplifies the semiconductor-fabrication heritage archetype with electron-emitter precision manufacturing capabilities. Canon represents captive research depth in surface-conduction physics. Toshiba anchors legacy cathode-ray engineering expertise informing thermal management approaches.
| Leading Market Players |
|---|
| Samsung Display |
| LG Display |
| Sharp Corporation |
| BOE Technology Group |
| Innolux Corporation |
| AUO Corporation |
| Sony Group Corporation |
| Canon |
| Toshiba |
| Others |
Value Network & Pricing Analysis
Specialized vacuum-physics technicians concentrated in Osaka and Suwon manufacturing clusters command premium compensation, widening labor-cost spreads between medical-grade and consumer-tier pricing bands. METI energy-efficiency mandates add certification overhead that concentrates pricing power among incumbent Japanese producers with captive compliance infrastructure.
Pricing Analysis
Capacity additions in Chinese borosilicate substrate fabrication are reshaping price floors for panel assemblers. Three-tier pricing structure across medical-certified, professional-grade, and consumer levels separates luminance-stability guarantees from basic phosphor-excitation performance. Cost compression in consumer electronics tiers is intensifying because OLED alternatives achieve comparable contrast at thinner form factors. Hospital procurement networks exhibit lowest price sensitivity due to diagnostic calibration mandates, while digital signage buyers prioritize acquisition cost over longevity metrics.
Supply Chain Analysis
JIS C 61000-6-2 electromagnetic compatibility certification gates access to Japanese healthcare procurement networks, extending commercialization timelines. Rare-earth phosphor processing concentrates in Chinese refining corridors, borosilicate glass substrate fabrication clusters in the Yangtze River Delta, and vacuum-sealing equipment production in German industrial zones. Supply chain risk centers on single-source vulnerability for terbium and europium phosphor precursors. Distribution runs through regional health system alliances in Kanagawa and Aichi prefectures for medical-grade panels, with specialized electronics retailers handling enthusiast consumer volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where METI standby power mandates and PMDA diagnostic calibration requirements create procurement preference for compliant domestic manufacturers.
For Market Incumbents: Anchor market position through backward integration into rare-earth phosphor precursor supply chains, mitigating Chinese refining corridor concentration risk. Deepen captive research in surface-conduction physics to defend against field-emission display substitution in mammography review applications. Prioritize JIS certification maintenance over incremental pixel-density gains.
For New Entrants and Emerging Players: Enter via underpenetrated surgical navigation segments in German university hospitals where legacy cathode-ray color standard continuity sustains replacement demand. Target ophthalmology practices in Seoul specifying individual display units with shorter procurement cycles. Lead with inkjet deposition manufacturing partnerships to bypass photolithography capital intensity.
For Investors and Strategic Acquirers: Semiconductor-fabrication heritage players are the most active acquirer in this space, seeking electron-emitter precision capabilities. Long-term viability hinges on defensible positioning between liquid-crystal precision limits and OLED commercialization scale. Monitor field-emission display prototype-to-production timelines at Tsukuba research corridors as inflection indicator for SED medical-grade pricing power erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Phosphor Supply Security Partnership | Canon and Toshiba are securing terbium precursor offtake agreements with Chinese refiners. |
| Inkjet Deposition Manufacturing Scale-Up | Samsung Display pilots roll-to-roll emitter patterning for cost reduction in professional tiers. |
| METI Compliance Recertification | Domestic manufacturers redesign driver circuits to satisfy sub-1-watt standby power mandates. |
| Regional Health System Alliance Contracting | Consolidated procurement in Kanagawa and Aichi prefectures favors multi-year panel supply agreements. |
| Field Emission Technology Licensing | Tsukuba research corridors license cold-cathode architectures to medical imaging specialists. |
Research Methodology
Multiple input streams — display panel procurement managers at Japanese university hospitals, vacuum-physics engineering directors in Osaka manufacturing clusters, and phosphor supply specialists — were reconciled against secondary validation from METI technical criteria releases, JIS standard documentation, and MFDS calibration requirement filings. Bottom-up shipment estimates from medical imaging and professional display segments were triangulated against top-down electron-emission research expenditure analysis.
Historical capacity utilization patterns were cross-referenced against panel-level input from procurement committees at Samsung Medical Center and Tokyo university hospital networks. Segmentation modeling incorporated product type tiers, technology physics alternatives, end-user procurement authority structures, and application-specific luminance stability requirements. CAGRs were derived from reconciled volume trajectories across the projection horizon, with specific weighting for METI subsidy disbursement timelines and rare-earth phosphor price volatility assumptions.
Inputs from hospital procurement databases and GPO contract filings were available through the study window; gaps in real-time borosilicate substrate pricing introduce uncertainty bands around panel assembler margin projections. Forecasts reflect assumptions regarding OLED substitution velocity in portable diagnostic equipment and field-emission display commercialization delays. A model refresh is warranted upon material change in METI energy-efficiency technical criteria or Chinese rare-earth export licensing protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global Wearable Display Market
Display Technologies
Electronic Display Signs Market
Display Technologies
Head-Mounted Display Market
Display Technologies
Electrochromic Window Market
Display Technologies
OLED Laptops Market
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
Quantum Dot Display Market
Display Technologies
Global Haptic Touchscreen Market
Display Technologies
Electronic Display Market
Display Technologies
Mono LCD Displays Market
Display Technologies
Visual Computing Market
Display Technologies
Digital Kiosk Display Market
Display Technologies
Global Display Panel Market
Display Technologies
Transparent Digital Signage Market
Display Technologies
Rental Outdoor LED Display Market
Display Technologies
Cathode Ray Tube Display Market