
 Touch and Display Integration IC for Tablet Market | 2026-2036
Touch and Display Integration IC for Tablet Market Size, Share, and Industry Trends Forecast 2026-2036
Touch and Display Integration IC for Tablet Market Insights
Enterprise fleet buyers and education procurement agencies are collapsing the historical dominance of retail consumers as the primary volume channel for tablet TDDI procurement. Samsung Electronics Co., Ltd. leverages captive display fabrication to control supply timing for its Galaxy Tab portfolio. Synaptics Inc. specializes in capacitive touch algorithms that reduce controller footprint for ultrathin designs. Himax Technologies, Inc. anchors its position through driver IC co-development with panel makers in Taiwan and China.
Touch and Display Integration ICs merge capacitive touch sensing layers with thin-film transistor display driver functions into single silicon dies, typically fabricated on 40nm to 28nm process nodes to balance power efficiency with signal processing density. These components eliminate discrete flex-cable interconnects between separate controller and driver chips, reducing device thickness by 0.3mm to 0.5mm while simplifying assembly for tablet OEMs. Integrated Circuits command the dominant revenue share by collapsing bill-of-materials complexity, while Capacitive technology leads unit volume due to its multi-touch precision and durability advantages over resistive alternatives. The Industrial Automation application segment generates premium pricing as ruggedized tablets require extended temperature range certifications and enhanced electromagnetic interference shielding in their TDDI designs.
The EU's RoHS and REACH frameworks restrict lead and cadmium content in semiconductor packaging materials, forcing foundry partners to qualify alternative solder compositions and mold compounds. China's MIIT enforces GB standards for display electromagnetic compatibility that TDDI vendors must validate before domestic tablet OEM integration. The US FCC regulates unintentional radiators including tablet subassemblies, with Part 15 compliance testing adding certification cycles for new TDDI architectures. Stakeholders must monitor foundry capacity allocation between automotive display drivers and consumer tablet TDDI as process node competition intensifies.
Market Dynamics
OEM tablet manufacturers are consolidating touch and display controller functions into single-die TDDI architectures to achieve sub-6mm chassis targets, compressing legacy two-chip supply chains and redistributing value capture toward foundry partners with 28nm mixed-signal expertise.
Growth Catalysts
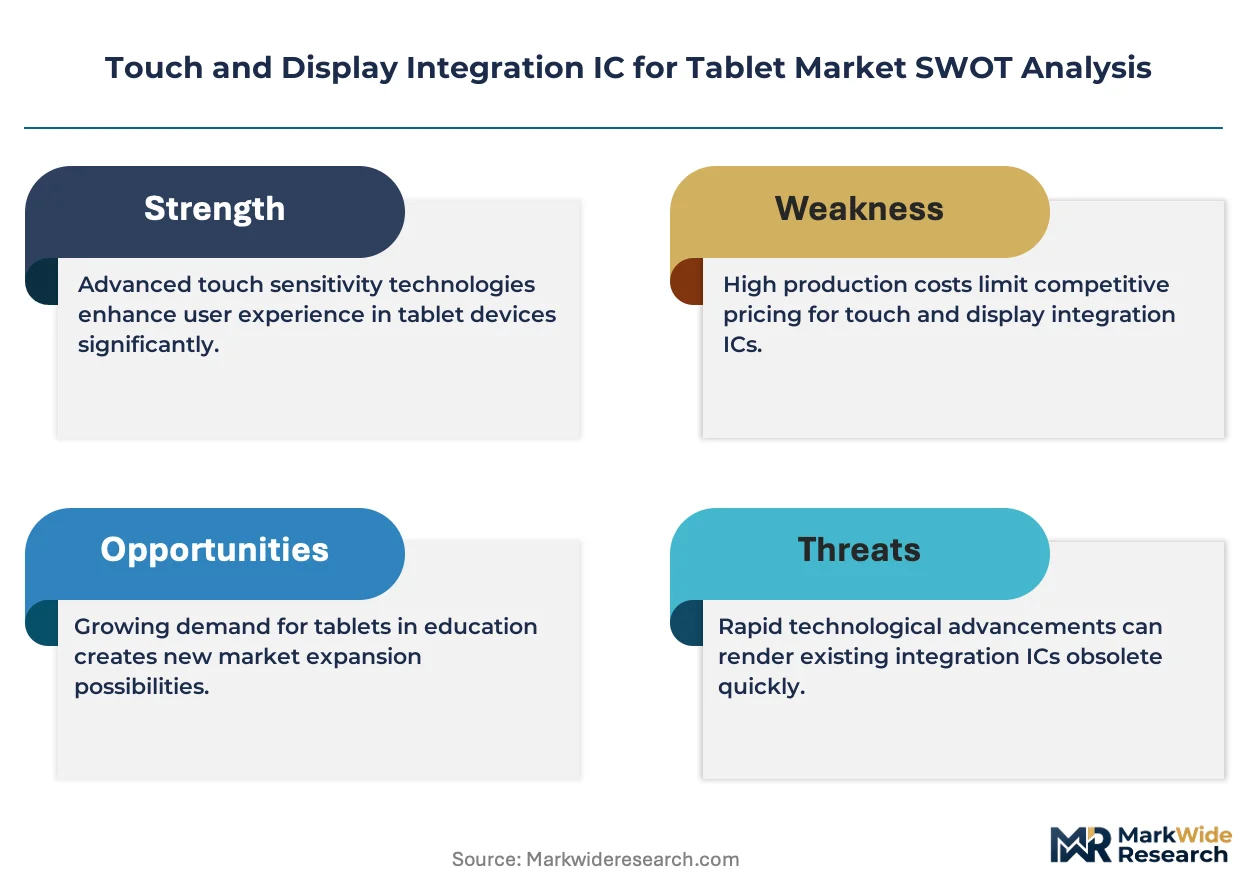
- EU RoHS hazardous substance limits:The directive mandates lead-free solder and cadmium-free packaging, accelerating qualification of compliant TDDI mold compounds and creating first-mover advantages for certified suppliers.
- In-cell integration architecture:Embedding touch sensors directly within TFT liquid-crystal layers eliminates discrete digitizer assemblies, reducing flex-cable counts and assembly labor for tablet OEMs.
- South Korea display cluster concentration:Samsung Display and LG Display anchor captive TDDI sourcing for premium tablet panels, concentrating advanced process demand in Gyeonggi-do and Paju fabrication zones.
Market Restraints
- 28nm foundry capacity scarcity:Automotive display driver ICs compete for the same mixed-signal process nodes, creating allocation bottlenecks for consumer tablet TDDI wafers.
- Input cost volatility in gold wire bonding:TDDI packaging relies on thermosonic gold interconnects, exposing margin structures to precious metal price swings.
- Technical limitation in high-refresh-rate TDDI:Integrated architectures struggle to match discrete controller latency performance at 120Hz+ tablet specifications, constraining gaming and pro-grade adoption.
Strategic Opportunities
- Industrial automation rugged tablets:Extended temperature range and EMI-hardened TDDI specifications command 40-60% pricing premiums over consumer-grade equivalents.
- China MIIT GB electromagnetic compatibility standards:Domestic certification mandates create captive demand windows for TDDI vendors with pre-validated reference designs.
- On-cell metal mesh convergence:Hybrid silver nanowire and metal-mesh touch layers enable larger-format tablet TDDI integration beyond traditional ITO conductivity limits.
Industry Challenges
- Multi-domain signal integrity engineering:TDDI architects must reconcile high-voltage TFT gate drivers with microvolt-level capacitive sensing circuits on shared silicon, creating specialized analog-mixed-signal talent scarcity.
- FCC Part 15 unintentional radiator certification:New TDDI architectures require 8-12 week electromagnetic interference testing cycles before US market entry, compressing product launch windows.
- Legacy tablet fleet compatibility:Enterprise buyers demand multi-generation driver consistency for field serviceability, constraining TDDI vendors from obsoleting established timing controller protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Touch and Display Integration IC for Tablet Market |
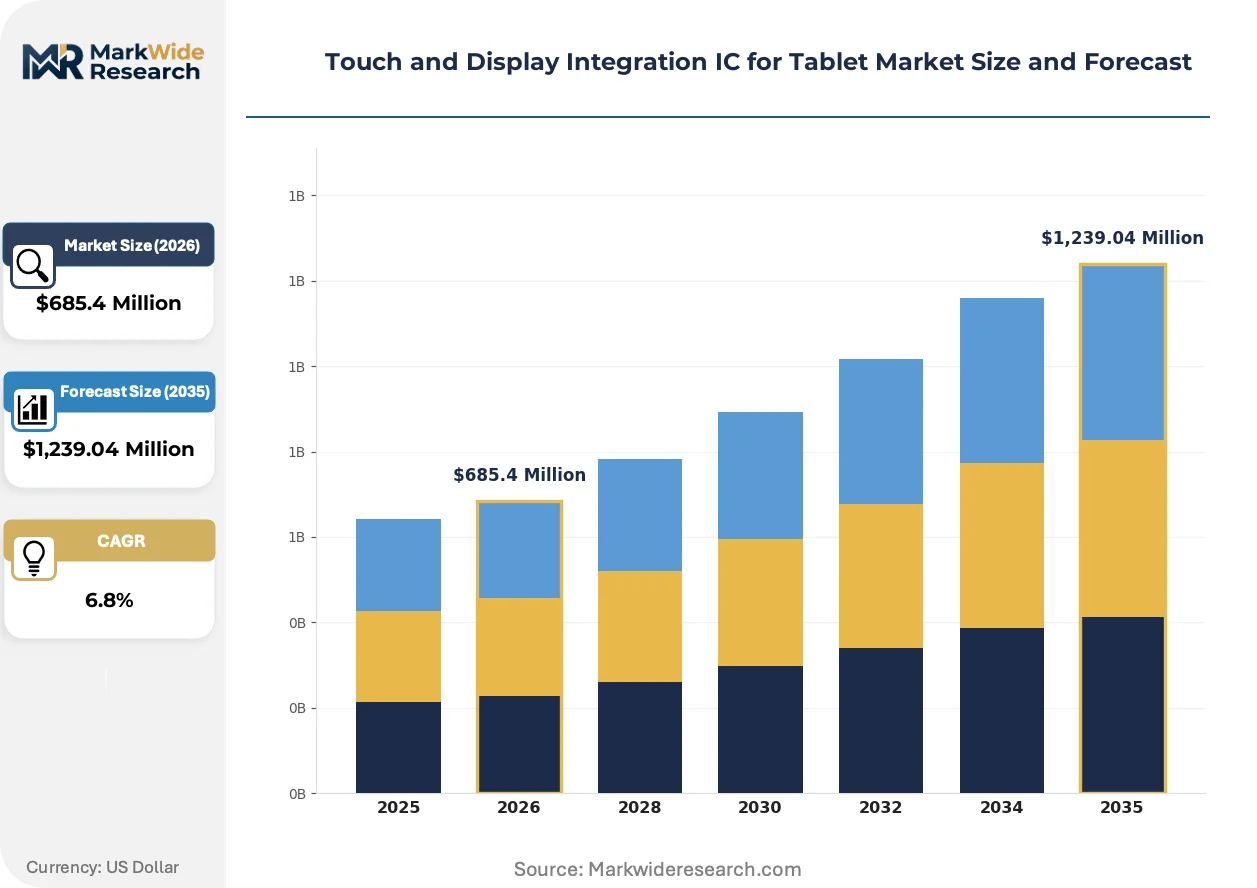
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touch Controllers, Display Drivers, Integrated Circuits, Sensor Chips Technology: Capacitive, Resistive, Optical, Hybrid Application: Consumer Electronics, Education, Healthcare, Industrial Automation End User: OEMs, System Integrators, Distributors, Retailers |
| Companies Covered | Synaptics Inc., Samsung Electronics Co., Ltd., Novatek Microelectronics Corporation, FocalTech Systems Co., Ltd., Himax Technologies, Inc., NXP Semiconductors N.V., STMicroelectronics, MediaTek Inc., Magnachip Semiconductor, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Touch and Display Integration IC for Tablet Market Trends and Innovations
Tablet TDDI architectures are bifurcating between cost-optimized solutions for education procurement and performance-differentiated designs for creative professional segments, with process node selection and touch algorithm sophistication becoming the primary axes of competition.
System-in-Package TDDI modules incorporating discrete DRAM for frame buffering are displacing traditional memory-less architectures in premium tablet tiers. Apple and Samsung Electronics specify SiP configurations for Pro and Ultra tablet lines, enabling local image processing without main memory bus contention. This integration is displacing external timing controller plus discrete touch IC combinations that dominated 2018-2022 flagship designs.
China's MIIT has tightened GB 9254 electromagnetic compatibility enforcement for display subassemblies, requiring TDDI vendors to submit pre-compliance test reports before domestic OEM integration approvals. The regulation forces redesign of switching noise suppression circuits and extends qualification timelines by 4-6 weeks. Domestic Chinese tablet brands are responding by consolidating supplier lists to vendors with established GB certification libraries.
Enterprise fleet buyers are consolidating annual tablet procurement through managed service contracts that bundle hardware, MDM software, and damage protection into per-seat monthly fees. This purchasing pattern is compressing discrete hardware margin visibility and elevating TDDI vendors who can commit to 5-year supply continuity guarantees. North American K-12 education agencies and European healthcare trusts represent the most visible adoption of this bundled acquisition model.
Touch and Display Integration IC for Tablet Market Segmentation
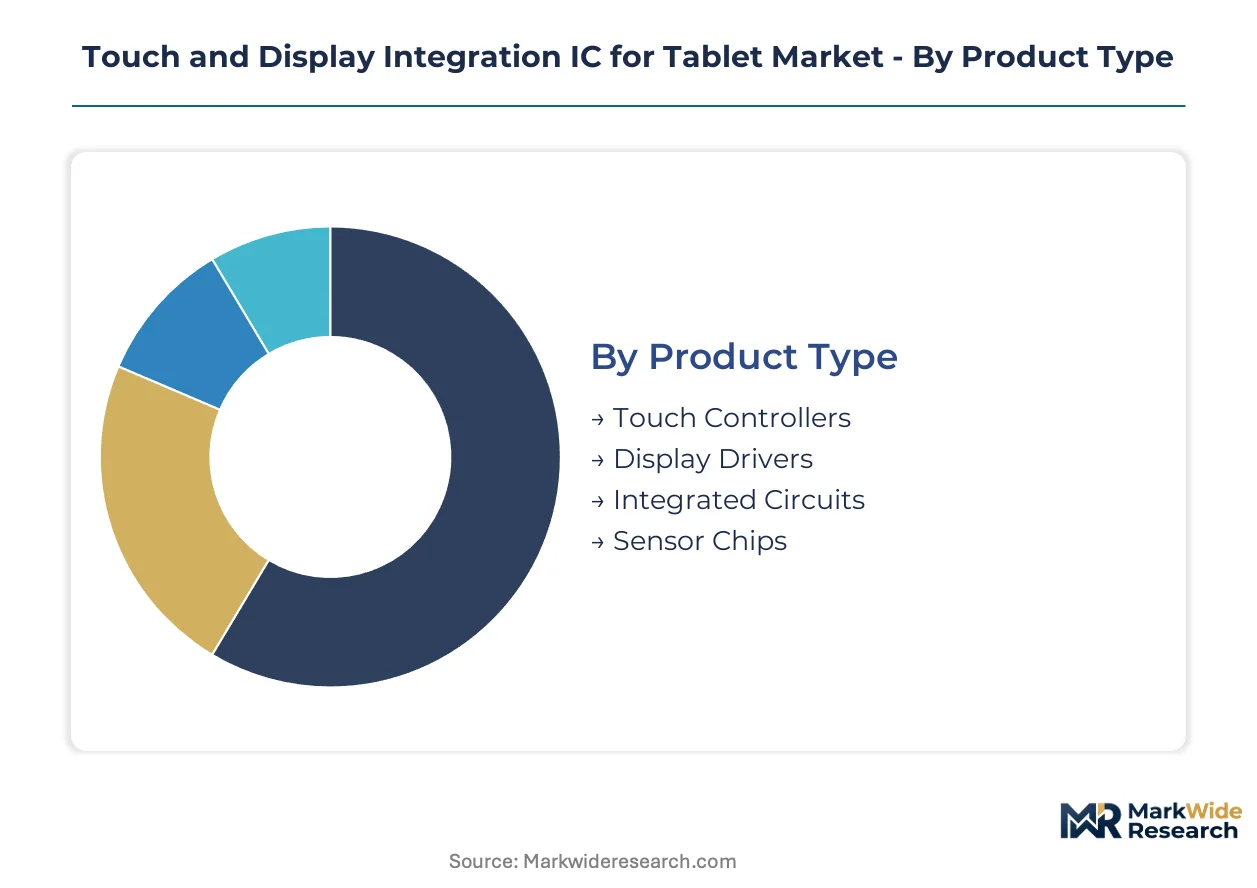
Tablet TDDI procurement patterns diverge sharply across product architectures and end-use specifications. OEM sourcing decisions cascade through technology selection, application requirements, and channel configuration, each dimension carrying distinct margin and volume implications for component vendors.
Product Type:
Margin pools concentrate in highly integrated single-die solutions that collapse legacy multi-chip bill-of-materials for premium tablet OEMs.
- Integrated Circuits:Single-die TDDI architectures merge TFT gate drivers with capacitive sensing circuits on 28nm to 40nm mixed-signal nodes. Samsung Electronics and Apple specify these for Galaxy Tab and iPad Pro portfolios, capturing the highest silicon value per square millimeter in tablet display electronics.
- Touch Controllers:Discrete capacitive sensing ICs persist in cost-optimized education tablets where assembly flexibility outweighs thickness reduction. Procurement concentrates in Taiwan and China panel integration houses serving white-label OEMs.
- Display Drivers:Standalone TFT timing controllers retain niche presence in automotive-to-tablet crossover panels requiring extended temperature validation.
- Sensor Chips:Discrete force and stylus proximity sensors complement TDDI in creative professional tablets with active pen input.
Integrated Circuits holds installed capacity. Touch Controllers is rotating up the share rankings.
Technology:
Volume leadership maps directly to manufacturing process scalability and foundry partner qualification breadth.
- Capacitive:Projected mutual-capacitance architectures dominate tablet TDDI, enabling ten-point multitouch with sub-millimeter positional accuracy. South Korea's display cluster—Samsung Display in Gyeonggi-do and LG Display in Paju—sources exclusively capacitive-optimized TDDI for advanced tablet panels.
- Resistive:Four-wire and five-wire analog layers persist in ruggedized industrial tablets where gloved operation and liquid immunity override touch precision.
- Optical:Infrared grid and camera-based touch overlays serve ultra-large format tablets and interactive whiteboards beyond traditional TDDI die-size economics.
- Hybrid:Metal-mesh silver nanowire combinations bridge ITO conductivity limits for emerging foldable tablet form factors.
Capacitive holds installed capacity. Hybrid is climbing the fastest.
Application:
Pricing power stratifies sharply between consumer-grade volume and certified industrial specifications.
- Industrial Automation:Ruggedized tablets require TDDI with extended temperature range certification and enhanced EMI shielding. These specifications command substantial premiums over consumer equivalents and anchor foundry relationships with automotive-qualified mixed-signal capacity.
- Consumer Electronics:Retail tablet demand concentrates in seasonal refresh cycles, with OEMs prioritizing thickness reduction and display-to-body ratio metrics in TDDI selection.
- Education:K-12 procurement agencies specify cost-optimized TDDI with five-year supply continuity guarantees, compressing margin visibility for vendors.
- Healthcare:Medical tablet TDDI requires IEC 60601-1 electromagnetic compatibility validation for patient proximity use, extending qualification timelines.
Industrial Automation holds installed capacity. Education is gaining share fastest.
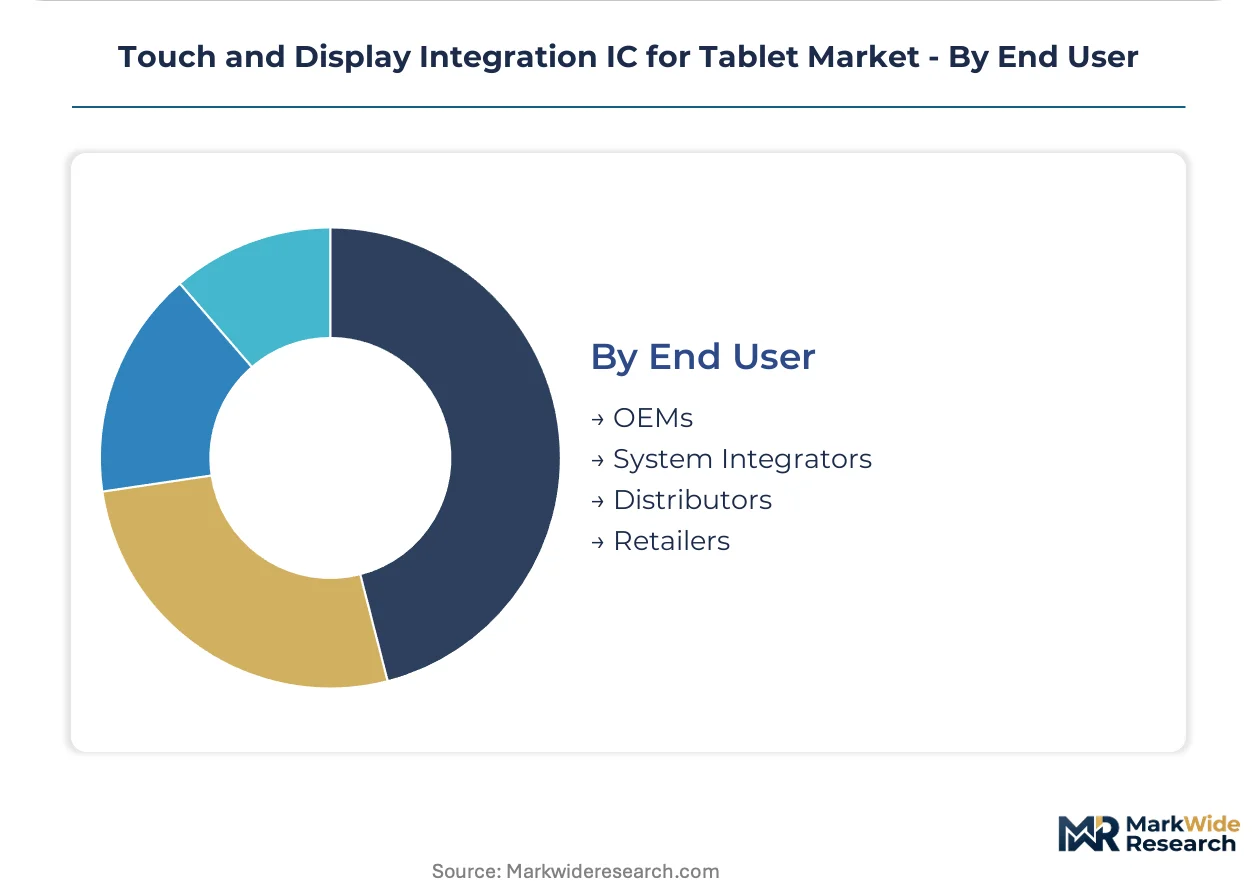
End User:
Channel configuration determines technical support burden and inventory liability allocation between TDDI vendors and downstream partners.
- OEMs:Direct procurement by Samsung Electronics, Lenovo, and Apple drives co-development roadmaps and captive foundry capacity reservation.
- System Integrators:Enterprise fleet deployers bundle tablet hardware with MDM software and damage protection, demanding multi-generation driver consistency.
- Distributors:Arrow Electronics and Avnet stock TDDI for mid-tier tablet OEMs with less predictable demand forecasting.
- Retailers:Best Buy and Amazon channel-specific SKUs influence TDDI packaging and labeling requirements for aftermarket serviceability.
OEMs holds installed capacity. System Integrators is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Incheon International Airport cargo hub underwrites South Korea's dominance in advanced display component logistics, connecting Gyeonggi-do fabrication zones to global tablet OEM assembly lines within 24-hour cycle times.
South Korea
Samsung Electronics and LG Display anchor captive TDDI procurement for Galaxy Tab and premium tablet portfolios. The Ministry of Trade, Industry and Energy enforces K-REACH chemical substance controls on semiconductor packaging materials. The Gyeonggi-do and Paju display clusters concentrate 28nm mixed-signal foundry capacity for in-cell TDDI architectures.
China
Domestic tablet brands BOE and TCL CSOT drive volume procurement of cost-optimized TDDI solutions for education and mid-tier consumer segments. The Ministry of Industry and Information Technology enforces GB 9254 electromagnetic compatibility standards requiring pre-compliance test submissions. The Yangtze River Delta and Pearl River Delta panel integration houses dominate white-label TDDI sourcing for export markets.
United States
Enterprise fleet buyers and K-12 education agencies consolidate procurement through managed service contracts bundling hardware with MDM software. The Federal Communications Commission regulates Part 15 unintentional radiator compliance for tablet subassemblies entering commercial distribution. Design engineering concentrates in California and Texas, with validation labs in the Northeast Corridor handling electromagnetic interference certification cycles.
Taiwan
Panel driver IC specialists co-develop TDDI reference designs with AU Optronics and Innolux for thin-bezel tablet specifications. The Bureau of Standards, Metrology and Inspection administers BSMI safety marking for display subassemblies. The Hsinchu Science Park anchors foundry partnerships for 40nm to 28nm mixed-signal process nodes serving tablet TDDI demand.
Japan
Industrial automation and healthcare tablet OEMs source EMI-hardened TDDI with extended temperature range certifications. The Ministry of Economy, Trade and Industry promotes JIS standardization for display component interoperability. The Chubu and Kansai manufacturing belts concentrate precision assembly capacity for ruggedized tablet supply chains.
Touch and Display Integration IC for Tablet Market Competitive Landscape
Listed leaders compete with private specialists across capital access and strategic flexibility dimensions. The vendor base fragments across three tiers: diversified semiconductor conglomerates with captive display fabrication, fabless mixed-signal specialists co-developing with panel makers, and regional integration houses serving cost-optimized education tablets. Strategic archetypes include foundry-integrated giants, algorithm-focused fabless designers, and packaging-centric module suppliers. Competitive moves center on 28nm mixed-signal capacity reservation and multi-year supply continuity guarantees for enterprise fleet contracts.
Among diversified electronics conglomerates, Samsung Electronics Co., Ltd. exemplifies foundry-integrated vertical control over TDDI timing and display panel output. Synaptics Inc. and Himax Technologies, Inc. represent fabless specialists anchoring positions through co-development partnerships with Taiwan and China panel makers. These three entities occupy distinct competitive spaces: captive supply assurance, touch algorithm differentiation, and driver IC integration expertise respectively.
| Leading Market Players |
|---|
| Synaptics Inc. |
| Samsung Electronics Co., Ltd. |
| Novatek Microelectronics Corporation |
| FocalTech Systems Co., Ltd. |
| Himax Technologies, Inc. |
| NXP Semiconductors N.V. |
| STMicroelectronics |
| MediaTek Inc. |
| Magnachip Semiconductor, Ltd. |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with foundry partners lock in 28nm mixed-signal wafer allocation for TDDI vendors, simultaneously securing supply visibility and insulating procurement costs from spot-market volatility in semiconductor fabrication. These arrangements concentrate pricing power among Samsung Electronics and Synaptics, who leverage captive or pre-committed capacity to stabilize margin structures against gold wire bonding and mold compound input swings.
Pricing Analysis
Volume-discount tiering structures stratify across premium in-cell architectures, standard on-cell configurations, and economy discrete-controller alternatives. Pricing separates industrial automation TDDI with extended temperature certification from consumer-grade equivalents by 40-60% margins. Cost compression in education procurement segments is intensifying as K-12 agencies consolidate annual tablet purchases into multi-year managed service bundles. Enterprise fleet buyers exhibit lowest price sensitivity due to bundled MDM software and damage protection inclusion, while white-label OEMs serving retail channels face acute margin pressure.
Supply Chain Analysis
Inbound logistics costs through Incheon International Airport cargo hub anchor South Korea's display cluster competitiveness, connecting Gyeonggi-do and Paju fabrication zones to global tablet assembly lines within 24-hour cycle times. Supply concentrates in South Korea, Taiwan, and China, drawing from 28nm mixed-signal foundry capacity, gold wire bonding packaging materials, and ITO-alternative silver nanowire substrates. Single-source vulnerability persists in thermosonic gold interconnect supply from Japanese precious metal refiners. Distribution runs through direct OEM procurement for Samsung and Apple, with Arrow Electronics and Avnet serving mid-tier tablet manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as enterprise fleet agencies and K-12 education procurement offices displace retail consumers as the dominant volume channel, collapsing historical margin visibility for TDDI vendors unable to commit to five-year supply continuity guarantees.
For Market Incumbents: Fortify captive foundry relationships through multi-year capacity reservation agreements at 28nm nodes, insulating against automotive display driver IC competition for mixed-signal wafer allocation. Invest in pre-validation of China MIIT GB 9254 electromagnetic compliance to compress domestic OEM qualification timelines. Defensive priority centers on blocking emerging fabless entrants from securing panel maker co-development partnerships in Taiwan and China. For New Entrants and Emerging Players: China MIIT certification fast-tracks create entry windows for TDDI vendors with established GB 9254 test report libraries, as domestic tablet brands consolidate supplier lists toward pre-qualified vendors. White-space concentrates in ruggedized industrial automation tablets requiring EMI-hardened specifications and extended temperature range validation. Target education procurement agencies in North America and Europe through system integrator channel partnerships bundling hardware with MDM software and damage protection. For Investors and Strategic Acquirers: Fabless mixed-signal specialists with panel maker co-development roadmaps represent the most defensible acquisition targets, given analog-mixed-signal talent scarcity and multi-domain signal integrity engineering barriers. Long-term viability hinges on 28nm capacity access and industrial automation certification breadth. Watch foundry capacity allocation shifts between automotive display drivers and consumer tablet TDDI as the primary inflection signal for margin compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| 28nm Foundry Capacity Reservation | Locks in wafer allocation against automotive display driver competition at Samsung Foundry and TSMC. |
| China MIIT GB 9254 Pre-Validation | Compresses qualification timelines for BOE and TCL CSOT domestic tablet integration approvals. |
| Industrial Automation Certification Investment | Captures 40-60% pricing premiums through extended temperature range and EMI-hardened specifications. |
| System-in-Package TDDI Module Development | Displaces external timing controller combinations for Apple and Samsung Pro-tier tablet lines. |
| Silver Nanowire Metal-Mesh Hybrid Integration | Enables foldable tablet form factors beyond traditional ITO conductivity limits. |
Research Methodology
Desk research of SEC semiconductor filings, foundry capacity utilization disclosures, and MIIT regulatory bulletins preceded structured interviews with tablet OEM procurement directors, display panel integration engineers, and mixed-signal IC design architects. Primary fieldwork with enterprise fleet buyers and K-12 education technology coordinators validated volume assumptions. Secondary sources included FCC Part 15 certification databases, EU RoHS substance restriction updates, and Taiwan BSMI safety marking records. Bottom-up TDDI unit shipment estimates triangulated against top-down tablet display panel production data.
Variance decomposition across product architecture, application certification tier, and foundry process node shaped the analytical framework over the projection horizon. Segmentation dimensions encompassed integrated circuit versus discrete controller configurations, capacitive versus hybrid touch technologies, and industrial automation versus consumer electronics end-use specifications. CAGRs derived from installed base replacement cycles, education procurement refresh schedules, and premium tablet refresh cadence. Forecast inputs included 28nm foundry capacity allocation ratios and gold wire bonding cost trajectories.
Underlying assumptions cover sustained OEM consolidation toward in-cell TDDI architectures, with deviation risk concentrated in automotive display driver IC demand spikes absorbing mixed-signal foundry capacity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Screenless Display Market
Display Technologies
Display Port Market
Display Technologies
Europe E-Paper Display Market
Display Technologies
Industrial Display Market
Display Technologies
Touch Screen Module Market
Display Technologies
3D Display Module Market
Display Technologies
Video Wall Display Market
Display Technologies
Flexible Display Market
Display Technologies
Global Ultra Wide Temperature TFT Display Market
Display Technologies
Global 5K Display Resolution Market
Display Technologies
Electronic Display Signs Market
Display Technologies
Laptop Panels Market
Display Technologies
Field Emission Display Market
Display Technologies
Multi-Touch Screen Market
Display Technologies
Display Fingerprint Technology Market
Display Technologies
Global Center Stack Display Market